
 Indonesia Plastic Packaging Films Market | 2026-2036
Indonesia Plastic Packaging Films Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Plastic Packaging Films Market Insights
Food & Beverage is restructuring Indonesia's plastic packaging films demand as brands shift from rigid to flexible formats for ready-to-eat meals and snack lines. PT Polyplex Films Indonesia leverages biaxial orientation capacity to dominate technical film supply for processed food exporters. PT Trias Sentosa TBK anchors the domestic flexible packaging substrate segment with integrated resin-to-film operations. Amcor Group GmbH differentiates through global sustainability protocols that align with Indonesian palm oil sector export requirements.
Indonesia plastic packaging films are thermoplastic polymer sheets typically ranging from 10 to 150 microns in gauge, extruded through blown or cast processes to provide moisture barriers, optical clarity, and seal integrity for commercial goods. Stretch Films leads the Product Type dimension due to palletization demand from Indonesia's expanding e-commerce fulfillment networks, while Barrier Films posts the fastest structural growth on shelf-life extension needs for tropical climate distribution. LLDPE captures the largest Material share on cost-performance balance, though LDPE maintains margin pools in premium clarity applications for Personal Care and Electronics end users.
BIS-equivalent Indonesian National Standards and the Ministry of Environment and Forestry's extended producer responsibility framework shape film composition rules, pushing converters toward recyclable mono-material structures. The central bank's green credit incentives and regional waste bank programs influence capital allocation for recycling-compatible film lines. Stakeholders must monitor regulatory alignment between Jakarta's national standards and provincial plastic waste ordinances to anticipate compliance-driven product redesign cycles.
Market Dynamics
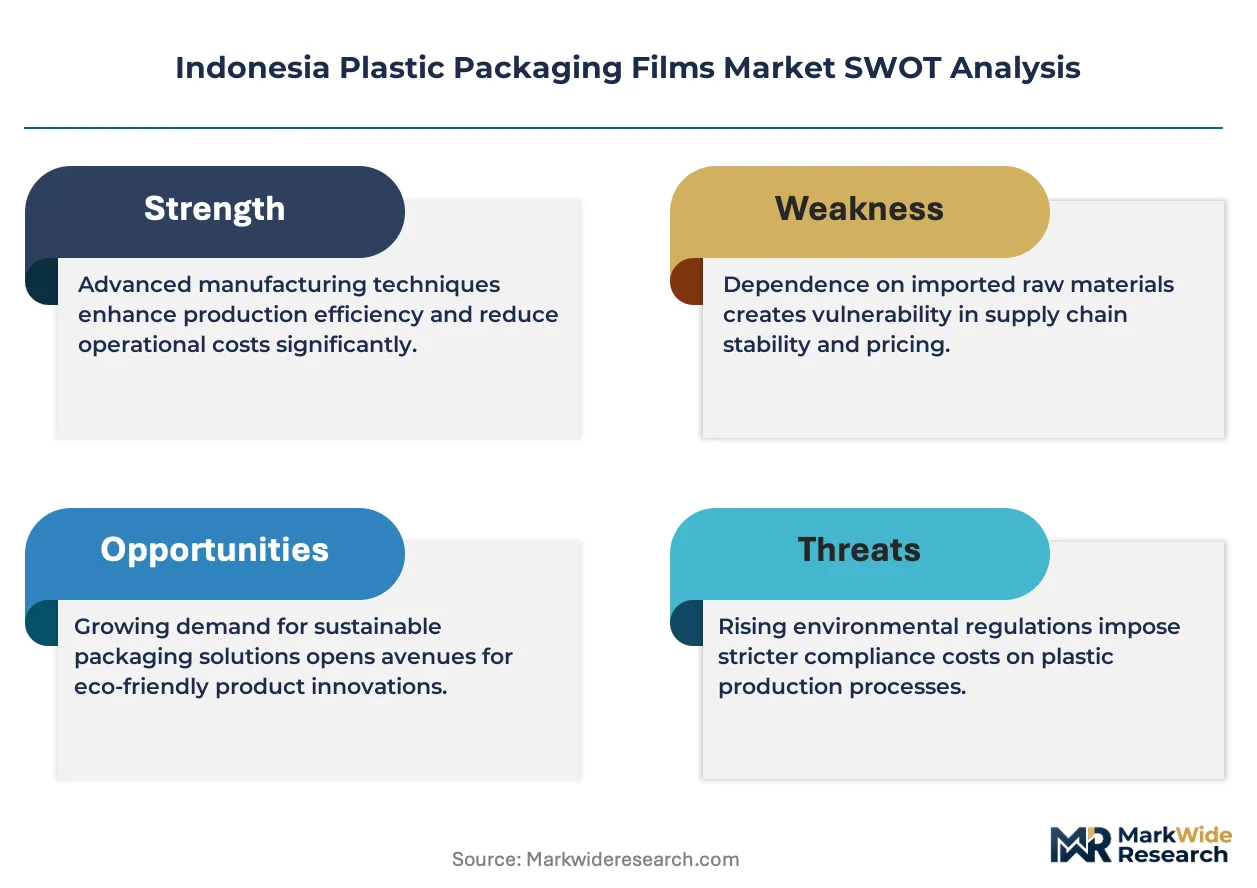
Indonesia's plastic packaging films sector is compressing around mono-material recyclability mandates from the Ministry of Environment and Forestry, forcing converters to abandon multi-layer laminates and rebuild extrusion lines for polyethylene-polypropylene compatibility.
Growth Catalysts
- E-commerce palletization surge:Stretch film consumption is accelerating across Java's fulfillment warehouse clusters as third-party logistics operators standardize load containment protocols for cross-archipelago distribution.
- Extended producer responsibility tightening:The Ministry of Environment and Forestry's revised waste management regulations are compelling brand owners to specify recyclable substrates, pulling technical film demand toward single-polymer structures.
- Processed food export compliance:Palm oil sector exporters are retrofitting packaging lines to meet EU packaging waste directive alignment requirements, driving barrier film specifications for tropical climate shelf-life extension.
Market Restraints
- Resin import dependency:Indonesia's polyethylene and polypropylene supply relies on Middle Eastern and Northeast Asian feedstock, exposing converters to naphtha-linked price volatility and rupiah-denominated working capital pressure.
- Multi-layer technical debt:Legacy metallized and coextruded barrier films lack domestic recycling infrastructure, creating stranded asset risk for converters with substantial biaxial orientation capacity in legacy formats.
- Paper-based substitution in premium segments:Personal care and cosmetics brands are piloting molded fiber and paper laminate alternatives for primary packaging, compressing addressable film demand in high-margin clarity applications.
Strategic Opportunities
- Chemical recycling feedstock partnerships:Pyrolysis operators in East Java are seeking consistent polyolefin waste streams, creating offtake agreements for post-industrial film scrap that converters can monetize as circular economy revenue.
- Halal certification integration:The Indonesian Ulema Council's expanding halal product assurance mandate covers packaging materials, enabling film suppliers to capture premium positioning in Muslim-majority export markets.
- Digital printing convergence:Narrow-web flexographic and inkjet systems are merging with mono-material substrates to enable short-run customization for regional snack brands, compressing minimum order quantities and expanding addressable customer bases.
Industry Challenges
- Mono-material reformulation expertise gap:Converters lack sufficient polymer science capability to replicate oxygen and moisture barrier performance of metallized PET-PE laminates using single-resin structures, delaying customer qualification cycles.
- Waste bank integration complexity:Coordinating collection logistics with Indonesia's decentralized waste bank network requires new reverse supply chain infrastructure that mid-scale film processors cannot self-finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Plastic Packaging Films Market |
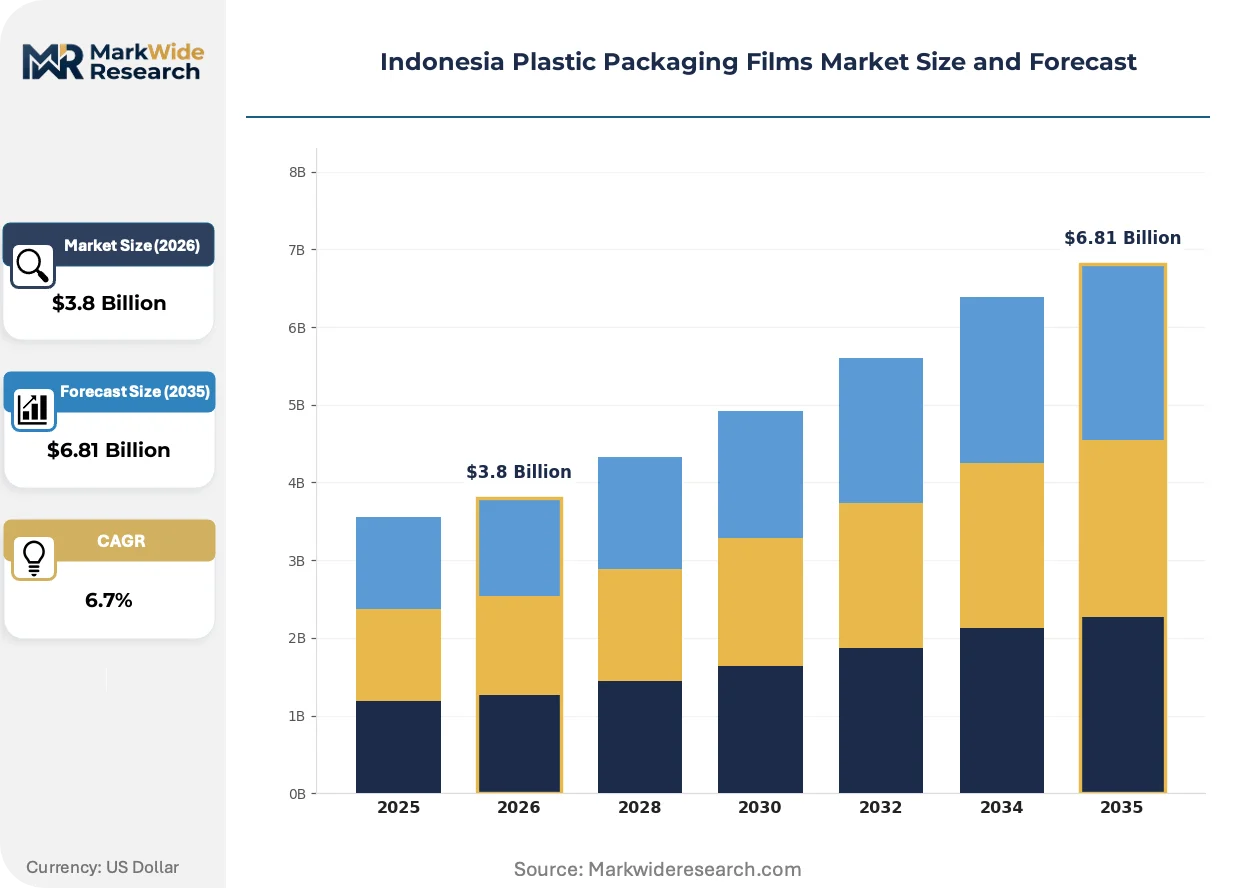
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stretch Films, Shrink Films, Barrier Films, Rigid Films Material: LDPE, HDPE, LLDPE, PVC End User: Food & Beverage, Personal Care, Healthcare, Electronics Packaging Type: Flexible Packaging, Rigid Packaging, Secured Packaging, Retail Packaging |
| Companies Covered | PT Polyplex Films Indonesia, PT Urban Plastik Indonesia, PT MC PET Film Indonesia, Amcor Group GmbH, PT Trias Sentosa TBK, PT Indopoly Swakarsa Industry TBK, PT MASPLAST POLY FILM, PT Argha Karya Prima Industry, ePac Holdings LLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Plastic Packaging Films Market Trends and Innovations
Mono-material compatibility is rewiring Indonesia's technical film specifications as brand owners pre-empt EU packaging waste directive alignment and domestic extended producer responsibility enforcement.
Biaxially oriented polypropylene film is absorbing metallized polyethylene terephthalate functionality in snack and confectionery applications. PT Trias Sentosa TBK and regional converters are accelerating qualification of transparent high-barrier BOPP grades to displace aluminum oxide-coated PET in humidity-sensitive tropical distribution. The structural consequence is compressing demand for multi-layer PET-PE laminates while expanding coating and metallization capacity for oriented polypropylene substrates.
Indonesia's Ministry of Environment and Forestry extended producer responsibility framework is mandating recyclable packaging design across food, beverage, and personal care sectors. Industrial consequence includes mandatory reporting of plastic packaging volumes and financing obligations for waste collection infrastructure. Small and mid-scale converters in Surabaya and Bandung industrial corridors face the steepest compliance cost escalation as they retrofit quality systems for mono-material traceability documentation.
Brand technical buyers are consolidating film supplier panels from fragmented regional converters toward integrated resin-to-film operators with certified recycling partnerships. The direct procurement model is displacing trader-mediated spot purchasing in Java's industrial corridor, particularly for multinational food manufacturers with centralized sustainability audit requirements. This concentration is most visible in Jakarta's processed food export cluster where palm oil sector packaging specifications now require chain-of-custody documentation from resin synthesis through final film conversion.
Indonesia Plastic Packaging Films Market Segmentation
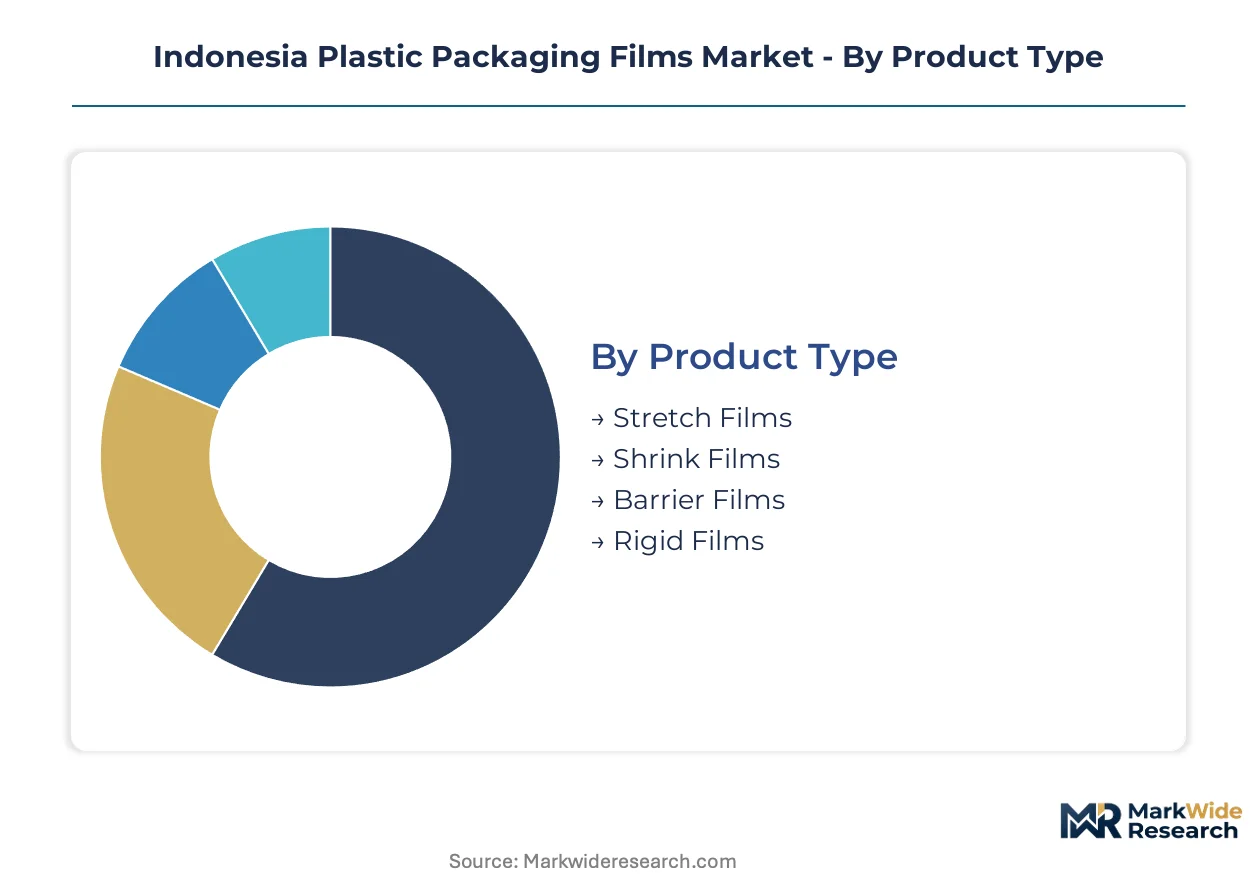
Indonesia's plastic packaging films market segments along four intersecting dimensions that determine converter capital allocation and resin procurement strategies. Each category carries distinct technical specifications, regulatory exposure, and margin profiles that shape competitive positioning across Java's industrial corridor.
Product Type:
Capital intensity varies sharply across extrusion technologies, with biaxial orientation lines demanding substantially higher upfront investment than cast film equipment.
- Stretch Films:Linear low-density polyethylene formulations dominate pallet wrap applications for e-commerce fulfillment networks in Bekasi and Cikarang warehouse clusters. Third-party logistics operators specify 17-23 micron cast LLDPE grades with high puncture resistance for cross-archipelago distribution loads.
- Barrier Films:Multi-layer coextrusions and metallized substrates provide oxygen and moisture protection for processed food exports facing tropical climate shelf-life requirements. Palm oil sector packaging lines in Medan and Surabaya are retrofitting specifications to meet EU packaging waste directive alignment, pulling demand toward recyclable mono-material barrier structures.
- Shrink Films:Polyolefin and PVC formulations enable bundle wrapping for beverage multipacks and retail display units.
- Rigid Films:Thermoformable PET and PP sheets serve tray and blister applications with higher gauge requirements than flexible alternatives.
Stretch Films absorbs the bulk of installed capacity; Barrier Films is expanding most quickly on processed food export compliance mandates.
Material:
Resin selection determines recyclability credentials under Indonesia's extended producer responsibility framework and influences converter exposure to naphtha-linked import price volatility.
- LLDPE:Hexene and butene copolymers balance tensile strength with puncture resistance across stretch film and general-purpose flexible packaging applications. Jakarta's industrial corridor converters favor LLDPE for its cost-performance ratio in high-volume palletization contracts.
- LDPE:Lower density formulations deliver optical clarity and seal integrity for premium personal care and electronics packaging where aesthetic requirements override mechanical performance. Surabaya converters maintain margin pools in clarity-grade LDPE despite narrower technical applications than linear alternatives.
- HDPE:Higher crystallinity provides stiffness and chemical resistance for industrial and agricultural film applications.
- PVC:Plasticized formulations serve shrink sleeve and blister pack segments with distinct processing requirements from polyolefin films.
LLDPE commands the largest volume position; LDPE retains premium pricing power in clarity-sensitive segments.
End User:
Customer concentration patterns segment the market between export-facing multinationals with centralized sustainability audits and fragmented domestic brands with spot procurement habits.
- Food & Beverage:Processed food manufacturers and palm oil exporters drive flexible format adoption for ready-to-eat meals and snack lines. Brand technical buyers are consolidating supplier panels toward integrated resin-to-film operators with certified recycling partnerships and chain-of-custody documentation.
- Personal Care:Cosmetics and hygiene brands pilot molded fiber and paper laminate alternatives, compressing addressable film demand in high-margin clarity applications. Bandung-based converters serving this segment face substitution pressure in primary packaging specifications.
- Healthcare:Sterile barrier and pharmaceutical packaging demands specialized cleanroom conversion capabilities with regulatory documentation.
- Electronics:Anti-static and moisture barrier films protect components through tropical distribution with exacting performance specifications.
Food & Beverage anchors procurement volume; Healthcare exhibits the steepest expansion trajectory on medical device manufacturing growth.
Packaging Type:
Format selection reflects the tension between shelf presence requirements and logistics efficiency in Indonesia's archipelago distribution challenges.
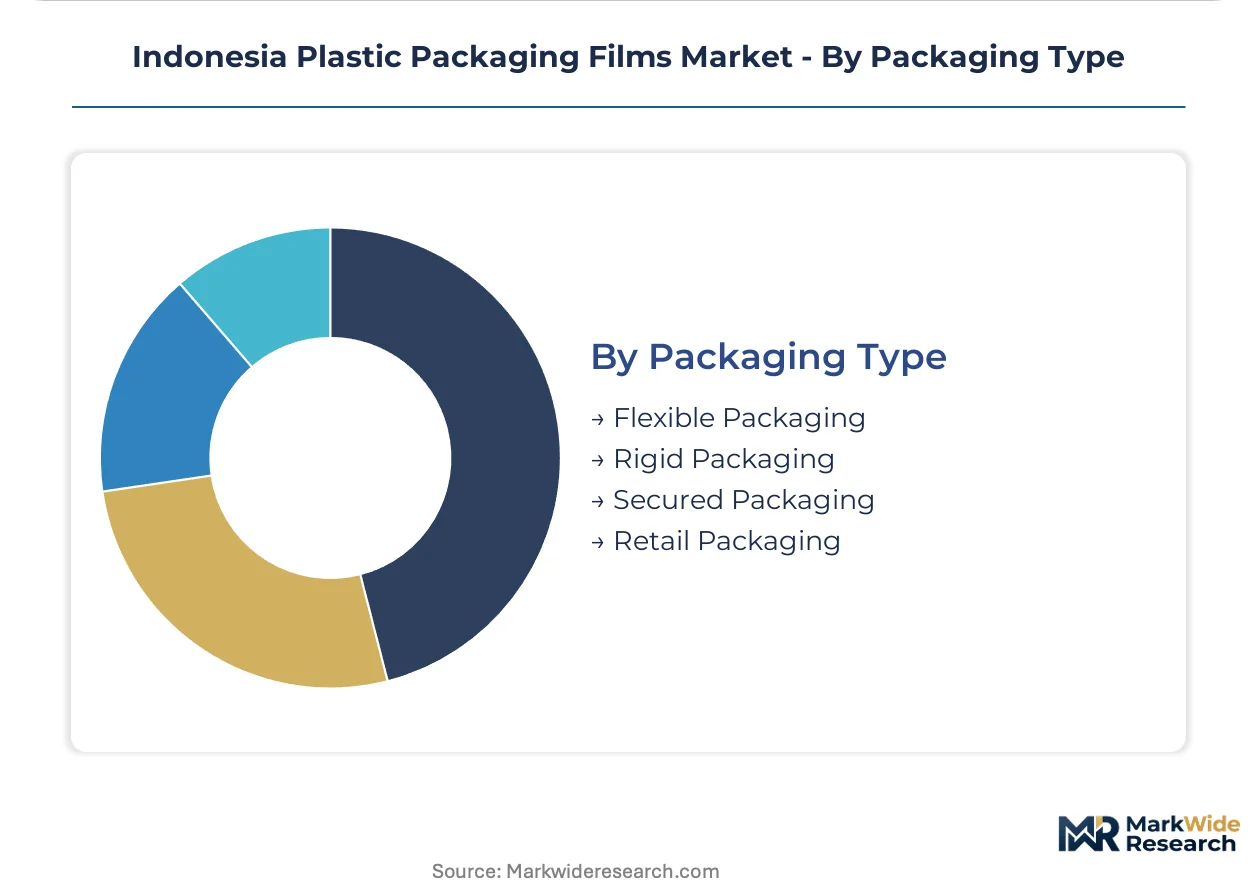
- Flexible Packaging:Pouches, sachets, and wrap formats reduce material weight and shipping cube versus rigid alternatives for processed food and personal care distribution. Mono-material polyethylene and polypropylene structures are displacing multi-layer laminates under Ministry of Environment and Forestry recyclability mandates.
- Secured Packaging:Tamper-evident films and anti-counterfeit features address premium product protection requirements in cosmetics and pharmaceuticals.
- Rigid Packaging:Thermoformed trays and blister packs maintain structural integrity for sensitive products despite higher material intensity.
- Retail Packaging:Point-of-sale display films and printed overwrap serve merchandising requirements with shorter run lengths than industrial formats.
Flexible Packaging holds the dominant share position; Secured Packaging is gaining share fastest on premium product authentication demands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kawasan Industri Jababeka and other bonded zones in Bekasi-Cikarang concentrate extrusion capacity near Jakarta's consumption gravity. The Ministry of Environment and Forestry's extended producer responsibility rules are compressing multi-layer film demand across Java's industrial corridor while pulling investment toward mono-material-compatible extrusion lines.
Java
Stretch film consumption accelerates in Bekasi and Cikarang warehouse clusters serving third-party logistics operators. The Ministry of Environment and Forestry mandates recyclable substrate specifications for brand owners. Surabaya converters retrofit legacy metallized lines for BOPP barrier compatibility to meet palm oil export compliance.
Sumatra
Medan's palm oil processing cluster drives barrier film demand for tropical climate shelf-life extension. The central bank's green credit incentives influence capital allocation for recycling-compatible film investments. Batam's free trade zone hosts import-dependent converters serving electronics manufacturers with anti-static specifications.
Sulawesi
Makassar's emerging food processing hub generates flexible packaging demand for regional snack distribution. Provincial plastic waste ordinances in South Sulawesi anticipate national EPR alignment. Palu industrial estates attract mid-scale converters seeking lower land costs than Java's saturated corridors.
Kalimantan
Balikpapan's logistics infrastructure supports film distribution to mining and agricultural end users across East Kalimantan. Regional waste bank programs in Samarinda pilot collection logistics for post-industrial film scrap. Pontianak converters leverage proximity to Malaysian resin supply chains for cost-competitive LLDPE sourcing.
Indonesia Plastic Packaging Films Market Competitive Landscape
Top-tier vendors anchor integrated resin-to-film operations, while mid-scale converters struggle with mono-material reformulation expertise gaps. The market compresses around certified recycling partnerships and chain-of-custody documentation capabilities. Three archetypes dominate: global sustainability protocol operators, integrated domestic resin-to-film players, and regional spot-market converters. Competitive moves concentrate on supplier panel consolidation by multinational brand technical buyers and backward integration into captive resin sourcing.
Within the integrated domestic tier, PT Trias Sentosa TBK and PT Polyplex Films Indonesia exemplify resin-to-film operators with biaxial orientation capacity. Amcor Group GmbH represents global sustainability protocol alignment for export-facing food manufacturers. These three anchors illustrate the divergence between technical film specialists serving processed food exporters and generalist converters facing stranded asset risk in legacy multi-layer formats.
| Leading Market Players |
|---|
| PT Polyplex Films Indonesia |
| PT Urban Plastik Indonesia |
| PT MC PET Film Indonesia |
| Amcor Group GmbH |
| PT Trias Sentosa TBK |
| PT Indopoly Swakarsa Industry TBK |
| PT MASPLAST POLY FILM |
| PT Argha Karya Prima Industry |
| ePac Holdings LLC |
| Others |
Pricing and Supply Chain Analysis
Naphtha-linked polyethylene resin imports from Saudi Arabia and Singapore flow through Jakarta's bonded zones into three-tier pricing structures that separate integrated resin-to-film operators from trader-dependent converters. LLDPE pellet costs transmit directly to stretch film contract tiers, while spot rupiah volatility compresses margins for mid-scale processors lacking captive resin sourcing.
Pricing Analysis
Short lead-time premiums of 8-12% apply to mono-material barrier film orders from palm oil exporters facing EU compliance deadlines, while spot inventory discounts attract domestic snack brands with flexible procurement calendars. Pricing stratifies across premium certified-recyclable, standard industrial-grade, and economy spot-market tiers based on chain-of-custody documentation and volume commitment scale. Cost compression in economy-grade LLDPE stretch film is intensifying because third-party logistics operators are consolidating pallet-wrap contracts toward annual offtake agreements. Small-scale converters in Bandung exhibit the highest price sensitivity due to working capital constraints and rupiah-denominated resin exposure, whereas multinational food manufacturers prioritize certification-grade premiums over unit cost.
Supply Chain Analysis
Regional distribution centers in Bekasi-Cikarang and Surabaya operate hub-and-spoke patterns radiating toward Sumatra and Sulawesi fulfillment nodes. Manufacturing concentrates in Indonesia, with resin feedstock dependency on Saudi Arabia, South Korea, and Singapore. The supply chain draws from Middle Eastern naphtha derivatives, Indonesian bauxite-derived catalysts, and Japanese biaxial orientation equipment. Single-source vulnerability pervades metallized barrier film substrate supply, where PET coating capacity clusters with three regional operators. Distribution runs through bonded zone consolidation points before final-mile deployment to Java's warehouse clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indonesia's plastic packaging films sector is consolidating around backward integration into captive resin sourcing and downstream recycling partnerships. Players securing pyrolysis offtake agreements and BIS-equivalent certification pathways will capture margin pools lost to fragmented converters.
For Market Incumbents: Anticipate Ministry of Environment and Forestry enforcement waves by retrofitting metallized lines for transparent high-barrier BOPP qualification before stranded asset risk crystallizes in legacy PET-PE laminate capacity. Deepen upstream control over hexene copolymer LLDPE supply through long-term offtake with Saudi and Singaporean resin producers, insulating margin pools from rupiah volatility that compresses trader-dependent competitors. For New Entrants and Emerging Players: Enter via chemical recycling feedstock partnerships with East Java pyrolysis operators seeking consistent polyolefin waste streams, monetizing post-industrial scrap as circular economy revenue. Target Makassar's emerging food processing hub in Sulawesi, where provincial waste bank programs anticipate national EPR alignment and land costs undercut Java's saturated corridors. Lead with digital printing convergence for short-run snack brand customization, compressing minimum order quantities that exclude integrated incumbents. For Investors and Strategic Acquirers: First-mover halal certification integration by film suppliers is the leading indicator that premium positioning in Muslim-majority export markets will consolidate around integrated resin-to-film operators with Indonesian Ulema Council partnerships. Over a multi-year horizon, acquisition targets should exhibit biaxial orientation capacity plus certified recycling documentation, as multinational brand technical buyers consolidate supplier panels away from fragmented regional converters. Monitor EU packaging waste directive alignment requirements as the inflection signal for barrier film specification shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Sourcing | Captive LLDPE supply from Saudi feedstock insulates margins from rupiah volatility and trader markups. |
| Mono-Material Line Retrofit | BOPP barrier qualification displaces metallized PET-PE laminates under Ministry of Environment and Forestry mandates. |
| Chemical Recycling Partnership | Pyrolysis offtake agreements with East Java operators convert post-industrial scrap into circular revenue streams. |
| Halal Certification Integration | Indonesian Ulema Council alignment enables premium positioning in palm oil sector export markets. |
| Digital Printing Convergence | Narrow-web flexographic systems merge with mono-material substrates to capture regional snack brand short-run demand. |
Research Methodology
Trade databases, Ministry of Environment and Forestry regulatory filings, and BIS-equivalent Indonesian National Standards documentation formed the secondary backbone, cross-referenced with primary interviews involving extrusion plant managers, palm oil sector packaging engineers, third-party logistics procurement leads, and chemical recycling facility operators. Bottom-up capacity assessments across Java's industrial corridor were triangulated with top-down demand modeling from food and beverage export data.
Historical trendline analysis of installed extrusion capacity and resin import volumes established baseline growth patterns across the projection horizon. Segmentation modeling incorporated product type, material grade, end-use industry, and packaging format dimensions, with CAGRs derived from elasticity-adjusted demand curves and substitution rate assumptions for mono-material structures. Forecast inputs included e-commerce fulfillment network expansion rates and EU packaging waste directive alignment timelines.
Revisions become necessary when naphtha price volatility exceeds historical bands, when provincial plastic waste ordinances diverge from national EPR frameworks, or when chemical recycling capacity deployment lags waste bank collection growth. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Vinyl Films Market
Poly film
Japan Plastic Packaging Film Market
Poly film
Global BOPET Packaging Films Market
Poly film
Light Reflective Film Market
Poly film
Anti Fog Polycarbonate Films and Sheets Market
Poly film
Vietnam Plastic Packaging Films Market
Poly film
Poly Coated Kraft Paper Market
Poly film
PCR Lidding Films Market
Poly film
China Plastic Packaging Film Market
Poly film
EVOH Encapsulation Film Market
Poly film
Timber Wrap Films Market
Poly film
Soft Touch Lamination Film Market
Poly film
Polyolefin (POF) Shrink Film Market
Poly film
Italy Plastic Packaging Films Market
Poly film
Canada Plastic Packaging Films Market
Poly film
PVC Cling Film Market