
 Nylon Films Market | 2026-2036
Nylon Films Market Size, Share, and Industry Trends Forecast 2026-2036
Nylon Films Market Outlook
High-barrier specification grades is rotating toward center stage as converters seek oxygen transmission rates below 0.5 cc/m²/day for protein packaging. FlexFilm leverages captive resin compounding to secure supply continuity for Nylon 6 formulations. COSMO Films anchors South Asian demand through blown film lines calibrated to local humidity conditions. GMP specializes in cast nylon thickness control for medical device blister formats.
Nylon films are semicrystalline polyamide sheets manufactured through cast or extrusion processes, typically ranging from 12 to 150 microns, engineered for puncture resistance, thermal stability, and gas barrier performance in demanding industrial environments. Cast Nylon dominates margin pools in medical device and electrical insulation applications where dimensional tolerances tighten below ±2%. Nylon 66 competes for automotive under-hood specifications where continuous service temperatures exceed 150°C. Thin Film categories lead packaging volume through downgauging programs that maintain barrier properties at reduced caliper.
FDA migration testing protocols and EU REACH Annex XVII restrictions on phthalate adjuncts shape formulation choices for food-contact and medical-grade nylon films. Germany's national implementation of EU Packaging and Packaging Waste Regulation tightens recyclability labeling requirements for multilayer structures. Stakeholders must monitor emerging mechanical recycling certification standards and decide whether to invest in monomaterial nylon designs or advanced sorting-compatible multilayer architectures.
Market Dynamics
Converters are pivoting toward monomaterial nylon architectures as EU Packaging and Packaging Waste Regulation recyclability mandates force redesign of legacy multilayer barrier structures. This regulatory pressure is compressing demand for conventional coextruded films while elevating certified recyclable grades.
Growth Catalysts
- High-barrier protein packaging specifications:Oxygen transmission rates below 0.5 cc/m²/day are becoming mandatory for vacuum-packed meat and cheese applications in Germany and France, pulling premium cast nylon volumes.
- REACH Annex XVII phthalate restrictions:ECHA's tightening migration limits for food-contact polymers are disqualifying conventional plasticized films and accelerating qualified nylon 6 formulations.
- Automotive under-hood thermal requirements:Continuous service temperatures exceeding 150°C in electric vehicle powertrain compartments are displacing commodity polyesters with nylon 66 films.
Market Restraints
- Caprolactam feedstock volatility:Benzene-derived monomer pricing swings compress margin predictability for Nylon 6 film extruders without captive resin compounding.
- Multilayer sorting incompatibility:Current mechanical recycling infrastructure cannot separate nylon from polyethylene tie layers, limiting circular economy claims and threatening premium positioning.
- Polyethylene furanoate substitution:Bio-based PEF films with comparable barrier performance are capturing pilot-scale interest from carbon-neutral packaging commitments.
Strategic Opportunities
- Medical device blister format expansion:Cast nylon thickness control below ±2% dimensional tolerance opens pharmaceutical primary packaging applications previously served by PVC and PVDC.
- India humidity-calibrated blown film:Local climatic conditions in Maharashtra and Gujarat require modified resin formulations that multinational suppliers have not optimized, creating white space for regional production.
- EU Green Deal circular material mandates:Packaging waste reduction targets and extended producer responsibility schemes reward films with certified mechanical recycling pathways.
Industry Challenges
- Coextrusion line reconfiguration costs:Transitioning from multilayer to monomaterial architectures requires capital-intensive die and cooling system replacement.
- FDA migration testing timeline compression:Food-contact notification review periods for novel nylon grades are extending, delaying commercialization of reformulated products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nylon Films Market |
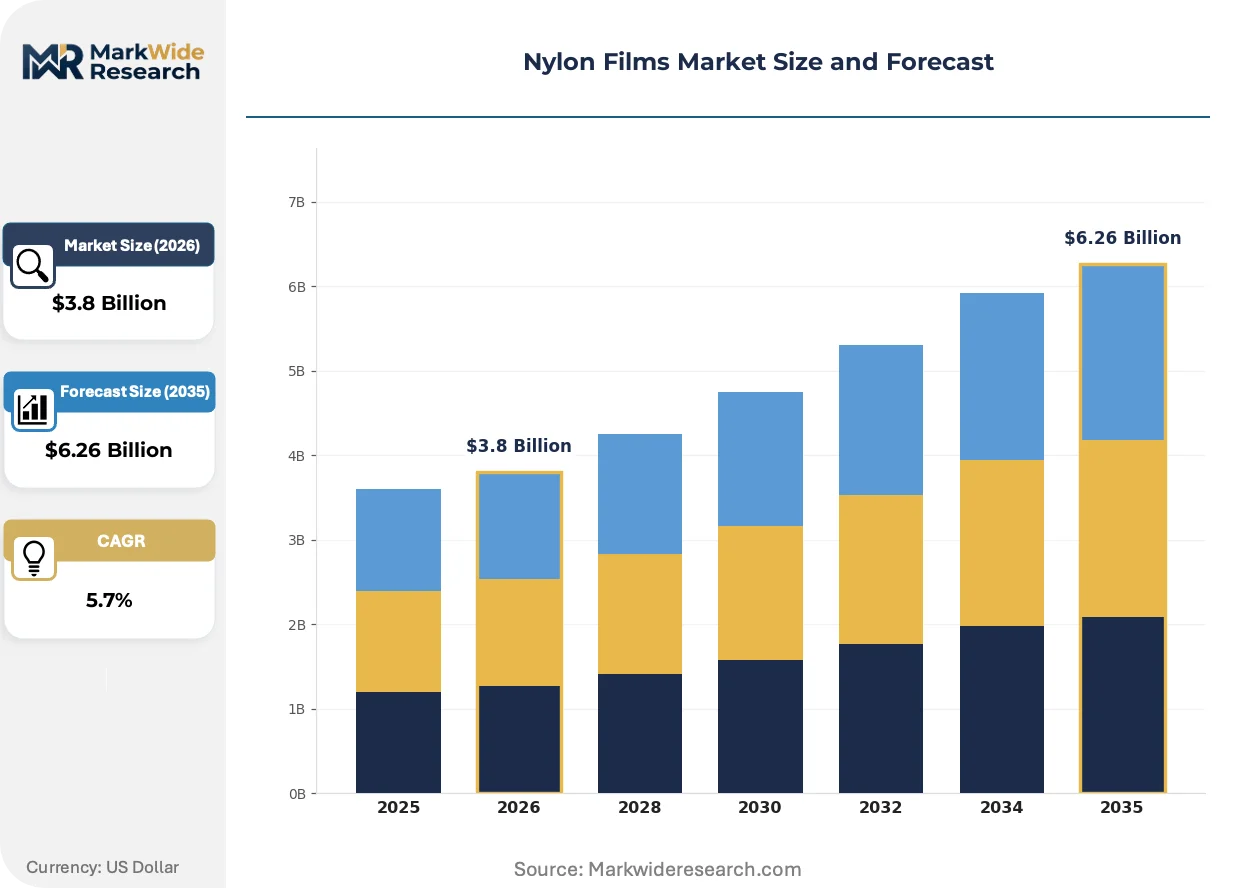
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cast Nylon, Extruded Nylon, Nylon 6, Nylon 66 Application: Packaging, Automotive Parts, Electrical Insulation, Medical Devices End User: Consumer Goods, Industrial, Healthcare, Food & Beverage Thickness: Thin Film, Medium Film, Thick Film, Ultra-Thin Film |
| Companies Covered | FlexFilm, GMP, COSMO Films, Ipak, Royal Sovereign, Transilwrap, Derprosa, Drytac, D&K, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nylon Films Market Strategic Shifts
Barrier film architecture is undergoing fundamental redesign as recyclability certification displaces pure performance metrics in buyer evaluation criteria. Three forces are reshaping competitive positioning.
Monomaterial nylon structures are fragmenting the conventional coextrusion market. Cast film lines in Germany and Italy are being retrofitted to produce all-polyamide barrier webs without polyethylene tie layers. Meat processors in France and the Netherlands are qualifying these films for vacuum skin packaging despite modest oxygen barrier trade-offs. The technology is fragmenting supplier hierarchies by elevating resin compounders with recycling certification over traditional film converters.
REACH chemical migration protocols are tightening formulation choices for food-contact applications. ECHA's 2024 updates to Annex XVII restricted substances lists are phasing out specific phthalate adjuncts used in nylon plasticization. Film manufacturers serving dairy and ready-meal segments are reformulating with bio-based plasticizers or shifting to unplasticized high-viscosity grades. Medical device packaging in Germany is experiencing the most acute compliance pressure due to dual food-contact and pharmaceutical-grade requirements.
Buyer evaluation criteria are rotating toward certified circularity metrics. Procurement teams at major European retailers are embedding recyclability scores alongside technical specifications in supplier scorecards. This behavioral shift is compressing demand for conventional multilayer films while elevating suppliers with third-party mechanical recycling certifications. The transformation is most visible in German and Austrian private-label food packaging programs, where extended producer responsibility fees now penalize non-recyclable structures.
Nylon Films Market Segmentation

Nylon film specifications diverge sharply across end-use requirements, with medical and automotive segments demanding precision tolerances while packaging volumes drive scale economics. Understanding where margin pools concentrate versus where tonnage accumulates shapes supplier portfolio decisions.
Product Type:
Cast Nylon commands premium pricing in applications where dimensional stability trumps raw material cost, while commodity extruded grades compete on throughput efficiency.
- Cast Nylon:Manufactured through solvent-free casting processes yielding superior surface finish and thickness uniformity. Medical device blister packs in Germany and precision electrical insulation in Japan absorb volumes where tolerances tighten below ±2%, with REACH-compliant formulations qualifying for pharmaceutical primary packaging.
- Extruded Nylon:Produced via melt extrusion at higher throughput rates with broader thickness variation acceptance. Food packaging converters in France and the Netherlands favor extruded grades for vacuum skin applications where oxygen barriers below 0.5 cc/m²/day offset modest dimensional trade-offs.
- Nylon 6:Caprolactam-based polymer dominating tonnage through lower monomer cost and processing flexibility. Automotive under-hood specifications in Germany and industrial belting applications across Italy represent core demand clusters.
- Nylon 66:Hexamethylenediamine-adipic acid condensation polymer with superior thermal resistance. Electric vehicle powertrain compartments requiring continuous service above 150°C are displacing commodity polyesters in German and South Korean automotive supply chains.
The dominant share belongs to Nylon 6, while Nylon 66 is closing the gap fastest.
Application:
Packaging tonnage dwarfs other segments, yet medical and automotive specifications extract disproportionate value through certification barriers and technical qualification timelines.
- Packaging:Encompasses flexible food wrapping, vacuum skin formats, and high-barrier meat and cheese applications. German and French retailers are qualifying monomaterial nylon structures for extended shelf-life protein packaging under EU Packaging and Packaging Waste Regulation recyclability mandates.
- Automotive Parts:Under-hood thermal shields, wire harness insulation, and battery component separators. German OEMs specify Nylon 66 films for electric vehicle power electronics where continuous temperatures exceed conventional polyester limits.
- Electrical Insulation:Motor slot liners, transformer barriers, and capacitor dielectrics requiring dielectric strength above 15 kV/mm. Japanese industrial equipment manufacturers and German switchgear producers maintain stringent thickness control requirements.
- Medical Devices:Sterile barrier systems, pharmaceutical blister packs, and implantable device packaging. FDA migration testing protocols and EMA medical device regulations impose dual compliance burdens that extend qualification timelines.
Packaging retains volume leadership, though medical device applications are expanding most quickly.
End User:
Healthcare procurement teams embed recyclability scores alongside technical specifications, while food and beverage buyers prioritize barrier performance at cost parity.
- Consumer Goods:Personal care packaging, household product overwrap, and durable goods protective films. German private-label retailers are penalizing non-recyclable multilayer structures through extended producer responsibility fee adjustments.
- Industrial:Conveyor belting, machinery wear strips, and pneumatic tubing applications. Italian and German machinery OEMs specify cast nylon thickness control for precision component integration.
- Healthcare:Pharmaceutical primary packaging, sterile barrier systems, and diagnostic device formats. EMA medical device regulations and FDA migration testing protocols create dual jurisdictional compliance requirements for suppliers serving German and US markets simultaneously.
- Food & Beverage:Vacuum-packed meat, cheese barrier webs, and ready-meal lidding. ECHA Annex XVII phthalate restrictions are disqualifying conventional plasticized films and accelerating qualified Nylon 6 formulations for dairy applications.
Food and beverage maintains the largest installed base, while healthcare is gaining share fastest.
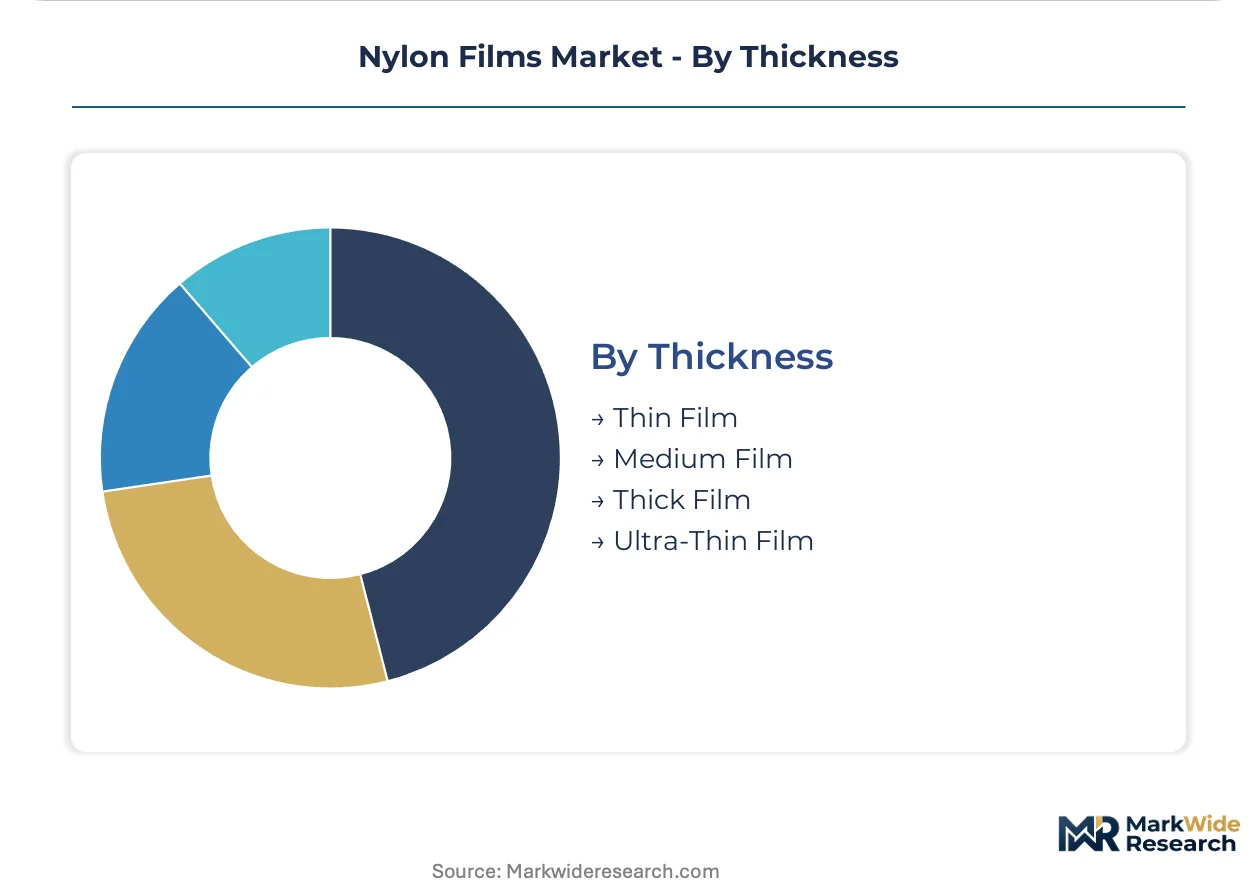
Thickness:
Downgauging programs in packaging are compressing average calipers while medical and electrical segments defend thicker specifications for functional integrity.
- Thin Film:12-25 micron calipers dominating flexible food packaging volumes. French and Dutch meat processors are qualifying downgauged structures that maintain barrier properties at reduced material intensity.
- Medium Film:25-50 micron range serving industrial laminates and medium-duty packaging. German automotive suppliers specify medium calipers for wire harness insulation where puncture resistance balances flexibility.
- Thick Film:50-100 micron specifications for heavy-duty industrial and electrical insulation. Japanese transformer manufacturers and German switchgear producers require dielectric consistency across thicker sections.
- Ultra-Thin Film:Below 12 micron developments targeting premium electronics and advanced medical formats. South Korean display component manufacturers and German pharmaceutical blister pack converters are piloting sub-10 micron cast nylon for space-constrained applications.
Thin Film holds the dominant position, while Ultra-Thin Film is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances are reshaping nylon film trade flows as European converters seek qualified suppliers for REACH-compliant food-contact grades while Asian producers expand calibrated capacity for humidity-sensitive markets.
Germany
Automotive under-hood specifications and medical device blister formats absorb premium cast nylon volumes. ECHA's REACH Annex XVII enforcement tightens migration limits for food-contact polymers. Advanced coextrusion lines in Bavaria and Baden-Württemberg supply automotive-grade specifications across the continent.
United States
FDA migration testing protocols and electric vehicle powertrain thermal requirements pull qualified nylon 66 formulations. EPA chemical safety reviews extend qualification timelines for novel food-contact grades. Midwestern resin compounders and Southeastern film converters serve protein packaging and industrial belting clusters.
China
Domestic caprolactam capacity expansion and electric vehicle battery component demand drive Nylon 6 film consumption. MIIT industrial standards and GB food-contact regulations shape formulation compliance. Yangtze River Delta processors supply precision electrical insulation for Japanese and South Korean OEMs.
India
Blown film demand concentrates in Maharashtra and Gujarat where local humidity conditions require modified resin formulations. FSSAI food safety standards and BIS polymer specifications create dual compliance thresholds. Regional converters exploit white space left by multinational suppliers lacking climate-calibrated product lines.
France
Vacuum skin packaging qualification for monomaterial nylon structures accelerates under EU Packaging and Packaging Waste Regulation mandates. ANSM pharmaceutical-grade requirements extend to medical device packaging formats. Meat processors in Île-de-France and Auvergne-Rhône-Alpes pilot recyclable barrier webs for extended shelf-life proteins.
Nylon Films Market Competitive Environment
Listed leaders compete with private specialists across resin compounding and film conversion capabilities. The supplier base fragments between captive resin producers with recycling certification and independent converters dependent on merchant polymer supply. Three archetypes dominate: vertically integrated compounder-converters, regional blown film specialists, and precision cast film engineers. Competitive moves concentrate on monomaterial architecture retrofits and third-party mechanical recycling certification acquisition.
Among the integrated compounder-converter tier, FlexFilm exemplifies captive resin strategy through in-house Nylon 6 formulation control. COSMO Films anchors South Asian positioning with humidity-calibrated blown film operations. GMP occupies the precision cast film vector where thickness tolerance below ±2% qualifies medical and pharmaceutical applications. These three represent distinct capability anchors rather than overlapping competitive terrain.
| Leading Market Players |
|---|
| FlexFilm |
| GMP |
| COSMO Films |
| Ipak |
| Royal Sovereign |
| Transilwrap |
| Derprosa |
| Drytac |
| D&K |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts with caprolactam suppliers lock in both resin access and margin visibility for German and Chinese film extruders, insulating qualified producers from benzene feedstock volatility that compresses spot-market competitors. These arrangements concentrate pricing power with backward-integrated compounders while forcing merchant-dependent converters into shorter-cycle exposure.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with REACH-certified medical grades commanding substantial premiums over commodity packaging tiers. Price differentiation rests on certification grade and captive resin compounding, with automotive under-hood specifications extracting the least elasticity. Pricing pressure stems from caprolactam cost compression in Asian merchant supply, squeezing independent converters without upstream integration. Food packaging procurement teams exhibit highest price sensitivity, while pharmaceutical blister format buyers prioritize dimensional tolerance over unit economics.
Supply Chain Analysis
Inventory cycles stretch to 8-12 weeks for specialty cast grades as qualified resin batches undergo migration testing protocols before release. Supply concentrates in Germany, China, and India, with Bavarian coextrusion lines feeding automotive specifications across Europe and Yangtze River Delta processors supplying Japanese electrical insulation demand. Raw material chains draw from benzene-derived caprolactam, hexamethylenediamine for Nylon 66, and bio-based plasticizer alternatives under ECHA Annex XVII pressure. Single-source vulnerability sits with European REACH-compliant resin supply, where qualified compounder capacity remains constrained. Distribution runs through direct mill relationships for automotive and medical tiers, with merchant distributors serving fragmented packaging converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Nylon films constitute a regulatory-entrenchment defensive moat, where REACH compliance timelines and FDA migration testing protocols create qualification barriers that extend 18-36 months for new resin formulations. Switching costs for qualified medical and automotive specifications protect incumbent positioning against commodity substitution.
For Market Incumbents: Consolidate captive resin compounding capacity in Germany and China to defend margin position against benzene feedstock volatility. Acquire third-party mechanical recycling certification ahead of EU Packaging and Packaging Waste Regulation enforcement, as extended producer responsibility fees increasingly penalize non-recyclable multilayer structures. Deepen coextrusion line retrofits for monomaterial architectures before qualification windows close for major French and Dutch meat processors.
For New Entrants and Emerging Players: Humidity-calibrated blown film formulations for Maharashtra and Gujarat climates represent an under-served service layer where multinational suppliers lack localized product optimization. Target India regional converters with modified resin specifications and technical field support that incumbent distributors do not provide. Pursue white-label supply arrangements with South Asian flexible packaging OEMs before captive multinational capacity expands.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated compounder-converters with recycling certification and pharmaceutical-grade qualification timelines. Long-term viability over the next decade hinges on monomaterial architecture transition completion and circular economy credential accumulation. Watch for ECHA Annex XVII enforcement acceleration as the inflection signal that disqualifies conventional plasticized film inventories and triggers replacement demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Caprolactam | Captive resin supply insulates German extruders from benzene volatility and REACH compliance delays. |
| Monomaterial Architecture Retrofit | Coextrusion line requalification secures EU recyclability certification before extended producer responsibility fees escalate. |
| Humidity-Calibrated Formulation Development | Localized resin optimization captures Maharashtra and Gujarat blown film demand underserved by multinational suppliers. |
| Mechanical Recycling Certification | Third-party validation qualifies films for German and Austrian private-label procurement scorecards embedding circularity metrics. |
| Medical Device Blister Format Expansion | Cast nylon thickness control below ±2% opens pharmaceutical primary packaging previously served by PVC and PVDC. |
Study Parameters
A spread of perspectives from extrusion plant managers, automotive Tier 1 procurement leads, pharmaceutical packaging engineers, and REACH compliance consultants converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation through ECHA regulatory filings, FDA food-contact notification databases, customs trade data, and SEC disclosures from listed resin compounders. Bottom-up volume modeling across cast and extruded product categories triangulated against top-down macroeconomic demand drivers.
Segmentation dimensions modeled include product type, application, end-use industry, thickness tier, and regional regulatory cluster across the analysis window. CAGRs were derived from elasticity-adjusted demand projections and capacity expansion announcements. Forecast inputs incorporated electric vehicle thermal specification adoption curves, ECHA enforcement trajectory assumptions, and downgauging program penetration in European protein packaging.
Underlying assumptions cover caprolactam price stability, REACH Annex XVII enforcement timing, and mechanical recycling infrastructure deployment, with deviation risk concentrated in benzene derivative volatility and FDA review period extension. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
In-Mould Label Film Market
Poly film
Isotropic Film Market
Poly film
Mexico Plastic Packaging Films Market
Poly film
Polylaminate Capsules Market
Poly film
Biaxially Oriented Polypropylene (BOPP) Films Market
Poly film
Middle East and Africa Plastic Packaging Films Market
Poly film
Americas Polypropylene (PP) Films Market
Poly film
Polybag Mailers Market
Poly film
Peelable and Resealable Films Market
Poly film
Polyurethane (PU) Film Market
Poly film
Germany Plastic Packaging Films Market
Poly film
Metallized Film Market
Poly film
Starch-Based Plastic Films Market
Poly film
Poly Tubing Market
Poly film
PVC Film for Medical Market
Poly film
MOPP Packaging Films Market