
 Antibody Drug Conjugates Contract Manufacturing Market | 2026-2036
Antibody Drug Conjugates Contract Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Antibody Drug Conjugates Contract Manufacturing Market Intelligence
Biopharma outsourcing channels are rewriting how antibody drug conjugates reach clinical and commercial stages. Lonza Group anchors European high-potency manufacturing through its Visp campus network. WuXi Biologics extends multi-modal biologics capacity across China and Ireland. Samsung Biologics dominates large-scale mammalian cell culture for ADC antibody supply.
Antibody drug conjugates contract manufacturing involves the outsourced production of monoclonal antibodies covalently linked to cytotoxic payloads via cleavable or non-cleavable linkers, requiring containment infrastructure for highly potent active pharmaceutical ingredients and validated conjugation chemistry under GMP conditions. The primary purpose is enabling biopharma developers to access specialized manufacturing without capital-intensive facility buildouts. Clinical-stage manufacturing leads volume demand as pipeline candidates advance through Phase II and III trials, while commercial production commands premium pricing due to validated process consistency requirements. Oncology applications concentrate the largest share of client programs, with immunology representing an emerging demand vector as payload diversification expands beyond cytotoxic mechanisms.
FDA, EMA, and ISO 13485 standards govern ADC contract manufacturing through potency assay validation, linker stability specifications, and contamination control protocols that determine facility qualification timelines. These frameworks shape market access by restricting high-potency handling to certified sites with demonstrated containment engineering. Stakeholders must monitor regulatory convergence on conjugation process analytical technology as agencies harmonize expectations for real-time release testing.
Market Dynamics
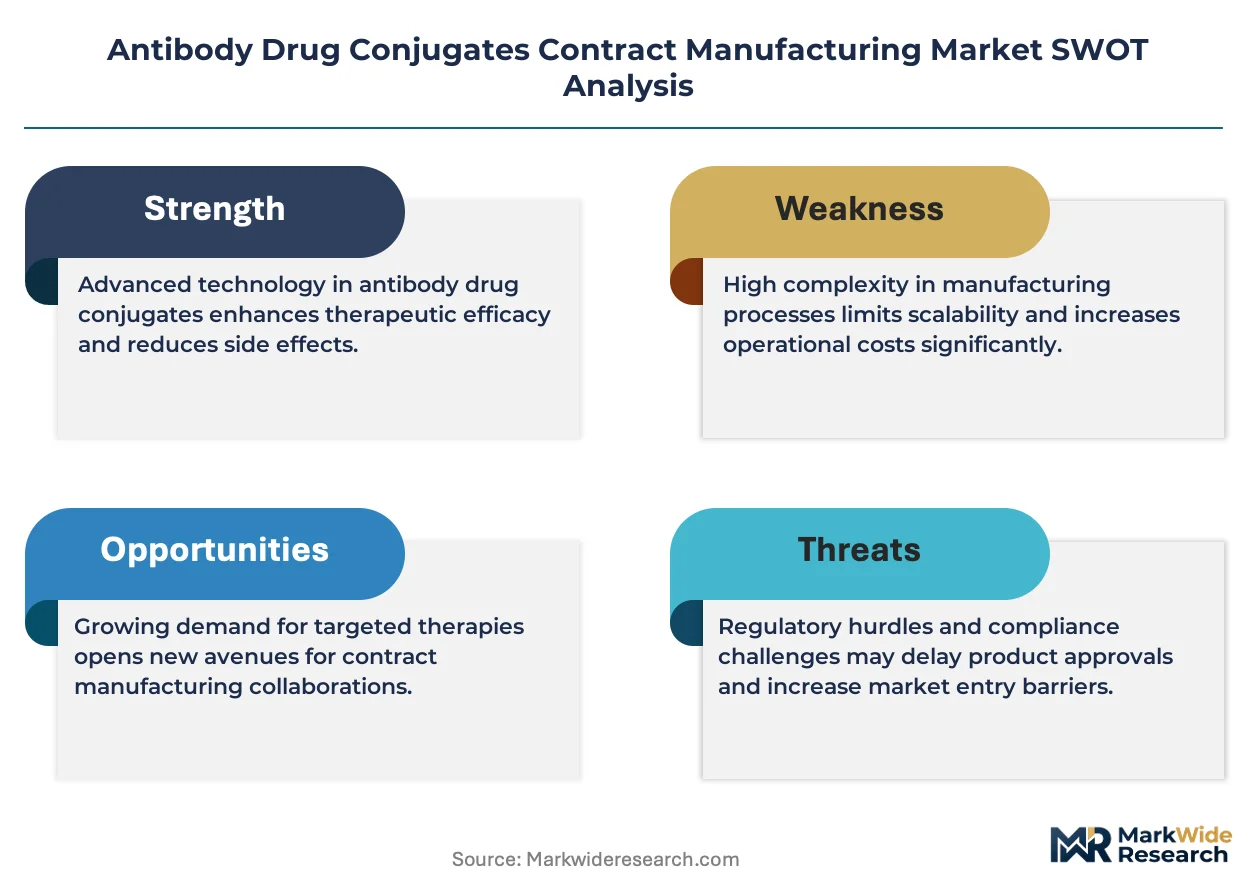
ADC contract manufacturing is consolidating around containment-engineering capabilities as FDA and EMA potency limits force biopharma sponsors toward certified high-potency facilities rather than in-house buildouts.
Growth Catalysts
- EMA tightened occupational exposure limits:Biopharma developers now require external partners with validated isolator technology and closed-system conjugation infrastructure.
- Payload diversification beyond cytotoxics:Immunology and inflammation indications are expanding ADC pipelines into new therapeutic areas requiring specialized linker chemistry expertise.
- Switzerland:Swissmedic's streamlined biologics approval pathways attract Phase III manufacturing commitments from US and European sponsors seeking regulatory convergence.
Market Restraints
- Auristatin and maytansinoid payload costs:Cytotoxic small-molecule supply concentrates with limited qualified API manufacturers, creating input price volatility.
- South Korean antibody supply dominance:Mammalian cell culture capacity for ADC antibody components clusters with Samsung Biologics, creating single-source risk for conjugation partners.
- Linker stability validation:FDA requires extended real-time stability data for cleavable linker platforms, extending program timelines.
Strategic Opportunities
- India:CDSCO's expanding biologics manufacturing framework and lower capex requirements create white space for high-potency containment facilities serving mid-tier biopharma.
- Site-less conjugation models:Modular manufacturing units with pre-qualified equipment skids enable rapid capacity deployment without permanent facility investment.
- ISO 13485 harmonization with FDA potency standards:Dual-certified facilities gain preferential access to both diagnostic and therapeutic ADC programs.
Industry Challenges
- Containment engineering talent scarcity:Qualified process engineers with isolator validation experience command premium compensation, constraining facility expansion timelines.
- Legacy antibody supply agreements:Biopharma sponsors hold long-term mammalian cell culture contracts with non-ADC-specialized CMOs, creating integration friction with conjugation partners.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antibody Drug Conjugates Contract Manufacturing Market |
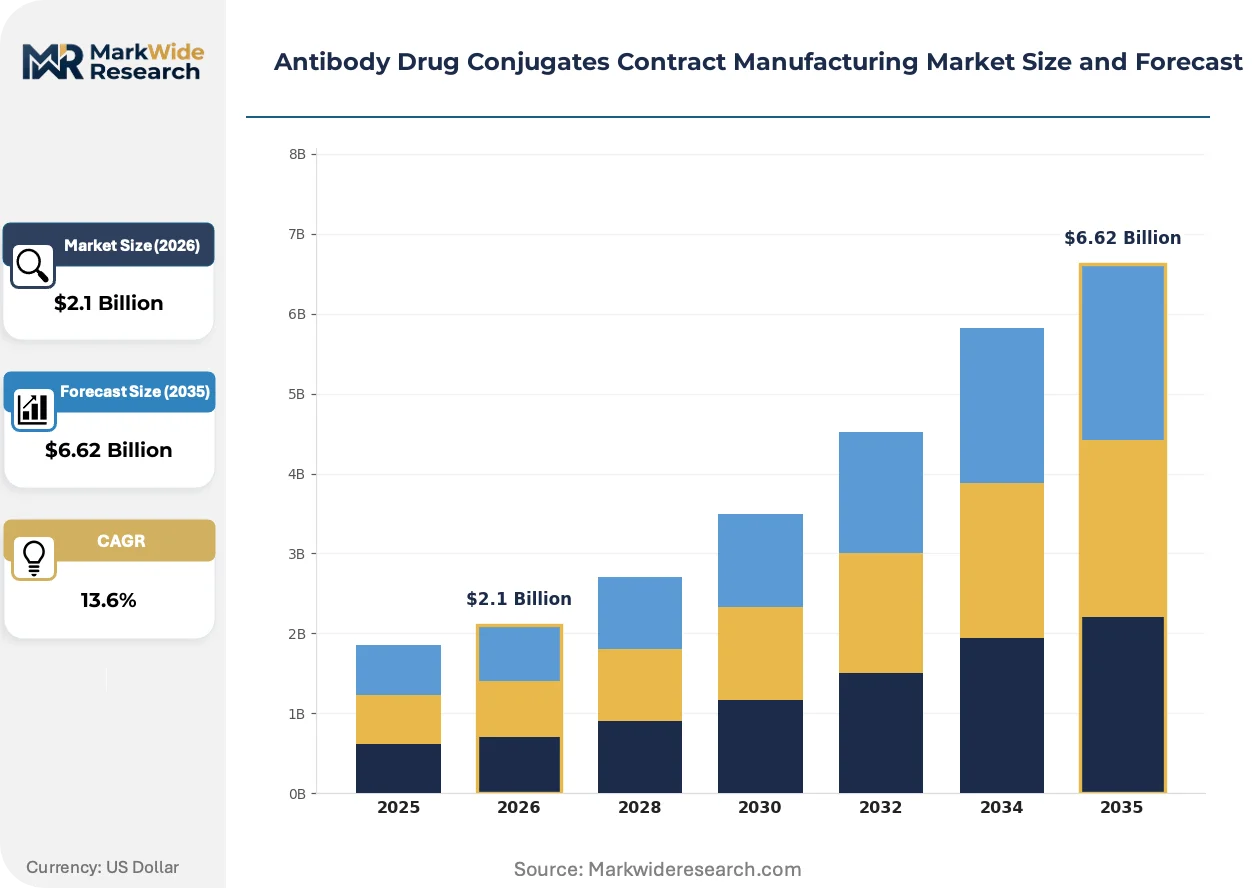
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $6.62 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Preclinical, Clinical, Commercial, Research Delivery Mode: Intravenous, Subcutaneous, Oral, Topical Client Type: Pharmaceutical Companies, Biotech Firms, Research Institutes, Contract Research Organizations Application: Oncology, Immunology, Neurology, Rare Diseases |
| Companies Covered | WuXi Biologics, Recipharm AB, Lonza Group, KBI Biopharma, Curia, Catalent Inc., Piramal Pharma Solutions, Abzena PLC, Samsung Biologics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antibody Drug Conjugates Contract Manufacturing Market Strategic Shifts & Innovations
Process analytical technology is compressing batch release timelines while regulatory agencies converge on real-time potency verification standards. These shifts are redrawing competitive boundaries between integrated and specialized manufacturing models.
Digital twin platforms for conjugation process development are virtualizing traditional scale-up workflows. Mid-cap biopharma sponsors deploy these simulations to de-risk tech transfer before committing to GMP manufacturing slots. The technology is virtualizing physical pilot-scale runs, reducing API consumption and accelerating IND-enabling timelines.
EMA's updated guideline on manufacturing of biological medicinal products tightens documentation requirements for multi-step bioconjugation processes. Contract manufacturers must now demonstrate continuous process verification across antibody production, linker-payload synthesis, and conjugation chemistry. European facilities with integrated antibody and conjugation capabilities capture disproportionate sponsor interest.
Biopharma procurement teams now unbundle antibody supply from conjugation services, creating dual-vendor structures that compress switching costs. Large sponsors maintain antibody relationships with mammalian culture specialists while sourcing conjugation from high-potency containment experts. This pattern is most visible among US oncology developers with multiple ADC candidates in parallel Phase II trials.
Antibody Drug Conjugates Contract Manufacturing Market Segmentation
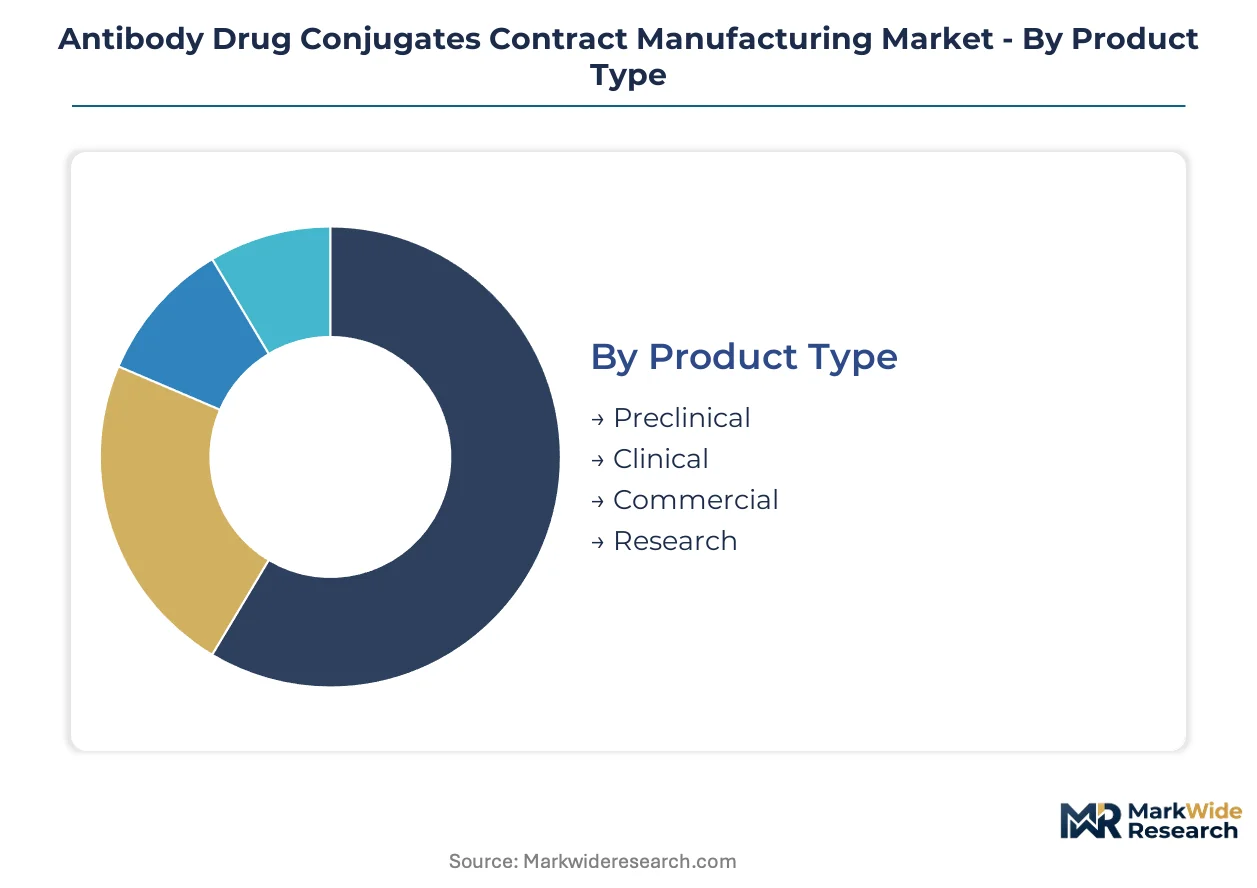
ADC contract manufacturing segmentation reveals how service intensity varies across development phases and client sophistication. Technical support requirements, regulatory documentation depth, and containment engineering specifications differ materially between preclinical screening batches and validated commercial supply.
Product Type:
After-sales service intensity escalates dramatically from preclinical through commercial stages, with GMP compliance documentation and regulatory filing support becoming dominant cost drivers at later phases.
- Preclinical:Small-batch conjugation runs for in vitro and in vivo characterization studies require rapid turnaround rather than extensive validation packages. Demand concentrates with US biotech firms advancing discovery programs through IND-enabling toxicology studies, constrained by limited API availability for exploratory linker-payload combinations.
- Clinical:Phase I through III manufacturing demands validated conjugation processes with documented scalability and regulatory submission support. Sponsors in Switzerland and the United States prioritize partners with FDA and Swissmedic inspection histories, driven by tightening EMA potency limit compliance requirements.
- Commercial:Large-scale GMP supply with validated stability data and commercial release specifications.
- Research:Non-GMP exploratory batches for internal mechanism-of-action studies.
Clinical holds the largest share; momentum sits with Commercial as approved ADCs expand manufacturing commitments.
Delivery Mode:
Formulation complexity and stability requirements create distinct manufacturing footprints across administration routes, with parenteral formats dominating current ADC infrastructure investment.
- Intravenous:Lyophilized or liquid formulations for hospital infusion require sterile fill-finish capabilities and extended stability validation. US oncology programs concentrate demand here, pressured by FDA requirements for endotoxin control and particulate matter specifications in high-potency handling environments.
- Subcutaneous:Higher concentration formulations with reduced infusion volumes demand advanced formulation science for viscosity management and injection site reaction mitigation. South Korean and Swiss sponsors are expanding programs in this category, seeking differentiated patient administration convenience.
- Oral:Experimental ADC formats with gastrointestinal stability challenges.
- Topical:Localized delivery systems for dermatological or ophthalmological applications.
Intravenous dominates current capacity allocation; subcutaneous is climbing the fastest as sponsors pursue administration differentiation.
Client Type:
Procurement sophistication and technical collaboration depth vary sharply across sponsor categories, determining contract structure and intellectual property handling protocols.
- Pharmaceutical Companies:Large sponsors with established antibody supply chains seek unbundled conjugation services, maintaining dual-vendor structures for risk mitigation. Demand concentrates among US and European oncology developers with parallel Phase II pipelines, driven by internal capacity constraints for high-potency containment.
- Biotech Firms:Emerging sponsors without mammalian cell culture infrastructure require integrated antibody-conjugation partnerships. These clients prioritize CDMOs with platform technology transfer capabilities, constrained by venture funding cycles that compress program timelines.
- Research Institutes:Academic and government laboratories with grant-funded exploratory programs.
- Contract Research Organizations:Service providers extending into manufacturing for vertical capture.
Pharmaceutical companies command the largest contract values; biotech firms represent the steepest expansion trajectory as ADC platform companies proliferate.
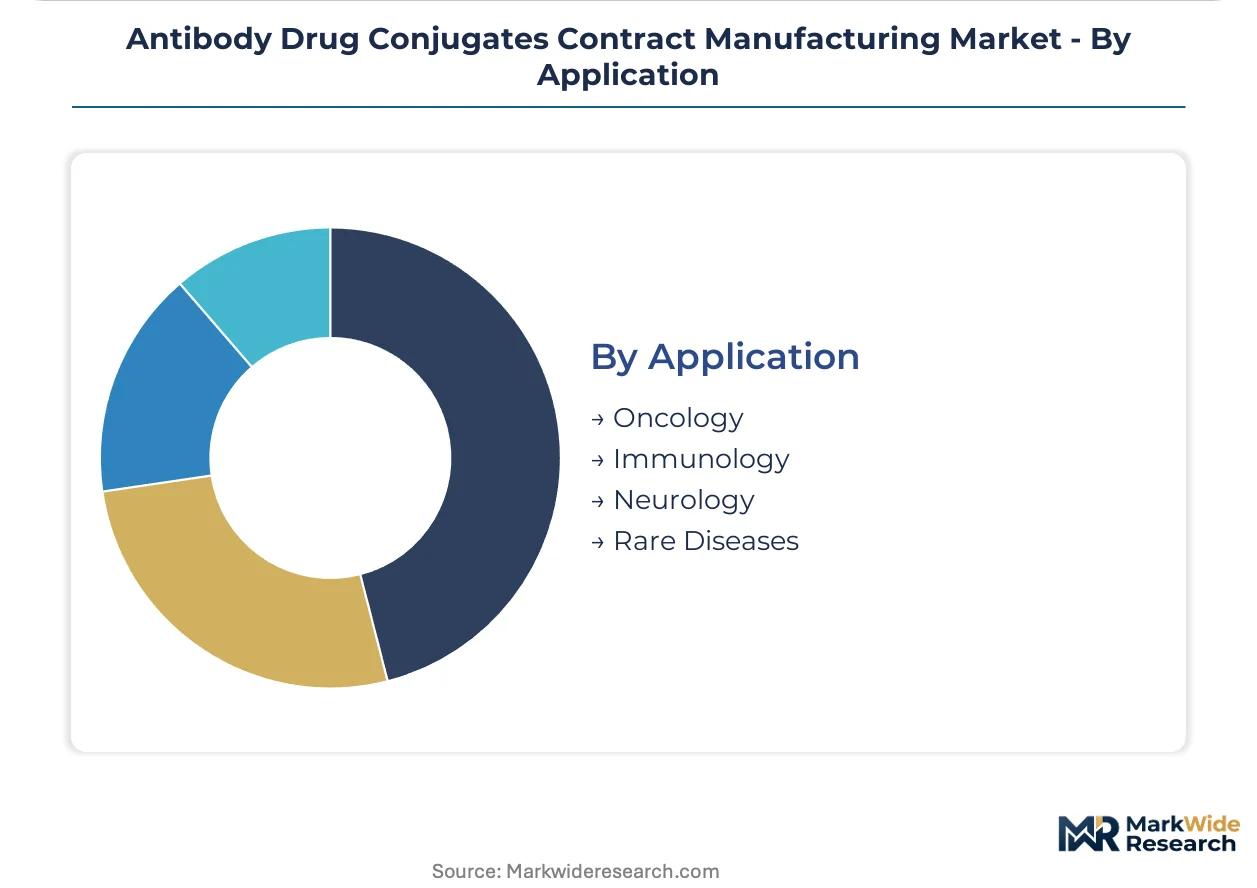
Application:
Therapeutic indication determines payload selection, linker chemistry requirements, and regulatory pathway complexity, with oncology establishing the baseline technical standards.
- Oncology:Cytotoxic payloads targeting proliferating cells remain the dominant application, with auristatin and maytansinoid conjugates requiring the most mature containment infrastructure. US and Swiss sponsors drive demand here, facing EMA and FDA convergence on real-time release testing standards for cleavable linker platforms.
- Immunology:Non-cytotoxic payloads including immune modulators and anti-inflammatory agents are expanding pipeline diversity. These programs concentrate with European biotech firms, constrained by limited precedent for regulatory approval pathways outside oncology.
- Neurology:Blood-brain barrier penetration challenges for antibody-based delivery.
- Rare Diseases:Small-patient-population indications with accelerated regulatory pathways.
Oncology holds the largest share; immunology is gaining share fastest as payload diversification extends beyond cytotoxic mechanisms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized biologics corridors anchor ADC contract manufacturing capacity, with pharmaceutical-grade cold chain infrastructure and high-potency containment zones underwriting geographic concentration. Regulatory convergence between FDA and EMA standards drives facility clustering near inspection-capable hubs.
United States
Oncology biopharma sponsors in Massachusetts and California drive clinical-stage demand for conjugation services. FDA potency assay validation requirements restrict high-potency handling to certified isolator facilities. The Greater Boston corridor concentrates antibody discovery-to-conjugation pipelines with integrated CDMO campuses.
Switzerland
Swissmedic's streamlined biologics approval pathways attract Phase III manufacturing commitments from European and US sponsors. The country's occupational exposure limit enforcement exceeds EMA baselines, favoring validated containment engineering. The Basel-Visp biotech corridor hosts multi-modal biologics infrastructure with conjugation specialization.
South Korea
Samsung Biologics anchors mammalian cell culture supply for ADC antibody components, creating downstream demand for conjugation partners. MFDS alignment with FDA inspection standards accelerates regulatory filing timelines. The Songdo biocluster integrates large-scale antibody production with specialized linker-payload handling capabilities.
Germany
EMA guideline implementation on multi-step bioconjugation documentation tightens facility qualification requirements. The country's chemical-pharma hybrid infrastructure supports linker-payload synthesis integration. The Rhine-Main and Bavarian biotech regions concentrate containment-engineering talent for high-potency manufacturing.
India
CDSCO's expanding biologics manufacturing framework creates white space for mid-tier biopharma seeking lower capex containment solutions. The country's API synthesis heritage supports payload diversification beyond traditional cytotoxics. Hyderabad and Bangalore bioclusters incubate modular high-potency facility deployments.
Antibody Drug Conjugates Contract Manufacturing Market Key Industry Players
On the supply side, the industry is consolidating around containment-engineering capabilities as regulatory potency limits force sponsor migration toward certified high-potency facilities. Three archetypes dominate: integrated antibody-to-conjugation platforms, specialized conjugation-only providers, and mammalian cell culture specialists extending into downstream services. Capacity expansion and strategic technology licensing represent the dominant competitive vectors as players race to secure validated isolator infrastructure.
Within the integrated platform tier, Lonza Group and WuXi Biologics exemplify multi-continental biologics infrastructure with conjugation capabilities spanning European and Asian manufacturing nodes. Samsung Biologics occupies a distinct position as a scale-driven antibody supply anchor, while specialized conjugation providers such as Abzena PLC represent the focused-service archetype targeting sponsors with unbundled procurement strategies.
| Leading Market Players |
|---|
| WuXi Biologics |
| Recipharm AB |
| Lonza Group |
| KBI Biopharma |
| Curia |
| Catalent Inc. |
| Piramal Pharma Solutions |
| Abzena PLC |
| Samsung Biologics |
| Others |
Cost & Logistics Intelligence
Undercapacity in validated high-potency isolator facilities across the United States and Switzerland compresses available manufacturing slots and hardens pricing power for certified CDMOs serving Phase III oncology programs. FDA and EMA potency limit convergence restricts supply expansion timelines, embedding cost premiums into clinical-stage conjugation services.
Pricing Analysis
Volume-discount tiering structures separate commercial-scale commitments from exploratory preclinical batches, with validated GMP slots commanding substantial premiums over non-GMP research runs. Price differentiation hinges on containment certification grade and regulatory inspection history, with dual FDA-EMA qualified facilities extracting maximum value. Cost compression in mid-tier clinical manufacturing intensifies as biotech sponsors consolidate programs with fewer partners. Emerging biotech firms exhibit highest price sensitivity, while large pharmaceutical sponsors prioritize regulatory risk mitigation over unit cost.
Supply Chain Analysis
Contract-manufacturing concentration rests with Lonza Group, WuXi Biologics, and Samsung Biologics, which anchor antibody supply and conjugation capacity across Switzerland, China, and South Korea. Auristatin and maytansinoid payload synthesis draws from limited qualified API manufacturers in the United States and Europe, creating input bottlenecks. Single-source vulnerability concentrates in mammalian cell culture supply, where Samsung Biologics dominates large-scale antibody production. Distribution runs through sponsor-directed dual-vendor structures that unbundle antibody supply from conjugation services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as payload diversification beyond cytotoxic mechanisms creates specialized manufacturing niches for immunology and inflammation ADC programs. Unbundled procurement patterns among large sponsors generate entry points for focused conjugation specialists.
For Market Incumbents: Harden isolator validation capabilities against emerging site-less conjugation models that threaten premium facility economics. Expand containment engineering talent pipelines through specialized training partnerships with Swiss and German technical universities. Prioritize backward integration into linker-payload synthesis to capture margin from auristatin supply constraints. For New Entrants and Emerging Players: India's CDSCO framework expansion offers white-space entry for mid-tier biopharma seeking lower capex containment solutions. Target modular manufacturing deployments in Hyderabad and Bangalore bioclusters. Pursue platform technology transfer partnerships with venture-funded ADC biotechs facing compressed program timelines. For Investors and Strategic Acquirers: Long-term, this sits as a capacity-constrained infrastructure play because regulatory certification timelines prevent rapid supply response to demand expansion. Acquisition candidates include specialized conjugation providers with validated isolator infrastructure and EMA inspection histories. Monitor CDSCO biologics manufacturing framework maturation as inflection signal for Indian market entry viability.| Strategic Initiative | Industry Significance |
|---|---|
| Containment Engineering Talent Expansion | Swiss and German technical university partnerships address qualified process engineer scarcity constraining facility expansion. |
| Modular Manufacturing Deployment | Pre-qualified equipment skids in Indian bioclusters enable rapid capacity deployment without permanent facility investment. |
| Dual-Certification Investment | ISO 13485 harmonization with FDA potency standards gains preferential access to diagnostic and therapeutic ADC programs. |
| Linker-Payload Synthesis Integration | Backward integration into auristatin production mitigates single-source API supply risk and input price volatility. |
| Site-Less Conjugation Platform Development | Virtual process development through digital twin platforms reduces API consumption and accelerates IND-enabling timelines. |
Research Approach
Desk research of FDA filing databases, EMA regulatory submissions, and clinical trial registries preceded structured interviews with drug development executives, regulatory affairs leads, and CDMO procurement managers. Secondary validation drew from GMP inspection records, containment engineering specifications, and biopharma sponsor manufacturing partnership announcements. Bottom-up capacity modeling triangulated against top-down market sizing across service tiers.
Assumptions held regulatory convergence timelines and payload diversification trajectories fixed while varying sponsor outsourcing penetration rates and capacity utilization scenarios across the projection horizon. Segmentation dimensions spanned development phase, delivery mode, client sophistication tier, and therapeutic indication. CAGRs derived from facility investment pipelines, sponsor pipeline advancement rates, and regulatory inspection capacity expansion. Forecast inputs incorporated isolator technology adoption curves and mammalian cell culture capacity commitments.
Practitioners should monitor CDSCO biologics framework implementation, EMA potency limit enforcement actions, and site-less conjugation technology maturation for early signals requiring forecast revision. Quarterly review of validated isolator facility utilization rates, sponsor dual-vendor procurement pattern shifts, and linker-payload API manufacturer qualification timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Services
Aptamers Market
Biotechnology Services
Riboflavin Kinase Market
Biotechnology Services
Drug Discovery Services Market
Biotechnology Services
Europe Recombinant Protein Manufacturing Services Market
Biotechnology Services
Global Vector Control Market
Biotechnology Services
Peptide and Oligonucleotide CDMO Market
Biotechnology Services
Global DNA and RNA Banking Services Market
Biotechnology Services
UK Biotechnology and Pharmaceutical Services Outsourcing Market
Biotechnology Services
Phospho-Specific Antibodies Market
Biotechnology Services
Global Molecular Biology Enzymes and Kits and Reagents Market
Biotechnology Services
Global Vero Cell Media Market
Biotechnology Services
Cell Line Development Market
Biotechnology Services
Cdna Synthesis Market
Biotechnology Services
Drug Discovery and Development Laboratory Services Market
Biotechnology Services
Antibody Purification Service Market
Biotechnology Services
Immunoassays in R & D Market