
 Antibody Purification Service Market | 2026-2036
Antibody Purification Service Market Size, Share, and Industry Trends Forecast 2026-2036
Antibody Purification Service Market Outlook
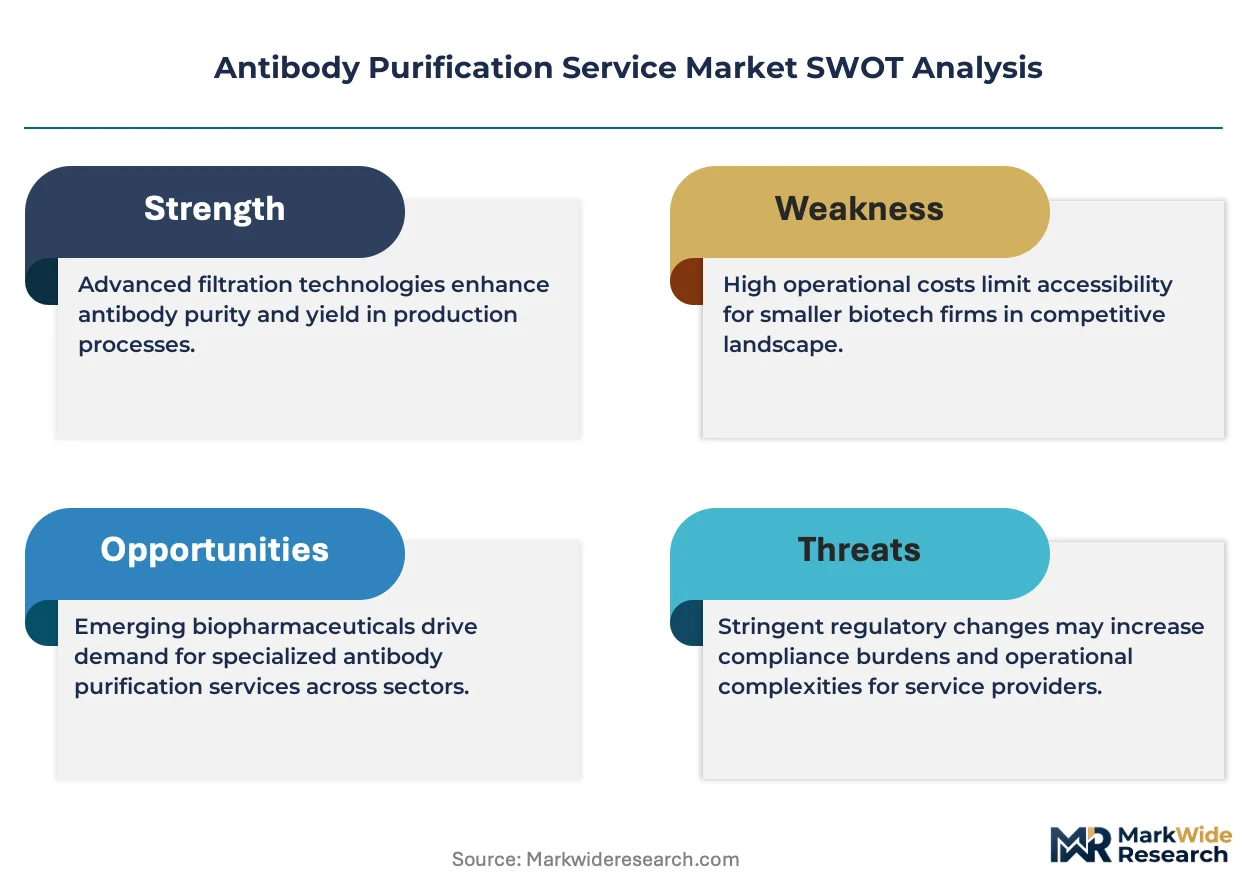
Platform access subscriptions for multi-column chromatography systems is rebalancing how purification capacity gets commercialized, shifting buyers from capital ownership to throughput-based contracting. Thermo Fisher Scientific leverages its instrument-to-service integration to anchor large-molecule programs across North American and European biopharma corridors. GenScript competes on recombinant antibody expression paired with downstream purification bundling, while Creative Biolabs specializes in species-specific polyclonal and monoclonal antibody isolation for research-stage clients.
Antibody purification services encompass the separation, concentration, and polishing of immunoglobulins from complex biological matrices using chromatographic or precipitation methods, typically achieving purity thresholds above 95% for therapeutic-grade material. The primary commercial purpose centers on supplying validated antibody material for diagnostic assay development, therapeutic candidate screening, and regulated biomanufacturing workflows. Affinity chromatography occupies the dominant margin pool due to Protein A resin premiums and established therapeutic validation, while ion exchange chromatography represents the fastest-growing technique dimension as bispecific and fragment-based antibodies drive charge-variant resolution needs. End-user demand from contract research organizations is accelerating fastest as these firms absorb outsourced early-phase biologics development from pharmaceutical companies seeking variable-cost structures.
FDA biologics license requirements and EMA Good Manufacturing Practice guidelines for active substance manufacture enforce purity, potency, and consistency standards that directly shape service provider qualification and facility investment decisions. China's NMPA alignment with ICH Q5A through Q5D guidelines for viral safety and cell-line characterization is expanding accessible contract purification capacity for export-oriented biologics. ISO 13485 certification for diagnostic-grade antibody production and WHO prequalification pathways for therapeutic applications add further compliance layers that stakeholders must monitor as qualification criteria tighten across destination markets.
Market Dynamics
Continuous processing platforms and single-use chromatography systems are compressing purification batch cycles from weeks to days, forcing contract providers to reconfigure facility layouts and staff training programs around flow-based rather than batch-based operational logic.
Growth Catalysts
- Bispecific antibody pipelines:Charge-variant resolution requirements for engineered immunoglobulins are expanding ion exchange chromatography service contracts. CROs in the United States and Germany are absorbing this demand surge.
- EMA Good Manufacturing Practice alignment:Streamlined active substance manufacture guidelines are reducing qualification timelines for European contract purification facilities. This regulatory clarity accelerates facility investment decisions.
- Protein A resin innovation:Synthetic ligand alternatives to traditional Protein A are lowering affinity chromatography cost structures. Service providers are expanding capacity without proportional capital expansion.
Market Restraints
- Resin supply concentration:Protein A resin production concentrates among three specialty chemical suppliers. Any disruption propagates directly into purification service pricing volatility.
- FDA biologics license stringency:Purity, potency, and consistency documentation requirements extend facility qualification timelines. Smaller service providers face capital barriers to full compliance.
- Chromatography system capital intensity:Multi-column continuous processing hardware requires seven-figure facility investments. This capex barrier limits market entry for mid-scale competitors.
Strategic Opportunities
- India biologics export corridor:CDSCO alignment with ICH viral safety guidelines is opening contract purification capacity for Western-market-bound biosimilars. Early entrants capture qualification advantages.
- Cell and gene therapy vectors:Viral vector purification workflows share chromatography infrastructure with antibody platforms. Service providers with existing antibody expertise are cross-training staff for AAV and lentiviral applications.
- Platform access subscriptions:Multi-column chromatography throughput-based contracting replaces capital ownership models. Biotech startups in Boston and San Francisco prefer this variable-cost structure.
Industry Challenges
- Continuous processing skill scarcity:Flow-based chromatography operation requires different expertise than traditional batch methods. Training programs lag equipment installation timelines.
- ISO 13485 diagnostic-grade certification:Antibody production for in vitro diagnostic kits demands separate quality systems from therapeutic GMP. Dual certification stretches quality assurance bandwidth.
- Legacy batch system integration:Hybrid facilities running both continuous and batch workflows face scheduling complexity. Changeover protocols consume operational capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antibody Purification Service Market |
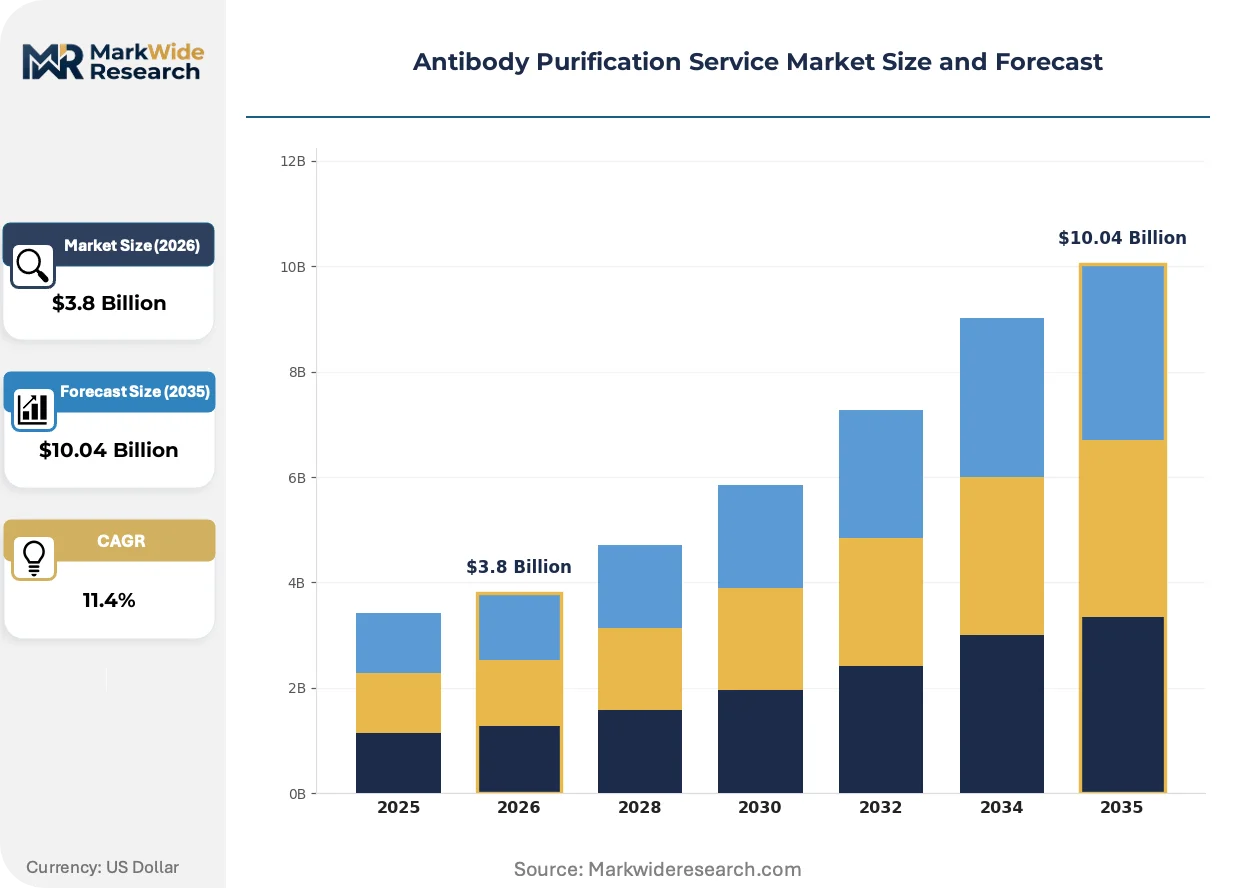
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Affinity Chromatography, Ion Exchange Chromatography, Size Exclusion Chromatography, Precipitation End User: Pharmaceutical Companies, Biotechnology Firms, Academic Institutions, Contract Research Organizations Application: Research and Development, Diagnostic Applications, Therapeutic Production, Quality Control Technique: Recombinant Technologies, Direct Isolation, Ultrafiltration, Dialysis |
| Companies Covered | Thermo Fisher Scientific, GenScript, Sino Biological Inc., Bio-synthesis Inc, Antibody Research Corporation, Creative Biolabs, ProteoGenix, Abcam, Rockland, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antibody Purification Service Market Strategic Shifts
Modular hardware architectures and software-defined chromatography control systems are enabling rapid reconfiguration of purification trains, collapsing the traditional distinction between platform processes and custom method development.
Single-use chromatography skids with pre-qualified flow paths are modularizing how purification capacity gets deployed across multi-product facilities. Biotech startups with unpredictable pipeline progression prefer this flexibility over fixed stainless-steel installations. The structural consequence is compressing the minimum efficient scale for contract purification operations.
China's NMPA implementation of ICH Q5A through Q5D guidelines for viral safety and cell-line characterization is harmonizing export-oriented biologics standards with FDA and EMA expectations. Domestic contract purification providers are qualifying under this framework to capture Western-market-bound biosimilar contracts. The most affected segment is mammalian cell culture-derived monoclonal antibodies destined for regulated markets.
Antibody discovery biotechs are consolidating their vendor base around integrated expression-to-purification service bundles rather than fragmenting across separate molecular biology and downstream specialists. CDMOs offering seamless handoffs from transient transfection to GMP drug substance are displacing point-solution providers. This consolidation pattern is most visible in the Boston-Cambridge and San Francisco Bay Area clusters where startup density supports integrated service economics.
Antibody Purification Service Market Segmentation
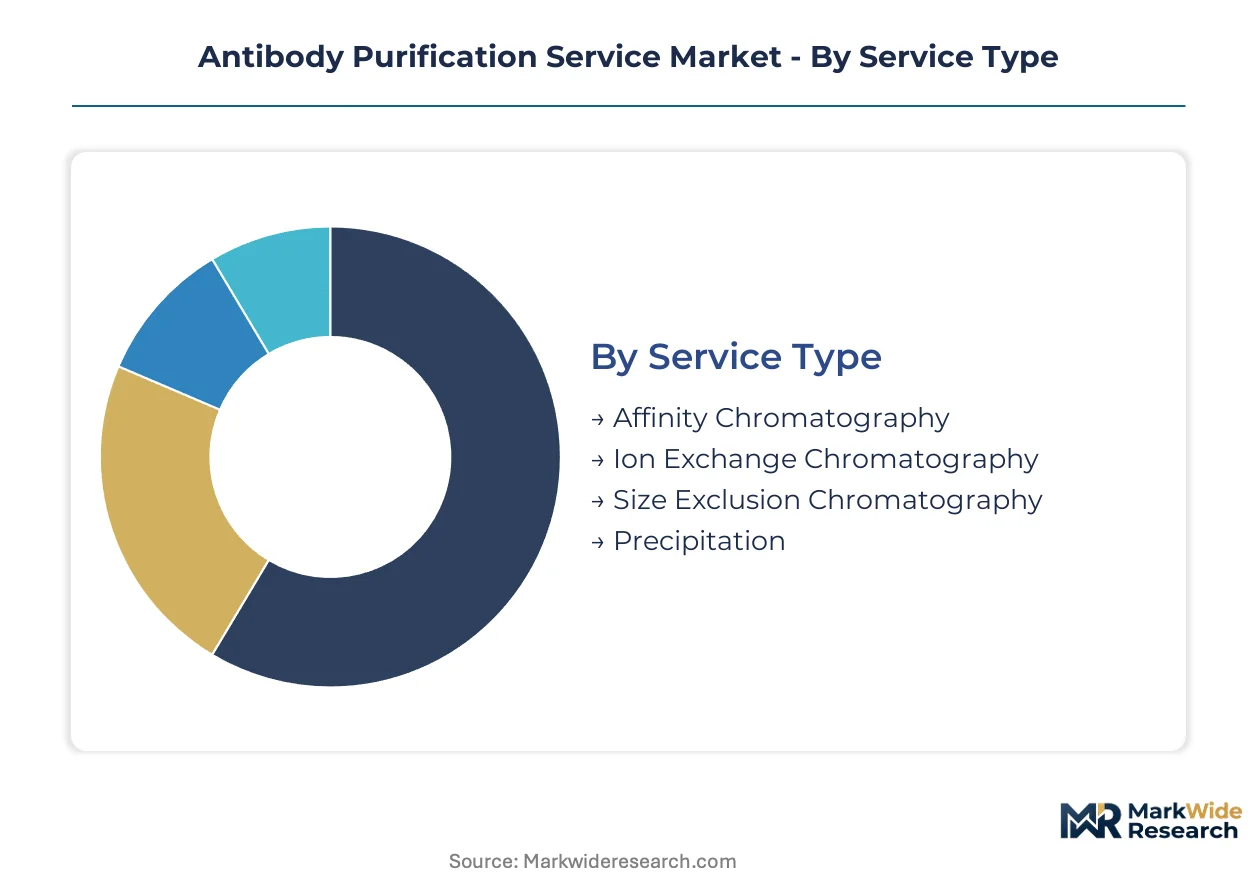
Antibody purification services fragment across four distinct classification axes. Each dimension carries specific technical requirements, regulatory burdens, and margin structures that reshape how service providers configure their commercial and operational strategies.
Service Type:
Chromatographic and precipitation methods separate immunoglobulins based on binding affinity, molecular charge, size, or solubility characteristics.
- Affinity Chromatography:Protein A and synthetic ligand resins capture target antibodies through specific binding interactions, typically achieving purity thresholds above 95% in a single step. Pharmaceutical companies in the United States and Germany absorb the majority of contract capacity here, driven by therapeutic-grade validation requirements and established regulatory pathways.
- Ion Exchange Chromatography:Charge-variant resolution separates antibody species based on surface electrostatic properties, critical for bispecific and fragment-based biologics where charge heterogeneity affects potency. Demand concentrates among CROs in Boston and San Francisco supporting early-phase engineered immunoglobulin programs.
- Size Exclusion Chromatography:Porous bead matrices fractionate molecules by hydrodynamic radius, removing aggregates and fragments from final drug substance preparations.
- Precipitation:Salting-out or solvent-induced protein aggregation offers lower-cost purification for research-grade material where chromatographic resolution exceeds requirements.
Mature deployment sits with affinity chromatography. Newer deployment is concentrated in ion exchange chromatography.
End User:
Customer archetypes span the full biologics value chain from discovery through commercial manufacturing.
- Pharmaceutical Companies:Large-cap drug developers outsource purification capacity for pipeline assets where in-house infrastructure lacks flexibility or regulatory scope. These buyers prioritize GMP qualification and FDA/EMA audit history over unit cost.
- Biotechnology Firms:Venture-backed startups with single-asset pipelines favor platform access subscriptions and single-use chromatography systems that eliminate capital commitment. Variable-cost structures align with unpredictable funding cycles and milestone-dependent progress.
- Academic Institutions:University core facilities and research hospitals drive demand for small-batch, non-GMP purification supporting grant-funded discovery biology.
- Contract Research Organizations:CROs absorb outsourced early-phase biologics development from pharmaceutical sponsors seeking operational leverage. These intermediaries are expanding purification service menus to capture integrated expression-to-drug-substance contracts.
Volume concentration rests with pharmaceutical companies. Fastest expansion is occurring among contract research organizations.
Application:
Purification purpose determines specification stringency, documentation depth, and acceptable yield trade-offs.
- Research and Development:Discovery-stage antibody candidates require rapid turnaround and method flexibility rather than validated reproducibility. Academic and biotech buyers dominate this segment, tolerating batch-to-batch variability for speed and cost containment.
- Diagnostic Applications:In vitro diagnostic kit manufacturing demands ISO 13485 certification and lot-to-lot consistency for assay calibration stability. Purification services here compete on documentation rigor and supply security rather than yield optimization.
- Therapeutic Production:GMP drug substance manufacture for clinical or commercial supply imposes the most stringent purity, potency, and viral safety requirements. FDA biologics license and EMA active substance guidelines directly shape facility investment and qualification timelines.
- Quality Control:Reference standard preparation and release testing support regulatory submission packages and stability programs.
Regulatory burden peaks in therapeutic production. Operational flexibility matters most in research and development.
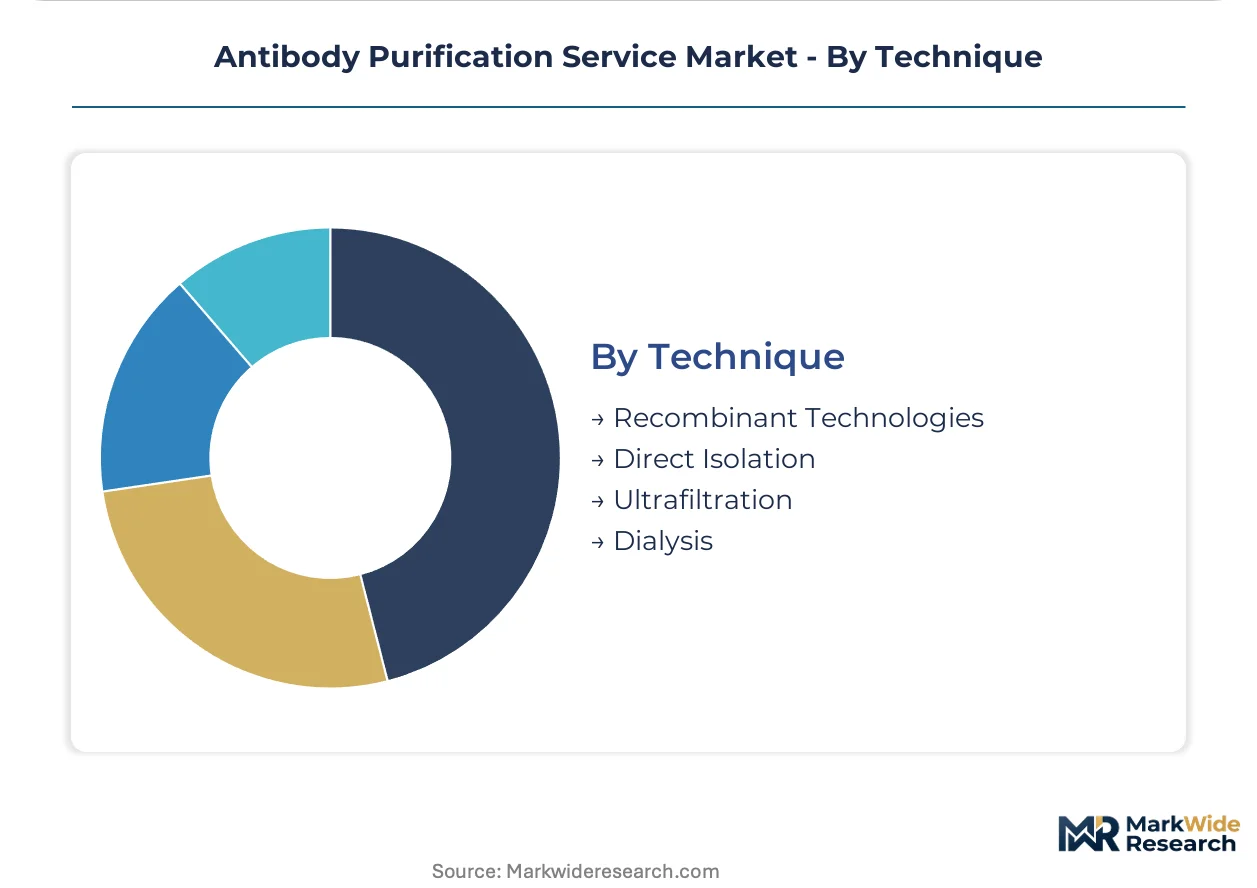
Technique:
Upstream and downstream process modalities determine starting material characteristics and purification train configuration.
- Recombinant Technologies:Mammalian cell culture-derived antibodies from CHO or HEK293 expression systems constitute the dominant commercial input. Chinese contract providers with NMPA-aligned viral safety qualification are capturing export-oriented biosimilar contracts under this technique.
- Direct Isolation:Polyclonal antibody recovery from immunized animal serum supports diagnostic and research applications where species-specific reactivity is required.
- Ultrafiltration:Tangential flow filtration concentrates and diafilters purified antibody solutions, typically deployed as a polishing step following chromatographic capture.
- Dialysis:Buffer exchange through semipermeable membranes removes small-molecule contaminants and adjusts formulation composition for final drug product preparation.
Recombinant technologies anchor commercial scale. Direct isolation retains niche value for specialized reagent supply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston-Cambridge anchors the densest concentration of antibody purification demand, with venture-backed biotech startups outsourcing integrated expression-to-purification workflows to specialized contract providers.
United States
San Francisco Bay Area biotechnology firms absorb single-use chromatography capacity through platform access subscriptions that eliminate capital ownership. FDA biologics license requirements enforce purity documentation standards that stretch qualification timelines for new service entrants. Greater Boston hosts the fastest-growing cluster of CROs expanding purification menus to capture integrated drug substance contracts.
Germany
Baden-Württemberg pharmaceutical manufacturers prioritize GMP-qualified facilities with established EMA audit histories over unit cost considerations. EMA Good Manufacturing Practice alignment for active substance manufacture reduces facility qualification barriers and accelerates capital deployment decisions. The Rhine-Main biopharma corridor concentrates contract purification investment serving Western European therapeutic pipelines.
China
Yangtze River Delta biosimilar exporters drive contract purification demand as NMPA alignment with ICH Q5A through Q5D guidelines opens Western-market access. Domestic service providers qualify under harmonized viral safety standards to capture regulated-market contracts. Shanghai-Suzhou biotech clusters host expanding CDMO capacity targeting export-oriented monoclonal antibody production.
India
Maharashtra-based biosimilar developers seek contract purification partnerships as CDSCO alignment with ICH viral safety guidelines creates Western-market qualification pathways. The country's national pharmaceutical regulator enforces evolving GMP standards that reshape facility investment priorities. Hyderabad-Bengaluru biopharma corridors attract early entrants capturing qualification advantages for export-bound biologics.
Switzerland
Basel-region pharmaceutical headquarters outsource purification capacity for pipeline assets requiring flexible regulatory scope across multiple jurisdictions. Swissmedic therapeutic guidelines enforce consistency standards that directly shape service provider selection criteria. The country's precision manufacturing heritage supports specialized providers serving high-value diagnostic and therapeutic antibody segments.
Antibody Purification Service Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the antibody purification service landscape. Facility ownership concentrates among integrated CDMOs with multi-million dollar chromatography infrastructure, while boutique specialists rent access to shared manufacturing suites. Three archetypes dominate: instrument-to-service integrators bundling hardware with purification contracts, expression-to-purification bundlers capturing seamless handoffs from molecular biology through drug substance, and research-stage specialists isolating species-specific reagents for diagnostic developers. Competitive moves center on capacity expansion in NMPA-aligned Chinese facilities and strategic partnerships linking instrument manufacturers with service providers.
Among North American-anchored integrators, Thermo Fisher Scientific occupies a position exemplifying instrument-to-service bundling across biopharma corridors. GenScript represents the expression-to-purification archetype, pairing recombinant antibody production with downstream processing for variable-cost buyers. Creative Biolabs sits within the research-specialist tier, serving discovery-stage demand for polyclonal and monoclonal isolation.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| GenScript |
| Sino Biological Inc. |
| Bio-synthesis Inc |
| Antibody Research Corporation |
| Creative Biolabs |
| ProteoGenix |
| Abcam |
| Rockland |
| Others |
Value Chain & Pricing Dynamics
GMP-certification tiering separates therapeutic-grade contracts from research-grade services, creating divergent margin pools that reshape how providers configure their supply bases and capacity investments. Pharmaceutical sponsors in the United States and Germany absorb premium pricing for FDA and EMA audit histories, while biotech startups in Boston and San Francisco negotiate throughput-based subscriptions that eliminate capital ownership. This bifurcation concentrates high-value resin purchasing power among qualified CDMOs while pushing commodity service providers toward synthetic ligand alternatives and shared manufacturing suites.
Pricing Analysis
Margin tightening in affinity chromatography reflects Protein A resin supply concentration among three specialty chemical suppliers. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and viral safety documentation depth. Cost-down pressure on ion exchange services accelerates because bispecific antibody pipelines demand charge-variant resolution at scale. Biotechnology firms exhibit highest price sensitivity, prioritizing variable-cost structures over GMP qualification, while pharmaceutical companies accept premium positioning for regulatory risk mitigation.
Supply Chain Analysis
Dual-sourcing requirements for Protein A and synthetic ligand resins mandate multi-supplier qualification among contract providers seeking supply security. Manufacturing concentrates in the United States, Germany, and China where biopharma clusters anchor chromatography system deployment. Raw material dependencies center on agarose bead matrices, recombinant Protein A ligands, and single-use flow path components. Single-source vulnerability in specialty resin production propagates pricing volatility directly into service contracts. Distribution runs through direct CDMO-client relationships with limited intermediary channel penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The antibody purification service market is becoming a vertical-integration race as providers seek upstream control over resin supply and downstream capture of fill-finish drug product capacity. Winners will anchor their economics in captive supply of critical inputs and seamless handoffs from expression through drug substance.
For Market Incumbents: Acquire synthetic ligand technology capabilities to reduce dependency on concentrated Protein A resin suppliers. Expand NMPA-aligned capacity in China's Yangtze River Delta to capture export-oriented biosimilar contracts before qualification windows narrow. Synthetic ligand alternatives and Chinese regulatory alignment represent the priority defensive levers against emerging CDMO competitors. For New Entrants and Emerging Players: CDSCO alignment with ICH viral safety guidelines in India opens a window for early entrants to establish Western-market qualification pathways before incumbent capacity saturates. Target Maharashtra-based biosimilar developers seeking contract purification partnerships with limited existing vendor relationships. Lead with platform access subscriptions that eliminate capital barriers for biotech startups with unpredictable funding cycles. For Investors and Strategic Acquirers: Re-rating potential sits with expression-to-purification bundlers given antibody discovery biotechs consolidating vendor relationships around integrated service workflows. Long-term viability favors CDMOs with simultaneous FDA, EMA, and NMPA qualification spanning the 5-10 year regulatory harmonization window. Monitor NMPA inspection readiness timelines as the inflection signal for Chinese contract provider competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | NMPA alignment with ICH Q5A through Q5D guidelines expands export-oriented capacity for Western-market-bound biosimilars. |
| Manufacturing Scale-Up | Single-use chromatography skids with pre-qualified flow paths compress minimum efficient scale for multi-product facilities. |
| Backward Integration | Synthetic ligand alternatives to traditional Protein A reduce resin cost structures and supply concentration risk. |
| Platform Integration | Software-defined chromatography control systems enable rapid reconfiguration between platform processes and custom method development. |
| Geographic Expansion | CDSCO-aligned facilities in Hyderabad-Bengaluru corridors capture qualification advantages for export-bound biologics. |
Study Parameters
Independent corroboration across drug development executives, regulatory affairs leads, CDMO operations directors, and biotech procurement managers underwrites the qualitative findings. Secondary validation draws from FDA biologics license filings, EMA active substance manufacture submissions, NMPA ICH alignment notices, and CDSCO regulatory updates. Bottom-up service provider capacity assessments and top-down biologics pipeline sizing anchor the quantitative framework.
Comparable-period anchoring to historical biologics outsourcing penetration rates shapes the projection horizon across service type, end user, application, and technique dimensions. Modeled segmentation spans chromatographic method, customer archetype, purification purpose, and upstream process modality. CAGRs derive from capacity expansion announcements, regulatory qualification timelines, and pipeline progression assumptions. Continuous processing adoption curves and single-use system deployment rates constitute key forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for continuous processing would alter the outlook if batch-based retention persists longer than projected. Forecasts reflect assumptions regarding regulatory harmonization velocity, resin innovation cycles, and biotech funding environment stability. Deviation in NMPA inspection readiness or Protein A supply disruption would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Services
Europe Flow Cytometry Market
Biotechnology Services
Global Custom Antibody Market
Biotechnology Services
In-Vitro Fertilization Services Market
Biotechnology Services
Global Reporter Gene Assay Market
Biotechnology Services
Global High Throughput Screening Market
Biotechnology Services
Plasmid DNA Preparation Market
Biotechnology Services
Peptide and Oligonucleotide CDMO Market
Biotechnology Services
Biologics Contract Manufacturing Market
Biotechnology Services
Loop-Mediated Isothermal Amplification (LAMP) Market
Biotechnology Services
Asia-Pacific Mirna Tools and Services Market
Biotechnology Services
Biotech API Manufacturing Services Market
Biotechnology Services
Global Eukaryotic Expression Systems Market
Biotechnology Services
Global Protein Labeling Market
Biotechnology Services
Serine Protease Market
Biotechnology Services
Global Bioprocess Validation Market
Biotechnology Services
Feruloyl Esterase Market