
 Global Antibody Market | 2026-2036
Global Antibody Market Size, Share, and Industry Trends Forecast 2026-2036
Global Antibody Market Analysis
Recombinant DNA technology is rewriting the production economics of antibody manufacturing, enabling mammalian cell culture yields that dwarf legacy hybridoma approaches. Roche leverages its captive biologics manufacturing network across Switzerland and the United States to sustain supply security for blockbuster therapeutic portfolios. AbbVie anchors its position through deep specialization in immunology monoclonal antibodies, while Johnson & Johnson competes via diversified exposure across oncology and autoimmune indications.
Antibodies are Y-shaped glycoproteins produced by B lymphocytes that bind with high specificity to target antigens, with molecular weights typically ranging from 150 kDa for standard IgG formats to smaller engineered fragments below 50 kDa; their primary commercial purpose centers on precision targeting of disease pathways with minimized off-tissue effects. Monoclonal antibodies occupy the dominant value pool given established manufacturing scale and biosimilar entry dynamics, while antibody-drug conjugates represent the fastest-expanding segment as payload-linker chemistry matures. Bispecific antibodies command premium positioning due to manufacturing complexity and dual-targeting functionality, though phage display technology continues to displace traditional immunization methods in early discovery workflows.
The FDA's Center for Drug Evaluation and Research and the EMA's Committee for Medicinal Products for Human Use enforce divergent but increasingly harmonized standards for antibody characterization, immunogenicity assessment, and comparability protocols that directly shape development costs and market access timelines. China's National Medical Products Administration has tightened Good Manufacturing Practice requirements for imported biologics, creating additional compliance layers for multinational suppliers. Stakeholders must monitor how evolving biosimilar interchangeability designations in the United States and Europe reshape pricing power for originator molecules across therapeutic areas.
Market Dynamics
Recombinant DNA technology has compressed antibody production timelines from months to weeks, forcing incumbent manufacturers to retool mammalian cell culture facilities or surrender margin to contract development organizations with superior expression system yields.
Growth Catalysts
- FDA Accelerated Approval Pathways:Compressed Phase II-to-approval timelines for breakthrough-designated oncology antibodies incentivize pipeline investment from venture-stage biotechs through multinational pharmaceutical portfolios.
- China's Biologics Manufacturing Scale:NMPA Good Manufacturing Practice harmonization with ICH standards enables domestic contract manufacturing organizations to capture overflow demand from Western originators facing capacity constraints.
- Antibody-Drug Conjugate Payload Innovation:Site-specific conjugation chemistry and novel linker technologies expand addressable oncology indications beyond CD30 and HER2 toward solid tumor microenvironments with heterogeneous antigen expression.
Market Restraints
- Chinese Hamster Ovary Cell Culture Input Concentration:Single-source dependency on specialized media and transfection reagents from a concentrated supplier base in Switzerland and the United States exposes production schedules to geopolitical friction.
- Biosimilar Interchangeability Designation Complexity:FDA and EMA divergent standards for automatic substitution without prescriber consultation fragment pricing power and extend legal defense expenditures for originator molecules.
- Immunogenicity Assessment Burden:Preclinical and clinical anti-drug antibody monitoring requirements impose non-negotiable cost structures that disproportionately burden indications requiring chronic administration.
Strategic Opportunities
- India's Underpenetrated Oncology Infrastructure:CDSCO streamlined approval for imported reference biologics creates first-mover positioning for manufacturers establishing local fill-finish partnerships ahead of compulsory licensing pressures.
- Bispecific Antibody Manufacturing Convergence:Common light chain platforms and knobs-into-holes engineering reduce downstream purification complexity, enabling mid-cap developers to access previously inaccessible dual-targeting modalities.
- Japan's Regenerative Medicine and Cell Therapy Synergies:PMDA priority review vouchers for combination products pairing antibodies with CAR-T or iPSC-derived cellular therapies open reimbursement pathways at premium price points.
Industry Challenges
- Process Analytical Technology Skill Scarcity:Real-time release testing and multivariate data analysis capabilities remain concentrated among a narrow cohort of process development scientists, inflating recruitment costs for manufacturing scale-up.
- Legacy Quality Management System Integration:Paper-based batch records and isolated data lakes in acquired manufacturing facilities obstruct traceability requirements under EU Good Manufacturing Practice Annex 11 computer system validation standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Antibody Market |
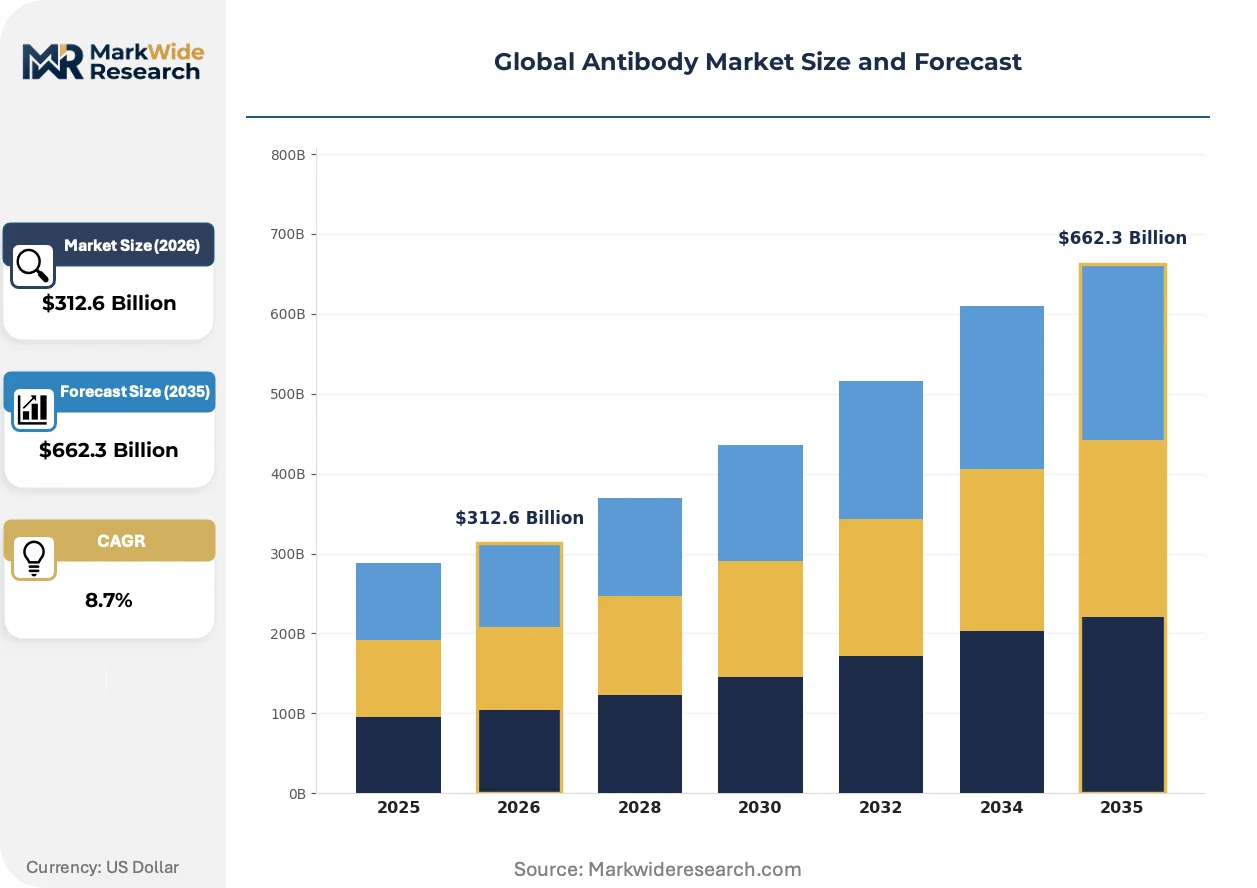
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $662.3 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Polyclonal Antibodies, Antibody-Drug Conjugates, Bispecific Antibodies End User: Pharmaceutical Companies, Biotechnology Firms, Research Institutions, Contract Manufacturing Organizations Application: Diagnostics, Therapeutic Use, Research, Clinical Trials Technology: Recombinant DNA Technology, Hybridoma Technology, Phage Display, Virus-Like Particle Technology |
| Companies Covered | Roche, AbbVie, Johnson & Johnson, Merck & Co., Amgen, Novartis, Bristol-Myers Squibb, Sanofi, GSK, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Antibody Market Emerging Trajectories
Antibody engineering workflows are converging with synthetic biology platforms and computational protein design, compressing discovery timelines while expanding the universe of druggable targets beyond canonical surface receptors.
Phage display technology for antibody library screening is collapsing the traditional immunization-to-lead timeline from six months to four weeks, enabling contract research organizations in Germany and the United States to deliver optimized binders before hybridoma campaigns complete their first fusion cycle. Biotech sponsors with limited internal infrastructure now outsource entire discovery campaigns, fragmenting the value chain between library providers and downstream developers.
EMA's adaptive licensing framework and rolling review procedures are compressing market access timelines for conditional approval candidates, particularly in oncology where surrogate endpoint acceptance has expanded. Regulators in Switzerland and the United Kingdom have mirrored these provisions, creating competitive pressure on FDA to maintain alignment or risk trial site migration toward European investigative networks.
Hospital procurement consortia in Germany and France are consolidating antibody purchasing through tender-based frameworks that unbundle distribution margins from product pricing, displacing traditional wholesale relationships. Specialty pharmacy direct contracting with integrated delivery networks in the United States is following this pattern, concentrating negotiating leverage among three to five national group purchasing organizations that set reference pricing for regional health systems.
Global Antibody Market Segmentation
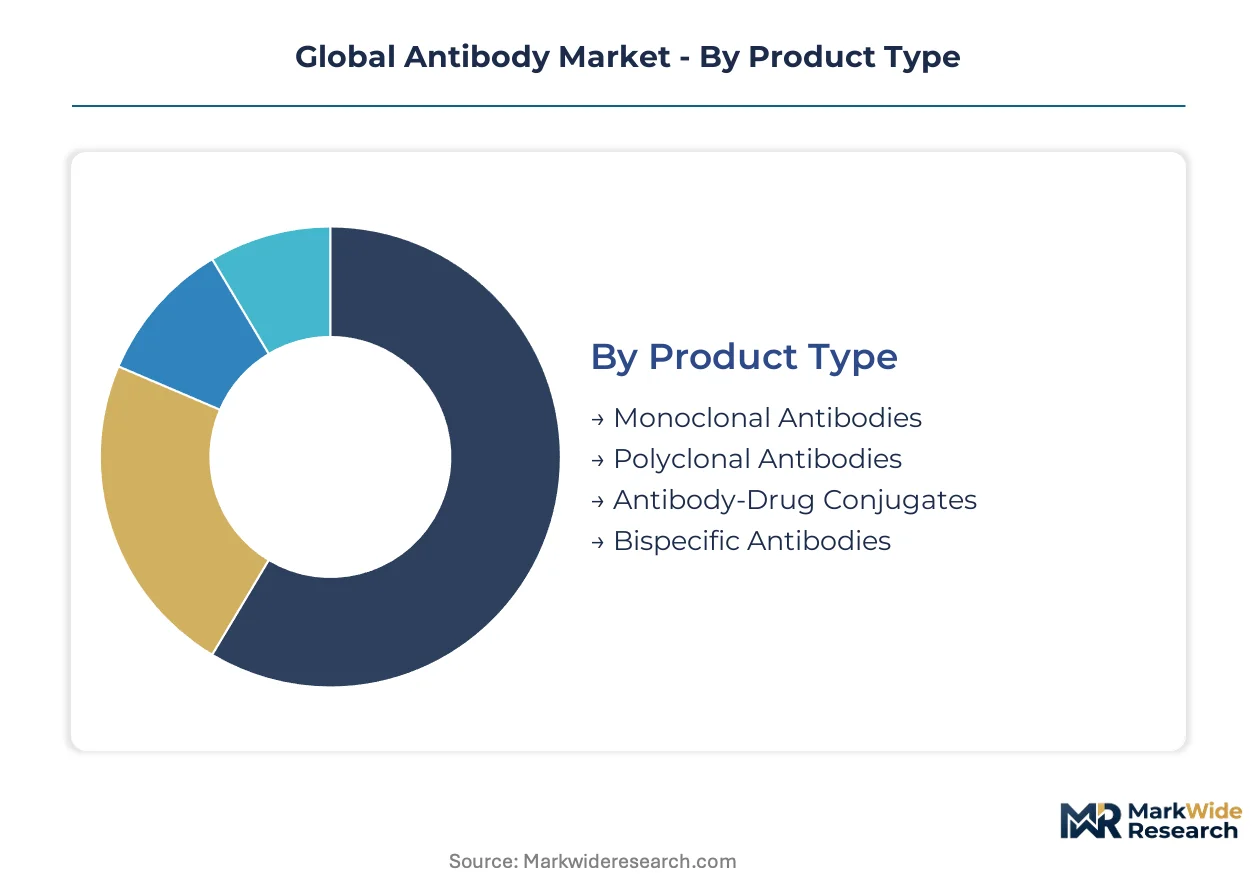
Antibody market segmentation reveals divergent velocity profiles across production technologies and customer archetypes. Cycle times compress from years for therapeutic approvals to weeks for research-grade reagents, creating distinct competitive arenas within the same molecular class.
Product Type:
Development velocity separates segments by an order of magnitude, with discovery-phase formats turning over in months while manufacturing-scale therapeutic modalities require decade-long investment horizons.
- Monoclonal Antibodies:Homogeneous immunoglobulin populations derived from single B-cell clones with defined specificity and reproducible glycosylation patterns. Hospital systems in the United States and Germany concentrate procurement for oncology and autoimmune indications, though biosimilar entry is compressing pricing power for legacy molecules.
- Antibody-Drug Conjugates:Cytotoxic payloads tethered to tumor-targeting antibodies via cleavable or non-cleavable linkers, demanding precise drug-to-antibody ratios for therapeutic index optimization. Specialty oncology clinics in Switzerland and the United States drive uptake as site-specific conjugation chemistry expands addressable solid tumor indications beyond hematologic malignancies.
- Polyclonal Antibodies:Heterogeneous serum-derived immunoglobulin mixtures recognizing multiple epitopes on target antigens.
- Bispecific Antibodies:Engineered constructs simultaneously engaging two distinct antigens, manufactured through knobs-into-holes or common light chain architectures.
Monoclonal antibodies dominate installed base. Antibody-drug conjugates are where expansion concentrates.
End User:
Customer concentration patterns map directly to capital intensity requirements, with asset-heavy manufacturers exhibiting stickier procurement relationships than research-stage consumers.
- Pharmaceutical Companies:Integrated developers with captive biologics manufacturing networks spanning Switzerland and the United States. These organizations internalize cell line development, process characterization, and commercial-scale production to protect supply security for blockbuster therapeutic portfolios.
- Contract Manufacturing Organizations:Third-party biologics producers operating under FDA and EMA Good Manufacturing Practice standards, with capacity concentration in China following NMPA harmonization with ICH guidelines. Biotechnology sponsors lacking internal infrastructure outsource entire production campaigns, fragmenting value capture between discovery innovators and manufacturing specialists.
- Biotechnology Firms:Venture-stage and mid-cap developers advancing novel modalities from discovery through Phase II proof-of-concept.
- Research Institutions:Academic laboratories and government research centers purchasing reagent-grade antibodies for mechanistic studies and target validation.
Pharmaceutical companies command procurement volume. Contract manufacturing organizations are gaining share fastest.
Application:
Revenue concentration and margin structure diverge sharply between regulated therapeutic pathways and unregulated research consumption.
- Therapeutic Use:FDA-approved biologics administered in hospital infusion centers and specialty pharmacy networks, requiring immunogenicity surveillance and risk evaluation mitigation strategies. Reimbursement infrastructure in the United States and Germany enables premium pricing for oncology and immunology indications with demonstrated survival benefits.
- Diagnostics:Immunoassay components for clinical laboratory detection of infectious disease, cardiac markers, and tumor antigens. Reference laboratories in the United States and China concentrate procurement as multiplexed assay platforms displace single-analyte testing workflows.
- Research:Non-GMP reagents for preclinical target validation, biomarker discovery, and mechanism-of-action studies.
- Clinical Trials:Investigational antibodies supplied under IND protocols with adaptive trial designs and surrogate endpoint frameworks.
Therapeutic use dominates installed base. Diagnostics is where expansion concentrates.
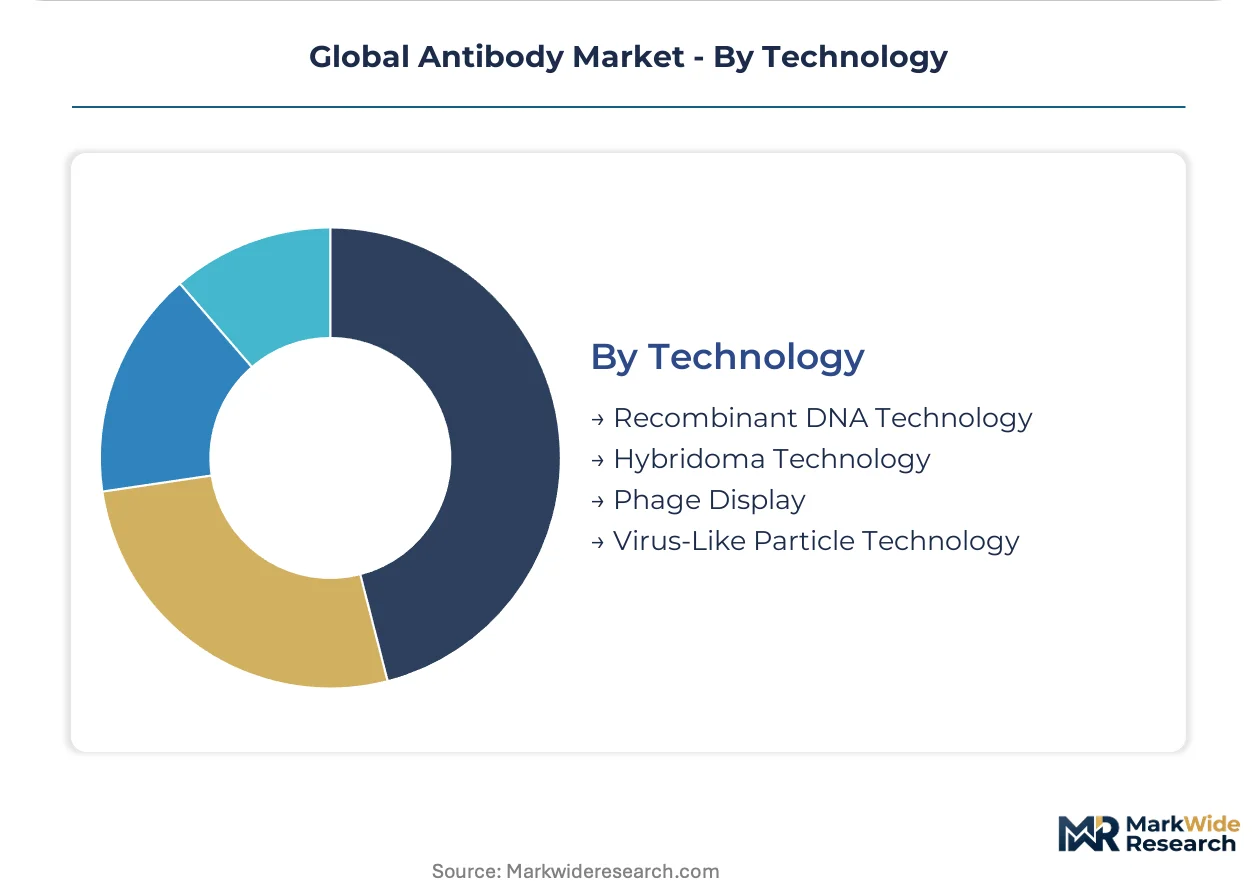
Technology:
Platform selection determines both discovery timeline compression and manufacturing yield economics, with newer modalities displacing legacy approaches across the value chain.
- Recombinant DNA Technology:Mammalian cell culture expression systems utilizing Chinese hamster ovary cells or human embryonic kidney lines for glycoprotein production with human-compatible glycosylation. Manufacturers in Switzerland and the United States leverage decades of process optimization to achieve titers exceeding legacy hybridoma yields by an order of magnitude.
- Phage Display:In vitro antibody library screening using filamentous bacteriophage particles displaying variable domain repertoires on surface coat proteins. Contract research organizations in Germany and the United States deliver optimized binders in four weeks, collapsing traditional immunization-to-lead timelines from six months.
- Hybridoma Technology:Murine myeloma fusion with immunized B cells for monoclonal antibody generation, now largely supplanted by humanization workflows.
- Virus-Like Particle Technology:Self-assembling capsid structures displaying antigenic epitopes for immunogen and vaccine applications.
Recombinant DNA technology dominates installed base. Phage display is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Antibody trade flows reveal stark asymmetries between manufacturing concentration and consumption gravity. Switzerland and the United States export finished therapeutic biologics while China and India import reference standards for biosimilar development. Germany occupies a middle position as both producer and net importer of specialized reagents.
United States
FDA accelerated approval pathways compress Phase II-to-market timelines for breakthrough-designated oncology antibodies, drawing venture capital toward Boston and San Francisco biotech clusters. The Inflation Reduction Act's Medicare price negotiation provisions reshape reimbursement calculus for chronic immunology indications. Massachusetts and California host the densest concentrations of contract manufacturing organization capacity, with Swiss and German multinationals operating captive facilities alongside domestic players.
Germany
Hospital procurement consortia in Bavaria and North Rhine-Westphalia consolidate antibody purchasing through tender-based frameworks that unbundle distribution margins from product pricing. EMA adaptive licensing frameworks enable earlier patient access for conditional approval candidates, particularly in hematologic oncology. The Rhine-Main and Munich biotech corridors concentrate process development talent for mammalian cell culture optimization.
China
NMPA Good Manufacturing Practice harmonization with ICH standards enables domestic contract manufacturing organizations to capture overflow demand from Western originators facing capacity constraints. Shanghai and Suzhou industrial parks host the fastest-expanding biologics manufacturing base outside Switzerland and the United States. Import reference biologics face tightened inspection protocols, accelerating local fill-finish partnerships for multinational suppliers.
Switzerland
Swissmedic maintains alignment with EMA standards while offering streamlined procedures for priority review of innovative biologics. Basel and Zurich anchor captive manufacturing networks for blockbuster therapeutic portfolios, with Roche operating the industry's largest integrated biologics production footprint. The country's dual role as manufacturing hub and regulatory reference point shapes global comparability protocol standards.
India
CDSCO streamlined approval for imported reference biologics creates first-mover positioning for manufacturers establishing local partnerships ahead of compulsory licensing pressures. Maharashtra and Telangana concentrate biosimilar development capabilities, with Hyderabad emerging as a contract research organization hub for antibody engineering services. Domestic oncology infrastructure remains underpenetrated relative to patient burden, creating demand asymmetry for imported therapeutics.
Global Antibody Market Vendor Landscape
On the supply side, the industry is consolidating around integrated biologics manufacturers with captive cell culture capacity and specialized contract development organizations with superior expression system yields. Three archetypes dominate: Swiss and US-based multinationals with decades of process optimization, mid-cap biotechnology firms advancing novel modalities through Phase II, and emerging Chinese manufacturers leveraging NMPA harmonization for global contract manufacturing organization qualification. Competitive intensity centers on manufacturing scale-up velocity and regulatory submission speed rather than price competition alone.
Within the integrated multinational tier, Roche, AbbVie, and Johnson & Johnson occupy positions shaped by manufacturing footprint depth and therapeutic specialization breadth. Roche exemplifies the captive biologics network archetype with Switzerland-United States manufacturing symmetry. AbbVie represents immunology monoclonal antibody concentration. Johnson & Johnson anchors diversified exposure across oncology and autoimmune indications. These three entities collectively shape benchmark standards for supply security and portfolio risk distribution.
| Leading Market Players |
|---|
| Roche |
| AbbVie |
| Johnson & Johnson |
| Merck & Co. |
| Amgen |
| Novartis |
| Bristol-Myers Squibb |
| Sanofi |
| GSK |
| Others |
Supply Flow & Price Mechanics
Chinese Hamster Ovary cell culture media suppliers in Switzerland and the United States concentrate upstream input production, anchoring margin capture for finished therapeutic antibodies in hospital procurement systems and specialty pharmacy networks. This upstream concentration shapes downstream pricing power, with manufacturers bearing input cost pass-through while competing for formulary placement through rebate structures.
Pricing Analysis
Hospital procurement consortia anchor three-tier pricing structure across premium, standard, and economy levels for therapeutic antibodies, with differentiation driven by biosimilar interchangeability designation and originator brand heritage. Cost compression in the standard tier intensifies because CDSCO and NMPA accelerated biosimilar approvals expand substitutable alternatives. Contract manufacturing organizations exhibit highest price sensitivity due to margin-thin toll manufacturing economics, while integrated pharmaceutical developers with captive biologics networks maintain lowest sensitivity through supply security premiums.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from specialized media suppliers in Switzerland and the United States enable working capital management for mammalian cell culture facilities. Manufacturing scale concentrates in Switzerland, the United States, and China following NMPA-ICH harmonization, with raw material dependencies on transfection reagents, specialized sera, and single-use bioreactor components. Single-source vulnerability on CHO cell lines and proprietary expression vectors creates structural risk, while distribution runs through cold-chain logistics networks serving hospital infusion centers and specialty pharmacy direct contracting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Antibody engineering convergence with synthetic biology platforms and computational protein design constitutes a technological inflection compressing discovery-to-manufacturing timelines and reshaping competitive barriers across therapeutic modalities.
For Market Incumbents: Harden manufacturing network resilience through backward integration into Chinese Hamster Ovary cell line development and captive media formulation capacity in Switzerland or the United States. Defend formulary positioning by accelerating FDA breakthrough therapy submissions for bispecific antibodies before common light chain platforms commoditize dual-targeting manufacturing. For New Entrants and Emerging Players: Build out contract manufacturing organization partnerships in China's Shanghai and Suzhou industrial parks to access NMPA-qualified capacity without capital-intensive facility construction. India's underpenetrated oncology infrastructure offers white-space positioning for imported reference biologics ahead of compulsory licensing pressures, with CDSCO streamlined approvals enabling first-mover hospital procurement relationships. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across antibody-drug conjugate manufacturing as site-specific conjugation chemistry standardizes, improving returns for mid-cap developers with novel payload-linker portfolios. Five-to-ten year viability favors acquisition targets with phage display discovery platforms and established CMO relationships over asset-heavy integrated manufacturers. Watch FDA biosimilar interchangeability designation velocity as the signal indicating originator pricing power erosion speed.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | NMPA-ICH harmonization enables Chinese CMOs to capture Western overflow demand. |
| Regulatory Approval Pathway | FDA accelerated approval compresses Phase II-to-market timelines for oncology antibodies. |
| Pipeline Diversification | Bispecific antibody platforms reduce dependence on mature monoclonal franchises. |
| Backward Integration | Captive CHO cell line development insulates against media supplier concentration. |
| Strategic Partnership | Local fill-finish partnerships in India anticipate CDSCO reference biologic demand. |
Methodological Framework
A standing panel of drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers provided ongoing calibration across primary interview cycles, with secondary validation drawing from FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases. Bottom-up therapeutic antibody revenue modeling triangulated against top-down market sizing from customs trade flows and pharmaceutical import records.
Scenario-bracketing framed analytical projections across the analysis window, with segmentation modeling spanning product type, therapeutic application, end-user archetype, and regional regulatory cluster. CAGRs derived from patient population epidemiology, treatment penetration curves, and pricing trajectory assumptions for originator and biosimilar molecules. Forecast inputs incorporated immunogenicity surveillance burden estimates and manufacturing yield improvements from recombinant DNA platform evolution.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese contract manufacturing organizations or accelerated FDA interchangeability designations would shift outcomes. Macroeconomic reimbursement pressure, regulatory divergence between FDA and EMA standards, or breakthroughs in non-antibody precision medicine platforms would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Global Anti-Infective Drugs Market
Biopharmaceuticals
Global Seasonal Influenza Vaccine Market
Biopharmaceuticals
Human Immunodeficiency Virus (HIV) Drugs Market
Biopharmaceuticals
Liposomal Doxorubicin Market
Biopharmaceuticals
Global Diagnostic Specialty Antibodies Market
Biopharmaceuticals
Global Recombinant Proteins Market
Biopharmaceuticals
Tamiflu (Oseltamivir Phosphate) Market
Biopharmaceuticals
Global Branded Generics Market
Biopharmaceuticals
Bio-Active Peptides Market
Biopharmaceuticals
North America and Europe Pegylated Drugs Market
Biopharmaceuticals
Drug Resistant Pulmonary Tuberculosis Market
Biopharmaceuticals
Interleukin-6 (IL-6) Inhibitors Market
Biopharmaceuticals
Compounded Bioidentical Hormone Therapy Market
Biopharmaceuticals
Antibacterial Drugs Market
Biopharmaceuticals
Antibiotics Market
Biopharmaceuticals
Thailand Insulin Drugs and Delivery Devices Market