
 Immunoassays in R & D Market | 2026-2036
Immunoassays in R & D Market Size, Share, and Industry Trends Forecast 2026-2036
Immunoassays in R & D Market Outlook
Magnetic bead substrates are hardening as the preferred solid-phase matrix over traditional polystyrene microplates, cutting incubation times by half while preserving binding kinetics. Thermo Fisher Scientific leverages its captive magnetic particle supply chain to dominate high-throughput screening workflows. Danaher Corporation anchors its position through integrated automation platforms that bundle detection hardware with consumable contracts. Bio-Rad Laboratories differentiates through open-architecture instruments that accept third-party reagent kits, appealing to academic labs with fragmented procurement budgets.
Immunoassays in R & D comprise analytical methods that use antibody-antigen binding reactions to quantify target molecules, typically achieving detection sensitivities in the picogram-per-milliliter range through enzymatic or fluorescent signal amplification. These techniques serve as the backbone of ligand-binding bioanalysis in pharmaceutical research, enabling pharmacokinetic profiling, immunogenicity assessment, and biomarker quantification across preclinical and clinical development stages. Enzyme-Linked Immunosorbent Assays retain the largest installed base due to decades of protocol standardization and reagent availability, though Multiplexing platforms are capturing the fastest growth as researchers prioritize sample volume conservation and parallel analyte measurement. Among end users, Pharmaceutical Companies command the deepest per-account spending, while Biotech Firms represent the most dynamic expansion segment as virtual development models outsource bioanalytical functions to specialized CRO partners.
FDA bioanalytical guidance and EMA immunogenicity guidelines jointly determine assay validation rigor, directly shaping reagent quality specifications and documentation burdens for kit suppliers seeking regulatory submission support. ISO 13485 and ISO 17025 accreditation requirements from notified bodies govern manufacturing consistency and analytical competency, creating tiered market access where certified providers capture premium pricing in regulated pharmaceutical accounts. Stakeholders must monitor evolving harmonization between FDA, EMA, and ICH guidelines, as divergent validation expectations threaten to fragment kit development roadmaps and inflate regional compliance costs.
Market Dynamics
Multiplexed immunoassay platforms are compressing biomarker validation timelines from months to weeks, forcing kit suppliers to re-architect reagent stability specifications and quality control protocols around parallel analyte detection workflows rather than single-plex batch processing.
Growth Catalysts
- NIH funding concentration:The National Institutes of Health channels billions annually into precision medicine initiatives, creating dense procurement ecosystems around Boston and San Diego where biopharmaceutical clusters demand high-throughput screening infrastructure.
- FDA bioanalytical method validation guidance:Tightening performance standards for ligand-binding assays are compelling pharmaceutical sponsors to upgrade to certified kit suppliers, filtering out uncertified vendors from regulated accounts.
- Magnetic bead substrate adoption:These solid-phase matrices cut incubation times by half versus polystyrene microplates while preserving binding kinetics, accelerating adoption in high-throughput screening workflows.
Market Restraints
- Reagent quality volatility:Antibody lot-to-lot variability and recombinant protein instability inflate validation failure rates, forcing redundant qualification runs that consume 15-20% of project timelines.
- ISO 17025 accreditation concentration:Certified analytical competency resides with a limited pool of contract research organizations, creating bottlenecks for biotech firms lacking in-house bioanalytical infrastructure.
- Cross-reactivity technical ceiling:Multiplex panels face fundamental binding interference limits when analyte concentrations span multiple orders of magnitude, constraining panel design flexibility.
Strategic Opportunities
- Virtual biotech outsourcing surge:Asset-light development models in Cambridge and South San Francisco are offloading entire bioanalytical functions to specialized contract research partners, expanding addressable kit volumes.
- ICH harmonization tailwind:Converging FDA-EMA validation expectations promise to collapse regional kit development roadmaps into single qualification packages, reducing compliance overhead for multi-territory submissions.
- Academic open-architecture demand:Fragmented procurement budgets at research universities favor instruments accepting third-party reagent kits, creating entry points for non-captive suppliers.
Industry Challenges
- Assay transfer complexity:Migrating validated ligand-binding methods between contract research organizations requires extensive bridging studies that delay clinical trial initiation timelines.
- Immunogenicity assay standardization:Anti-drug antibody detection lacks universal reference materials, forcing sponsors to maintain parallel method development tracks for regulatory submission defense.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Immunoassays in R & D Market |
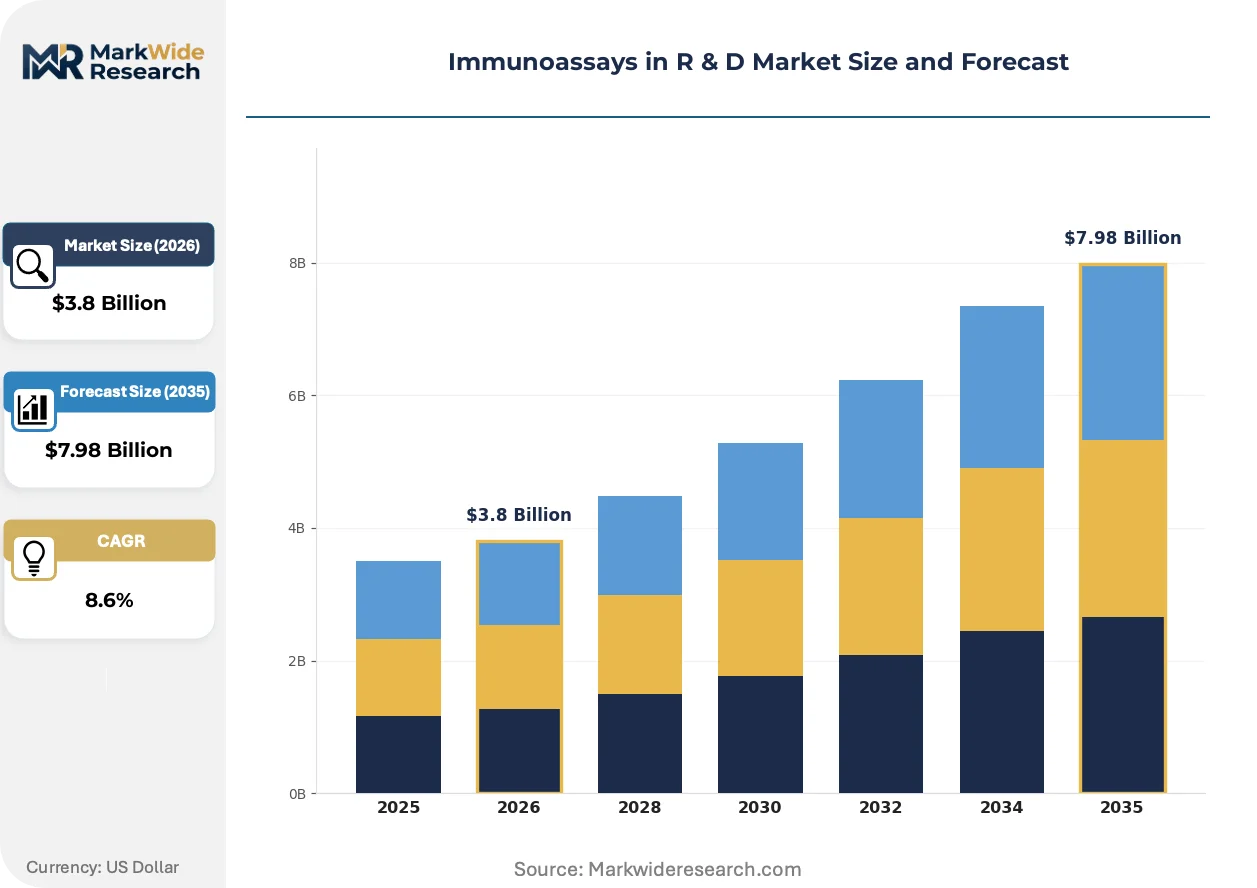
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enzyme-Linked Immunosorbent Assays, Radioimmunoassays, Lateral Flow Assays, Western Blotting Application: Biomarker Discovery, Drug Development, Clinical Diagnostics, Environmental Testing End User: Pharmaceutical Companies, Research Institutions, Clinical Laboratories, Biotech Firms Technology: Fluorescent Detection, Chemiluminescent Detection, Colorimetric Detection, Multiplexing |
| Companies Covered | Thermo Fisher Scientific, Danaher Corporation, Bio-Rad Laboratories, Meso Scale Diagnostics, PerkinElmer, Merck KGaA, Abbott, F. Hoffmann-La Roche Ltd., Siemens Healthineers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Immunoassays in R & D Market Strategic Shifts
Electrochemiluminescence detection architectures and microfluidic sample handling are converging to redefine sensitivity benchmarks and throughput economics across pharmaceutical bioanalysis. These shifts are compressing the traditional trade-off between detection limit and multiplexing density.
Single-molecule array technology is decentralizing ultra-sensitive protein quantification from centralized reference laboratories into discovery-stage screening workflows. Biopharmaceutical companies are deploying Simoa platforms earlier in preclinical pipelines to detect previously unmeasurable biomarkers. This diffusion is decentralizing pharmacokinetic study design by enabling sparse sampling protocols that reduce animal usage and accelerate dose selection decisions.
EMA immunogenicity guidelines are tightening documentation requirements for anti-drug antibody assays used in European marketing authorization applications. Sponsors must now demonstrate drug tolerance and sensitivity in matrix-specific bridging studies. Biologics developers with EU submission strategies are front-loading validation rigor into early-phase protocols to avoid retrospective method redevelopment.
Consolidated procurement through preferred vendor agreements is displacing fragmented reagent purchasing across top-twenty pharmaceutical accounts. Procurement teams are bundling detection hardware, consumable contracts, and method transfer services into multi-year partnerships. This concentration is most visible in the United States, where procurement centralization at headquarters level overrides site-level purchasing autonomy.
Immunoassays in R & D Market Segmentation
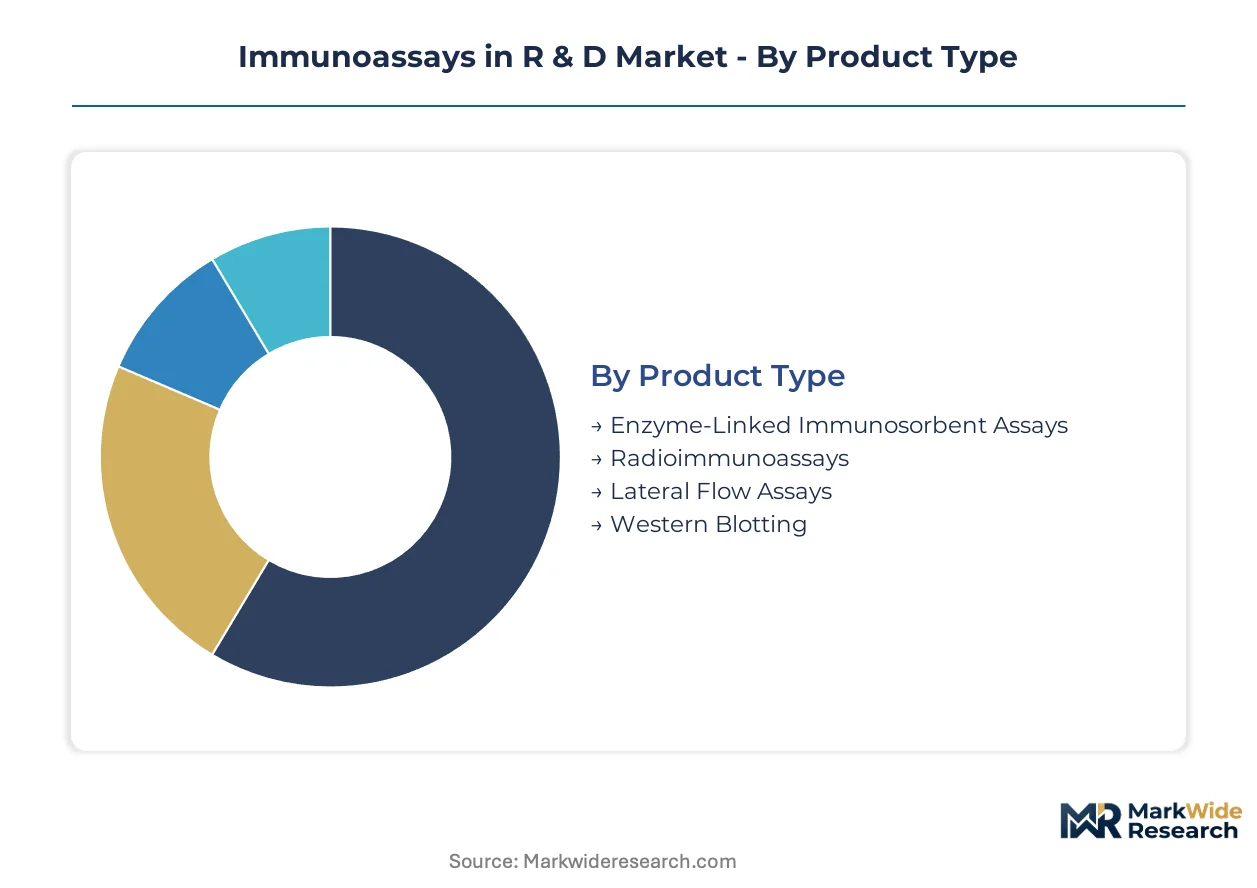
Immunoassay procurement patterns diverge sharply across product architectures, application workflows, and detection modalities. Understanding these segment boundaries clarifies why kit suppliers maintain parallel development tracks rather than unified platform strategies.
Product Type:
Supply concentration in magnetic bead substrates and detection consumables has reorganized competitive positioning around reagent stability specifications rather than instrument hardware differentiation.
- Enzyme-Linked Immunosorbent Assays:These colorimetric or fluorometric plate-based methods leverage horseradish peroxidase or alkaline phosphatase signal amplification to achieve picogram-per-milliliter sensitivities. Pharmaceutical companies in the United States sustain the deepest procurement volumes due to decades of protocol standardization and cross-laboratory comparability requirements.
- Multiplexing:Bead-based and planar array platforms enable simultaneous quantification of dozens to hundreds of analytes from single sample volumes. Biotech firms in Cambridge and South San Francisco are compressing biomarker validation timelines by migrating from sequential ELISA workflows to parallel detection architectures.
- Radioimmunoassays:Iodine-125 labeled tracers deliver femtomolar detection limits for peptide hormones and steroids where antibody affinity constraints limit enzymatic alternatives.
- Lateral Flow Assays:Membrane-based immunochromatographic strips provide qualitative or semi-quantitative readouts without instrumentation requirements.
- Western Blotting:Gel electrophoresis combined with antibody probing enables molecular weight-resolved protein detection for specificity confirmation.
Enzyme-Linked Immunosorbent Assays absorb the bulk of installed capacity; Multiplexing is expanding most quickly.
Application:
Cost tier segmentation separates premium-validated kits for regulatory submission support from exploratory-grade reagents used in discovery screening.
- Drug Development:Pharmacokinetic profiling and immunogenicity assessment demand lot-to-lot consistency documentation and bridging study protocols. Sponsors targeting FDA and EMA submissions concentrate procurement with ISO 17025-accredited CRO partners around Boston and San Diego.
- Biomarker Discovery:Exploratory protein quantification prioritizes multiplexing density and sample volume conservation over regulatory compliance documentation. Academic medical centers and virtual biotechs drive adoption of open-architecture platforms accepting third-party antibody panels.
- Clinical Diagnostics:IVD-compliant immunoassays require design control documentation and manufacturing quality systems under ISO 13485.
- Environmental Testing:Water and soil contaminant detection employs competitive immunoassay formats for small molecule quantification.
Drug Development commands premium pricing tiers; Biomarker Discovery is climbing the fastest as precision medicine initiatives expand funding flows.
End User:
Customer type determines whether procurement flows through centralized vendor management or fragmented laboratory-level purchasing.
- Pharmaceutical Companies:Consolidated procurement functions at headquarters level bundle multi-year consumable contracts with method transfer services and dedicated field application support. Top-twenty sponsors in the United States have displaced site-level autonomy with preferred supplier agreements.
- Biotech Firms:Asset-light development models outsource entire bioanalytical functions to specialized CRO partners rather than building in-house ligand-binding infrastructure. Cambridge, South San Francisco, and San Diego clusters represent the most dynamic expansion segment.
- Research Institutions:Fragmented budgets and principal investigator autonomy favor open-architecture instruments accepting third-party reagent kits.
- Clinical Laboratories:High-throughput routine testing demands walkaway automation and LIS connectivity for regulatory compliance.
Pharmaceutical Companies anchor revenue concentration; Biotech Firms are gaining share fastest through outsourcing proliferation.
Technology:
Detection modality selection trades sensitivity depth against multiplexing breadth and reagent cost structure.
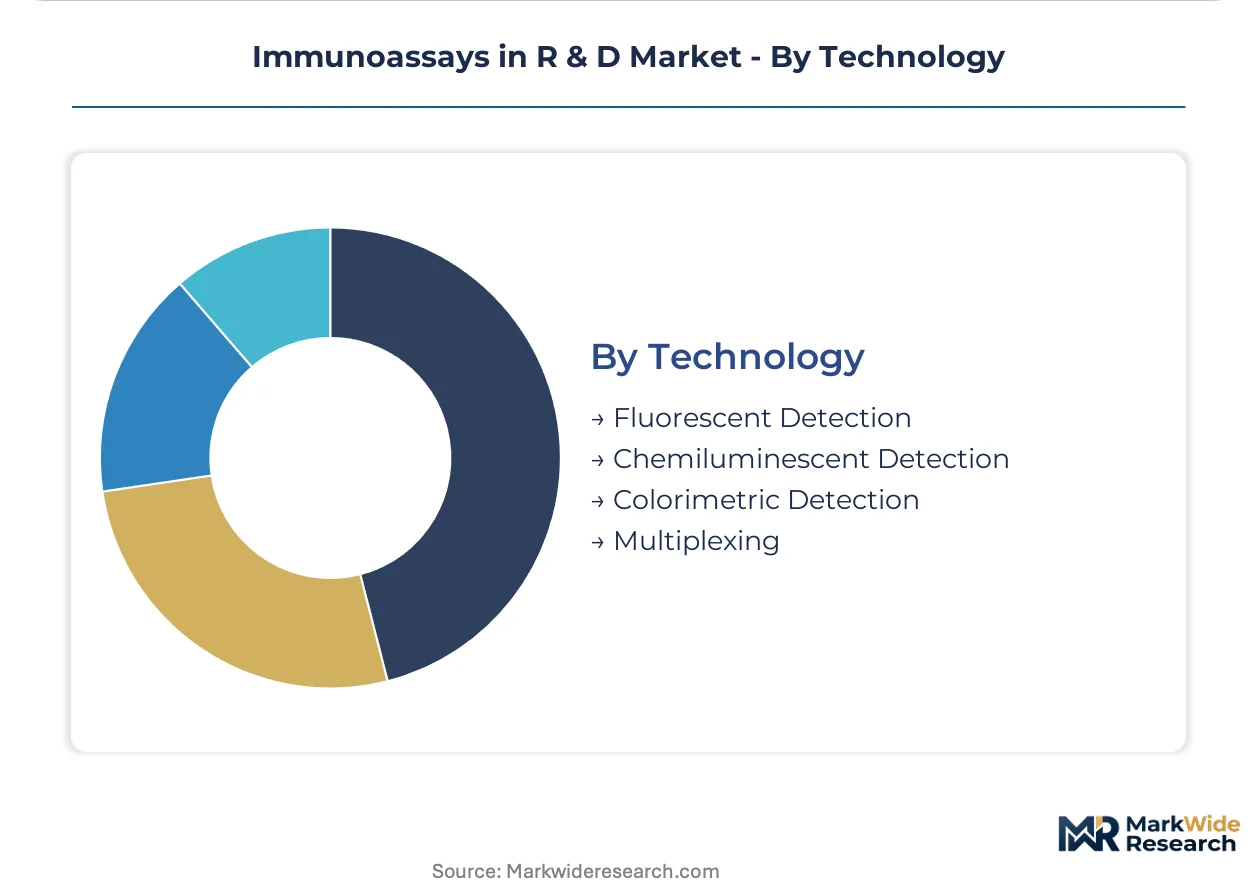
- Fluorescent Detection:Organic fluorophores and quantum dots enable multi-channel spectral resolution for multiplexed bead-based assays. NIH-funded precision medicine consortia in the United States are standardizing on fluorescent readouts for biomarker panel harmonization.
- Chemiluminescent Detection:Acridinium ester and luminol-based signal generation delivers femtomolar sensitivity with broad dynamic range. EMA immunogenicity guideline tightening is compelling sponsors to upgrade from colorimetric to chemiluminescent architectures for European submission defense.
- Colorimetric Detection:Absorbance-based ELISA readouts retain cost advantages for single-plex applications with moderate sensitivity requirements.
- Multiplexing:Spatially encoded beads and planar arrays compress parallel analyte measurement into single sample volumes.
Fluorescent Detection maintains the largest installed base; Chemiluminescent Detection is expanding most quickly as validation standards tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NIH funding concentration and CRO clustering around specific metropolitan areas create dense procurement ecosystems that concentrate immunoassay demand in the United States. European regulatory harmonization efforts and precision medicine initiatives in Asia are redistributing growth vectors across three continents.
United States
NIH precision medicine initiatives channel billions annually into biomarker validation infrastructure. FDA bioanalytical method validation guidance tightens performance standards for ligand-binding assays, filtering uncertified vendors from regulated accounts. Boston and San Diego host dense CRO clustering where biopharmaceutical sponsors demand high-throughput screening infrastructure.
Germany
EMA immunogenicity guidelines drive adoption of chemiluminescent detection architectures for European submission defense. ISO 17025 accreditation requirements from notified bodies govern manufacturing consistency for kit suppliers targeting regulated pharmaceutical accounts. Munich and Heidelberg anchor bioanalytical CRO concentration serving EU-wide biologics developers.
Switzerland
Swissmedic oversight of clinical trial applications demands rigorous ligand-binding assay documentation for marketing authorization. Precision medicine consortia funded through federal innovation programs expand biomarker discovery infrastructure. Basel and Zurich clusters concentrate biopharmaceutical headquarters procurement functions.
China
NMPA evolving bioanalytical standards are compelling domestic sponsors to upgrade kit qualification protocols for innovative drug applications. National precision medicine initiatives expand funding flows into biomarker validation infrastructure. Shanghai and Suzhou biotech parks concentrate CRO capacity serving both domestic and multinational sponsors.
United Kingdom
MHRA post-Brexit regulatory autonomy is diverging from EMA immunogenicity guidance, creating parallel validation requirements for UK-EU dual submissions. NHS Genomic Medicine Service expands demand for multiplexed biomarker panels. London-Oxford-Cambridge golden triangle concentrates academic-industry collaboration in ligand-binding bioanalysis.
Immunoassays in R & D Market Competitive Environment
Strategic partnerships dominate the current landscape as kit suppliers bundle detection hardware with consumable contracts and method transfer services. The vendor base organizes into three tiers: integrated platform providers with captive reagent supply chains, open-architecture instrument specialists, and regional reagent suppliers serving fragmented academic accounts. Two archetypes define positioning: full-stack integrators capturing multi-year pharmaceutical partnerships versus modular specialists penetrating budget-constrained research institutions. Portfolio diversification around magnetic bead substrates and chemiluminescent detection architectures represents the primary competitive vector alongside geographic expansion into precision medicine clusters.
Among integrated platform providers, Thermo Fisher Scientific anchors the full-stack archetype through captive magnetic particle supply chains. Danaher Corporation occupies a position bundling automation hardware with consumable contracts. Bio-Rad Laboratories exemplifies the open-architecture specialist tier, serving academic labs with fragmented procurement budgets. These three entities collectively represent the competitive structure: scale-driven integration, automation-centric bundling, and modular accessibility.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Danaher Corporation |
| Bio-Rad Laboratories |
| Meso Scale Diagnostics |
| PerkinElmer |
| Merck KGaA |
| Abbott |
| F. Hoffmann-La Roche Ltd. |
| Siemens Healthineers |
| Others |
Value Chain & Pricing Dynamics
Top-twenty pharmaceutical sponsors in the United States operate consolidated procurement functions that bundle multi-year consumable contracts with method transfer services, anchoring a contract-based pricing model where volume commitments secure preferential unit economics and dedicated field application support.
Pricing Analysis
High-volume kit consumption by pharmaceutical companies sustains margin pools while biotech outsourcing proliferation intensifies price competition in the mid-tier. Pricing stratifies across premium-validated, standard-research-grade, and economy-exploratory tiers based on ISO 17025 accreditation status and lot-to-lot documentation depth. Cost compression in the standard tier is intensifying as virtual biotechs consolidate purchasing through preferred CRO partnerships. Academic labs with fragmented budgets exhibit highest price sensitivity; regulated pharmaceutical sponsors show lowest sensitivity due to submission risk aversion.
Supply Chain Analysis
ISO 13485 and ISO 17025 certification requirements from notified bodies gate market access for magnetic bead substrates and recombinant antibody suppliers, concentrating qualified manufacturing in the United States, Germany, and Switzerland. Captive supply chains for magnetic particles and acridinium ester chemiluminescent substrates hinge on specialized chemical synthesis and biologics production capabilities concentrated with integrated platform providers. Single-source vulnerability for high-affinity monoclonal antibodies creates bottlenecks when lot-to-lot variability triggers redundant qualification runs. Distribution runs through direct sales forces for top-twenty pharmaceutical accounts and specialized distributors serving fragmented academic procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISO 17025-accredited analytical competency resides with a limited pool of contract research organizations, creating supply-constrained conditions that prop pricing power for certified kit suppliers serving regulated pharmaceutical development.
For Market Incumbents: Deploy captive magnetic particle supply chains to defend against open-architecture competitors encroaching on high-throughput screening workflows. Deepen backward integration into recombinant antibody production to reduce lot-to-lot variability exposure and compress redundant qualification timelines that inflate project costs. For New Entrants and Emerging Players: Single-molecule array technology diffusion into preclinical pipelines offers entry points for ultra-sensitive protein quantification platforms targeting biomarker discovery workflows. Academic medical centers with fragmented procurement budgets represent the most penetrable segment; pursue open-architecture instrument positioning that accepts third-party reagent kits to bypass captive consumable lock-in. For Investors and Strategic Acquirers: The window for entry favors specialized CRO partners with ISO 17025 accreditation and established method transfer protocols serving virtual biotech clusters in Cambridge and South San Francisco. Target acquisition archetypes include magnetic bead substrate specialists with pharmaceutical-grade manufacturing scale and chemiluminescent detection consumable providers. Watch for ICH harmonization progress between FDA and EMA as inflection indicator collapsing regional kit development roadmaps into single qualification packages.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 17025 Accreditation Investment | Filters uncertified vendors from regulated pharmaceutical accounts per tightening FDA guidance. |
| Magnetic Bead Substrate Scale-Up | Captures high-throughput screening demand from NIH-funded precision medicine consortia. |
| Open-Architecture Platform Development | Penetrates academic labs with fragmented procurement budgets and principal investigator autonomy. |
| CRO Partnership Consolidation | Bundles method transfer services with multi-year consumable contracts for virtual biotech outsourcing. |
| Chemiluminescent Detection Migration | Defends European submission positioning as EMA immunogenicity guidelines tighten documentation requirements. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with bioanalytical directors at contract research organizations, regulatory affairs leads at biopharmaceutical sponsors, procurement managers at top-twenty pharmaceutical accounts, and principal investigators at academic medical centers. FDA bioanalytical method validation guidance documents, EMA immunogenicity guidelines, ISO 17025 accreditation databases, and NIH precision medicine initiative funding disclosures provided structured secondary validation. Bottom-up triangulation across kit supplier revenue disclosures and top-down cross-checks against pharmaceutical R&D expenditure patterns ensured analytical consistency.
Granularity-level modeling disaggregated volume and value projections across enzyme-linked immunosorbent assays, multiplexing platforms, and chemiluminescent detection architectures, further segmented by pharmaceutical company, biotech firm, and research institution end users. CAGRs were derived from regression analysis of historical procurement patterns and forward-looking biomarker validation pipeline expansion. Magnetic bead substrate adoption curves and single-molecule array technology diffusion rates served as industry-specific forecast inputs across the projection horizon.
Several conditions sit outside the modeled scope, including unforeseen regulatory divergence between FDA and EMA, abrupt NIH funding reallocation, and breakthrough displacement of ligand-binding assays by mass spectrometry bioanalysis. Forecasts reflect assumptions about continued precision medicine initiative expansion and sustained virtual biotech outsourcing proliferation. A model refresh is warranted upon material change in ICH harmonization progress or magnetic bead substrate supply concentration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Services
Electrophoresis Market
Biotechnology Services
Phospho-Specific Antibodies Market
Biotechnology Services
Peptide and Oligonucleotide CDMO Market
Biotechnology Services
Global Protein Purification and Isolation Market
Biotechnology Services
Global Western Blotting Market
Biotechnology Services
Global Bioprocess Validation Market
Biotechnology Services
Serine Protease Market
Biotechnology Services
Europe Flow Cytometry Market
Biotechnology Services
3D Ready Organoid Expansion Service Market
Biotechnology Services
Global Protein Binding Assay Market
Biotechnology Services
Cell Line Development Market
Biotechnology Services
Asia-Pacific Mirna Tools and Services Market
Biotechnology Services
Drug Discovery and Development Laboratory Services Market
Biotechnology Services
Antibody Drug Conjugates Contract Manufacturing Market
Biotechnology Services
Global Culture Media Market
Biotechnology Services
Global Vero Cell Media Market