
 Riboflavin Kinase Market | 2026-2036
Riboflavin Kinase Market Size, Share, and Industry Trends Forecast 2026-2036
Riboflavin Kinase Market Analytics
Specialized biocatalysis talent is bifurcating the competitive landscape, with European and North American firms struggling to recruit fermentation engineers while Asian producers expand trained workforces rapidly. BASF SE leverages its integrated vitamin B2 complex to sustain captive riboflavin kinase output for pharmaceutical customers. Koninklijke DSM NV anchors its position through enzymatic process leadership in high-purity grades. Shanghai Acebright Pharmaceuticals Group Co. Ltd competes on fermentation scale, dominating bulk powder supply to regional feed producers.
Riboflavin kinase is an ATP-dependent enzyme that catalyzes the phosphorylation of riboflavin to flavin mononucleotide, operating optimally at pH 7.0-8.5 and requiring magnesium ion cofactors for industrial biotransformation processes. The enzyme serves as a critical biocatalyst in vitamin B2 derivative synthesis and as a reagent in cellular metabolism research. Powder formulations occupy the largest volume share due to stability in bulk pharmaceutical chemical distribution, while liquid preparations represent the fastest-expanding category as contract manufacturers adopt continuous enzymatic processing. Healthcare supplements command premium pricing through pharmacy and hospital channels, whereas animal feed applications compete on cost efficiency via distributor networks to integrated livestock operations.
FDA Current Good Manufacturing Practice standards and EMA excipient quality guidelines shape purity thresholds for pharmaceutical-grade riboflavin kinase, forcing producers to validate endotoxin limits and microbial contamination controls. China's NMPA and India's CDSCO impose parallel bioactive substance registration requirements that delay market entry for unqualified foreign suppliers. Stakeholders must monitor evolving pharmacopeial monograph revisions and regional supply chain reconfiguration as fermentation capacity shifts between Asia-Pacific production clusters and Western formulation sites.
Market Dynamics
Pharmaceutical-grade purity mandates from FDA and EMA are compressing supplier margins while concentrating production among fermentation specialists capable of validating endotoxin limits below 0.25 EU/mg. This regulatory tightening is accelerating capital deployment toward closed-system bioreactors and single-use containment technologies.
Growth Catalysts
- FDA Current Good Manufacturing Practice enforcement:Tighter endotoxin and microbial contamination thresholds for vitamin B2 derivatives are disqualifying commodity-grade suppliers and expanding addressable market for validated producers.
- Nutraceutical contract manufacturing expansion:Third-party enzyme processors in India and China are installing dedicated riboflavin kinase production lines to serve Western pharmaceutical customers seeking qualified supply alternatives.
- Continuous enzymatic processing adoption:Liquid formulation demand from biopharmaceutical CMOs is pulling investment toward immobilized enzyme reactor systems with real-time titer monitoring.
Market Restraints
- Magnesium cofactor cost volatility:Industrial-grade magnesium sulfate price swings directly compress biotransformation process economics for high-volume manufacturers.
- Upstream fermentation concentration in China and India:Geographic clustering of raw riboflavin supply creates single-source vulnerability for European and North American formulators.
- Substitution by chemical phosphorylation:Synthetic FMN production routes using phosphorus oxychloride remain cost-competitive for feed-grade applications where enzymatic purity premiums cannot be recovered.
Strategic Opportunities
- Underpenetrated Brazilian pharmaceutical market:ANVISA's bioactive substance registration pathway for imported enzymes remains underutilized by qualified Asian suppliers with existing FDA master files.
- Cellular metabolism research reagent segment:Academic and CRO demand for high-specific-activity kinase preparations is outpacing supply from generalist biochemical distributors.
- EU Green Deal biomanufacturing incentives:Fermentation-based enzyme production qualifies for circular economy funding streams that offset capital costs for European production facilities.
Industry Challenges
- Fermentation engineering talent scarcity:European and North American producers face recruitment gaps for specialists in pH-stat control and fed-batch optimization at commercial scale.
- Pharmacopeial monograph synchronization delays:Divergent USP, EP, and ChP purity specifications force multi-standard compliance costs on exporters serving multiple registration territories.
- Legacy batch record system integration:Continuous processing adoption requires expensive MES upgrades to replace paper-based manufacturing execution systems in established facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Riboflavin Kinase Market |
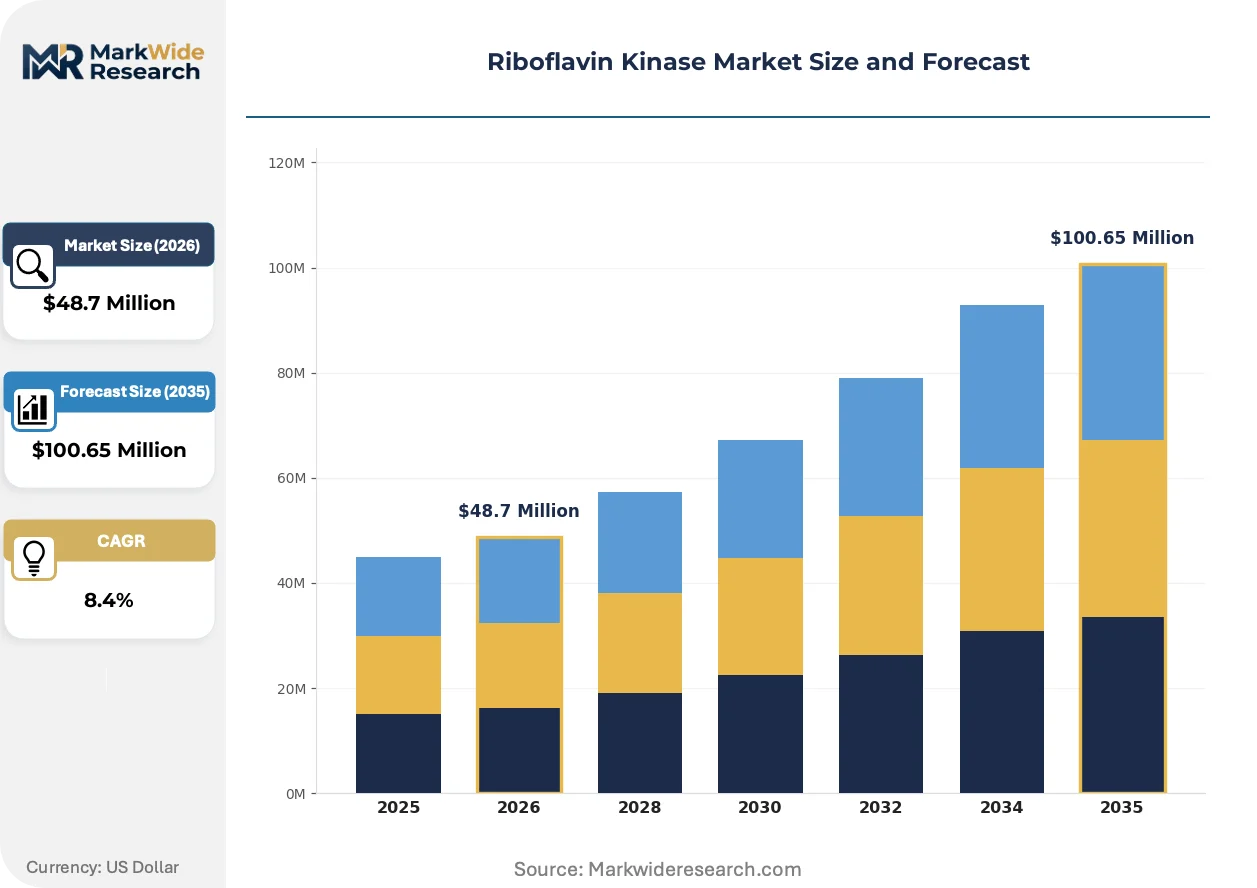
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $100.65 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Tablets, Capsules Application: Healthcare Supplements, Food Additives, Pharmaceuticals, Animal Feed End User: Pharmacies, Hospitals, Nutraceutical Manufacturers, Feed Producers Distribution Channel: Online Sales, Retail Stores, Distributors, Wholesalers |
| Companies Covered | BASF SE, Koninklijke DSM NV, Shanghai Acebright Pharmaceuticals Group Co. Ltd, Xinfa Pharmaceutical Co. Ltd, Hubei Guangji Pharmaceutical Co. Ltd, NB Group Co. Ltd, Hebei Shengxue dacheng Pharmaceutical Co. Ltd, Legend Industries, Duchefa Biochemie, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Riboflavin Kinase Market Evolving Landscape
Biocatalysis platform technologies are compressing development timelines for enzyme variants with altered substrate specificity, while regulatory data harmonization efforts are reshaping qualification requirements for multi-territory suppliers.
Immobilized riboflavin kinase preparations on methacrylate resins are miniaturizing reactor footprints for continuous FMN synthesis. Contract manufacturers serving orphan drug programs are adopting these packed-bed systems to reduce facility capital intensity. The technology is miniaturizing production economics for mid-scale pharmaceutical batches previously uneconomical under traditional stirred-tank fermentation.
EMA's revised excipient quality guidelines now mandate elemental impurity risk assessments for enzyme-derived drug substances, forcing suppliers to document heavy metal clearance across purification trains. European compounders are responding by qualifying additional ion-exchange polishing steps that extend release timelines by two to four weeks. High-purity human therapeutic grades bear disproportionate compliance burden relative to veterinary or research-grade categories.
Hospital and pharmacy channel buyers are consolidating supplier lists to reduce audit burden, preferring single-source relationships with manufacturers holding simultaneous FDA, EMA, and NMPA drug master files. This concentration is displacing fragmented procurement across multiple regional distributors. The shift is most visible in German and Swiss hospital purchasing cooperatives where GPO contract structures now specify dual-filed suppliers exclusively.
Riboflavin Kinase Market Segmentation
Segmentation in riboflavin kinase markets reflects divergent purity requirements across regulatory jurisdictions. FDA and EMA pharmaceutical-grade standards create tiered value capture that commodity feed-grade producers cannot access.
Product Type:
FDA Current Good Manufacturing Practice standards enforce endotoxin thresholds below 0.25 EU/mg for pharmaceutical-grade preparations, bifurcating the competitive landscape between validated and commodity suppliers.
- Powder:Lyophilized formulations dominate bulk pharmaceutical chemical distribution due to extended shelf stability and ambient temperature logistics. Hospital and pharmacy procurement teams in Germany and Switzerland specify powder grades for vitamin B2 derivative synthesis. Powder handles the majority of throughput; liquid is the fastest mover on share.
- Liquid:Aqueous enzyme preparations enable continuous enzymatic processing in contract manufacturing operations. Biopharmaceutical CMOs in India and China are installing immobilized enzyme reactor systems with real-time titer monitoring to serve Western pharmaceutical customers.
- Tablets:Solid dosage forms for direct healthcare supplement consumption require additional excipient compatibility testing under EMA revised guidelines.
- Capsules:Gelatin and vegetable-shell encapsulation targets nutraceutical channel distribution with simplified dosing protocols.
Powder formulations absorb the bulk of fermentation output; liquid preparations are climbing the fastest as continuous processing spreads.
Application:
Cost tier differentiation separates premium human therapeutic uses from price-sensitive animal nutrition applications where synthetic FMN routes compete.
- Healthcare Supplements:Pharmacy and hospital channels command premium pricing through validated supply chains with simultaneous FDA, EMA, and NMPA drug master files. German hospital purchasing cooperatives now specify dual-filed suppliers exclusively in GPO contracts.
- Pharmaceuticals:High-purity kinase serves as critical biocatalyst in vitamin B2 derivative synthesis for therapeutic formulations. EMA elemental impurity risk assessments force additional ion-exchange polishing steps that extend release timelines.
- Food Additives:Fortification applications for processed foods operate under FSSAI and FDA food additive regulations with lower purity thresholds than pharmaceutical grades.
- Animal Feed:Integrated livestock operations purchase through distributor networks on cost efficiency metrics where enzymatic purity premiums cannot be recovered against chemical phosphorylation alternatives.
Healthcare supplements concentrate margin capture; pharmaceuticals is expanding most quickly as orphan drug programs multiply.
End User:
Customer type determines audit burden intensity and supplier qualification depth across the value chain.
- Pharmacies:Retail dispensaries consolidate supplier lists to reduce audit burden, preferring single-source relationships with multi-filed manufacturers. Swiss and German pharmacy chains now exclude non-dual-filed vendors from tenders.
- Nutraceutical Manufacturers:Third-party enzyme processors in India and China are installing dedicated production lines to serve Western customers seeking qualified supply alternatives to European compounders.
- Hospitals:German and Swiss hospital purchasing cooperatives specify GPO contract structures with exclusive dual-filed supplier requirements.
- Feed Producers:Regional livestock operations in Brazil and Southeast Asia source bulk powder through distributor networks with minimal regulatory documentation.
Pharmacies dominate procurement volume; nutraceutical manufacturers are gaining share fastest as contract manufacturing expands.
Distribution Channel:
Channel selection reflects buyer scale and regulatory documentation requirements rather than pure cost optimization.
- Distributors:Specialized biochemical distributors handle multi-territory logistics for research reagent and pharmaceutical-grade segments requiring cold chain validation and customs documentation for NMPA and CDSCO registrations.
- Online Sales:E-commerce platforms serve academic and CRO demand for high-specific-activity kinase preparations that outpaces supply from generalist biochemical distributors.
- Retail Stores:Pharmacy and health food retail channels move finished supplement formulations rather than bulk enzyme.
- Wholesalers:Volume aggregation for animal feed applications operates through regional agricultural supply networks with minimal specification requirements.
Distributors manage the largest flow; online sales shows steepest expansion trajectory as research reagent procurement digitizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European compounders command premium pricing for validated pharmaceutical-grade kinase while Chinese fermentation specialists capture volume through bulk powder exports. This asymmetry reflects divergent regulatory compliance costs and downstream formulation capabilities across production clusters.
United States
FDA Current Good Manufacturing Practice enforcement tightens endotoxin thresholds for vitamin B2 derivative manufacturers. Hospital purchasing cooperatives in the Northeast now specify dual-filed suppliers exclusively in GPO contracts. The Greater Boston biopharma corridor attracts contract manufacturing investment for high-purity enzyme processing.
Germany
Pharmaceutical-grade demand from nutraceutical compounders drives specialized biocatalysis procurement. EMA revised excipient quality guidelines mandate elemental impurity risk assessments that extend release timelines. The Rhine-Ruhr industrial basin concentrates enzymatic process leadership for human therapeutic applications.
China
NMPA bioactive substance registration requirements accelerate fermentation capacity expansion for domestic and export markets. Yangtze River Delta producers dominate upstream riboflavin supply through closed-system bioreactor installations. Shanghai pharmaceutical clusters integrate downstream formulation capabilities for regional healthcare supplement brands.
India
CDSCO parallel registration pathways attract contract manufacturing investment from Western pharmaceutical customers. Third-party enzyme processors in Hyderabad and Bangalore install dedicated production lines for qualified supply alternatives. The country's fermentation engineering workforce expansion outpaces European recruitment timelines.
Brazil
ANVISA's bioactive substance registration pathway for imported enzymes remains underpenetrated by qualified Asian suppliers. Regional livestock operations in São Paulo state source bulk powder through agricultural distributor networks. Local pharmaceutical formulators seek validated kinase supply for expanding healthcare supplement portfolios.
Riboflavin Kinase Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the riboflavin kinase supply base. European compounders concentrate on high-specification formulations with validated endotoxin controls, while Asian fermentation specialists compete on scale and workforce availability. The market structure separates into three strategic archetypes: integrated vitamin B2 complex producers, enzymatic process specialists, and bulk fermentation scale operators. Dominant competitive moves include captive supply integration into downstream formulation and geographic expansion through qualified contract manufacturing partnerships.
Within the integrated producer tier, BASF SE and Koninklijke DSM NV exemplify European compounders with pharmaceutical-grade capabilities. Shanghai Acebright Pharmaceuticals Group Co. Ltd occupies a position among Asian fermentation scale operators serving regional feed and bulk pharmaceutical markets. These three anchors represent the divergence between technology-driven and cost-driven competitive positioning across the value chain.
| Leading Market Players |
|---|
| BASF SE |
| Koninklijke DSM NV |
| Shanghai Acebright Pharmaceuticals Group Co. Ltd |
| Xinfa Pharmaceutical Co. Ltd |
| Hubei Guangji Pharmaceutical Co. Ltd |
| NB Group Co. Ltd |
| Hebei Shengxue dacheng Pharmaceutical Co. Ltd |
| Legend Industries |
| Duchefa Biochemie |
| Others |
Value Network & Pricing Analysis
Fermentation capacity utilization rates above 85% in Yangtze River Delta facilities create asymmetric scale economies that compress unit economics for bulk powder grades while elevating price floors for pharmaceutical-grade output. This concentration dynamic forces European formulators to absorb logistics premiums for qualified supply or invest in captive fermentation assets.
Pricing Analysis
The customization-premium spread separates configured-to-order pharmaceutical-grade kinase from standard feed-grade powder, with contract-based long-term offtake dominating validated supply relationships. Price differentiation hinges on FDA endotoxin certification tier and magnesium cofactor inclusion in process economics. Cost compression in feed-grade segments is intensifying because synthetic FMN routes undercut enzymatic premiums. Animal feed producers exhibit highest price sensitivity; hospital purchasing cooperatives show lowest.
Supply Chain Analysis
Inventory lead times for pharmaceutical-grade powder extend 8-12 weeks due to ion-exchange polishing validation queues at European compounders. Supply concentrates in China, India, and Germany for fermentation and downstream processing respectively. Raw material dependencies center on riboflavin feedstock, magnesium sulfate cofactors, and methacrylate resin carriers for immobilization. Single-source vulnerability from Yangtze River Delta clustering creates tariff exposure risk. Distribution runs through specialized biochemical distributors with cold chain validation for multi-territory NMPA and CDSCO registrations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated hospital purchasing cooperatives in Germany and Switzerland, where GPO contract structures now specify exclusive dual-filed supplier requirements that fragment procurement alternatives.
For Market Incumbents: Secure captive riboflavin supply through backward integration into Yangtze River Delta fermentation assets or long-term offtake agreements with validated Chinese producers. Prioritize EMA elemental impurity certification investment to defend margin position against Asian contract manufacturers installing dedicated kinase production lines. For New Entrants and Emerging Players: Continuous enzymatic processing service gaps in mid-scale orphan drug manufacturing present white-space entry points. Target Brazilian pharmaceutical formulators seeking ANVISA-registered kinase supply as the most penetrable geography. Deploy qualified contract manufacturing partnerships as the primary go-to-market angle rather than greenfield fermentation buildout. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among enzymatic process specialists with simultaneous FDA and EMA drug master files. Long-term viability over the projection horizon favors acquisition targets with immobilized enzyme reactor technology and established CMO relationships. Watch for CDSCO registration acceleration in Indian third-party processors as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Assets | Captive riboflavin supply secures margin control against Yangtze River Delta price volatility. |
| EMA Elemental Impurity Certification | Ion-exchange polishing qualification extends release timelines but locks in hospital GPO contracts. |
| Immobilized Enzyme Reactor Deployment | Methacrylate resin packed-bed systems miniaturize economics for mid-scale pharmaceutical batches. |
| ANVISA Registration Pathway Utilization | Brazilian bioactive substance filing opens underpenetrated pharmaceutical market for qualified Asian suppliers. |
| Continuous Processing Technology Adoption | Liquid formulation capability pulls investment from biopharmaceutical CMOs seeking real-time titer monitoring. |
Research Methodology
Cross-validation between fermentation engineering executives and regulatory affairs specialists anchors the qualitative findings, with secondary validation against NMPA registration databases and EMA excipient quality guideline revisions. Primary interviews encompassed plant managers at Yangtze River Delta facilities, procurement leads at German hospital purchasing cooperatives, and technical R&D directors at European compounders. Secondary sources included FDA drug master file records, CDSCO bioactive substance registrations, customs trade data for riboflavin derivatives, and SEC filings from integrated vitamin B2 producers. Bottom-up capacity modeling and top-down demand segmentation triangulate volume estimates.
Sensitivity analysis around magnesium cofactor price volatility and fermentation yield assumptions informs the projection framework. Segmentation dimensions encompass product grade tier, application end-use, and regional regulatory cluster. CAGRs derive from compound growth trajectory fitting across the modeling period. Industry-specific inputs include pH-stat control efficiency metrics and fed-batch optimization parameters from commercial-scale operations.
Forecasts assume regulatory continuity in FDA Current Good Manufacturing Practice enforcement and EMA excipient quality guidelines; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Services
Biologics Contract Manufacturing Market
Biotechnology Services
Acetylglucosamine Market
Biotechnology Services
Global Custom Antibody Market
Biotechnology Services
Phycobiliproteins Market
Biotechnology Services
Biomarker Research Services Market
Biotechnology Services
Global Cell Isolation/Cell Separation Market
Biotechnology Services
Global DNA and RNA Banking Services Market
Biotechnology Services
Global Vero Cell Media Market
Biotechnology Services
Loop-Mediated Isothermal Amplification (LAMP) Market
Biotechnology Services
Global Reporter Gene Assay Market
Biotechnology Services
Europe Recombinant Protein Manufacturing Services Market
Biotechnology Services
Global Vector Control Market
Biotechnology Services
Marine Polysaccharides Fucoidan Alginate Market
Biotechnology Services
Peptide and Oligonucleotide CDMO Market
Biotechnology Services
Plasma Feed Market
Biotechnology Services
Europe Downstream Processing Market