
 Robotic Arms in Laboratories Market | 2026-2036
Robotic Arms in Laboratories Market Size, Share, and Industry Trends Forecast 2026-2036
Robotic Arms in Laboratories Market Analytics
Pharmaceutical companies are collapsing the traditional gap between research and clinical operations by deploying robotic arms for end-to-end automation. Thermo Fisher Scientific Inc. leverages its integrated platform strategy to dominate high-throughput screening installations across North American pharma networks. Hamilton Company sustains its position through precision liquid-handling specialization that anchors recurring consumable revenue streams.
Robotic arms in laboratories are programmable articulated or Cartesian manipulators with positional repeatability typically below 0.1 millimeter, designed to execute repetitive protocols such as sample aliquoting, plate handling, and reagent dispensing in controlled environments. Their primary purpose is to eliminate human variability while sustaining throughput in 24/7 operations. Collaborative robots are capturing the fastest expansion trajectory as labs retrofit existing benches without safety enclosures, while SCARA configurations retain margin concentration in pharmaceutical quality control due to their speed-rigidity balance. Cartesian robots occupy mature demand in clinical laboratories where simple linear motions suffice for high-volume sample processing.
FDA 21 CFR Part 11 and ISO 13485 shape product validation requirements, compelling vendors to embed audit trails and electronic signature capabilities directly into control software. EPA Good Automated Laboratory Practices further constrain instrument qualification protocols for environmental testing applications. Buyers must weigh total cost of ownership against interoperability with existing Laboratory Information Management Systems when evaluating platform commitments.
Market Dynamics
FDA 21 CFR Part 11 validation requirements are compressing vendor qualification timelines and forcing pharmaceutical buyers toward pre-validated robotic platforms rather than custom integrations.
Growth Catalysts
- High-throughput screening automation:Pharmaceutical manufacturers are collapsing research-to-clinical handoffs by deploying end-to-end robotic workflows for compound screening and assay development.
- EPA Good Automated Laboratory Practices:Environmental testing laboratories face mandated instrument qualification protocols that favor robotic systems with embedded audit trails and electronic signature capabilities.
- Collaborative robot retrofitting:Existing bench infrastructure across academic and contract research facilities is being upgraded with force-limited cobots that operate without safety enclosures.
Market Restraints
- Precision motion component concentration:Harmonic drive and linear encoder supply chains concentrate in East Asian manufacturing clusters, exposing lead times to geopolitical friction.
- Validation cost structure:FDA-compliant software documentation and IQ/OQ/PQ protocols add 15-25% to total system cost for pharmaceutical deployments.
- Liquid-handling accuracy thresholds:Sub-microliter dispensing repeatability below 0.5% CV remains technically constrained for high-viscosity reagents.
Strategic Opportunities
- Cell therapy manufacturing:Aseptic processing requirements in CAR-T and stem cell production are creating demand for isolator-integrated robotic arms with vaporized hydrogen peroxide compatibility.
- India's PLI scheme for medical devices:Domestic manufacturing incentives are attracting robotic component assembly and localized service infrastructure development.
- AI-guided adaptive pipetting:Machine vision convergence with force-feedback control is enabling real-time droplet verification that reduces failed assay rates.
Industry Challenges
- Mechatronics talent scarcity:Cross-functional expertise spanning precision mechanics, control systems, and GxP compliance remains concentrated among senior engineers at established automation vendors.
- LIMS integration complexity:Proprietary communication protocols from legacy laboratory information management systems create middleware development burdens for multi-vendor robotic installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Robotic Arms in Laboratories Market |
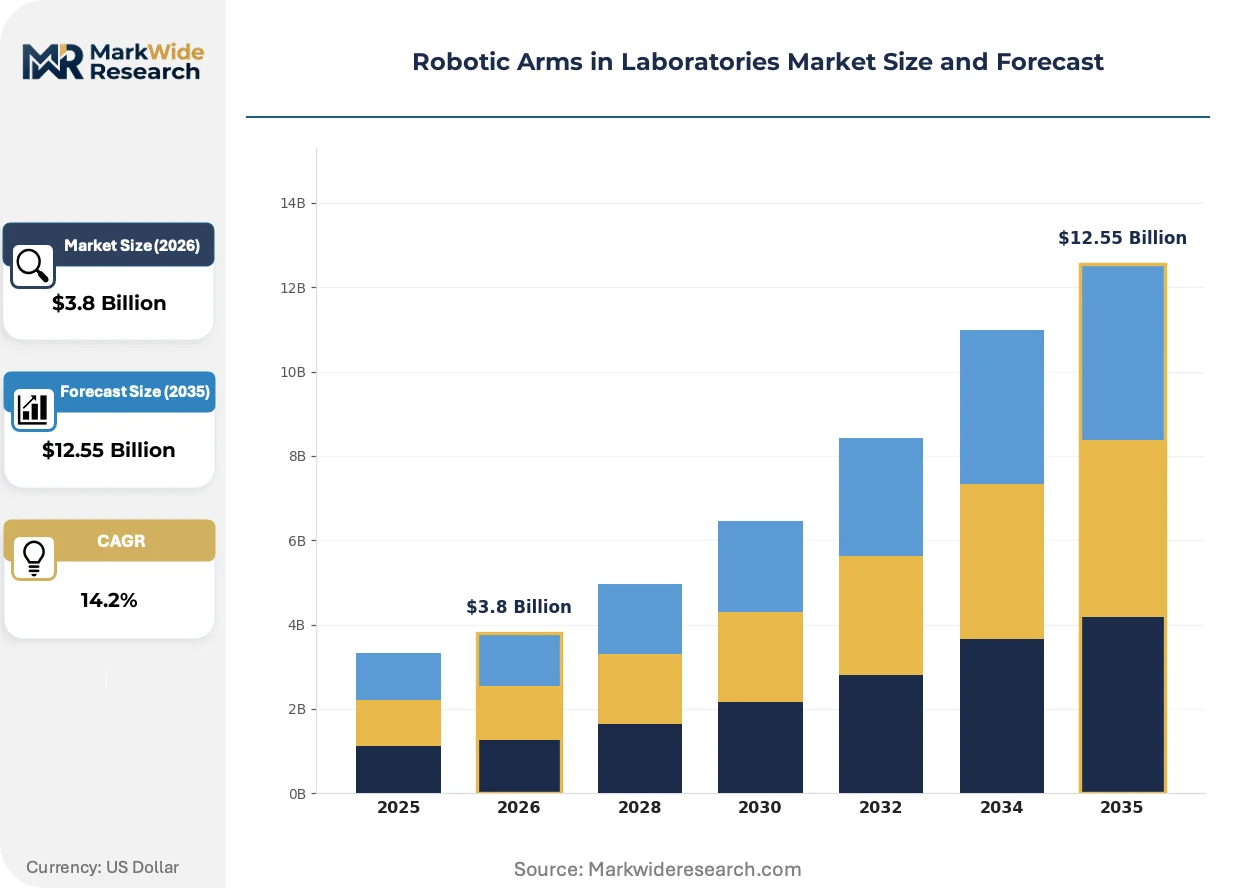
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Articulated Robots, SCARA Robots, Cartesian Robots, Collaborative Robots End User: Research Labs, Pharmaceutical Companies, Educational Institutions, Clinical Laboratories Application: Sample Handling, Automated Assembly, Quality Control, Material Handling Technology: Machine Learning, Computer Vision, Sensor Technology, Control Systems |
| Companies Covered | Thermo Fisher Scientific Inc., Hamilton Company, Hudson Robotics, Inc., Tecan Group, Anton Paar GmbH, Beckman Coulter Inc., PerkinElmer Inc., Peak Analysis & Automation, Biomérieux SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Robotic Arms in Laboratories Market Evolving Landscape
Robotic architectures are converging around modular payload systems that decouple manipulator hardware from application-specific end-effectors, compressing reconfiguration downtime between protocols.
Parallel kinematics for microplate handling is miniaturizing. Delta robots with carbon-fiber linkages now achieve sub-50-micron repeatability in footprint-constrained biosafety cabinets. Contract research organizations in Boston and San Diego are adopting these platforms for viral vector production. The technology is miniaturizing cleanroom infrastructure requirements while maintaining the speed-rigidity balance previously exclusive to larger SCARA configurations.
EU MDR Annex I general safety and performance requirements are extending to in-vitro diagnostic instrument software. Robotic control systems must now demonstrate cybersecurity validation and post-market surveillance traceability. European diagnostic manufacturers are responding by embedding IEC 62304-compliant software lifecycle documentation into platform releases, shifting competitive advantage toward vendors with established quality management systems.
Service contract unbundling is fragmenting traditional vendor-buyer relationships. End-users are separating hardware maintenance from application support and software updates, creating procurement leverage. Academic core facilities and mid-sized biotechs in the United States are driving this pattern, negotiating à la carte service tiers that match utilization intensity rather than accepting bundled annual contracts.
Robotic Arms in Laboratories Market Segmentation
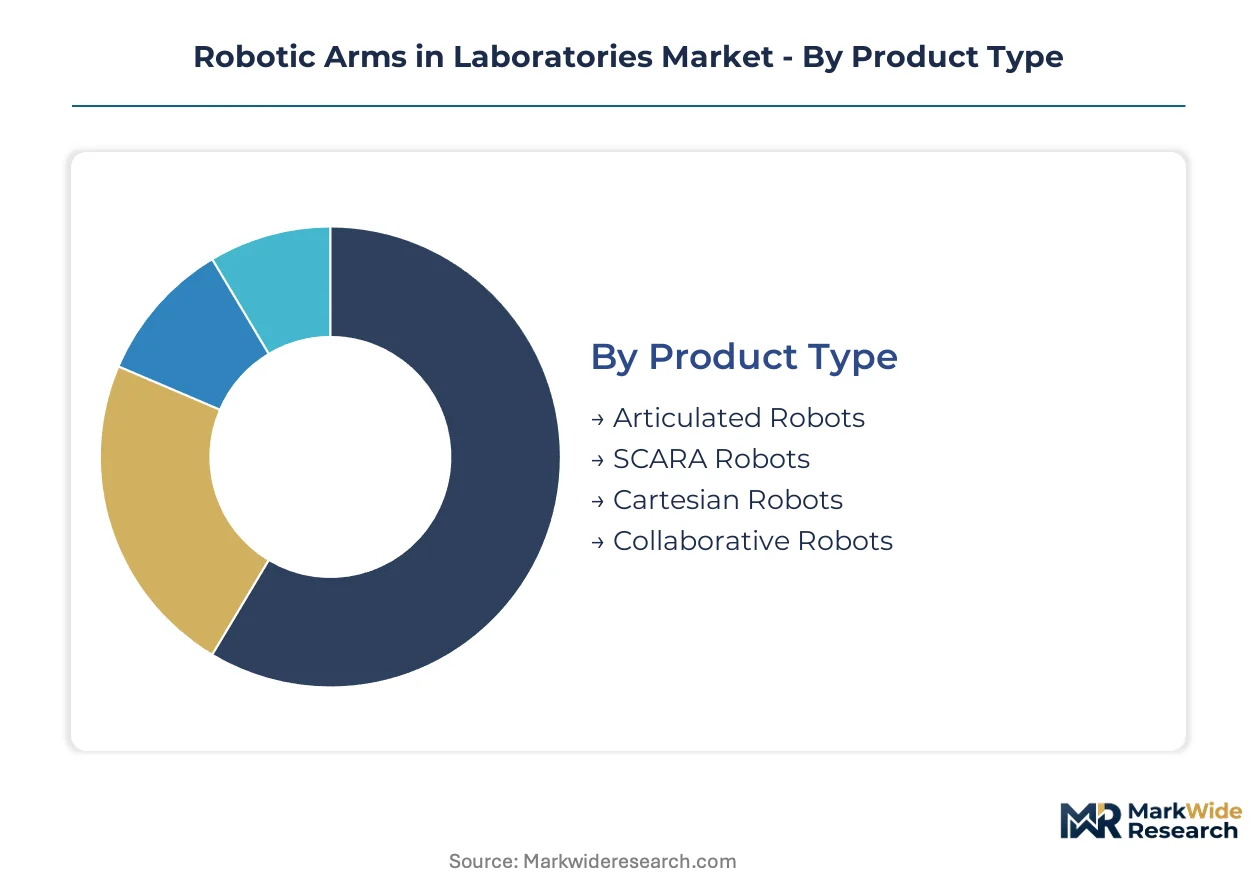
Segmentation in laboratory robotics reveals how hardware architectures, end-user workflows, and embedded intelligence layers compete for capital allocation. Buyers prioritize interoperability and validation documentation over raw specifications, reshaping vendor competitive priorities across every dimension.
Product Type:
Cartesian configurations face the most acute substitution pressure from collaborative platforms that retrofit existing benches without structural modifications.
- Articulated Robots:Six-axis kinematic chains with rotary joints achieve positional repeatability below 0.05 millimeter in pharmaceutical quality control suites. Thermo Fisher Scientific deploys these for end-to-end compound screening in Boston biotech clusters, though harmonic drive supply concentration in East Asia constrains scaling.
- SCARA Robots:Selective compliance articulated arms balance speed and rigidity through parallel joint architecture. These dominate high-throughput microplate handling in San Diego contract research facilities where FDA 21 CFR Part 11 validation requirements favor pre-qualified platforms.
- Cartesian Robots:Three-axis linear gantries execute simple pick-and-place motions in clinical laboratories processing high-volume sample loads.
- Collaborative Robots:Force-limited cobots with embedded safety sensors retrofit academic core facilities without protective enclosures, compressing installation timelines.
Articulated configurations retain volume leadership; collaborative robots hold the steepest expansion curve.
End User:
Cost tier stratification separates capital-intensive pharmaceutical deployments from budget-constrained academic procurement patterns.
- Research Labs:Academic and government facilities prioritize modular payload systems that reconfigure between proteomics, genomics, and cell biology protocols. Core facilities at MIT and Stanford negotiate unbundled service contracts separating hardware maintenance from application support.
- Pharmaceutical Companies:Merck and Pfizer collapse research-to-clinical handoffs through validated robotic workflows for high-throughput screening and assay development, absorbing 15-25% validation cost premiums for FDA-compliant documentation.
- Educational Institutions:Undergraduate training programs purchase entry-level Cartesian systems for liquid-handling fundamentals instruction.
- Clinical Laboratories:Hospital-based diagnostic operations deploy SCARA arms for 24/7 sample processing where simple linear motions suffice.
Pharmaceutical buyers command the highest per-unit spend; research labs generate the largest aggregate installation base.
Application:
Application maturity correlates with regulatory exposure, with quality control workflows commanding premium pricing for embedded audit trail capabilities.
- Sample Handling:Automated aliquoting, centrifugation loading, and storage retrieval in biobanks demand sub-microliter dispensing repeatability. CAR-T manufacturing facilities in Maryland integrate isolator-compatible arms with vaporized hydrogen peroxide sterilization cycles.
- Automated Assembly:Microplate sealing, cap decapping, and reagent cartridge construction in consumables manufacturing lines.
- Quality Control:In-process testing and release assays in pharmaceutical production require ISO 13485-aligned instrument qualification protocols with electronic signature capture.
- Material Handling:Bulk reagent transport and waste disposal automation in high-throughput screening facilities.
Sample handling dominates current deployment volumes; quality control applications are climbing fastest as EU MDR Annex I extends to diagnostic instrument software.
Technology:
Technology integration intensity separates premium platforms with embedded intelligence from commodity hardware requiring external control systems.
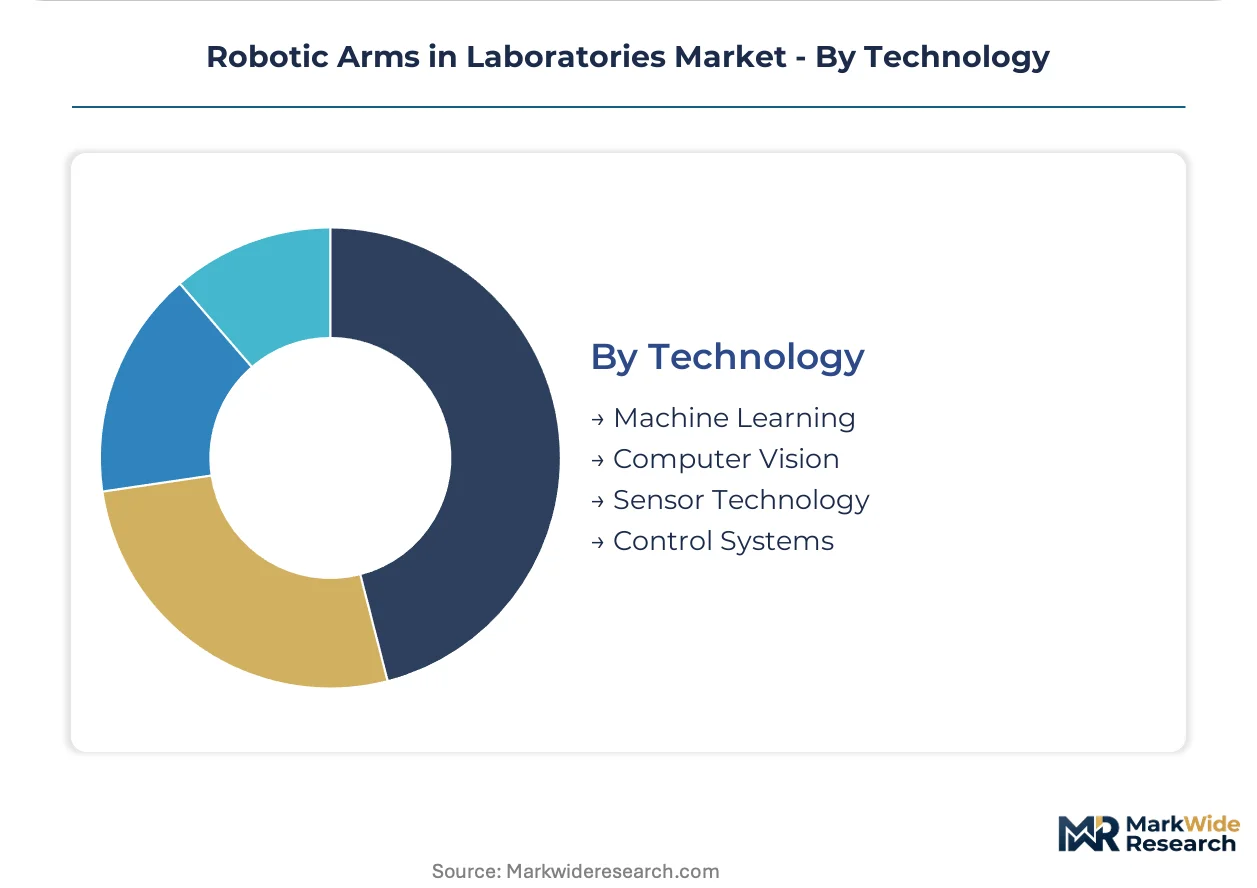
- Machine Learning:Adaptive pipetting algorithms trained on assay failure patterns enable real-time droplet verification, reducing failed screening rates in compound libraries. These capabilities concentrate in platforms from established automation vendors with GxP-compliant software lifecycle documentation.
- Computer Vision:Machine vision systems verify tip presence, liquid levels, and plate orientation during unattended operation.
- Sensor Technology:Force-feedback torque sensors and capacitive liquid level detection enable collaborative robot safety and precision liquid handling.
- Control Systems:Proprietary motion controllers and IEC 62304-compliant software architectures manage trajectory planning and LIMS integration.
Control systems constitute the mandatory foundation layer; machine learning represents the fastest-climbing differentiation vector.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical logistics corridors anchor European supply chains for laboratory automation equipment, while trans-Pacific shipping lanes from Shanghai and Busan feed component flows into North American biotech clusters.
United States
FDA 21 CFR Part 11 compliance deadlines compress procurement timelines for pharmaceutical buyers. The National Institutes of Health's extramural funding sustains academic core facility upgrades across the research ecosystem. Greater Boston's biotech corridor concentrates CAR-T manufacturing installations with isolator-integrated robotic arms.
Germany
EU MDR Annex I software validation requirements extend to diagnostic instrument platforms. The country's national pharmaceutical regulator enforces post-market surveillance traceability for robotic control systems. Baden-Württemberg's precision engineering clusters supply harmonic drive components to automation OEMs.
China
NMPA medical device registration pathways accelerate for in-vitro diagnostic instruments with embedded robotics. The MIIT's intelligent manufacturing initiatives subsidize laboratory automation adoption in provincial hospital networks. Yangtze River Delta biopharma parks deploy high-throughput screening platforms for contract research services.
India
CDSCO medical device rules harmonize with IMDRF standards for automated diagnostic platforms. The PLI scheme for medical devices attracts robotic component assembly and localized service infrastructure. Maharashtra's pharmaceutical manufacturing zones integrate SCARA arms into quality control workflows.
Switzerland
Swissmedic's quality system requirements align with ISO 13485 for robotic instrument qualification. The country's precision mechanics heritage sustains specialized encoder and motion control component production. Basel's pharmaceutical headquarters drive demand for validated robotic platforms in drug discovery operations.
Robotic Arms in Laboratories Market Competitive Landscape
Listed leaders compete with private specialists across validation documentation and service contract structures. The vendor base stratifies into three tiers: diversified life science conglomerates with integrated platform portfolios, precision liquid-handling specialists with recurring consumable revenue, and regional automation integrators serving mid-sized contract research facilities. Dominant competitive moves include strategic partnerships for LIMS interoperability and geographic expansion through localized service infrastructure.
Among diversified platform providers, Thermo Fisher Scientific Inc. exemplifies the integrated life science archetype spanning instrumentation through consumables. Hamilton Company occupies the precision specialist position with force-feedback liquid-handling expertise. Hudson Robotics, Inc. represents the mid-market automation tier serving academic core facilities with modular payload configurations.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Hamilton Company |
| Hudson Robotics, Inc. |
| Tecan Group |
| Anton Paar GmbH |
| Beckman Coulter Inc. |
| PerkinElmer Inc. |
| Peak Analysis & Automation |
| Biomérieux SA |
| Others |
Value Network & Pricing Analysis
Carbon-fiber linkage substitution for traditional steel armatures is redrawing component sourcing maps from Baden-Württemberg toward Yangtze River Delta manufacturing zones while compressing per-unit material costs for precision motion systems.
Pricing Analysis
Volume-discount tiering structures separate pharmaceutical procurement contracts from academic core facility purchases. Pricing stratifies across premium, standard, and economy tiers based on FDA 21 CFR Part 11 validation documentation depth and embedded software audit trail capabilities. Cost compression in economy-tier Cartesian configurations is intensifying because collaborative robot retrofitting eliminates enclosure infrastructure. Contract research organizations in Boston and San Diego exhibit the least price sensitivity, absorbing 15-25% validation premiums, while undergraduate training programs in educational institutions drive aggressive standard-tier negotiation.
Supply Chain Analysis
Inventory lead times for harmonic drive gearboxes now stretch 14-20 weeks, constraining vendor qualification timelines for pharmaceutical buyers. Precision motion component manufacturing concentrates in Germany, Japan, and China, with encoder production anchored in Swiss precision mechanics clusters. Supply chains draw from rare-earth magnet feedstocks, high-grade aluminum extrusions, and semiconductor-grade sensor substrates. Single-source vulnerability in vaporized hydrogen peroxide-compatible isolator seals creates qualification bottlenecks for CAR-T manufacturing installations. Distribution runs through trans-Pacific shipping lanes feeding North American biotech clusters and Port of Rotterdam corridors serving European diagnostic manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent robotic arm vendors face substitution pressure from AI-guided adaptive pipetting platforms that bypass traditional hardware architectures entirely.
For Market Incumbents: Secure harmonic drive supply agreements through backward integration into East Asian manufacturing clusters or captive supply partnerships with Baden-Württemberg precision engineering specialists. Lock pharmaceutical buyers into bundled validation documentation and IQ/OQ/PQ protocol packages that raise switching costs against emerging AI-native competitors. For New Entrants and Emerging Players: Lead with machine vision convergence offerings targeting academic core facilities in the United States where unbundled service contracts create procurement leverage. India's PLI scheme for medical devices offers the most penetrable geography for localized component assembly and service infrastructure development. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed precision liquid-handling specialists holding recurring consumable revenue streams but lacking GxP-compliant software documentation. Long-term viability hinges on IEC 62304-compliant control system architectures as EU MDR Annex I extends to diagnostic instrument platforms. Watch for FDA enforcement discretion shifts on 21 CFR Part 11 electronic signature requirements as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Thermo Fisher's consolidated LIMS interoperability compresses multi-vendor middleware development burdens for pharmaceutical networks. |
| Regulatory Approval Pathway | Pre-validated FDA 21 CFR Part 11 platforms accelerate procurement timelines for compound screening installations in Boston biotech corridors. |
| Backward Integration | Captive supply of harmonic drive components insulates lead times from East Asian geopolitical friction affecting pharmaceutical qualification schedules. |
| Geographic Expansion | Localized service infrastructure in Maharashtra pharmaceutical zones captures CDSCO-aligned instrument qualification demand from quality control workflows. |
| Strategic Partnership | AI-guided adaptive pipetting alliances with machine vision specialists enable real-time droplet verification that reduces failed assay rates in high-throughput screening. |
Research Methodology
Desk research of FDA 510(k) filings, ISO 13485 certification databases, and patent landscapes preceded structured interviews with automation vendor product managers, pharmaceutical quality control directors, academic core facility managers, and GxP compliance consultants. Secondary validation drew from SEC 10-K instrument revenue disclosures, NIH extramural funding reports, and EU MDR technical documentation filings. Bottom-up installation counts across Boston and San Diego biotech clusters triangulated against top-down vendor shipment estimates.
Variance decomposition across product type, end user, application, and technology segmentation dimensions shaped the analytical framework throughout the projection horizon. CAGRs derived from curve-fitting historical installation growth against pharmaceutical R&D expenditure trajectories and academic funding cycles. Forecast inputs incorporated NMPA registration pathway acceleration timelines and PLI scheme subsidy disbursement patterns.
Underlying assumptions cover sustained NIH funding levels and stable East Asian component supply chains, with deviation risk concentrated in FDA enforcement discretion shifts and EU MDR software validation timeline extensions. Revision becomes warranted when collaborative robot safety standard revisions cross implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
Laboratory Andrology Equipment Market
Biotechnology Equipment
Global Cell Separation Technology Market
Biotechnology Equipment
Global Latex Agglutination Test Kits Market
Biotechnology Equipment
Biobanking Equipment Market
Biotechnology Equipment
Global Bioreactor Market
Biotechnology Equipment
Automated Molecular Diagnostics Testing System Market
Biotechnology Equipment
Automated Cell Culture Systems Market
Biotechnology Equipment
US Cell Culture Media Market
Biotechnology Equipment
Single Use Bioprocessing Market
Biotechnology Equipment
Moving Bed Bioreactor Market
Biotechnology Equipment
Plant Phenotyping Equipment Market
Biotechnology Equipment
Global Bovine Serum Albumin Market
Biotechnology Equipment
United States Transfection Technologies Market
Biotechnology Equipment
Global Transfection Technologies Market
Biotechnology Equipment
IVF Workstation Market
Biotechnology Equipment
Automated Cell Counting Market