
 Antibody Drug Conjugates Market | 2026-2036
Antibody Drug Conjugates Market Size, Share, and Industry Trends Forecast 2026-2036
Antibody Drug Conjugates Market Intelligence
Next-generation payloads with higher potency is reorganizing the therapeutic landscape for difficult-to-treat cancers. Seagen Inc. leverages its pioneering work in ADC technology to maintain a strong portfolio in hematologic malignancies. Daiichi Sankyo Company Ltd competes with its proprietary DXd ADC technology, while F. Hoffmann-La Roche Ltd sustains its market presence through established products like Trastuzumab Emtansine.
Antibody Drug Conjugates are a class of biopharmaceutical drugs designed as targeted therapy for treating cancer. They consist of a monoclonal antibody linked to a biologically active cytotoxic payload via a chemical linker. Within therapy areas, oncology applications, especially for breast cancer and lymphoma, command the largest share. The development of novel cleavable and non-cleavable linkers represents a critical area of innovation, influencing drug stability and efficacy.
The U.S. Food and Drug Administration (FDA) provides accelerated approval pathways for ADCs targeting unmet medical needs. Similarly, the European Medicines Agency (EMA) and Japan's Pharmaceuticals and Medical Devices Agency (PMDA) have frameworks that support the development of innovative cancer therapies. Stakeholders must navigate the complex intellectual property landscape and manage the high costs of clinical development to succeed.
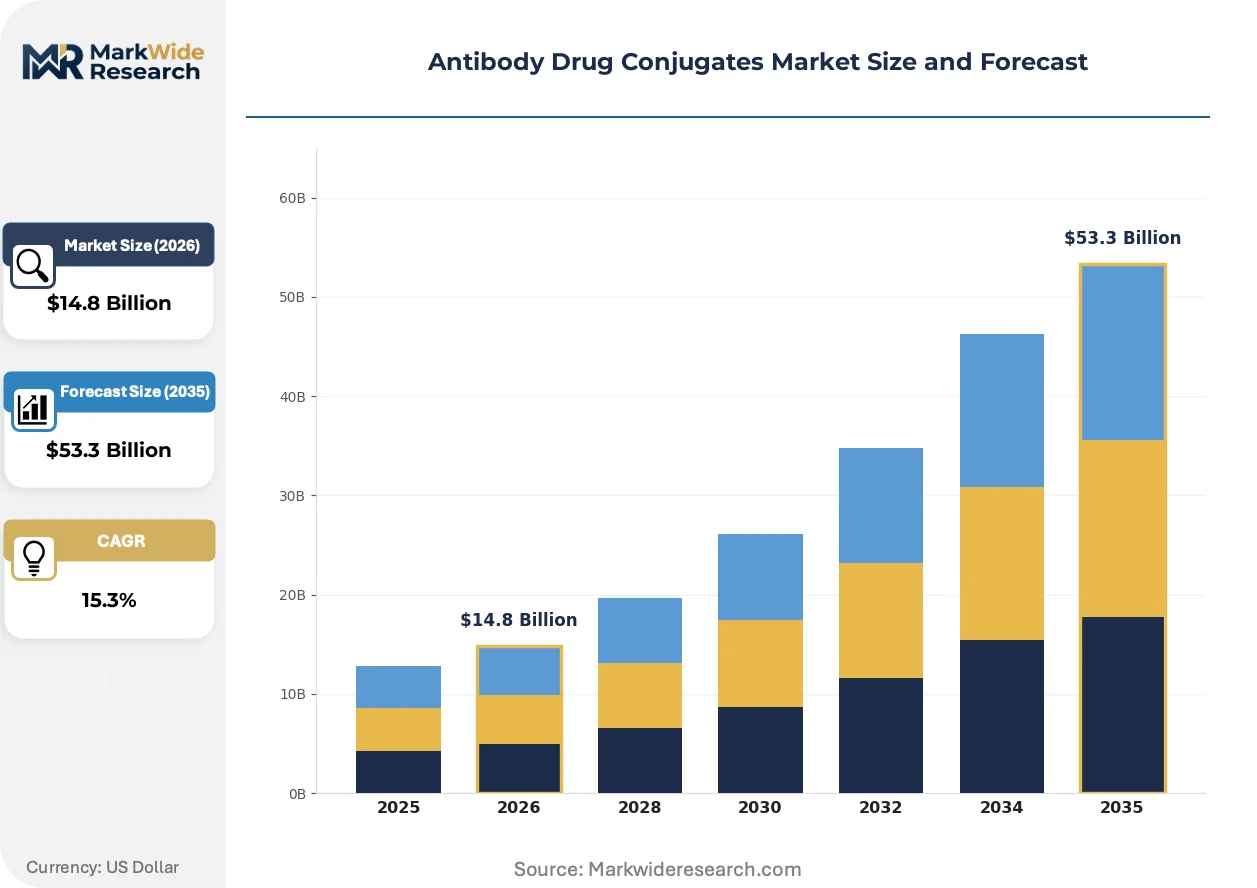
Market Dynamics
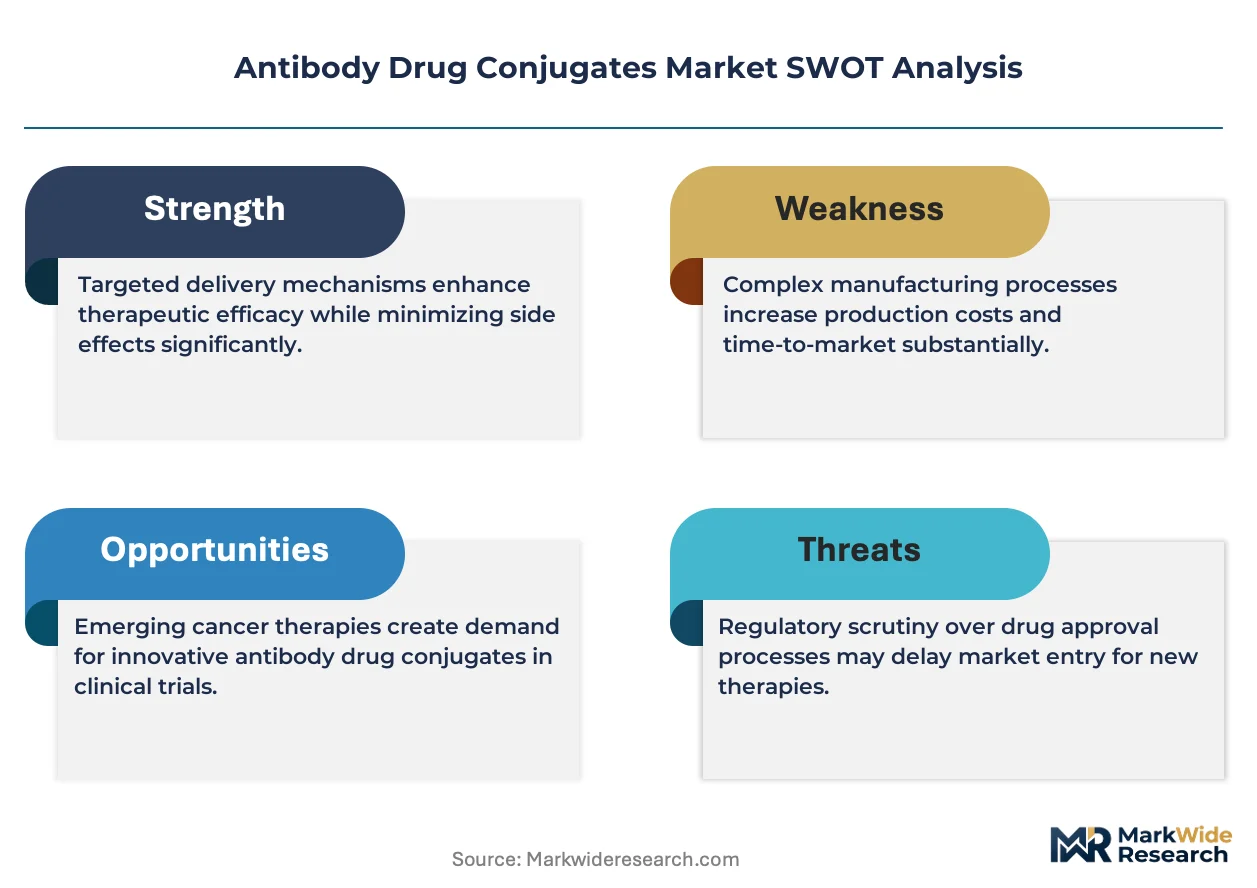
The balance between escalating payload potency and the necessity for ultra-precise targeting defines the ADC market's core tension. This dynamic compels continuous innovation in linker chemistry and monoclonal antibody engineering to mitigate off-target effects while maximizing therapeutic efficacy for difficult-to-treat cancers.
Growth Catalysts
- Accelerated Regulatory Pathways:The FDA's framework, including Breakthrough Therapy Designation, expedites the clinical review process for ADCs that address significant unmet medical needs in oncology.
- Linker Technology Advancement:Innovations in cleavable linkers, particularly enzyme-labile and pH-sensitive variants, improve the controlled release of cytotoxic payloads, enhancing efficacy and reducing systemic toxicity.
- Biomarker Discovery:Expanding research in genomics and proteomics is identifying novel tumor-specific antigens, opening new therapeutic avenues for ADC development beyond established targets like HER2.
Market Restraints
- High Manufacturing Costs:The complex multi-step synthesis and conjugation process, combining monoclonal antibody production with potent cytotoxic drug chemistry, drives exceptionally high cost of goods.
- Mechanisms of Resistance:Tumor cells can develop resistance through antigen loss, alterations in lysosomal function, or upregulation of drug efflux pumps, limiting the durability of ADC treatment.
- Intellectual Property Complexity:The patent landscape is highly fragmented across antibody, linker, and payload components, requiring developers to navigate intricate cross-licensing agreements which can delay programs.
Strategic Opportunities
- Therapeutic Area Expansion:Exploring applications beyond oncology, such as in immunology for treating autoimmune disorders, represents a significant avenue for market growth by targeting specific pathogenic cell populations.
- Novel Payload Development:The creation of payloads with new mechanisms of action, including DNA damage response inhibitors or immunomodulators, can address resistance to traditional microtubule inhibitors.
- Clinical Trial Globalization:Establishing clinical trial sites in emerging markets like Brazil and South Korea can accelerate patient enrollment, particularly for cancers with high regional prevalence.
Industry Challenges
- Interdisciplinary Talent Gap:A shortage of scientists and engineers with dual expertise in large-molecule biologics and small-molecule high-potency chemistry hampers process development and scale-up activities.
- Payload-Related Toxicity:Accurately predicting and mitigating off-target toxicities associated with the cytotoxic payload remains a critical hurdle, often complicating dose selection and clinical trial design.
- Supply Chain Security:Ensuring a stable supply of highly potent payloads and proprietary linker technologies from a limited number of specialized contract manufacturers is a persistent operational risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antibody Drug Conjugates Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $53.3 Billion |
| CAGR (2026 – 2036) | 15.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Brentuximab Vedotin, Trastuzumab Emtansine, Inotuzumab Ozogamicin, Polatuzumab Vedotin, Moxetumomab Pasudotox Therapy Area: Oncology, Hematologic Malignancies, Breast Cancer, Lymphoma, Leukemia End User: Specialty Clinics, Cancer Treatment Centers, Research Institutes, Biopharmaceutical Companies Linker Technology: Cleavable Linkers, Non-Cleavable Linkers, Enzyme-Responsive Linkers, Acid-Labile Linkers |
| Companies Covered | Seagen Inc., Gilead Sciences Inc., F. Hoffmann-La Roche Ltd, ADC Therapeutics SA, Daiichi Sankyo Company Ltd, Pfizer Inc., Takeda Pharmaceutical Company Ltd, GSK plc, AstraZeneca, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antibody Drug Conjugates Market Strategic Shifts & Innovations
A fundamental shift toward optimizing the therapeutic index is underway, moving beyond raw cytotoxicity to an emphasis on precision and safety. This evolution is driven by innovations in payload design and conditional activation mechanisms that better distinguish cancerous from healthy tissue.
Site-specific conjugation technologies allow for the precise attachment of payloads to the monoclonal antibody, creating homogeneous ADCs with a uniform drug-to-antibody ratio. Biopharmaceutical firms are standardizing these techniques to enhance predictability and reduce batch-to-batch variation in manufacturing. This level of molecular control is miniaturizing the analytical uncertainty in product characterization, simplifying regulatory submissions and improving clinical translation.
Regulatory bodies like the European Medicines Agency (EMA) and Japan's PMDA are harmonizing data requirements for innovative oncology drugs, including ADCs. This convergence allows developers to use a common set of clinical data to support marketing applications across multiple major jurisdictions. Consequently, developers focused on rare cancers or biomarker-defined populations benefit most, as they can more efficiently execute global development programs.
Oncologists are increasingly selecting therapies based on specific biomarker profiles rather than just the cancer's tissue of origin. This practice disrupts traditional treatment algorithms, creating demand for ADCs paired with companion diagnostic tests that identify eligible patient populations. This biomarker-led approach is most prominent within specialized cancer centers in North America and Europe for treating breast and lung cancers.
Antibody Drug Conjugates Market Segmentation
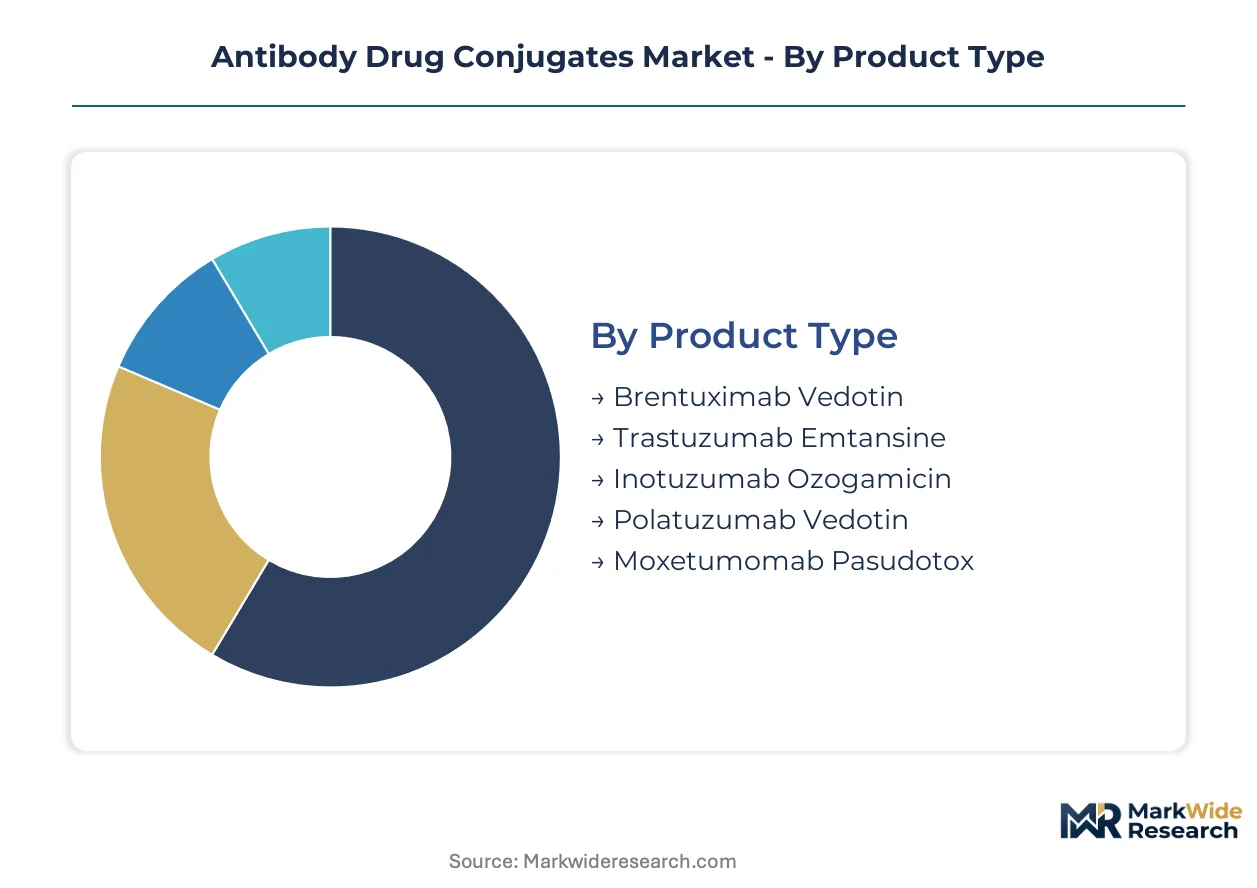
Segmentation analysis illuminates the diverse applications and technological underpinnings of the Antibody Drug Conjugates market. This framework categorizes ADCs by their specific product composition, therapeutic targets, and operational use cases. Understanding these distinctions helps stakeholders identify areas of concentrated value and future development.
Product Type:
Margin pools within the product type category reflect the clinical efficacy and market exclusivity of established Antibody Drug Conjugates.
- Trastuzumab Emtansine:A HER2-targeted ADC combining trastuzumab with the cytotoxic agent emtansine via a non-cleavable linker. Demand concentrates in advanced HER2-positive breast cancer due to its established efficacy and favorable safety profile in this patient population.
- Brentuximab Vedotin:This ADC targets CD30-expressing cells, linking an anti-CD30 antibody to monomethyl auristatin E (MMAE), a microtubule-disrupting agent. Its demand is concentrated in Hodgkin lymphoma and systemic anaplastic large cell lymphoma, driven by regulatory approvals for relapsed or refractory cases.
- Inotuzumab Ozogamicin:Targets CD22 on B-cell acute lymphoblastic leukemia cells for precise drug delivery.
- Polatuzumab Vedotin:An anti-CD79b ADC used for diffuse large B-cell lymphoma treatment.
- Moxetumomab Pasudotox:A CD22-directed immunotoxin for hairy cell leukemia therapy.
The dominant share belongs to Trastuzumab Emtansine, while Brentuximab Vedotin is closing the gap fastest.
Therapy Area:
Application specificity defines the market structure within the therapy area segment, directing research efforts and clinical utility.
- Oncology:The primary therapeutic application for Antibody Drug Conjugates, encompassing a wide range of solid tumors and hematologic malignancies. Demand is concentrated globally due to the high unmet medical need and the targeted nature of ADC therapies for various cancer types.
- Breast Cancer:A significant area for ADC development, particularly for HER2-positive subtypes, where targeted therapies demonstrate superior outcomes. Demand is concentrated in developed markets like North America and Europe, driven by advanced diagnostic capabilities and established treatment protocols.
- Hematologic Malignancies:ADCs treat cancers affecting blood, bone marrow, and lymph nodes.
- Lymphoma:ADCs target specific markers on lymphoma cells to deliver cytotoxic payloads.
- Leukemia:This area sees ADC use in targeting specific antigens on leukemic blast cells.
The largest volume of ADC prescriptions occurs within Oncology, with Breast Cancer representing a significant and expanding sub-segment.
End User:
Customer type delineation within end-user segments shapes the distribution channels and service models for Antibody Drug Conjugates.
- Cancer Treatment Centers:Specialized medical facilities providing comprehensive diagnostic, therapeutic, and supportive care for cancer patients. Demand for ADCs is concentrated here due to the direct administration of these complex therapies and the multidisciplinary approach required for patient management.
- Biopharmaceutical Companies:These entities are instrumental in the discovery, development, manufacturing, and commercialization of Antibody Drug Conjugates. Their internal demand for ADCs centers on research and development activities, including preclinical and clinical trial material production.
- Specialty Clinics:Offer targeted therapies and follow-up care for specific cancer types.
- Research Institutes:Focus on basic science and translational research in ADC mechanisms and applications.
The primary point of patient access for ADCs remains Cancer Treatment Centers, while Biopharmaceutical Companies drive the upstream innovation pipeline.
Linker Technology:
Supply concentration for linker technology reflects the specialized chemical synthesis required for these critical ADC components.
- Cleavable Linkers:These chemical linkers are designed to release the cytotoxic payload from the antibody under specific physiological conditions, such as low pH or enzymatic activity. Their demand concentrates due to improved therapeutic index and reduced systemic toxicity compared to non-cleavable counterparts.
- Enzyme-Responsive Linkers:A subset of cleavable linkers, these are engineered to be cleaved by specific enzymes overexpressed in tumor microenvironments or lysosomes. Demand focuses on these for enhanced tumor selectivity and controlled drug release, minimizing off-target effects.
- Non-Cleavable Linkers:Maintain stability until the ADC is internalized and degraded within the target cell.
- Acid-Labile Linkers:Designed to release payload in acidic environments, often within endosomes or lysosomes.
Cleavable Linkers dominate the current market landscape, with Enzyme-Responsive Linkers showing the steepest expansion trajectory due to advanced design.
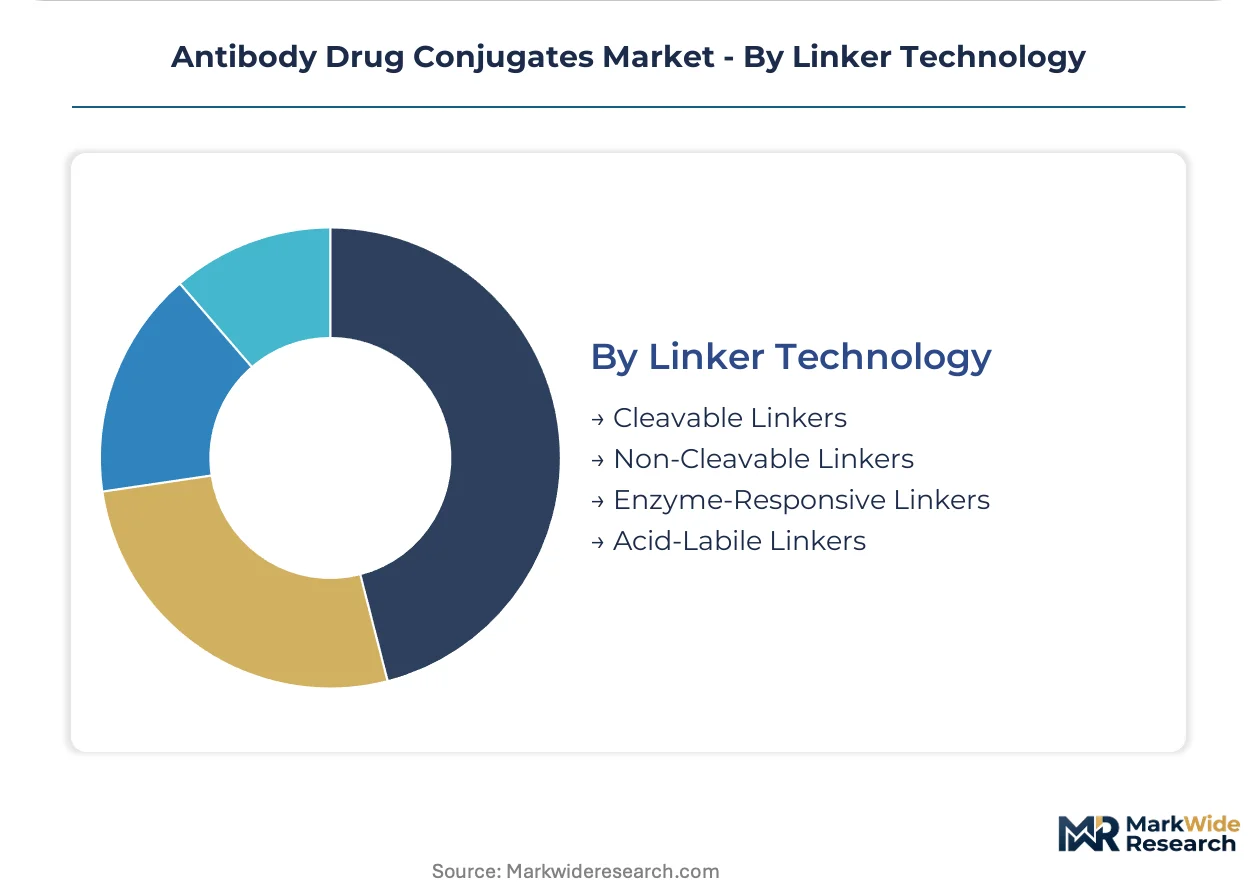
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for Antibody Drug Conjugates varies significantly across regions, reflecting differing healthcare infrastructure and reimbursement models. Developed markets in North America and Europe exhibit lower price sensitivity due to established oncology budgets and advanced diagnostic capabilities. Conversely, emerging economies often prioritize cost-effectiveness, influencing market access and product uptake.
United States
The United States drives substantial demand for Antibody Drug Conjugates, particularly for HER2-positive breast cancer and hematologic malignancies. The FDA's accelerated approval pathways, including Breakthrough Therapy Designation, expedite market entry for novel ADCs addressing unmet medical needs. Major biopharmaceutical hubs like Boston and San Francisco concentrate R&D and clinical trials, fostering innovation and commercialization.
Germany
Germany represents a strong European market for Antibody Drug Conjugates, supported by a robust healthcare system and high oncology treatment standards. The European Medicines Agency (EMA) provides centralized authorization for ADCs across the European Union, streamlining regulatory processes for pharmaceutical companies. Research clusters in cities like Munich and Berlin contribute significantly to advanced cancer therapy development.
Japan
Japan exhibits a growing demand for ADCs, driven by an aging population and increasing cancer incidence rates. Japan's Pharmaceuticals and Medical Devices Agency (PMDA) offers specific frameworks to support the development and approval of innovative oncology treatments. Pharmaceutical companies and research institutions in Tokyo and Osaka actively engage in ADC clinical development and manufacturing advancements.
China
China's Antibody Drug Conjugates market is expanding rapidly, fueled by a large patient population and government initiatives to improve cancer care access. The National Medical Products Administration (NMPA) has streamlined approval processes for innovative drugs, including ADCs, to meet domestic demand. Biopharmaceutical parks in Shanghai and Suzhou are becoming key centers for ADC research, development, and production.
India
India presents an emerging market for Antibody Drug Conjugates, characterized by increasing healthcare expenditure and a rising burden of cancer. The Central Drugs Standard Control Organization (CDSCO) regulates pharmaceutical products, with a focus on ensuring accessibility and affordability of advanced therapies. Pharmaceutical manufacturing hubs in Hyderabad and Ahmedabad are developing capabilities for biosimilar and complex drug production.
Antibody Drug Conjugates Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the Antibody Drug Conjugates market. The market structure exhibits a tiered consolidation, with pioneering biopharmaceutical firms dominating innovation and specialized contract manufacturers supporting complex production. Strategic archetypes include integrated developers, specialized technology licensors, and regional manufacturers focusing on market access. Dominant competitive moves involve strategic partnerships for technology co-development and aggressive portfolio diversification into new therapeutic areas.
Within the integrated developer archetype, Seagen Inc. maintains a strong portfolio in hematologic malignancies, leveraging its foundational ADC technology. Daiichi Sankyo Company Ltd exemplifies a firm competing with proprietary DXd ADC technology, expanding its global footprint. F. Hoffmann-La Roche Ltd sits within the established product segment, sustaining its market presence through products like Trastuzumab Emtansine and extensive clinical development capabilities.
| Leading Market Players |
|---|
| Seagen Inc. |
| Gilead Sciences Inc. |
| F. Hoffmann-La Roche Ltd |
| ADC Therapeutics SA |
| Daiichi Sankyo Company Ltd |
| Pfizer Inc. |
| Takeda Pharmaceutical Company Ltd |
| GSK plc |
| AstraZeneca |
| Others |
Cost & Logistics Intelligence
The U.S. Food and Drug Administration (FDA) and European Medicines Agency (EMA) regulatory regimes gate both supply qualification and price differentiation simultaneously for Antibody Drug Conjugates. These agencies ensure ADCs meet stringent quality and safety standards, directly influencing their market access and premium pricing potential. The complex manufacturing processes and high development costs for ADCs reinforce the need for robust regulatory pathways.
Pricing Analysis
After-sales service and long-term patient support drive significant lifetime value in the Antibody Drug Conjugates market. Value-based pricing models dominate, reflecting the substantial clinical benefits ADCs offer for difficult-to-treat cancers. Price differentiation stems from established clinical efficacy and the unique safety profile of each ADC. Pricing pressure arises from the high cost of goods and extensive R&D investment. Government payers and national health systems represent the most price-sensitive buyer segments, while specialized cancer centers prioritize patient outcomes.
Supply Chain Analysis
Strategic stockpiling of critical raw materials and finished goods is a common inventory strategy due to the specialized nature of ADC components. Geographic supply concentration includes the United States for advanced R&D, Switzerland for established biopharmaceutical manufacturing, and Japan for proprietary linker technologies. Raw material dependencies include highly potent cytotoxic payloads and specialized linker chemicals. Single-source vulnerability for these complex components poses a structural supply chain risk. Distribution runs through a highly controlled cold chain network directly to specialized cancer treatment centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Antibody Drug Conjugates market presents a fragmentation opportunity, driven by biomarker-led therapy selection creating distinct patient niches.
For Market Incumbents: Shield existing market share by aggressively investing in next-generation linker technologies that improve stability and targeting. Expand the clinical pipeline into novel cancer targets to mitigate the threat of emerging resistance mechanisms. Strategic partnerships for intellectual property licensing in payload development can reinforce a strong competitive position. Focus R&D efforts on enhancing the therapeutic index to address payload-related toxicity.
For New Entrants and Emerging Players: A service-layer gap exists in developing ADCs for ultra-orphan indications and rare cancers, where incumbents may under-serve. Target these biomarker-defined patient populations, leveraging accelerated regulatory pathways like the FDA's Breakthrough Therapy Designation. Focus on novel payload development or innovative conjugation strategies as a go-to-market angle. Early clinical trial globalization in emerging markets can accelerate patient enrollment and data generation.
For Investors and Strategic Acquirers: Successful Phase 3 clinical trial readouts for novel ADC indications reshape the acquisition landscape, signaling validated technology platforms. Long-term viability hinges on sustained innovation in payload and linker chemistry, extending the therapeutic utility beyond current applications. Target specialized technology licensors or firms with robust early-stage pipelines in immuno-oncology or autoimmune disorders. The signal to watch is regulatory approval for ADCs in non-oncology therapeutic areas.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Accelerates market entry for novel Antibody Drug Conjugates targeting unmet medical needs. |
| Regulatory Approval Pathway | Streamlines market access for innovative ADCs by leveraging accelerated review programs. |
| Licensing Agreement | Expands product portfolios and access to proprietary technologies, reducing internal R&D costs. |
| Manufacturing Scale-Up | Ensures stable supply of complex ADCs, meeting growing patient demand globally. |
| Pipeline Diversification | Reduces reliance on single therapeutic areas, exploring new applications like autoimmune diseases. |
Research Approach
Desk research of scientific literature, regulatory filings, and industry reports preceded structured interviews with biopharmaceutical R&D executives, clinical oncologists, and regulatory affairs specialists. This approach combined secondary data validation with primary insights from key industry stakeholders. Bottom-up market sizing was triangulated with top-down industry revenue analysis, ensuring comprehensive data coverage.
Variance decomposition analysis informed the forecast framework across the analysis window, attributing growth to specific market drivers and restraints. Segmentation dimensions modeled included product type, therapy area, end user, linker technology, and regional regulatory clusters. Compound Annual Growth Rates were derived from historical data extrapolation and projected future market dynamics, incorporating anticipated new drug approvals and clinical trial success rates.
Underlying assumptions cover the stability of the global regulatory landscape and continued R&D investment levels, with deviation risk concentrated in unforeseen clinical trial failures or the emergence of superior alternative therapies. Revision becomes warranted when significant shifts in treatment paradigms or regulatory policies cross established thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Discovery Bioanalysis Market
Biopharmaceuticals
Octreotide Market
Biopharmaceuticals
Anti-Neoplastic Pharmaceutical Agents Market
Biopharmaceuticals
Atipamezole Market
Biopharmaceuticals
Latin America Insulin Pens Market
Biopharmaceuticals
Brexucabtagene Autoleucel Market
Biopharmaceuticals
Europe Insulin Delivery Devices Market
Biopharmaceuticals
Drug Discovery Outsourcing Market
Biopharmaceuticals
Bio-Active Peptides Market
Biopharmaceuticals
Coagulation Factor IX Market
Biopharmaceuticals
North America Biotechnology Market
Biopharmaceuticals
Global Protein Expression Market
Biopharmaceuticals
Insulin Aspart Market
Biopharmaceuticals
Ovarian Cancer Drugs Market
Biopharmaceuticals
Iran Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
US Influenza Vaccine Market