
 Cell Line Development Market | 2026-2036
Cell Line Development Market Size, Share, and Industry Trends Forecast 2026-2036
Cell Line Development Market Analysis
Biopharmaceutical contract manufacturing networks are reshaping how cell line development services reach end users. Lonza leverages its integrated manufacturing footprint across multiple continents to anchor high-volume therapeutic production workflows. Thermo Fisher Scientific sustains technology leadership through specialized cell culture media and gene editing tool portfolios. Danaher competes by extending life sciences instrumentation into automated cell line engineering platforms.
Cell line development encompasses the isolation, genetic modification, and stable cultivation of mammalian or microbial host cells expressing recombinant proteins, with CHO cells achieving titers exceeding 5 grams per liter in fed-batch bioreactors. The process serves as the foundational manufacturing step for monoclonal antibodies, viral vectors, and biosimilars entering regulated supply chains. CHO cells dominate commercial therapeutic production due to established glycosylation profiles and regulatory familiarity, while stem cell lines represent the fastest-expanding segment for cell therapy applications. CRISPR technology commands premium positioning among gene editing approaches, though transfection methods retain volume leadership in routine industrial workflows.
FDA biosimilar guidelines, EMA cell-based medicinal product frameworks, and ISO 10993 biocompatibility standards collectively govern cell line qualification, characterization documentation, and clinical translation pathways. These requirements shape R&D investment toward clonal derivation traceability and host cell protein impurity profiling. Stakeholders must monitor evolving gene therapy regulations and emerging platform standardization initiatives to align capacity decisions with downstream therapeutic modality demand.
Market Dynamics
CRISPR-Cas9 editing workflows are compressing cell line generation timelines from months to weeks, forcing contract manufacturers to reconfigure service architectures around rapid clonal derivation rather than traditional sequential screening protocols.
Growth Catalysts
- FDA Biosimilar Pathway Expansion:Abbreviated approval frameworks for interchangeable biologics accelerate CHO cell line qualification investments by generic pharmaceutical manufacturers seeking therapeutic equivalence certification.
- Gene Therapy Manufacturing:Viral vector production requirements for AAV and lentiviral platforms drive demand for HEK293 suspension adaptations with enhanced packaging capacities.
- Continuous Bioprocessing:Perfusion bioreactor adoption in Singapore and Switzerland enables real-time cell line performance monitoring that feeds back into upstream strain optimization cycles.
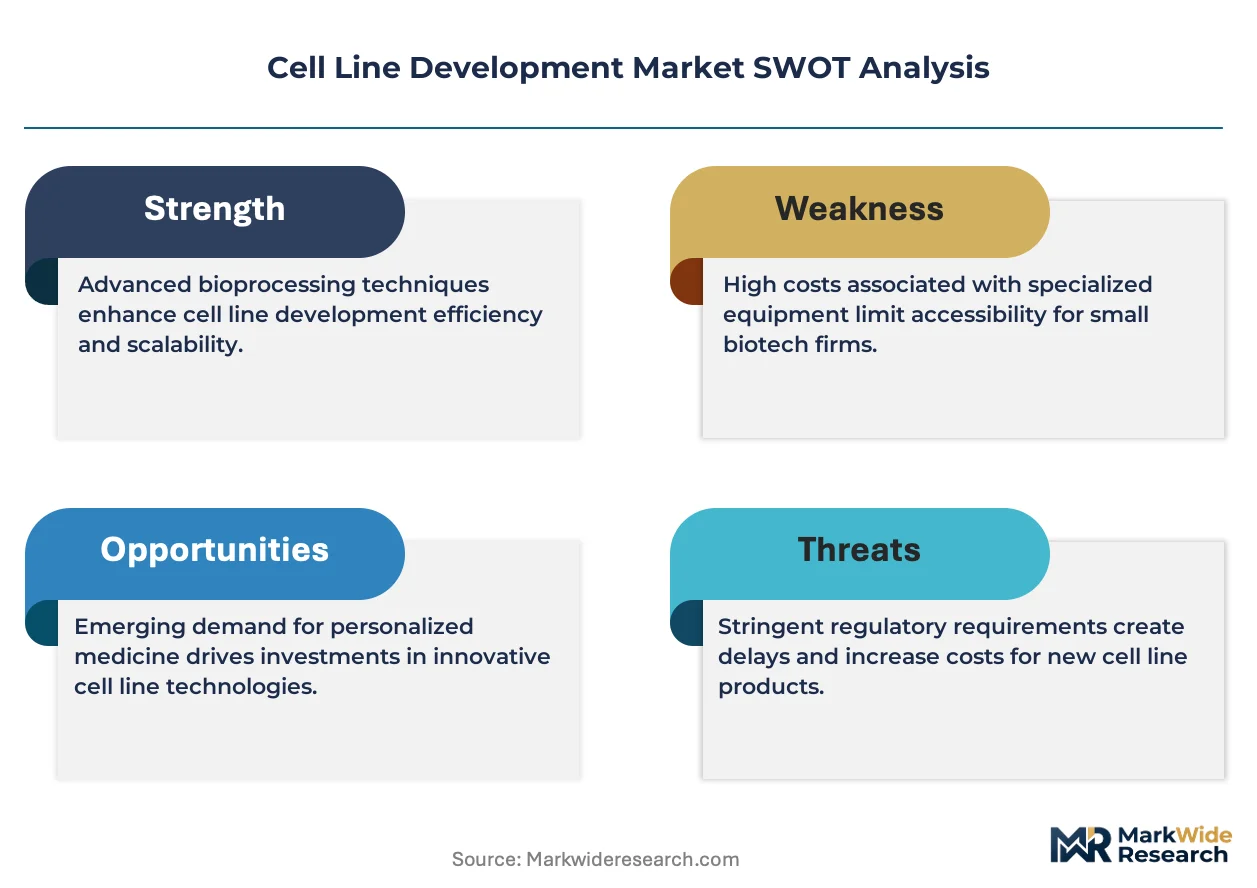
Market Restraints
- Fetal Bovine Serum Volatility:Supply interruptions from Australia and New Zealand trigger chemically-defined media reformulation costs that erode margin predictability for legacy adherent culture workflows.
- Single-Use Equipment Concentration:German and US bioreactor bag suppliers command pricing leverage that inflates facility retrofit expenditures for multi-product manufacturing suites.
- Glycoengineering Complexity:Humanized glycosylation pattern requirements for antibody-dependent cellular cytotoxicity functions extend cell line screening timelines beyond standard IND-enabling schedules.
Strategic Opportunities
- India CDMO Expansion:CDSCO streamlined biosimilar guidelines and PLI scheme incentives attract foreign direct investment into Bangalore and Hyderabad-based mammalian cell culture infrastructure.
- Microbiome Therapeutics:Engineered bacterial chassis for live biotherapeutic products represent untapped demand for anaerobic cell line development capabilities distinct from aerobic CHO workflows.
- AI-Assisted Clone Selection:Machine learning integration with high-content imaging platforms collapses clonal outgrowth prediction cycles, enabling service differentiation for time-sensitive gene therapy programs.
Industry Challenges
- Cell Culture Specialist Scarcity:GMP-compliant aseptic technique and metabolic flux analysis expertise shortages constrain facility expansion timelines across contract manufacturing networks.
- Host Cell Protein Assay Validation:ELISA and mass spectrometry method qualification for process-specific impurity detection extends analytical development phases prior to BLA submission.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cell Line Development Market |
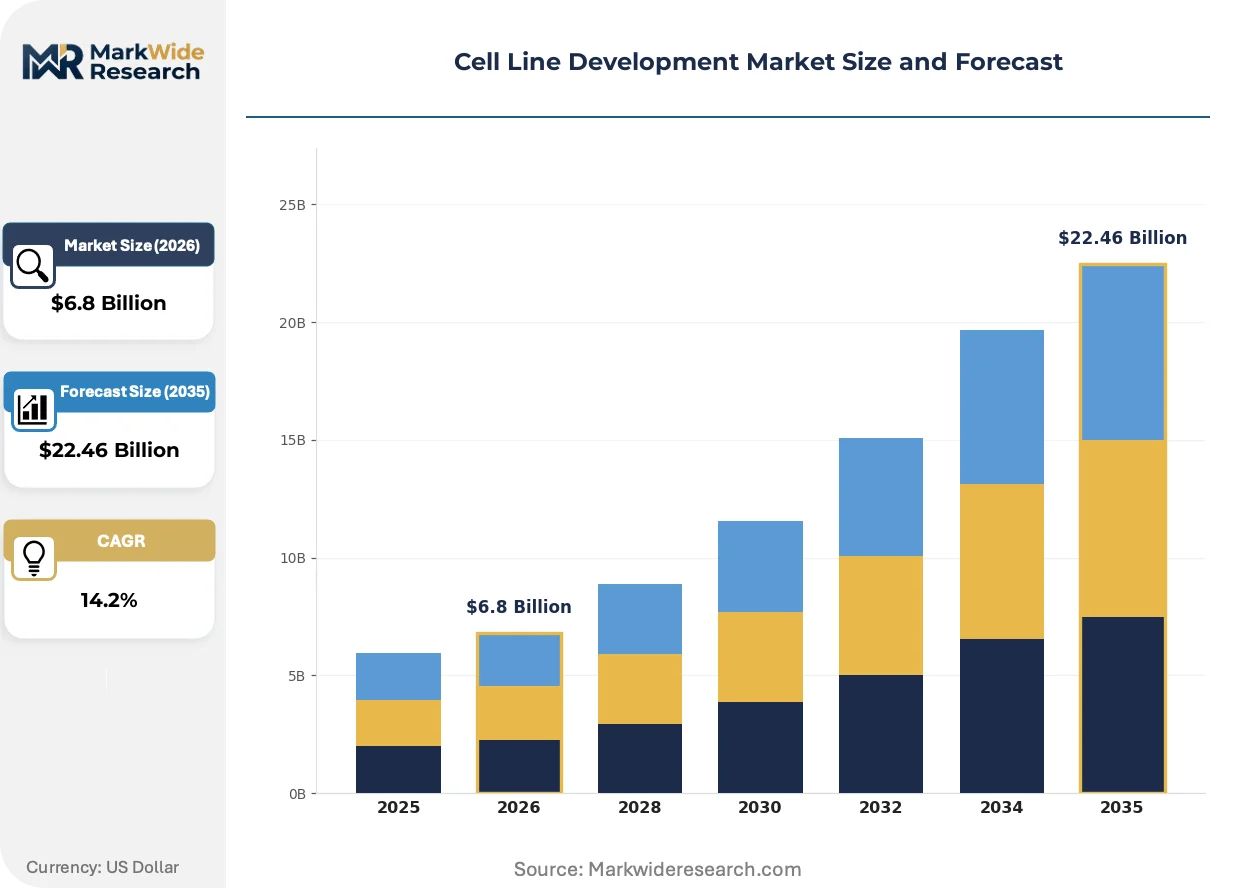
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $22.46 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hybridoma, CHO Cells, Stem Cells, MSCs Application: Drug Development, Therapeutic Production, Vaccine Development, Toxicity Testing End User: Biopharmaceutical Companies, Research Institutions, Contract Research Organizations, Academic Institutions Technology: Gene Editing, CRISPR, Transfection, Cell Culture Technologies |
| Companies Covered | Thermo Fisher Scientific, Lonza, Sartorius, Danaher, Merck KGaA, WuXi Biologics, Charles River Laboratories, Corning, Cytiva, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cell Line Development Market Emerging Trajectories
Automation architectures are displacing manual pipetting and microscopy-based clone picking across cell line development workflows, compressing labor dependencies while amplifying throughput consistency for high-volume therapeutic pipelines.
Site-specific nuclease platforms including CRISPR-Cas12a and base editors are collapsing off-target mutation rates in CHO genome engineering, enabling biopharmaceutical developers to bypass antibiotic resistance marker selection and accelerate regulatory-compliant master cell bank establishment. Lonza and Thermo Fisher Scientific have integrated these tools into commercial service offerings. The structural consequence is collapsing timeline premiums previously commanded by rare transgene integration events.
EMA's revised Guideline on the Quality, Non-Clinical and Clinical Aspects of Gene Therapy Medicinal Products mandates extended adventitious agent testing for viral vector-producing cell lines. This forces European manufacturers to implement next-generation sequencing-based contamination detection earlier in clone selection workflows. Germany and Switzerland-based CDMOs are responding by qualifying orthogonal nucleic acid amplification methods to satisfy both speed and stringency requirements.
Biopharmaceutical developers are consolidating preferred supplier relationships with integrated cell line-to-drug-substance providers, displacing fragmented outsourcing across discrete gene synthesis, cell engineering, and bioproduction specialists. This procurement consolidation concentrates contract value among vendors with captive analytical development and regulatory submission capabilities. The shift is most visible in US and UK markets where biosimilar developers prioritize single-source accountability for IND-enabling packages.
Cell Line Development Market Segmentation
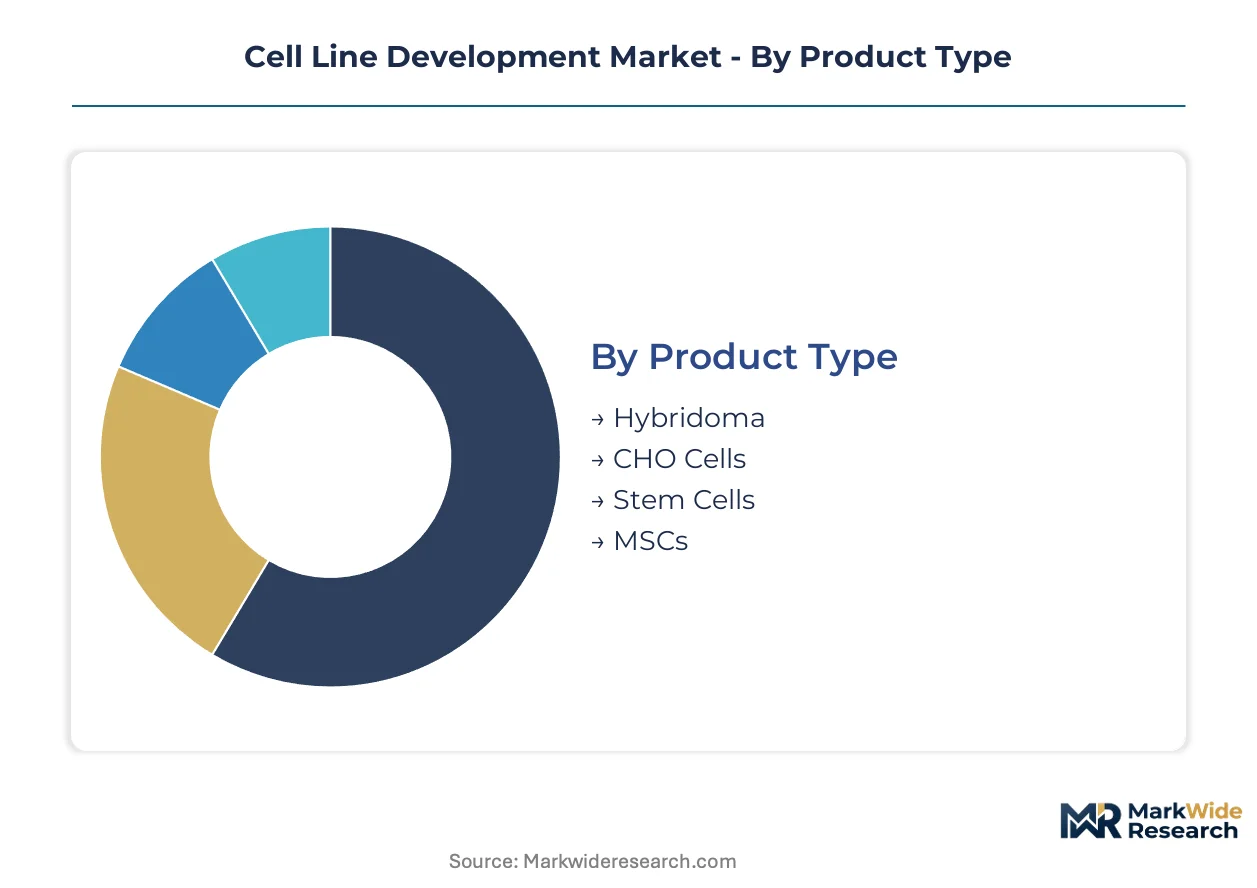
Cell line development segmentation reveals how therapeutic modality demands reshape platform investments. Product type and technology choices determine glycosylation fidelity, regulatory pathway complexity, and manufacturing scalability for biologics developers.
Product Type:
Mature mammalian platforms dominate commercial manufacturing, while emerging cell sources reshape therapeutic boundaries.
- CHO Cells:Chinese hamster ovary lines achieve titers exceeding 5 grams per liter in fed-batch bioreactors with human-compatible glycosylation profiles. FDA biosimilar guidelines cement CHO dominance among generic pharmaceutical manufacturers seeking abbreviated approval pathways.
- Stem Cells:Pluripotent and multipotent lines enable autologous and allogeneic cell therapies with expansion capacities exceeding 10 population doublings. Singapore and Switzerland perfusion bioreactor installations accelerate stem cell adaptation for regenerative medicine applications.
- Hybridoma:Murine-derived fusion cell lines for monoclonal antibody discovery retain established intellectual property frameworks.
- MSCs:Mesenchymal stromal cells from bone marrow, adipose, and umbilical cord sources address immunomodulatory therapeutic targets.
CHO cells retain volume leadership; stem cells hold the steepest expansion curve.
Application:
Commercial manufacturing applications command premium platform investments, while preclinical applications drive technology access democratization.
- Therapeutic Production:Commercial-scale monoclonal antibody and recombinant protein manufacturing requires GMP-compliant master cell banks with documented clonal derivation. CDSCO streamlined biosimilar guidelines in India attract foreign direct investment into Bangalore and Hyderabad mammalian culture infrastructure for export-oriented therapeutic production.
- Drug Development:Lead optimization and candidate selection workflows demand rapid cell line generation with predictive pharmacokinetic profiles. AI-assisted clone selection integration with high-content imaging collapses timelines for time-sensitive IND-enabling packages.
- Vaccine Development:Viral vector and subunit antigen production platforms address pandemic preparedness requirements.
- Toxicity Testing:Hepatocyte and cardiomyocyte lines replace animal models for early-stage safety pharmacology screening.
Therapeutic production captures margin concentration; drug development exhibits the most rapid technology turnover.
End User:
Integrated biopharmaceutical manufacturers anchor capacity investments, while outsourced service providers fragment procurement across specialized competencies.
- Biopharmaceutical Companies:Vertically integrated developers from discovery through commercialization establish captive cell line engineering capabilities. Preferred supplier consolidation toward integrated cell line-to-drug-substance providers concentrates contract value among vendors with analytical development and regulatory submission capabilities.
- Contract Research Organizations:CDMOs and CROs compete on timeline compression and platform standardization for multi-sponsor programs. Cell culture specialist scarcity constrains facility expansion timelines across contract manufacturing networks in Germany and Switzerland.
- Research Institutions:Academic medical centers and national laboratories pursue exploratory cell engineering without GMP compliance requirements.
- Academic Institutions:University-based technology transfer offices license novel cell line innovations to commercial partners.
Biopharmaceutical companies retain procurement volume leadership; contract research organizations are expanding most quickly.
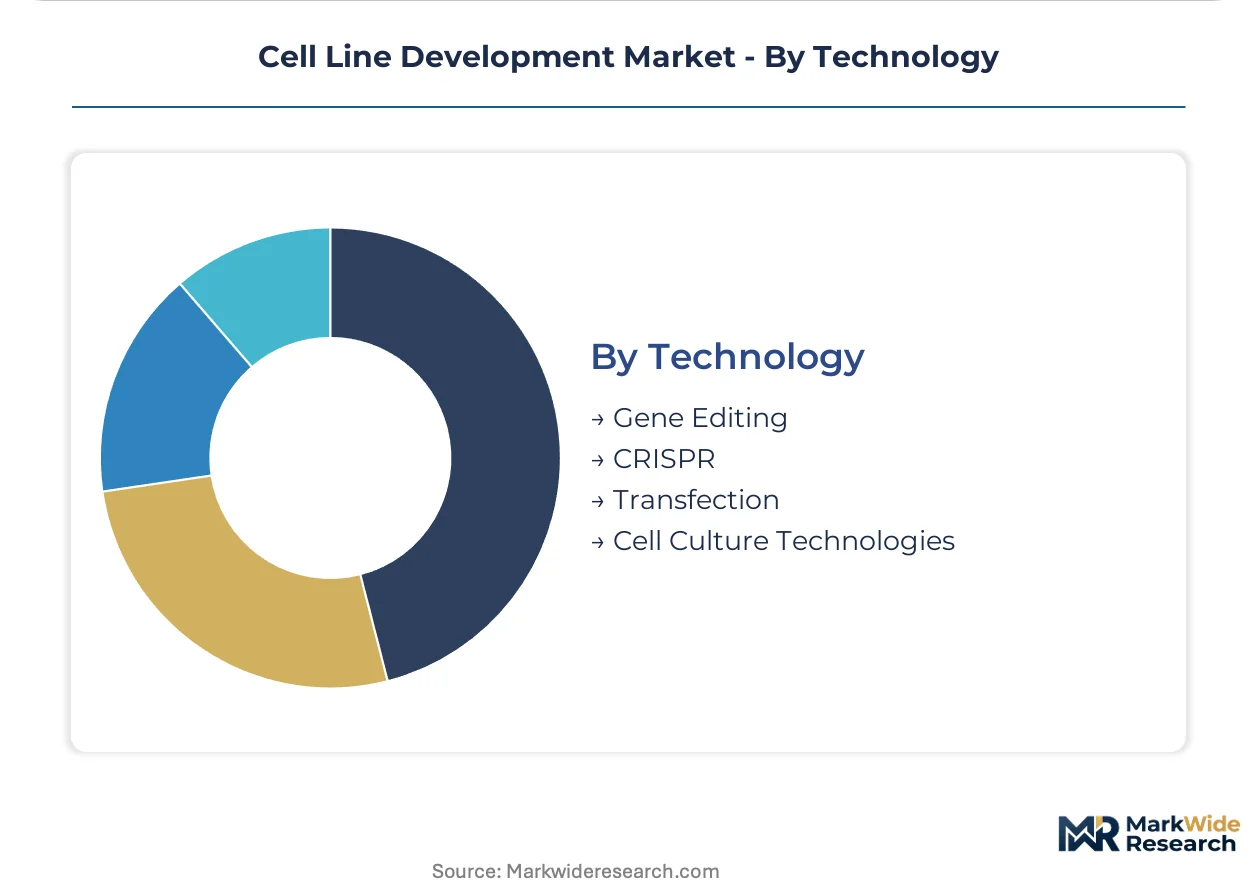
Technology:
Gene editing precision differentiates premium service tiers, while conventional transfection methods sustain high-throughput screening economics.
- CRISPR:CRISPR-Cas9 and Cas12a platforms compress cell line generation timelines from months to weeks with site-specific nuclease precision. Lonza and Thermo Fisher Scientific integration of base editors into commercial offerings collapses timeline premiums previously commanded by rare transgene integration events.
- Gene Editing:Zinc finger nucleases and transcription activator-like effector nucleases retain regulatory familiarity for legacy therapeutic programs. EMA revised gene therapy guidelines mandate extended adventitious agent testing, forcing European manufacturers to implement next-generation sequencing earlier in clone selection workflows.
- Transfection:Electroporation and lipid-based delivery methods sustain volume leadership in routine industrial workflows.
- Cell Culture Technologies:Chemically-defined media and perfusion bioreactor systems enable real-time performance monitoring.
Transfection retains volume leadership; CRISPR commands the steepest capability premium expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold chain infrastructure underwrites European biologics distribution, while Singapore's Changi Airport pharmaceutical hub anchors Asia-Pacific cell therapy logistics networks.
United States
FDA biosimilar pathway expansion and gene therapy manufacturing investments drive CHO cell platform adoption. The agency's abbreviated approval frameworks accelerate qualification timelines for interchangeable biologics. Greater Boston and San Francisco Bay Area clusters concentrate CRISPR-integrated cell engineering capabilities serving IND-enabling programs.
Germany
EMA revised gene therapy guidelines mandate extended adventitious agent testing for viral vector production. Single-use bioreactor equipment suppliers in Bavaria and Baden-Württemberg command pricing leverage over multi-product facility retrofits. Heidelberg and Munich academic-industrial partnerships anchor automated clone selection technology development.
Switzerland
Continuous bioprocessing adoption in Basel-Zurich corridor enables real-time cell line performance monitoring. Swissmedic harmonization with EMA standards streamlines cross-border master cell bank qualification. Perfusion bioreactor installations at Lonza facilities feed upstream strain optimization cycles for commercial antibody production.
Singapore
Stem cell therapy manufacturing investments leverage the Biopolis research cluster's regulatory sandbox environment. The Economic Development Board's biomedical sciences initiative attracts perfusion technology providers for regenerative medicine applications. Tuas Biomedical Park infrastructure supports GMP-compliant expansion of allogeneic cell therapy platforms.
India
CDSCO streamlined biosimilar guidelines and PLI scheme incentives attract foreign direct investment into mammalian culture infrastructure. Bangalore and Hyderabad CDMO clusters compete on timeline compression for export-oriented therapeutic production. The Department of Biotechnology's National Biopharma Mission funds indigenous cell line engineering capability development.
Cell Line Development Market Vendor Landscape
On the supply side, the industry is consolidating around integrated cell line-to-drug-substance providers with captive analytical development capabilities. The vendor base separates into three strategic archetypes: diversified life sciences conglomerates with gene editing tool portfolios, specialized contract manufacturers with multi-continental manufacturing footprints, and analytical instrumentation providers extending into automated cell engineering platforms. Dominant competitive moves include preferred supplier relationship consolidation by biopharmaceutical developers and technology licensing partnerships for CRISPR-based clonal derivation workflows.
Within the diversified conglomerate tier, Thermo Fisher Scientific and Danaher exemplify platform integration strategies spanning cell culture media, gene editing reagents, and analytical instrumentation. Lonza occupies a position representing specialized contract manufacturing scale with integrated bioproduction capabilities across multiple continents. WuXi Biologics anchors the Asia-Pacific CDMO archetype, leveraging regional cost structures for global biopharmaceutical outsourcing demand.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Lonza |
| Sartorius |
| Danaher |
| Merck KGaA |
| WuXi Biologics |
| Charles River Laboratories |
| Corning |
| Cytiva |
| Others |
Supply Flow & Price Mechanics
German and US single-use bioreactor bag suppliers anchor upstream concentration, capturing margin pools downstream through pricing leverage over multi-product facility retrofits across contract manufacturing networks.
Pricing Analysis
Volume-discount tiering separates GMP-compliant master cell bank services from rapid clonal derivation workflows. Pricing stratifies across premium, standard, and economy tiers based on regulatory documentation depth and analytical development bundling. Cost compression in standard-tier transfection services is intensifying because CRISPR-based workflows collapse timeline premiums previously commanded by rare integration events. Emerging biopharmaceutical developers exhibit highest price sensitivity; vertically integrated innovators with captive regulatory affairs capabilities show lowest.
Supply Chain Analysis
Export-control regimes limiting CRISPR reagent flows from US-based gene editing tool providers reshape procurement geography for European and Asia-Pacific manufacturers. Supply concentration centers on Germany, Switzerland, and Singapore for single-use bioprocessing equipment and perfusion technologies. Raw material dependencies include chemically-defined media formulations, fetal bovine serum alternatives, and synthetic gene synthesis services. Single-source vulnerability pervades GMP-compliant aseptic technique specialist labor pools. Distribution runs through integrated cell line-to-drug-substance providers with captive analytical development capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cell line development markets are crossing a platform-economics inflection as CRISPR tool standardization and automated clone selection interoperability collapse switching costs between service providers.
For Market Incumbents: Build regulatory documentation moats through investment in clonal derivation traceability systems and host cell protein impurity profiling capabilities. Deepen backward integration into chemically-defined media manufacturing to offset fetal bovine serum volatility. Consolidate preferred supplier relationships by extending analytical development and BLA submission capabilities. For New Entrants and Emerging Players: Establish a beachhead in India CDMO expansion zones where CDSCO streamlined biosimilar guidelines and PLI scheme incentives attract foreign direct investment into Bangalore and Hyderabad infrastructure. Target microbiome therapeutics anaerobic cell line development as white-space distinct from aerobic CHO workflows. Lead with AI-assisted clone selection integration as differentiated go-to-market positioning. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across stem cell therapy manufacturing infrastructure as perfusion bioreactor installations and GMP-compliant expansion capabilities require sustained facility investment. Acquisition targets should demonstrate integrated cell line-to-drug-substance service architectures with regulatory submission track records. Watch for FDA gene therapy guideline revisions as inflection signal for viral vector-producing cell line demand shifts.| Strategic Initiative | Industry Significance |
|---|---|
| CRISPR Platform Integration | Site-specific nuclease precision compresses cell line generation timelines from months to weeks. |
| Continuous Bioprocessing Adoption | Perfusion bioreactor installations at Lonza facilities enable real-time strain optimization cycles. |
| India CDMO Capacity Expansion | CDSCO streamlined biosimilar guidelines attract foreign direct investment into mammalian culture infrastructure. |
| AI-Assisted Clone Selection | Machine learning integration with high-content imaging collapses clonal outgrowth prediction cycles. |
| Regulatory Submission Capability Buildout | EMA revised gene therapy guidelines mandate extended adventitious agent testing for viral vector production. |
Methodological Framework
Cross-validation between primary interviews with biopharmaceutical development executives, regulatory affairs leads, contract manufacturing officers, and analytical development directors and secondary sources including FDA filings, EMA submissions, ClinicalTrials.gov records, and CDSCO biosimilar guideline documents anchors the qualitative findings. Bottom-up service revenue aggregation and top-down therapeutic modality demand sizing provide triangulation checks across the analysis window.
Calibration against historical capacity expansion announcements and gene therapy clinical trial initiation rates validates projection trajectories. Segmentation modeling spans product type, application, end user, and technology dimensions with regional regulatory cluster differentiation. CAGRs derive from fitted growth curves incorporating CRISPR adoption velocity and stem cell therapy manufacturing investment cycles as industry-specific inputs.
Sensitivities concentrate around FDA biosimilar pathway expansion pace, EMA gene therapy guideline implementation timelines, and fetal bovine serum supply interruption recurrence. Forecasts reflect documented assumptions regarding CRISPR platform standardization and continuous bioprocessing adoption rates. Material shifts in regulatory stringency for viral vector-producing cell lines or breakthroughs in base editor off-target reduction would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Services
Membrane Protein Characterization Service Market
Biotechnology Services
In-Vitro Fertilization Services Market
Biotechnology Services
3D Ready Organoid Expansion Service Market
Biotechnology Services
Phospho-Specific Antibodies Market
Biotechnology Services
Global Bioprocess Validation Market
Biotechnology Services
Global Eukaryotic Expression Systems Market
Biotechnology Services
Immunoassays in R & D Market
Biotechnology Services
Europe Recombinant Protein Manufacturing Services Market
Biotechnology Services
Dnases, Ligases, and RNA Polymerases Market
Biotechnology Services
US Digital PCR Market
Biotechnology Services
Recombinant Proteins Manufacturing Services Market
Biotechnology Services
Biobanking Market
Biotechnology Services
Aptamers Market
Biotechnology Services
Global Alpha Galactosidase Market
Biotechnology Services
Antibody Drug Conjugates Contract Manufacturing Market
Biotechnology Services
Global DNA and RNA Banking Services Market