
 Drug Discovery Services Market | 2026-2036
Drug Discovery Services Market Size, Share, and Industry Trends Forecast 2026-2036
Drug Discovery Services Market Intelligence
The substitution of traditional in vivo animal models with advanced in silico computational modeling is restructuring the economics of preclinical drug development. Charles River Laboratories International Inc. expands its portfolio in this specific area, offering a suite of predictive models. WuXi AppTec leverages its fully integrated platform to provide services from computational chemistry to lead optimization. Evotec SE specializes in high-throughput screening and complex data-driven discovery partnerships with biotech firms.
Drug discovery services encompass outsourced scientific activities supporting the identification and validation of new therapeutic candidates, from hit identification to lead optimization. These services utilize specialized platforms for tasks like ADMET profiling to assess a compound's viability, aiming to de-risk and accelerate the early-stage pipeline for clients. Oncology remains the dominant therapy area due to high R&D investment and its complex biology. Among service types, high-throughput screening and lead optimization constitute the largest segments for contract research organizations.
Regulatory frameworks from the FDA in the United States and the EMA in Europe set stringent data requirements for Investigational New Drug (IND) applications. Good Laboratory Practice (GLP) standards, enforced globally, dictate the quality and integrity of nonclinical laboratory studies submitted to these agencies. Stakeholders must continually evaluate how evolving regulations on data sharing and AI model validation will impact future service contracts and intellectual property.
Market Dynamics
The industrialization of biological research, driven by the convergence of artificial intelligence with high-throughput automation, is the central force shaping the drug discovery services market. This shift transforms drug discovery from a bespoke scientific art into a scalable, data-driven engineering discipline.
Growth Catalysts
- Surging Biotech Funding:A sustained influx of venture capital into emerging biotechnology firms, particularly in the United States and China, creates strong demand for outsourced discovery services to rapidly advance preclinical assets.
- AI and ML Integration:The adoption of artificial intelligence and machine learning platforms for target identification, hit-to-lead optimization, and predictive toxicology accelerates discovery timelines and improves success rates for client programs.
- Regulatory Modernization:Initiatives by regulators like the FDA and EMA to accept in silico data and other New Approach Methodologies (NAMs) in submissions encourages investment in computational and advanced cell-based screening services.
Market Restraints
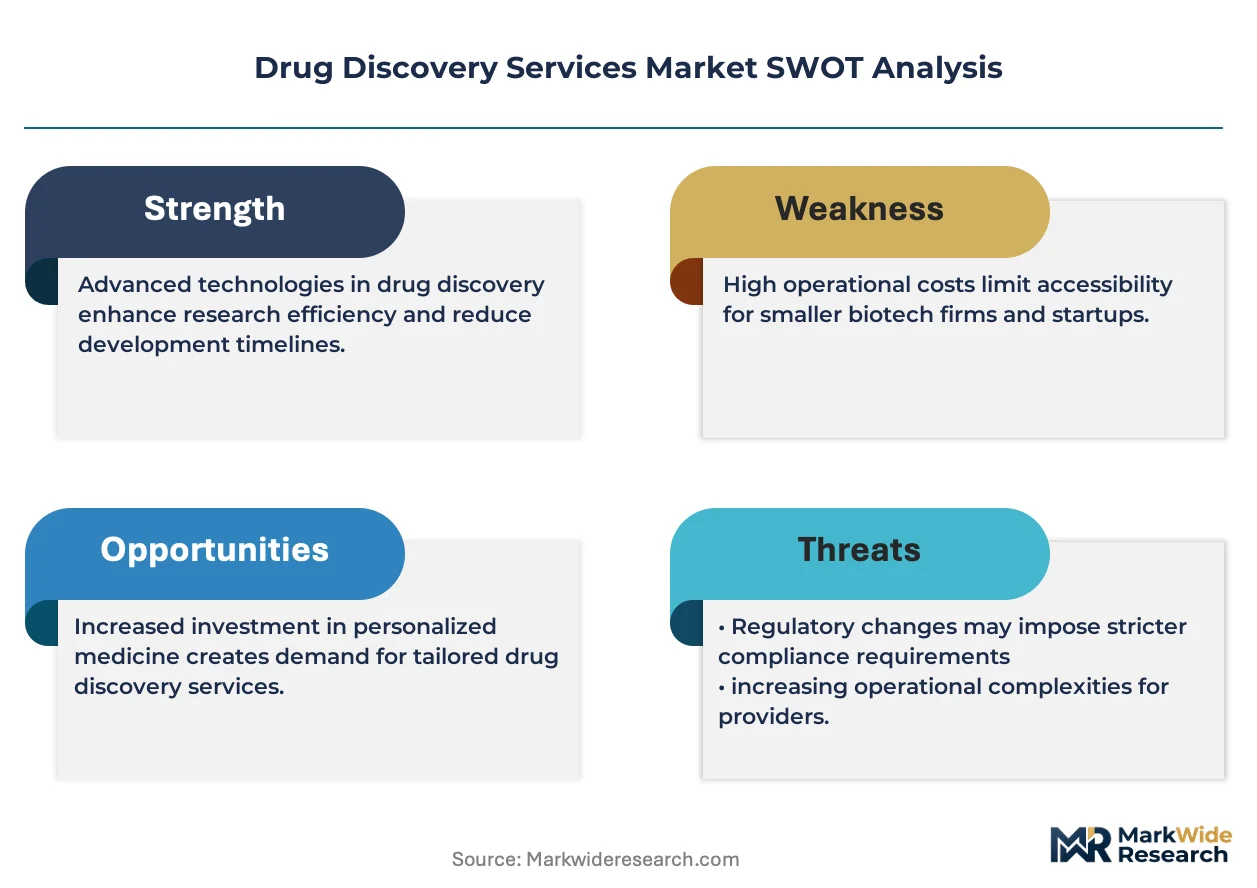
- High Capital Intensity:The substantial upfront investment required for state-of-the-art instrumentation, such as mass spectrometry and automated screening platforms, creates a high barrier to entry for smaller service providers.
- Predictive Model Limitations:Despite advances, the predictive accuracy of in silico and in vitro models for complex human biology remains a technical hurdle, often requiring costly and time-consuming validation with in vivo studies.
- Data Integrity Requirements:Adherence to stringent Good Laboratory Practice (GLP) standards for nonclinical studies submitted to agencies like the FDA and EMA adds significant operational overhead and compliance costs for service providers.
Strategic Opportunities
- Geographic Expansion:There is significant opportunity in establishing integrated discovery service hubs in growing biopharma ecosystems outside of traditional centers, such as in South Korea and Australia, to support local innovation.
- New Therapeutic Modalities:Service providers can develop specialized platforms for novel modalities like cell therapies, gene therapies, and RNA-based therapeutics, which require unique discovery and characterization workflows.
- Cryo-EM Services:The convergence of Cryo-Electron Microscopy with AI-powered data processing creates an opportunity for specialized structural biology services that can resolve previously intractable drug targets for clients.
Industry Challenges
- Bioinformatics Talent Scarcity:A critical shortage of bioinformaticians and data scientists capable of managing and interpreting the large, complex datasets generated by modern discovery platforms constrains operational capacity.
- Intellectual Property Ambiguity:Structuring intellectual property rights in multi-party, AI-driven discovery collaborations presents significant legal and contractual challenges, potentially delaying or complicating partnerships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drug Discovery Services Market |
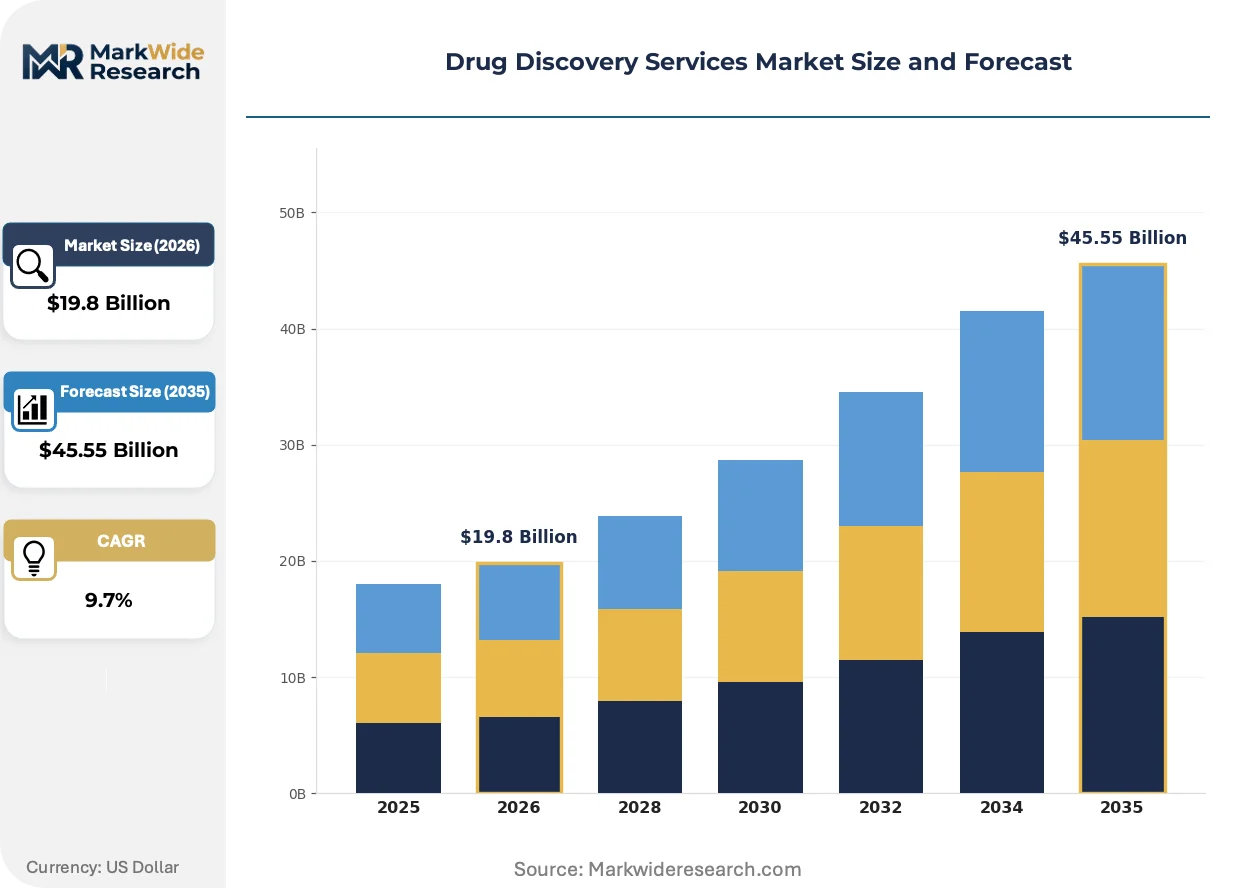
| Market Size in 2026 | $19.8 Billion |
| Market Size in 2035 | $45.55 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: High-Throughput Screening, Compound Synthesis, Lead Optimization, ADMET Profiling, Biomarker Discovery Technology: Computational Chemistry, Molecular Modeling, Biophysical Analysis, Genomics, Proteomics, Metabolomics Therapy Area: Oncology, Neurology, Infectious Diseases, Cardiovascular, Immunology, Rare Diseases End User: Pharmaceutical Companies, Biotechnology Firms, Research Institutes, Contract Research Organizations, Academic Labs |
| Companies Covered | Thermo Fisher Scientific Inc., Charles River Laboratories International Inc., Laboratory Corporation of America Holdings, WuXi AppTec Co., Ltd., Evotec SE, Eurofins Scientific SE, Syngene International Ltd., Pharmaron Beijing Co., Ltd., Aragen Life Sciences Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drug Discovery Services Market Strategic Shifts & Innovations
The market's evolution reflects a fundamental shift toward the industrialization of early-stage research. This transformation is characterized by the integration of computational science, robotics, and novel partnership models to improve the efficiency and predictability of identifying new medicines.
Cryo-Electron Microscopy (Cryo-EM) provides high-resolution, near-native state visualization of complex biological macromolecules. Pharmaceutical and biotechnology firms increasingly use specialized CROs for this structure determination work. This technology is electrifying the field of structure-based drug design, compressing the timeline for understanding how a potential drug binds to its target protein from months to weeks.
New guidance from the United States Food and Drug Administration (FDA) actively promotes the use of Model-Informed Drug Development (MIDD) pathways. This policy shift provides a clear framework for sponsors to use computational modeling and simulation data in regulatory submissions. The preclinical services segment is most affected, with providers expanding their validated ADMET and systems biology modeling capabilities to align with this regulatory preference.
A notable behavioral change involves clients moving from transactional, fee-for-service engagements toward integrated, risk-sharing discovery partnerships. This disrupts the traditional CRO model by demanding shared scientific accountability and milestone-based payments instead of fixed fees. This trend is most visible within the North American biopharma clusters of Boston and San Francisco, where venture-backed biotechs seek to align CRO incentives with their own pipeline goals.
Drug Discovery Services Market Segmentation
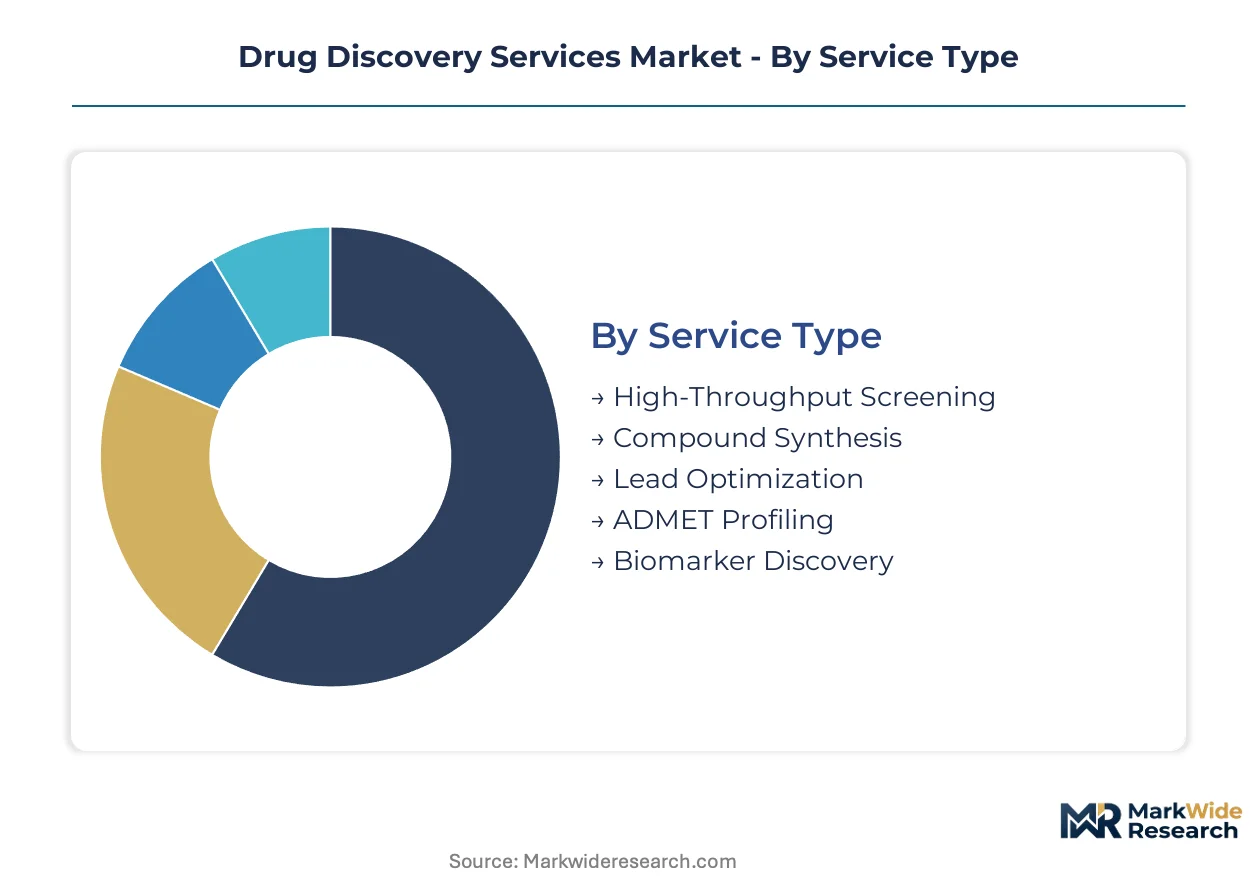
The drug discovery services market segments across distinct service types, underlying technologies, therapeutic areas, and diverse end-user profiles. Understanding these divisions reveals how specialized capabilities are deployed to accelerate preclinical development and improve success rates for new therapeutic candidates.
Service Type:
Service types in this market differentiate between standalone, transactional offerings and integrated, multi-stage discovery support. Each service addresses specific bottlenecks within the drug development pipeline, from early-stage target validation to lead compound refinement.
- High-Throughput Screening:This service rapidly assays thousands of compounds against biological targets, identifying initial hits for drug development programs. Demand concentrates in established biopharma hubs like Boston, driven by the integration of artificial intelligence into screening platforms.
- Lead Optimization:Following hit identification, lead optimization refines compounds to improve efficacy, safety, and pharmacokinetic properties, transforming them into viable drug candidates. Emerging biotechnology firms frequently outsource these complex services to de-risk their early-stage pipelines.
- Compound Synthesis:Service providers synthesize novel chemical entities and libraries for screening and optimization, supporting both bespoke and high-volume requirements. Pharmaceutical companies rely on these services for rapid access to diverse chemical matter.
- ADMET Profiling:This segment assesses a compound's absorption, distribution, metabolism, excretion, and toxicity characteristics, critical for predicting in vivo behavior and de-risking candidates. Regulatory bodies like the FDA increasingly accept validated in silico ADMET data.
- Biomarker Discovery:Services in this area identify and validate biological markers for disease diagnosis, prognosis, and therapeutic response, enhancing precision medicine approaches. Research institutes leverage these offerings to elucidate disease mechanisms and stratify patient populations.
Volume placements concentrate in High-Throughput Screening; the faster expansion belongs to Lead Optimization.
Technology:
The technological segmentation reflects the diverse scientific tools and computational approaches employed to accelerate and de-risk drug discovery projects. These technologies range from atomic-level structural analysis to broad-scale biological data interpretation.
- Computational Chemistry:This technology uses computer simulations to model molecular interactions, predict compound properties, and design new chemical entities, significantly reducing experimental costs. Regulatory modernization by the FDA and EMA encourages investment in these advanced in silico capabilities.
- Genomics:Genomics involves the study of an organism's entire genome to identify potential drug targets and understand disease mechanisms, providing foundational insights for precision medicine. Biotechnology firms utilize genomic services for target identification and patient stratification.
- Molecular Modeling:This segment employs computational methods to visualize and manipulate molecular structures, aiding in structure-based drug design and lead optimization. Specialized CROs offer these services to resolve complex protein-ligand binding interactions.
- Biophysical Analysis:Biophysical techniques characterize molecular interactions and conformational changes, providing quantitative data on drug-target binding and stability. Academic labs frequently partner with service providers for specialized biophysical assays.
- Proteomics:Proteomics focuses on the large-scale study of proteins, including their structure, function, and interactions, offering insights into disease pathways and drug action. Research institutes leverage proteomics to identify novel biomarkers and therapeutic targets.
- Metabolomics:Metabolomics involves the comprehensive analysis of metabolites within a biological system, revealing metabolic changes associated with disease or drug treatment. Pharmaceutical companies use metabolomics to understand drug metabolism and toxicity profiles.
The largest revenue contributions stem from Computational Chemistry, while Genomics is expanding most quickly.
Therapy Area:
Segmentation by therapy area highlights the specialized expertise and distinct research priorities within different disease categories. Each area demands unique scientific approaches and regulatory considerations for drug discovery.
- Oncology:This segment focuses on the discovery of new cancer therapies, including small molecules, biologics, and immunotherapies, addressing a highly complex disease landscape. High R&D investment and intricate biology make oncology the dominant therapy area.
- Rare Diseases:Discovery services for rare diseases target conditions affecting a small percentage of the population, often characterized by high unmet medical needs and expedited regulatory pathways. Specialized platforms for cell and gene therapies are crucial in this area.
- Neurology:This therapy area involves the discovery of treatments for disorders affecting the nervous system, such as Alzheimer's and Parkinson's diseases, posing significant challenges due to blood-brain barrier penetration. Biotechnology firms seek services for neurodegenerative disease models.
- Infectious Diseases:Services in this area concentrate on developing new antimicrobial, antiviral, and antiparasitic agents to combat pathogens and emerging global health threats. Pharmaceutical companies prioritize rapid discovery for novel infectious disease targets.
- Cardiovascular:This segment focuses on therapies for heart and blood vessel conditions, including hypertension, heart failure, and atherosclerosis. Research institutes collaborate on services addressing complex cardiovascular disease mechanisms.
- Immunology:Immunology services support the discovery of treatments for autoimmune diseases, allergies, and inflammatory conditions, often involving complex biological pathways. Contract research organizations offer specialized assays for immune modulation.
High-value discovery efforts are largely directed towards Oncology, with Rare Diseases showing significant pipeline acceleration.
End User:
The end-user segmentation illustrates the diverse clientele for drug discovery services, ranging from large multinational corporations to academic institutions, each with distinct needs and outsourcing strategies.
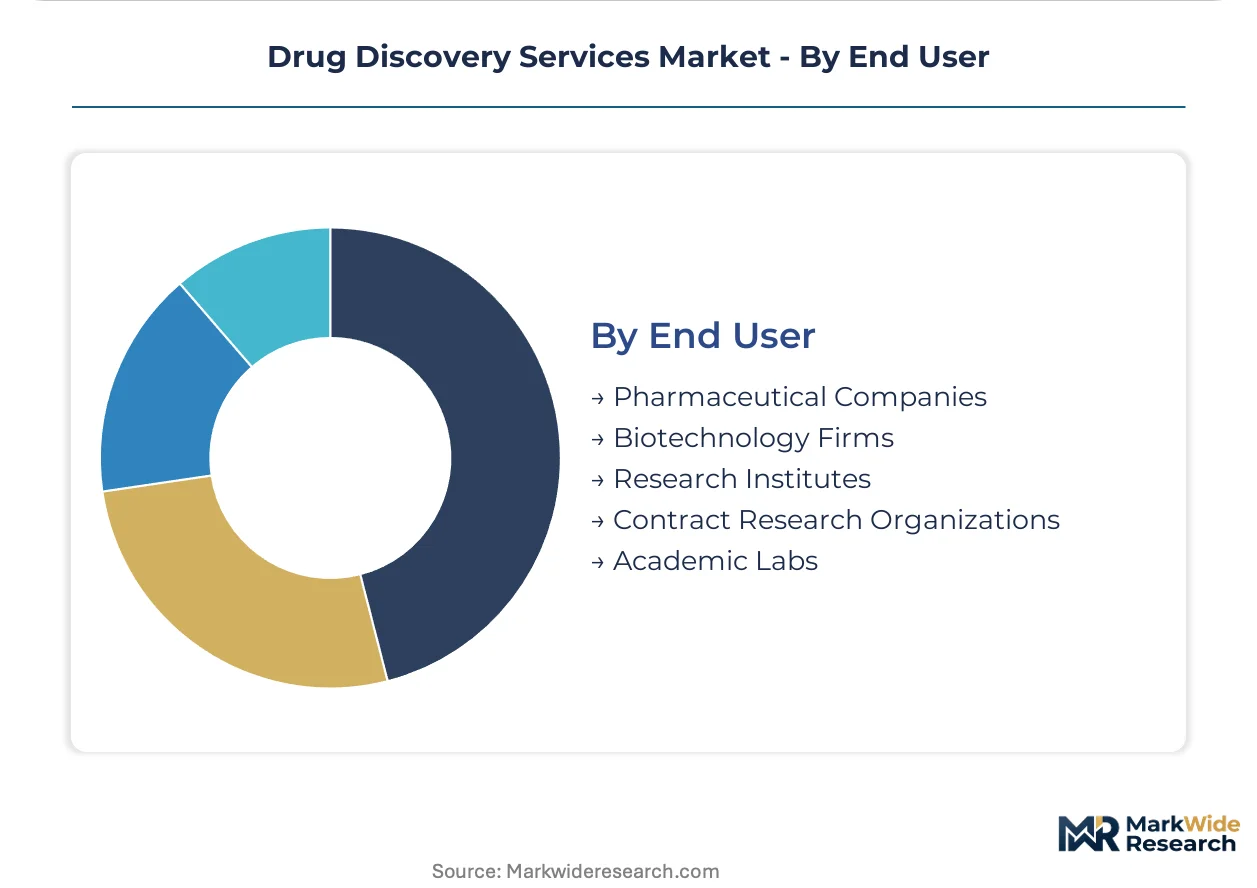
- Pharmaceutical Companies:These large enterprises outsource specific discovery activities to augment internal capabilities, access specialized technologies, and accelerate their extensive pipelines. Established pharmaceutical companies drive substantial demand for lead optimization services.
- Biotechnology Firms:Emerging biotechnology firms, often venture-backed, rely heavily on outsourced discovery services to rapidly advance preclinical assets without significant in-house infrastructure. Surging venture capital influx creates strong demand from these clients.
- Research Institutes:Academic and non-profit research institutions utilize discovery services for basic research, target validation, and early-stage drug development projects. These institutes frequently partner for specialized high-throughput screening.
- Contract Research Organizations:CROs themselves may utilize specialized discovery services from other providers to enhance their offerings or manage overflow, particularly for niche technologies. Mid-sized CROs often seek specific ADMET profiling capabilities.
- Academic Labs:Individual academic laboratories leverage discovery services for specific experiments, data analysis, and access to advanced instrumentation. These labs often require support for genomics and proteomics studies.
Established market demand is anchored by Pharmaceutical Companies, with Biotechnology Firms demonstrating robust new service uptake.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones and tax-incentive regions are driving significant concentration in the drug discovery services market. These areas attract substantial investment and foster dense biopharma ecosystems. The strategic focus on R&D infrastructure within these zones accelerates preclinical development pipelines for clients.
United States
Surging venture capital funding into emerging biotechnology firms generates strong demand for outsourced discovery services. The FDA's Model-Informed Drug Development (MIDD) pathways encourage investment in computational and advanced cell-based screening. The Boston-Cambridge region and San Francisco Bay Area anchor innovation, fostering integrated, risk-sharing discovery partnerships.
China
A sustained influx of venture capital into Chinese biotechnology firms creates strong demand for rapid preclinical asset advancement. The NMPA's evolving regulatory framework emphasizes quality and data integrity for nonclinical studies. Shanghai and Beijing function as prominent biopharma hubs, leveraging fully integrated platforms from computational chemistry to lead optimization.
Germany
Germany's robust pharmaceutical industry and strong academic research base drive consistent demand for advanced discovery services. The EMA's stringent data requirements for Investigational New Drug applications necessitate adherence to GLP standards. Munich and Heidelberg represent key biotech clusters, specializing in high-throughput screening and complex data-driven discovery.
United Kingdom
The established UK biopharma sector, coupled with strong academic-industry collaboration, fuels demand for specialized discovery capabilities. The Medicines and Healthcare products Regulatory Agency (MHRA) ensures compliance with global GLP standards and data integrity. Cambridge, UK, remains a significant biopharma hub, integrating artificial intelligence into high-throughput screening platforms.
South Korea
South Korea's growing biopharma ecosystem and government support for R&D present a strategic opportunity for integrated discovery service hubs. The Ministry of Food and Drug Safety (MFDS) actively promotes novel therapeutic modalities, requiring unique discovery and characterization workflows. Seoul and Gyeonggi Province are emerging centers for biotech innovation, attracting investment in specialized platforms.
Drug Discovery Services Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments within the drug discovery services market. The market exhibits a tiered structure, with large, integrated contract research organizations (CROs) competing alongside specialized technology providers and niche regional players. Strategic partnerships and geographic expansion represent dominant competitive moves among market participants.
Global contract research organizations like Charles River Laboratories International Inc. and WuXi AppTec Co., Ltd. exemplify the integrated platform approach, offering comprehensive services from early discovery to lead optimization. Evotec SE occupies a position as a specialized partner, focusing on high-throughput screening and complex data-driven discovery partnerships. These companies anchor the market's capabilities, providing essential infrastructure and expertise to clients worldwide.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Charles River Laboratories International Inc. |
| Laboratory Corporation of America Holdings |
| WuXi AppTec Co., Ltd. |
| Evotec SE |
| Eurofins Scientific SE |
| Syngene International Ltd. |
| Pharmaron Beijing Co., Ltd. |
| Aragen Life Sciences Ltd. |
Cost & Logistics Intelligence
Outsourced discovery services, particularly from integrated Contract Research Organizations, anchor the supply position for emerging biotechnology firms and dictate pricing power based on specialized capabilities and comprehensive platforms. This model allows clients to access advanced technologies without significant capital expenditure.
Pricing Analysis
High-volume, standardized services like basic high-throughput screening often operate on tighter margins, while specialized, data-driven partnerships command higher value-based pricing. The dominant pricing model involves project-based fees, increasingly shifting towards milestone-based payments for integrated discovery collaborations. Price differentiation stems from the complexity of the scientific challenge, the integration of advanced technologies like AI, and adherence to stringent GLP standards. Emerging biotechnology firms exhibit greater price sensitivity compared to established pharmaceutical companies seeking advanced capabilities.
Supply Chain Analysis
Access to specialized scientific talent and advanced instrumentation forms the primary input dependency for drug discovery service providers. Service supply concentrates in established biopharma hubs like Boston-Cambridge, Shanghai, and Munich, leveraging dense academic and industrial ecosystems. Key raw material dependencies include specialized reagents for assays and high-throughput screening platforms. A structural risk involves the scarcity of bioinformatics talent, which constrains operational capacity for data-intensive projects. Distribution primarily runs through direct client engagement models, often via integrated CRO platforms offering end-to-end support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The drug discovery services market is undergoing a consolidation play, driven by the high capital intensity required for state-of-the-art instrumentation and advanced AI platforms. Smaller service providers face significant barriers to entry and operational scaling, forcing market integration.
For Market Incumbents: Deploy integrated AI and ML platforms to enhance predictive accuracy and accelerate discovery timelines, mitigating predictive model limitations. Incumbents should pursue strategic geographic expansion into emerging biopharma ecosystems like South Korea to capture new demand. Developing specialized platforms for novel therapeutic modalities, such as cell and gene therapies, reinforces market leadership against niche technology providers. This approach also addresses the scarcity of bioinformatics talent by centralizing expertise.
For New Entrants and Emerging Players: A price-point gap exists where specialized services, particularly in emerging technologies, lack robust mid-tier offerings. New entrants can target niche technology areas like Cryo-EM services combined with AI-powered data processing to resolve intractable drug targets. The most penetrable segment involves emerging biotechnology firms seeking specialized support for rare disease pipelines. A key go-to-market angle involves offering integrated, risk-sharing discovery partnerships with milestone-based payments.
For Investors and Strategic Acquirers: Exit pathways concentrate in specialized technology providers and regional market leaders with strong client relationships. The market demonstrates long-term viability over the next 5-10 years, driven by sustained venture capital funding into biotech and increasing AI integration. Acquisition targets should include firms with validated advanced computational modeling capabilities or unique platforms for novel therapeutic modalities. A critical signal to watch is the continued regulatory modernization, particularly the FDA's acceptance of in silico data in IND submissions.
| Strategic Initiative | Industry Significance |
|---|---|
| AI/ML Platform Integration | Accelerates discovery timelines and improves success rates for client programs, particularly in lead optimization. |
| Specialized Modality Development | Addresses unique discovery workflows for cell and gene therapies, supporting high-value rare disease pipelines. |
| Geographic Hub Expansion | Establishes integrated service centers in growing biopharma ecosystems like South Korea, attracting local innovation. |
| Risk-Sharing Partnership Models | Aligns CRO incentives with client pipeline goals, disrupting traditional fee-for-service engagements. |
| Cryo-EM Service Enhancement | Resolves previously intractable drug targets, compressing timelines for understanding drug-target binding. |
Research Approach
FDA filings, EMA submissions, and venture capital funding reports formed the secondary backbone for this analysis, complemented by extensive scientific literature. Primary interviews with drug development executives, regulatory affairs leads, and biotech founders provided qualitative insights and market validation. This approach combined bottom-up data aggregation with top-down market sizing, ensuring robust triangulation.
A bottom-up approach aggregated segment-specific data, while a top-down validation cross-referenced overall market size across the analysis window. Segmentation dimensions modeled included service type, technology, therapy area, end-user, and regional regulatory cluster. Compound annual growth rates were derived from historical trends, identified growth catalysts, and prevailing market dynamics. Key forecast inputs included global R&D investment trends and evolving regulatory policy shifts.
Inputs from public company reports and regulatory databases were available through the study window; gaps in proprietary client data introduce uncertainty bands. Forecasts reflect assumptions regarding AI model validation and evolving data sharing regulations. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Services
Biomarker Research Services Market
Biotechnology Services
Global Molecular Biology Enzymes and Kits and Reagents Market
Biotechnology Services
In-Vitro Fertilization Services Market
Biotechnology Services
Global Cell Banking Outsourcing Market
Biotechnology Services
Global Digital PCR (Dpcr) and Real-Time PCR (Qpcr) Market
Biotechnology Services
Molecular Methods Market
Biotechnology Services
US Digital PCR Market
Biotechnology Services
Vaccine and Biologic Product Distribution Optimization Services Market
Biotechnology Services
Plasmid DNA Contract Manufacturing Market
Biotechnology Services
Global Reporter Gene Assay Market
Biotechnology Services
Mirna Tools and Services Market
Biotechnology Services
Stable Cell Line Development Market
Biotechnology Services
Research Antibodies and Reagents Market
Biotechnology Services
Riboflavin Kinase Market
Biotechnology Services
Research Antibodies Market
Biotechnology Services
Biologics Contract Manufacturing Market