
 Cdna Synthesis Market | 2026-2036
Cdna Synthesis Market Size, Share, and Industry Trends Forecast 2026-2036
Cdna Synthesis Market Outlook
The EU Green Deal is rebalancing procurement criteria for molecular biology consumables toward suppliers with verified sustainable manufacturing. Thermo Fisher Scientific leverages its integrated reagent-instrument ecosystem to dominate high-throughput cDNA workflows. QIAGEN anchors its position through sample-to-insight automation that bundles cDNA synthesis with downstream analytics. New England Biolabs differentiates via enzyme engineering leadership, sustaining premium positioning in research-grade reverse transcriptases.
Complementary DNA synthesis refers to the enzymatic production of DNA strands from RNA templates, typically employing reverse transcriptase enzymes at reaction temperatures between 42°C and 55°C to generate stable DNA copies for gene expression profiling and cloning applications. Kits and reagents capture the dominant share of product value due to recurring consumption in high-volume sequencing pipelines, while instruments face longer replacement cycles. Next-generation sequencing applications command accelerating cDNA demand as clinical transcriptomics expands, though gene expression analysis remains the mature workhorse segment anchoring baseline volumes.
The FDA enforces current Good Manufacturing Practice standards for cDNA inputs destined for therapeutic applications, while ISO 13485 certification governs diagnostic-grade reagent quality systems. The EPA monitors solvent and hazardous waste streams from phosphoramidite chemistry used in some synthesis workflows. Stakeholders must monitor evolving nucleic acid therapeutic regulations and decide whether to pursue dual-track quality certifications that bridge research and clinical markets.
Market Dynamics
The FDA's evolving nucleic acid therapeutic guidance is compressing quality certification timelines, forcing suppliers to bridge research-grade and clinical-grade production systems simultaneously.
Growth Catalysts
- mRNA vaccine pipelines:Pharmaceutical manufacturers are scaling cDNA synthesis capacity to support personalized cancer vaccines and infectious disease prophylactics.
- EU Green Deal procurement criteria:European biotech procurement teams now weight verified sustainable manufacturing in molecular biology consumable sourcing decisions.
- Reverse transcriptase engineering:Thermostable enzyme variants enable single-reaction workflows that reduce hands-on time in high-throughput sequencing facilities.
Market Restraints
- Phosphoramidite chemistry waste streams:EPA hazardous waste monitoring increases compliance overhead for oligonucleotide synthesis operations.
- Enzyme supply concentration:Research-grade reverse transcriptase production clusters among specialized fermentation facilities in Massachusetts and California.
- ISO 13485 certification barriers:Diagnostic-grade reagent qualification timelines extend 18-24 months, freezing out mid-tier suppliers without dedicated quality infrastructure.
Strategic Opportunities
- Gene therapy CDMO expansion:Contract development organizations in Singapore and South Korea are building cDNA synthesis capabilities to capture Asia-Pacific nucleic acid therapeutic manufacturing.
- Sample-to-insight automation:Integrated platforms bundling cDNA synthesis with real-time PCR and digital PCR analytics reduce per-sample processing costs.
- REACH-aligned reagent portfolios:European suppliers reformulating chemistries to eliminate substances of very high concern are capturing premium positioning in sustainability-weighted tenders.
Industry Challenges
- Dual-track quality system management:Suppliers must maintain separate GMP and research-grade production lines without cross-contamination, straining facility design and personnel training.
- Legacy instrument integration:New high-fidelity reverse transcriptase formulations require protocol revalidation on installed base thermal cyclers, slowing adoption cycles in established genomics core facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cdna Synthesis Market |
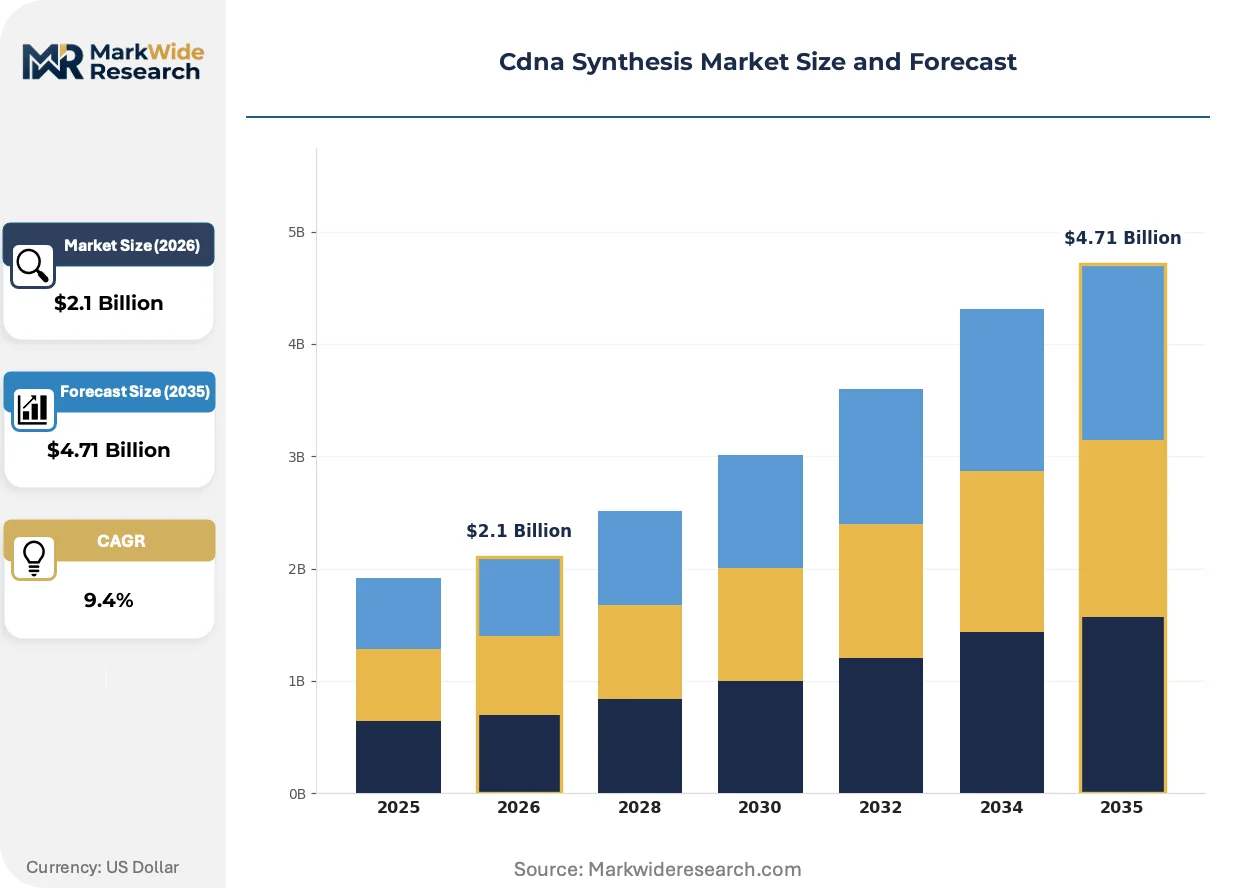
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.71 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Kits, Reagents, Enzymes, Instruments End User: Academic Institutions, Research Laboratories, Pharmaceutical Companies, Biotechnology Firms Technology: Polymerase Chain Reaction, Reverse Transcription, Microfluidics, Next-Generation Sequencing Application: Gene Expression Analysis, Clone Development, Diagnostic Testing, RNA Sequencing |
| Companies Covered | Thermo Fisher Scientific, Bio-Rad Laboratories, QIAGEN, New England Biolabs, Takara Bio, Agilent Technologies, Roche Diagnostics, Bioline, Promega Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cdna Synthesis Market Strategic Shifts
Enzyme engineering and regulatory harmonization are compressing the gap between research tools and clinical inputs, reshaping how suppliers structure quality systems and customer support.
Engineered reverse transcriptases with proofreading activity are consolidating error rates in single-molecule sequencing applications below 10^-4 per base. Clinical transcriptomics laboratories in the United States are adopting these enzymes for liquid biopsy workflows within 12-18 month validation cycles. The technology is consolidating the previously separate markets for research-grade and diagnostic-grade cDNA synthesis reagents.
EMA's evolving guidance on nucleic acid active substance manufacturing is tightening documentation requirements for starting materials in gene therapy products. European contract manufacturers must now implement enhanced change control procedures for cDNA synthesis inputs. Small-scale suppliers without dedicated regulatory affairs teams are exiting the therapeutic-grade segment rather than absorbing compliance costs.
Consolidated procurement through integrated reagent-instrument contracts is displacing standalone kit purchasing in sequencing core facilities. Academic and commercial genomics centers in Boston and San Diego are negotiating multi-year supply agreements that bundle cDNA synthesis with downstream analytics. This bundling compresses vendor margins on commoditized reagents while locking in instrument ecosystem loyalty.
Cdna Synthesis Market Segmentation
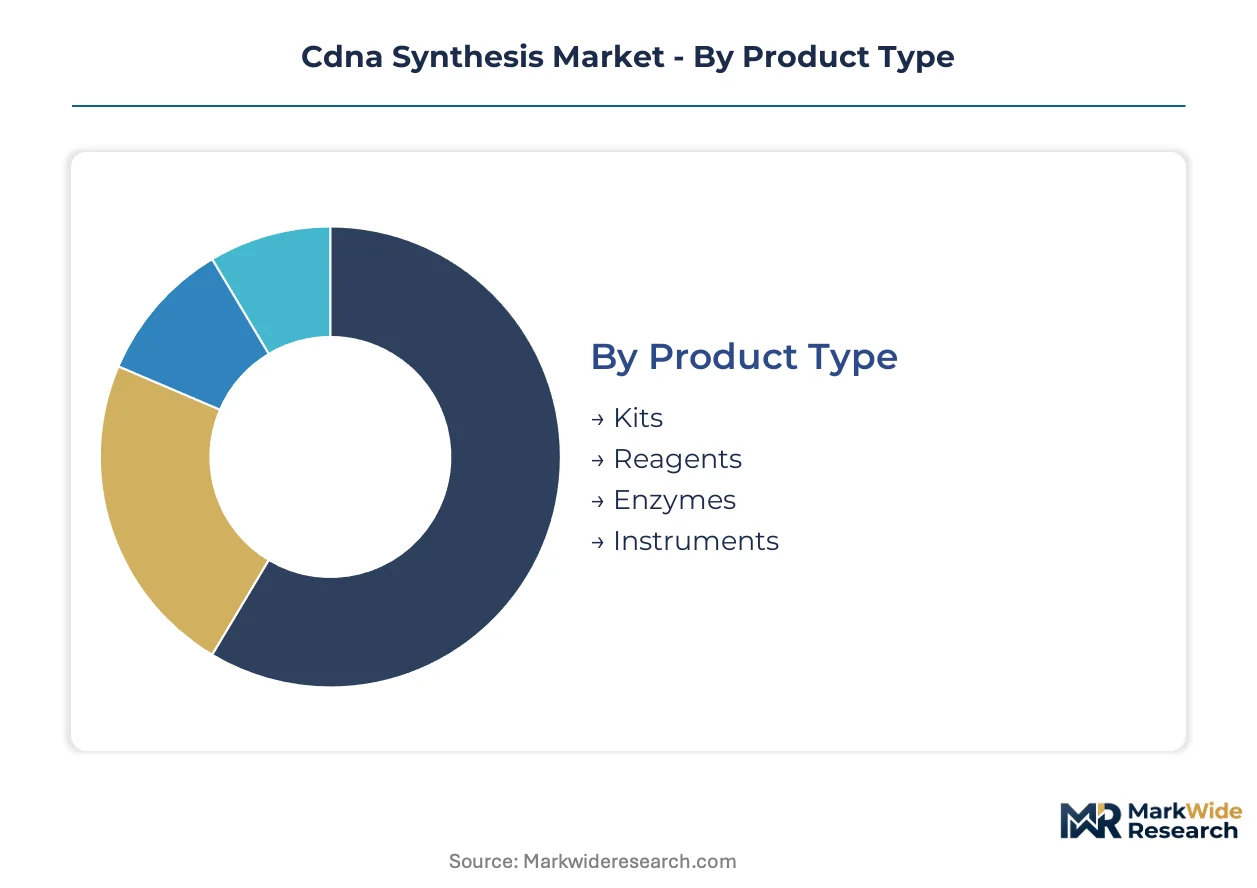
Segmentation in cDNA synthesis reveals distinct capital requirements and margin profiles across product categories. Understanding these structural differences guides supplier resource allocation and customer targeting strategies.
Product Type:
Capital intensity varies dramatically across this category, with instruments demanding the heaviest upfront investment while reagents generate recurring revenue through consumable models.
- Kits:Pre-formulated reaction systems bundle reverse transcriptase, primers, and buffers in standardized configurations. Pharmaceutical companies in Boston and San Diego biotech clusters consume these at scale for mRNA vaccine development pipelines. Kits capture premium positioning through ISO 13485-certified formulations for diagnostic workflows.
- Reagents:Individual chemistries including nucleotides, primers, and specialized buffers enable protocol customization. Demand concentrates in academic genomics cores where researchers optimize reaction conditions for novel RNA templates. Reagent purchasing patterns track closely with NGS facility expansion cycles.
- Enzymes:Reverse transcriptase variants engineered for thermostability or proofreading activity. Massachusetts and California fermentation facilities supply research-grade formulations to global distributors.
- Instruments:Thermal cyclers and automated liquid handlers with multi-channel dispensing capabilities. Replacement cycles extend 5-7 years, constraining revenue predictability for equipment manufacturers.
Most installed capacity flows through Reagents. Expansion is steepest in Kits as diagnostic laboratories standardize workflows.
End User:
Customer type determines pricing power and contract structure, with pharmaceutical buyers extracting volume discounts unavailable to fragmented academic purchasers.
- Academic Institutions:University genomics cores and departmental research labs operating on grant-funded procurement cycles. Budget constraints favor kit-based purchasing over custom reagent formulation. Funding volatility from NIH and NSF creates demand unpredictability.
- Research Laboratories:Government and nonprofit research institutes with standardized quality requirements. These facilities prioritize enzyme fidelity metrics over cost minimization for publication-grade data.
- Pharmaceutical Companies:Large manufacturers scaling cDNA synthesis for therapeutic mRNA and gene therapy pipelines. GMP-compliant inputs command 3-5x pricing premiums over research-grade equivalents.
- Biotechnology Firms:Venture-backed startups and mid-stage developers in Singapore and South Korea CDMO networks. These buyers negotiate flexible supply agreements tied to clinical milestone timelines.
Pharmaceutical Companies deploy the largest order values. Biotechnology Firms are expanding most quickly as Asia-Pacific nucleic acid therapeutic manufacturing scales.
Technology:
Technical sophistication separates commodity workflows from premium applications, with microfluidics and NGS platforms commanding specialized expertise.
- Polymerase Chain Reaction:Endpoint and quantitative amplification methods for cDNA quantification. Mature technology with established protocol libraries across research and clinical settings.
- Reverse Transcription:Core enzymatic process employing engineered transcriptases at 42-55°C reaction temperatures. Thermo Fisher Scientific and New England Biolabs dominate through proprietary enzyme variants.
- Microfluidics:Integrated chip-based systems miniaturizing reaction volumes for single-cell transcriptomics. Clinical laboratories in the United States adopt these for liquid biopsy workflows within 12-18 month validation cycles.
- Next-Generation Sequencing:High-throughput cDNA library preparation for RNA-seq and targeted expression profiling. Sequencing core facilities in Boston and San Diego anchor demand for automation-compatible reagent formats.
Reverse Transcription underpins the largest installed base. Microfluidics is gaining share fastest as single-cell applications expand.
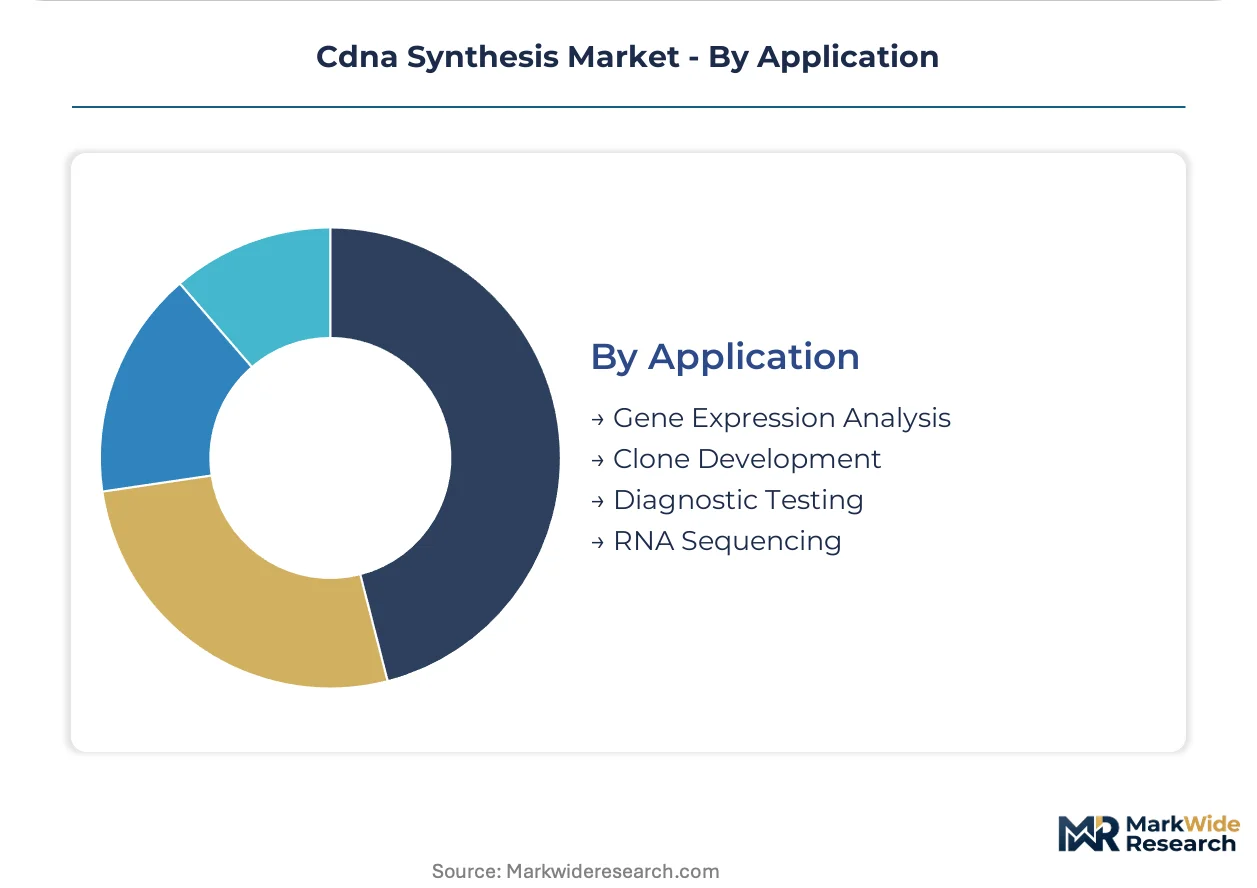
Application:
Use case maturity shapes competitive dynamics, with established gene expression workflows facing pricing pressure while emerging diagnostic applications sustain premiums.
- Gene Expression Analysis:Quantitative measurement of transcript abundance via qPCR and RNA-seq methods. Mature workhorse segment anchoring baseline reagent volumes across academic and commercial labs.
- Clone Development:cDNA insertion into expression vectors for recombinant protein production. Contract manufacturers in Europe implement enhanced change control procedures for therapeutic-grade inputs per EMA guidance.
- Diagnostic Testing:Clinical transcriptomics for disease biomarker detection and monitoring. FDA cGMP standards govern cDNA inputs, compressing supplier qualification timelines.
- RNA Sequencing:Comprehensive transcriptome profiling for discovery research and precision medicine. NGS facilities prioritize high-fidelity reverse transcriptase formulations to minimize error rates below 10^-4 per base.
Gene Expression Analysis processes the highest sample volumes. RNA Sequencing shows the steepest expansion trajectory as clinical transcriptomics scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Molecular biology PhD concentrations in Boston, San Diego, and the Research Triangle anchor North American cDNA synthesis demand. European enzyme engineering talent clusters around Heidelberg and Cambridge. Singapore and South Korea CDMO workforces are expanding fastest.
United States
mRNA vaccine manufacturing scale-up and gene therapy clinical trials drive cDNA synthesis procurement. FDA cGMP standards compress supplier qualification timelines for therapeutic-grade inputs. Boston and San Diego biotech clusters negotiate multi-year reagent-instrument supply agreements.
Germany
Heidelberg's enzyme engineering research institutes and industrial fermentation facilities sustain research-grade reverse transcriptase production. EMA nucleic acid therapeutic guidance tightens documentation requirements for gene therapy starting materials. Bavarian contract manufacturers implement enhanced change control procedures for clinical-grade cDNA inputs.
Singapore
Gene therapy CDMO expansion and nucleic acid therapeutic manufacturing investments accelerate cDNA synthesis capacity buildout. The country's national pharmaceutical regulator aligns with EMA standards for active substance documentation. Biopolis research parks attract multi-national biotech firms establishing Asia-Pacific production hubs.
South Korea
Oligonucleotide therapeutic pipelines and biosimilar development programs expand cDNA synthesis demand. MFDS nucleic acid product guidance shapes local quality certification requirements. Seoul-Incheon biotech corridors host fermentation facilities supplying engineered reverse transcriptases to regional distributors.
Switzerland
Precision medicine research and diagnostic reagent manufacturing sustain premium cDNA synthesis consumption. Swissmedic gene therapy regulations govern starting material traceability. Basel-Zurich biopharma clusters source ISO 13485-certified kits for clinical transcriptomics workflows.
Cdna Synthesis Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the cDNA synthesis landscape. Integrated reagent-instrument ecosystems dominate high-throughput sequencing facilities, while specialized enzyme engineering firms capture premium positioning in research-grade reverse transcriptases. Three archetypes define competitive structure: diversified life science conglomerates with platform ecosystems, enzyme-focused biotechnology specialists, and regional fermentation-based suppliers. M&A activity concentrates on sample-to-insight automation capabilities, while strategic partnerships bridge research-grade and clinical-grade quality systems.
Within the diversified conglomerate tier, Thermo Fisher Scientific exemplifies platform integration strategies spanning reagents, instruments, and analytics. QIAGEN occupies a position emphasizing sample-to-insight workflow automation. New England Biolabs represents enzyme engineering specialization, anchoring premium positioning through proprietary reverse transcriptase variants. These three firms illustrate how competitive advantage in cDNA synthesis flows from distinct capability configurations rather than scale alone.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Bio-Rad Laboratories |
| QIAGEN |
| New England Biolabs |
| Takara Bio |
| Agilent Technologies |
| Roche Diagnostics |
| Bioline |
| Promega Corporation |
| Others |
Value Chain & Pricing Dynamics
Phosphoramidite chemistry feedstocks flow from specialty chemical manufacturers through three certification tiers that stratify pricing across research-grade, diagnostic-grade, and GMP-compliant reagent portfolios. Enzyme fermentation capacity in Massachusetts and California anchors upstream cost structures, while downstream buyers in Boston and San Diego biotech clusters negotiate bundled reagent-instrument contracts that compress standalone kit margins.
Pricing Analysis
Bundled service contracts dominate high-throughput sequencing facilities, while unbundled kit purchasing persists in grant-funded academic cores. Three-tier pricing structure across premium, standard, and economy levels separates ISO 13485-certified diagnostic formulations from research-grade equivalents, with GMP-compliant inputs commanding 3-5x premiums. Cost compression in standard-tier reagents is intensifying because consolidated procurement through multi-year supply agreements displaces spot purchasing. Academic institutions exhibit highest price sensitivity due to NIH funding volatility, while pharmaceutical companies prioritize quality certification over unit cost minimization.
Supply Chain Analysis
Reverse-logistics flows for temperature-sensitive enzymes and reagents require cold-chain refurbishment networks that extend from fermentation facilities to end-user laboratories. Manufacturing concentrates in the United States, Germany, and Singapore, with Massachusetts and Heidelberg anchoring enzyme engineering and Bavarian contract manufacturers supplying clinical-grade formulations. Raw material dependencies center on phosphoramidite chemistries, specialized fermentation media, and purified nucleotide triphosphates. Single-source vulnerability in thermostable reverse transcriptase variants creates supply risk given concentration among Massachusetts and California production sites. Distribution runs through authorized distributors and direct sales teams serving pharmaceutical and diagnostic laboratory segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cDNA synthesis market functions as a stable compounder anchored by recurring consumable demand from expanding mRNA vaccine and gene therapy pipelines. Therapeutic nucleic acid development creates durable reagent pull-through that outpaces capital equipment replacement cycles.
For Market Incumbents: Anticipate margin compression in commoditized research-grade kits by accelerating sample-to-insight automation platform development. Thermo Fisher Scientific and QIAGEN illustrate how integrated reagent-instrument ecosystems defend positioning against standalone reagent competitors. FDA cGMP certification investments create switching costs that freeze out mid-tier suppliers lacking dedicated quality infrastructure. Priority levers include backward integration into proprietary enzyme variants and multi-year supply agreements with Boston and San Diego biotech clusters.
For New Entrants and Emerging Players: EU Green Deal procurement criteria in Europe opens a window for REACH-aligned reagent portfolios to capture sustainability-weighted tenders from European biotech procurement teams. White-space targets include single-cell transcriptomics microfluidics workflows and Asia-Pacific CDMO cDNA synthesis capacity serving Singapore and South Korea gene therapy manufacturing. The most penetrable segment lies in flexible supply agreements for venture-backed biotechnology firms with clinical milestone-tied procurement needs. A sample-to-insight bundling go-to-market angle reduces per-sample processing costs and accelerates adoption in sequencing core facilities.
For Investors and Strategic Acquirers: Roll-up economics work for enzyme engineering specialists because proofreading-capable reverse transcriptase variants command premium positioning that consolidates previously separate research and diagnostic-grade markets. Long-term viability across a 5-10 year window hinges on regulatory harmonization compressing quality certification timelines. Acquisition targets should display ISO 13485 quality infrastructure paired with proprietary enzyme formulations. The signal to watch is EMA nucleic acid therapeutic guidance tightening documentation requirements for gene therapy starting materials, which accelerates supplier consolidation as small-scale players exit therapeutic-grade segments.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Track Quality Certification Investment | ISO 13485 and FDA cGMP bridging enables simultaneous research and clinical market access. |
| Enzyme Engineering Partnership | Thermostable reverse transcriptase variants reduce hands-on time in high-throughput sequencing facilities. |
| Sample-to-Insight Automation Platform | Integrated cDNA synthesis with real-time PCR analytics lowers per-sample processing costs. |
| REACH-Aligned Chemistry Reformulation | Elimination of substances of very high concern captures premium positioning in EU Green Deal tenders. |
| Asia-Pacific CDMO Capacity Buildout | Singapore and South Korea fermentation facilities serve regional nucleic acid therapeutic manufacturing demand. |
Study Parameters
Bottom-up pharmaceutical and biotechnology procurement modeling reconciled against top-down enzyme manufacturing capacity tracking forms the analytical core of this study. Primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers combined with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases. Bottom-up and top-down triangulation cross-checks segment-level demand assumptions against supplier production capacity disclosures.
Historical trendline analysis of cDNA synthesis kit and reagent consumption patterns established baseline growth trajectories across the projection horizon. Segmentation dimensions modeled include product type, end user category, technology platform, and application workflow, with regional regulatory cluster as an industry-specific overlay. CAGRs were derived through regression analysis of installed base expansion, replacement cycle timing, and therapeutic pipeline progression. Forecast inputs incorporate mRNA vaccine manufacturing scale-up assumptions and gene therapy clinical trial enrollment trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt FDA nucleic acid therapeutic guidance revisions or phosphoramidite chemistry supply disruptions. Forecasts reflect documented assumptions regarding therapeutic pipeline progression, quality certification adoption rates, and enzyme engineering innovation cycles. Practitioners should monitor EMA active substance documentation requirements, EPA hazardous waste enforcement intensity, and Asia-Pacific CDMO capacity announcements for early signals of forecast deviation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Services
Antibodies Contract Manufacturing Market
Biotechnology Services
Transport Protein Assays Kits Market
Biotechnology Services
Feruloyl Esterase Market
Biotechnology Services
Biotechnology and Pharmaceutical Services Outsourcing Market
Biotechnology Services
Antibody Purification Service Market
Biotechnology Services
Biobank Market
Biotechnology Services
Custom Peptide Synthesis Services Market
Biotechnology Services
Global Eukaryotic Expression Systems Market
Biotechnology Services
Research Antibodies Market
Biotechnology Services
Cell Line Development Market
Biotechnology Services
Marine Polysaccharides Fucoidan Alginate Market
Biotechnology Services
Recombinant Proteins Manufacturing Services Market
Biotechnology Services
Bioanalytical Testing Services Market
Biotechnology Services
Global Western Blotting Market
Biotechnology Services
Antibody Contract Development & Manufacturing Organization Market
Biotechnology Services
Monoclonal Antibody Custom Service Market