
 Europe Recombinant Protein Manufacturing Services Market | 2026-2036
Europe Recombinant Protein Manufacturing Services Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Recombinant Protein Manufacturing Services Market Analytics
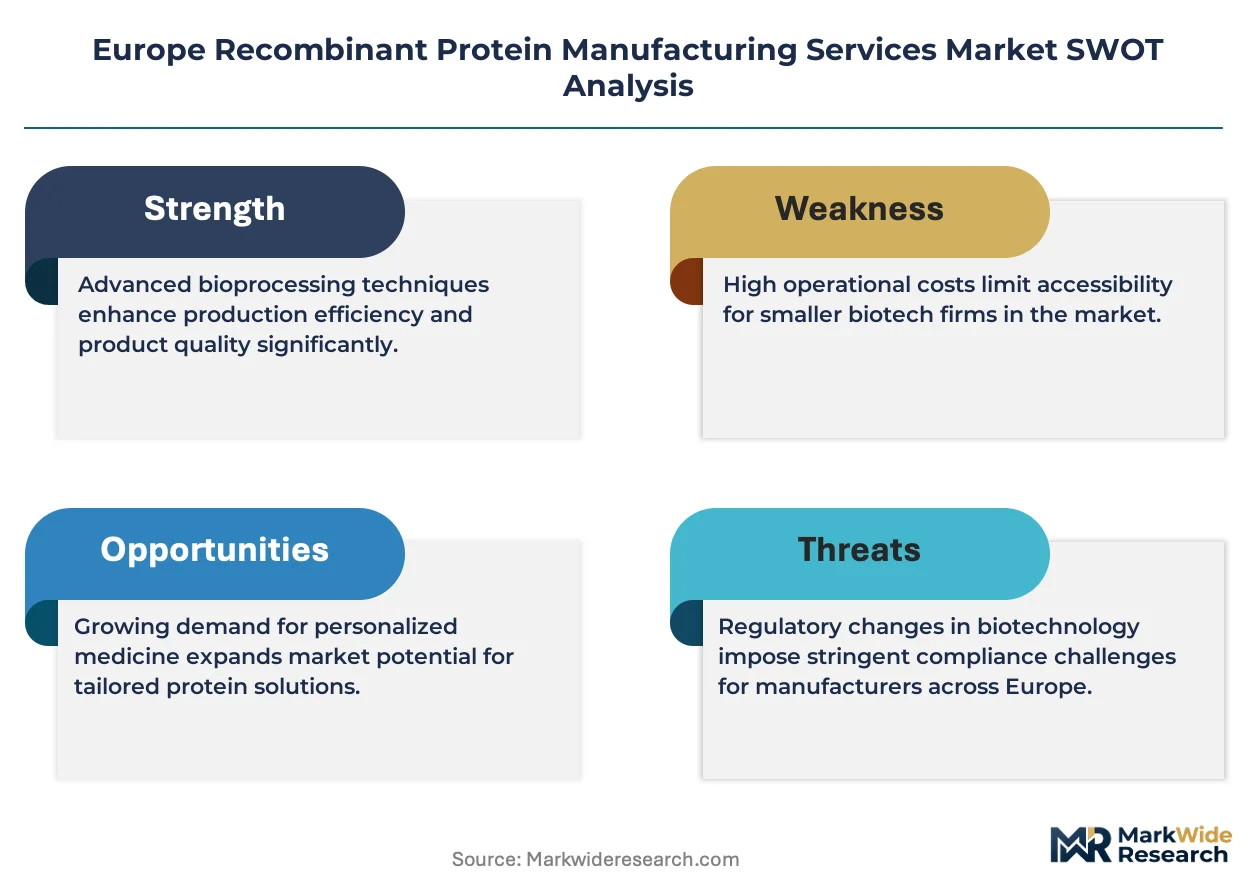
Single-use bioreactor systems and continuous processing platforms are reshaping recombinant protein production economics across European CDMO networks. Lonza leverages its Swiss manufacturing footprint to anchor multi-product biologics campaigns for global pharmaceutical clients. Boehringer Ingelheim International GmbH sustains one of Europe's largest mammalian cell culture capacities through dedicated facilities in Germany. FUJIFILM Diosynth Biotechnologies competes aggressively on microbial and cell-based expression flexibility across its European sites.
Recombinant protein manufacturing services encompass the contract production of genetically engineered proteins using host expression systems, typically achieving titers of 3-5 grams per liter in optimized mammalian cultures and requiring downstream purification to 95% plus purity for therapeutic applications. These services supply active pharmaceutical ingredients for biologics development and commercial supply, with monoclonal antibodies occupying the dominant product category by value due to oncology and autoimmune therapy pipelines. Mammalian cell systems lead technology adoption for complex glycoproteins, while bacterial systems dominate hormone and enzyme production where simpler post-translational modifications suffice.
EMA's biosimilar approval pathways and the EU's updated GMP Annex 1 for sterile manufacturing shape facility investment priorities across European CDMOs. REACH chemical registration requirements and the EU Green Deal's carbon reduction mandates are forcing process redesign toward lower-energy purification and reduced solvent consumption. Stakeholders must monitor how EMA's evolving guidance on complex generics and the EU AI Act's deployment rules for automated bioprocess analytics will reshape qualification requirements and competitive differentiation in contract manufacturing selection.
Market Dynamics
EMA's tightened GMP Annex 1 standards for sterile manufacturing are forcing European CDMOs into facility-wide upgrades, compressing legacy stainless-steel capacity while accelerating single-use platform adoption across mammalian cell culture networks.
Growth Catalysts
- EU Green Deal carbon mandates:REACH chemical registration and solvent reduction targets are driving investment in aqueous purification technologies and continuous processing platforms.
- Oncology pipeline expansion:Biopharmaceutical developers in Germany and Switzerland are outsourcing monoclonal antibody production to specialized mammalian cell culture facilities.
- EMA biosimilar pathway maturation:Streamlined approval frameworks for complex generics are expanding contract manufacturing demand for reference product characterization and analytical services.
Market Restraints
- Plasma-derived protein competition:Established fractionation infrastructure for albumin and immunoglobulin limits recombinant substitution in volume-driven therapeutic segments.
- Swiss-German capacity concentration:Over half of European mammalian cell culture capacity clusters in the Basel-Zurich and Rhine-Main corridors, creating geographic supply risk.
- Skilled technician scarcity:Cell culture specialist wages in the Netherlands and Switzerland have escalated faster than process automation can offset.
Strategic Opportunities
- Spanish and Italian CDMO expansion:Lower facility operating costs and underutilized biotech parks in Barcelona and Milan attract multi-product campaign diversification.
- Continuous bioprocessing convergence:Integration of perfusion cell culture with single-use chromatography is collapsing batch cycle times for high-titer antibody programs.
- EU AI Act automated analytics:Machine learning-driven bioprocess monitoring qualifies for regulatory fast-track pathways, differentiating service providers with validated algorithmic control.
Industry Challenges
- Annex 1 qualification timelines:Facility revalidation for isolator-based aseptic processing extends project start dates by 12-18 months.
- Legacy ERP integration:Paper batch records and validated electronic systems create data integrity friction during technology transfers from sponsor companies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Recombinant Protein Manufacturing Services Market |
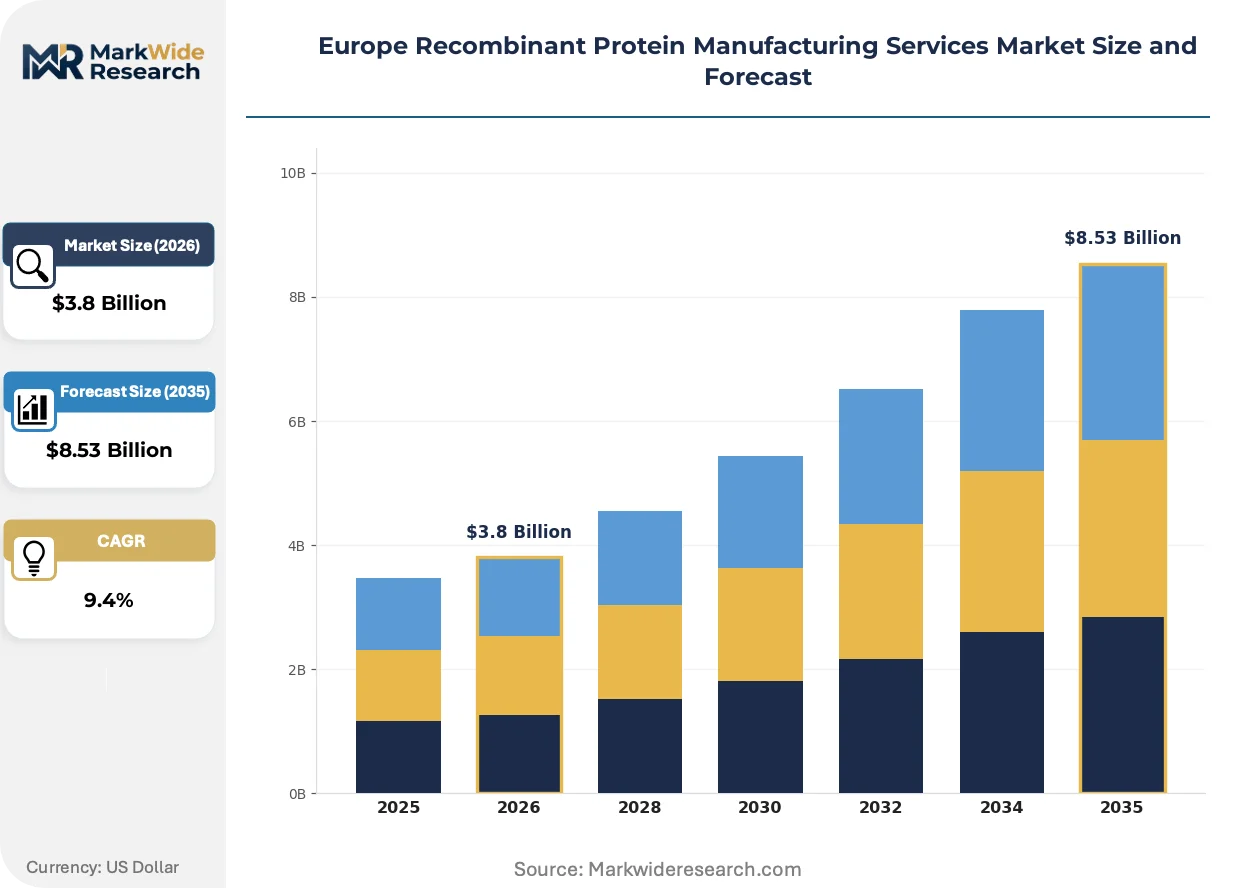
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cell Line Development, Protein Expression, Purification, Quality Control Product Type: Monoclonal Antibodies, Vaccines, Enzymes, Hormones Technology: Recombinant DNA, Mammalian Cells, Bacterial Systems, Yeast Systems End User: Pharmaceutical Companies, Biotechnology Firms, Research Institutions, Contract Manufacturers |
| Companies Covered | Lonza, Boehringer Ingelheim International GmbH, FUJIFILM Diosynth Biotechnologies, Merck KGaA, Bruker, Sino Biological, GenScript, Kaneka Eurogentec S.A, Trenzyme GmbH, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Recombinant Protein Manufacturing Services Market Evolving Landscape
Single-use technologies and continuous processing architectures are compressing capital requirements and batch timelines across European biologics manufacturing, redrawing competitive boundaries between stainless-steel legacy operators and modular platform specialists.
Perfusion bioreactor systems coupled with alternating tangential flow cell retention are rendering obsolete traditional fed-batch processes for high-value monoclonal antibodies. Mid-sized biopharmaceutical developers in Germany and the Netherlands are adopting these platforms for Phase III campaigns. The shift is collapsing facility footprint requirements and enabling multi-product flexibility that stainless-steel infrastructure cannot match.
EMA's updated GMP Annex 1 for sterile medicinal products mandates barrier technology and contamination control strategy documentation for all new biological manufacturing licenses. European CDMOs are retrofitting isolator lines and investing in automated environmental monitoring. Mammalian cell culture facilities in Switzerland and Germany face the steepest compliance curves due to higher legacy cleanroom exposure.
Biopharmaceutical sponsors are consolidating contract manufacturing relationships around full-service CDMOs with integrated analytical and regulatory capabilities. Small and mid-cap developers in the Netherlands are abandoning fragmented supplier networks for single-source partnerships spanning cell line development through commercial release. This concentration is most pronounced in oncology and autoimmune therapeutic segments where program complexity demands seamless technology transfer.
Europe Recombinant Protein Manufacturing Services Market Segmentation
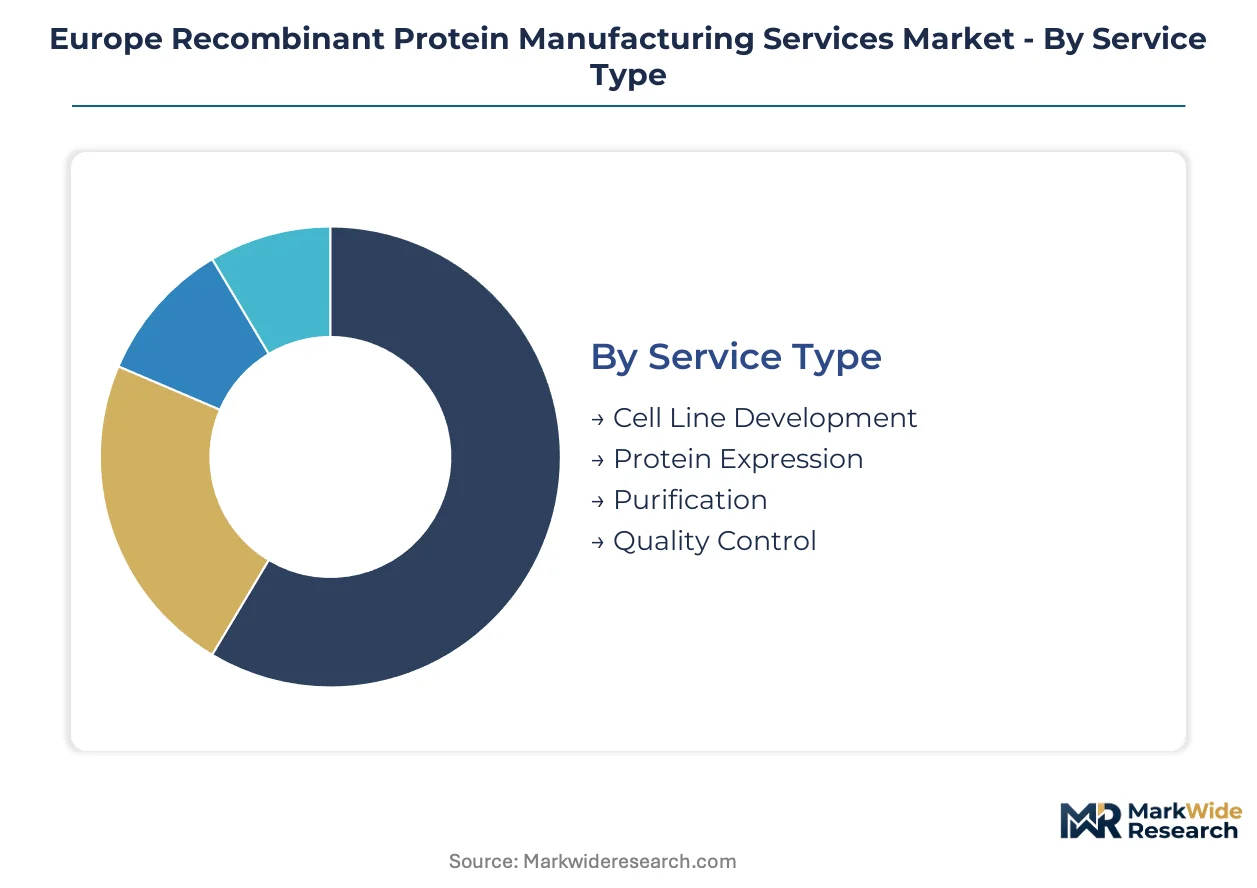
Segmentation in European recombinant protein manufacturing services reveals how contract manufacturing demand fragments across technical capabilities, therapeutic categories, and client sophistication tiers. Each dimension carries distinct margin profiles and facility investment requirements that reshape competitive positioning among CDMOs.
Service Type:
Cost tier differentiation across the manufacturing value chain determines which service modules command premium pricing versus commoditization pressure.
- Cell Line Development:Early-stage genetic engineering of host expression systems establishes productivity ceilings for entire manufacturing campaigns. German and Swiss biotech clusters concentrate demand here as sponsors seek high-titer mammalian platforms for oncology antibodies. EMA's evolving biosimilar comparability guidelines are extending timelines for clonal cell line qualification.
- Protein Expression:Bioreactor operation and process optimization constitute the largest revenue pool in contract manufacturing services. Perfusion-based mammalian cultures in the Netherlands and Switzerland are displacing fed-batch legacy capacity for high-value monoclonal antibody programs.
- Purification:Downstream chromatography and filtration steps consume the majority of batch cycle time and solvent volume. REACH chemical registration and EU Green Deal carbon mandates are forcing aqueous buffer substitution and continuous capture column adoption.
- Quality Control:Analytical method development and release testing represent the compliance gateway for commercial supply. EMA's updated GMP Annex 1 standards are mandating enhanced environmental monitoring and automated contamination detection systems.
Cell Line Development holds installed capacity. Quality Control is rotating up the share rankings.
Product Type:
Application focus across therapeutic categories determines facility configuration, regulatory pathway complexity, and client risk tolerance in outsourcing decisions.
- Monoclonal Antibodies:Complex glycoproteins requiring mammalian expression systems dominate revenue concentration in European CDMO portfolios. Oncology and autoimmune pipelines in Germany and Switzerland are expanding demand for multi-product biologics facilities with flexible campaign scheduling.
- Vaccines:Recombinant subunit and virus-like particle platforms span microbial and mammalian expression depending on immunogen complexity. EMA's streamlined approval pathways for pandemic preparedness are accelerating investment in dedicated antigen manufacturing suites.
- Enzymes:Bacterial and yeast expression systems suffice for therapeutic enzymes with minimal post-translational modification requirements. Lower regulatory complexity and faster development timelines attract mid-cap biopharmaceutical developers seeking cost-efficient manufacturing partnerships.
- Hormones:Insulin analogs and growth factors represent mature recombinant product categories with established microbial expression platforms. Price compression in diabetes and endocrine therapy segments limits margin expansion for contract manufacturers.
Monoclonal Antibodies holds installed capacity. Vaccines is rotating up the share rankings.
Technology:
Volume concentration across expression platforms reflects the trade-off between manufacturing complexity and product structural requirements.
- Recombinant DNA:Foundational genetic engineering techniques underpin all heterologous protein production regardless of host system. CRISPR-mediated gene editing and synthetic promoter libraries are advancing titers across bacterial, yeast, and mammalian platforms.
- Mammalian Cells:CHO and HEK293 systems command premium positioning for complex glycoproteins requiring human-compatible post-translational modifications. Basel-Zurich and Rhine-Main corridor facilities anchor European capacity for therapeutic antibody commercial supply.
- Bacterial Systems:E. coli and other prokaryotic hosts deliver rapid growth kinetics and high cell densities for simpler protein products. Lower capital intensity and faster batch turnaround attract contract manufacturing demand for enzyme and hormone production.
- Yeast Systems:Pichia pastoris and Saccharomyces cerevisiae bridge prokaryotic efficiency with eukaryotic secretion capabilities. Glyco-engineered yeast strains are expanding addressable product categories beyond traditional bacterial limitations.
Mammalian Cells holds installed capacity. Yeast Systems is rotating up the share rankings.
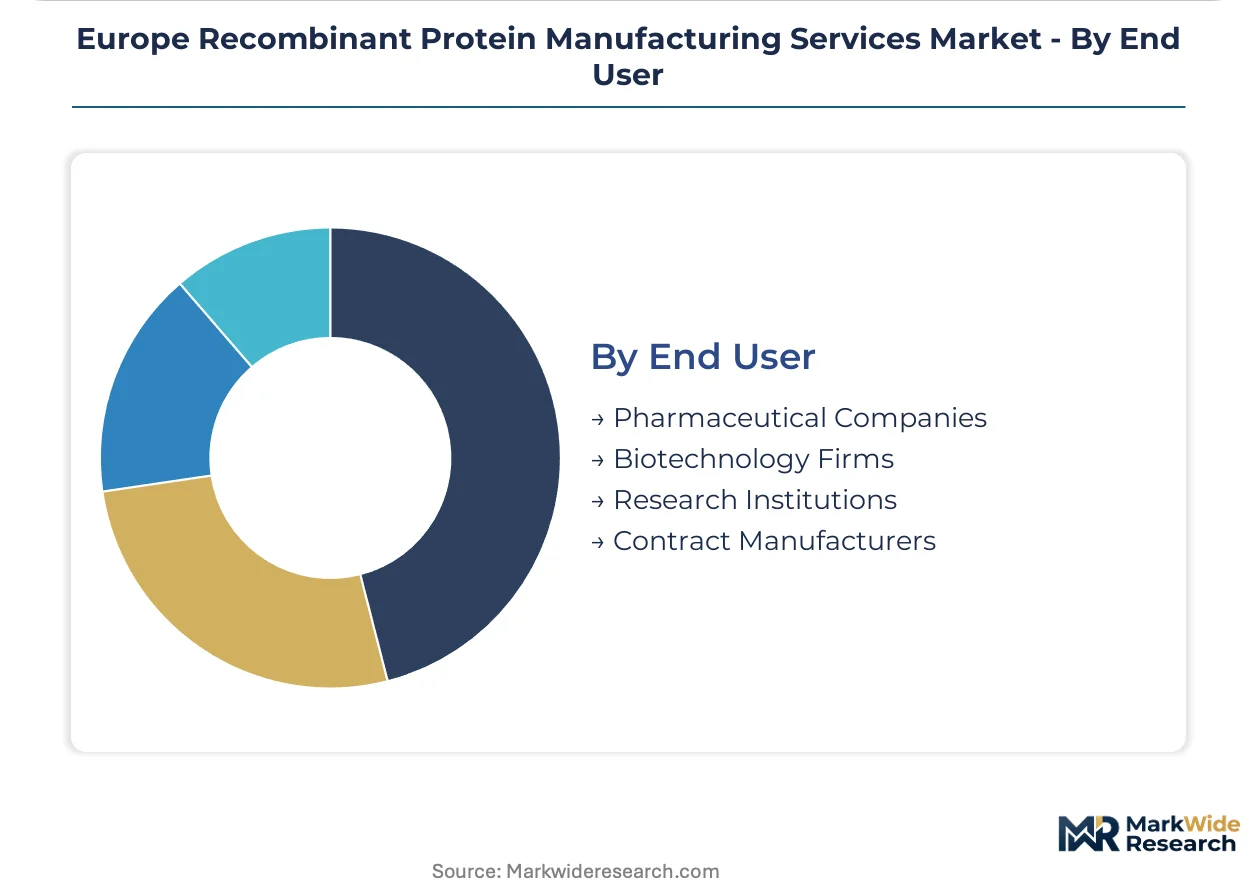
End User:
Customer type segmentation reveals divergent procurement patterns across integrated pharmaceutical organizations, venture-backed biotechs, academic translational programs, and manufacturing-specialist CDMOs.
- Pharmaceutical Companies:Large-cap developers with internal biologics capacity selectively outsource overflow demand and geographic supply diversification. German pharmaceutical headquarters are consolidating European manufacturing partnerships around full-service CDMOs with integrated regulatory capabilities.
- Biotechnology Firms:Venture-funded and mid-cap developers without captive manufacturing infrastructure represent the core growth constituency for contract services. Netherlands-based biotech clusters are abandoning fragmented supplier networks for single-source partnerships spanning development through commercial release.
- Research Institutions:Academic and government laboratories require small-scale protein production for mechanistic studies and early discovery validation. Lower volume thresholds and non-GMP specifications limit revenue contribution relative to therapeutic manufacturing segments.
- Contract Manufacturers:CDMO-to-CDMO subcontracting addresses capacity constraints and specialized capability gaps across the European network. Multi-product facility scheduling and technology transfer efficiency determine competitive positioning in this intermediary tier.
Pharmaceutical Companies holds installed capacity. Biotechnology Firms is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European recombinant protein manufacturing services generate substantial export value through contract supply to North American and Asian pharmaceutical sponsors, while importing specialized expression technologies and single-use equipment components from Swiss and German precision engineering clusters.
Germany
Boehringer Ingelheim International GmbH anchors mammalian cell culture capacity in the Rhine-Main corridor for monoclonal antibody production. EMA's tightened GMP Annex 1 standards are forcing facility-wide upgrades across Hesse and Bavaria manufacturing sites. The Heidelberg-Mannheim biotech cluster concentrates demand for high-titer CHO platform development services.
Switzerland
Lonza leverages its Swiss manufacturing footprint to anchor multi-product biologics campaigns for global pharmaceutical clients. Swissmedic maintains stringent biological manufacturing licensing requirements that exceed baseline EU standards. The Basel-Zurich corridor hosts Europe's densest concentration of mammalian cell culture capacity for therapeutic antibody commercial supply.
Netherlands
Biotechnology firms in the Leiden-Utrecht corridor are consolidating fragmented supplier networks into single-source partnerships spanning development through commercial release. REACH chemical registration requirements are accelerating aqueous buffer substitution in downstream purification processes. FUJIFILM Diosynth Biotechnologies competes on microbial and cell-based expression flexibility from its Dutch operational base.
United Kingdom
Post-Brexit regulatory divergence from EMA guidelines is creating parallel qualification requirements for UK biological manufacturing licenses. MHRA maintains independent GMP inspection schedules for sterile medicinal products. The Cambridge-London biotech corridor sustains demand for cell line development and analytical services despite reduced EU market access.
France
ANSM oversight of biological manufacturing is converging with EMA standards while retaining national pharmacovigilance requirements. The Paris-Saclay research cluster generates academic demand for small-scale recombinant protein production. Merck KGaA maintains European service capabilities that include French market access for contract manufacturing clients.
Europe Recombinant Protein Manufacturing Services Market Competitive Landscape
On the supply side, the industry is consolidating around full-service CDMOs with integrated analytical and regulatory capabilities, compressing margins for fragmented single-service providers. Three archetypes dominate: Swiss-German mammalian cell culture specialists with legacy stainless-steel infrastructure, modular single-use platform operators competing on campaign flexibility, and microbial expression generalists serving enzyme and hormone markets. Competitive moves center on continuous bioprocessing technology licensing and strategic partnerships for multi-product facility scheduling.
Within the Swiss-German infrastructure tier, Lonza and Boehringer Ingelheim International GmbH exemplify capacity concentration in the Basel-Zurich and Rhine-Main corridors. FUJIFILM Diosynth Biotechnologies occupies a position bridging microbial and mammalian expression flexibility across European sites. These three anchors represent divergent strategic postures: legacy scale dominance, hybrid platform versatility, and Asian-parented global network integration.
| Leading Market Players |
|---|
| Lonza |
| Boehringer Ingelheim International GmbH |
| FUJIFILM Diosynth Biotechnologies |
| Merck KGaA |
| Bruker |
| Sino Biological |
| GenScript |
| Kaneka Eurogentec S.A |
| Trenzyme GmbH |
| Others |
Value Network & Pricing Analysis
German precision engineering clusters for single-use bioreactor components and chromatography resins anchor upstream supply concentration, directing margin pools toward CDMOs with captive purification technology partnerships and multi-year equipment offtake agreements.
Pricing Analysis
Biotechnology firm buyers anchor project-based pricing structures for mammalian cell culture campaigns, with premium-mid-economy pricing differentiation driven by GMP certification tier and campaign volume scale. Pricing pressure stems from REACH chemical registration compliance costs transferring downstream to sponsors. Mid-cap developers in the Netherlands exhibit highest price sensitivity due to constrained venture funding cycles, while large-cap pharmaceutical partners prioritize regulatory track record over unit cost.
Supply Chain Analysis
Upstream cell culture media and single-use bioreactor bags draw from German, Swiss, and US precision manufacturing corridors. Raw material dependencies center on recombinant protein-free media formulations, chromatography resins, and sterile filtration membranes. Single-source vulnerability concentrates in Swiss-German isolator technology suppliers. Distribution runs through direct CDMO-sponsor partnerships with embedded quality agreements rather than spot market transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Plasma-derived protein fractionation infrastructure poses a persistent substitution threat that recombinant manufacturing incumbents must navigate through cost and glycosylation precision advantages.
For Market Incumbents: Harden facility compliance positions against EMA's evolving GMP Annex 1 standards through isolator line retrofits in Basel-Zurich and Rhine-Main corridors. Deepen backward integration into aqueous buffer supply chains to offset REACH-driven solvent cost inflation. Priority defensive lever rests on continuous bioprocessing technology licensing to collapse batch cycle times against emerging modular platform competitors. For New Entrants and Emerging Players: Build out Spanish and Italian CDMO capacity in Barcelona and Milan biotech parks where facility operating costs undercut Swiss-German benchmarks by substantial margins. Most penetrable white-space sits in microbial expression services for hormone and enzyme markets where regulatory complexity remains manageable. Go-to-market angle should emphasize single-source partnership models spanning cell line development through commercial release for mid-cap biotechnology developers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed CDMO platforms in the Netherlands and United Kingdom lacking integrated analytical capabilities. Long-term viability across the analysis window favors full-service operators with validated AI-driven bioprocess monitoring qualifying for EU AI Act regulatory fast-track pathways. Acquisition target archetype: mid-scale mammalian cell culture facilities with underutilized perfusion capacity. Signal to watch: EMA guidance publication timelines on complex generics comparability standards.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Bioprocessing Technology Licensing | Perfusion cell culture integration collapses batch timelines for high-titer antibody programs. |
| GMP Annex 1 Compliance Investment | Isolator-based aseptic processing upgrades secure EMA manufacturing licenses for biologicals. |
| Spanish-Italian Geographic Expansion | Lower facility operating costs in Barcelona and Milan attract multi-product campaign diversification. |
| AI-Driven Bioprocess Monitoring Deployment | Validated algorithmic control qualifies for EU AI Act regulatory fast-track differentiation. |
| Single-Source Partnership Consolidation | Integrated analytical and regulatory capabilities capture biotechnology firm outsourcing demand. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with cell culture facility directors, regulatory affairs leads at EMA-experienced CDMOs, biotechnology firm procurement officers, and bioprocess engineering specialists; and secondary validation through EMA biosimilar submission databases, EU GMP inspection records, REACH chemical registration filings, and Swissmedic licensing disclosures. Bottom-up capacity modeling and top-down revenue triangulation anchored market size estimates.
Forecast inputs considered service type segmentation across cell line development, protein expression, purification, and quality control tiers; technology platform splits between mammalian, bacterial, and yeast expression systems; and end-user differentiation between pharmaceutical companies and biotechnology firms. CAGRs derived from facility investment pipeline tracking and sponsor outsourcing intention surveys across the projection horizon. Industry-specific inputs included perfusion adoption rates and single-use platform penetration curves.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Asian-parented CDMO networks or accelerated plasma-derived protein substitution would shift outcomes. Cross-checking against EMA manufacturing license issuance rates and CDMO facility utilization disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Services
Cell Lysis and Dissociation Market
Biotechnology Services
Global Vector Control Market
Biotechnology Services
Industrial Microbiology Testing Services Market
Biotechnology Services
Global Bioprocess Validation Market
Biotechnology Services
Bio-Services Market
Biotechnology Services
Precast Agarose Gel Market
Biotechnology Services
Research Antibodies and Reagents Market
Biotechnology Services
Biobanking Market
Biotechnology Services
GMO Testing Services Market
Biotechnology Services
Cell Culture Media Market
Biotechnology Services
Marine Polysaccharides Fucoidan Alginate Market
Biotechnology Services
Cell Lysis and Disruption Market
Biotechnology Services
Plasma Feed Market
Biotechnology Services
Biologics CDMO Market
Biotechnology Services
Immunoassays in R & D Market
Biotechnology Services
Recombinant Factor C Assay Market