
 Global Molecular Biology Enzymes and Kits and Reagents Market | 2026-2036
Global Molecular Biology Enzymes and Kits and Reagents Market Size, Share, and Industry Trends Forecast 2026-2036
Global Molecular Biology Enzymes and Kits and Reagents Market Foresight
The capability gap between integrated platform providers and specialized reagent suppliers is unwinding competitive dynamics across the sector. Thermo Fisher Scientific leverages its end-to-end workflow portfolio to anchor large-scale sequencing operations. New England Biolabs specializes in enzyme engineering for high-fidelity applications, sustaining premium positioning in research-intensive segments. QIAGEN competes through sample-to-insight automation, controlling distribution in clinical and academic channels.
Molecular biology enzymes, kits, and reagents comprise purified biocatalysts and pre-formulated consumables designed for nucleic acid manipulation, amplification, and analysis, typically requiring activity specifications measured in units per milligram and storage at minus twenty degrees Celsius to preserve functional integrity. These products enable DNA replication, RNA transcription, and gene editing workflows across life science research, diagnostic testing, and therapeutic manufacturing. Polymerases command the largest product type volume due to their centrality in PCR and next-generation sequencing protocols, while RNA isolation kits represent the fastest-expanding kit type segment driven by transcriptomics and mRNA therapeutics demand. Academic research centers and pharmaceutical R&D together occupy the dominant end-user positions, though diagnostic laboratories are capturing expanding share as molecular testing standardizes in clinical settings.
FDA oversight of in vitro diagnostic reagents and EPA guidelines for genetically modified organism research shape product validation requirements and facility compliance costs in the United States, while EMA's In Vitro Diagnostic Regulation and REACH chemical safety standards govern market access across European Union member states. China's NMPA and national GB standards impose additional testing and registration burdens for imported enzyme formulations. Stakeholders must monitor regulatory convergence between clinical diagnostic and research-use-only classifications, as this boundary shift will determine which product categories require expanded quality management investments and which channels face restricted access.
Market Dynamics
CRISPR-based gene editing workflows are forcing polymerase specifications toward high-fidelity variants, compressing margins for standard Taq suppliers while rewarding enzyme engineering specialists with premium positioning in biologics development pipelines.
Growth Catalysts
- mRNA therapeutics manufacturing:Commercial-scale production of modified RNA vaccines requires specialized reverse transcriptases and capping enzymes, creating sustained procurement pull from contract development organizations.
- China's genomic medicine infrastructure:NMPA streamlined registration pathways for imported research-use reagents, accelerating kit adoption in Shanghai and Beijing academic medical centers.
- REACH chemical safety standards:European Union enforcement of substance registration for enzyme formulations drives consolidation toward suppliers with compliant manufacturing, favoring established distributors with ECHA documentation capabilities.
Market Restraints
- Lyophilized enzyme input volatility:Purified protein feedstock costs fluctuate with fermentation capacity constraints in contract manufacturing organizations, squeezing gross margins for kit assemblers without captive enzyme production.
- Supply concentration in Massachusetts and California:Over sixty percent of high-fidelity polymerase manufacturing clusters in two US states creates geographic risk exposure from state-level environmental enforcement or logistics disruption.
- Sample integrity limitations:Ambient-temperature stabilization chemistry remains inadequate for field-deployed nucleic acid collection, restricting point-of-care diagnostic kit penetration in resource-limited settings.
Strategic Opportunities
- India's biotech manufacturing zones:BIS certification harmonization with ISO 13485 opens pathways for reagent kit localization in Genome Valley and Bengaluru clusters, reducing import duty exposure.
- Digital PCR workflow convergence:Integration of microfluidic partitioning with absolute quantification creates white space for enzyme kits optimized for low-copy detection in liquid biopsy applications.
- Japan's PMDA regenerative medicine framework:Accelerated approval pathways for cell therapy manufacturing reagents incentivize GMP-grade enzyme qualification investments for Japanese market entry.
Industry Challenges
- CRISPR guide RNA synthesis expertise:Shortage of chemists with phosphoramidite oligonucleotide manufacturing experience constrains expansion of gene editing kit production lines.
- ISO 13485 certification timelines:Eighteen-to-twenty-four month quality management system implementation periods delay research-use product transitions to in vitro diagnostic classifications.
- Cross-border cold chain integrity:Minus-eighty-degree shipping requirements for certain high-activity enzyme formulations generate customs clearance friction and temperature excursion disputes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Molecular Biology Enzymes and Kits and Reagents Market |
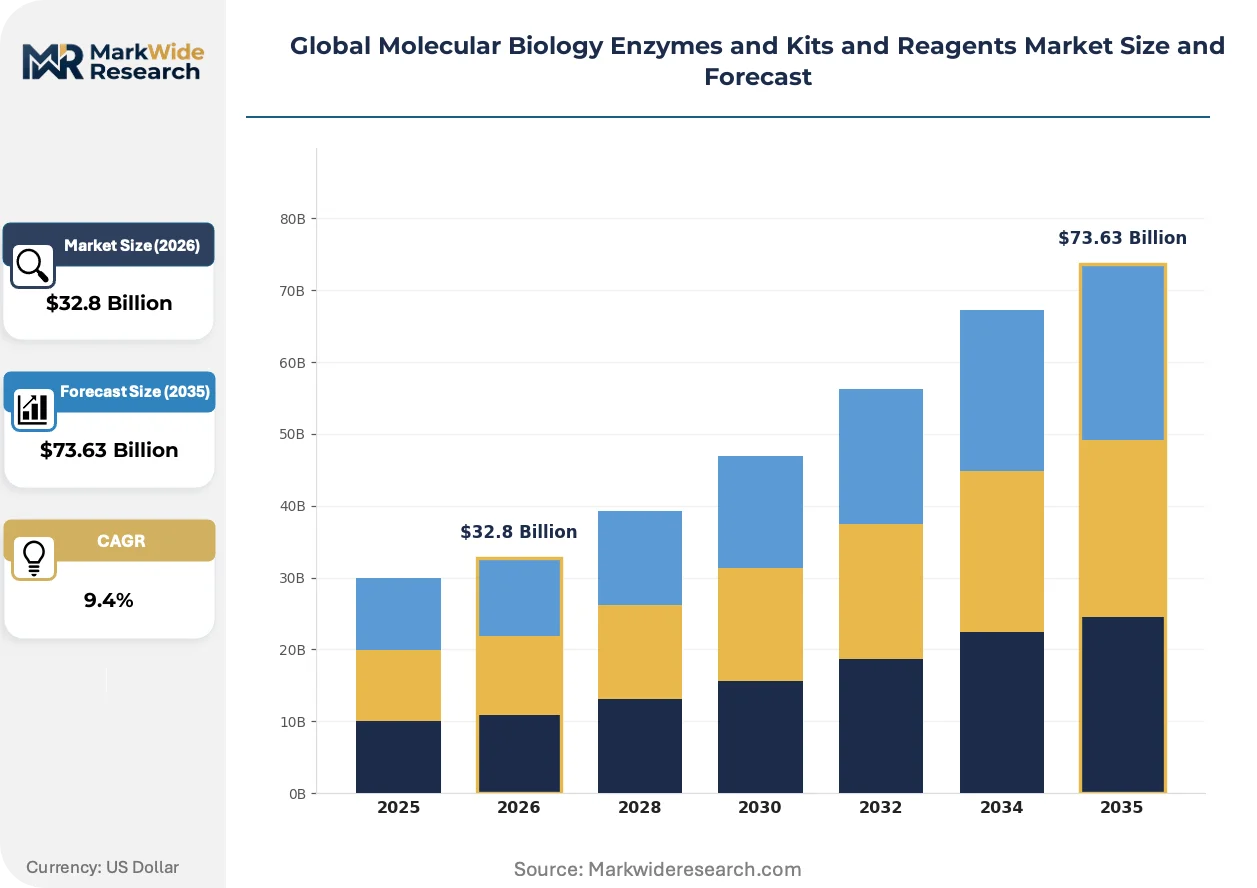
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $73.63 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymerases, Ligases, Restriction Enzymes, Nucleases, Reverse Transcriptases, Transferases Application: Cloning, Sequencing, Gene Expression Analysis, Genotyping, PCR, DNA Repair End User: Biotechnology Laboratories, Pharmaceutical R&D, Academic Research Centers, Diagnostic Laboratories, Government Agencies, Forensic Labs Kit Type: DNA Extraction Kits, RNA Isolation Kits, PCR Kits, Gel Electrophoresis Kits, cDNA Synthesis Kits, Labeling Kits |
| Companies Covered | Thermo Fisher Scientific, Agilent Technologies, Merck KGaA, QIAGEN, Illumina, F. Hoffmann-La Roche, Promega Corporation, New England Biolabs, Bio-Rad Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Molecular Biology Enzymes and Kits and Reagents Market Shifts & Advancements
Enzyme engineering platforms are fragmenting traditional polymerase categories into application-specific variants, while regulatory boundaries between research and clinical use reagents shift quality management requirements across supplier portfolios.
High-fidelity polymerase engineering is fragmenting the historical dominance of Taq-based amplification. CRISPR-mediated base editing workflows in pharmaceutical R&D laboratories now specify error rates below one mutation per million bases. This specification tier rewards suppliers with directed evolution capabilities while compressing demand for standard PCR enzymes in gene therapy process development.
EMA's In Vitro Diagnostic Regulation reclassification timeline is compressing research-use-only kit distribution channels. Manufacturers must now maintain dual quality systems for CE-IVD and RUO product streams. Diagnostic laboratories in Germany and France are accelerating procurement from suppliers with established notified body relationships, displacing academic-channel distributors without certification infrastructure.
Consolidated procurement through group purchasing organizations is concentrating buying power among large health systems and pharmaceutical consolidators. Smaller research institutions now access reagents through shared service centers rather than direct supplier relationships. This channel shift is most visible in United States academic medical centers, where centralized biorepositories negotiate master service agreements spanning enzymes, kits, and nucleic acid extraction automation.
Global Molecular Biology Enzymes and Kits and Reagents Market Segmentation
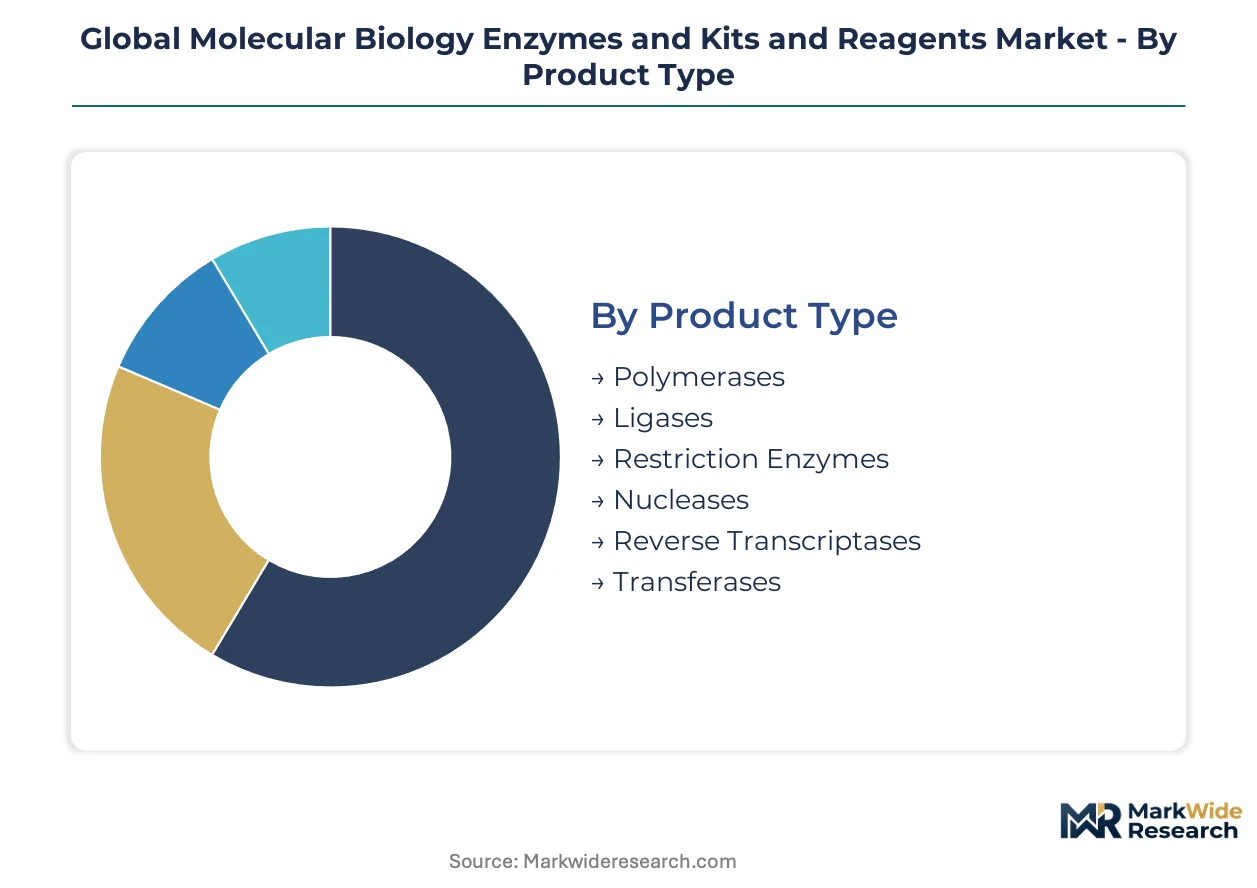
Product differentiation in molecular biology reagents hinges on thermal stability, fidelity specifications, and workflow integration depth. Segmentation reveals where enzyme engineering investments concentrate versus where commoditization pressures dominate.
Product Type:
Polymerases face the most acute substitution pressure as engineered high-fidelity variants displace standard Taq formulations in pharmaceutical process development.
- Polymerases:These DNA-synthesizing enzymes dominate PCR and next-generation sequencing protocols. Thermostable variants with error rates below one per million bases command premium positioning in CRISPR workflows across United States and German biologics facilities.
- Ligases:Enzymes catalyzing phosphodiester bond formation enable cloning and repair applications. Demand concentrates in contract manufacturing organizations producing plasmid DNA for mRNA therapeutics, where T4 DNA ligase specifications anchor quality agreements.
- Restriction Enzymes:Sequence-specific DNA cutters remain essential for traditional cloning workflows despite CRISPR displacement in gene editing.
- Nucleases:Nonspecific and targeted nucleic acid degraders support sample preparation and quality control steps.
- Reverse Transcriptases:RNA-dependent DNA polymerases enable cDNA synthesis for transcriptomics and viral detection protocols.
- Transferases:Enzymes modifying nucleic acid termini support labeling and modification workflows in research settings.
Polymerases anchor the volume base while high-fidelity engineered variants gain share at the steepest rate.
Application:
Cost tier stratification separates clinical diagnostic applications requiring ISO 13485 certification from research-use workflows with lower compliance burdens.
- Cloning:Traditional recombinant DNA workflows maintain steady demand in academic settings. Chinese and Indian contract research organizations drive procurement of restriction enzyme and ligase combinations for plasmid construction.
- Sequencing:Next-generation sequencing library preparation consumes specialized polymerases and adapter ligation kits. United States genomic medicine centers in Boston and San Francisco represent concentrated demand nodes for high-throughput compatible formulations.
- Gene Expression Analysis:Quantitative PCR and RNA-seq workflows require reverse transcriptases with reduced RNase H activity.
- Genotyping:SNP detection and forensic identification applications specify thermostable enzymes for thermal cycling robustness.
- PCR:Amplification workflows span endpoint, real-time, and digital variants with diverging enzyme fidelity requirements.
- DNA Repair:Enzymatic restoration of damaged nucleic acids supports aging research and synthetic biology applications.
Sequencing applications command the highest per-reaction value while PCR workflows maintain the broadest installed base across customer types.
End User:
Customer type determines procurement channel structure, with consolidated buying power concentrating in pharmaceutical consolidators versus fragmented academic purchasing.
- Biotechnology Laboratories:Cell therapy and gene editing developers in Cambridge, Massachusetts and South San Francisco procure GMP-grade enzymes under long-term supply agreements. These facilities specify lot-to-lot consistency metrics exceeding research-grade standards.
- Pharmaceutical R&D:Large molecule development groups in Basel, Switzerland and Shanghai integrate high-fidelity polymerases into biologics process analytical technology. Regulatory filing requirements drive documentation depth for enzyme suppliers.
- Academic Research Centers:University core facilities negotiate multi-investigator pricing for standard molecular biology workflows.
- Diagnostic Laboratories:Clinical testing facilities face IVDR compliance deadlines in European Union markets.
- Government Agencies:Public health and environmental monitoring programs specify ambient-temperature stable formulations for field deployment.
- Forensic Labs:Criminal justice system requirements drive chain-of-custody documentation and validated protocol adherence.
Pharmaceutical R&D anchors premium pricing while diagnostic laboratories represent the fastest-expanding certified product demand.
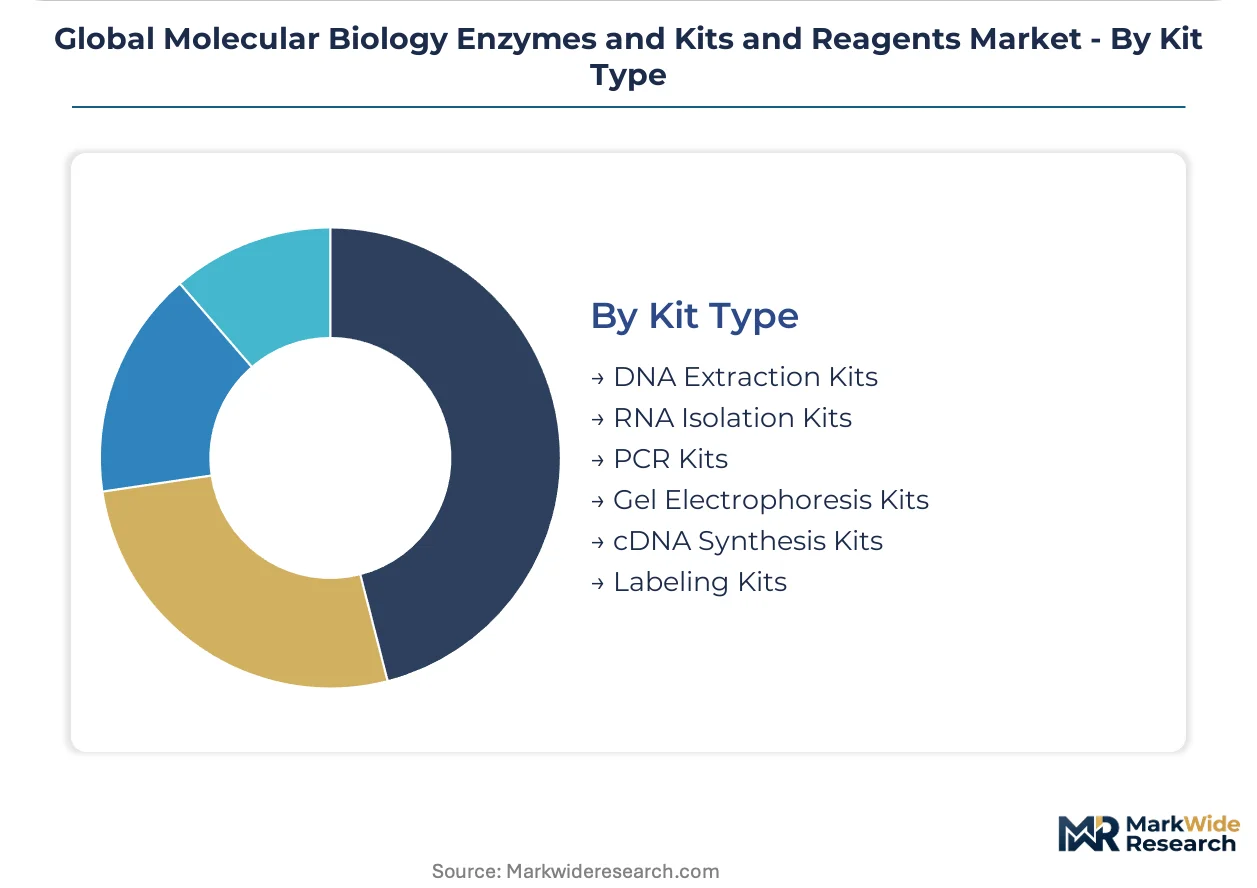
Kit Type:
Supply concentration in Massachusetts and California manufacturing clusters shapes kit availability for ambient-temperature versus cold-chain dependent formulations.
- RNA Isolation Kits:Transcriptomics and mRNA therapeutics manufacturing drive steep demand expansion. These kits incorporate chaotropic salts and silica membrane technologies optimized for biofluid input types, with Shanghai and Beijing academic medical centers accelerating adoption under streamlined NMPA registration.
- DNA Extraction Kits:Genomic DNA purification supports sequencing and genotyping workflows across research and clinical settings. United States reference laboratories specify high-molecular-weight DNA recovery for long-read sequencing platforms.
- PCR Kits:Pre-formulated master mixes reduce setup variability in high-throughput environments.
- Gel Electrophoresis Kits:Nucleic acid separation consumables maintain steady replacement demand in educational and research settings.
- cDNA Synthesis Kits:Reverse transcription workflows integrate oligo(dT) and random primer strategies for transcriptome coverage.
- Labeling Kits:Fluorescent and hapten modification reagents enable detection in hybridization and imaging applications.
DNA extraction kits anchor the revenue base while RNA isolation kits climb the fastest as mRNA therapeutics manufacturing scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across geographies. Academic buyers in India and China negotiate aggressively on standard PCR reagents, while pharmaceutical R&D groups in the United States and Switzerland absorb premium pricing for GMP-grade enzymes without volume reduction.
United States
FDA oversight of in vitro diagnostic reagents shapes validation requirements for clinical-grade kits. Boston and San Francisco anchor concentrated demand for high-throughput sequencing formulations. Massachusetts and California manufacturing clusters supply over sixty percent of high-fidelity polymerase production.
Germany
EMA's In Vitro Diagnostic Regulation compresses research-use-only distribution channels. REACH chemical safety standards drive consolidation toward ECHA-compliant suppliers. Academic medical centers in Munich and Heidelberg accelerate procurement from notified body-certified distributors.
China
NMPA streamlined registration pathways for imported research-use reagents. Shanghai and Beijing academic medical centers drive RNA isolation kit adoption. Genomic medicine infrastructure expansion concentrates procurement in Yangtze River Delta biotech zones.
Japan
PMDA's regenerative medicine framework accelerates approval pathways for cell therapy manufacturing reagents. Tokyo and Osaka therapeutic developers specify GMP-grade enzyme qualifications. METI incentives support localization investments for imported formulations.
India
BIS certification harmonization with ISO 13485 opens reagent kit localization pathways. Genome Valley and Bengaluru clusters reduce import duty exposure for domestic assemblers. Contract research organizations drive procurement of restriction enzyme and ligase combinations.
Global Molecular Biology Enzymes and Kits and Reagents Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating tiered competitive dynamics. Integrated platform providers anchor large-scale sequencing operations through end-to-end workflow portfolios. Specialized enzyme engineering firms sustain premium positioning in research-intensive segments. Sample-to-insight automation specialists control distribution in clinical and academic channels. Competitive moves concentrate on strategic partnerships for workflow integration and geographic expansion through regulatory certification investments.
Within the integrated platform tier, Thermo Fisher Scientific represents scale-driven consolidation. Among enzyme engineering specialists, New England Biolabs exemplifies premium positioning through fidelity specifications. On the sample-to-insight automation vector, QIAGEN occupies a position controlling clinical channel access. These three anchors illustrate how capability differentiation fragments procurement decisions across customer types.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Agilent Technologies |
| Merck KGaA |
| QIAGEN |
| Illumina |
| F. Hoffmann-La Roche |
| Promega Corporation |
| New England Biolabs |
| Bio-Rad Laboratories |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements for GMP-grade enzymes lock in supply access and price visibility for pharmaceutical R&D groups in Basel and Cambridge, insulating premium tiers from spot-market volatility in standard PCR reagents while compressing margins for non-contracted suppliers.
Pricing Analysis
After-sales revenue from technical support contracts and lot-to-lot consistency guarantees drives lifetime value for enzyme suppliers. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume scale. Pricing pressure stems from academic buyers in India and China negotiating aggressively on standard Taq formulations. Diagnostic laboratories in Germany and France absorb premium pricing for CE-IVD certified kits without volume reduction.
Supply Chain Analysis
Inventory lead times for high-activity enzyme formulations stretch due to minus-eighty-degree shipping requirements and customs clearance friction. Manufacturing concentrates in Massachusetts, California, and Germany. Purified protein feedstock draws from fermentation capacity in contract manufacturing organizations. Single-source vulnerability in phosphoramidite oligonucleotide synthesis constrains guide RNA kit expansion. Distribution runs through group purchasing organizations and shared service centers at United States academic medical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is in cyclical recovery driven by mRNA therapeutics manufacturing scale-up, which creates sustained procurement pull reversing prior R&D budget contraction.
For Market Incumbents: Fortify enzyme engineering capabilities through directed evolution platform investments to defend against CRISPR workflow displacement of standard polymerases. Deepen backward integration into captive fermentation capacity to offset purified protein feedstock cost volatility. Prioritize ISO 13485 certification infrastructure to capture diagnostic laboratory channel consolidation in European Union markets.
For New Entrants and Emerging Players: BIS certification fast-track harmonization with ISO 13485 opens reagent kit localization pathways in Genome Valley and Bengaluru clusters. Target India's contract research organizations for restriction enzyme and ligase combinations where import duty exposure disadvantages foreign suppliers. Pursue digital PCR workflow convergence for low-copy detection in liquid biopsy applications as the most penetrable white space.
For Investors and Strategic Acquirers: Capital is best deployed toward enzyme engineering specialists with fidelity specifications below one mutation per million bases, as these capabilities concentrate pricing power across the analysis window. Monitor NMPA registration pathway streamlining for imported research-use reagents as the signal indicating inflection in China genomic medicine infrastructure investment.
| Strategic Initiative | Industry Significance |
|---|---|
| GMP-Grade Enzyme Qualification | PMDA regenerative medicine framework accelerates approval for cell therapy manufacturing reagents in Japan. |
| High-Fidelity Polymerase Engineering | CRISPR base editing workflows in pharmaceutical R&D specify error rates below one per million bases. |
| Sample-to-Insight Automation | QIAGEN controls clinical and academic channel distribution through integrated nucleic acid extraction platforms. |
| RNA Isolation Kit Localization | NMPA streamlined registration accelerates adoption in Shanghai and Beijing academic medical centers. |
| Digital PCR Workflow Integration | Microfluidic partitioning with absolute quantification creates white space for low-copy detection enzyme kits. |
Research Methodology
The analysis maps polymerase engineering platforms, kit type specifications, and end-user procurement channels, each validated through laboratory directors, pharmaceutical process development leads, diagnostic procurement managers, and regulatory affairs specialists at notified bodies. Primary interviews with these stakeholders combined with secondary validation from FDA 510(k) filings, EMA IVDR technical documentation, NMPA registration databases, and United States customs import records. Bottom-up enzyme unit demand estimates and top-down market value triangulation cross-checked for consistency.
Consistency checks against external benchmarks validated volume and value outputs across the modeling period. Segmentation dimensions modeled include product type fidelity tiers, application certification requirements, end-user procurement consolidation levels, and geographic regulatory cluster. CAGRs derived from normalized growth trajectory fitting to historical procurement patterns and forward pipeline visibility. Industry-specific forecast inputs incorporated mRNA therapeutics manufacturing scale projections and CRISPR workflow adoption curves.
Decision-makers should treat outputs as directional under base assumptions of sustained pharmaceutical R&D expenditure and regulatory pathway stability; material deviation in biologics development funding or IVDR enforcement intensity would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Services
Polymerase Chain Reaction Reagent Market
Biotechnology Services
Global Downstream Processing Market
Biotechnology Services
Proteinase K Market
Biotechnology Services
Biotechnology and Pharmaceutical Services Outsourcing Market
Biotechnology Services
Mirna Tools and Services Market
Biotechnology Services
Biotech API Manufacturing Services Market
Biotechnology Services
Antibody Purification Service Market
Biotechnology Services
Biobanking Market
Biotechnology Services
Serine Protease Market
Biotechnology Services
Dnases, Ligases, and RNA Polymerases Market
Biotechnology Services
Research Antibodies and Reagents Market
Biotechnology Services
US Digital PCR Market
Biotechnology Services
UK Biotechnology and Pharmaceutical Services Outsourcing Market
Biotechnology Services
Biomarker Research Services Market
Biotechnology Services
Global Culture Media Market
Biotechnology Services
Transport Protein Assays Kits Market