
 UK Biotechnology and Pharmaceutical Services Outsourcing Market | 2026-2036
UK Biotechnology and Pharmaceutical Services Outsourcing Market Size, Share, and Industry Trends Forecast 2026-2036
UK Biotechnology and Pharmaceutical Services Outsourcing Market Intelligence
Regulatory consulting as a subscription-layer service is shifting how sponsors procure outsourcing partners across the UK life sciences sector. IQVIA Holdings Inc leverages its integrated data infrastructure to anchor large-scale real-world evidence programs for NHS-affiliated trials. Charles River Laboratories International Inc specializes in preclinical biologics testing from its Scottish facilities, competing with emerging domestic CROs on specialized toxicology capacity. Icon PLC dominates decentralized clinical trial execution, extending remote monitoring capabilities that reduce site dependency for UK biotech sponsors.
UK biotechnology and pharmaceutical services outsourcing encompasses contracted research, development, manufacturing, and regulatory support functions performed by third-party specialists on behalf of originator companies. These services integrate Good Manufacturing Practice compliance, quality assurance protocols, and pharmacovigilance reporting to accelerate therapeutic commercialization while maintaining MHRA and EMA-aligned standards. Clinical trial management commands the largest service-type revenue pool due to sustained NHS investigator-site demand and adaptive protocol complexity. Pharmacovigilance represents the fastest-expanding segment as the MHRA's strengthened post-market surveillance requirements expand mandatory safety reporting obligations. Hybrid delivery models are capturing margin concentration by blending onshore regulatory expertise with offshore data processing cost structures.
The Medicines and Healthcare products Regulatory Agency governs clinical trial authorizations and marketing approval standards, while the Human Medicines Regulations 2012 framework shapes pharmacovigilance and good distribution practice obligations for all UK-based service providers. MHRA recognition agreements with FDA and Health Canada create dual-access pathways that attract international sponsors to British CRO infrastructure. Stakeholders must monitor evolving UK-EU regulatory divergence on gene therapy classifications and advanced therapy medicinal products to preserve competitive positioning in cross-border trial execution.
Market Dynamics
MHRA's post-Brexit regulatory autonomy is fragmenting approval pathways for advanced therapy medicinal products, forcing sponsors to duplicate dossier preparation for UK and EU market access. This divergence is concentrating demand on CROs with dual-jurisdiction expertise while compressing margins for single-market specialists.
Growth Catalysts
- Human Medicines Regulations 2012:The strengthened pharmacovigilance mandates expand mandatory safety reporting obligations, creating recurring revenue streams for specialist service providers.
- Gene therapy manufacturing:Viral vector production capacity constraints in England are attracting CDMO investment into Scottish bioprocessing clusters.
- Oxford-Cambridge-London corridor:Specialist CRO concentration in this golden triangle accelerates early-phase trial startup timelines through investigator-site density.
Market Restraints
- Skilled toxicologist scarcity:Preclinical biologics testing capacity in Scotland faces bottlenecks from limited GLP-certified pathologist availability.
- EU-UK regulatory divergence:Divergent classification standards for cell therapies force parallel quality system maintenance, inflating compliance overhead.
- Specialized cold-chain logistics:Temperature-controlled distribution for biologics concentrates among three national courier networks, creating single-source vulnerability.
Strategic Opportunities
- NHS real-world evidence integration:Electronic health record linkage capabilities create differentiated positioning for data-analytics-enabled CROs.
- Northern England biomanufacturing:Underutilized pharmaceutical production infrastructure in Yorkshire offers cost-advantaged fill-finish capacity.
- Decentralized trial platforms:Remote monitoring technology convergence with direct-to-patient logistics opens investigator-site-independent execution models.
Industry Challenges
- Clinical data scientist recruitment:Adaptive trial design complexity outpaces supply of biostatisticians proficient in Bayesian protocol amendment.
- Legacy quality management system migration:MHRA's updated GMP Annex 11 requirements force validated software replacement timelines that disrupt operational continuity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Biotechnology and Pharmaceutical Services Outsourcing Market |
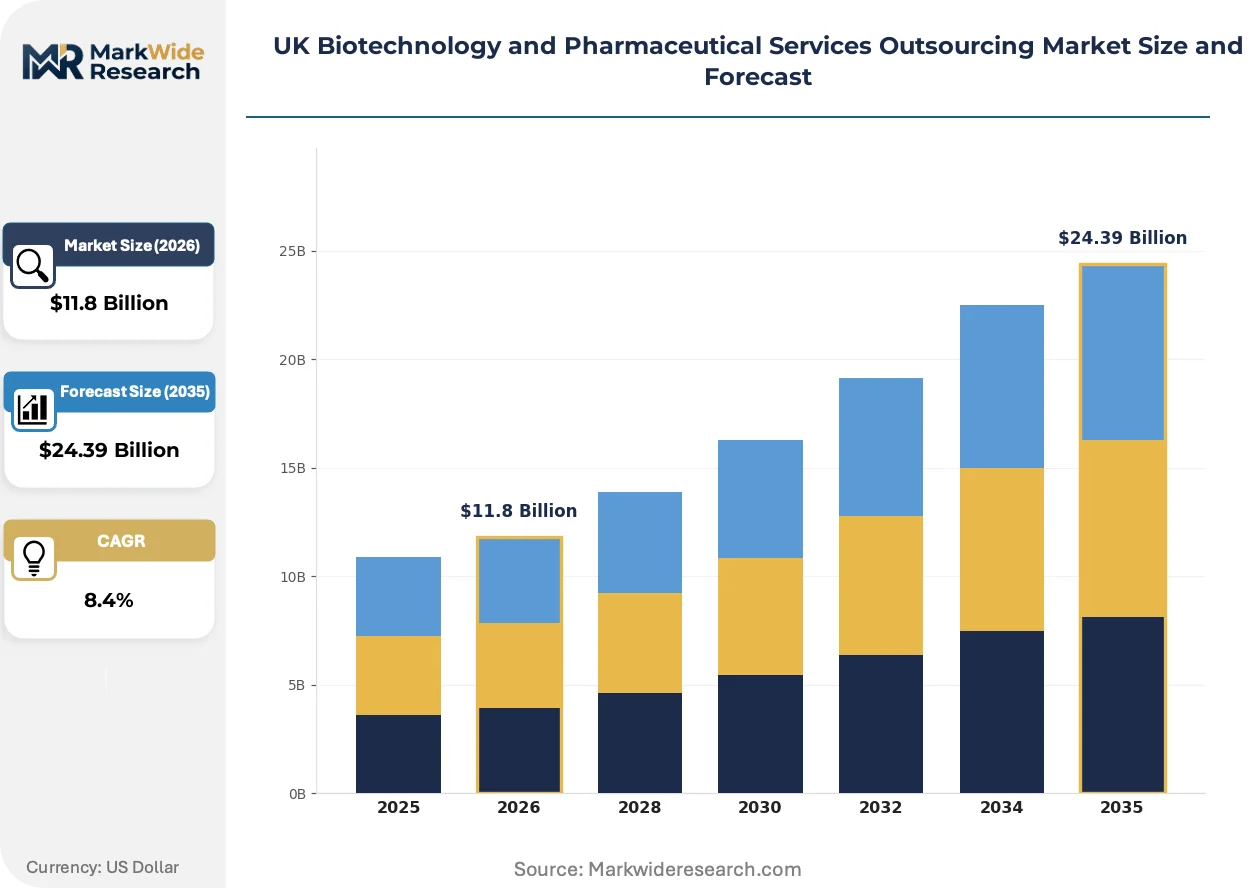
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $24.39 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Clinical Trial Management, Drug Development, Regulatory Affairs, Pharmacovigilance Client Type: Pharmaceutical Companies, Biotech Firms, Research Institutions, Contract Manufacturers Delivery Model: Onshore Services, Offshore Services, Hybrid Solutions, Remote Support Application: Drug Discovery, Biologics Development, Preclinical Studies, Market Access |
| Companies Covered | IQVIA Holdings Inc, PAREXEL International Corporation, Charles River Laboratories International Inc, Icon PLC, The Quantic Group, Concept Heidelberg GmbH, Lachman Consultant Services, GMP Pharmaceuticals, Quality Context Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Biotechnology and Pharmaceutical Services Outsourcing Market Strategic Shifts & Innovations
Platform standardization across preclinical and clinical service modules is compressing sponsor procurement cycles from multi-year partnerships to project-based engagements. This modularity is redistributing margin capture from full-service integrators to specialized point-solution vendors.
Artificial intelligence-enabled patient recruitment is modularizing site selection and feasibility assessment workflows. Mid-cap biotech sponsors in the Oxford-Cambridge corridor are adopting these tools at accelerated pace, collapsing traditional six-month startup timelines into eight-week execution windows. The technology is modularizing CRO value chains by separating data-layer services from physical-site management.
The MHRA's recognition agreements with FDA and Health Canada are creating dual-access regulatory pathways for international sponsors. This framework positions British CRO infrastructure as a bridgehead for simultaneous UK-North American market entry, particularly affecting gene therapy developers seeking streamlined multi-jurisdiction approval. Scottish preclinical facilities are capturing expanded toxicology study volume from US sponsors leveraging these agreements.
Subscription-layer regulatory consulting is displacing traditional project-based advisory engagements. Biotech sponsors in England are procuring ongoing MHRA liaison services through annual retainers rather than discrete submission support contracts. This shift concentrates relationship value with CROs embedding former agency reviewers, visible most acutely among virtual pharmaceutical companies lacking in-house regulatory affairs capacity.
UK Biotechnology and Pharmaceutical Services Outsourcing Market Segmentation
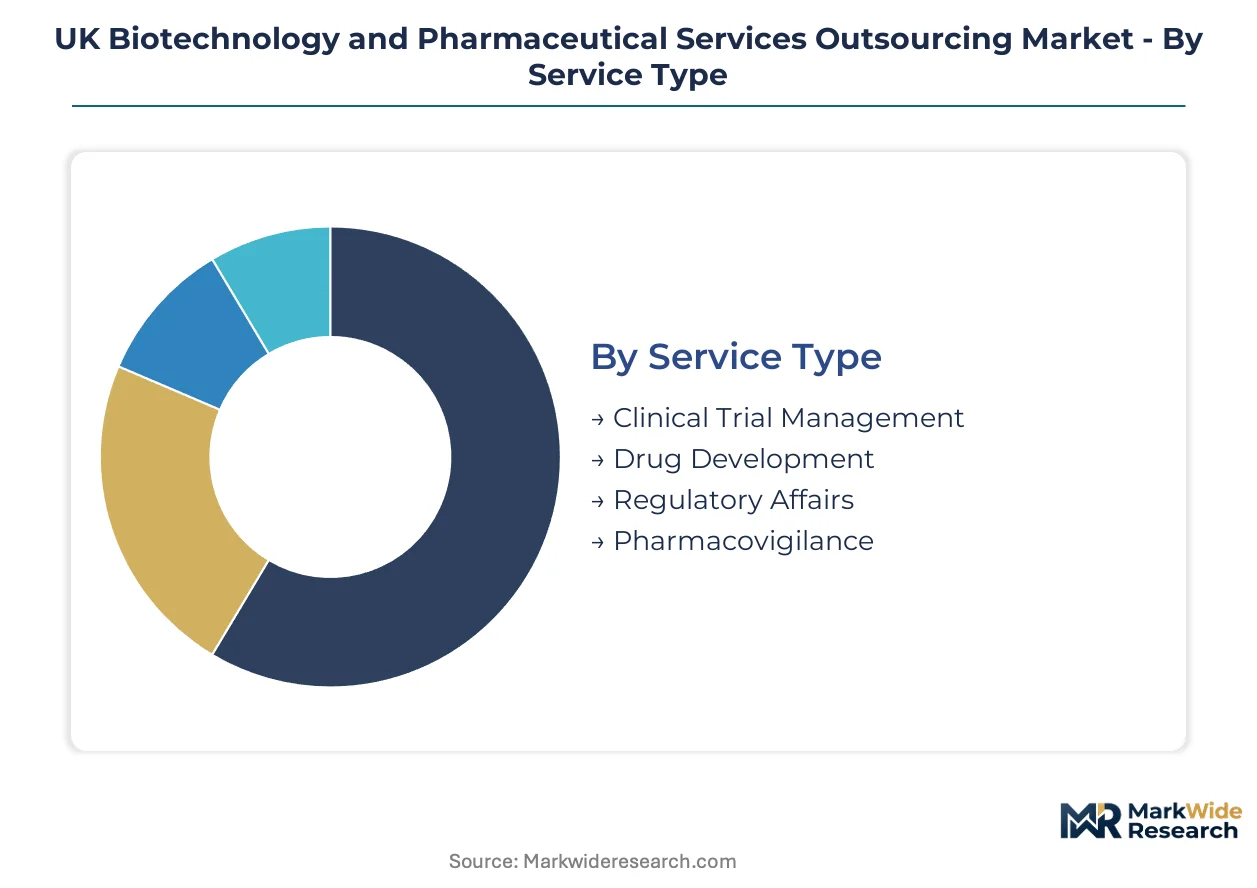
Service procurement patterns in the UK biotechnology and pharmaceutical services outsourcing market diverge sharply between volume-driven clinical operations and premium-priced regulatory advisory. Sponsors segment vendor selection by therapeutic complexity, geographic compliance requirements, and data infrastructure maturity rather than cost alone.
Service Type:
Volume concentration sits with established trial execution functions, while premium capture belongs to specialized safety and regulatory layers.
- Clinical Trial Management:Protocol design, site activation, and patient recruitment coordination across NHS-affiliated investigator networks. Demand concentrates in the Oxford-Cambridge-London corridor where site density accelerates startup timelines, though adaptive trial complexity is stretching biostatistician capacity.
- Drug Development:Preclinical through Phase III formulation, analytical testing, and manufacturing process development. Scottish facilities are capturing expanded toxicology study volume from North American sponsors leveraging MHRA-FDA recognition agreements.
- Regulatory Affairs:MHRA submission preparation, scientific advice coordination, and post-approval lifecycle management.
- Pharmacovigilance:Signal detection, periodic safety reporting, and risk management plan execution under strengthened Human Medicines Regulations 2012 mandates.
Mature deployment sits with Clinical Trial Management. Newer deployment is concentrated in Pharmacovigilance.
Client Type:
Customer sophistication tiers separate integrated pharmaceutical sponsors from capital-constrained biotech developers.
- Pharmaceutical Companies:Large-cap originators with in-house clinical operations seeking functional supplementation for geographic expansion or therapeutic diversification. Procurement emphasizes vendor consolidation and quality system harmonization across multiple UK sites.
- Biotech Firms:Venture-backed and publicly traded developers lacking full-service infrastructure, particularly prevalent in the golden triangle cluster. These sponsors are driving adoption of subscription-layer regulatory consulting and decentralized trial platforms.
- Research Institutions:University-affiliated translational centers and NHS trusts conducting investigator-initiated studies.
- Contract Manufacturers:CDMOs subcontracting specialized analytical or regulatory functions to maintain GMP compliance without captive capability.
Established procurement frameworks dominate Pharmaceutical Companies. Emerging demand patterns are reshaping Biotech Firms.
Delivery Model:
Geographic configuration of service delivery is fragmenting between regulatory proximity requirements and data processing cost arbitrage.
- Onshore Services:Full UK-based execution with MHRA-facing personnel and physical site management. Premium pricing reflects regulatory liaison expertise and investigator relationship maintenance, particularly critical for gene therapy submissions.
- Offshore Services:Data management, biostatistics, and pharmacovigilance case processing relocated to lower-cost jurisdictions. Margin compression in standard functions is accelerating this migration.
- Hybrid Solutions:Blended models combining UK-based regulatory strategy with offshore operational execution. These configurations are capturing margin concentration by preserving client-facing expertise while reducing back-office costs.
- Remote Support:Technology-enabled decentralized trial execution with direct-to-patient logistics and virtual monitoring.
Traditional deployment persists in Onshore Services. Fastest share gains are occurring in Hybrid Solutions.
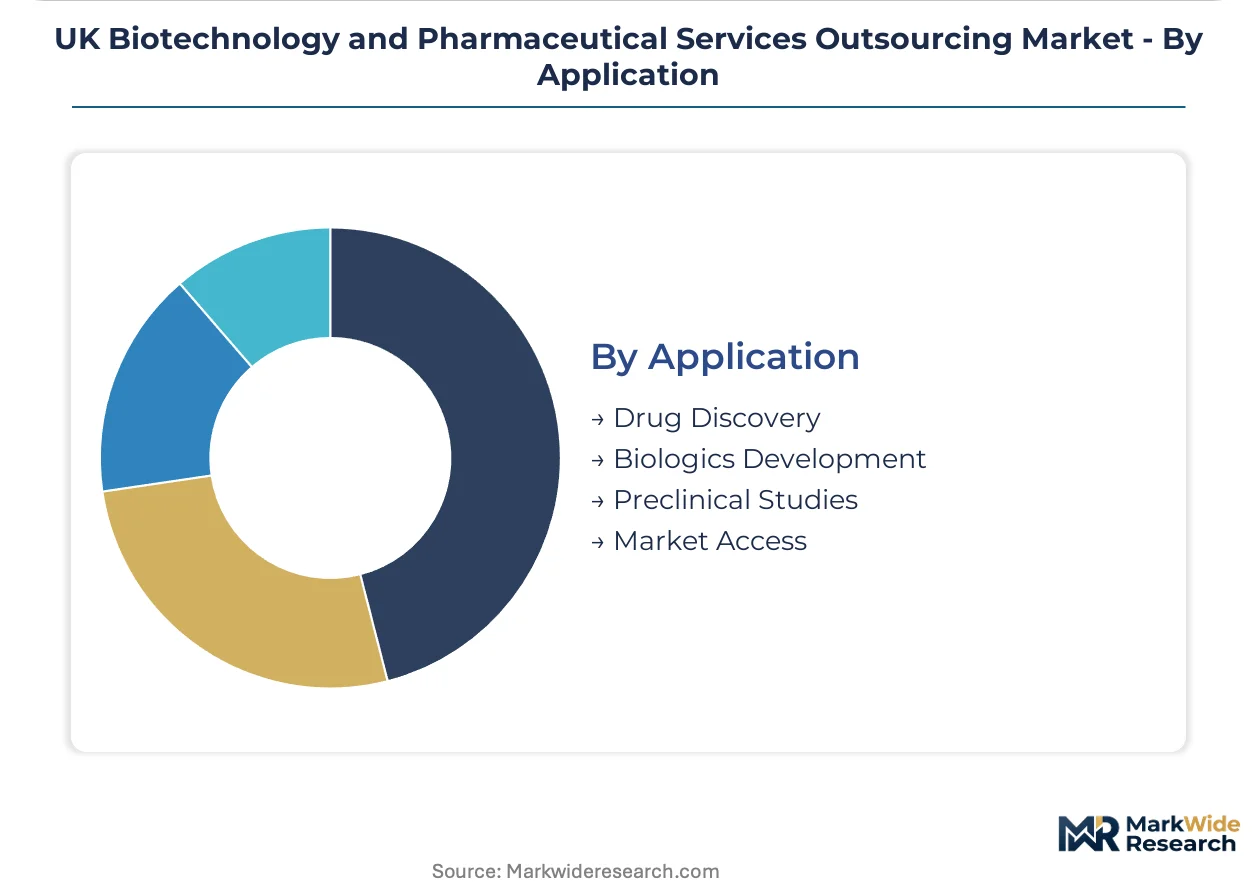
Application:
Therapeutic focus areas separate small-molecule commodity services from complex biologics requiring specialized infrastructure.
- Drug Discovery:Target identification, hit-to-lead optimization, and early pharmacology studies. Academic and biotech demand in Cambridge and Oxford is sustaining CRO capacity for high-throughput screening and structural biology.
- Biologics Development:Cell line development, viral vector production, and biosimilar analytical characterization. Viral vector manufacturing constraints in England are attracting CDMO investment into Scottish bioprocessing clusters.
- Preclinical Studies:GLP toxicology, pharmacokinetics, and safety pharmacology in rodent and non-rodent species.
- Market Access:Health technology assessment preparation, NICE engagement, and payer evidence generation.
Concentrated infrastructure characterizes Drug Discovery. Capacity expansion is accelerating fastest in Biologics Development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Oxford-Cambridge-London golden triangle anchors UK biotechnology and pharmaceutical services outsourcing activity, concentrating early-phase clinical trial capacity, regulatory expertise, and biologics manufacturing infrastructure within a 90-mile corridor.
England
London and the Southeast dominate pharmacovigilance and regulatory consulting demand, driven by virtual pharmaceutical companies lacking in-house MHRA liaison capacity. The Human Medicines Regulations 2012 mandate expanded safety reporting obligations that sustain recurring revenue for specialist service providers clustered around the capital.
Scotland
Scottish preclinical facilities capture expanded toxicology study volume from North American sponsors leveraging MHRA-FDA recognition agreements. Viral vector manufacturing constraints in England redirect CDMO investment toward Scottish bioprocessing clusters, particularly around Glasgow and Edinburgh life science parks.
Wales
Welsh pharmaceutical manufacturing infrastructure offers underutilized fill-finish capacity attractive to cost-sensitive biotech sponsors. The country's central location within the UK market supports distribution optimization for temperature-controlled biologics requiring specialized cold-chain logistics.
North England
Yorkshire and the Northern Powerhouse region present cost-advantaged biomanufacturing alternatives to Southeast England's premium real estate markets. NHS-affiliated investigator networks in Manchester and Leeds sustain mid-scale clinical trial execution for regional biotech developers.
UK Biotechnology and Pharmaceutical Services Outsourcing Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the UK biotechnology and pharmaceutical services outsourcing landscape. Full-service integrators with captive manufacturing infrastructure face margin pressure from specialized point-solution vendors delivering modular preclinical and clinical service modules. Three strategic archetypes dominate: integrated data-analytics platforms anchoring real-world evidence programs, preclinical biologics specialists with GLP-certified toxicology capacity, and decentralized trial execution platforms reducing site dependency. Competitive dynamics center on strategic partnerships for NHS data access and capacity expansion into Scottish viral vector manufacturing clusters.
Within the integrated data infrastructure tier, IQVIA Holdings Inc exemplifies the analytics-enabled archetype anchoring large-scale NHS-affiliated programs. Charles River Laboratories International Inc occupies a position representing preclinical biologics specialization from Scottish facilities. Icon PLC sits within the decentralized execution vector, exemplifying remote monitoring capabilities that reduce site dependency for UK biotech sponsors.
| Leading Market Players |
|---|
| IQVIA Holdings Inc |
| PAREXEL International Corporation |
| Charles River Laboratories International Inc |
| Icon PLC |
| The Quantic Group |
| Concept Heidelberg GmbH |
| Lachman Consultant Services |
| GMP Pharmaceuticals |
| Quality Context Ltd |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up CRO specialists have concentrated ownership across the Oxford-Cambridge-London corridor, tightening pricing discipline through portfolio-company coordination on large-sponsor RFPs while simultaneously constraining supply-side flexibility through standardized vendor panels.
Pricing Analysis
Outcome-linked pricing for pharmacovigilance and regulatory consulting anchors value capture in the UK market. Three-tier pricing structure across premium, standard, and economy levels separates MHRA-embedded advisory retainers from transactional project fees and offshore data processing rates. Cost compression in standard clinical operations is intensifying because biotech sponsors are unbundling full-service contracts into modular procurement. Virtual pharmaceutical companies exhibit the highest price sensitivity, while large-cap originators prioritize quality system harmonization over unit cost.
Supply Chain Analysis
Reverse-logistics flows for temperature-controlled biologics create specialized cold-chain complexity that concentrates among three national courier networks. Viral vector manufacturing draws from Scottish bioprocessing clusters, English fill-finish infrastructure, and Welsh distribution hubs. Single-source vulnerability in specialized cold-chain logistics represents the dominant structural risk. Distribution runs through NHS-affiliated investigator sites for clinical materials and direct-to-patient channels for decentralized trial execution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
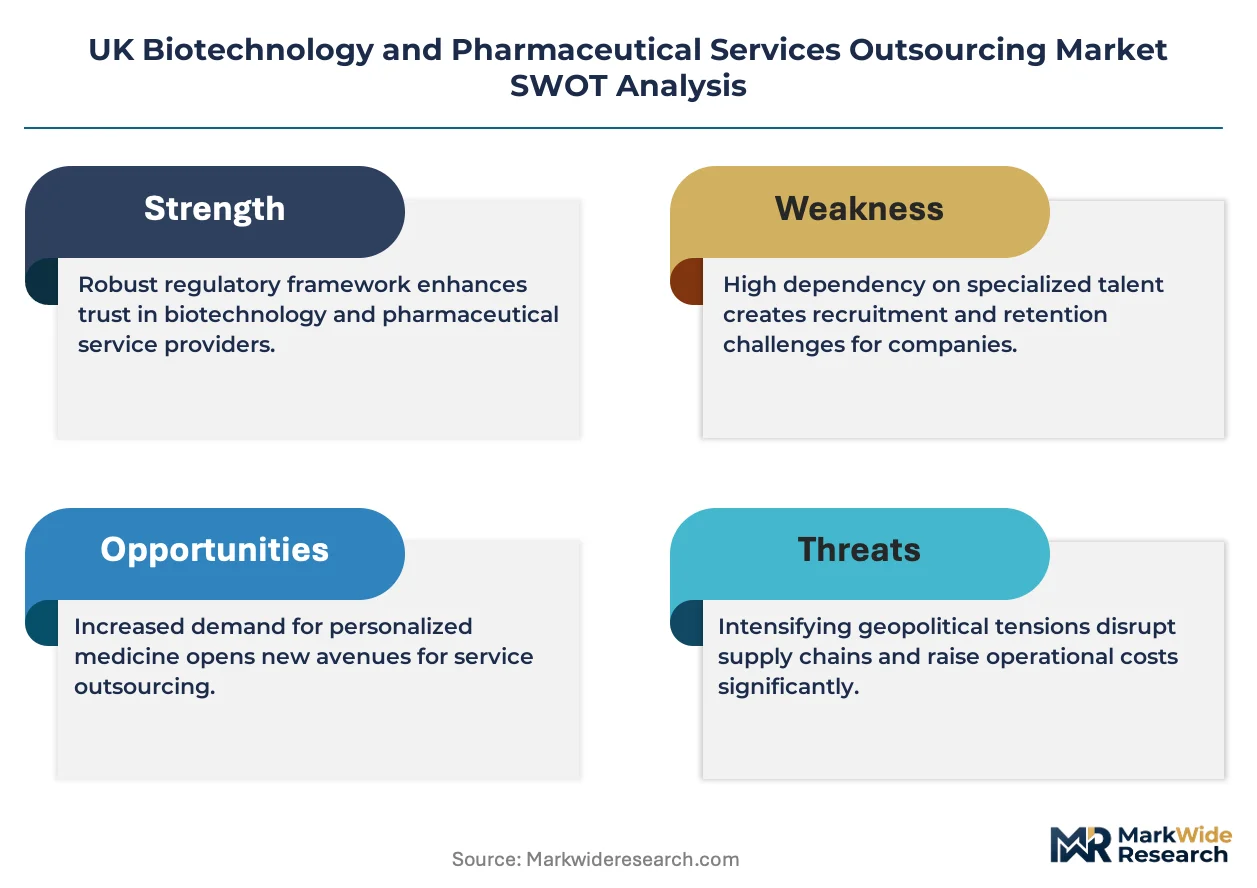
EU-UK regulatory divergence on gene therapy classifications is compressing margins for single-market specialists, forcing consolidation among CROs lacking dual-jurisdiction expertise.
For Market Incumbents: Lock in NHS data access partnerships before electronic health record linkage capabilities commoditize. Acquire Scottish toxicology capacity to capture North American sponsor volume leveraging MHRA-FDA recognition agreements. Defend against modular point-solution vendors by embedding former agency reviewers in subscription-layer regulatory consulting offerings. For New Entrants and Emerging Players: Begin with Northern England biomanufacturing infrastructure where underutilized fill-finish capacity offers cost-advantaged positioning against Southeast England's premium real estate markets. Yorkshire and the Northern Powerhouse region present the most penetrable geography for mid-scale clinical trial execution. Pursue direct-to-patient logistics partnerships as the primary go-to-market angle for decentralized trial platform differentiation. For Investors and Strategic Acquirers: CDMO investment announcements into Scottish viral vector manufacturing clusters are the leading indicator that capacity-constrained biologics development is shifting competitive gravity northward. The five-to-ten-year viability window favors asset-heavy producers with captive manufacturing infrastructure over pure-service CROs. Target preclinical biologics specialists with GLP-certified toxicology capacity and validated software systems compliant with updated MHRA GMP Annex 11 requirements. Monitor MHRA-EU divergence negotiations for early signals of sustained dual-dossier demand.| Strategic Initiative | Industry Significance |
|---|---|
| Scottish Viral Vector Capacity Expansion | Attracts CDMO investment redirecting from constrained English bioprocessing infrastructure toward Glasgow and Edinburgh life science parks. |
| NHS Real-World Evidence Integration | Creates differentiated positioning for data-analytics-enabled CROs through electronic health record linkage capabilities. |
| Hybrid Delivery Model Deployment | Captures margin concentration by blending UK-based regulatory expertise with offshore pharmacovigilance case processing. |
| Decentralized Trial Platform Launch | Reduces site dependency for UK biotech sponsors through remote monitoring convergence with direct-to-patient logistics. |
| Regulatory Consulting Subscription Tier | Displaces project-based advisory engagements among virtual pharmaceutical companies lacking in-house MHRA liaison capacity. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists. MHRA submission databases, ClinicalTrials.gov records, NHS procurement disclosures, and EMA divergence documentation provided cross-referenced validation. Bottom-up service-type demand modeling and top-down market sizing triangulated volume estimates.
Segmentation granularity extended to delivery model configuration, client sophistication tier, therapeutic application focus, and regional regulatory cluster across the projection horizon. CAGRs were derived from weighted average growth trajectories incorporating sponsor pipeline velocity, CDMO capacity expansion announcements, and MHRA staffing projections. Bayesian protocol amendment complexity and adaptive trial design penetration served as biostatistics-demand forecast inputs.
Underlying measurement precision varies by segment; pharmacovigilance and regulatory consulting carry tighter precision than decentralized trial platform adoption. Forecasts reflect documented assumptions regarding sustained NHS investigator-site demand and MHRA-FDA recognition agreement continuity. Practitioners should monitor UK-EU advanced therapy medicinal product classification negotiations and Scottish bioprocessing cluster investment flows for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Services
Biologics CDMO Market
Biotechnology Services
Plant Tissue Culture Products Market
Biotechnology Services
Custom Peptide Synthesis Services Market
Biotechnology Services
Europe Downstream Processing Market
Biotechnology Services
Global Cell Banking Outsourcing Market
Biotechnology Services
Global High Throughput Screening Market
Biotechnology Services
Europe Recombinant Protein Manufacturing Services Market
Biotechnology Services
Global Alpha Galactosidase Market
Biotechnology Services
Cell Line Development Market
Biotechnology Services
Recombinant Proteins Manufacturing Services Market
Biotechnology Services
Dnases, Ligases, and RNA Polymerases Market
Biotechnology Services
Cell Lysis and Dissociation Market
Biotechnology Services
Isothermal Nucleic Acid Amplification Technology (INAAT) Market
Biotechnology Services
Global Western Blotting Market
Biotechnology Services
Asia-Pacific Biotechnology Market
Biotechnology Services
Global Protein Purification and Isolation Market