
 Global Vector Control Market | 2026-2036
Global Vector Control Market Size, Share, and Industry Trends Forecast 2026-2036
Global Vector Control Market Outlook
Precision-targeted genetic modification technologies, including Wolbachia deployment and gene drive systems, are reshaping how vector populations are suppressed at scale. Syngenta Group leverages its agrochemical R&D infrastructure to develop next-generation larvicides with enhanced target specificity. BASF SE anchors its position through integrated pest management platforms that combine chemical and biological modalities. Rentokil Initial Plc extends its service footprint through predictive analytics platforms that optimize treatment scheduling for commercial clients.
Vector control encompasses the systematic management of arthropod populations—principally mosquitoes, ticks, and flies—that transmit pathogens to humans, livestock, and crops, utilizing chemical formulations with specified active ingredient concentrations, biological agents with defined colony-forming units, and physical barriers with calibrated mesh specifications to interrupt disease transmission cycles. The primary commercial purpose spans public health protection, agricultural yield preservation, and environmental compliance in inhabited spaces. Chemical treatments dominate current procurement volumes across government tenders, while biological control agents capture expanding margin pools as residue restrictions tighten in food-producing regions. Genetic control technologies represent the fastest-expanding segment, though physical barriers sustain stable replacement demand in residential and commercial construction.
The EPA regulates pesticide registration and tolerance thresholds in the United States, while the WHO issues normative guidance on insecticide resistance monitoring protocols that shape national procurement standards. The EU Green Deal and REACH frameworks restrict persistent organic pollutant formulations, accelerating reformulation investments among established suppliers. Stakeholders must monitor regulatory divergence between jurisdictions that accept gene-edited organisms and those maintaining precautionary moratoriums, as this bifurcation will determine technology licensing strategies and manufacturing location decisions.
Market Dynamics
The EPA's re-evaluation of neonicotinoid registrations is forcing procurement officers across municipal agencies to accelerate biological alternative sourcing before 2027 compliance deadlines.
Growth Catalysts
- Wolbachia deployment protocols:WHO insecticide resistance monitoring guidelines now endorse bacterial endosymbiont releases as a core intervention modality, expanding eligible procurement categories for national dengue programs.
- Climate-driven season extension:Brazil's municipal public health agencies are extending integrated vector management contracts as transmission windows lengthen in the Amazon basin and southeastern states.
- REACH framework restrictions:Persistent organic pollutant reformulation mandates under EU Green Deal implementation are redirecting R&D investment toward biodegradable active ingredient platforms.
Market Restraints
- Pyrethroid resistance mapping costs:Molecular diagnostic requirements for resistance surveillance impose capital burdens on national malaria control programs with limited laboratory infrastructure.
- Gene drive moratorium divergence:Precautionary regulatory stances in the European Union block field trial approvals that proceed under streamlined frameworks in Burkina Faso and Mali, fragmenting technology licensing territories.
- Biological agent cold chain dependency:Bacillus thuringiensis israelensis formulations require uninterrupted refrigerated logistics that fail in rural Indonesia and Vietnam distribution networks.
Strategic Opportunities
- Gene-edited organism acceptance zones:Brazil and Burkina Faso regulatory pathways for Oxitec's Friendly mosquito permits create first-mover licensing advantages before wider WHO prequalification.
- Predictive analytics integration:Larval habitat mapping through satellite-derived hydrology data is compressing treatment response times for commercial pest management contracts in Southeast Asian industrial zones.
- Residual spraying service unbundling:Municipal procurement in Vietnam and Indonesia is separating chemical supply from application labor, opening margin capture for specialized service platforms.
Industry Challenges
- Entomological field capacity scarcity:Vector bionomics expertise required for Wolbachia release site selection and monitoring outpaces training program throughput in Indonesia's provincial health departments.
- Gene drive containment protocol validation:Ecological risk assessment methodologies lack harmonization between the Cartagena Protocol national focal points and WHO guidance, delaying trial initiation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Vector Control Market |
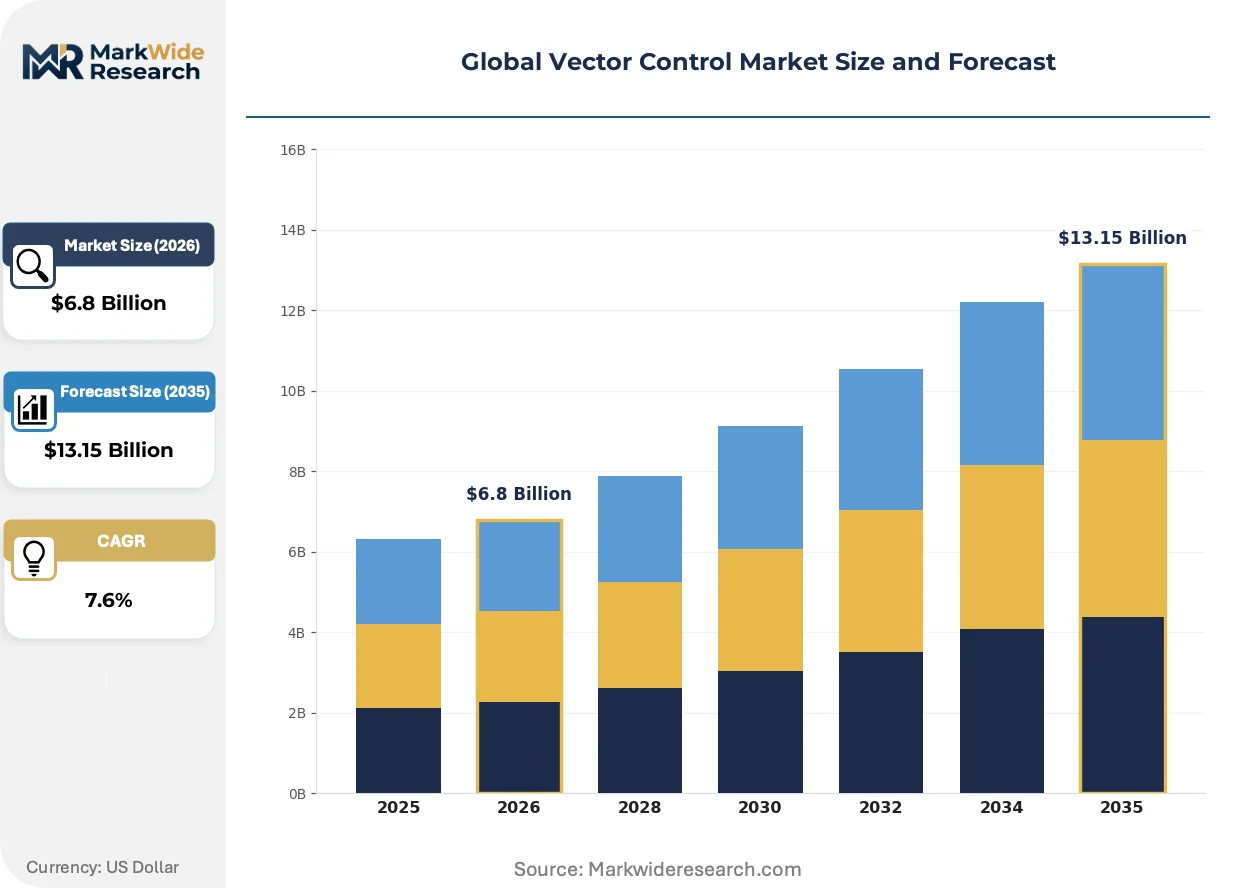
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pesticides, Traps, Insect Growth Regulators, Biological Control Agents End User: Commercial, Government, Residential, Agricultural Application: Disease Prevention, Pest Management, Environmental Health, Public Health Technology: Biotechnology, Chemical Treatments, Physical Barriers, Genetic Control |
| Companies Covered | Syngenta Group, Ecolab, BASF SE, Anticimex, Rollins Inc., Rentokil Initial Plc, FMC Corporation, Neogen Corporation, Sumitomo Chemical Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Vector Control Market Strategic Shifts
Precision genetic modification tools are compressing the intervention cycle from seasonal chemical application to persistent population suppression through heritable trait transmission.
RNA interference larvicides are hybridizing conventional chemical modes of action with sequence-specific genetic disruption, enabling rotation strategies that bypass metabolic resistance mechanisms in Anopheles populations. West African national malaria control programs are piloting these formulations in indoor residual spraying protocols. The technology is hybridizing procurement categories that previously separated biological and chemical control budgets.
REACH authorization requirements for persistent organic pollutants are eliminating legacy organophosphate formulations from EU tender eligibility, accelerating supplier portfolio restructuring toward microbial and botanical alternatives. Agricultural extension services in Spain and Italy face reformulation deadlines that compress registration timelines. Vector control product lines serving Mediterranean basin markets are most affected, with manufacturers redirecting active ingredient sourcing to fermentation-derived compounds.
Subscription-based service contracts are displacing per-treatment procurement in commercial and residential segments, bundling monitoring, intervention, and warranty into recurring revenue structures. Rentokil Initial and regional competitors in Southeast Asia are consolidating technician deployment through predictive routing algorithms. This model concentrates most visibly in Singapore and urban Vietnam, where property management companies favor fixed-cost vector risk transfer over variable spraying expenses.
Global Vector Control Market Segmentation
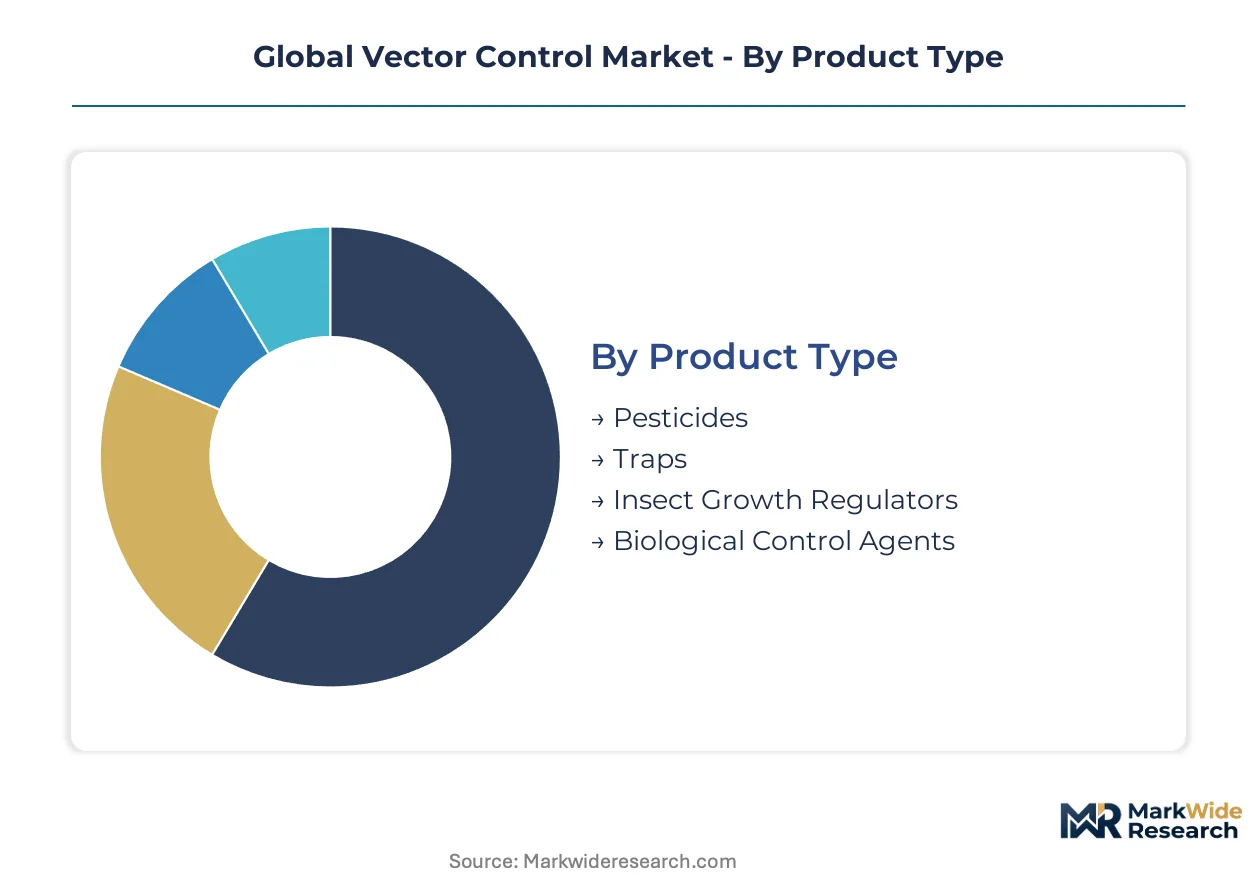
Vector control procurement diverges sharply across customer types, with government tenders favoring bulk chemical formulations while commercial clients prioritize subscription-based integrated services. Technology selection determines margin structure, as biological and genetic modalities command premium pricing against commodity insecticide volumes.
Product Type:
Cost tier differentiation separates commodity chemical formulations from precision-engineered biological systems with cold-chain dependencies.
- Pesticides:Synthetic pyrethroids and organophosphates dominate municipal tender volumes in Brazil and Southeast Asia. Resistance monitoring costs in Vietnam and Indonesia are redirecting procurement toward rotation-ready formulations with documented susceptibility baselines.
- Biological Control Agents:Bacillus thuringiensis israelensis formulations and Wolbachia-infected mosquito releases require calibrated colony-forming unit specifications and refrigerated logistics. Demand concentrates in EU member states where REACH restrictions eliminate persistent organic pollutant alternatives.
- Traps:Gravitational and light-attraction devices with specified mesh apertures serve residential and commercial monitoring applications.
- Insect Growth Regulators:Juvenile hormone analogs and chitin synthesis inhibitors interrupt metamorphosis at larval stages for agricultural integration.
Pesticides command the established base. The steepest expansion runs through Biological Control Agents.
End User:
Customer type determines contract structure, payment terms, and regulatory compliance burden across the procurement landscape.
- Government:National malaria and dengue control programs in Burkina Faso, Mali, and Indonesia issue multi-year tenders for indoor residual spraying and larval source management. EPA neonicotinoid re-evaluation deadlines are accelerating biological alternative sourcing before compliance thresholds.
- Commercial:Property management firms in Singapore and urban Vietnam are adopting subscription-based service contracts bundling monitoring, intervention, and warranty. Predictive analytics platforms optimize technician routing and treatment scheduling.
- Residential:Individual household procurement of physical barriers and perimeter treatments concentrates in new construction clusters.
- Agricultural:Crop protection applications face residue tolerance thresholds under FDA and EFSA oversight, favoring microbial and botanical formulations.
Government agencies anchor volume procurement. Commercial segments are climbing the fastest as risk-transfer contracting displaces per-treatment purchasing.
Application:
Application focus shapes intervention modality selection and regulatory oversight intensity.
- Disease Prevention:Malaria and dengue transmission interruption drives WHO-prequalified procurement standards. West African national programs pilot RNA interference larvicides in indoor residual spraying protocols.
- Pest Management:Commercial and residential nuisance control emphasizes rapid knockdown and residual efficacy.
- Public Health:Municipal agencies in Brazil extend integrated vector management contracts as climate patterns lengthen transmission windows in Amazon basin and southeastern states.
- Environmental Health:Ecosystem protection applications prioritize biodegradable active ingredients with minimal non-target effects.
Public Health applications concentrate institutional spending. Disease Prevention represents the fastest-growing trajectory as gene drive and Wolbachia platforms expand eligible intervention categories.
Technology:
Technology maturity determines capital requirements, regulatory pathway length, and intellectual property licensing potential.
- Genetic Control:Gene drive systems and Oxitec's Friendly mosquito releases proceed under streamlined regulatory frameworks in Brazil and Burkina Faso. Precautionary moratoriums in the European Union fragment technology licensing territories and manufacturing location decisions.
- Biotechnology:RNA interference larvicides hybridize chemical and genetic disruption modes, enabling rotation strategies that bypass metabolic resistance in Anopheles populations.
- Chemical Treatments:Conventional synthetic formulations face resistance erosion and registration pressure from EPA and REACH frameworks.
- Physical Barriers:Mesh-specified screens and netting sustain stable replacement demand in residential and commercial construction.
Chemical Treatments retain the volume base. Genetic Control is gaining share fastest as heritable trait transmission compresses intervention cycles from seasonal application to persistent population suppression.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazilian municipal agencies export technical expertise to Southeast Asian dengue programs, creating knowledge-transfer corridors that reshape procurement patterns across tropical disease belts.
Brazil
Climate-driven transmission season extension in Amazonas and São Paulo states is forcing municipal health departments to expand integrated vector management contracts. ANVISA maintains streamlined pathways for gene-edited organism field trials that attract Oxitec and other developers. The Campinas technology cluster anchors Wolbachia deployment infrastructure serving Latin American export markets.
United States
EPA neonicotinoid re-evaluation deadlines are accelerating biological alternative sourcing across municipal vector control districts. The agency's tolerance threshold reviews reshape procurement eligibility for legacy synthetic formulations. Research Triangle Park in North Carolina concentrates federal laboratory capacity for resistance monitoring protocols that inform WHO guidance documents.
Indonesia
National dengue control budget expansion is scaling procurement for larval source management and indoor residual spraying programs. The country's national pharmaceutical regulator enforces cold-chain requirements for Bacillus thuringiensis israelensis formulations that strain rural distribution networks. Java's industrial corridors concentrate biological agent formulation capacity serving archipelago-wide public health programs.
Germany
REACH authorization requirements for persistent organic pollutants are eliminating legacy organophosphate formulations from tender eligibility. ECHA reformulation mandates accelerate supplier portfolio restructuring toward microbial and botanical alternatives. The Rhine-Ruhr chemical manufacturing belt anchors fermentation-derived active ingredient production for EU vector control markets.
Burkina Faso
National malaria control programs pilot RNA interference larvicides in indoor residual spraying protocols with WHO technical support. Streamlined regulatory frameworks for gene drive field trials proceed under national biosafety committee oversight that diverges from EU precautionary moratoriums. Ouagadougou anchors West African entomological field capacity for resistance surveillance and trial monitoring.
Global Vector Control Market Competitive Environment
Channel-controlling players compete with product-specialist players across procurement tiers that separate government tender volumes from commercial service contracts. The structure consolidates around agrochemical conglomerates with legacy registration portfolios, pest management service platforms with predictive analytics integration, and biotechnology developers with gene-edited organism pipelines. Three archetypes dominate: formulation manufacturers with EPA and REACH-compliant active ingredient libraries, integrated service providers bundling monitoring and intervention, and precision genetic technology licensors. Competitive moves concentrate on portfolio diversification into biological alternatives and geographic licensing expansion for gene drive platforms.
Within the agrochemical formulation tier, Syngenta Group and BASF SE exemplify multinational conglomerates with integrated R&D infrastructure spanning conventional and next-generation active ingredient development. Among service-platform operators, Rentokil Initial Plc occupies a position representing predictive analytics integration and subscription-based contracting models. These anchors illustrate how competitive positioning separates product-centric from service-centric value capture across divergent procurement channels.
| Leading Market Players |
|---|
| Syngenta Group |
| Ecolab |
| BASF SE |
| Anticimex |
| Rollins Inc. |
| Rentokil Initial Plc |
| FMC Corporation |
| Neogen Corporation |
| Sumitomo Chemical Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on Chinese fermentation-derived active ingredient production determines both the premium commanded by REACH-compliant biological formulations and the geographic restructuring of formulation capacity toward EU member states and Brazil.
Pricing Analysis
The technology-generation pricing gap between legacy pyrethroid formulations, current RNA interference larvicides, and emerging gene drive licensing structures stratifies procurement budgets across government tenders. Three-tier pricing structure across premium genetic platforms, standard biological agents, and economy chemical volumes reflects certification grade differentiation under WHO prequalification standards. Cost compression in commodity insecticide tiers is intensifying because Brazilian and Southeast Asian municipal agencies unbundle chemical supply from application services. Government malaria control programs exhibit highest price sensitivity due to fixed budget envelopes, while commercial subscription clients in Singapore demonstrate lowest sensitivity through risk-transfer contracting models.
Supply Chain Analysis
Export-control regime restrictions on gene-edited organism transport technologies limit cross-border flow of Wolbachia-infected mosquito eggs and gene drive containment equipment between regulatory jurisdictions. Active ingredient manufacturing concentrates in China, India, and Germany, with formulation capacity anchored in Brazil, Indonesia, and the Rhine-Ruhr corridor. Supply chain risk rests on single-source vulnerability for Bacillus thuringiensis israelensis master seed stocks held by limited fermentation facilities. Distribution runs through cold-chain logistics networks that fail in rural Indonesian archipelago distribution, alongside direct government tender fulfillment for bulk chemical formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gene drive platform interoperability with national biosafety monitoring systems is reshaping competitive architecture around data-sharing ecosystems rather than standalone product sales.
For Market Incumbents: Pre-empt biological formulation commoditization by securing backward integration into fermentation-derived active ingredient production in Brazil and Germany. Anchor capacity addition in Campinas and Rhine-Ruhr corridors before REACH reformulation deadlines eliminate legacy organophosphate eligibility. Channel control through predictive analytics platforms defends margin position against unbundled procurement trends in Vietnam and Indonesia. For New Entrants and Emerging Players: Rural Indonesian provinces outside Java's industrial corridor represent the most penetrable geography for cold-chain-independent biological agent distribution partnerships. White-space targets include subscription-based commercial pest management in secondary Vietnamese cities and RNA interference larvicide co-development with West African national malaria programs. A go-to-market angle through municipal technician training partnerships bypasses entomological field capacity scarcity barriers. For Investors and Strategic Acquirers: EPA neonicotinoid re-evaluation reshapes the acquisition landscape toward biological alternative developers with existing ANVISA or ECHA registration pathways. Long-term viability centers on gene-edited organism licensing portfolios in regulatory acceptance zones spanning Brazil, Burkina Faso, and Mali. Acquisition target archetypes include precision genetic technology licensors with streamlined national biosafety approvals. The signal to watch is WHO prequalification timeline acceleration for Wolbachia deployment protocols.| Strategic Initiative | Industry Significance |
|---|---|
| Biological Formulation Scale-Up | Fermentation capacity expansion in Rhine-Ruhr anchors EU REACH compliance before organophosphate elimination deadlines. |
| Gene Drive Regulatory Licensing | ANVISA and Burkinabe biosafety pathway precedents create first-mover manufacturing location advantages in Brazil and West Africa. |
| Predictive Analytics Integration | Satellite-derived hydrology data compression of treatment response times locks in commercial subscription contract renewals in Singapore. |
| Cold-Chain Distribution Partnership | Rural Indonesia logistics network investments bypass Bacillus thuringiensis israelensis refrigeration failures in provincial health departments. |
| Technician Training Program | Wolbachia release site selection expertise development addresses entomological field capacity scarcity in Indonesia's provincial health departments. |
Study Parameters
Initial hypotheses were tested against primary input from vector control program directors, municipal procurement officers, biological agent formulation plant managers, and gene drive technology licensing executives and refined through secondary validation across EPA registration databases, WHO insecticide resistance monitoring guidelines, ANVISA field trial approvals, ECHA REACH authorization records, and national malaria control program tender documents. Bottom-up triangulation of procurement volumes across Brazilian municipal health departments and Indonesian national dengue programs was cross-checked against top-down agrochemical conglomerate segment disclosures.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling segmentation dimensions spanning product type tiers, end-user procurement structures, application focus areas, and technology maturity stages alongside regulatory pathway length differentials. CAGRs were derived from compound growth trajectory analysis of historical tender volumes and projected biological alternative substitution rates. Industry-specific forecast inputs incorporated climate-driven transmission season extension patterns in Amazon basin states and EPA compliance deadline acceleration effects on biological sourcing timelines.
Macroeconomic conditions sit as an overlay; deviation in Brazilian real volatility, Indonesian rupiah depreciation against fermentation input costs, or EU carbon border adjustment implementation would shift the trajectory. Forecasts reflect documented assumptions on regulatory acceptance zone expansion timelines and cold-chain infrastructure investment rates. Material shifts in WHO gene drive prequalification standards or Cartagena Protocol national focal point harmonization would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Services
Europe Recombinant Protein Manufacturing Services Market
Biotechnology Services
Global Reporter Gene Assay Market
Biotechnology Services
Plasma Feed Market
Biotechnology Services
Acetylglucosamine Market
Biotechnology Services
Europe Flow Cytometry Market
Biotechnology Services
Molecular Methods Market
Biotechnology Services
Antibody Contract Development & Manufacturing Organization Market
Biotechnology Services
US Digital PCR Market
Biotechnology Services
Global Digital PCR (Dpcr) and Real-Time PCR (Qpcr) Market
Biotechnology Services
Custom Peptide Synthesis Services Market
Biotechnology Services
Insect Cell Lines Market
Biotechnology Services
Industrial Microbiology Testing Services Market
Biotechnology Services
Research Antibodies Market
Biotechnology Services
Cell Line Development Services Market
Biotechnology Services
Luciferase Assay Market
Biotechnology Services
Global Molecular Biology Enzymes and Kits and Reagents Market