
 Phospho-Specific Antibodies Market | 2026-2036
Phospho-Specific Antibodies Market Size, Share, and Industry Trends Forecast 2026-2036
Phospho-Specific Antibodies Market Analytics
Chinese contract research organizations is restructuring phospho-specific antibody production capacity to serve Western biopharma outsourcing needs. Thermo Fisher Scientific leverages its global distribution network to sustain reagent availability across multiple continents. Cell Signaling Technology anchors premium positioning through its specialized catalog of pathway-specific phospho-antibodies. Abcam competes on digital platform reach, offering researchers extensive product documentation and validation data.
Phospho-specific antibodies are immunoreagents engineered to recognize protein epitopes containing phosphorylated serine, threonine, or tyrosine residues, typically requiring affinity purification and rigorous cross-reactivity testing to ensure phospho-state selectivity. These reagents enable quantitative detection of activated signaling proteins in cell lysates and tissue sections, serving as essential tools for kinase drug discovery and cancer pathway research. Monoclonal antibodies dominate the product landscape due to their batch-to-batch consistency and defined clonality, while recombinant antibodies represent the fastest-growing category as manufacturers seek animal-origin-free production systems. Western blotting remains the foundational application for phospho-detection workflows, though flow cytometry is gaining traction for single-cell phosphoprotein analysis in immuno-oncology studies.
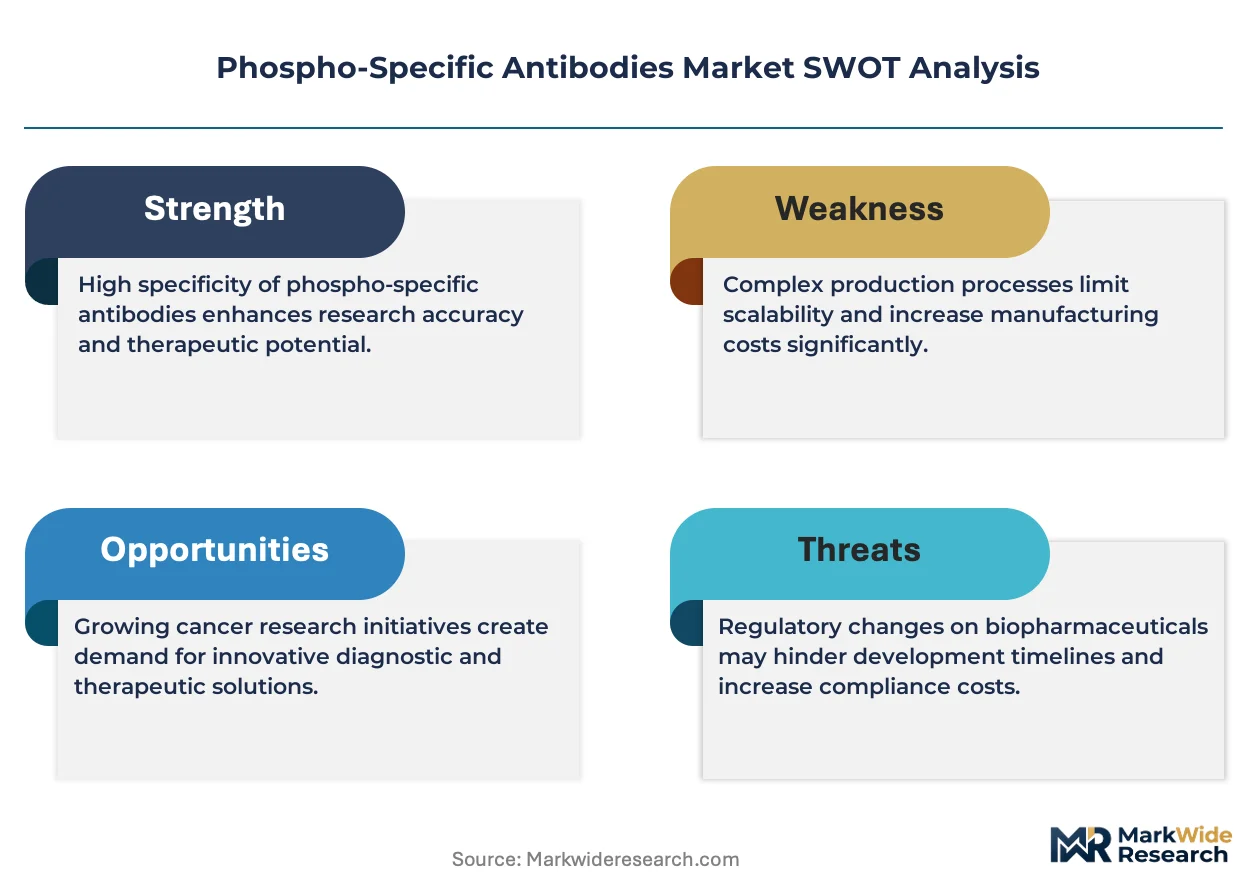
FDA guidance on bioanalytical method validation and ISO 13485 quality management standards shape reagent performance expectations and manufacturing documentation requirements for phospho-specific antibody suppliers. The EPA monitors waste streams from hybridoma production facilities, while REACH compliance in Europe constrains certain conjugate chemistries and preservative formulations used in antibody stabilization. Stakeholders must monitor evolving regulatory harmonization between the FDA and EMA regarding antibody characterization standards, as divergence in validation requirements could fragment product development strategies across major markets.
Market Dynamics
FDA tightening of antibody validation standards is compressing supplier margins while simultaneously elevating performance benchmarks across the phospho-specific antibody value chain. This regulatory pressure is reshaping manufacturing documentation requirements and forcing upstream investment in characterization infrastructure.
Growth Catalysts
- Kinase drug discovery pipelines:Pharmaceutical researchers in Boston and San Diego life science clusters are scaling phospho-detection workflows for target validation studies, driving volume procurement of pathway-specific reagents.
- ISO 13485 quality mandates:Medical device and diagnostic manufacturers require certified antibody suppliers for companion diagnostic development, creating premium-tier demand for documented manufacturing controls.
- Single-cell phosphoprotein analysis:Immuno-oncology research programs are adopting flow cytometry-based phospho-detection to profile signaling heterogeneity in tumor microenvironments.
Market Restraints
- Hybridoma facility waste compliance:EPA monitoring of cell culture effluent streams raises operating costs for monoclonal antibody producers in United States manufacturing zones.
- Cross-reactivity validation burden:Each phospho-specific clone requires extensive peptide competition assays to demonstrate phospho-state selectivity, extending development timelines.
- REACH-constrained formulations:European preservative and conjugate chemistry restrictions limit stabilization options for antibody shelf-life extension.
Strategic Opportunities
- Chinese CRO outsourcing pivot:Western biopharma contract research organizations are redirecting phospho-antibody production to specialized Chinese manufacturing partners for cost-optimized supply.
- Recombinant antibody platforms:Animal-origin-free production systems are capturing share from traditional hybridoma methods as regulatory agencies tighten biosafety documentation requirements.
- Digital validation data monetization:Extensive product documentation and batch-specific performance certificates are becoming differentiable service layers for research reagent distributors.
Industry Challenges
- Phosphopeptide synthesis expertise scarcity:Qualified immunogen design specialists capable of generating stable phospho-epitope mimics command premium compensation in tight labor markets.
- Batch-to-batch consistency enforcement:Maintaining clonal stability across recombinant production runs demands capital-intensive bioreactor monitoring infrastructure and analytical QC suites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Phospho-Specific Antibodies Market |
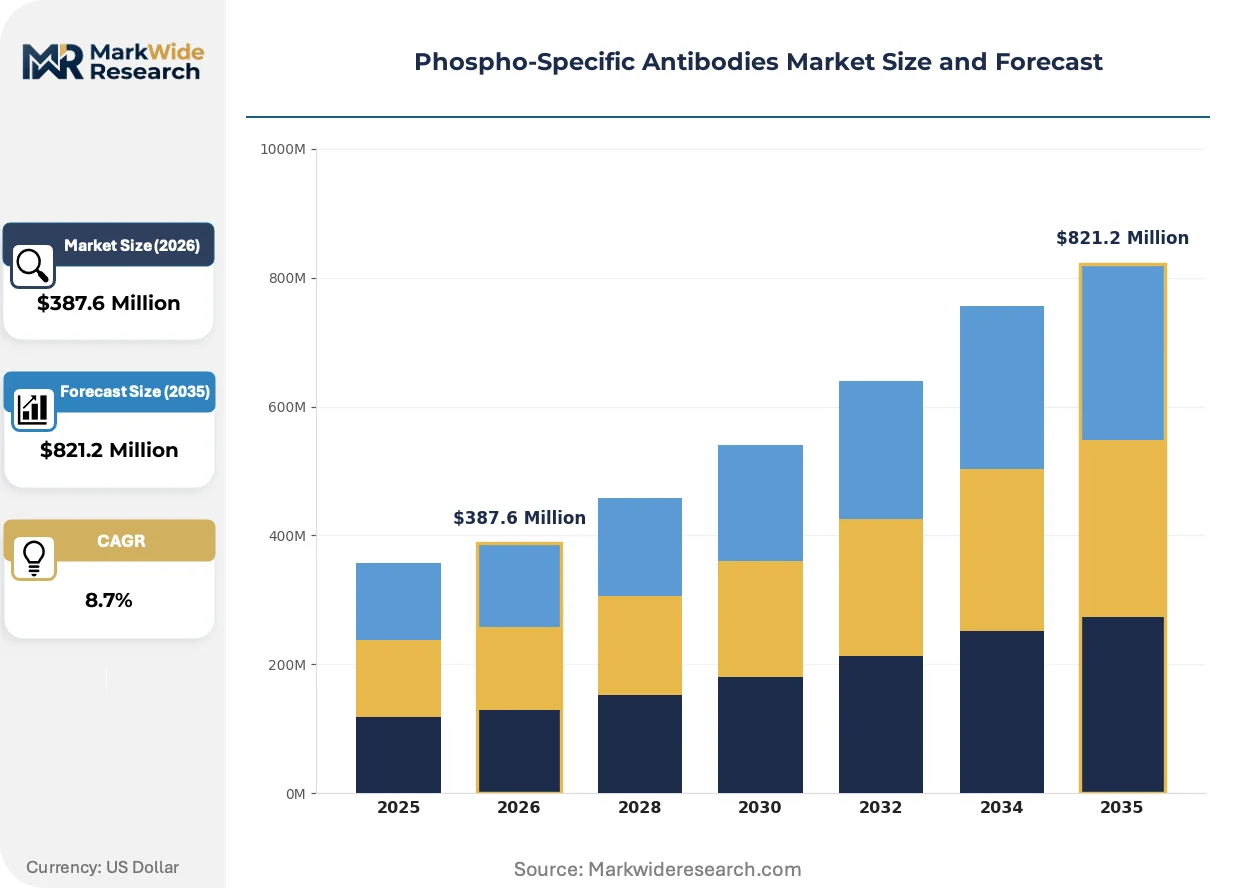
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Polyclonal Antibodies, Recombinant Antibodies, Conjugated Antibodies Application: Western Blotting, Immunohistochemistry, Flow Cytometry, ELISA End User: Academic Research Institutes, Pharmaceutical Companies, Biotechnology Firms, Clinical Laboratories Sales Channel: Direct Sales, Online Retail, Distributors, Resellers |
| Companies Covered | Abcam, Rockland Immunochemicals, Thermo Fisher Scientific, Bethyl Laboratories, Merck MilliporeSigma, Cell Signaling Technology, GenScript Biotech, Creative Diagnostics, Bio-Rad Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Phospho-Specific Antibodies Market Evolving Landscape
Recombinant antibody engineering is displacing conventional hybridoma dominance as manufacturers seek production consistency and regulatory documentation advantages. Three convergent developments are restructuring competitive positioning in phospho-specific reagent supply.
Recombinant monoclonal platforms are absorbing development investment from legacy hybridoma infrastructure. Cell Signaling Technology and specialized catalog providers are sequencing defined clonal frameworks for animal-origin-free manufacturing. This transition compresses development timelines for new phospho-target specificities while satisfying evolving FDA guidance on reagent traceability.
REACH compliance deadlines in Europe are forcing reformulation of antibody stabilization chemistries. Suppliers serving EMA-regulated diagnostic markets are substituting alternative preservatives and buffer systems to maintain shelf-life performance. Recombinant antibody producers with flexible formulation capabilities are capturing share in continental European procurement cycles.
Research reagent buyers are consolidating vendor relationships around integrated digital platforms. Extensive validation datasets and batch-specific certificates of analysis are becoming baseline procurement requirements rather than premium add-ons. Academic core facilities in United States research universities are prioritizing suppliers with searchable antibody performance databases and transparent cross-reactivity documentation.
Phospho-Specific Antibodies Market Segmentation
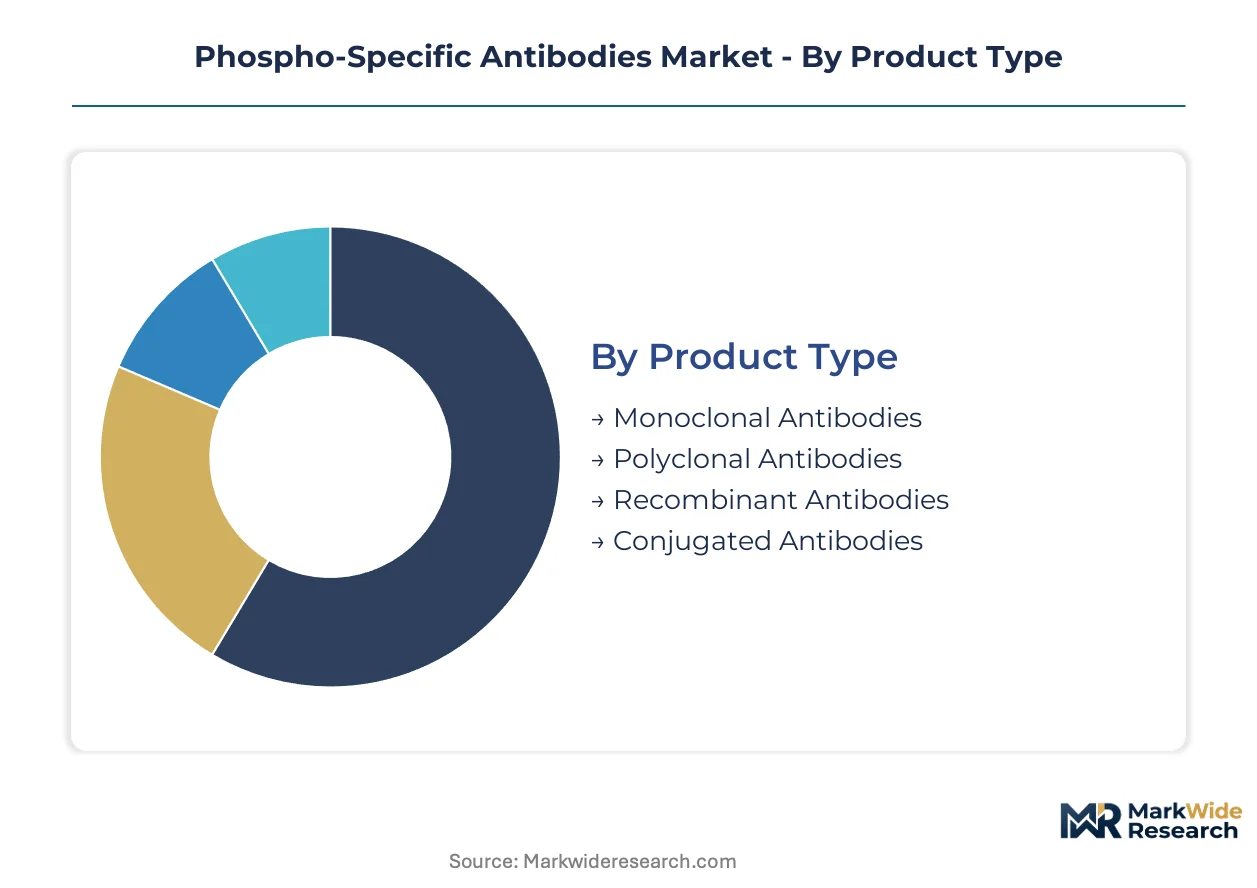
Phospho-specific antibody procurement patterns diverge sharply across research settings, with kinase drug discovery programs demanding validated monoclonal reagents while core facilities prioritize cost-flexible polyclonal alternatives. Segment boundaries in this market reflect tension between regulatory documentation requirements and experimental throughput economics.
Product Type:
Research groups with limited validation budgets gravitate toward different reagent architectures than pharmaceutical quality control departments.
- Monoclonal Antibodies:Defined clonal frameworks deliver batch-to-batch consistency essential for longitudinal kinase inhibitor studies. Boston and San Diego pharmaceutical researchers specify these reagents for regulatory submission packages requiring traceable manufacturing documentation.
- Recombinant Antibodies:Animal-origin-free production systems satisfy tightening FDA guidance on biosafety documentation while compressing development timelines for novel phospho-target specificities. Cell Signaling Technology and specialized catalog providers are sequencing defined frameworks for recombinant manufacturing.
- Polyclonal Antibodies:Heterogeneous serum-derived reagents serve academic core facilities with constrained procurement budgets.
- Conjugated Antibodies:Pre-labeled detection reagents streamline workflow integration for high-throughput screening operations.
Volume sits with monoclonal formats; growth tilts toward recombinant platforms as regulatory agencies tighten traceability mandates.
Application:
Detection methodology selection tracks directly with sample throughput requirements and single-cell resolution needs.
- Western Blotting:Semi-quantitative protein separation remains the foundational phospho-detection workflow for cell lysate analysis. Academic research institutes maintain high procurement volumes for standard immunoblotting protocols.
- Flow Cytometry:Single-cell phosphoprotein analysis enables signaling heterogeneity profiling in immuno-oncology studies. United States research universities are prioritizing suppliers with validated flow cytometry antibody performance databases.
- Immunohistochemistry:Tissue section staining supports companion diagnostic development requiring spatial context.
- ELISA:Quantitative sandwich assays serve pharmaceutical quality control and biomarker validation programs.
Western blotting commands current procurement spend; flow cytometry applications are climbing the fastest as tumor microenvironment research expands.
End User:
Documentation depth and validation rigor separate institutional procurement priorities across the research-commercial spectrum.
- Academic Research Institutes:Budget-constrained investigators prioritize extensive product documentation and transparent cross-reactivity data over premium pricing. Core facilities are consolidating vendor relationships around integrated digital platforms with searchable antibody performance databases.
- Pharmaceutical Companies:Kinase drug discovery pipelines in Boston and San Diego drive volume procurement of pathway-specific reagents with ISO 13485-certified manufacturing controls.
- Biotechnology Firms:Mid-stage developers balance validation requirements with capital efficiency in reagent selection.
- Clinical Laboratories:Diagnostic manufacturers require companion diagnostic-grade antibodies with batch-specific certificates of analysis.
Academic institutes anchor procurement volume; biotechnology firms show steepest expansion trajectory as preclinical pipeline activity intensifies.
Sales Channel:
Relationship depth and technical support availability shape channel preference across customer sophistication tiers.
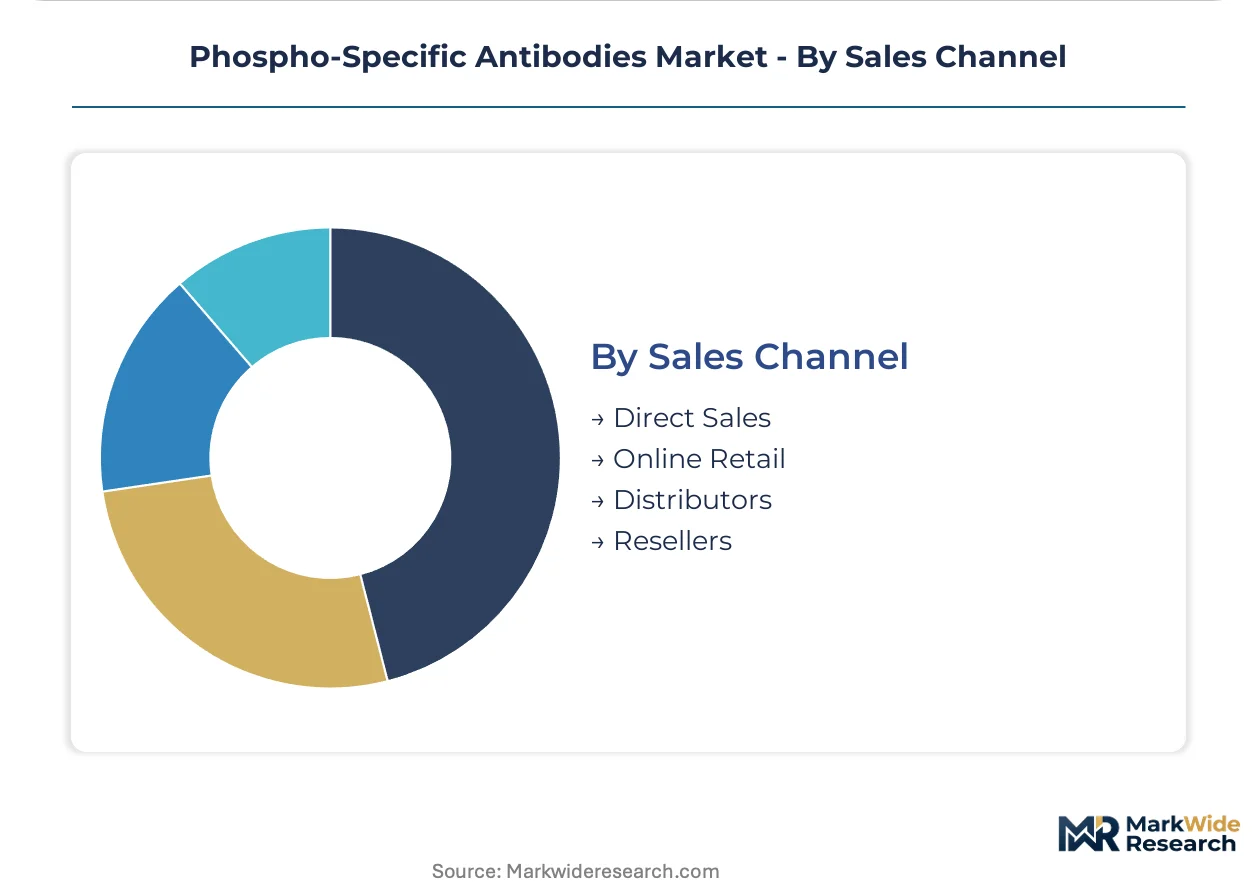
- Direct Sales:Field-based technical specialists serve pharmaceutical accounts with complex validation requirements. Thermo Fisher Scientific leverages direct relationships for reagent availability across multiple continents.
- Distributors:Regional inventory positioning enables rapid fulfillment for academic core facilities with unpredictable project timelines.
- Online Retail:Digital platform reach with extensive product documentation serves researchers prioritizing procurement efficiency.
- Resellers:Secondary channel partners extend geographic coverage in emerging research markets.
Direct sales capture premium-tier pharmaceutical accounts; online retail is gaining share fastest among digitally native research groups.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hybridoma cell lines and phosphopeptide synthesis expertise concentrate in established life science clusters across the United States, Germany, China, Japan, and the United Kingdom. These geographies anchor production capacity while serving distinct regulatory and demand environments for phospho-specific antibody supply.
United States
FDA tightening of antibody validation standards is compressing supplier margins while elevating performance benchmarks across the value chain. Boston and San Diego life science clusters drive volume procurement for kinase drug discovery pipelines. EPA monitoring of hybridoma facility waste streams raises operating costs for monoclonal antibody producers in domestic manufacturing zones.
Germany
REACH compliance deadlines are forcing reformulation of antibody stabilization chemistries for EMA-regulated diagnostic markets. Munich and Heidelberg research institutes prioritize suppliers with ISO 13485-certified manufacturing controls for companion diagnostic development. German preservative restrictions limit stabilization options for antibody shelf-life extension in continental European procurement cycles.
China
Contract research organizations are restructuring phospho-specific antibody production capacity to serve Western biopharma outsourcing needs. NMPA evolving guidance on reagent traceability is accelerating adoption of recombinant antibody platforms. Shanghai and Suzhou manufacturing hubs capture redirected production from cost-optimized supply chain restructuring.
Japan
PMDA quality management standards shape reagent performance expectations for phospho-specific antibody suppliers serving diagnostic manufacturers. Tokyo and Osaka pharmaceutical researchers specify monoclonal reagents for regulatory submission packages requiring documented manufacturing controls. METI support for biotech infrastructure sustains domestic production capacity amid import competition.
United Kingdom
Academic core facilities in Cambridge and Oxford consolidate vendor relationships around integrated digital platforms with searchable antibody performance databases. MHRA alignment with FDA validation standards influences procurement requirements for research reagent distributors. UK research universities prioritize extensive product documentation and transparent cross-reactivity data over premium pricing.
Phospho-Specific Antibodies Market Competitive Landscape
Global majors compete with regional champions across distribution reach and specialized catalog depth in phospho-specific antibody supply. The vendor base stratifies between diversified life science conglomerates with continental logistics networks and focused reagent specialists with pathway-specific expertise. Three archetypes dominate: premium catalog providers with validated monoclonal frameworks, digital platform distributors with extensive documentation databases, and contract manufacturers serving outsourced biopharma production. Competitive moves center on recombinant platform investment and digital validation data monetization as service differentiation.
Among diversified life science conglomerates, Thermo Fisher Scientific leverages global distribution infrastructure to sustain reagent availability across multiple continents. Cell Signaling Technology anchors premium positioning through specialized pathway-specific phospho-antibody catalogs. Abcam competes on digital platform reach, offering researchers extensive product documentation and validation data as baseline procurement requirements.
| Leading Market Players |
|---|
| Abcam |
| Rockland Immunochemicals |
| Thermo Fisher Scientific |
| Bethyl Laboratories |
| Merck MilliporeSigma |
| Cell Signaling Technology |
| GenScript Biotech |
| Creative Diagnostics |
| Bio-Rad Laboratories |
| Others |
Value Network & Pricing Analysis
Phosphopeptide synthesis costs cascade through antibody pricing tiers, with immunogen preparation labor in United States and German facilities commanding premium compensation that concentrates in monoclonal validation packages sold to Boston pharmaceutical researchers, while academic buyers absorb cross-subsidized polyclonal alternatives from distributors with regional inventory positioning.
Pricing Analysis
Batch-specific certificates of analysis and extended validation datasets are unbundled as premium service layers rather than baseline inclusions. Three-tier pricing structure across premium, standard, and economy levels separates ISO 13485-certified manufacturing controls from research-grade documentation and bulk polyclonal serum. Pricing pressure stems from FDA tightening of antibody validation standards compressing supplier margins. Academic core facilities show highest price sensitivity; clinical diagnostic manufacturers absorb premium tier costs for regulatory submission packages.
Supply Chain Analysis
Hybridoma cell line returns and expired reagent refurbishment flows are minimal given biological stability constraints and single-use protocols in phospho-detection workflows. Manufacturing gravity centers on United States, China, and Germany, with Shanghai CROs absorbing redirected Western biopharma production. Supply chains draw from phosphoamino acid chemistries, recombinant expression systems, and affinity chromatography resins. Single-source vulnerability concentrates in qualified immunogen design specialists. Distribution runs through direct field specialists for pharmaceutical accounts and digital platforms for academic procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The phospho-specific antibody market operates as a cost-of-compliance story where FDA guidance on antibody validation standards erects barrier-to-entry moats favoring incumbents with capital-intensive characterization infrastructure.
For Market Incumbents: Acquire recombinant antibody platform capabilities to displace legacy hybridoma dependence as regulatory agencies tighten biosafety documentation requirements. Consolidate digital validation database assets to defend against Abcam's documentation-centric positioning. Capacity addition in Chinese CRO partnerships captures cost-optimized supply chain restructuring demand from Western biopharma. For New Entrants and Emerging Players: Capture flow cytometry phospho-detection workflows in United States immuno-oncology research programs as the most penetrable application segment. Target academic core facilities with searchable antibody performance databases as underserved buyers prioritizing transparency over brand premium. Pursue recombinant platform licensing agreements to bypass phosphopeptide synthesis expertise scarcity. For Investors and Strategic Acquirers: NMPA guidance alignment with FDA traceability standards is the leading indicator that Chinese manufacturing hubs will consolidate export-oriented production capacity. Five-to-ten year viability favors specialized catalog providers with pathway-specific phospho-antibody depth over diversified distributors. Monitor recombinant platform adoption rates in EMA-regulated diagnostic markets as inflection signal for animal-origin-free production dominance.| Strategic Initiative | Industry Significance |
|---|---|
| Recombinant Platform Migration | Animal-origin-free manufacturing satisfies tightening FDA guidance on reagent traceability documentation. |
| Digital Validation Database Buildout | Searchable antibody performance records become baseline procurement requirement for academic core facilities. |
| Chinese CRO Partnership Structuring | Shanghai and Suzhou hubs capture Western biopharma cost-optimized supply chain restructuring. |
| REACH-Compliant Formulation Development | Alternative preservative systems unlock EMA-regulated diagnostic market access. |
| Flow Cytometry Application Expansion | Single-cell phosphoprotein analysis serves immuno-oncology tumor microenvironment research demand. |
Research Methodology
Document review covered FDA guidance filings, ISO 13485 certification registries, and EMA antibody characterization standards, complemented by interviews with antibody development directors at catalog providers, regulatory affairs leads at diagnostic manufacturers, and procurement managers at academic core facilities. Secondary validation drew from SEC 10-K disclosures of diversified life science conglomerates, NIH grant funding databases, and hybridoma facility EPA compliance records. Bottom-up reagent demand modeling and top-down market sizing triangulated volume estimates.
Segment-level value outputs trace procurement patterns across monoclonal, recombinant, polyclonal, and conjugated antibody architectures, Western blotting versus flow cytometry application splits, and academic versus pharmaceutical end-user concentrations. CAGRs were derived from longitudinal procurement trend analysis and kinase drug discovery pipeline scaling assumptions. Forecast inputs incorporated FDA validation timeline projections and Chinese CRO capacity expansion trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory harmonization divergence between FDA and EMA, recombinant platform cost parity achievement, and phosphopeptide synthesis labor market tightening. Practitioners should monitor NMPA traceability guidance implementation, REACH reformulation compliance deadlines, and flow cytometry protocol standardization for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Services
Global Custom Antibody Market
Biotechnology Services
Luciferase Assay Market
Biotechnology Services
Antibody Drug Conjugates Contract Manufacturing Market
Biotechnology Services
Global Qpcr Reagents Market
Biotechnology Services
Immunoassays in R & D Market
Biotechnology Services
Vaccine and Biologic Product Distribution Optimization Services Market
Biotechnology Services
Global Vero Cell Media Market
Biotechnology Services
Custom Assays Market
Biotechnology Services
Bio-Services Market
Biotechnology Services
Biobank Market
Biotechnology Services
Transport Protein Assays Kits Market
Biotechnology Services
GMO Testing Services Market
Biotechnology Services
Biologics CDMO Market
Biotechnology Services
Global Molecular Biology Enzymes and Kits and Reagents Market
Biotechnology Services
Europe Recombinant Protein Manufacturing Services Market
Biotechnology Services
Asia-Pacific Biotechnology Market