
 Global Vero Cell Media Market | 2026-2036
Global Vero Cell Media Market Size, Share, and Industry Trends Forecast 2026-2036
Global Vero Cell Media Market Analysis
The gap between chemically defined and serum-supplemented formulations is narrowing as biomanufacturers prioritize lot-to-lot consistency for regulatory filings. Lonza leverages its integrated media-services portfolio to anchor large-scale vaccine contracts across multiple continents. Biological Industries specializes in serum-free alternatives that reduce supply-chain vulnerability for GMP-grade production. Sigma Aldrich extends its catalog breadth to compete in research-use segments where formulation flexibility commands premium positioning.
Vero cell media comprises nutrient mixtures engineered to support the continuous growth of African green monkey kidney-derived Vero cells, typically containing amino acids, vitamins, inorganic salts, glucose, and buffering systems at pH 7.2–7.4 for adherent or suspension culture platforms. Its primary purpose is to enable high-titer propagation of viruses for vaccine and viral vector manufacturing under serum-free or reduced-serum conditions. Serum-free media commands the dominant margin pool as regulatory agencies tighten scrutiny on transmissible spongiform encephalopathy risks from animal-derived components. Frozen media formats represent the fastest-growing configuration among contract manufacturing organizations seeking to minimize on-site preparation time and contamination exposure. Media for bioproduction applications absorbs the largest volume share as single-use bioreactor adoption simplifies scale-up from seed trains to commercial batches.
FDA guidance on characterization of cell substrates and EMA requirements for adventitious agent testing shape formulation standards and raw-material qualification protocols for Vero cell media suppliers. The EU Green Deal chemical sustainability framework and REACH registration obligations for novel media additives create compliance thresholds that favor established manufacturers with dedicated regulatory affairs teams. Stakeholders must monitor evolving pharmacopoeial standards for serum-free performance benchmarks and decide whether to internalize media production or lock in long-term supply agreements with qualified vendors.
Market Dynamics
Serum-free formulation standardization is compressing supplier margins while locking in long-term vaccine manufacturing contracts for qualified vendors. FDA and EMA guidance on animal-origin-free substrates forces rapid process revalidation across bioproduction facilities.
Growth Catalysts
- EMA adventitious agent testing mandates:European vaccine producers accelerate media qualification cycles to meet batch-release timelines. This tightens vendor selection criteria toward pre-validated serum-free portfolios.
- Single-use bioreactor diffusion:Disposable vessel adoption simplifies scale-up from seed trains to commercial batches. Media suppliers integrate frozen-format offerings to match this infrastructure shift.
- India viral vaccine capacity expansion:CDSCO licensing reforms attract contract manufacturing investment. Local media demand concentrates around GMP-grade serum-free formulations for export-bound production.
Market Restraints
- Raw material qualification costs:Novel chemically defined additives require extensive REACH registration and pharmacopoeial validation. Small suppliers lack capital to clear these compliance thresholds.
- Hydrolysate supply concentration:Plant-derived peptone sourcing clusters in specific agricultural regions. Climate volatility and trade restrictions threaten lot-to-lot consistency for non-synthetic formulations.
- Classical media substitution:Low-cost serum-supplemented alternatives persist in research-use segments. Budget-constrained academic labs delay migration to chemically defined platforms.
Strategic Opportunities
- Brazil vaccine self-sufficiency programs:ANVISA local production incentives create captive demand for regional media formulation facilities. Suppliers establishing São Paulo technical centers capture import substitution flows.
- Continuous processing convergence:Perfusion bioreactor technology intersects with real-time metabolite monitoring. Media developers co-optimize nutrient feed strategies with sensor-integrated control systems.
- EU Green Deal chemical sustainability framework:REACH-registered bio-based media additives qualify for green procurement preferences. Early movers secure preferential supplier status with European public health institutes.
Industry Challenges
- Cell culture scientist scarcity:Specialized expertise in Vero cell line adaptation for suspension platforms commands premium compensation. Contract manufacturers compete with innovator companies for limited talent pools.
- GMP certification timeline compression:FDA pre-approval inspection backlogs delay new media facility qualification. Suppliers must front-load validation documentation to maintain customer production schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Vero Cell Media Market |
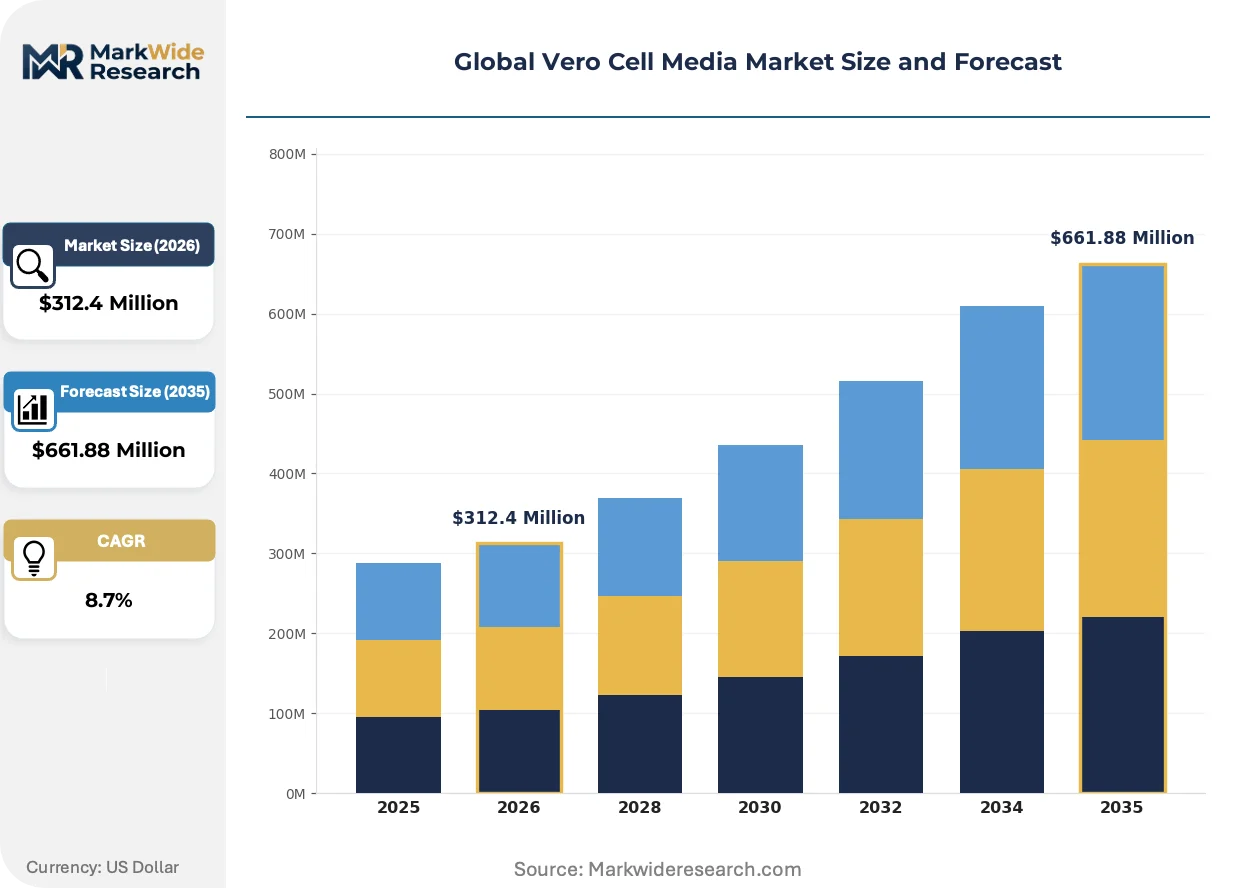
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Serum-Free Media, Supplemented Media, Frozen Media, Media for Bioproduction End User: Biopharmaceutical Companies, Research Institutions, Contract Manufacturing Organizations, Academic Institutions Application: Vaccine Production, Viral Vector Production, Cell Culture, Protein Production Distribution Channel: Direct Sales, Online Sales, Distributors, Retailers |
| Companies Covered | Boster Bio, Hospira Inc, Biological Industries, Serana Bio, Lonza, Sigma Aldrich, Arcomed AG, Terumo Medical Corporation, Mindray Medical International Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Vero Cell Media Market Emerging Trajectories
Frozen media formats and real-time metabolite analytics are compressing preparation timelines while tightening process control. Suppliers now compete on integrated service portfolios rather than standalone formulation catalogs.
Advanced chemically defined media is rendering obsolete classical serum-supplemented formulations in commercial vaccine manufacturing. Contract manufacturing organizations adopt these platforms to minimize lot-to-lot variability for regulatory filings. The technology is rendering obsolete legacy supply chains dependent on fetal bovine serum sourcing.
REACH registration obligations for novel media additives are elevating compliance costs for specialty chemical suppliers. Established manufacturers with dedicated regulatory affairs teams capture market access that newcomers cannot replicate. European vaccine producers prioritize pre-registered additive portfolios to avoid formulation reformulation delays.
Direct long-term supply agreements are displacing spot-market purchasing for GMP-grade media. Large vaccine manufacturers lock in multi-year contracts with qualified vendors to secure capacity and pricing predictability. This concentration is most visible in United States and German production clusters where single-use bioreactor adoption accelerates fastest.
Global Vero Cell Media Market Segmentation
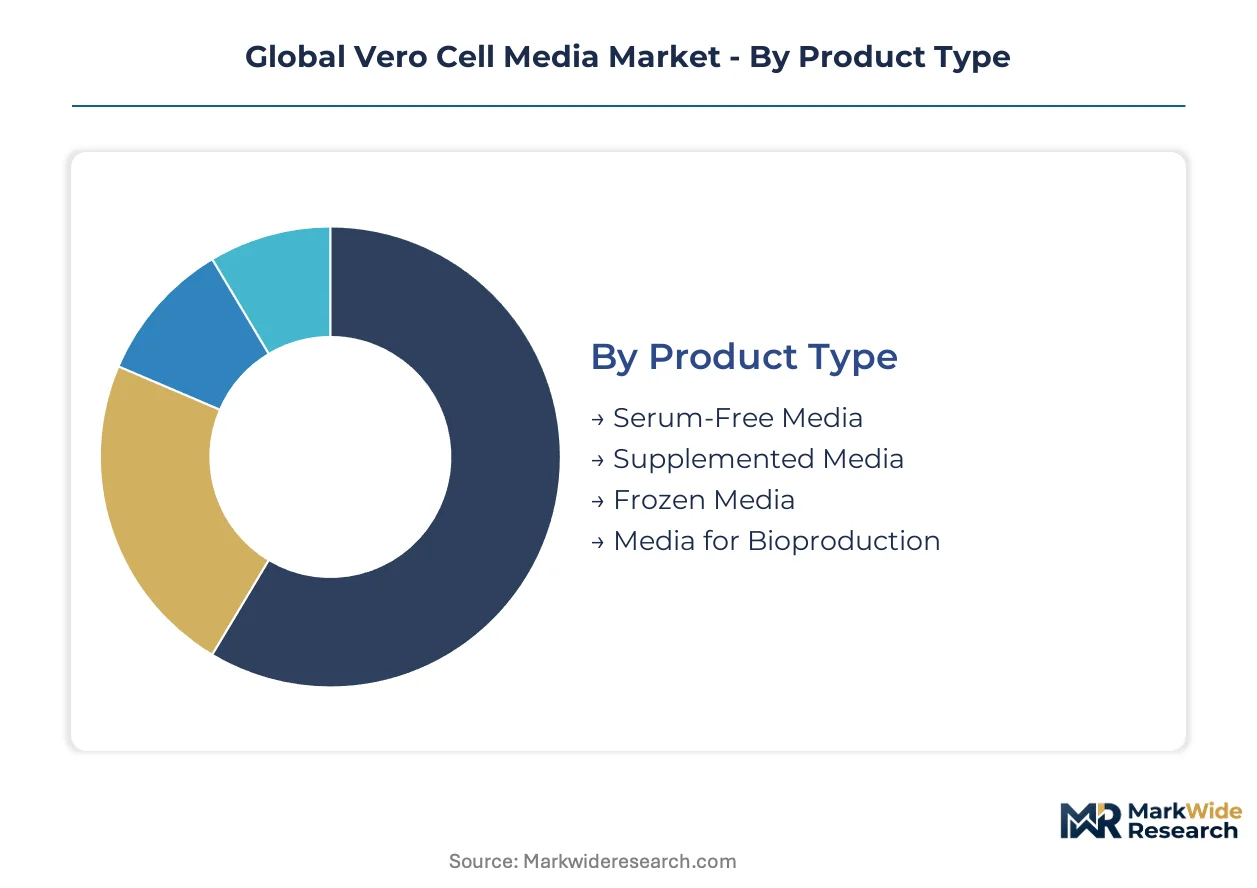
Vero cell media segmentation reflects divergent technical requirements across commercial vaccine manufacturing and exploratory research settings. Formulation complexity, regulatory burden, and scale economics create distinct purchasing behaviors that suppliers must address through targeted portfolio architecture.
Product Type:
Serum-free formulations anchor commercial bioproduction while supplemented alternatives retain footholds in cost-sensitive research environments.
- Serum-Free Media:Chemically defined formulations eliminate fetal bovine serum to satisfy FDA and EMA adventitious agent testing mandates. Large-scale vaccine manufacturers in the United States and Germany prioritize these platforms for regulatory submission consistency.
- Supplemented Media:Classical formulations incorporating serum or hydrolysate derivatives persist in academic and early-stage discovery work. Budget constraints and legacy protocol inertia sustain demand despite regulatory headwinds.
- Frozen Media:Ready-to-use aliquots reduce contamination risk and preparation labor for contract manufacturing organizations operating single-use bioreactor infrastructure.
- Media for Bioproduction:GMP-grade formulations with validated supply chains and documentation packages serve commercial viral vaccine and vector manufacturing.
Established volume favors Media for Bioproduction; emerging adoption favors Frozen Media.
End User:
Purchasing sophistication varies sharply between regulated manufacturers and grant-funded laboratories.
- Biopharmaceutical Companies:Internal media qualification teams audit suppliers against pharmacopoeial standards. Long-term supply agreements with locked pricing dominate procurement strategy for commercial vaccine programs.
- Contract Manufacturing Organizations:Flexible volume requirements and rapid turnaround needs drive preference for pre-qualified frozen formats. CDSCO licensing reforms in India attract CMO investment seeking export capacity.
- Research Institutions:Exploratory cell culture work tolerates higher lot-to-lot variability. Catalog purchasing through distributors accommodates project-specific formulation experiments.
- Academic Institutions:Constrained budgets sustain demand for classical supplemented media despite institutional pressure to reduce animal-derived component use.
Commercial scale concentrates with Biopharmaceutical Companies; flexibility premiums accrue to Contract Manufacturing Organizations.
Application:
Viral propagation applications command formulation precision that protein expression work rarely requires.
- Vaccine Production:Polio, rabies, and COVID-19 vaccines rely on high-titer Vero cell infection. Serum-free platforms enable regulatory filings across United States, European, and Indian health authorities.
- Viral Vector Production:Gene therapy manufacturing demands low-residue media to simplify downstream purification. Suspension-adapted Vero lines require specialized nutrient optimization.
- Cell Culture:Maintenance and expansion of seed trains for bioproduction scale-up. Consistent performance across passage numbers reduces process deviation risk.
- Protein Production:Recombinant protein expression in Vero cells remains niche compared to CHO or HEK platforms. Limited specialized media availability constrains adoption.
Regulatory intensity peaks in Vaccine Production; steepest expansion trajectory appears in Viral Vector Production.
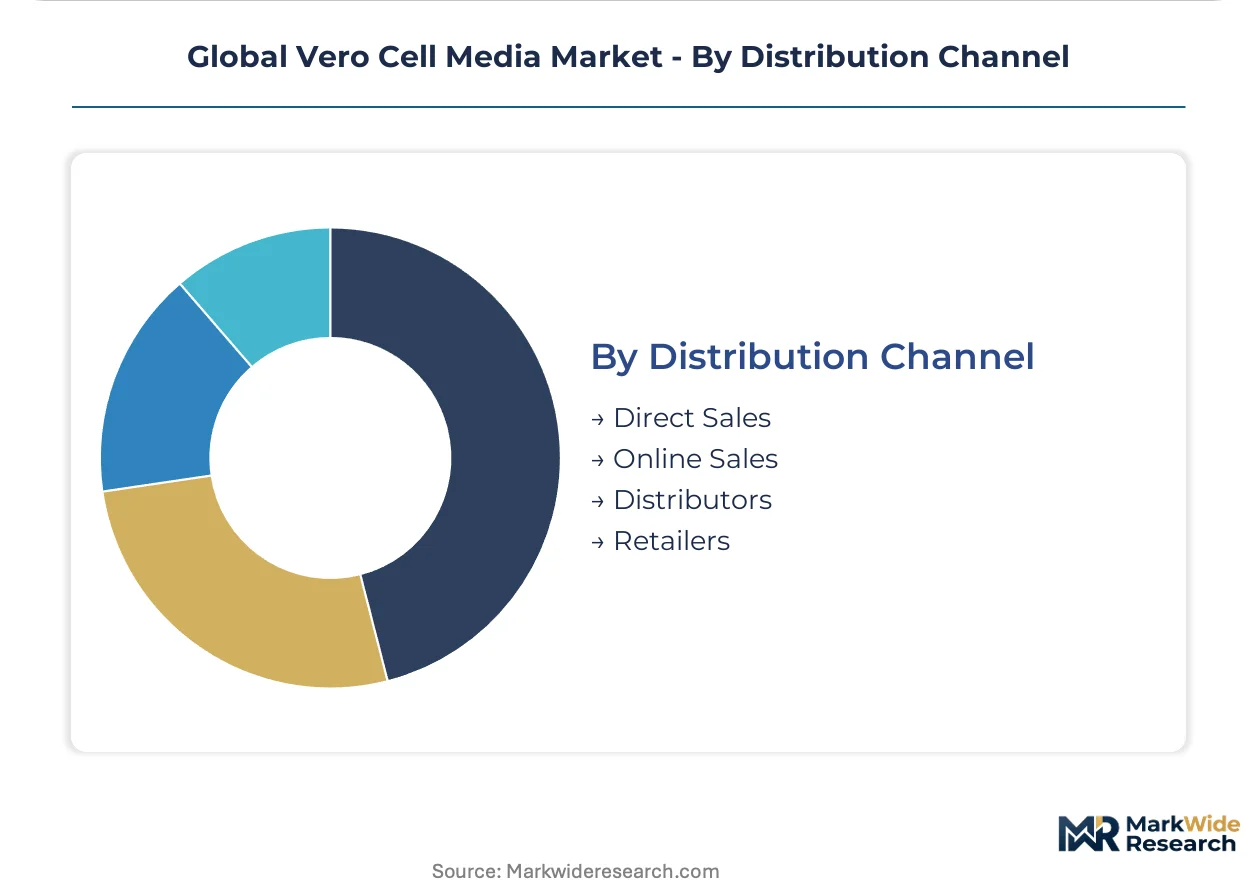
Distribution Channel:
Channel selection tracks order volume, technical support requirements, and geographic proximity to manufacturing sites.
- Direct Sales:Multi-year framework agreements with dedicated account management serve top-tier vaccine manufacturers. Technical service integration includes media customization and on-site troubleshooting.
- Distributors:Regional stocking points accelerate delivery for mid-volume customers. Local language regulatory documentation support differentiates competitive positioning.
- Online Sales:Catalog browsing and rapid ordering suit research-scale purchases. Sigma Aldrich and similar suppliers compete on formulation breadth and technical data accessibility.
- Retailers:Minimal role in Vero cell media given cold-chain requirements and technical specification complexity. Limited to emergency spot purchases in peripheral markets.
Volume concentration favors Direct Sales; geographic coverage expansion favors Distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India exports serum-free Vero cell media formulations to vaccine manufacturers across Southeast Asia and Africa, establishing a critical supply corridor for low-cost GMP-grade bioproduction inputs.
United States
Single-use bioreactor adoption accelerates demand for frozen media formats among Maryland and Massachusetts vaccine producers. FDA guidance on adventitious agent testing mandates pre-validated serum-free portfolios. The Research Triangle Park cluster in North Carolina anchors contract manufacturing investment for viral vector programs.
Germany
EMA batch-release timelines compress media qualification cycles for Bavarian and North Rhine-Westphalian facilities. REACH registration obligations for novel additives favor established suppliers with dedicated regulatory teams. The Heidelberg-Mannheim biotech corridor concentrates gene therapy manufacturing capacity requiring low-residue formulations.
India
CDSCO licensing reforms attract contract manufacturing investment targeting export-bound polio and rabies vaccine production. Serum Institute of India and Bharat Biotech anchor demand for GMP-grade serum-free media in Pune and Hyderabad clusters. Local formulation facilities emerge to capture import substitution flows from European suppliers.
Brazil
ANVISA local production incentives drive captive demand for regional media formulation capabilities. São Paulo technical centers attract suppliers seeking preferential positioning for Latin American vaccine self-sufficiency programs. Butantan Institute expansion anchors public-sector procurement concentration.
Japan
PMDA stringent substrate characterization requirements elevate qualification barriers for imported media formulations. Osaka-Kobe pharmaceutical manufacturing belt prioritizes lot-to-lot consistency for domestic influenza vaccine security. Real-time metabolite monitoring integration differentiates supplier selection for perfusion bioreactor deployments.
Global Vero Cell Media Market Vendor Landscape
Channel-controlling players compete with product-specialist players for procurement contracts across direct sales and distributor networks. The supplier base organizes into three tiers: integrated life science conglomerates with regulatory affairs depth, mid-scale media specialists with serum-free formulation expertise, and catalog distributors serving research-use segments. Consolidation pressure intensifies as vaccine manufacturers lock in multi-year framework agreements. Capacity expansion and geographic licensing partnerships represent the dominant competitive moves.
Within the integrated conglomerate tier, Lonza and Sigma Aldrich occupy positions spanning GMP-grade production and research-scale distribution. Biological Industries exemplifies the serum-free specialist archetype, anchoring formulation innovation for regulatory-compliant vaccine manufacturing. These three entities collectively represent the competitive spectrum from captive supply integration to flexible catalog accessibility.
| Leading Market Players |
|---|
| Boster Bio |
| Hospira Inc |
| Biological Industries |
| Serana Bio |
| Lonza |
| Sigma Aldrich |
| Arcomed AG |
| Terumo Medical Corporation |
| Mindray Medical International Limited |
| Others |
Supply Flow & Price Mechanics
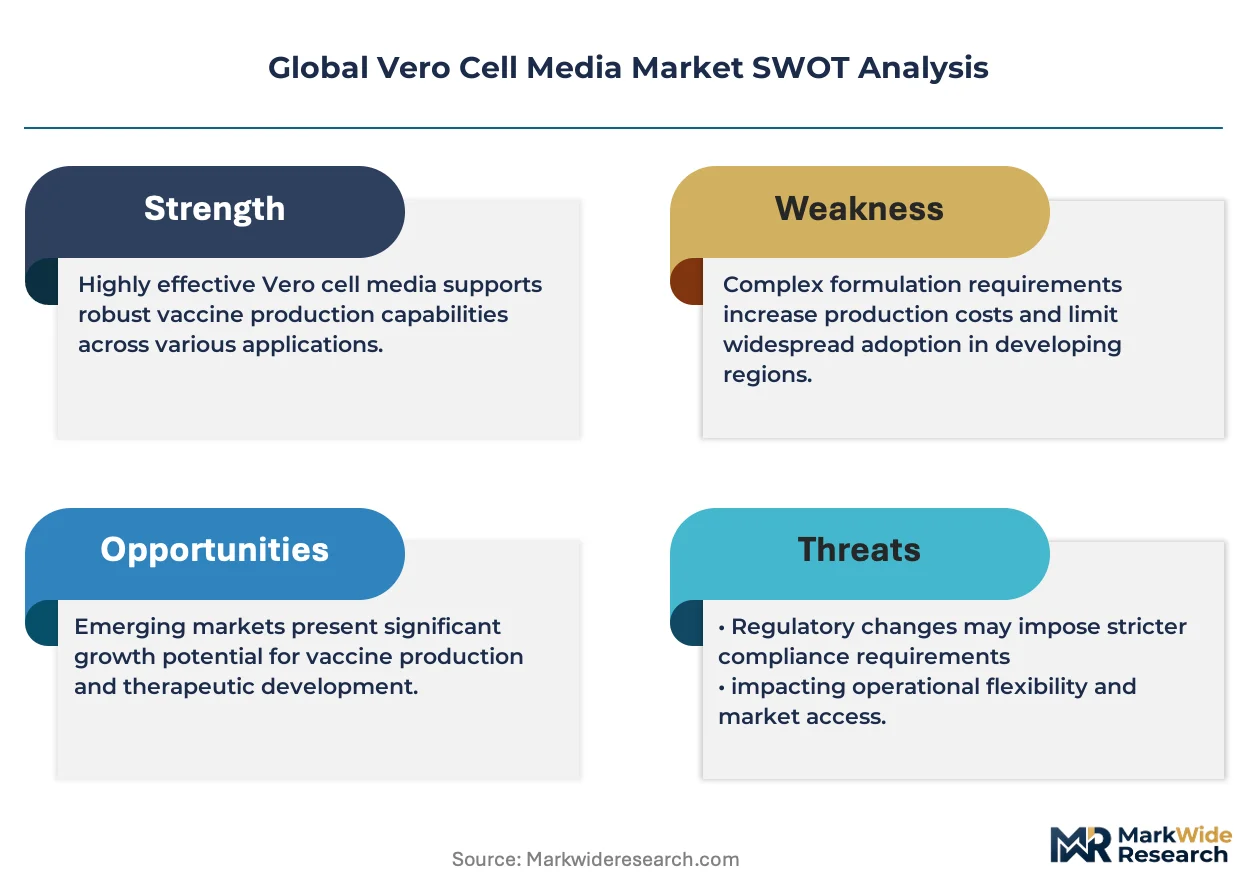
Single-source dependency on plant-derived peptone suppliers in specific agricultural regions determines both the premium commanded by GMP-grade serum-free formulations and the geographic clustering of qualified media manufacturing facilities. FDA and EMA adventitious agent testing mandates compress pricing spreads between tiers while amplifying supply chain qualification costs for novel entrants.
Pricing Analysis
The pricing gap between classical serum-supplemented formulations and chemically defined serum-free alternatives narrows as regulatory compliance costs amortize across larger contract volumes. Pricing stratifies across GMP-certified premium tiers for commercial vaccine manufacturers, validated standard tiers for contract manufacturing organizations, and research-grade economy tiers for academic institutions. Price differentiation hinges on pharmacopoeial certification depth and volume scale commitments. Cost compression in the research-grade tier intensifies because budget-constrained academic labs delay migration to chemically defined platforms. Contract manufacturing organizations exhibit the highest price sensitivity due to flexible volume requirements, while large vaccine manufacturers prioritize supply security over unit cost.
Supply Chain Analysis
Tariff exposure between European REACH-registered additive suppliers and Indian formulation facilities dominates supply chain risk assessment for GMP-grade media. Manufacturing concentrates in the United States, Germany, and India where viral vaccine production capacity expansion anchors demand. Raw material sourcing draws from agricultural peptone suppliers in specific climate-vulnerable regions, chemically defined amino acid manufacturers in Western Europe, and inorganic salt producers in China. Single-source vulnerability in plant-derived hydrolysate supply threatens lot-to-lot consistency for non-synthetic formulations. Distribution runs through direct sales channels for top-tier vaccine manufacturers and regional distributors for mid-volume contract manufacturing organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment creates durable competitive positions. EMA and FDA qualification documentation requirements generate switching costs that lock in incumbent supplier relationships across multi-year vaccine manufacturing contracts.
For Market Incumbents: Insulate market position by deepening backward integration into chemically defined additive manufacturing and expanding frozen-format production capacity in Pune and Hyderabad to capture Indian contract manufacturing growth. Serum-free formulation standardization compresses margins while locking in long-term contracts, making captive supply of critical raw materials essential for margin defense. Prioritize REACH registration maintenance for novel additives to preserve European market access against emerging competitors. For New Entrants and Emerging Players: Build out regional formulation capabilities in São Paulo to capture ANVISA local production incentives driving Brazilian vaccine self-sufficiency programs. The Brazilian market presents the most penetrable geography due to import substitution flows and limited established supplier presence. Target gene therapy viral vector production as the application entry point, where suspension-adapted Vero line expertise remains scarce and real-time metabolite monitoring integration commands premium positioning. For Investors and Strategic Acquirers: EMA adventitious agent testing mandate implementation reshapes the acquisition landscape toward serum-free formulation specialists with pre-validated portfolios. The five-to-ten year viability window favors targets with established regulatory affairs teams and locked multi-year supply agreements with top-tier vaccine manufacturers. Prioritize acquisition candidates with demonstrated perfusion bioreactor nutrient optimization capabilities. Watch CDSCO licensing reform pace in India as the signal for contract manufacturing investment inflection.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Registration Investment | Secures European market access for novel chemically defined additives under EMA scrutiny. |
| Frozen Format Capacity Expansion | Matches single-use bioreactor adoption among contract manufacturing organizations in Maryland and Massachusetts. |
| Regional Formulation Facility Establishment | Captures ANVISA import substitution flows for Brazilian vaccine self-sufficiency programs. |
| Perfusion Bioreactor Co-Optimization | Integrates nutrient feed strategies with real-time metabolite monitoring for gene therapy manufacturing. |
| Long-Term Supply Agreement Lock-In | Secures capacity and pricing predictability with Serum Institute of India and Bharat Biotech. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with cell culture scientists, regulatory affairs leads at vaccine manufacturers, contract manufacturing procurement directors, and GMP facility qualification specialists; and secondary validation against FDA guidance documents, EMA batch-release protocols, CDSCO licensing reform records, and REACH registration databases. Bottom-up triangulation across media volume estimates by formulation type and top-down cross-checks against vaccine production capacity announcements anchored the market sizing framework.
Forecast inputs across the projection horizon incorporated serum-free versus supplemented formulation adoption curves, single-use bioreactor diffusion rates by geography, and regulatory timeline compression effects on media qualification cycles. Segmentation modeling spanned product type, end-user purchasing sophistication, application regulatory intensity, and distribution channel structure. CAGRs were derived from growth driver elasticity analysis calibrated to historical vaccine capacity expansion patterns. Industry-specific inputs included perfusion biorector technology convergence timelines and EU Green Deal chemical sustainability framework implementation pace.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese media suppliers or accelerated REACH reformulation deadlines would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Services
Transport Protein Assays Kits Market
Biotechnology Services
Antibody Purification Service Market
Biotechnology Services
Asia-Pacific Mirna Tools and Services Market
Biotechnology Services
Global High Throughput Screening Market
Biotechnology Services
Global Cell Isolation/Cell Separation Market
Biotechnology Services
DNA and RNA Sample Preparation Market
Biotechnology Services
Phycobiliproteins Market
Biotechnology Services
Riboflavin Kinase Market
Biotechnology Services
Electrophoresis Market
Biotechnology Services
Vaccine and Biologic Product Distribution Optimization Services Market
Biotechnology Services
Custom Assays Market
Biotechnology Services
Research Antibodies and Reagents Market
Biotechnology Services
Global Custom Antibody Market
Biotechnology Services
Antibodies Contract Manufacturing Market
Biotechnology Services
Spain Specialty Enzymes Market
Biotechnology Services
UK Biotechnology and Pharmaceutical Services Outsourcing Market