
 Mrna Therapeutics Contract Development & Manufacturing Market | 2026-2036
Mrna Therapeutics Contract Development & Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Mrna Therapeutics Contract Development & Manufacturing Market Analytics
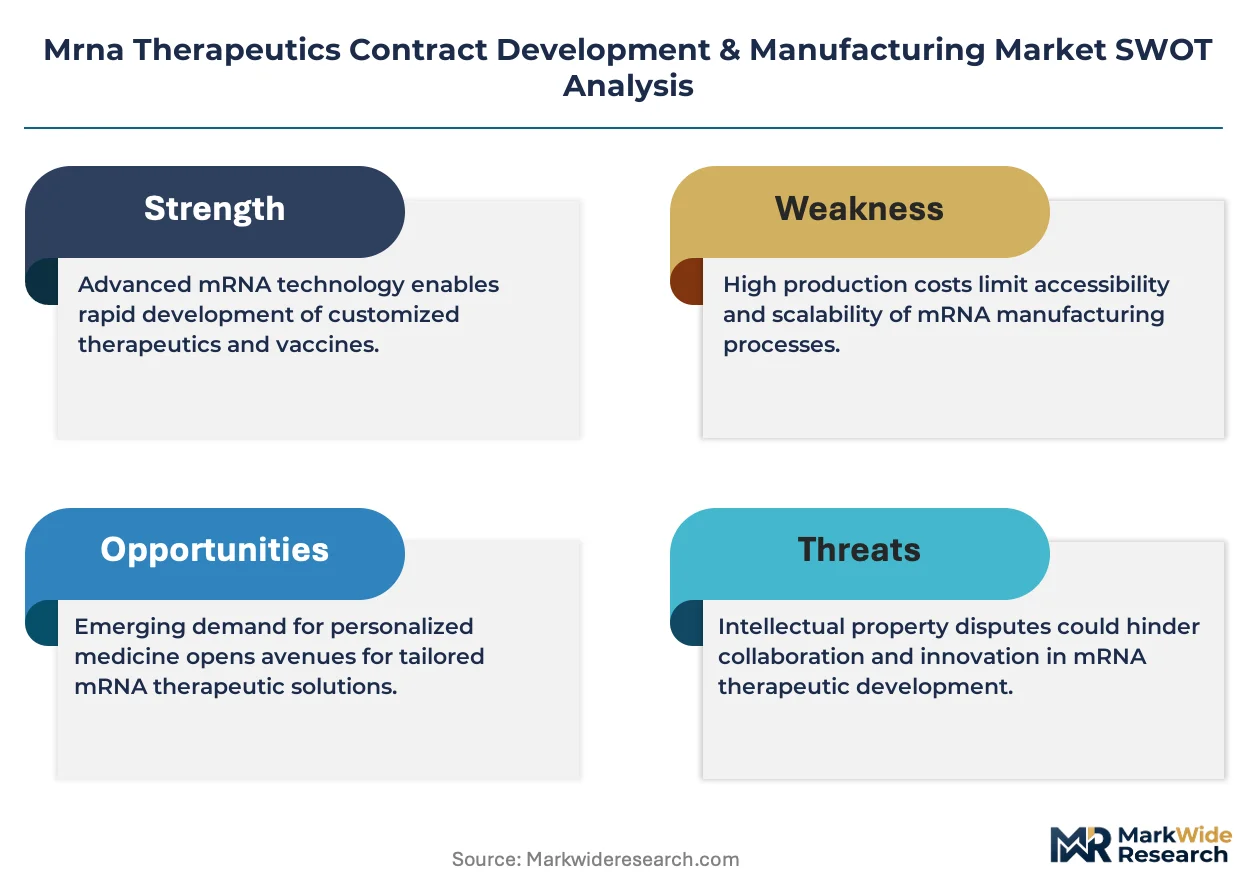
European biotech clusters is recalibrating mRNA CDMO capacity as regional governments fund domestic vaccine sovereignty programs. Thermo Fisher Scientific leverages its integrated analytical-to-commercial platform to anchor multi-product contracts across North American sites. Lonza Group sustains leadership in lipid nanoparticle formulation through dedicated Swiss-based manufacturing lines. Samsung Biologics competes aggressively on Korean peninsula capacity, offering accelerated timelines for late-stage clinical programs.
mRNA therapeutics contract development and manufacturing encompasses the outsourced design, optimization, and GMP production of messenger RNA drug substances and drug products, typically synthesized through in vitro transcription using DNA templates, T7 RNA polymerase, and modified nucleosides to enhance stability and reduce immunogenicity, with the primary commercial purpose of enabling pharmaceutical and biotech developers to access specialized production expertise without building captive facilities. Vaccine manufacturing occupies the largest revenue share within product type segments, reflecting pandemic-era infrastructure investments now repurposed for oncology and infectious disease pipelines. Lipid nanoparticle delivery dominates the delivery mode landscape, though electroporation gains traction in ex vivo cell therapy applications where direct membrane permeabilization proves advantageous. Process development services command premium pricing relative to downstream analytical or scale-up offerings, as early-phase optimization decisions lock in cost structures for commercial campaigns.
FDA oversight through CBER and the Center for Drug Evaluation and Research governs investigational new drug submissions and biologics license applications, while EMA's Committee for Advanced Therapies imposes additional quality benchmarks for gene therapy-aligned mRNA products. The International Council for Harmonisation Q5A-Q5D guidelines and ISO 13485 quality management standards further constrain supplier qualification and batch release protocols across jurisdictions. Stakeholders must monitor how national stockpiling mandates and export restriction frameworks redistribute contract volumes among geographically dispersed manufacturing networks.
Market Dynamics
The mRNA therapeutics CDMO sector faces acute capacity scarcity as developers rush to secure GMP manufacturing slots for personalized cancer vaccines, forcing contract pricing upward and lengthening queue times for late-stage programs.
Growth Catalysts
- Oncology Pipeline Expansion:Biotech firms are advancing mRNA-encoded neoantigen vaccines into Phase 3 trials, requiring dedicated manufacturing partnerships with established lipid nanoparticle capabilities.
- FDA Accelerated Approval Pathways:The CBER breakthrough therapy designation compresses clinical-to-commercial timelines, compelling developers to lock in CDMO capacity earlier in development cycles.
- South Korean Government Subsidies:Seoul's K-Bio Lab initiative funds domestic mRNA infrastructure, attracting foreign biotech sponsors seeking non-US manufacturing alternatives.
Market Restraints
- Specialized Raw Material Concentration:Modified nucleoside suppliers in Germany and Switzerland control critical inputs, exposing CDMOs to single-source vulnerability and price volatility.
- EMA ATMP Complexity:The Committee for Advanced Therapies imposes evolving quality benchmarks for gene therapy-aligned mRNA products, extending qualification timelines for European commercial campaigns.
- Plasmid DNA Bottleneck:GMP-grade DNA template production concentrates among a handful of North American suppliers, constraining upstream throughput for IVT reactions.
Strategic Opportunities
- Japanese Regenerative Medicine Commercialization:PMDA's conditional early approval framework for mRNA cell therapies creates first-mover openings for CDMOs establishing Tokyo-area GMP facilities.
- Self-Amplifying mRNA Formats:saRNA constructs reduce dose requirements tenfold, enabling smaller-batch commercial economics that favor flexible CDMO networks over dedicated captive plants.
- Indian Biosimilar Export Channels:CDSCO's streamlined biosimilar pathway positions Indian manufacturers to supply mRNA starting materials to cost-sensitive vaccine programs across Southeast Asia.
Industry Challenges
- Analytical Method Transfer:Complex potency assays for mRNA integrity and translation efficiency require 12-18 month validation cycles, delaying tech transfers between development and commercial sites.
- Cold Chain Infrastructure:Ultra-low temperature storage requirements for drug substance stability strain existing logistics networks, particularly in emerging markets lacking validated cryogenic distribution.
- Skilled Workforce Scarcity:IVT process engineers with GMP biologics experience command premium compensation, constraining CDMO expansion velocity in competitive labor markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mrna Therapeutics Contract Development & Manufacturing Market |
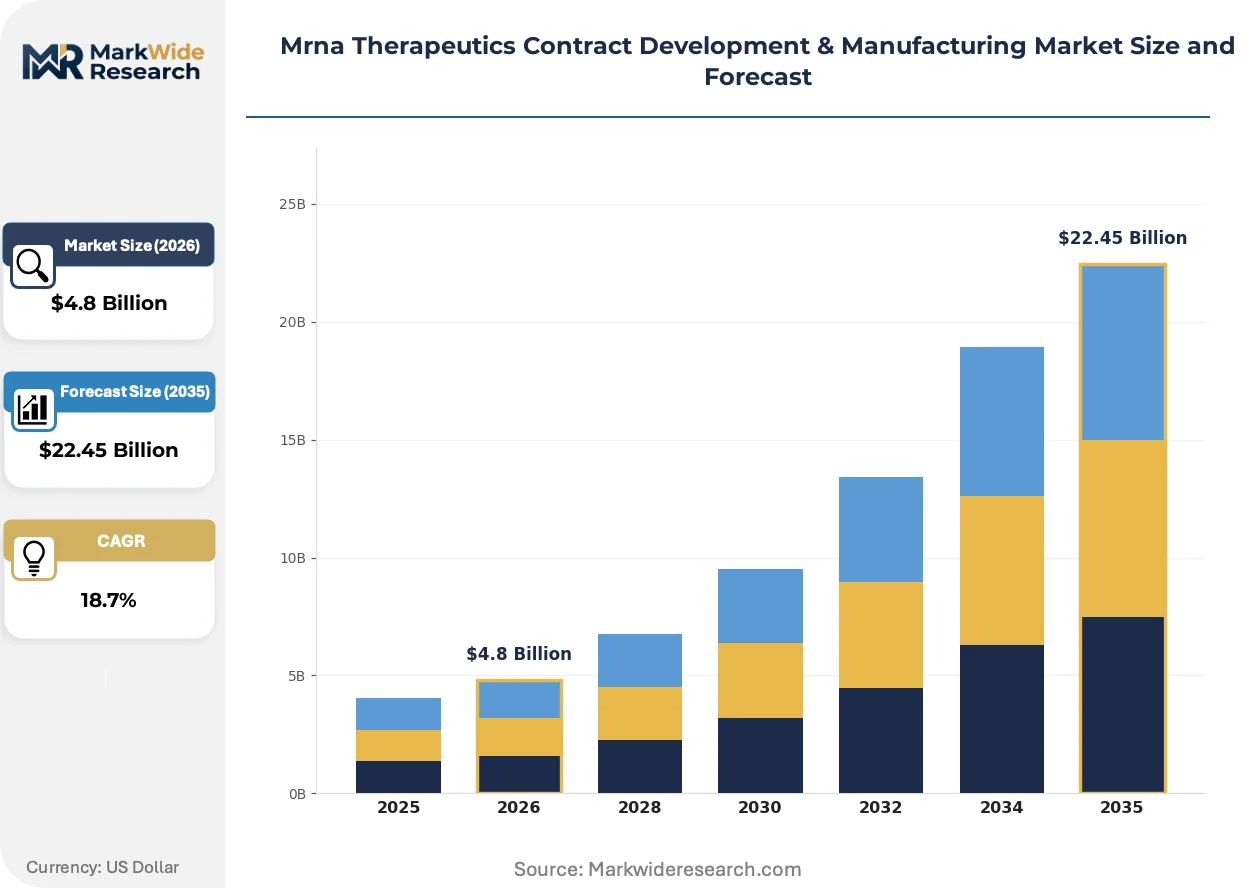
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.45 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vaccine, Gene Therapy, Diagnostic, Therapeutic Delivery Mode: Lipid Nanoparticles, Electroporation, Microinjection, Viral Vectors End User: Pharmaceutical Companies, Biotech Firms, Research Institutions, Contract Manufacturers Service Type: Process Development, Analytical Services, Clinical Manufacturing, Scale-Up |
| Companies Covered | Danaher (Aldevron), Thermo Fisher Scientific, BioNTech SE, Lonza Group, Samsung Biologics, Merck KGaA, WuXi Biologics, Novo Holdings (Catalent, Inc.), Biomay AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mrna Therapeutics Contract Development & Manufacturing Market Evolving Landscape
Continuous manufacturing architectures are displacing batch-based mRNA production, promising yield improvements and reduced facility footprints that reshape capital deployment strategies across the contract manufacturing base.
Automated in vitro transcription systems are integrating real-time process analytical technology to monitor nucleotide incorporation rates and transcript length distributions. Mid-cap biotech sponsors are adopting these platforms for Phase 1-2 campaigns to compress development timelines. The technology is integrating quality-by-design principles that reduce batch failure rates and accelerate regulatory filing preparation.
EMA's revised Annex 1 guidelines on sterile manufacturing impose stricter environmental monitoring requirements for mRNA drug product fill-finish operations. CDMOs serving European markets must upgrade isolator technology and environmental monitoring systems. Oncology-focused developers with pan-European distribution strategies are prioritizing Swissmedic-certified facilities to ensure unified compliance across continental supply chains.
Biotech procurement teams are consolidating vendor relationships under multi-product master service agreements that bundle process development, analytical services, and commercial manufacturing. Large-cap pharmaceutical sponsors are displacing fragmented supplier networks with strategic partnerships spanning five-year horizons. This concentration is most pronounced among US-based immuno-oncology developers seeking guaranteed capacity access for competitive pipeline assets.
Mrna Therapeutics Contract Development & Manufacturing Market Segmentation
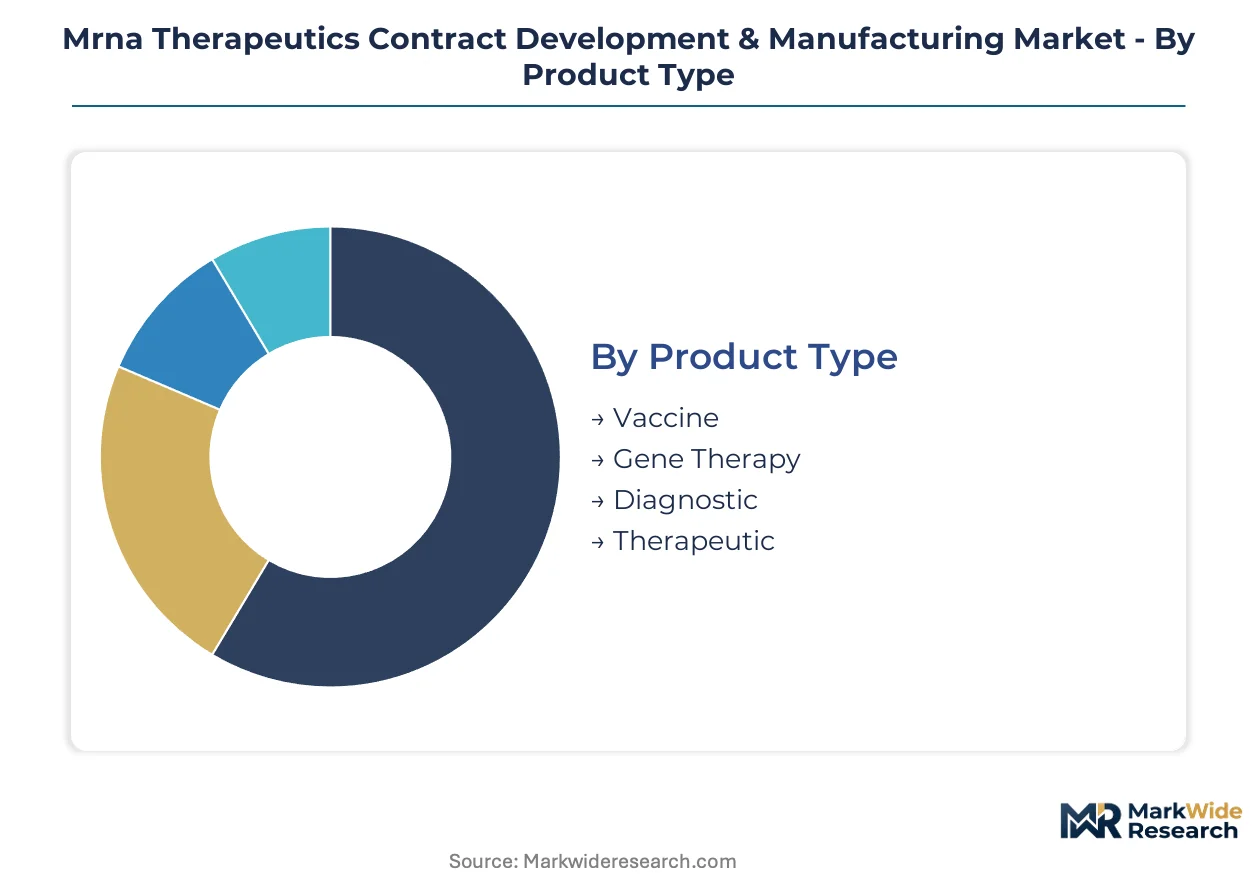
mRNA CDMO procurement decisions cluster around technical capability matching rather than commodity pricing. Developers select partners based on validated platform compatibility with specific therapeutic modalities. The segmentation below maps how supply-side specialization aligns with demand-side program requirements.
Product Type:
Supply concentration for GMP-grade mRNA production capacity varies sharply across therapeutic categories, with pandemic-era infrastructure investments creating uneven availability.
- Vaccine:In vitro transcription processes for prophylactic and therapeutic immunization dominate existing manufacturing footprints. Demand concentrates among US and German biotech firms advancing personalized cancer vaccines, though queue times now extend 18-24 months for Phase 3 campaigns.
- Therapeutic:Protein replacement and gene editing applications require modified nucleoside incorporation rates that strain standard production workflows. Korean CDMOs are capturing rising sponsor interest for these programs through dedicated high-complexity suites.
- Gene Therapy:Ex vivo transfection protocols for hematopoietic stem cell modification.
- Diagnostic:Reference standard and control material synthesis for companion diagnostic development.
Today's leader: Vaccine. Tomorrow's challenger: Therapeutic.
Delivery Mode:
Formulation technology ownership determines margin capture across the CDMO value chain, with lipid nanoparticle expertise commanding premium pricing.
- Lipid Nanoparticles:Ionizable lipid encapsulation systems enable liver-targeted and extra-hepatic distribution of mRNA payloads. Swiss and North American facilities with validated LNP platforms anchor multi-year partnerships with oncology-focused sponsors seeking guaranteed capacity access.
- Electroporation:Electrical membrane permeabilization for ex vivo cell therapy applications eliminates lipid-associated immunogenicity concerns. Japanese developers are integrating this modality into iPSC-derived therapeutic programs under PMDA's regenerative medicine framework.
- Viral Vectors:AAV and lentiviral co-delivery systems for hybrid gene therapy approaches.
- Microinjection:Direct cytoplasmic delivery for research-scale and embryonic applications.
Lipid Nanoparticles anchor current revenue; Electroporation is climbing the fastest as cell therapy pipelines mature.
End User:
Customer scale and internal capability depth shape service bundling preferences across the contract manufacturing base.
- Biotech Firms:Venture-backed developers without captive manufacturing rely on full-service partnerships spanning DNA template synthesis through drug product release. These sponsors prioritize speed over unit cost, accepting premium pricing for dedicated program teams and accelerated timeline commitments.
- Pharmaceutical Companies:Large-cap sponsors with partial internal capacity use CDMOs for surge manufacturing and geographic diversification. Their procurement teams negotiate multi-product master service agreements that bundle analytical and commercial services across five-year horizons.
- Research Institutions:Academic and government laboratories requiring GMP material for investigator-initiated trials.
- Contract Manufacturers:Tier-2 CDMOs subcontracting specialized steps to platform specialists.
Biotech Firms currently drive volume; Pharmaceutical Companies are gaining share fastest as pipeline assets advance to registrational stages.
Service Type:
Margin structure inverts across the development lifecycle, with early-phase process development commanding multiples over downstream manufacturing.
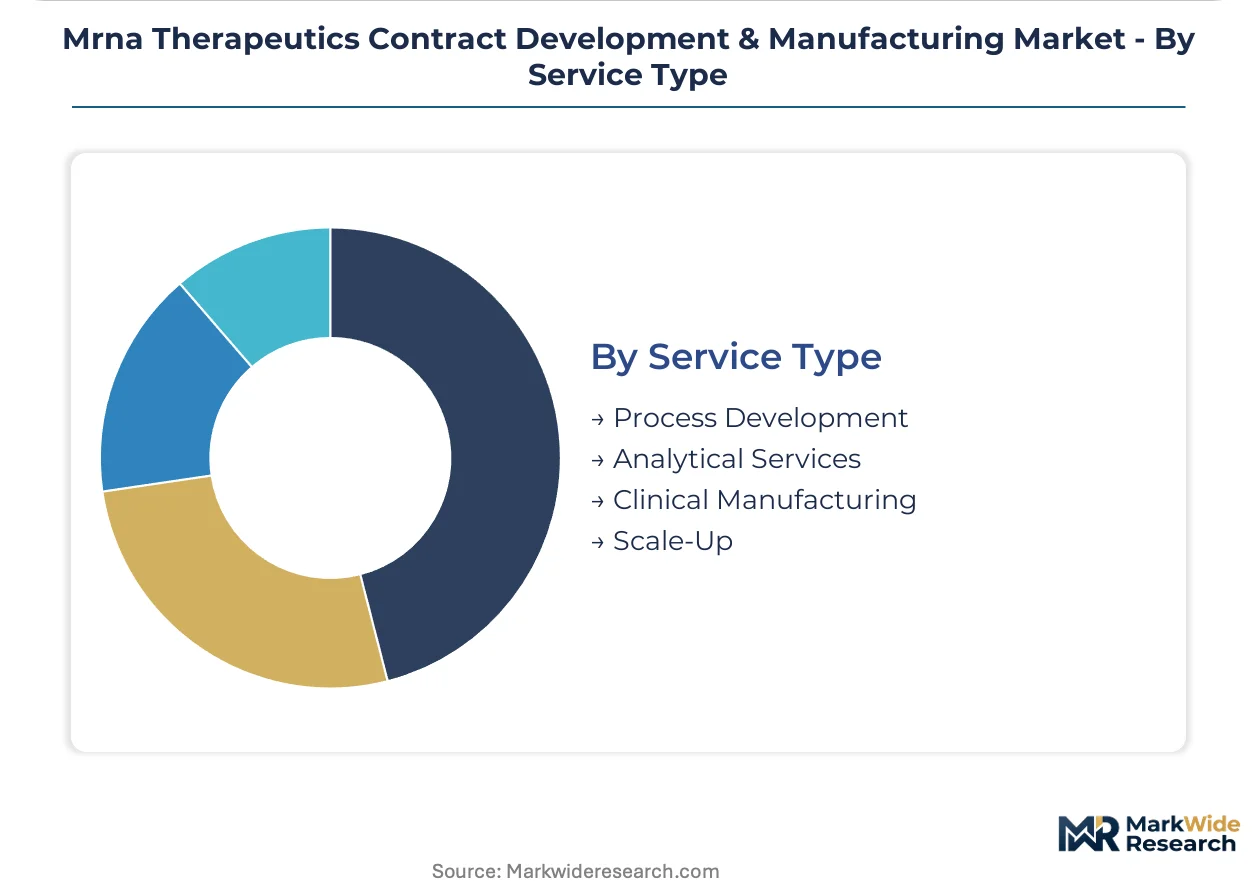
- Process Development:Cell-free IVT optimization, purification scheme design, and formulation screening establish cost structures that persist through commercial campaigns. These services concentrate among CDMOs with dedicated R&D facilities in Massachusetts and Basel, where PhD-level staff density supports complex troubleshooting.
- Analytical Services:Potency assay development, impurity profiling, and stability testing require 12-18 month validation cycles that delay tech transfers. Sponsors are consolidating these activities with manufacturing partners rather than maintaining separate analytical CRO relationships.
- Clinical Manufacturing:GMP batch production for Phase 1-2 supply.
- Scale-Up:Technology transfer and process validation for commercial readiness.
Process Development captures premium pricing today; Analytical Services represent the steepest expansion trajectory as regulatory scrutiny intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and the United States maintain the deepest GMP mRNA manufacturing footprints, though South Korea's government-funded expansion is narrowing the capacity gap for late-stage clinical programs.
United States
FDA breakthrough therapy designations compress clinical-to-commercial timelines for oncology developers, forcing earlier CDMO capacity commitments. The CBER oversees investigational new drug submissions through accelerated pathways. Massachusetts and North Carolina clusters host the densest concentrations of IVT process engineers and lipid nanoparticle formulation specialists.
Germany
Modified nucleoside suppliers in Bavaria and Baden-Württemberg control critical raw material inputs for European mRNA production. EMA's Committee for Advanced Therapies imposes evolving quality benchmarks for gene therapy-aligned products. The Rhine-Main biotech corridor anchors multi-product contract manufacturing for personalized cancer vaccine sponsors.
South Korea
Seoul's K-Bio Lab initiative funds domestic mRNA infrastructure to attract foreign biotech sponsors seeking non-US manufacturing alternatives. The Ministry of Food and Drug Safety aligns with MFDS standards for accelerated clinical trial approvals. The Songdo and Incheon free economic zones concentrate new GMP capacity for late-stage viral and non-viral delivery programs.
Switzerland
Swissmedic certification enables unified compliance across continental European supply chains for oncology-focused developers. The revised Annex 1 guidelines on sterile manufacturing drive isolator technology upgrades at Basel-area facilities. The country's lipid nanoparticle expertise anchors premium-priced formulation partnerships with North American immuno-oncology sponsors.
Japan
PMDA's conditional early approval framework for mRNA cell therapies creates first-mover openings for CDMOs establishing Tokyo-area GMP facilities. METI funding supports regenerative medicine commercialization infrastructure. The Kanto region concentrates academic-industry partnerships for ex vivo electroporation applications in iPSC-derived therapeutic programs.
Mrna Therapeutics Contract Development & Manufacturing Market Competitive Landscape
North American producers anchor one tier; Swiss and Korean specialists hold differentiated positions in formulation technology and accelerated timeline delivery. The vendor base clusters around three strategic archetypes: integrated analytical-to-commercial platforms, lipid nanoparticle formulation specialists, and peninsula-based capacity competitors. M&A activity concentrates among mid-cap CDMOs seeking IVT process capabilities, while greenfield capacity expansion dominates in government-subsidized Asian markets.
Within the integrated platform tier, Thermo Fisher Scientific and Danaher (through Aldevron) exemplify end-to-end service bundling from DNA template synthesis through commercial release. Lonza Group occupies a position among formulation-focused specialists leveraging Swiss-based manufacturing lines for lipid nanoparticle delivery systems. Samsung Biologics represents the scale-driven archetype competing on Korean peninsula capacity with compressed timeline offerings for late-stage clinical programs.
| Leading Market Players |
|---|
| Danaher (Aldevron) |
| Thermo Fisher Scientific |
| BioNTech SE |
| Lonza Group |
| Samsung Biologics |
| Merck KGaA |
| WuXi Biologics |
| Novo Holdings (Catalent, Inc.) |
| Biomay AG |
| Others |
Value Network & Pricing Analysis
Modified nucleoside spot pricing in Bavaria and Baden-Württemberg cascades through three-tier pricing structures across premium, standard, and economy levels, with Swiss and North American CDMOs commanding premiums for validated lipid nanoparticle platforms while Korean peninsula competitors compress margins through government-subsidized capacity.
Pricing Analysis
Direct-to-biotech contracting discounts dominate transactional flows, with premium-mid-economy pricing differentiation anchored in GMP certification tier and analytical capability depth. Cost compression in standard-tier process development is intensifying because mid-cap CDMOs are competing on accelerated timeline commitments. Venture-backed biotech sponsors exhibit lowest price sensitivity, prioritizing dedicated program teams over unit economics, while research institutions and government laboratories drive economy-tier volume.
Supply Chain Analysis
Cryogenic freight costs for ultra-low temperature mRNA drug substance distribution strain logistics networks, particularly for cross-continental movements lacking validated cold chain infrastructure. Upstream concentration in Germany, Switzerland, and the United States for modified nucleosides and GMP-grade plasmid DNA templates creates single-source vulnerability exposure. Distribution runs through hub-and-spoke models centered on Basel, Boston, and Seoul, with regional fill-finish nodes in Songdo and Research Triangle Park reducing last-mile thermal risk.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, with oncology developers now demanding Swissmedic-certified facilities and real-time process analytical technology integration as baseline procurement criteria rather than premium differentiators.
For Market Incumbents: Deploy analytical-to-commercial platform bundling to lock in multi-product master service agreements spanning five-year horizons. Incumbents must secure captive supply of modified nucleoside inputs through backward integration into German and Swiss supplier networks, insulating margin structures from raw material volatility while extending qualification timelines for emerging electroporation competitors. For New Entrants and Emerging Players: Capture Japanese regenerative medicine commercialization opportunities under PMDA's conditional early approval framework for mRNA cell therapies. White-space concentration sits with Tokyo-area GMP facilities serving iPSC-derived therapeutic programs, where ex vivo electroporation protocols eliminate lipid-associated immunogenicity concerns and command premium positioning through academic-industry partnership channels. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap CDMOs possessing validated IVT process capabilities but lacking integrated analytical platforms, as consolidation pressure from large-cap pharmaceutical sponsors favors end-to-end service bundling. Long-term viability hinges on differentiation through continuous manufacturing architectures and real-time quality-by-design systems. The signal to watch is FDA breakthrough therapy designation velocity for personalized cancer vaccine sponsors, which compresses clinical-to-commercial timelines and forces earlier capacity commitment patterns.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Manufacturing Adoption | Yield improvements and reduced facility footprints reshape capital deployment strategies across Basel and Boston manufacturing clusters. |
| Multi-Product Master Service Agreements | Five-year partnership horizons bundle process development, analytical services, and commercial manufacturing for US immuno-oncology developers. |
| Swissmedic Certification Investment | Unified compliance across continental European supply chains becomes mandatory for oncology-focused developers with pan-European distribution. |
| Modified Nucleoside Backward Integration | Captive supply of critical raw materials from Bavarian and Baden-Württemberg suppliers insulates margin structures from single-source volatility. |
| Tokyo-Area GMP Facility Establishment | PMDA's conditional early approval framework for mRNA cell therapies creates first-mover positioning in regenerative medicine commercialization. |
Research Methodology
Bottom-up biotech firm and pharmaceutical sponsor demand modeling reconciled against top-down CDMO capacity and raw material supply tracking forms the analytical core of this study. Primary interviews with drug development executives, regulatory affairs leads, GMP facility managers, and lipid nanoparticle formulation specialists combined with secondary validation against FDA CBER filings, EMA Committee for Advanced Therapies submissions, ClinicalTrials.gov records, and ISO 13485 certification databases. Supply-side triangulation incorporated customs data for modified nucleoside trade flows and MFDS accelerated approval pathway disclosures.
Input-output matrices map IVT process throughput, lipid nanoparticle formulation batch yields, and analytical service capacity against sponsor pipeline stage distributions across the projection horizon. Segmentation dimensions encompass product type, delivery mode, end user scale, and service category, with CAGRs derived from sponsor capital allocation patterns and government funding trajectory analysis. Forecast inputs incorporate K-Bio Lab subsidy disbursement rates and EMA ATMP framework evolution timelines.
Regulatory pathway delays, raw material supply disruptions, and sponsor pipeline attrition are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding CDMO qualification timeline compression and continuous manufacturing adoption velocity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Cell Therapy Market
Cell & Gene Therapy
Genetic Disorder Therapeutics Market
Cell & Gene Therapy
Asia Pacific Cancer Biological Therapy Market
Cell & Gene Therapy
Natural Killer (NK) Cell Therapeutics Market
Cell & Gene Therapy
Global Mrna Therapeutics Market
Cell & Gene Therapy
Gene Panel Market
Cell & Gene Therapy
Stem Cell and Gene Therapy Biological Testing Market
Cell & Gene Therapy
Global Tissue Regeneration Market
Cell & Gene Therapy
NTRK Fusion Gene Positive Advanced Solid Tumor Market
Cell & Gene Therapy
Engineered T Cells Market
Cell & Gene Therapy
US Cell and Gene Therapy Clinical Trial Services Market
Cell & Gene Therapy
Global Duchenne Muscular Dystrophy Treatment Market
Cell & Gene Therapy
Leukemia Therapeutics Treatment Market
Cell & Gene Therapy
Niemann-Pick Disease Type C (NPC) Market
Cell & Gene Therapy
Cellular Reprogramming Tools Market
Cell & Gene Therapy
Sandhoff Disease Therapeutics Market