
 Antibody Production Market | 2026-2036
Antibody Production Market Size, Share, and Industry Trends Forecast 2026-2036
Antibody Production Market Intelligence
The expansion of diverse expression systems beyond traditional mammalian cells, including yeast and transgenic platforms, is fragmenting the once-monolithic production workflow. Thermo Fisher Scientific leverages its comprehensive portfolio of cell culture media and purification tools. Lonza Group specializes in large-scale contract development and manufacturing for global pharmaceutical partners. Sartorius provides critical bioprocessing equipment, such as bioreactors and filtration systems, that underpins modern antibody manufacturing.
Antibody production is the in vitro or in vivo process of generating immunoglobulin proteins that bind to specific antigens. This typically involves culturing genetically engineered host cells, like Chinese Hamster Ovary (CHO) cells, to secrete the desired antibody at high titers. The primary purpose is to manufacture highly specific monoclonal antibodies for therapeutic, diagnostic, and research applications. Monoclonal antibodies dominate the product landscape, while the therapeutics segment, driven by pharmaceutical company investment, forms the largest application area.
Regulatory oversight from bodies like the US FDA, the European Medicines Agency (EMA), and China's NMPA is stringent. These agencies mandate adherence to Good Manufacturing Practices (GMP) and require extensive clinical data on antibody efficacy and safety for market approval. Consequently, navigating the complex regulatory pathway for new biologics remains a critical challenge for developers. Future investment decisions will hinge on balancing the speed of novel production technologies against the established validation of traditional platforms.
Market Dynamics
The central dynamic shaping the antibody production market is the tension between the accelerated discovery timelines offered by novel platforms, like single B cell technologies, and the extensive validation requirements favoring established, high-titer CHO cell-based manufacturing workflows.
Growth Catalysts
- Target Complexity:The maturation of single B cell screening and synthetic biology tools enables the rapid discovery of functional antibodies against previously intractable targets, such as G-protein coupled receptors, expanding the therapeutic pipeline.
- Oncology Demand:A rising global incidence of cancer fuels continuous investment in monoclonal antibody therapeutics, including antibody-drug conjugates and bispecific antibodies, which form the largest and fastest-growing application segment.
- Biologics Infrastructure Investment:Significant government and private sector investment in biologics infrastructure, particularly within biopharmaceutical clusters in the United States, China, and Germany, creates concentrated hubs of production capability and expertise.
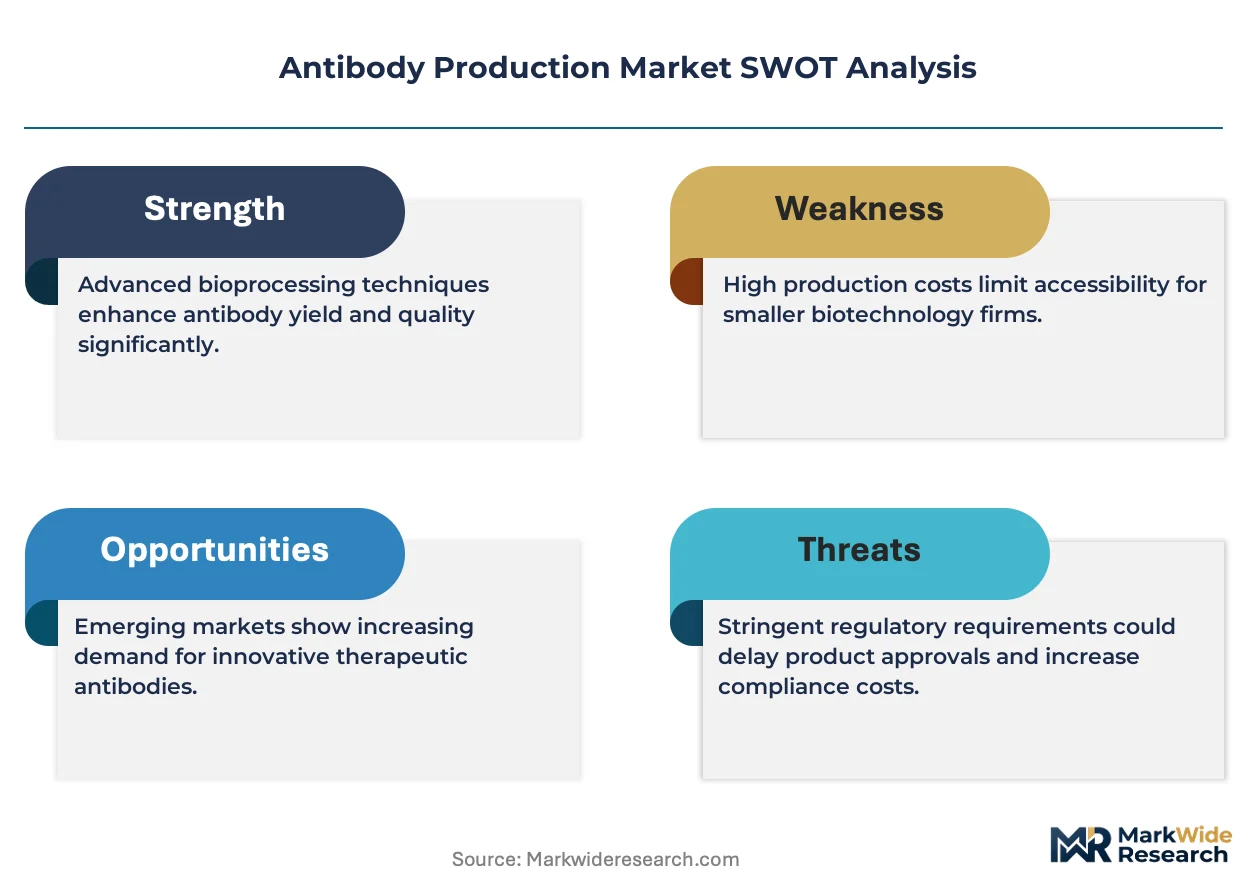
Market Restraints
- Regulatory Hurdles:Navigating the stringent and lengthy approval pathways set by the US FDA, EMA, and China's NMPA for new biologics requires extensive data on safety and efficacy, creating a significant barrier for new entrants.
- Production Costs:The high cost of specialized cell culture media, purification resins, and single-use consumables, combined with the capital-intensive nature of GMP-compliant facilities, constrains profitability and limits scalability for smaller developers.
- Technical Limitations:Achieving consistent high-titer yields and maintaining product quality for complex or difficult-to-express antibodies remains a significant technical challenge, often leading to increased development timelines and manufacturing costs.
Strategic Opportunities
- Alternative Expression Systems:Developing and optimizing non-mammalian expression systems, such as yeast, insect cells, and transgenic plants, offers the potential to significantly reduce production costs and timelines compared to traditional CHO platforms.
- Expansion into Neurology:The application of monoclonal antibodies to treat neurodegenerative diseases like Alzheimer's and Parkinson's represents a substantial area of untapped demand, attracting significant research and development funding.
- Biosimilar Development:As patents for major blockbuster monoclonal antibodies expire, there is a significant opportunity for developing and marketing biosimilar versions, particularly in emerging markets seeking more affordable therapeutic options.
Industry Challenges
- Talent Scarcity:A persistent shortage of skilled personnel with expertise in bioprocess engineering, data analytics for process control, and navigating complex international regulatory submissions hampers project execution and inflates labor costs.
- Intellectual Property Complexity:The dense and often overlapping patent landscape for antibody sequences, cell lines, and manufacturing processes creates a high risk of litigation and requires complex licensing negotiations, delaying product development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antibody Production Market |
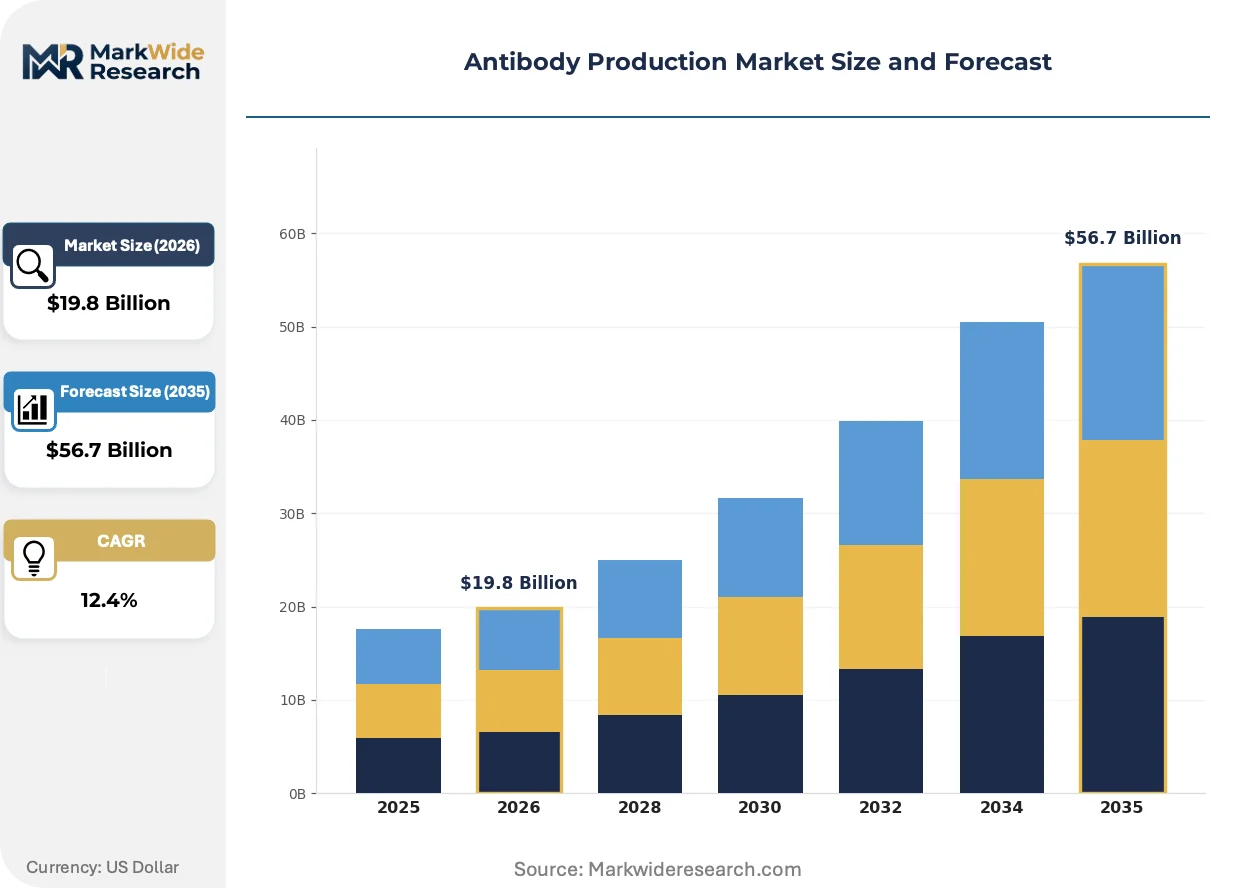
| Market Size in 2026 | $19.8 Billion |
| Market Size in 2035 | $56.7 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Polyclonal Antibodies, Recombinant Antibodies, Bispecific Antibodies, Antibody Fragments Production Technology: Hybridoma Technology, Phage Display, Transgenic Animals, Single B Cell Technology, Yeast Display Application: Therapeutics, Diagnostics, Research, Biosensors, Agriculture End User: Pharmaceutical Companies, Biotechnology Firms, Academic Research Institutes, Contract Research Organizations |
| Companies Covered | Danaher Corporation, Thermo Fisher Scientific, Sartorius, Merck KGaA, Lonza Group, Wuxi Biologics, Charles River Laboratories, AGC Biologics, Eppendorf, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antibody Production Market Strategic Shifts & Innovations
The convergence of advanced analytics and bioprocessing is transforming antibody manufacturing from a series of discrete, empirical steps into a more integrated and predictive system. This shift enables greater process control and accelerates the path from cell line development to commercial production.
Process Analytical Technology (PAT) provides real-time monitoring of critical quality attributes and process parameters within bioreactors. Large biopharmaceutical companies and CDMOs are increasingly implementing PAT to gain deeper process understanding and ensure batch-to-batch consistency. The integration of these real-time data streams with machine learning models is digitizing the entire production workflow, enabling predictive quality control and reducing the risk of costly batch failures.
Regulatory frameworks are evolving to support innovation in biologics manufacturing. The US FDA's advanced manufacturing initiatives, such as the Emerging Technology Program, provide a collaborative pathway for developers to discuss and implement novel production methods like continuous manufacturing. This program reduces regulatory uncertainty for companies investing in next-generation technologies. The cell and gene therapy segment benefits most, as these new platforms are often essential for viable commercial production.
A notable behavioral change is the move toward more flexible manufacturing arrangements to manage pipeline uncertainty. Instead of investing heavily in dedicated, large-scale facilities, many companies now reserve capacity at contract development and manufacturing organizations (CDMOs). This operational strategy is most prominent among venture-backed biotechnology firms in North America and Europe, allowing them to defer large capital expenditures while advancing multiple candidates through clinical trials.
Antibody Production Market Segmentation
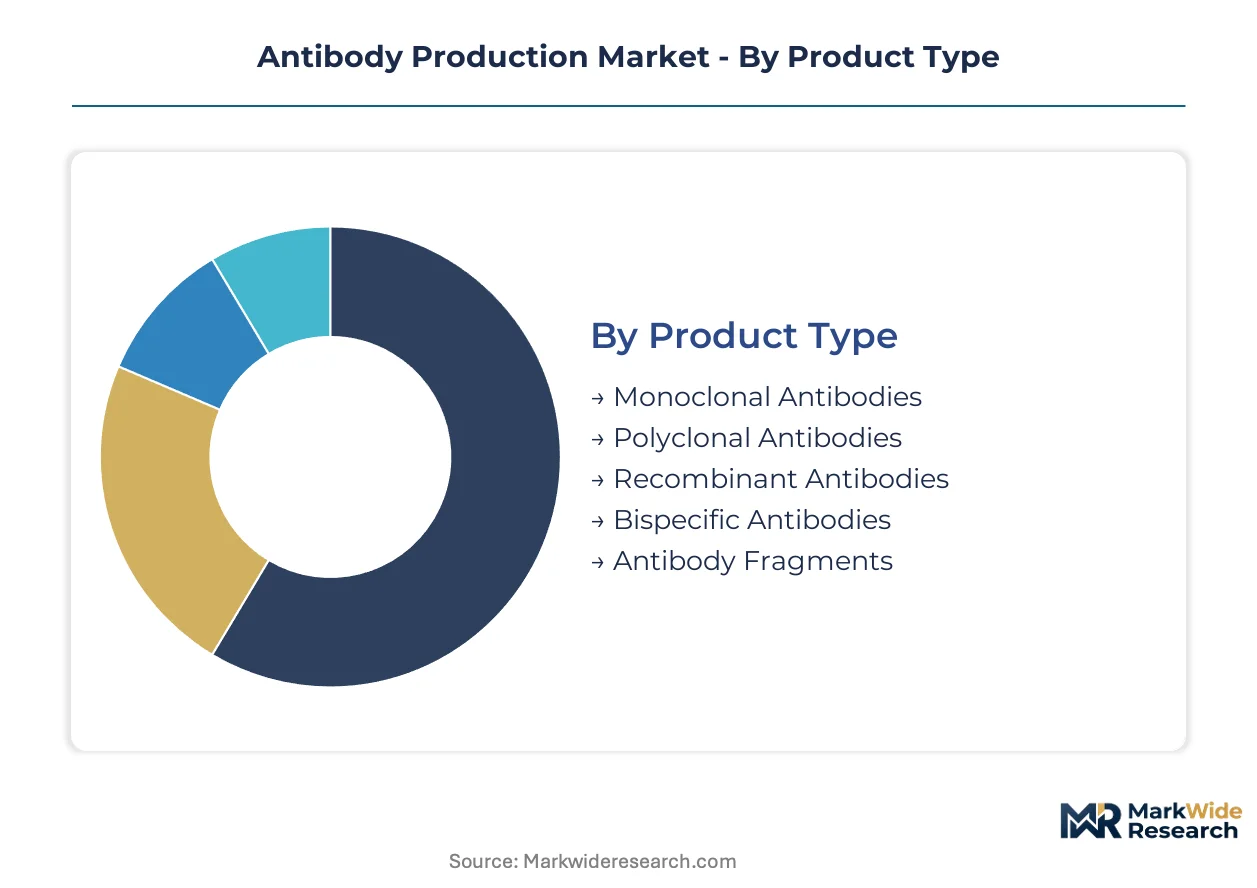
Segmenting the antibody production market reveals distinct pathways for innovation and commercialization. Each segment reflects unique technological demands or end-use requirements. Understanding these divisions helps stakeholders identify areas of concentrated investment and emerging growth opportunities within the biologics industry.
Product Type:
The product type segmentation highlights the maturity spectrum of antibody formats available for therapeutic and diagnostic applications.
- Monoclonal Antibodies:These highly specific antibodies target a single epitope on an antigen, produced from a single B cell clone. Demand concentrates in oncology and autoimmune disease therapeutics due to their precise targeting capabilities and established clinical efficacy.
- Bispecific Antibodies:Engineered antibodies simultaneously bind to two different antigens or two different epitopes on the same antigen. Their development is accelerating in immuno-oncology for redirecting immune cells to tumor targets, particularly in the United States and China.
- Polyclonal Antibodies:A heterogeneous mixture of antibodies derived from multiple B cell clones, recognizing various epitopes on a single antigen. They find use in research applications and some diagnostic assays for their broad reactivity.
- Recombinant Antibodies:Antibodies produced using genetic engineering techniques, allowing for precise control over sequence and structure without animal immunization. This class offers high batch-to-batch consistency for diagnostic kit manufacturing.
- Antibody Fragments:Smaller, engineered portions of antibodies that retain antigen-binding specificity, often improving tissue penetration or reducing immunogenicity. They are explored for targeted drug delivery and imaging agents.
Monoclonal Antibodies retain volume leadership; Bispecific Antibodies hold the steepest expansion curve.
Production Technology:
Production technologies dictate the scalability, cost-efficiency, and complexity of antibody manufacturing workflows.
- Single B Cell Technology:This advanced method isolates and screens individual B cells to identify high-affinity antibody-producing clones, significantly accelerating discovery timelines. Its application is expanding in complex protein targets like G-protein coupled receptors, particularly in European biotech hubs.
- Hybridoma Technology:A traditional method involving the fusion of antibody-producing B cells with myeloma cells to create immortal hybridoma cell lines. It remains a foundational platform for generating monoclonal antibodies used in established diagnostic assays.
- Phage Display:A molecular biology technique where peptides or proteins are expressed on the surface of bacteriophages, enabling rapid screening for antigen-binding antibodies. This technology is crucial for identifying novel antibody candidates in early-stage research.
- Transgenic Animals:Genetically modified animals, typically mice or cows, engineered to produce human antibodies in vivo. This platform offers high-affinity human antibody generation for therapeutic development, reducing immunogenicity concerns.
- Yeast Display:A protein engineering technique utilizing yeast cells to express and screen libraries of antibody fragments on their cell surface. It provides a robust and cost-effective system for antibody affinity maturation and optimization.
Hybridoma technology maintains a foundational role, while Single B Cell Technology demonstrates accelerated adoption for novel antibody discovery.
Application:
Applications for antibodies span critical sectors, driven by their high specificity and versatile binding capabilities.
- Therapeutics:The primary application involves using antibodies as drugs to treat a wide range of diseases, including cancer, autoimmune disorders, and infectious diseases. Pharmaceutical companies are heavily investing in novel antibody-drug conjugates and bispecific antibodies for oncology.
- Diagnostics:Antibodies are integral components in various diagnostic assays, such as ELISA and immunohistochemistry, for detecting specific biomarkers or pathogens. Demand is consistent in clinical laboratories and point-of-care testing across global healthcare systems.
- Research:Antibodies serve as essential tools in fundamental biological research, enabling protein detection, quantification, and functional studies. Academic institutions and biotech firms utilize them for target validation and pathway elucidation.
- Biosensors:Antibodies are integrated into biosensor devices to detect specific analytes with high sensitivity and selectivity, offering real-time monitoring capabilities. This application is emerging in environmental monitoring and medical diagnostics.
- Agriculture:Antibodies are increasingly explored in veterinary medicine for disease prevention and treatment, and in crop protection against pathogens. This segment represents a niche but expanding area of application.
Therapeutics remains the dominant application area, with Diagnostics showing consistent demand across healthcare systems.
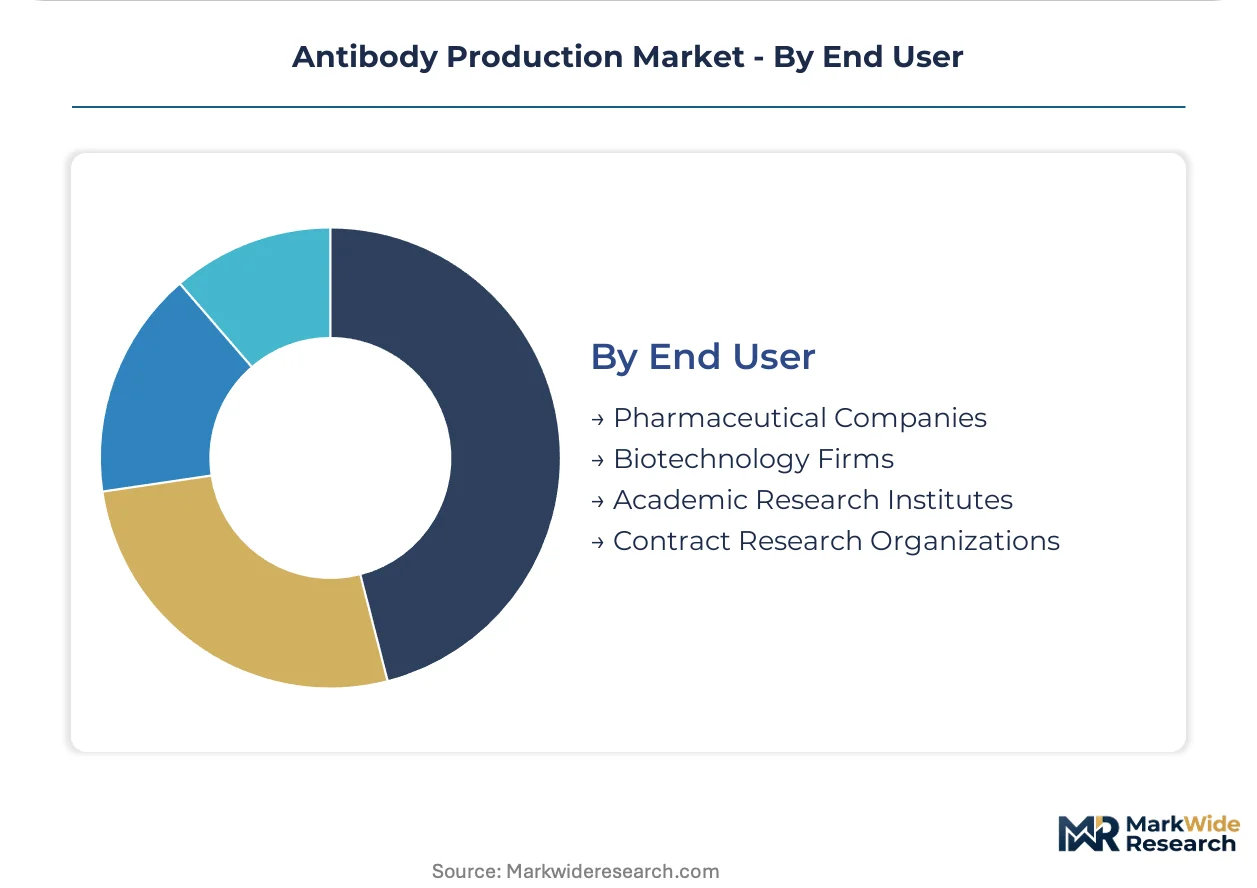
End User:
End-user segments reflect the diverse organizational structures involved in antibody development and commercialization.
- Pharmaceutical Companies:Large corporations that develop, manufacture, and commercialize therapeutic antibodies on a global scale. Their demand for high-titer, GMP-compliant antibody production drives significant investment in contract manufacturing and internal bioprocessing capabilities.
- Contract Research Organizations:Companies offering specialized research services, including antibody discovery, development, and preclinical testing, to pharmaceutical and biotechnology clients. They provide crucial support for pipeline advancement, particularly for smaller firms.
- Biotechnology Firms:Innovative companies focused on developing novel biological products, often specializing in early-stage antibody discovery and preclinical development. These firms frequently outsource large-scale production to CDMOs.
- Academic Research Institutes:Universities and research centers conducting fundamental and applied research involving antibodies for various scientific investigations. Their demand focuses on research-grade antibodies and specialized custom production for novel targets.
Pharmaceutical Companies represent the largest end-user segment, with Contract Research Organizations expanding their service offerings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The trade-flow corridor between established biopharmaceutical hubs in the United States and emerging markets in Asia drives significant demand for antibody production services. This global market sees specialized biologics and advanced manufacturing techniques moving across continents to meet therapeutic needs. Investment in infrastructure and R&D capability underpins regional growth.
United States
Strong demand for novel monoclonal antibodies in oncology and autoimmune diseases fuels production capacity expansion. The US FDA's stringent approval pathways ensure high product quality for therapeutic biologics. Major biopharmaceutical clusters in Boston and San Francisco attract significant venture capital for antibody discovery.
Germany
European demand for advanced biotherapeutics, particularly bispecific antibodies, supports Germany's robust antibody manufacturing sector. The European Medicines Agency (EMA) oversees rigorous GMP standards for biologics produced within the EU. The Munich and Berlin regions host numerous biotech firms specializing in complex protein expression.
China
A rapidly expanding patient base and government initiatives like "Healthy China 2030" drive substantial investment in domestic antibody production. China's NMPA actively streamlines regulatory processes for innovative biologics. Shanghai and Suzhou are emerging as major biopharmaceutical manufacturing and R&D centers.
Japan
High demand for advanced therapies and an aging population contribute to Japan's steady growth in therapeutic antibody development. The Pharmaceuticals and Medical Devices Agency (PMDA) ensures strict regulatory compliance for new biological products. The Tokyo and Osaka regions concentrate biopharmaceutical research institutions and production facilities.
United Kingdom
Increased R&D spending on antibody-drug conjugates and cell therapies boosts the UK's specialized antibody production capabilities. The Medicines and Healthcare products Regulatory Agency (MHRA) maintains high standards for biologics market authorization. The Golden Triangle of Oxford, Cambridge, and London fosters a vibrant biotech ecosystem.
Antibody Production Market Key Industry Players
Channel-controlling players compete with product-specialist players across the antibody production market. The market exhibits a tiered structure, with large, diversified life science companies offering end-to-end solutions alongside specialized contract development and manufacturing organizations. Strategic partnerships between biotechnology firms and large pharmaceutical companies represent a dominant competitive move. Capacity expansion in GMP-compliant facilities further shapes the competitive landscape.
At the scale-driven end of the market, Thermo Fisher Scientific exemplifies comprehensive portfolio offerings, providing essential cell culture media and purification tools across the antibody production workflow. Lonza Group, a Switzerland-based corporation, occupies a position as a leading contract development and manufacturing organization, specializing in large-scale biologics production for global pharmaceutical partners. Wuxi Biologics, a China-based company, anchors the market for large-scale biologics production, particularly for novel antibody therapeutics, leveraging significant investment in advanced bioprocessing capabilities. These companies collectively represent the archetype of integrated service providers and specialized CDMOs.
| Leading Market Players |
|---|
| Danaher Corporation |
| Thermo Fisher Scientific |
| Sartorius |
| Merck KGaA |
| Lonza Group |
| Wuxi Biologics |
| Charles River Laboratories |
| AGC Biologics |
| Eppendorf |
| Others |
Cost & Logistics Intelligence
Under-capacity in GMP-compliant biologics facilities, particularly for complex antibody formats, directly influences supplier behavior and pricing posture. This creates a competitive environment where access to validated manufacturing slots commands a premium, impacting both development timelines and overall project costs.
Pricing Analysis
Cost-plus contract models, often indexed to specialized raw material costs and labor rates, dominate large-scale antibody manufacturing. The pricing structure is heavily influenced by GMP compliance and the level of customization required for novel antibody formats. Upward pricing pressure stems from the high cost of specialized cell culture media and purification resins. Small biotech firms exhibit higher price sensitivity, whereas large pharmaceutical companies prioritize reliable capacity and quality assurance over marginal cost savings.
Supply Chain Analysis
Single-source vulnerability for highly specialized cell culture media and purification resins presents a significant structural risk in the antibody production supply chain. Production capability concentrates in the United States, China, and Germany, reflecting major infrastructure investments. The supply chain sources critical inputs such as chemically defined cell culture media and chromatography resins. Downstream distribution primarily runs through contract development and manufacturing organizations (CDMOs) to pharmaceutical clients globally.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a high-growth disruption, driven by the maturation of single B cell technology accelerating antibody discovery timelines. Strategic positioning is critical for all stakeholders navigating this evolving landscape.
For Market Incumbents: Harden existing large-scale mammalian cell production capabilities through significant investment in Process Analytical Technology (PAT). Expand GMP-compliant CDMO capacity in established biopharmaceutical clusters to counter pipeline uncertainty from smaller biotechs. This defends against margin erosion from novel, potentially lower-cost alternative expression systems. Leverage R&D into continuous manufacturing to optimize existing workflows.
For New Entrants and Emerging Players: Build out expertise in alternative expression systems like yeast or transgenic plants to offer cost-effective production for biosimilars. Target the neurology application segment, which remains largely untapped and attracts significant R&D funding. Biosimilar development for emerging markets represents the most penetrable segment due to demand for affordable therapies. Position offerings on speed-to-market and reduced production costs.
For Investors and Strategic Acquirers: Capital is best deployed toward specialized contract development and manufacturing organizations (CDMOs) with validated expertise in novel antibody formats. This market demonstrates strong long-term viability over the next decade due to sustained demand for biologics. Acquisition targets should focus on firms with robust IP portfolios in advanced bioprocessing technologies. Watch for increased regulatory approvals for continuous manufacturing platforms as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Expanding GMP capacity enables meeting rising global demand for monoclonal antibody therapeutics. |
| Regulatory Approval Pathway | Navigating stringent US FDA and EMA requirements accelerates market access for novel biologics. |
| Pipeline Diversification | Investing in bispecific antibodies and ADCs reduces reliance on traditional monoclonal antibody portfolios. |
| Platform Integration | Integrating Process Analytical Technology (PAT) enhances real-time process control in bioreactors. |
| Joint Venture | Partnering with biotech firms allows access to novel single B cell discovery technologies. |
Research Approach
The analysis maps antibody product types and production technologies, each validated through extensive interviews with bioprocess engineers and regulatory affairs specialists. This combines primary insights from R&D directors and procurement leads with rigorous secondary validation. Secondary data sources include US FDA filings, European Medicines Agency reports, company annual statements, and scientific literature. A bottom-up and top-down triangulation approach ensured data consistency and market sizing accuracy.
Assumptions regarding the stability of regulatory frameworks and continuous technological advancements were held constant across the analysis window. The analytical framework modeled segmentation dimensions including product type, production technology, application, and end-user. Compound Annual Growth Rates were derived using regression analysis on historical and projected market data. Industry-specific inputs included pharmaceutical R&D spending and clinical trial success rates for novel biologics.
The forecast holds incumbent behavior within observed patterns; aggressive moves by large pharmaceutical companies or leading CDMOs would shift outcomes. Unexpected regulatory changes or breakthrough alternative technologies represent key risk factors that could revise projections. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Drug Resistant Pulmonary Tuberculosis Market
Biopharmaceuticals
Global Blood Product Market
Biopharmaceuticals
Global Recombinant Proteins Market
Biopharmaceuticals
Global Resistant Pseudomonas Aeruginosa Infections Drugs Market
Biopharmaceuticals
Anti-Neoplastic Pharmaceutical Agents Market
Biopharmaceuticals
Human Insulin Drugs Market
Biopharmaceuticals
Amphotericin B Market
Biopharmaceuticals
Compounded Bioidentical Hormone Therapy Market
Biopharmaceuticals
North America Monoclonal Antibody Market
Biopharmaceuticals
Glucagon Injectable Market
Biopharmaceuticals
Vaccine Ampoules Market
Biopharmaceuticals
NF-KB Inhibitors Market
Biopharmaceuticals
Macrolide Antibiotics Market
Biopharmaceuticals
Triptorelin Market
Biopharmaceuticals
Global Lenalidomide Market
Biopharmaceuticals
Global Kinase Inhibitors Market