
 Antibody Discovery Market | 2026-2036
Antibody Discovery Market Size, Share, and Industry Trends Forecast 2026-2036
Antibody Discovery Market Analysis
The EU Green Deal's pharmaceutical sustainability package is recalibrating how contract research organizations qualify their discovery supply chains. GenScript Biotech Corporation leverages its integrated gene-to-antibody platform to anchor large-molecule programs for European clients navigating REACH-aligned chemical disclosure rules. Charles River Laboratories dominates North American toxicology-integrated antibody discovery with its captive vivarium network and GLP-compliant screening infrastructure.
Antibody discovery encompasses the systematic identification and optimization of immunoglobulin sequences capable of binding specific antigens, typically employing phage display libraries with diversities exceeding 10^10 variants or transgenic animal platforms expressing human immunoglobulin loci. Its primary commercial purpose is generating therapeutic and diagnostic ligands with defined affinity, specificity, and developability profiles. Monoclonal antibodies occupy the largest value pool given their established manufacturing scalability and regulatory familiarity, while bispecific antibodies represent the fastest-expanding technology segment as oncology developers pursue simultaneous dual-target engagement. Phage display and next-generation sequencing together are displacing legacy hybridoma workflows in early-stage campaigns where timeline compression determines competitive positioning.
FDA's Investigational New Drug application requirements and EMA's Good Manufacturing Practice Annex 2 guidelines for biological active substances jointly shape antibody lead selection criteria, forcing earlier developability assessments before candidate nomination. China's NMPA alignment with ICH Q5D through its updated technical guidelines for recombinant DNA products is opening parallel filing strategies for discovery-stage assets. Stakeholders must monitor how emerging AI-driven epitope prediction tools interact with existing regulatory validation expectations for complementarity-determining region characterization.
Market Dynamics
The FDA's accelerated approval pathways for biologics are compressing antibody discovery timelines from years to months, forcing contract research organizations to reconfigure their screening architectures around higher-throughput platforms.
Growth Catalysts
- Oncology therapeutic expansion:Pharmaceutical companies are expanding their outsourced antibody generation programs as internal pipelines face capacity constraints. Bispecific antibody demand for dual-target engagement in solid tumors is pulling discovery capacity toward complex formats.
- REACH-aligned chemical disclosure:The EU Green Deal's pharmaceutical sustainability package is recalibrating how European contract research organizations qualify their discovery supply chains. GenScript Biotech Corporation leverages its integrated gene-to-antibody platform to anchor large-molecule programs for clients navigating these rules.
- Phage display maturation:Library diversities exceeding 10^10 variants are displacing legacy hybridoma workflows in early-stage campaigns where speed determines competitive positioning. Next-generation sequencing integration is collapsing the time between panning and lead identification.
Market Restraints
- Transgenic animal platform concentration:Supply of human immunoglobulin loci-expressing rodents concentrates among a handful of captive breeding facilities. Any disruption to these specialized vivarium networks propagates directly into client program delays.
- GLP toxicology infrastructure scarcity:Charles River Laboratories dominates North American toxicology-integrated antibody discovery through its captive vivarium network. This concentration limits price competition and extends queue times for IND-enabling studies.
- Developability assessment cost inflation:Forced earlier candidate characterization under FDA and EMA guidelines is adding non-billable overhead to discovery contracts. Aggregation propensity, immunogenicity prediction, and manufacturability scoring now precede nomination decisions.
Strategic Opportunities
- China parallel filing strategies:NMPA alignment with ICH Q5D through updated technical guidelines for recombinant DNA products is opening simultaneous development tracks. Discovery-stage assets can now enter Chinese and Western regulatory pathways without sequence modification.
- AI-driven epitope prediction:Machine learning tools for complementarity-determining region characterization are converging with next-generation sequencing data. This technology pairing creates new service layers around rational immunogen design and in silico affinity maturation.
- Diagnostic ligand diversification:Immunoassay developers are expanding beyond therapeutic antibodies into specialized diagnostic binders with defined specificity profiles. Companion diagnostic co-development agreements represent a channel innovation for discovery providers.
Industry Challenges
- Hybridoma-to-display workflow migration:Technical staff trained in classical fusion-based monoclonal generation require retraining in phage display library construction and bioinformatics interpretation. Talent scarcity in next-generation sequencing data analysis is constraining platform expansion.
- CDR characterization validation:Emerging AI prediction tools are outpacing regulatory validation frameworks for complementarity-determining region documentation. Stakeholders must reconcile computational outputs with existing FDA and EMA expectations for structural characterization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antibody Discovery Market |
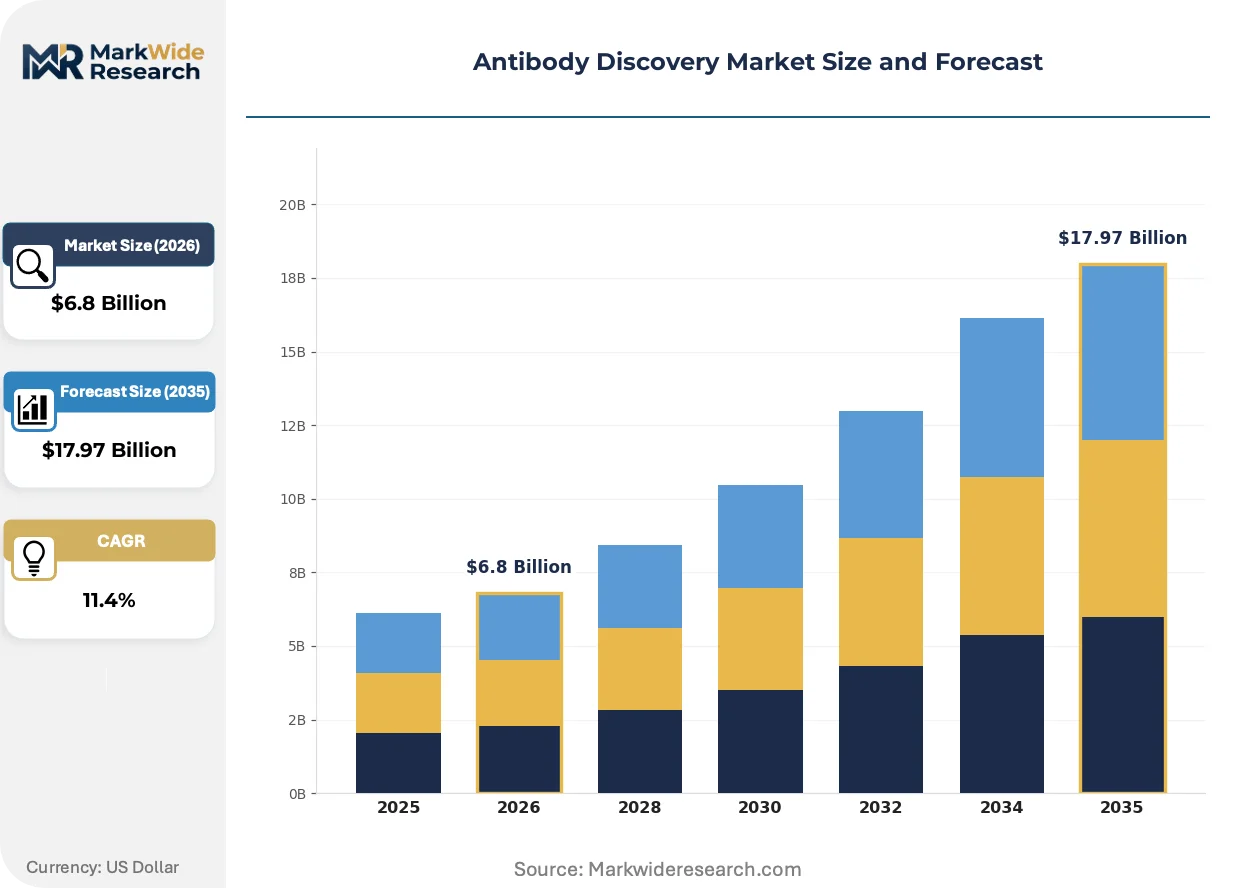
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Polyclonal Antibodies, Antibody Fragments, Bispecific Antibodies Technology: Phage Display, Hybridoma Technology, Transgenic Animals, Next-Generation Sequencing Application: Drug Development, Diagnostic Testing, Research, Therapeutic Applications End User: Pharmaceutical Companies, Biotechnology Firms, Academic Institutions, Contract Research Organizations |
| Companies Covered | GenScript Biotech Corporation, Absolute Antibody, Charles River Laboratories, Twist Bioscience, Creative Biolabs, Biocytogen Pharmaceuticals, WuXi AppTec, Sino Biological, Sartorius AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antibody Discovery Market Emerging Trajectories
Antibody discovery is undergoing platform consolidation as sequencing costs collapse and computational prediction tools mature, compressing the traditional gene-to-lead pipeline into integrated workflows.
Single-cell B-cell receptor sequencing is overtaking bulk repertoire analysis as the dominant input for therapeutic antibody mining. Biotech firms in Boston-Cambridge and San Francisco Bay Area clusters are adopting this technology at pace, replacing hybridoma rescue with direct native pairing of heavy and light chains. This shift is enabling access to rare antigen-specific clones that bulk methods miss while collapsing the timeline from immunization to validated binder.
EMA's Good Manufacturing Practice Annex 2 guidelines for biological active substances are forcing earlier developability assessments into discovery contracts. The industrial consequence is upstream integration of bioprocess simulation and forced degradation studies before candidate nomination. Oncology programs with accelerated approval designations are most affected, responding by embedding cell line development scientists within discovery teams.
Buyer concentration among top-20 pharmaceutical companies is reshaping contracting structures for antibody discovery services. These sponsors are consolidating vendor panels and demanding platform exclusivity arrangements that lock out competitors from the same transgenic animal or phage display library. This pattern is most visible in United States therapeutic antibody procurement, where three sponsors now account for the majority of outsourced large-molecule discovery spend.
Antibody Discovery Market Segmentation
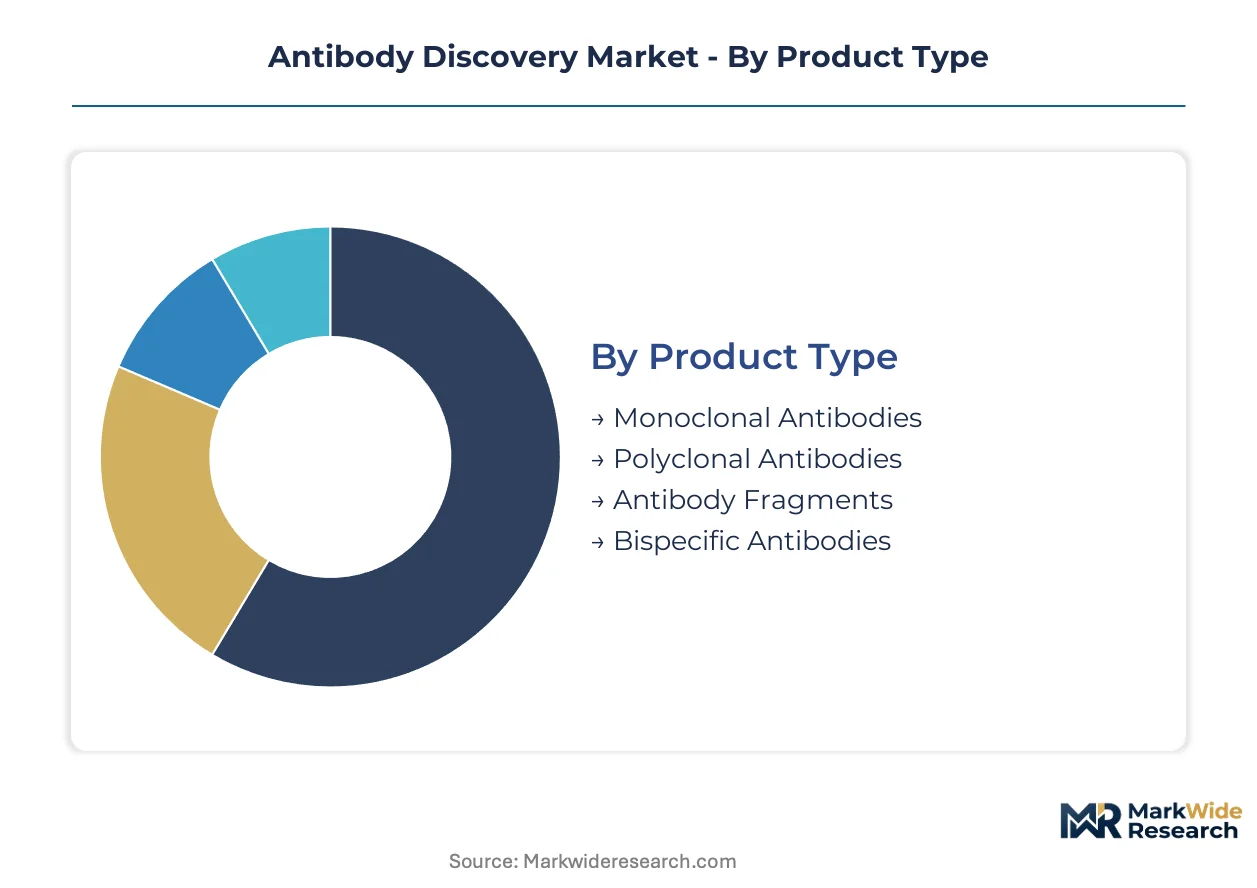
Antibody discovery segmentation reveals how regulatory validation requirements and platform economics concentrate value differently across molecular formats and customer types. Understanding these divides helps procurement teams align vendor selection with program risk profiles and timeline constraints.
Product Type:
Monoclonal antibodies carry the heaviest FDA and EMA validation burden given their dominance in approved therapeutics, while bispecific formats face emerging scrutiny under updated ICH Q5D guidelines for multi-specific biologics.
- Monoclonal Antibodies:These full-length immunoglobulins with defined specificity against single epitopes remain the workhorse format for oncology and autoimmune indications. Demand concentrates among top-20 pharmaceutical sponsors in the United States who require GLP-compliant developability screening before candidate nomination. Their established manufacturing scalability and regulatory familiarity sustain premium pricing despite platform commoditization.
- Bispecific Antibodies:Engineered constructs enabling simultaneous engagement of two distinct antigens are pulling discovery capacity toward complex protein engineering. Boston-Cambridge biotech clusters are adopting these formats fastest for solid tumor applications where dual-target blockade addresses resistance mechanisms. EMA's evolving guidance on multi-specific product quality attributes is forcing earlier analytical characterization into discovery contracts.
- Polyclonal Antibodies:Heterogeneous serum-derived reagents serve diagnostic and research applications where epitope breadth outweighs specificity requirements.
- Antibody Fragments:Smaller antigen-binding units including Fabs and scFvs enable tissue penetration advantages in imaging and certain therapeutic modalities.
Monoclonal antibodies sit at the top of the volume ranking, with bispecific antibodies climbing the fastest.
Technology:
Platform selection directly shapes cost structures, with phage display and next-generation sequencing commanding premium service fees while hybridoma workflows compete on familiarity for conservative procurement teams.
- Phage Display:In vitro selection from bacteriophage libraries with diversities exceeding 10^10 variants enables rapid access to binders against toxic or non-immunogenic targets. San Francisco Bay Area discovery-stage firms are displacing hybridoma workflows with this technology to compress immunization-to-lead timelines. Library construction and bioinformatics interpretation talent scarcity constrains platform expansion despite sequencing cost collapse.
- Next-Generation Sequencing:Deep repertoire profiling of immunized animals or human donors is collapsing the time between antigen exposure and lead identification. Single-cell B-cell receptor sequencing specifically is overtaking bulk analysis in United States therapeutic programs, enabling direct native pairing of heavy and light chains from rare antigen-specific clones.
- Hybridoma Technology:Classical fusion-based monoclonal generation retains foothold in diagnostic and research applications where regulatory novelty is minimized.
- Transgenic Animals:Rodents expressing human immunoglobulin loci produce fully human antibodies without subsequent humanization, though supply concentrates among captive breeding facilities with limited price competition.
Phage display captures the largest share of new therapeutic program starts, while next-generation sequencing is expanding most quickly as sequencing economics improve.
Application:
Therapeutic applications impose the steepest regulatory barriers, with diagnostic testing and research segments permitting faster commercialization under less stringent quality frameworks.
- Drug Development:Discovery-stage campaigns for IND-track assets require integrated toxicology screening and developability assessment before candidate nomination. FDA accelerated approval pathways are compressing timelines and intensifying throughput requirements for contract research organizations serving this segment.
- Therapeutic Applications:Approved and late-stage clinical biologics drive recurring demand for backup candidates and biosimilar alternatives. Oncology therapeutic expansion by pharmaceutical companies is pulling outsourced antibody generation capacity toward this application.
- Diagnostic Testing:Immunoassay developers are expanding into specialized diagnostic binders with defined specificity profiles, creating companion diagnostic co-development opportunities.
- Research:Exploratory reagent procurement by academic and institutional customers operates on shorter decision cycles with reduced documentation requirements.
Drug development commands the highest absolute spending, with diagnostic testing gaining share fastest through companion diagnostic convergence.
End User:
Procurement sophistication varies sharply, with pharmaceutical companies demanding platform exclusivity arrangements while academic institutions prioritize cost minimization over vendor consolidation.
- Pharmaceutical Companies:Top-20 sponsors are consolidating vendor panels and locking competitors out of preferred transgenic animal or phage display libraries through exclusivity clauses. These buyers account for the majority of outsourced large-molecule discovery spend in the United States and drive pricing power toward volume-based contracting.
- Contract Research Organizations:Discovery service providers themselves source platform technologies and specialized reagents, creating tiered supply chain dynamics where GLP toxicology infrastructure scarcity limits price competition.
- Biotechnology Firms:Venture-backed discovery-stage companies in Boston-Cambridge and San Francisco Bay Area clusters represent high-growth demand concentrated in single-cell sequencing and rapid lead identification services.
- Academic Institutions:Research grant-funded procurement operates with extended payment terms and reduced platform integration requirements compared to commercial sponsors.
Pharmaceutical companies dominate absolute contract value, with contract research organizations expanding fastest through platform specialization and sponsor outsourcing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
PhD-level immunologists and protein engineers concentrate in three distinct geographic clusters, each commanding premium discovery service pricing. Boston-Cambridge and San Francisco Bay Area talent pools anchor North American therapeutic antibody development. European contract research organizations leverage REACH-aligned sustainability credentials to capture cross-border outsourcing from Western pharmaceutical sponsors. Chinese discovery platforms exploit NMPA-ICH harmonization to offer parallel Western-Chinese regulatory filing pathways.
United States
FDA accelerated approval pathways compress antibody discovery timelines from years to months, forcing contract research organizations to reconfigure screening architectures around higher-throughput platforms. The agency's Investigational New Drug application requirements shape lead selection criteria nationwide. Boston-Cambridge and San Francisco Bay Area biotech clusters host the densest concentration of discovery-stage firms adopting single-cell B-cell receptor sequencing.
Germany
EMA Good Manufacturing Practice Annex 2 guidelines for biological active substances force earlier developability assessments into discovery contracts with German sponsors. The EU Green Deal's pharmaceutical sustainability package recalibrates how contract research organizations qualify discovery supply chains. Heidelberg and Munich metropolitan areas concentrate toxicology-integrated antibody discovery infrastructure serving European therapeutic programs.
China
NMPA alignment with ICH Q5D through updated technical guidelines for recombinant DNA products opens simultaneous Western-Chinese development tracks without sequence modification. Shanghai and Suzhou industrial parks anchor large-scale phage display library operations serving multinational pharmaceutical outsourcing contracts. Domestic biotechnology firms exploit regulatory harmonization to capture discovery-stage asset flows previously directed exclusively to Western vendors.
Switzerland
Swissmedic's stringent biologics quality standards drive demand for GLP-compliant screening infrastructure among Basel-area pharmaceutical headquarters. The country's dual role as European regulatory hub and neutral commercial territory attracts discovery platform investments from Asian contract research organizations. Zurich and Geneva metropolitan regions concentrate specialized vivarium networks supplying human immunoglobulin loci-expressing rodents.
United Kingdom
Post-Brexit regulatory divergence from EMA frameworks creates procurement complexity for antibody discovery services serving UK-based sponsors. London-Oxford-Cambridge golden triangle retains concentration of academic spinouts pursuing AI-driven epitope prediction tools. Manchester and Birmingham emerging clusters attract cell line development scientists embedded within discovery teams responding to compressed oncology timelines.
Antibody Discovery Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the antibody discovery landscape, creating tiered service structures. Vivarium-dependent transgenic animal platforms require captive breeding infrastructure that limits price competition and extends queue times. Three archetypes dominate: integrated gene-to-antibody platforms, toxicology-integrated full-service providers, and specialized phage display library operators. Competitive moves concentrate on strategic partnerships for geographic expansion and technology licensing for platform diversification.
Among Asia-Pacific platform operators, GenScript Biotech Corporation and WuXi AppTec exemplify integrated service architectures spanning gene synthesis through candidate nomination. Charles River Laboratories anchors the North American toxicology-integrated tier through captive vivarium networks. These three entities occupy positions reflecting distinct capital intensity profiles and regulatory compliance specializations.
| Leading Market Players |
|---|
| GenScript Biotech Corporation |
| Absolute Antibody |
| Charles River Laboratories |
| Twist Bioscience |
| Creative Biolabs |
| Biocytogen Pharmaceuticals |
| WuXi AppTec |
| Sino Biological |
| Sartorius AG |
| Others |
Supply Flow & Price Mechanics
GLP certification tiering creates a bifurcation between premium toxicology-integrated discovery services and commoditized phage display screening, with Charles River Laboratories commanding exclusivity premiums for captive vivarium access while Asian platform operators compete on unbundled gene-to-antibody velocity. This divergence manifests in contract structures where FDA-track programs absorb 40-60% cost premiums for integrated IND-enabling packages, whereas diagnostic developers optimize for per-clone pricing without developability overhead.
Pricing Analysis
Bundled toxicology-integrated discovery services command project-based fees anchored to IND-enabling study completion, while unbundled phage display screening competes on per-clone transactional pricing with bioinformatics interpretation billed separately. Price differentiation rests on GLP certification tier and transgenic animal platform exclusivity, with pharmaceutical sponsors least sensitive to cost and academic institutions driving standard-tier commoditization. Pricing pressure intensifies in hybridoma displacement segments as sequencing economics collapse panning-to-lead timelines and compress service margins.
Supply Chain Analysis
Reverse-logistics flows for transgenic animal genetic material concentrate breeding stock refurbishment through Charles River Laboratories' North American vivarium network and Biocytogen's Shanghai captive facilities. Discovery supply chains draw from United States, China, and Switzerland for human immunoglobulin loci-expressing rodents, with phage display library construction depending on synthetic gene synthesis inputs and next-generation sequencing reagent supply. Single-source vulnerability concentrates in specialized rodent breeding infrastructure, while distribution runs through sponsor-integrated platform partnerships rather than open market procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Antibody discovery functions as a geographic-arbitrage play where NMPA-ICH harmonization enables Chinese platform operators to capture Western-sponsored programs at 30-40% cost structures below Boston-Cambridge equivalents.
For Market Incumbents: Anchor GLP-compliant toxicology infrastructure through captive vivarium expansion in United States and Swiss metropolitan regions, locking pharmaceutical sponsors into multi-year platform exclusivity arrangements before AI-driven epitope prediction tools mature sufficiently to displace animal-based immunization workflows. Defend against Asian cost compression by embedding cell line development scientists within discovery teams to compress oncology timelines beyond unbundled competitors' reach. For New Entrants and Emerging Players: Mid-tier biotechnology firms in Manchester and Birmingham emerging clusters represent an underserved buyer archetype seeking rapid lead identification without top-20 pharmaceutical procurement complexity. White-space targets include AI-augmented epitope prediction services for rational immunogen design and companion diagnostic co-development agreements with immunoassay developers. A specialized phage display library operator can penetrate this segment through direct native pairing expertise and single-cell B-cell receptor sequencing velocity. For Investors and Strategic Acquirers: Consolidation pressure builds where GLP toxicology infrastructure scarcity meets sponsor demands for integrated IND-enabling capacity. Long-term viability favors asset-light phage display platforms with bioinformatics interpretation capabilities over vivarium-dependent transgenic animal operators facing breeding facility capacity constraints. Monitor FDA accelerated approval pathway expansion rates and EMA multi-specific biologics guidance evolution as inflection indicators for bispecific antibody discovery demand.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Exclusivity Arrangements | Charles River Laboratories locks top-20 pharmaceutical sponsors into multi-year toxicology-integrated contracts. |
| AI-Driven Epitope Prediction Integration | Machine learning tools for CDR characterization converge with next-generation sequencing to create new service layers. |
| Parallel Western-Chinese Regulatory Filing | GenScript and WuXi AppTec exploit NMPA-ICH Q5D alignment to capture multinational outsourcing contracts. |
| Single-Cell B-Cell Receptor Sequencing Adoption | Boston-Cambridge biotech clusters displace hybridoma rescue with direct native pairing of heavy and light chains. |
| Companion Diagnostic Co-Development | Immunoassay developers expand beyond therapeutic antibodies into specialized diagnostic binders with defined specificity. |
Methodological Framework
Bottom-up drug development modeling reconciled against top-down contract research organization capacity tracking forms the analytical core, combining primary interviews with drug development executives, regulatory affairs leads, discovery platform scientists, and hospital procurement managers with secondary validation through FDA IND filings, EMA submission databases, ClinicalTrials.gov records, and GPO contract repositories. Triangulation across sponsor-reported outsourcing spend and vendor-disclosed platform utilization rates ensures segmentation integrity.
Historical trendline analysis of therapeutic antibody program starts and phage display library construction velocity informs projection frameworks across the analysis window, with segmentation modeling spanning molecular format, technology platform, application endpoint, and end-user procurement sophistication. CAGRs derive from sponsor pipeline disclosure patterns and contract research organization capacity expansion announcements, incorporating NMPA regulatory harmonization timelines and EMA multi-specific biologics guidance evolution as structural inputs.
Underlying measurement precision varies by segment; therapeutic applications carry tighter precision than research reagent procurement due to mandatory disclosure requirements. Forecasts reflect assumptions regarding sustained FDA accelerated approval pathway utilization and stable transgenic animal breeding facility capacity, though practitioners should monitor REACH-aligned chemical disclosure enforcement intensity and AI-driven epitope prediction regulatory validation frameworks for early signals of workflow displacement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
North America Contraceptives Market
Biopharmaceuticals
Conjugated Estrogen Market
Biopharmaceuticals
Progesterone Market
Biopharmaceuticals
East Africa Generic Drug Market
Biopharmaceuticals
Canada Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Heparin API Market
Biopharmaceuticals
Global Breast Cancer Drugs Market
Biopharmaceuticals
Antibiotics Market
Biopharmaceuticals
Global Pegylated Proteins Market
Biopharmaceuticals
Insulin Market
Biopharmaceuticals
Glycoprotein Market
Biopharmaceuticals
Benzbromarone API Market
Biopharmaceuticals
Rhu Albumin Market
Biopharmaceuticals
Tuberculosis Drugs Market
Biopharmaceuticals
Global Hairy Cell Leukemia Drugs Market
Biopharmaceuticals
Drug Discovery Outsourcing Market