
 China BOPP Film Market | 2026-2036
China BOPP Film Market Size, Share, and Industry Trends Forecast 2026-2036
China BOPP Film Market Outlook
China's GB standards for food-contact plastics is broadening the addressable market for certified BOPP film suppliers. Anhui Guofeng New Materials leverages captive polypropylene resin supply to sustain margin stability across volatile feedstock cycles. Zhejiang Yimei Film Industry Group anchors its position through co-extrusion technology leadership in high-barrier formats. Guangdong Eko Film Manufacture competes on proximity to Pearl River Delta converters, reducing logistics friction for just-in-time delivery.
Biaxially oriented polypropylene film consists of polypropylene resin stretched in machine and transverse directions to achieve tensile strength between 150-250 MPa, moisture barrier below 1 g/m²/day, and optical clarity exceeding 90% haze-free transmission, serving primarily as a printable, heat-sealable substrate for flexible consumer and industrial packaging. Clear BOPP dominates volume throughput due to its cost-positioning in mass-market snack and bakery wrapping, while metalized BOPP captures disproportionate margin pools in premium cosmetic and confectionery barrier applications where oxygen and light exclusion command price premiums. Co-extrusion technology differentiates technical suppliers by enabling asymmetric layer structures that combine sealant functionality with stiffness in single-pass production.
SAMR enforces food-contact material compliance through GB 4806 series standards, while MEE implements extended producer responsibility frameworks that pressure converters toward recyclable mono-material structures, collectively elevating certified substrate demand. MIIT's dual carbon goals are accelerating energy-efficiency audits across film extrusion lines, favoring capital-intensive producers with modern tenter frame configurations. Stakeholders must monitor evolving GB standard revisions and provincial carbon intensity benchmarks to anticipate which technical specifications will become mandatory market access filters.
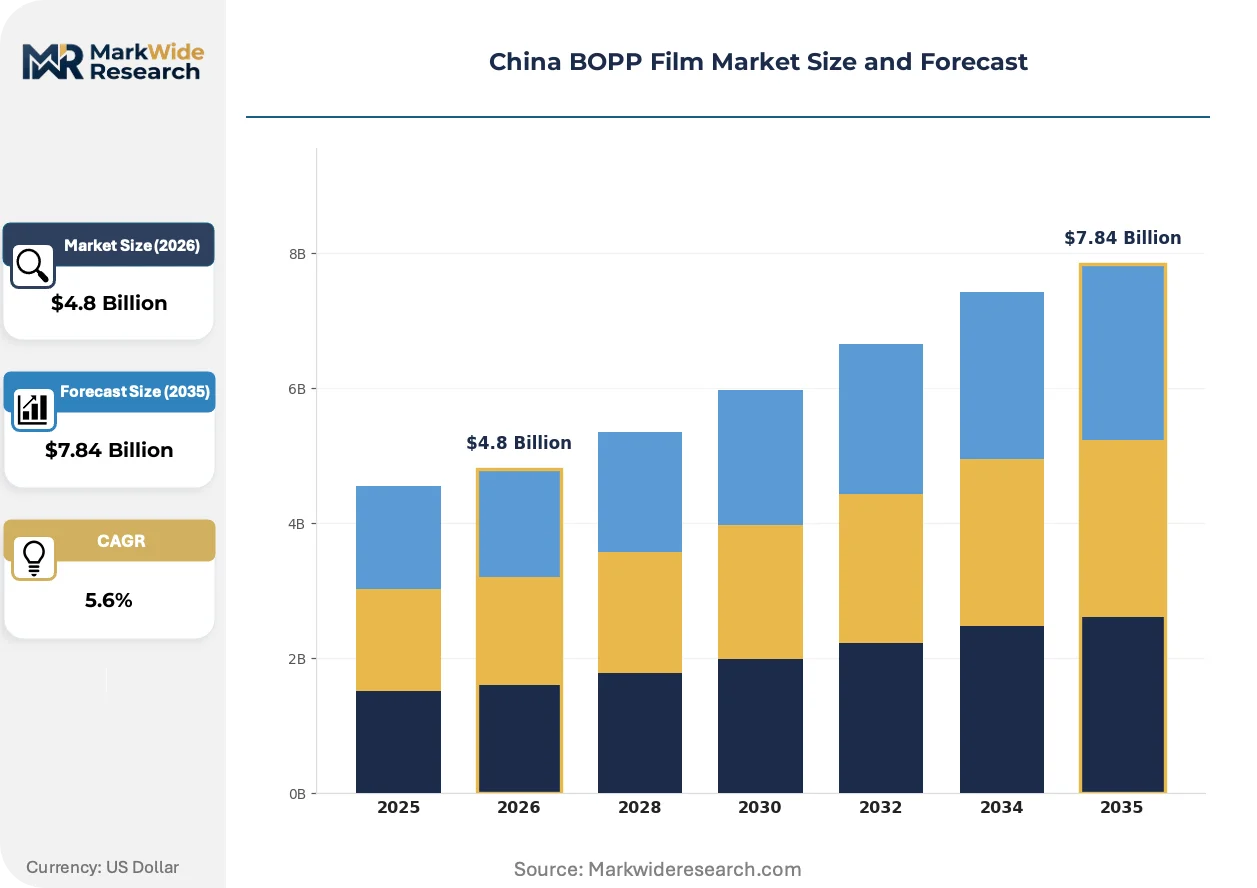
Market Dynamics
GB 4806 series compliance requirements are compressing supplier margins while elevating certified substrate premiums, as SAMR enforcement tightens material purity thresholds for food-contact applications.
Growth Catalysts
- Extended Producer Responsibility frameworks:MEE regulations pressure converters toward recyclable mono-material structures, elevating demand for certified BOPP substrates that meet circularity criteria.
- Tier-one city food packaging expansion:Urban consumption clusters in Shanghai and Beijing drive premium barrier film adoption for fresh and ready-to-eat categories.
- Co-extrusion technology maturation:Asymmetric layer structures enable single-pass production combining sealant functionality with stiffness, reducing unit costs for high-barrier formats.
Market Restraints
- Propylene feedstock volatility:Crude-linked naphtha and propane dehydrogenation economics create margin compression for non-integrated film extruders lacking captive resin supply.
- Zhejiang-Guangdong supply concentration:Converter cluster dominance in these provinces creates logistics bottlenecks and pricing power asymmetry for regional distributors.
- Metalized film substitution ceiling:Aluminum deposition thickness limitations below 40 nanometers restrict oxygen barrier performance in ultra-high-sensitivity pharmaceutical applications.
Strategic Opportunities
- Central China converter migration:Hubei and Henan provinces offer underpenetrated flexible packaging demand with lower labor and energy costs than coastal manufacturing zones.
- MIIT dual carbon incentive alignment:Energy-efficiency audit compliance for modern tenter frame configurations unlocks preferential financing and provincial subsidy access.
- Digital print substrate specialization:Corona treatment and surface energy optimization for water-based ink adhesion addresses emerging short-run packaging workflows.
Industry Challenges
- Certification timeline compression:GB standard revision cycles now outpace laboratory testing capacity, delaying new product commercialization by 8-14 months.
- Multi-layer film recycling infrastructure:Sorting and reprocessing capabilities for co-extruded structures remain underdeveloped, creating stranded asset risk for EPR compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China BOPP Film Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.84 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clear BOPP, Metalized BOPP, White BOPP, Colored BOPP End Use: Food Packaging, Cosmetic Packaging, Industrial Packaging, Labels Thickness: 15 Micron, 20 Micron, 30 Micron, 50 Micron Technology: Blown Film, Cast Film, Co-extrusion, Surface Treatment |
| Companies Covered | Anhui Guofeng New Materials Co., Ltd., Wenzhou Gettel Plastic Industry Co., Ltd., Shanghai Saillage International Trade Co., Ltd., Fujian Baohuan New Material Technology Co., Ltd., Guangdong Eko Film Manufacture Co., Ltd., Zhejiang Yimei Film Industry Group Co., Ltd., Shaoxing Kinlead Film Co., Ltd., XinXing Biaxially Oriented Polypropylene (BOPP) Film Co., Ltd., Qingdao Kingchuan Packaging Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China BOPP Film Market Strategic Shifts
Active alignment between regulatory stringency and manufacturing capability is reshaping competitive differentiation, with technical specifications becoming mandatory market access filters rather than optional premiums.
Water-based barrier coatings are absorbing surface-functionalization demand previously served by solvent-based acrylics and extrusion-laminated polyethylene. Snack and bakery converters in Jiangsu province are adopting these substrates at accelerated pace to preempt VOC emission penalties. This chemistry transition is absorbing technical service capacity from incumbent coating suppliers and compressing equipment retrofit timelines across mid-scale extrusion lines.
SAMR's 2023 GB 4806.7 revision tightens heavy metal and primary aromatic amine migration limits for food-contact plastics. Industrial consequence includes mandatory third-party laboratory certification for all new resin formulations and annual renewal testing for existing product registrations. Premium confectionery and infant food packaging segments are responding fastest, with buyers now requiring batch-level compliance documentation that extends upstream to BOPP substrate certificates.
Converter procurement consolidation is compressing supplier bases as Pearl River Delta flexible packaging groups centralize purchasing through dedicated sourcing platforms. Traditional distributor networks are losing share to direct mill relationships with volume-commitment contracts. This behavioral shift is most visible in Guangdong province, where top-ten converters now represent over forty percent of regional BOPP film offtake and negotiate specification customization as standard terms.
China BOPP Film Market Segmentation
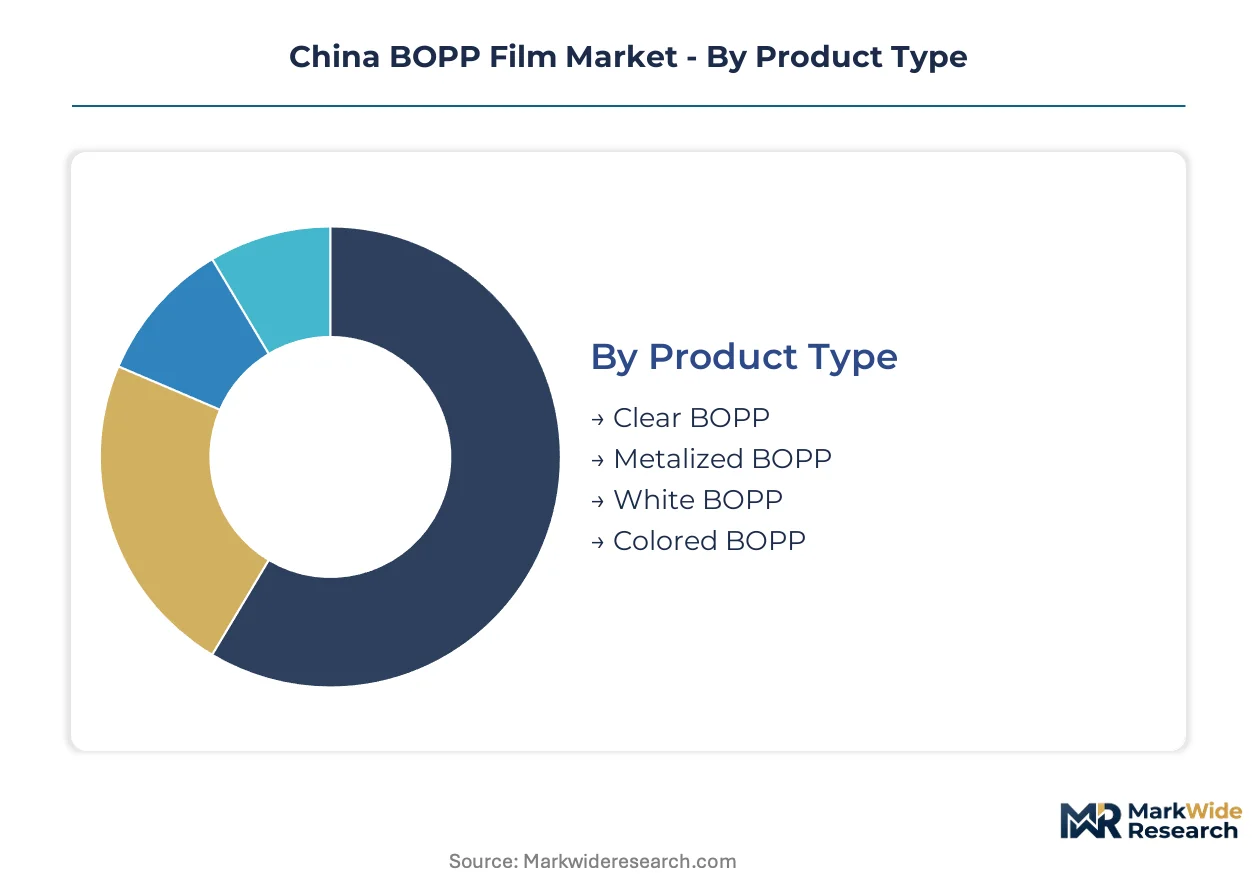
BOPP film segmentation in China tracks divergent margin pools across commodity and specialty grades. Technical specifications increasingly determine market access as GB standards harden. Converter procurement consolidation rewards suppliers with breadth across multiple segment categories.
Product Type:
Volume throughput concentrates in transparent commodity grades, while metallization and pigmentation command premium positioning.
- Clear BOPP:Unpigmented polypropylene stretched to optical clarity exceeding 90% haze-free transmission serves mass-market snack and bakery wrapping in Zhejiang converter clusters. GB 4806 compliance documentation now required at batch level compresses supplier margins while sustaining volume dominance.
- Metalized BOPP:Vacuum-deposited aluminum layers below 40 nanometers thickness create oxygen and light barriers for premium confectionery and cosmetic applications. Pearl River Delta converters absorb disproportionate margin pools here, though pharmaceutical oxygen barrier requirements expose deposition thickness limitations.
- White BOPP:Opacified grades through mineral filler incorporation provide print contrast for label applications.
- Colored BOPP:Pigmented extrusion serves branded retail packaging with shorter production runs.
Mature deployment sits with Clear BOPP. Newer deployment is concentrated in Metalized BOPP.
End Use:
Application-driven specification divergence separates food-contact compliance burdens from industrial durability requirements.
- Food Packaging:Heat-sealable, printable substrates for fresh and ready-to-eat categories face SAMR's tightened heavy metal and primary aromatic amine migration limits. Tier-one cities in Shanghai and Beijing drive premium barrier adoption with mandatory third-party laboratory certification extending upstream to substrate suppliers.
- Labels:Pressure-sensitive adhesive face stocks and wrap-around bottle labels demand corona-treated surface energy optimization for water-based ink adhesion. Digital print substrate specialization is expanding most quickly here as short-run packaging workflows proliferate.
- Cosmetic Packaging:High-barrier formats for premium skin care and fragrance applications.
- Industrial Packaging:Heavy-duty woven bag lamination and strapping tapes prioritize tensile strength over optical properties.
Food Packaging absorbs the steepest compliance cost escalation. Labels capture the fastest technology transition.
Thickness:
Calender selection maps directly to end-use performance requirements and resin consumption economics.
- 20 Micron:Balanced stiffness-to-yield ratio dominates general-purpose flexible packaging with machine-direction tensile strength between 150-250 MPa. Jiangsu province snack converters are absorbing this specification at accelerated pace for VOC emission-compliant water-based barrier coatings.
- 15 Micron:Downgauged formats reduce unit material costs for high-volume bakery and confectionery wrapping.
- 30 Micron:Enhanced puncture resistance serves heavier food contents and industrial applications.
- 50 Micron:Maximum stiffness grades for multi-ply lamination structures and stand-up pouch formats.
20 Micron specifications anchor current converter procurement. 15 Micron downgauging is gaining share fastest under MEE extended producer responsibility pressure.
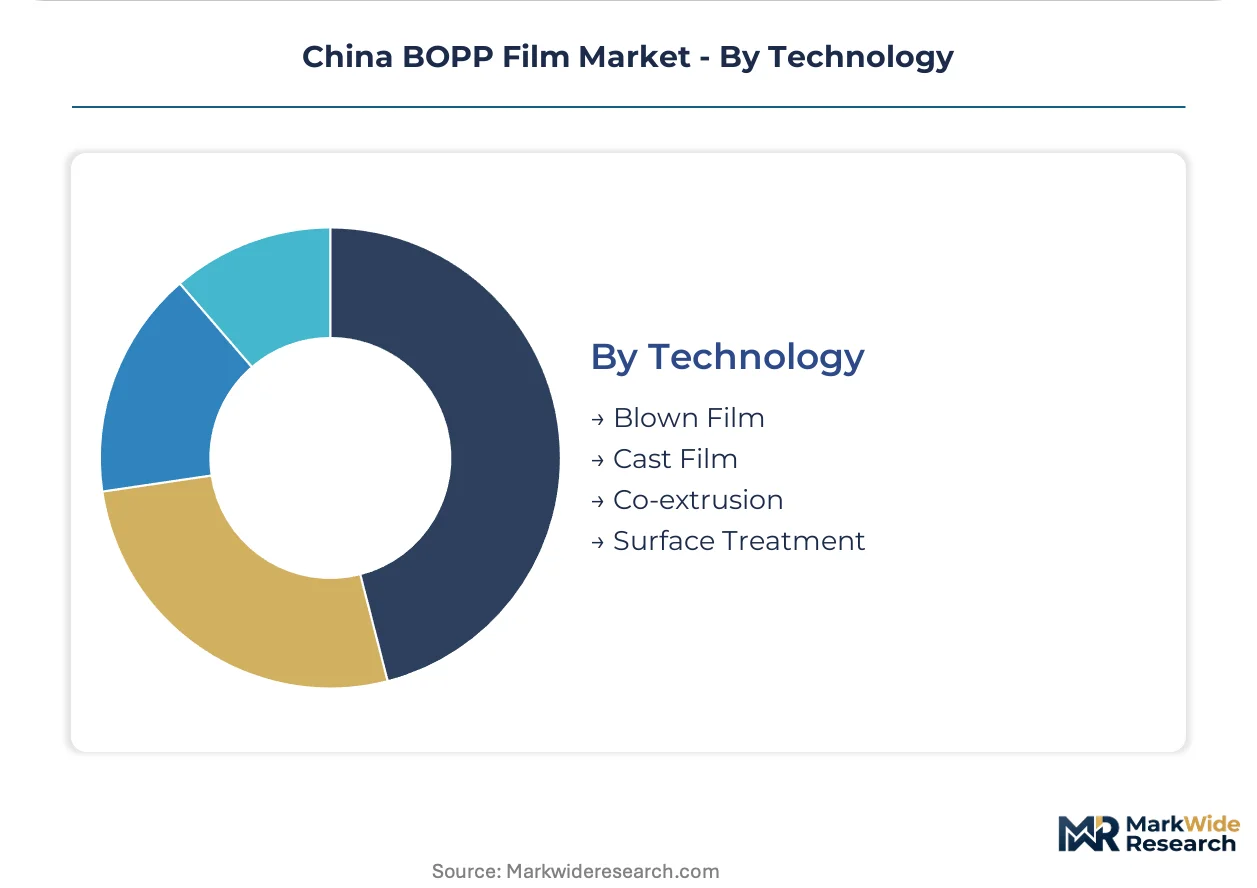
Technology:
Process selection determines layer complexity capability and energy efficiency audit compliance under MIIT dual carbon frameworks.
- Co-extrusion:Asymmetric layer structures combine sealant functionality with stiffness in single-pass production, reducing unit costs for high-barrier formats. Modern tenter frame configurations with energy-efficiency compliance unlock preferential financing and provincial subsidy access.
- Surface Treatment:Corona and plasma activation enables water-based ink adhesion and metallization adhesion for digital print substrate specialization. Surface-functionalization demand is climbing the fastest as solvent-based acrylic chemistry faces emission penalties.
- Blown Film:Tubular orientation process for lower-volume specialty grades with balanced biaxial properties.
- Cast Film:Machine-direction orientation preceding transverse stretching for high-clarity applications.
Co-extrusion technology commands capital-intensive producer advantage. Surface Treatment specialization is expanding most quickly among mid-scale extrusion lines retrofitting for compliance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Zhejiang and Guangdong provinces anchor converter procurement, with Shanghai and Beijing driving premium barrier specifications through tightened food-contact compliance mandates.
Guangdong Province
Pearl River Delta flexible packaging groups centralize purchasing through dedicated sourcing platforms, absorbing over forty percent of regional BOPP film offtake. MEE extended producer responsibility frameworks pressure converters toward recyclable mono-material structures. Guangzhou and Shenzhen converter clusters negotiate specification customization as standard contract terms, compressing traditional distributor networks.
Zhejiang Province
Wenzhou and Shaoxing industrial corridors concentrate co-extrusion technology deployment for high-barrier formats. MIIT dual carbon goals accelerate energy-efficiency audits across film extrusion lines, favoring capital-intensive producers with modern tenter frame configurations. Local converter demand for 20 micron specifications dominates general-purpose flexible packaging procurement.
Jiangsu Province
Nanjing and Suzhou snack converters absorb water-based barrier coatings at accelerated pace to preempt VOC emission penalties. SAMR's GB 4806.7 revision tightens heavy metal migration limits, mandating third-party laboratory certification for new resin formulations. Surface-functionalization demand climbs fastest here as solvent-based acrylic chemistry faces regulatory penalties.
Shandong Province
Qingdao packaging exporters serve Japanese and South Korean food-contact markets with certified substrate documentation. Provincial carbon intensity benchmarks under MIIT frameworks favor producers with energy-efficient extrusion configurations. Local film extruders compete on batch-level compliance documentation extending upstream to BOPP substrate certificates.
Anhui Province
Hefei-based resin integration supports margin stability across volatile propylene feedstock cycles. Central China location offers logistics advantages for converter migration into Hubei and Henan underpenetrated markets. Captive polypropylene supply distinguishes regional producers from coastal competitors dependent on merchant resin markets.
China BOPP Film Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification documentation and co-extrusion technology capabilities. The supplier base stratifies into three tiers: integrated resin-to-film producers with captive feedstock, technology-specialized extruders with asymmetric layer expertise, and regional converters competing on logistics proximity. Dominant competitive moves include direct mill relationships replacing distributor networks and energy-efficiency retrofit investments unlocking MIIT subsidy access.
Among integrated producers, Anhui Guofeng New Materials Co., Ltd. exemplifies the resin-captive archetype stabilizing margins through upstream control. Zhejiang Yimei Film Industry Group Co., Ltd. and Guangdong Eko Film Manufacture Co., Ltd. occupy positions within the technology-differentiated tier, with geographic anchoring in their respective provincial converter clusters. These three entities represent the structural segmentation between feedstock-integrated and technology-specialized competitive positioning.
| Leading Market Players |
|---|
| Anhui Guofeng New Materials Co., Ltd. |
| Wenzhou Gettel Plastic Industry Co., Ltd. |
| Shanghai Saillage International Trade Co., Ltd. |
| Fujian Baohuan New Material Technology Co., Ltd. |
| Guangdong Eko Film Manufacture Co., Ltd. |
| Zhejiang Yimei Film Industry Group Co., Ltd. |
| Shaoxing Kinlead Film Co., Ltd. |
| XinXing Biaxially Oriented Polypropylene (BOPP) Film Co., Ltd. |
| Qingdao Kingchuan Packaging Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Propylene feedstock volatility cascades through three distinct pricing tiers as captive resin supply separates integrated producers from merchant-dependent extruders, with Zhejiang and Guangdong converter clusters capturing divergent margin pools based on logistics proximity to film mills.
Pricing Analysis
Throughput-based contract structures dominate converter procurement, with volume-commitment agreements securing specification customization as standard terms. Price differentiation hinges on GB 4806 certification grade and co-extrusion layer complexity, with certified high-barrier substrates commanding sustained premiums. Cost compression in commodity clear grades is intensifying because Pearl River Delta purchasing consolidation squeezes spot-market participants. Mass-market snack converters exhibit highest price sensitivity, while infant food and premium cosmetic packaging buyers prioritize batch-level compliance documentation over unit cost.
Supply Chain Analysis
Dual-sourcing mandates from consolidated Pearl River Delta flexible packaging groups are forcing mid-scale extruders to qualify secondary resin suppliers. Manufacturing concentrates in China, with South Korea and Japan supplying metallization equipment and specialty coating chemistry. Feedstock exposure rests on naphtha-crude linkages and propane dehydrogenation economics. Single-source vulnerability concentrates in Zhejiang tenter frame configurations. Distribution runs through direct mill relationships replacing traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Water-based barrier coatings are displacing solvent-based acrylic surface treatments, compressing equipment retrofit timelines and absorbing technical service capacity across Jiangsu and Zhejiang extrusion corridors.
For Market Incumbents: To counter converter procurement consolidation, deepen direct mill relationships through volume-commitment contracts with specification customization terms, and accelerate energy-efficiency retrofit investments to unlock MIIT dual carbon subsidy access before provincial benchmark tightening. For New Entrants and Emerging Players: SAMR's GB 4806.7 revision in China opens a window for certified substrate specialization targeting underpenetrated Hubei and Henan converter markets, with digital print substrate optimization for short-run packaging workflows offering the most penetrable entry angle. For Investors and Strategic Acquirers: Batch-level compliance documentation becoming mandatory across premium food packaging is the leading indicator that resin-captive integrated producers will outlast merchant-dependent competitors, positioning upstream-integrated film extruders as priority acquisition targets with extended producer responsibility frameworks as the critical policy signal to monitor.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polypropylene Resin | Captive feedstock supply insulates margin stability against propylene volatility cycles. |
| Co-extrusion Technology Upgrade | Asymmetric layer capability unlocks high-barrier format premiums under GB 4806 compliance. |
| Energy-Efficiency Tenter Frame Retrofit | MIIT audit compliance secures preferential financing and provincial subsidy access. |
| Digital Print Substrate Specialization | Corona treatment optimization captures emerging short-run packaging workflow demand. |
| Central China Converter Proximity Expansion | Hubei and Henan logistics positioning addresses migration of flexible packaging demand. |
Study Parameters
Independent corroboration across film extrusion plant managers, flexible packaging procurement leads at Pearl River Delta converters, distribution channel partners, and MIIT policy researchers underwrites the qualitative findings. Primary interviews with technical R&D directors at co-extrusion equipment suppliers combined with secondary validation from customs trade data, SEC filings of listed chemical companies, and SAMR regulatory bulletins enabled bottom-up and top-down triangulation.
Rate-of-change decomposition across the projection horizon models product type segmentation by barrier grade, end-use application by compliance burden, thickness specification by downgauging trajectory, and technology deployment by energy-efficiency tier. CAGRs derive from extrusion line capacity utilization trends and converter offtake patterns. Forecast inputs incorporate propylene-naphtha spread dynamics and provincial carbon intensity benchmark evolution.
The model assumes a particular technology adoption path; alternative pathways for water-based barrier coating chemistry would alter the outlook. Forecasts reflect assumptions about SAMR enforcement intensity and MIIT subsidy continuity. Deviation in GB standard revision timing or extended producer responsibility implementation pace would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Resealable Films Market
Poly film
Silicone Release Films Market
Poly film
Anti Fog Polycarbonate Films and Sheets Market
Poly film
United States Polycarbonate Sheets and Films Market
Poly film
North America Polyimide Films Market
Poly film
MOPP Packaging Films Market
Poly film
Australia and New Zealand Plastic Packaging Film Market
Poly film
Global Fluoropolymer Films Market
Poly film
Asia Pacific Plastic Packaging Film Market
Poly film
Polyolefin (POF) Shrink Film Market
Poly film
Polystyrene Films Market
Poly film
Germany Plastic Packaging Films Market
Poly film
Embossed Film Market
Poly film
India Plastic Packaging Film Market
Poly film
Soft Touch Film Market
Poly film
Cleanroom Film and Bags Market