
 Liquid Pouch Packing Machine Market | 2026-2036
Liquid Pouch Packing Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Liquid Pouch Packing Machine Market Foresight
The capital-intensity divergence between turnkey system builders and component assemblers is redrawing competitive boundaries in liquid pouch packing machinery. Tetra Pak leverages integrated aseptic lines to sustain premium positioning across dairy and beverage accounts. Bosch Packaging Technology anchors European demand through precision servo-driven filling systems. Nichrome India competes on cost-engineered configurations for emerging market processors.
Liquid pouch packing machines form-fill-seal flexible containers for liquids using heat-sealing, ultrasonic welding, or impulse sealing at speeds ranging from 30 to 600 pouches per minute depending on automation tier. These systems serve food, pharmaceutical, and personal care sectors where shelf stability, portion control, and transport efficiency matter. Stand-up pouches and spouted pouches command the strongest margin pools as brand owners shift from rigid bottles to flexible formats. Automatic technology lines lead volume shipments while hybrid configurations represent the fastest-growing installation category among mid-scale processors retrofitting legacy equipment.
FDA 21 CFR Part 11 validation requirements shape pharmaceutical-grade machine specifications in the United States, while EU MDR and CE marking frameworks govern European market access for medical and food-contact applications. India's BIS certification and China's GB standards add compliance layers for exporters targeting those manufacturing bases. Stakeholders must monitor evolving extended producer responsibility mandates and material-recycling targets that will determine permissible pouch substrates and sealing technologies.
Market Dynamics
The spouted pouch format migration from rigid bottles is compressing machine replacement cycles as beverage and personal care processors retool lines for flexible packaging. This substrate shift demands new sealing architectures and validation protocols.
Growth Catalysts
- EU MDR compliance pressure:Medical device manufacturers in Germany and France are upgrading to servo-driven filling systems that satisfy CE marking and traceability mandates for sterile liquid packaging.
- Stand-up pouch adoption in dairy:Processors across India and Brazil are installing automatic form-fill-seal lines to capture shelf differentiation and transport cost savings versus glass and rigid plastics.
- Spouted pouch technology maturation:Heat-sealing and ultrasonic welding advances now support 600 pouches per minute at pharmaceutical-grade tolerances, opening medical nutrition and oral care applications.
Market Restraints
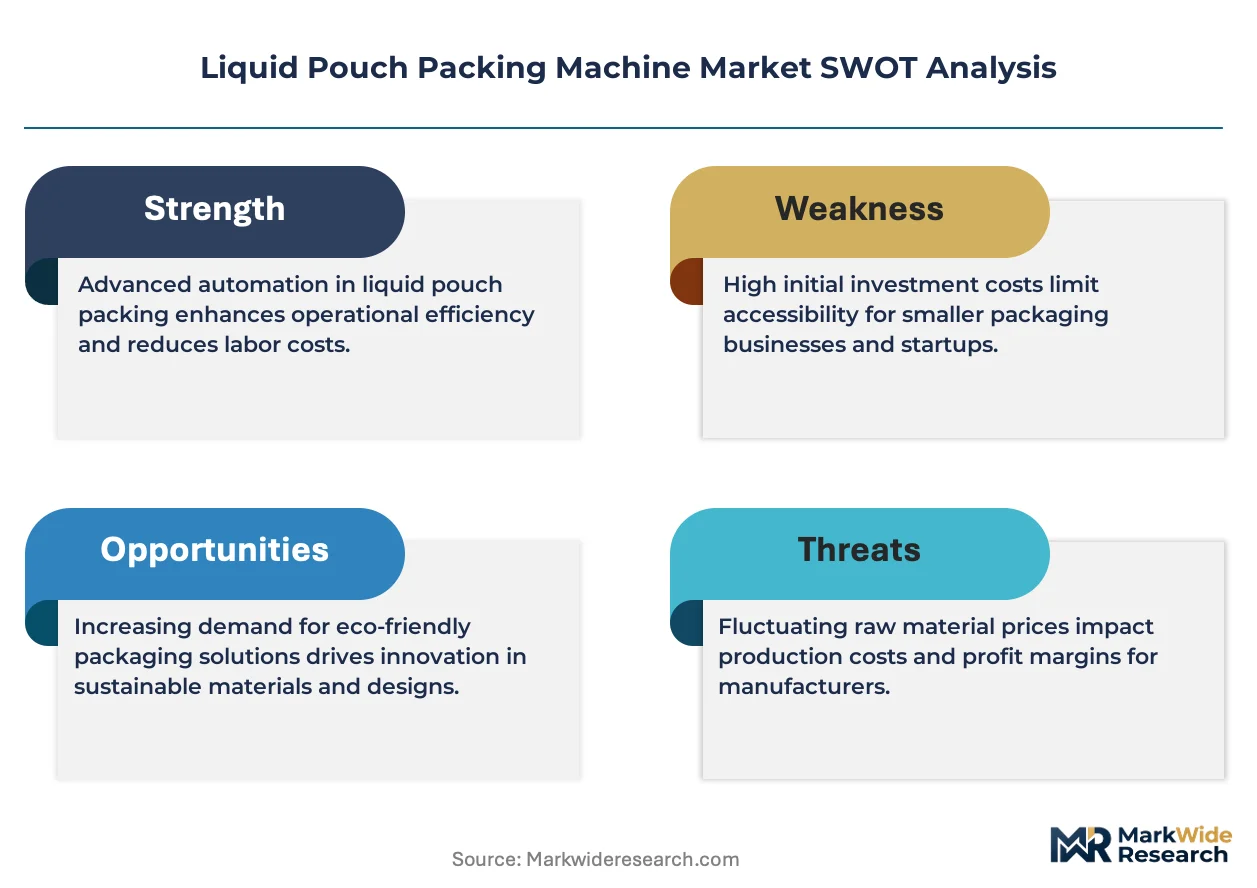
- Stainless steel and servo motor cost volatility:Input price swings for 316L grade steel and precision motion components compress margins for mid-scale machine builders in China and India.
- European component supplier concentration:Precision filling valves and vision inspection modules rely on German and Italian sub-suppliers, creating lead time vulnerability for turnkey assemblers elsewhere.
- Impulse sealing throughput ceiling:Heat-seal alternatives face speed constraints above 400 pouches per minute in high-viscosity liquid applications, limiting displacement of legacy thermal systems.
Strategic Opportunities
- Underpenetrated Brazilian pharmaceutical packaging:ANVISA's evolving GMP requirements for liquid dosage forms create first-mover advantage for validated aseptic pouch systems in São Paulo and Rio de Janeiro manufacturing clusters.
- Extended producer responsibility tailwinds:EU Green Deal packaging waste directives and India's Plastic Waste Management Rules are mandating recyclable mono-material pouches, requiring new sealing chemistry and machine retrofit demand.
- Hybrid automation convergence:Mid-scale processors are blending automatic filling with semi-automatic changeover to bridge legacy asset utilization and new format flexibility, creating service and upgrade revenue pools.
Industry Challenges
- FDA 21 CFR Part 11 validation timelines:Pharmaceutical-grade machine qualification in the United States demands 12-18 month documentation cycles, delaying revenue recognition and stretching engineering resources.
- Retrofit integration complexity:Legacy form-fill-seal lines from the 2010-2015 installation wave require mechanical and control architecture overhauls to accommodate spouted pouch formats, inflating total cost of ownership calculations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liquid Pouch Packing Machine Market |
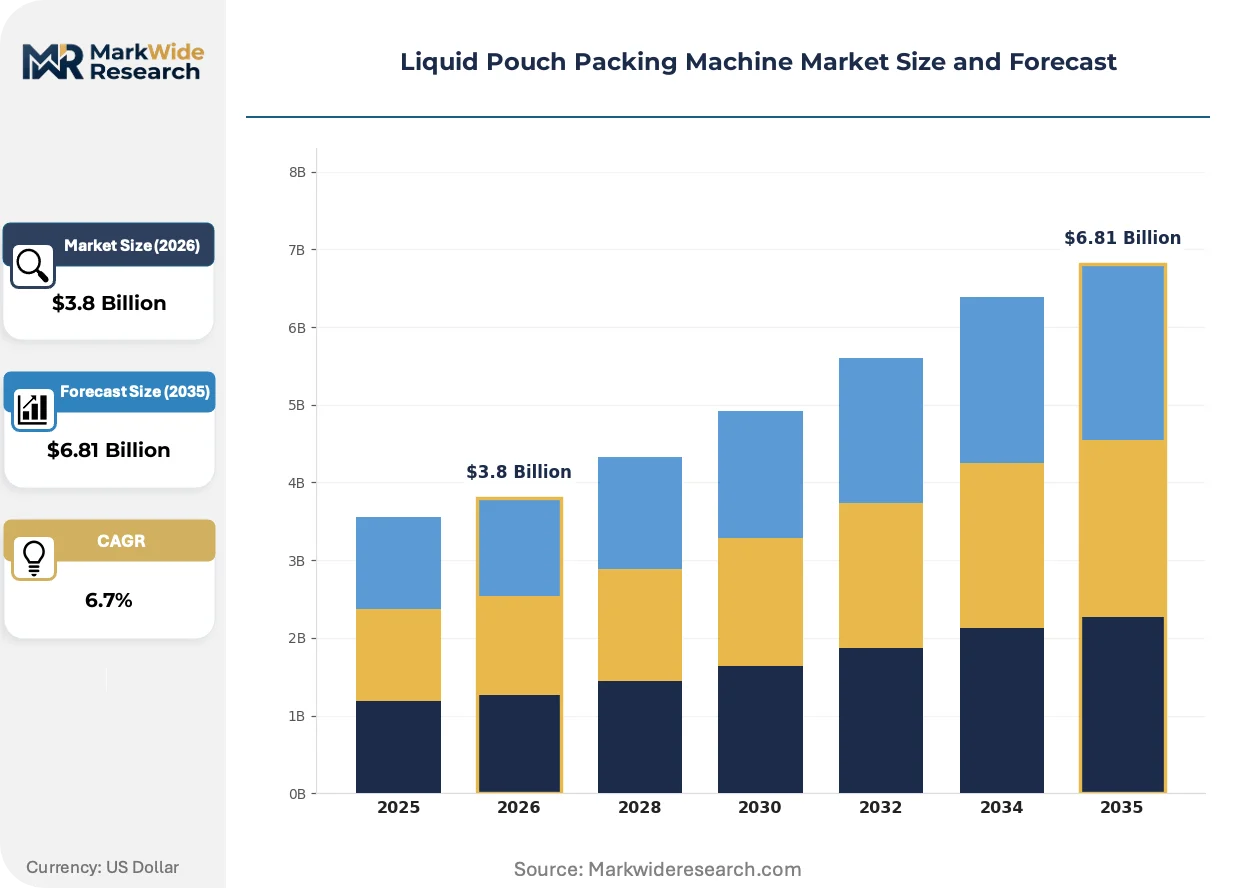
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-Up Pouches, Flat Pouches, Spouted Pouches, Sealable Pouches End User: Food & Beverage, Pharmaceuticals, Personal Care, Household Products Technology: Automatic, Semi-Automatic, Manual, Hybrid Material: Plastic, Paper, Composite, Aluminum |
| Companies Covered | Nichrome India, Bosch Packaging Technology, Tetra Pak, Viking Masek, GEA Group, Spack Machine, Universal Pack, Synda Pack, Turpack, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liquid Pouch Packing Machine Market Shifts & Advancements
Ultrasonic sealing technology is reshaping competitive positioning in high-speed liquid packaging. Machine builders and material suppliers are co-developing mono-film structures that satisfy both performance specifications and emerging recyclability mandates.
Ultrasonic welding systems operate without direct heat application, enabling hermetic seals through molecular friction in polymer layers. Dairy and beverage processors in Germany and the Netherlands are piloting these units at 400-500 pouches per minute for sensitive probiotic products. This thermal-free approach is fragmenting the incumbent heat-seal equipment base by eliminating thermal mass warm-up cycles and reducing energy intensity.
EU MDR's Unique Device Identification requirements are forcing pharmaceutical packaging lines to integrate serialization and aggregation modules. Machine builders must now embed track-and-trace hardware at the sealing station rather than as downstream add-ons. European medical device contract manufacturers are absorbing 15-20% capex premiums for compliant configurations, while Indian exporters to the EU face certification bottlenecks at notified bodies.
Brand owners are unbundling after-sales service contracts from initial equipment purchases, treating spare parts and technical support as competitive procurement categories. Mid-scale food processors in Brazil and India now negotiate multi-year service level agreements separately from capital equipment financing. This disaggregation is visible most acutely in the Indian dairy cooperative sector, where state-level federations aggregate maintenance spend across distributed processing plants.
Liquid Pouch Packing Machine Market Segmentation
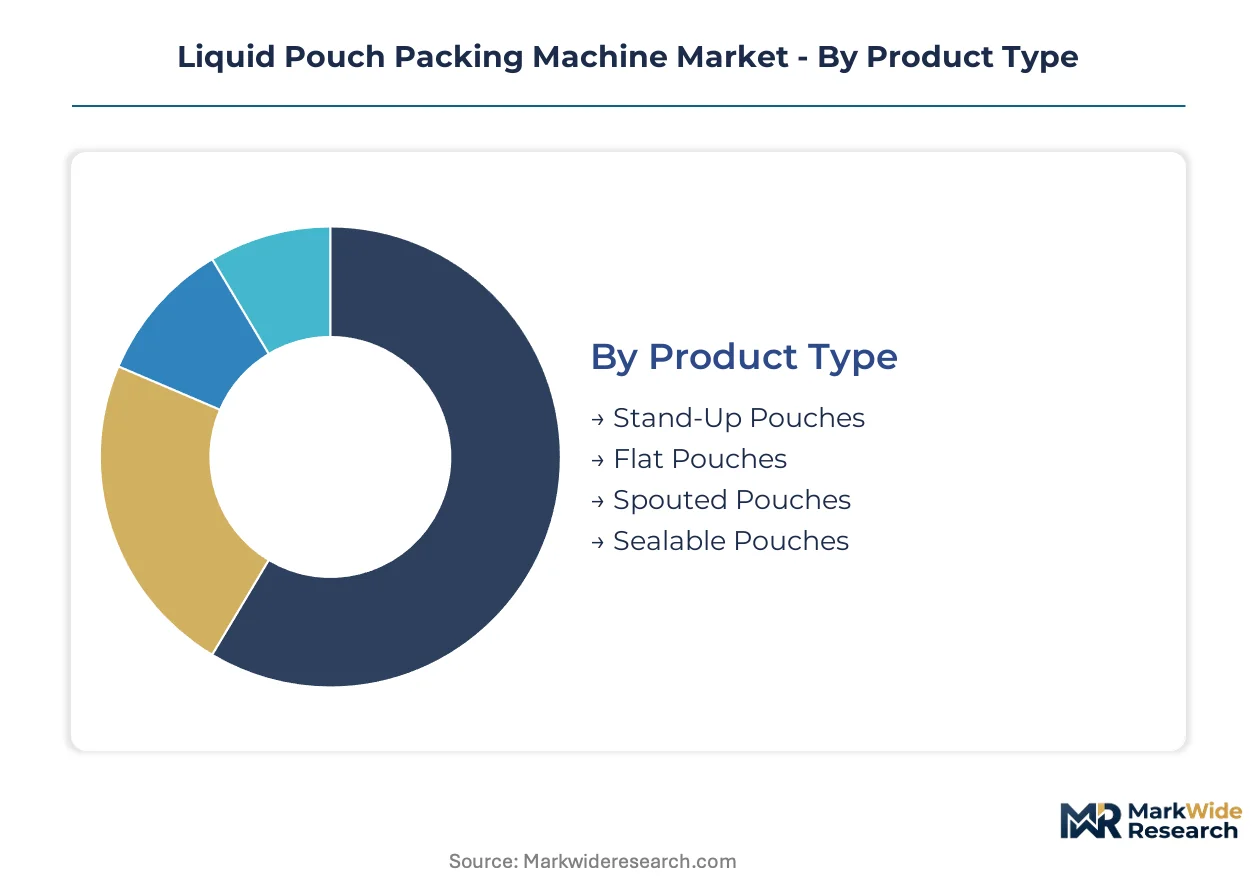
Liquid pouch packing machinery segments diverge sharply on validation intensity and throughput requirements. Food-grade systems prioritize speed economics while pharmaceutical configurations absorb documentation overhead for FDA and EU MDR compliance.
Product Type:
Regulatory differentiation separates medical-grade spouted formats from commodity flat pouches in validation protocols and sealing architecture.
- Stand-Up Pouches:These self-supporting formats use gusseted bottom seals to create shelf-stable vertical presentation. German dairy processors deploy automatic form-fill-seal lines at 400-600 pouches per minute to capture retail differentiation against rigid bottles. FDA 21 CFR Part 11 validation timelines stretch 12-18 months for pharmaceutical applications using this format.
- Spouted Pouches:Integrated fitment welding demands precision servo-driven sealing stations with vision inspection modules. EU MDR's Unique Device Identification requirements are forcing medical nutrition manufacturers in France and Germany to embed track-and-trace hardware at the sealing station. Heat-sealing and ultrasonic welding advances now support 600 pouches per minute at pharmaceutical-grade tolerances.
- Flat Pouches:Two-dimensional seals suit single-serve condiments and sample sachets with minimal material overhead.
- Sealable Pouches:Reclosable zipper integrations target premium snack and personal care segments requiring repeated access.
Established volume favors Stand-Up Pouches; emerging adoption favors Spouted Pouches.
End User:
Cost tier stratification places pharmaceutical systems at 40-60% capex premiums over food-grade equivalents due to aseptic validation and serialization modules.
- Food & Beverage:Dairy cooperatives across India and Brazil drive automatic line installations for shelf differentiation and transport cost savings. India's BIS certification and FSSAI compliance add regulatory layers for equipment exporters. Mid-scale processors favor hybrid configurations blending automatic filling with semi-automatic changeover.
- Pharmaceuticals:Sterile liquid dosage forms demand servo-driven filling systems satisfying CE marking and traceability mandates. ANVISA's evolving GMP requirements in Brazil create first-mover advantage for validated aseptic pouch systems in São Paulo manufacturing clusters. EU MDR compliance pressure is accelerating medical device manufacturer upgrades in Germany.
- Personal Care:Spouted pouch migration from rigid bottles compresses replacement cycles for oral care and cosmetic applications.
- Household Products:Concentrated detergent and cleaner formats prioritize chemical resistance in seal layer specification.
Food & Beverage dominates unit shipments; Pharmaceuticals commands the steepest expansion trajectory on regulatory upgrade cycles.
Technology:
Application maturity separates legacy thermal systems from ultrasonic welding pilots in energy intensity and warm-up economics.
- Automatic:Integrated form-fill-seal lines operate at 30-600 pouches per minute depending on viscosity and pouch complexity. German and Dutch dairy processors pilot ultrasonic sealing at 400-500 pouches per minute for probiotic products. Full automation carries 15-20% capex premiums for EU MDR-compliant pharmaceutical configurations.
- Hybrid:Mid-scale processors retrofit legacy equipment with automatic filling stations and semi-automatic changeover mechanisms. This configuration is gaining share fastest among Brazilian and Indian food processors bridging asset utilization and format flexibility.
- Semi-Automatic:Operator-assisted loading suits batch-scale pharmaceutical trials and specialty beverage startups.
- Manual:Benchtop impulse sealers serve laboratory validation and ultra-low-volume artisan production.
Automatic technology leads volume shipments; Hybrid configurations capture emerging retrofit demand.
Material:
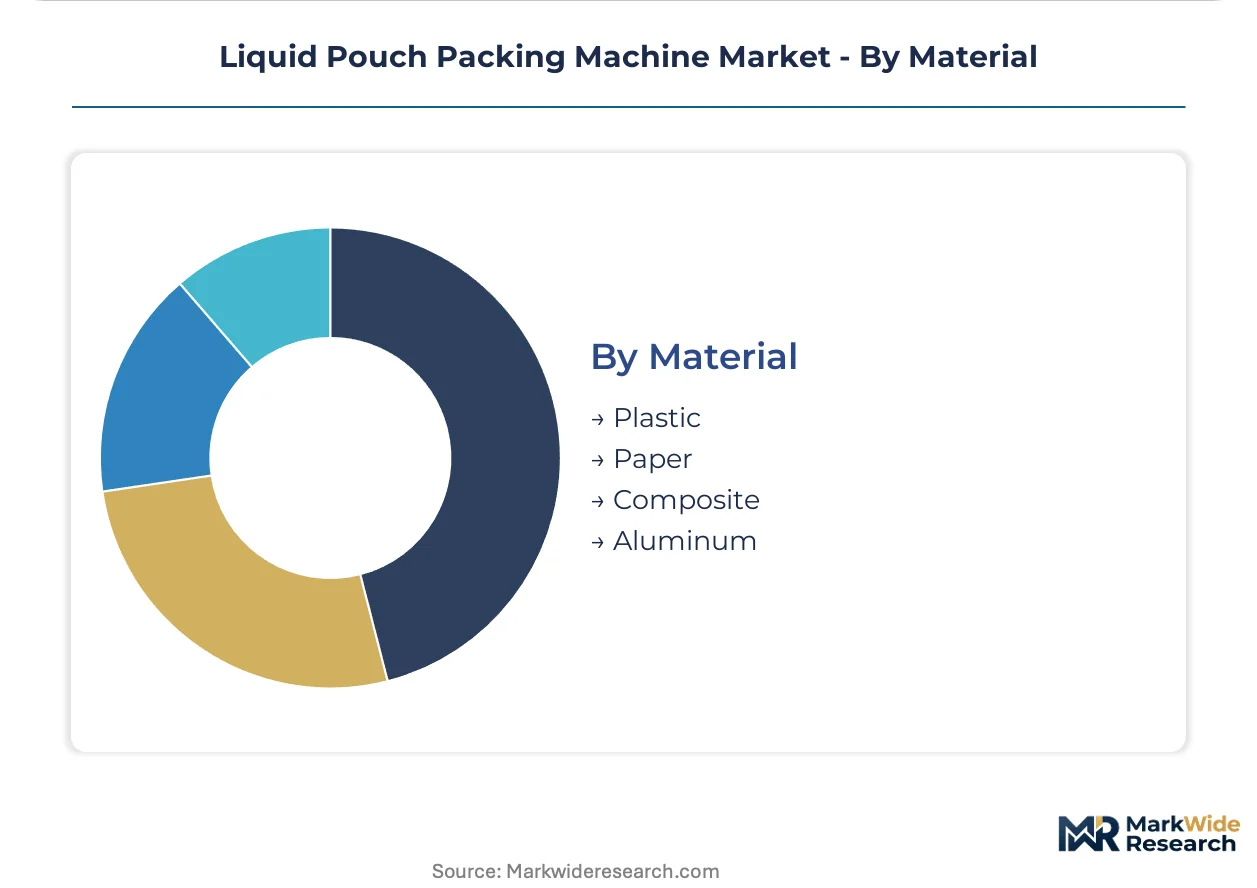
Supply concentration in European component vendors shapes machine architecture for multi-layer versus mono-material substrates.
- Plastic:Polyethylene and polypropylene laminates dominate food and beverage applications with established heat-seal compatibility. EU Green Deal packaging waste directives are mandating recyclable mono-material pouches, requiring new sealing chemistry and machine retrofit demand across German and French installations.
- Composite:Multi-layer barrier structures combining plastic, aluminum, and paper serve pharmaceutical and extended-shelf-life food applications. India's Plastic Waste Management Rules are pressuring brand owners to shift toward separable mono-material alternatives.
- Paper:Fiber-based substrates with polymer seal layers target sustainability-positioned premium brands.
- Aluminum:Foil laminates provide absolute barrier protection for sensitive pharmaceutical and personal care formulations.
Plastic substrates dominate current installed base; Composite structures face regulatory pressure toward material redesign.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India and Brazil prioritize cost-engineered configurations, while German and French pharmaceutical processors absorb 15-20% capex premiums for EU MDR-compliant systems. This demand-elasticity contrast shapes regional equipment specifications and validation intensity.
Germany
Dairy processors in Bavaria and Baden-Württemberg deploy automatic form-fill-seal lines at 400-600 pouches per minute to capture retail differentiation against rigid bottles. EU MDR compliance pressure is accelerating medical device manufacturer upgrades in Stuttgart and Munich manufacturing clusters. CE marking and traceability mandates for sterile liquid packaging dominate procurement specifications.
India
Dairy cooperatives across Maharashtra and Gujarat drive automatic line installations for shelf differentiation and transport cost savings. BIS certification and FSSAI compliance add regulatory layers for equipment exporters targeting Indian manufacturing bases. State-level federations in Karnataka and Tamil Nadu aggregate maintenance spend across distributed processing plants.
Brazil
ANVISA's evolving GMP requirements for liquid dosage forms create first-mover advantage for validated aseptic pouch systems. São Paulo and Rio de Janeiro manufacturing clusters concentrate demand for pharmaceutical-grade machinery. Mid-scale food processors favor hybrid configurations blending automatic filling with semi-automatic changeover.
United States
FDA 21 CFR Part 11 validation requirements shape pharmaceutical-grade machine specifications, demanding 12-18 month documentation cycles. Beverage and personal care processors retool lines for flexible packaging formats. California and Texas packaging hubs absorb extended qualification timelines for sterile liquid applications.
France
Medical nutrition manufacturers absorb 15-20% capex premiums for EU MDR-compliant configurations with embedded track-and-trace hardware. EU Green Deal packaging waste directives mandate recyclable mono-material pouches, requiring new sealing chemistry. Lyon and Paris manufacturing clusters pilot ultrasonic sealing at 400-500 pouches per minute for sensitive probiotic products.
Liquid Pouch Packing Machine Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Integrated system builders command premium positioning through aseptic line validation, while component assemblers compete on modular flexibility and price points. The market stratifies across three strategic archetypes: turnkey solution providers, precision subsystem specialists, and emerging-market cost optimizers. Dominant competitive moves include geographic expansion into underpenetrated pharmaceutical packaging clusters and portfolio diversification toward hybrid automation configurations.
Within the integrated solution tier, Tetra Pak and Bosch Packaging Technology occupy positions defined by regulatory validation depth and precision servo architecture. Nichrome India exemplifies the cost-engineered archetype targeting emerging-market dairy cooperatives. These three anchors represent the span from premium pharmaceutical-grade systems to volume-focused food-grade configurations, with each sitting within distinct price-performance bands that reflect their geographic origins and structural positioning.
| Leading Market Players |
|---|
| Nichrome India |
| Bosch Packaging Technology |
| Tetra Pak |
| Viking Masek |
| GEA Group |
| Spack Machine |
| Universal Pack |
| Synda Pack |
| Turpack |
| Others |
Supply & Pricing Matrix
Sixteen-week lead times for German precision filling valves and Italian vision inspection modules concentrate pricing power among European subsystem suppliers, while Indian and Brazilian turnkey assemblers absorb margin compression from stainless steel and servo motor cost volatility. This inventory-to-delivery gap forces mid-scale machine builders to choose between strategic stockpiles of critical components or just-in-time exposure to supply disruption.
Pricing Analysis
After-sales revenue from multi-year service level agreements and spare parts procurement now drives lifetime value beyond initial equipment sales. Three-tier pricing structure across premium pharmaceutical-grade, standard food-grade, and economy emerging-market configurations separates Tetra Pak and Bosch Packaging Technology at the top from Nichrome India's cost-engineered offerings. Pricing pressure stems from brand owners unbundling service contracts from capital purchases, treating maintenance spend as competitive procurement. Mid-scale food processors in Brazil and India exhibit highest price sensitivity, while German medical device manufacturers absorb 15-20% capex premiums for EU MDR-compliant systems with embedded serialization.
Supply Chain Analysis
Strategic stockpile preferences dominate among pharmaceutical-grade machine builders buffering against sixteen-week lead times for precision components, while food-grade assemblers favor just-in-time inventory to minimize working capital. Supply concentrates in Germany and Italy for filling valves and vision systems, China for servo motors and control electronics, and India for cost-engineered mechanical assemblies. Raw material dependencies center on 316L grade stainless steel, precision motion components, and multi-layer polymer films. Single-source vulnerability from European component supplier concentration creates lead time risk for turnkey assemblers elsewhere. Distribution runs through direct OEM relationships for large processors and regional equipment distributors serving mid-scale dairy cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The liquid pouch packing machine market sits in early-cycle expansion as spouted pouch migration from rigid bottles accelerates machine replacement cycles across beverage and personal care sectors. This format shift creates sustained retrofit demand and first-mover positioning for validated aseptic systems.
For Market Incumbents: Compound defensive positioning through backward integration into precision filling valve production and captive supply of servo-driven sealing stations to reduce European component dependency. Invest in hybrid automation R&D to capture mid-scale processor retrofit demand bridging legacy asset utilization and new format flexibility. Certification investment for FDA 21 CFR Part 11 and EU MDR compliance maintains premium tier access against emerging-market cost optimizers. For New Entrants and Emerging Players: Differentiate on ultrasonic sealing technology pilots for probiotic and medical nutrition applications where thermal-free sealing commands performance premiums. Target underpenetrated Brazilian pharmaceutical packaging clusters where ANVISA's evolving GMP requirements create first-mover advantage for validated aseptic pouch systems. Pursue white-label equipment supply to Indian state-level dairy federations aggregating maintenance spend across distributed processing plants. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across pharmaceutical-grade configurations absorbing 15-20% capex premiums for EU MDR compliance and embedded track-and-trace hardware. Long-term viability favors precision subsystem specialists with regulatory validation depth over commodity component assemblers exposed to stainless steel cost volatility. Acquisition target archetype: hybrid automation specialists bridging automatic filling with semi-automatic changeover. Signal to watch: ANVISA certification bottlenecks clearing for Indian exporters to Brazil indicating regulatory pathway maturation.| Strategic Initiative | Industry Significance |
|---|---|
| Ultrasonic Sealing Technology Deployment | German and Dutch dairy processors pilot thermal-free sealing at 400-500 pouches per minute for sensitive probiotic products. |
| EU MDR Compliance Investment | Medical device manufacturers in France and Germany absorb 15-20% capex premiums for CE marking and traceability mandates. |
| Hybrid Automation Configuration Development | Mid-scale Brazilian and Indian food processors bridge legacy asset utilization and format flexibility through retrofit demand. |
| Extended Producer Responsibility Adaptation | EU Green Deal packaging waste directives mandate recyclable mono-material pouches requiring new sealing chemistry investment. |
| Service Contract Unbundling Response | Indian dairy cooperatives and Brazilian processors now negotiate multi-year maintenance agreements separately from equipment financing. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with packaging machinery OEMs, dairy cooperative procurement heads, pharmaceutical contract manufacturers, and aftermarket service directors; and secondary validation through FDA 510(k) filings, EU MDR technical documentation, BIS certification records, and customs trade data for packaging machinery imports. Bottom-up equipment shipment tallies by technology tier and end-use segment were triangulated against top-down market sizing derived from capital expenditure disclosures of major food and pharmaceutical processors.
Across the analysis window, the forecasting framework modeled volume and value outputs through segmentation across product type, end user, automation technology, and material substrate dimensions. CAGRs were derived from regression analysis of historical installation data against regulatory compliance cycle timing and format migration patterns. Industry-specific forecast inputs included EU MDR upgrade timelines for medical device manufacturers and ANVISA GMP evolution trajectories for Brazilian pharmaceutical packaging.
The analysis sits within stated boundaries; outcomes outside sustained spouted pouch adoption rates or stable stainless steel pricing would require recalibration. Forecasts reflect assumptions regarding regulatory compliance timeline continuity and component supplier lead time stability. Revision becomes warranted when EU MDR certification bottlenecks at notified bodies or ANVISA pathway delays cross thresholds affecting equipment delivery schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Contour Pouches Market
Pouch
Standcap Pouch Market
Pouch
Indonesia Pouch Packaging Market
Pouch
North America Pouch Packaging Market
Pouch
Heat Seal Pouch Market
Pouch
Feminine Care Pouch Film Market
Pouch
Doy Pouch Packaging Market
Pouch
Pre-Made Pouch Packaging Market
Pouch
Aluminum Pouches Market
Pouch
Italy Pouch Packaging Market
Pouch
Middle East and Africa Pouch Packaging Market
Pouch
Portion Control Packs Market
Pouch
Asia-Pacific Retort Pouch Market
Pouch
Child Resistant Single Dose Pouches Market
Pouch
Mexico Pouch Packaging Market
Pouch
Europe Pouch Packaging Market