
 Anti-Fog Lidding Films Market | 2026-2036
Anti-Fog Lidding Films Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Fog Lidding Films Market Intelligence
High-clarity specification tiers is redrawing competitive dynamics in anti-fog lidding films. Amcor Plc leverages its global manufacturing footprint to supply multi-layer structures for protein packaging. Uflex Ltd. anchors its position through backward integration into resin compounding and biaxial orientation lines. Toray Plastics (America), Inc. specializes in PET-based lidding with controlled crystallinity for steam-hot-fill applications.
Anti-fog lidding films are thin, heat-sealable flexible webs engineered with surface-active additives or nano-coatings to maintain optical transparency across temperature differentials, primarily serving ready-meal and fresh-produce packaging where consumer visual inspection drives purchase decisions. Multi-layer coextruded films lead volume due to their tunable barrier properties and seal-strength reliability, while coated films capture margin pools through premium anti-fog durability and thinner gauge potential. Food packaging dominates application demand, though medical packaging segments are gaining traction as sterilization-compatible lidding requirements tighten.
FDA food-contact substance notifications govern anti-fog additive migration limits in the United States, while EFSA and REACH regulate surfactant chemistry and substance authorization across Europe, compelling reformulation toward bio-based and GRAS-listed alternatives. The EU Green Deal's packaging recyclability targets are forcing film producers to redesign multi-material laminates into mono-polymer or certified-compostable structures. Stakeholders must monitor evolving extended producer responsibility schemes and decide between retrofitting existing coextrusion assets or investing in novel coating deposition technologies.
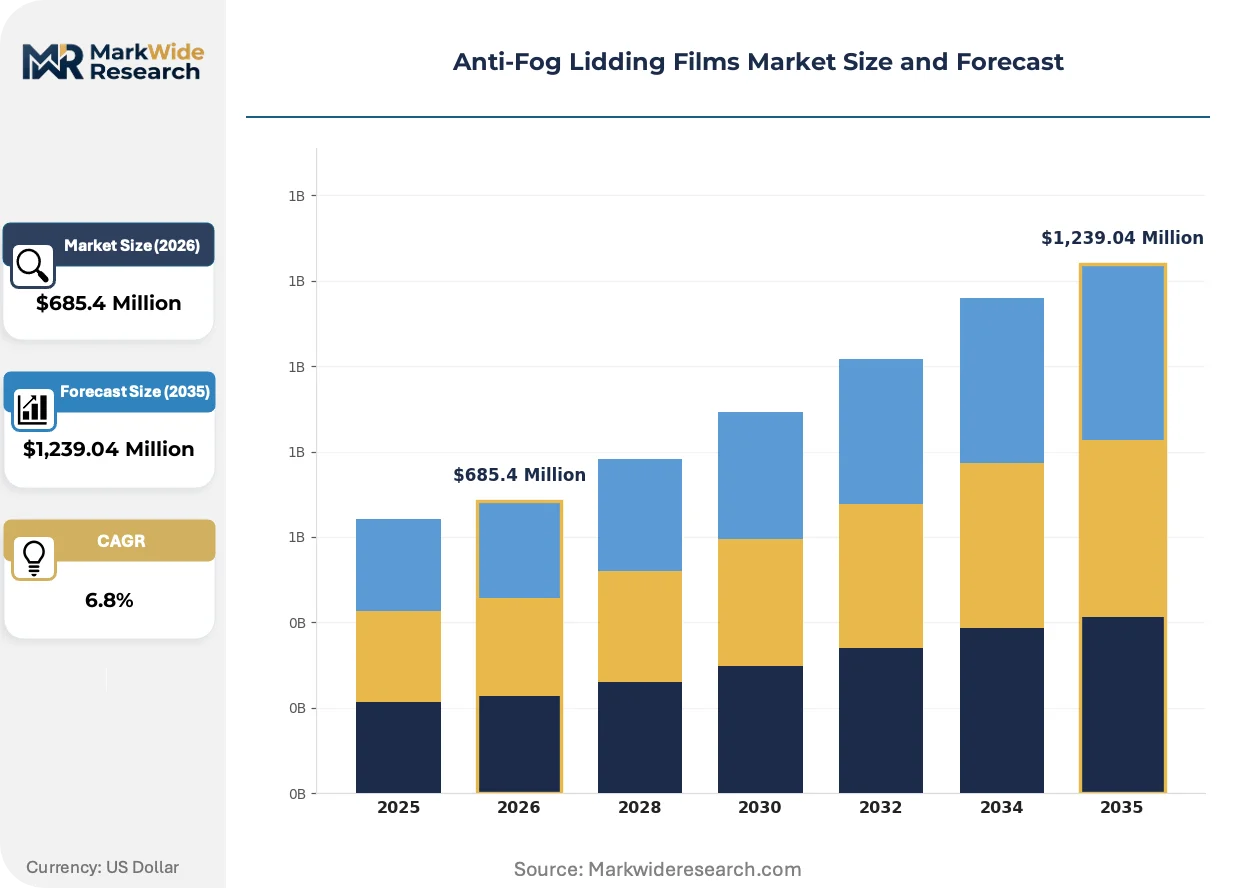
Market Dynamics
The EU's Packaging and Packaging Waste Regulation is compressing design cycles for multi-layer lidding structures, forcing converters to choose between asset retrofitting and greenfield coating investments before recyclability mandates take full effect.
Growth Catalysts
- Fresh Produce Visibility Mandates:German and French retailers now require optical-grade lidding for pre-packaged salads and berries, converting shelf-space metrics directly into film specification tiers.
- REACH Annex XVII Reformulation:ECHA restrictions on perfluorinated surfactants are accelerating migration toward bio-based anti-fog additives derived from vegetable glycerol esters.
- Steam-Hot-Fill Protein Packaging:Ready-meal processors in Lower Saxony are specifying PET-based lidding with controlled crystallinity to survive retort temperatures without haze formation.
Market Restraints
- Ethylene-Vinyl Alcohol Copolymer Supply Concentration:Three Japanese and Korean resin suppliers control high-barrier EVOH grades essential for oxygen-sensitive produce, exposing converters to allocation risk during petrochemical disruptions.
- Multi-Material Laminate Recycling Infrastructure Gap:Current mechanical separation systems cannot recover PE-tie-EVOH-PET structures, forcing producers to absorb extended producer responsibility fees in Germany and France.
- Silicone Anti-Fog Coating Durability Limitation:Surface-active coatings degrade after 14-21 days in high-humidity cold chain environments, limiting adoption for export-oriented seafood packaging.
Strategic Opportunities
- Medical Device Sterilization Lidding:Gamma-stable anti-fog films for surgical kit packaging remain underpenetrated in the United States, where FDA 510(k) clearance pathways favor established material master files.
- Mono-Polymer PP Structures:Borealis and LyondellBasell are developing high-clarity random copolymer grades that enable full-polypropylene lidding recyclable within existing European streams.
- Direct-to-Retailer E-Commerce Channels:Fresh meal-kit distributors are bypassing traditional converter-distributor networks, creating specification relationships with film producers for customized roll widths and printed branding.
Industry Challenges
- Multi-Layer Coextrusion Operator Skill Gap:Die gap adjustment for layer uniformity requires 18-24 month apprenticeship periods, constraining capacity expansion at mid-tier converters in Bavaria.
- ISO 17025 Migration Testing Backlog:Third-party laboratories in Europe report 12-16 week queues for anti-fog additive extraction studies, delaying product launches for reformulated bio-based chemistries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Fog Lidding Films Market |
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Layer Films, Multi-Layer Films, Coated Films, Laminated Films Material: Polypropylene, Polystyrene, PVC, PET Application: Food Packaging, Medical Packaging, Consumer Goods, Electronics Packaging End User: Food Industry, Healthcare, Pharmaceuticals, Retail |
| Companies Covered | Amcor Plc, Uflex Ltd., Toray Plastics (America), Inc., Plastopil Hazorea Company Ltd, Effegidi International S.p.A., Mondi Plc, Sealed Air Corporation, ProAmpac Holdings Inc., Winpak Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Fog Lidding Films Market Strategic Shifts & Innovations
Anti-fog lidding film development is pivoting from barrier-performance optimization toward optical consistency under extreme temperature differentials, with coating deposition and resin crystallinity control emerging as the primary technical battlegrounds.
Plasma-enhanced chemical vapor deposition of nano-scale silica coatings is fragmenting the traditional anti-fog additive market. Poultry and seafood processors in the Netherlands and Belgium are specifying these inorganic layers for 60-day shelf-life requirements. The technology is fragmenting margin pools by enabling sub-25 micron gauges that outperform 40-micron coextruded alternatives on clarity metrics.
EFSA's 2023 re-evaluation of glycerol ester surfactants has triggered reformulation cascades across European compounders. Manufacturers must resubmit food-contact notifications for previously grandfathered chemistries, compressing R&D timelines by 8-12 months. Small and mid-sized converters in Italy and Spain are responding by consolidating purchasing through distributor networks with pre-validated additive portfolios.
Retailers are consolidating fresh-produce lidding specifications around three clarity grades rather than accepting converter-proposed variants. Discounters in Germany now mandate haze values below 5% for premium private-label lines, forcing film producers to install inline optical inspection systems. This consolidation is most visible in the ready-meal segment, where Lidl and Aldi Süd have standardized on two approved suppliers per category.
Anti-Fog Lidding Films Market Segmentation
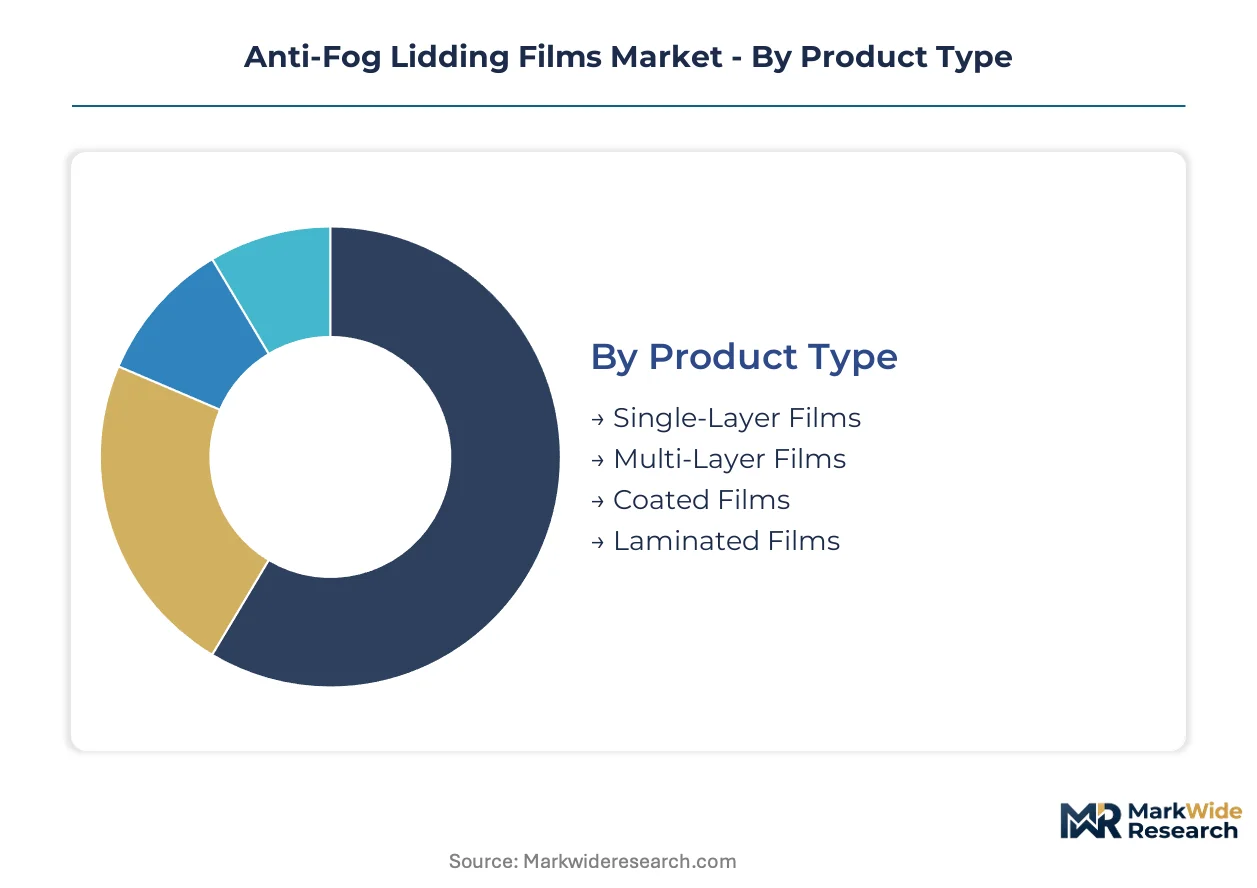
Anti-fog lidding film purchasing decisions split across technical performance tiers and regulatory compliance thresholds. Specification divergence between fresh-produce visibility requirements and medical sterilization standards creates distinct margin architectures within each segment category.
Product Type:
Margin pools concentrate in structures offering tunable barrier properties combined with optical-grade clarity specifications.
- Multi-Layer Films:Coextruded structures with PE-tie-EVOH-PET configurations dominate volume through adjustable oxygen transmission rates and seal-strength reliability. German ready-meal processors in Lower Saxony specify these for retort-compatible lidding where steam-hot-fill survivability determines supplier selection.
- Coated Films:Nano-scale silica or vegetable glycerol ester surface treatments command premium positioning through sub-25 micron gauge potential and extended anti-fog durability. Dutch poultry processors specify plasma-enhanced chemical vapor deposition coatings for 60-day shelf-life export requirements.
- Single-Layer Films:Basic polypropylene structures serve cost-sensitive applications with limited barrier demands.
- Laminated Films:Adhesive-bonded multi-material webs persist in legacy equipment installations despite recyclability compliance pressures.
Multi-Layer Films hold installed capacity. Coated Films is rotating up the share rankings.
Material:
Resin selection determines recyclability pathway eligibility and temperature resistance ceilings.
- PET:Controlled crystallinity grades from Toray Plastics enable steam-hot-fill survivability without haze formation. Bavarian protein packers specify PET-based lidding for dual-ovenable ready-meal trays where optical consistency across temperature differentials drives purchase decisions.
- Polypropylene:High-clarity random copolymer grades from Borealis and LyondellBasell enable mono-polymer structures recyclable within existing European streams. French retailers mandate PP lidding for private-label berry packaging to meet EU Green Deal targets.
- Polystyrene:Crystal grades retain niche presence in cost-optimized fresh produce applications with short cold-chain windows.
- PVC:Phasedown accelerates across European food-contact applications under REACH Annex XVII pressure.
PET commands specification authority in premium tiers. Polypropylene is climbing the fastest as recyclability mandates harden.
Application:
End-use differentiation separates commodity volume from sterilization-validated premium positioning.
- Food Packaging:Fresh produce and ready-meal segments drive specification consolidation around haze-value thresholds below 5% for German discounter private-label lines. Lidl and Aldi Süd have standardized on two approved suppliers per category, compressing converter margins.
- Medical Packaging:Gamma-stable anti-fog films for surgical kit packaging remain underpenetrated in the United States where FDA 510(k) clearance pathways favor established material master files. EMA MDR compliance requirements tighten sterilization validation protocols across European hospital networks.
- Consumer Goods:Cosmetic and personal care applications specify lidding with fragrance-barrier additives.
- Electronics Packaging:Anti-static variants protect moisture-sensitive components during shipment.
Food Packaging anchors volume throughput. Medical Packaging is gaining specification share as sterilization requirements tighten.
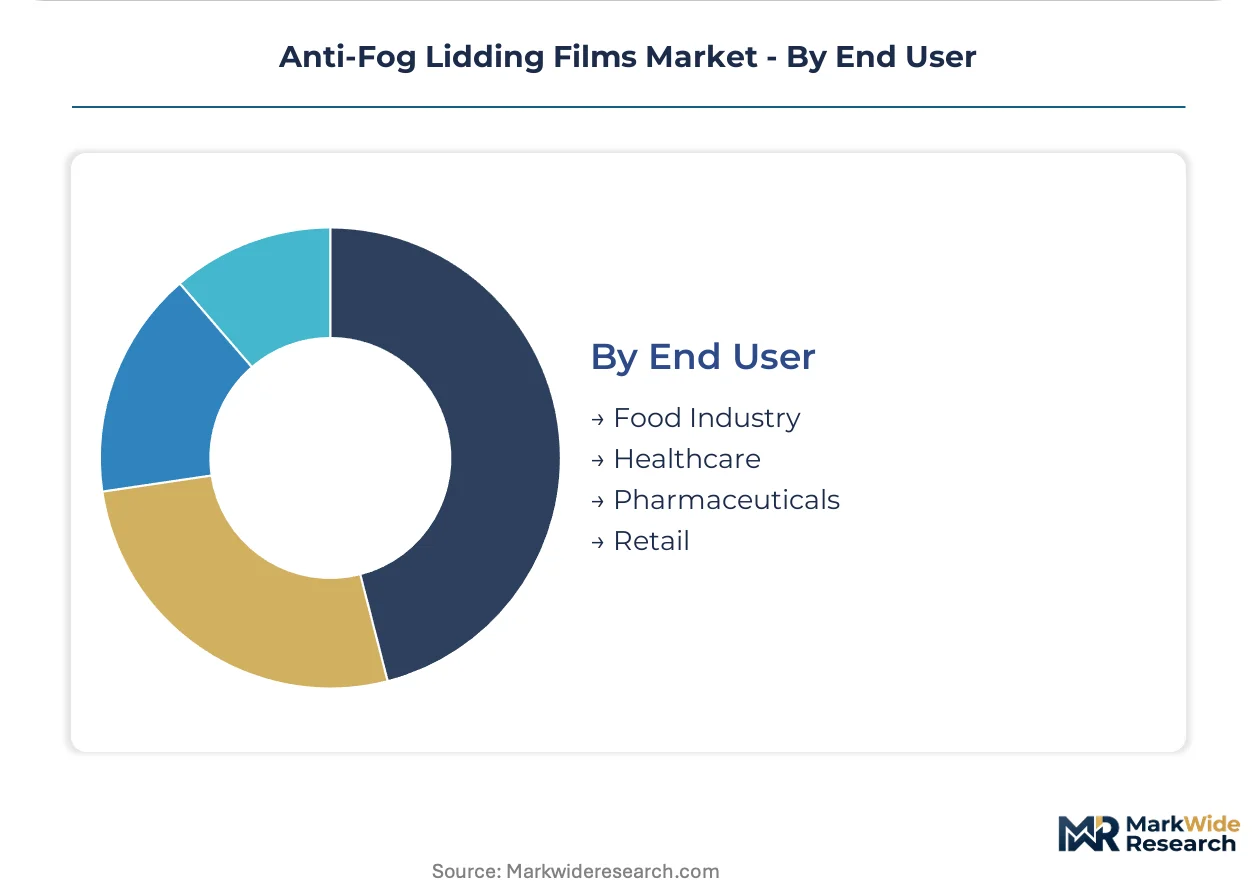
End User:
Procurement authority concentrates with retailers and healthcare systems capable of mandating tiered specification standards.
- Food Industry:Processors in Germany's Lower Saxony and Bavaria corridors specify optical-grade lidding directly with film producers, bypassing traditional converter-distributor networks for customized roll widths and printed branding. Fresh meal-kit distributors drive direct-to-retailer e-commerce channel formation.
- Healthcare:Hospital systems and surgical kit assemblers require gamma-stable lidding with validated master files. FDA 510(k) clearance timelines favor incumbent suppliers with established device history records.
- Pharmaceuticals:Blister pack lidding for moisture-sensitive dosages demands WVTR specifications below 0.5 g/m²/day.
- Retail:Discounters and supermarket chains consolidate supplier panels around three clarity grades rather than accepting converter-proposed variants.
Food Industry maintains procurement volume leadership. Healthcare is ascending fastest as sterilization standards proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German film converters supply anti-fog lidding to fresh-produce packers across the Netherlands and Belgium, forming the dominant trade corridor in European flexible packaging. This export-driven architecture shapes regional capacity placement and specification standards.
Germany
Retailer mandates for sub-5% haze values in private-label berry packaging drive specification consolidation. The EU Packaging and Packaging Waste Regulation forces converters in Lower Saxony to redesign multi-layer structures before recyclability deadlines. Bavarian protein processors specify PET-based lidding with controlled crystallinity for dual-ovenable ready-meal trays.
United States
FDA food-contact substance notifications govern anti-fog additive migration limits for protein and produce packaging. Fresh meal-kit distributors in the Northeast bypass traditional converter networks, sourcing customized roll widths directly from film producers. Gamma-stable lidding for surgical kit packaging remains underpenetrated due to FDA 510(k) clearance timelines favoring established material master files.
Netherlands
Poultry and seafood processors specify plasma-enhanced chemical vapor deposition coatings for 60-day export shelf-life requirements. ECHA restrictions on perfluorinated surfactants accelerate bio-based additive adoption among Rotterdam-area converters. Dutch retailers consolidate supplier panels around three clarity grades, compressing margins for non-approved film sources.
France
Discounters mandate mono-polypropylene lidding for private-label packaging to meet EU Green Deal recyclability targets. EFSA's 2023 glycerol ester re-evaluation triggers reformulation cascades across compounders serving the Île-de-France food processing corridor. Paris-region converters absorb extended producer responsibility fees for legacy multi-material laminates.
Japan
METI guidelines on plastic resource circulation push converters toward mono-material structures compatible with domestic recycling streams. Three resin suppliers control high-barrier EVOH grades essential for oxygen-sensitive produce, exposing Japanese film producers to allocation risk. Osaka-area converters specialize in thin-gauge coated films for premium seafood export packaging.
Anti-Fog Lidding Films Market Key Industry Players
Listed leaders compete with private specialists across specification tiers and geographic coverage, creating a bifurcated structure where scale-driven multinationals anchor premium segments and regional fabricators capture commoditized volume. The vendor base separates into three archetypes: integrated resin-to-film producers with captive compounding assets, coating technology specialists leveraging deposition equipment differentiation, and regional converters serving single-country retailer specifications. Competitive moves concentrate on backward integration into resin compounding and strategic partnerships with meal-kit distributors seeking direct sourcing relationships.
Within the integrated producer tier, Amcor Plc and Uflex Ltd. exemplify scale-driven positioning through multi-layer coextrusion capabilities and geographic manufacturing footprints. Toray Plastics (America), Inc. occupies a specialization niche as a PET-based lidding anchor with crystallinity control expertise. These three entities represent distinct competitive vectors: global supply coverage, backward integration depth, and material-specific technical authority.
| Leading Market Players |
|---|
| Amcor Plc |
| Uflex Ltd. |
| Toray Plastics (America), Inc. |
| Plastopil Hazorea Company Ltd |
| Effegidi International S.p.A. |
| Mondi Plc |
| Sealed Air Corporation |
| ProAmpac Holdings Inc. |
| Winpak Ltd. |
| Others |
Cost & Logistics Intelligence
Long-term offtake contracts between German converters and Japanese EVOH resin suppliers lock in both supply access and price visibility across the forecast window, insulating film producers from petrochemical volatility while constraining flexibility to pivot toward bio-based alternatives.
Pricing Analysis
The technology-generation pricing gap separates plasma-enhanced chemical vapor deposition coated films commanding premium positioning from legacy coextruded multi-layer structures facing cost compression. Three-tier pricing structure across premium, standard, and economy levels stratifies by clarity grade and recyclability certification, with EU Green Deal compliance tiers extracting margin premiums. Price erosion runs through commodity polypropylene lidding as Chinese resin capacity expands. Fresh produce packers in Germany exhibit highest price sensitivity, while medical sterilization lidding buyers prioritize gamma-stability validation over unit cost.
Supply Chain Analysis
Inventory lead times for high-barrier EVOH grades stretch to 16-20 weeks, forcing converters to maintain safety stocks that tie up working capital. Supply concentrates in Japan, South Korea, and Germany, with three resin suppliers controlling oxygen-barrier polymer feedstocks. Raw material dependencies center on ethylene-vinyl alcohol copolymers, glycerol ester surfactants, and PET resin with controlled crystallinity. Single-source vulnerability in EVOH grades exposes converters to allocation risk during petrochemical disruptions. Distribution runs through converter-distributor networks serving retailer private-label specifications, though meal-kit distributors increasingly bypass intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation across specification tiers creates entry niches as retailer consolidation around three clarity grades displaces mid-tier converter relationships.
For Market Incumbents: Compound technical authority in crystallinity-controlled PET lidding for steam-hot-fill applications to defend against coating technology displacement. Deepen backward integration into resin compounding to secure glycerol ester supply chains ahead of EFSA reformulation deadlines. Prioritize capacity retrofitting in Lower Saxony for mono-polymer recyclability compliance. For New Entrants and Emerging Players: Lead with plasma-enhanced chemical vapor deposition coating services for Dutch poultry and seafood exporters demanding 60-day shelf-life specifications. Target medical sterilization lidding in the United States where FDA 510(k) clearance pathways favor new material master files. Pursue direct specification relationships with fresh meal-kit distributors bypassing traditional converter networks. For Investors and Strategic Acquirers: Coating technology specialists with validated plasma deposition equipment represent the most defensible acquisition archetype as nano-scale silica layers displace traditional additive formulations. Long-term viability hinges on recyclability mandate compliance across the European Union. Monitor ECHA substance restriction announcements as inflection indicators for bio-based chemistry migration timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive glycerol ester supply secures EFSA reformulation compliance for European converters. |
| Plasma Deposition Capacity Expansion | Sub-25 micron coated films penetrate Dutch poultry export specifications against thicker coextruded alternatives. |
| Mono-Polymer Structure Development | Full-PP lidding aligns with Lidl and Aldi Süd recyclability mandates in German private-label berry packaging. |
| Medical Device Master File Investment | FDA 510(k) pathway access unlocks gamma-stable surgical kit lidding in underpenetrated United States hospital networks. |
| Direct-to-Retailer Channel Formation | Meal-kit distributor relationships bypass converter-distributor margin compression in e-commerce fresh packaging. |
Research Approach
Initial hypotheses were tested against primary input from film production engineers, retail packaging procurement managers, resin compounding technical directors, and regulatory affairs specialists at food-contact material suppliers and refined through secondary validation against EFSA food-contact notifications, ECHA REACH registrations, EU Packaging and Packaging Waste Regulation impact assessments, and trade data from German flexible packaging associations. Bottom-up capacity modeling triangulated against top-down demand segmentation across product type, material, application, and end-user dimensions.
Variance decomposition across the analysis window isolates volume drivers by segmentation tier, with CAGRs derived from installed capacity expansion schedules, retailer specification consolidation timelines, and regulatory compliance deadline modeling. Segmentation dimensions include film structure technology, resin chemistry, end-use temperature requirements, recyclability pathway eligibility, and geographic regulatory cluster. Forecast inputs incorporate EVOH resin supply allocation scenarios and plasma deposition equipment installation pipelines.
Forecasts assume regulatory continuity in EU REACH and FDA food-contact substance regimes; material policy shifts would require re-modeling of additive migration limits and recyclability target enforcement. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Oxygen Barrier Films and Coatings for Dry Food Market
Packaging Barrier Films
Cryogenic Insulation Films Market
Packaging Barrier Films
Pan Liners Market
Packaging Barrier Films
Barrier Coated Flexible Paper Packaging Market
Packaging Barrier Films
High Barrier Lidding Film Market
Packaging Barrier Films
Heat Seal Coating Market
Packaging Barrier Films
Barrier Coated Carton Market
Packaging Barrier Films
Stretch Hood Films Market
Packaging Barrier Films
Liquid Masking Film Market
Packaging Barrier Films
Aluminum Barrier Laminate (ABL) Tubes Market
Packaging Barrier Films
Sealant Films Market
Packaging Barrier Films
Stretch Films Packaging Market
Packaging Barrier Films
Polyethylene Vapor Barrier Films for Under Slab Market
Packaging Barrier Films
Europe Barrier Coated Paper Market
Packaging Barrier Films
Microwavable Barrier Films Market
Packaging Barrier Films
Global Micro-Perforated Films Market