
 Global Thermoplastic Films Market | 2026-2036
Global Thermoplastic Films Market Size, Share, and Industry Trends Forecast 2026-2036
Global Thermoplastic Films Market Foresight
Flexible packaging buyers are bifurcating from industrial wrapping purchasers as sustainability mandates reshape procurement criteria. Covestro leverages its polycarbonate film expertise to anchor positions in medical and electronics applications. BASF sustains competitive pressure through differentiated specialty polyamide grades for high-barrier food packaging.
Thermoplastic films are polymer-based sheet materials manufactured through cast, blown, or extrusion processes with thicknesses typically ranging from 12 micrometers to 250 micrometers, engineered for barrier protection, electrical insulation, or structural adhesion across industrial and consumer applications. Polyethylene films dominate volume shipments due to cost-efficient blown film production serving mass-market flexible packaging, while polyamide films command premium positions in vacuum-formed automotive and aerospace components where thermal resistance justifies higher unit economics. Cast films occupy mature margin pools in optical and display applications, whereas coated and laminated film constructions are capturing growth in pharmaceutical blister packaging demanding multi-layer barrier performance.
REACH in Europe, FDA food-contact regulations in the United States, and China's GB standards collectively elevate compliance costs for resin formulation and additive migration limits, effectively filtering smaller compounders from medical and food-grade supply chains. ECHA's expanding restriction candidate list is forcing reformulation of plasticizers and stabilizers across PVC and flexible packaging segments. Stakeholders must monitor regulatory divergence between EU chemical strategy ambitions and emerging economy enforcement capacities when allocating technical service and certification investments.
Market Dynamics
Flexible packaging buyers are decoupling from industrial film purchasers as sustainability mandates and food-contact compliance reshape procurement criteria across polyethylene and polypropylene supply chains.
Growth Catalysts
- REACH compliance deadlines:ECHA's expanding restriction candidate list accelerates reformulation of plasticizers and stabilizers, filtering smaller compounders from medical and food-grade supply chains and consolidating demand among certified processors in Germany and France.
- Blown film capacity expansion:Converting investments in China and India scale polyethylene output for mass-market flexible packaging serving beverage and fresh-produce distribution networks.
- Pharmaceutical blister packaging:Multi-layer barrier constructions capture volume as CDSCO and FDA alignment on migration limits drives specification upgrades across oral-solid-dose formats.
Market Restraints
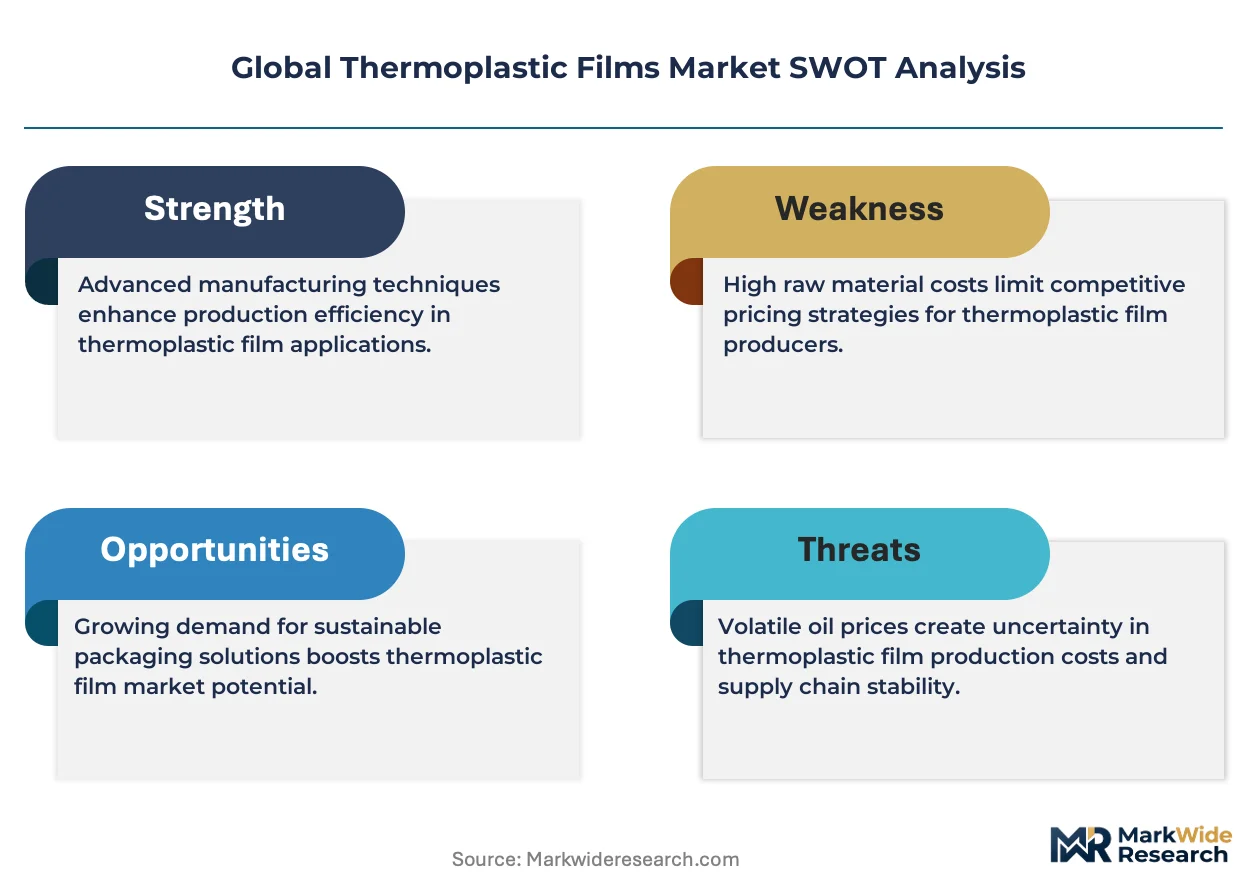
- Crude-linked resin volatility:Naphtha and ethylene feedstock costs swing with Brent crude movements, compressing margin stability for commodity polyethylene film extruders serving price-sensitive flexible packaging accounts.
- Cast film supply concentration:Optical-grade capacity clusters in Japan and South Korea, creating bottleneck risk for display and electronics laminators dependent on thin-gauge polycarbonate and cyclic olefin polymer substrates.
- Mechanical recycling contamination thresholds:FDA and EFSA food-contact approvals for post-consumer recycled content remain restrictive, limiting closed-loop adoption in direct-contact packaging applications.
Strategic Opportunities
- India's PLI scheme for specialty chemicals:Domestic polyamide and polyester film investments qualify for production-linked incentives, reducing import dependence for automotive and electrical insulation grades.
- Bio-based barrier coatings:Cellulose nanofibril and chitosan surface treatments converge with conventional extrusion lines to enable compostable flexible packaging structures without capital-intensive line replacement.
- Direct-to-brand e-commerce channels:Specialty film converters bypass traditional distribution tiers to serve mid-sized food and cosmetics brands seeking shorter-run customized barrier specifications.
Industry Challenges
- Migration testing capacity:EFSA and FDA food-contact notification backlogs extend certification timelines for novel additive packages, delaying commercialization of reformulated high-clarity films.
- Multi-layer delamination:Separating incompatible polymer layers in post-consumer waste streams requires solvent-based or thermal processes that conflict with mechanical recycling infrastructure investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Thermoplastic Films Market |
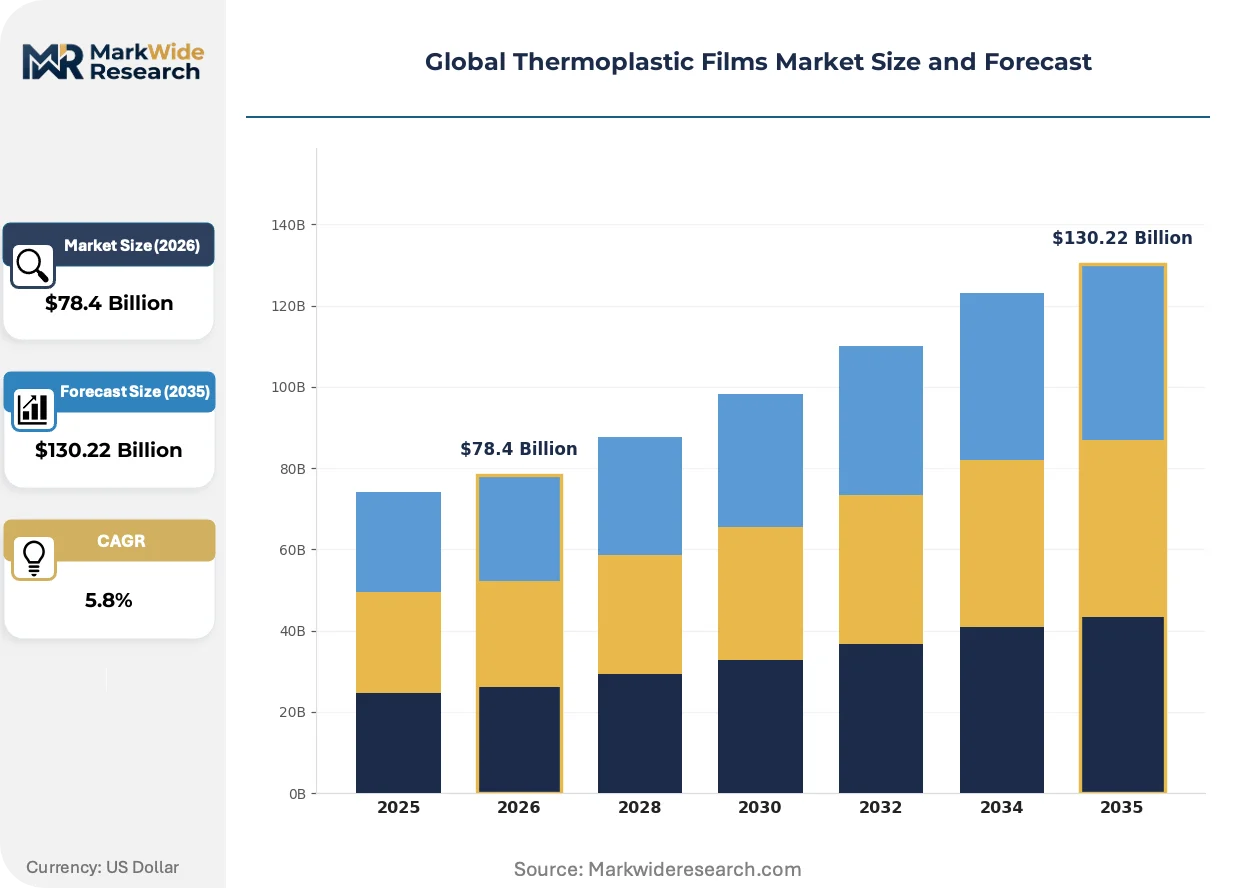
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $130.22 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Film Type: Polyethylene, Polypropylene, Polyvinyl Chloride, Polyethylene Terephthalate, Polyamide, Polystyrene Application: Flexible Packaging, Electrical Insulation, Industrial Wrapping, Agricultural Films, Consumer Goods, Protective Coverings End User Industry: Packaging Manufacturers, Electrical Equipment Producers, Agricultural Suppliers, Consumer Products Companies, Construction Firms, Textile Suppliers Form: Cast Films, Blown Films, Extruded Films, Coated Films, Laminated Films, Vacuum-Formed Films |
| Companies Covered | Covestro, BASF, Huntsman Corporation, Lubrizol Corporation, 3M, Dow, DuPont, Sika, SWM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Thermoplastic Films Market Shifts & Advancements
Film manufacturing is bifurcating between commodity scale and specialty precision as digital printing, barrier coextrusion, and regulatory traceability reshape technical requirements across end-use verticals.
Mono-material polyethylene constructions are fragmenting legacy multi-layer flexible packaging specifications. Retailers and brand owners in France and the Netherlands accelerate adoption of all-polyethylene pouches to meet Extended Producer Responsibility sorting requirements. The technology is fragmenting incumbent adhesive lamination demand while creating specification chaos as converters balance seal performance against recyclability claims.
EU Green Deal packaging waste regulations are compressing permissible polymer combinations in single-use formats. The delegated acts under revision mandate design-for-recycling criteria that disqualify conventional PET/PE/EVOH structures from premium shelf placement. Food and personal care brands in Germany and Italy respond with simplified coextruded barrier films sacrificing some oxygen protection for sorting-stream compliance.
Brand technical audits now penetrate tier-three resin suppliers. Major beverage and snack manufacturers in the United States deploy blockchain-anchored batch tracking from polymer pellet through finished laminate, displacing paper-based chain-of-custody documentation. The practice concentrates specification power with vertically integrated compounders capable of real-time additive and migration data disclosure.
Global Thermoplastic Films Market Segmentation
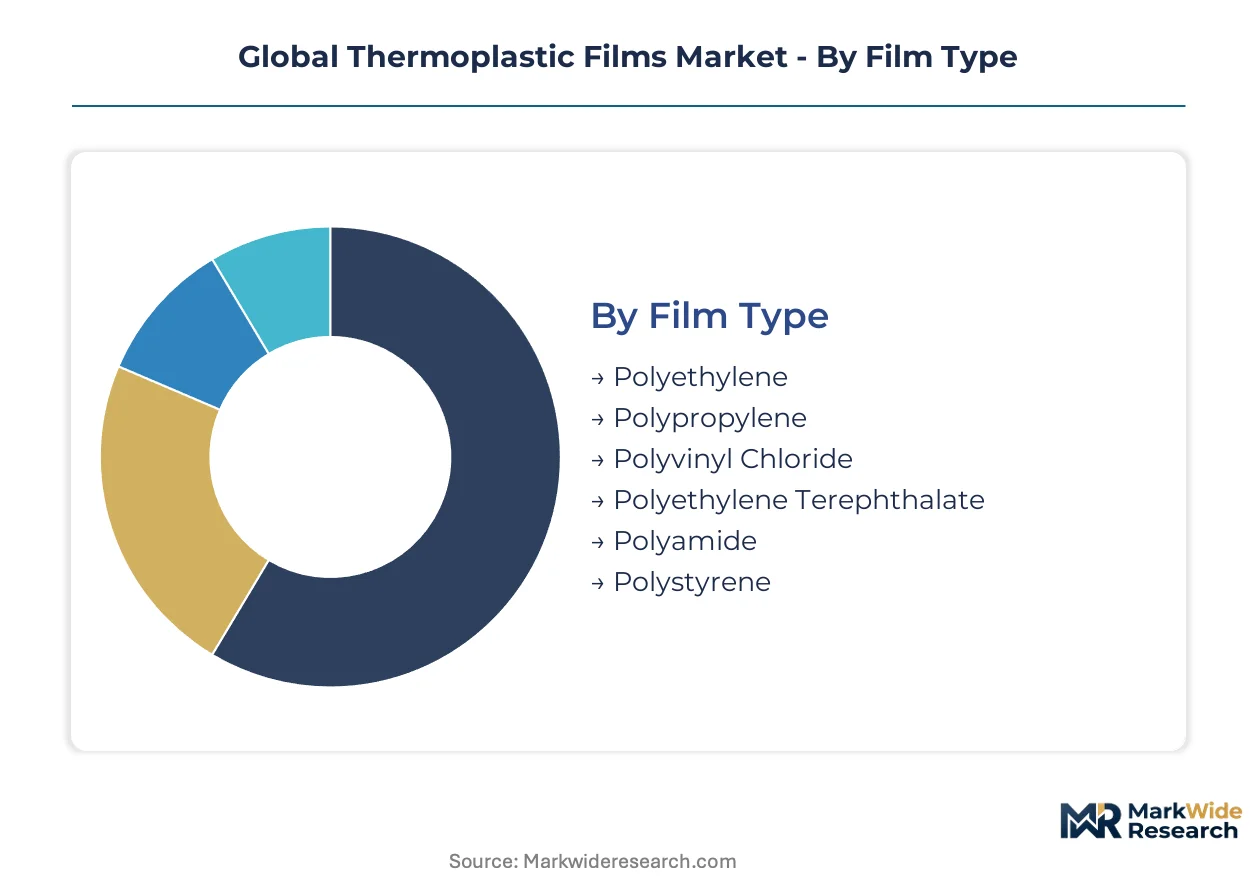
Thermoplastic films fragment across polymer chemistry, manufacturing process, and end-use performance requirements. Buyers select film constructions based on barrier specifications, thermal tolerance, and regulatory compliance thresholds rather than commodity pricing alone.
Film Type:
Polyethylene and polypropylene dominate domestic consumption in China and India, while polyamide and specialty grades sustain export-led demand from Germany and Japan.
- Polyethylene:Low-density and linear-low-density variants manufactured through blown film extrusion serve mass-market flexible packaging for fresh produce and frozen foods. Demand concentrates in domestic Chinese beverage distribution networks where cost-efficient barrier performance outweighs premium specifications.
- Polypropylene:Biaxially oriented and cast unoriented grades deliver higher thermal resistance and clarity for retort pouches and microwaveable formats. Export-led demand from Thai and Vietnamese converting clusters supplies Japanese and Australian food brands requiring FSSAI and FDA dual compliance.
- Polyvinyl Chloride:Plasticized formulations for medical blister packs and shrink sleeves face REACH restriction pressure across European pharmaceutical supply chains.
- Polyethylene Terephthalate:Biaxially oriented PET films anchor optical display and electronics lamination demand from South Korean and Taiwanese panel manufacturers.
- Polyamide:Nylon 6 and nylon 66 grades command premium positioning in vacuum-formed automotive underhood components and aerospace insulation.
- Polystyrene:High-impact and oriented polystyrene films serve specialty release liner and medical diagnostic applications with limited volume scale.
Polyethylene commands the established base. The steepest expansion runs through polyamide as automotive electrification multiplies thermal management film requirements.
Application:
Flexible packaging absorbs the highest volume throughput, while electrical insulation and agricultural films diverge on margin structure and customer concentration.
- Flexible Packaging:Multi-layer coextruded and adhesive-laminated constructions protect food, beverage, and personal care products from moisture, oxygen, and light degradation. Brand owners in France and the Netherlands now specify mono-material polyethylene designs to satisfy Extended Producer Responsibility sorting mandates.
- Electrical Insulation:Polypropylene and polyester films engineered for dielectric strength and thermal endurance separate conductive layers in motors, capacitors, and battery packs. Demand clusters around German automotive wiring harness suppliers and Chinese electric vehicle battery manufacturers.
- Industrial Wrapping:Stretch and shrink films palletize goods for logistics networks, competing primarily on meterage cost and cling performance.
- Agricultural Films:Greenhouse covers, mulch films, and silage wraps stabilize crop yields across Mediterranean and Southeast Asian growing regions.
- Consumer Goods:Overwrap and form-fill-seal applications for household products balance printability against seal initiation temperature.
- Protective Coverings:Temporary surface guards for electronics, appliances, and automotive panels during assembly and shipping.
Flexible packaging generates the dominant revenue pool. Electrical insulation claims the most rapid ascent as powertrain electrification multiplies film-intensive components.
End User Industry:
Packaging manufacturers source commodity grades through annual volume contracts, while electrical equipment producers negotiate specification-driven supply agreements with technical service attachments.
- Packaging Manufacturers:Converters of flexible pouches, bags, and wraps purchase polyethylene and polypropylene masterbatches for food-contact applications. Major accounts in Germany and Italy now audit tier-three resin suppliers for blockchain-anchored batch traceability.
- Electrical Equipment Producers:Manufacturers of motors, transformers, and capacitors specify polypropylene and PET films for slot liners, phase insulation, and dielectric barriers. Japanese and South Korean electronics assemblers dominate premium demand.
- Agricultural Suppliers:Distributors of greenhouse and mulch films serve farming cooperatives across Spain, Italy, and Vietnam with UV-stabilized polyethylene constructions.
- Consumer Products Companies:Personal care and household goods brands balance shelf appeal against recyclability claims in film specification.
- Construction Firms:Vapor barriers, waterproofing membranes, and temporary protective films utilize PVC and polyethylene grades with limited performance differentiation.
- Textile Suppliers:Heat-transfer films and synthetic leather substrates employ polyurethane and polyamide constructions for apparel and automotive upholstery applications.
Packaging manufacturers anchor volume demand. Electrical equipment producers drive the sharpest specification upgrades as efficiency regulations tighten insulation performance thresholds.
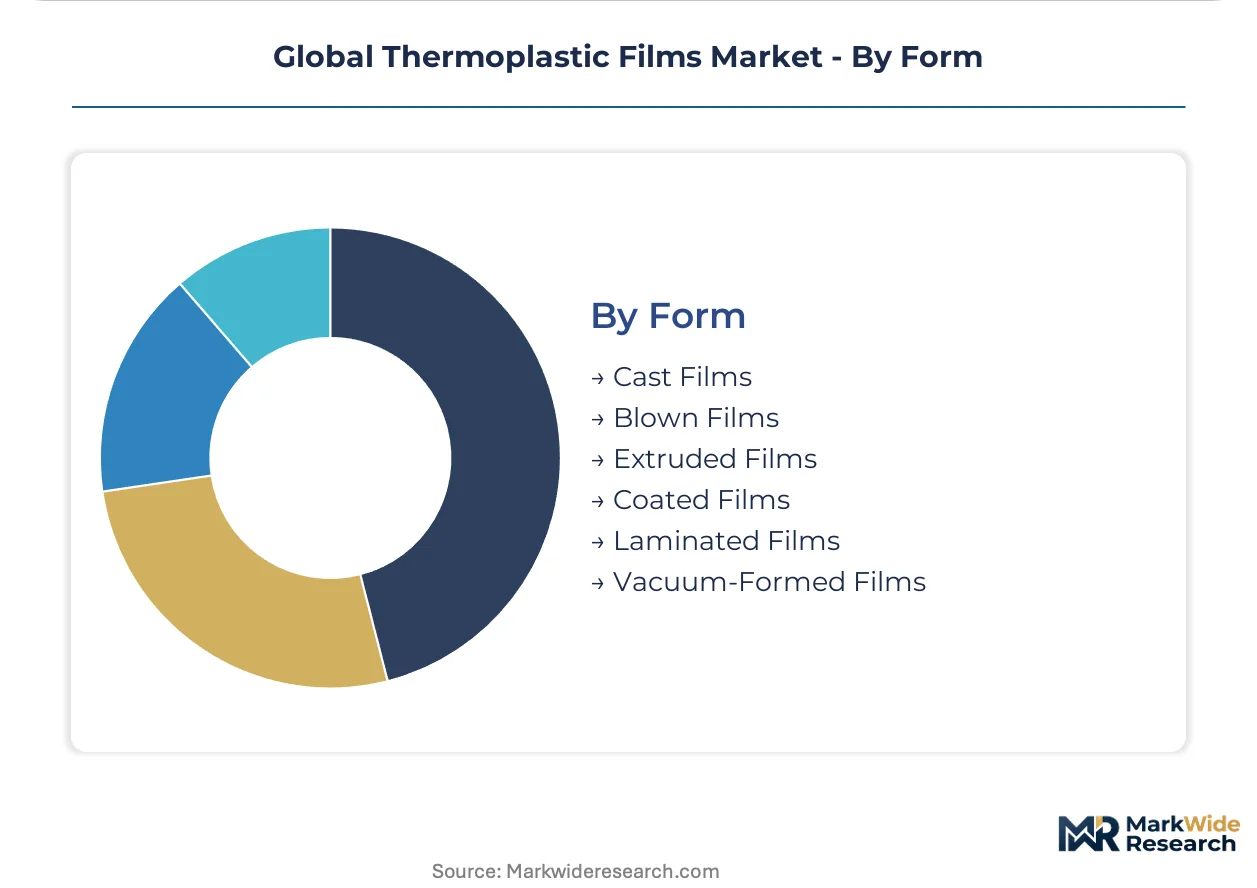
Form:
Blown film capacity concentrates in China and India for domestic flexible packaging, while cast and coated film production clusters in Japan and Germany for export-oriented optical and medical applications.
- Cast Films:Chill-roll extrusion produces optically clear, gauge-precise films for display laminates and medical packaging. Japanese and South Korean producers dominate thin-gauge polycarbonate and cyclic olefin polymer supply.
- Blown Films:Tubular extrusion with internal bubble cooling yields biaxially balanced mechanical properties for shrink wrap, stretch film, and general-purpose bags. Chinese and Indian converters scale capacity to serve domestic retail distribution expansion.
- Extruded Films:Flat-die extrusion covers medium-performance applications with lower capital intensity than cast or oriented alternatives.
- Coated Films:Surface deposition of barrier coatings—aluminum oxide, silicon oxide, or polymer nanolayers—enhances oxygen and moisture protection for pharmaceutical blister packs.
- Laminated Films:Adhesive and extrusion lamination bond dissimilar polymer layers for multi-functional barrier constructions, though recyclability concerns now constrain specification growth.
- Vacuum-Formed Films:Heated sheet thermoforming shapes polyamide and ABS blends into automotive interior and aerospace cabin components.
Blown films sustain the volume foundation. Coated films capture the most aggressive expansion as pharmaceutical barrier requirements tighten and delamination-resistant constructions penetrate oral-solid-dose formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Flexible packaging converters in China, India, and Germany absorb the highest film volumes as food distribution networks expand and sustainability mandates tighten material specifications across pharmaceutical and consumer goods supply chains.
China
Domestic beverage brands and fresh-produce distributors scale blown polyethylene film purchases for cost-efficient barrier packaging. GB standards on food-contact materials enforce stricter additive migration limits, filtering smaller compounders from medical-grade supply chains. Converting capacity clusters in Zhejiang and Guangdong provinces where cast and blown film lines serve both domestic retail and export laminators.
India
Snack food manufacturers and dairy cooperatives drive polypropylene film demand for extended shelf-life formats. The PLI scheme for specialty chemicals subsidizes domestic polyamide and polyester film investments, reducing import dependence for automotive and electrical insulation grades. Converting hubs in Maharashtra and Gujarat expand biaxially oriented film capacity to serve Southeast Asian export markets.
Germany
Automotive suppliers and pharmaceutical packagers specify high-barrier polyamide and coated films for thermal management and blister applications. REACH compliance deadlines and ECHA's expanding restriction candidate list accelerate reformulation of plasticizers, consolidating demand among certified processors. Industrial film production concentrates in North Rhine-Westphalia and Bavaria where technical service capabilities anchor European medical-device supply chains.
United States
Major beverage and snack manufacturers deploy blockchain-anchored batch tracking from polymer pellet through finished laminate, displacing paper-based chain-of-custody documentation. FDA food-contact notification backlogs extend certification timelines for novel additive packages, delaying commercialization of reformulated high-clarity films. Flexible packaging converters in the Midwest and Southeast scale mono-material polyethylene constructions to meet retailer Extended Producer Responsibility requirements.
Japan
Electronics assemblers and display manufacturers import thin-gauge polycarbonate and cyclic olefin polymer substrates for optical lamination. METI efficiency regulations tighten insulation performance thresholds for polypropylene films in motor and capacitor applications. Cast film production concentrates in the Chubu and Kansai regions where gauge precision serves premium electronics and medical packaging demand.
Global Thermoplastic Films Market Competitive Landscape
Player mix skews toward diversified chemical conglomerates with captive resin supply and specialty film converters with technical service attachments. BASF and Covestro anchor the European premium tier through differentiated polyamide and polycarbonate grades, while Asian compounders compete on polyethylene volume scale. Strategic moves concentrate on backward integration into polymer production and geographic expansion into India and Southeast Asia to capture PLI-subsidized growth.
Within the diversified chemical tier, BASF and Covestro exemplify European competitors leveraging material science expertise to anchor positions in medical and electronics applications. Dow and DuPont occupy North American positions spanning commodity polyethylene through specialty barrier constructions. SWM and Sika represent mid-scale specialists concentrating on coated and laminated film architectures for pharmaceutical and construction end-uses.
| Leading Market Players |
|---|
| Covestro |
| BASF |
| Huntsman Corporation |
| Lubrizol Corporation |
| 3M |
| Dow |
| DuPont |
| Sika |
| SWM |
| Others |
Supply & Pricing Matrix
Mono-material polyethylene substitution for multi-layer laminates is redrawing supply geography toward China and India while collapsing premium pricing tiers previously sustained by complex barrier constructions. This displacement concentrates volume purchasing power with domestic Chinese beverage brands and Indian snack manufacturers, forcing European and Japanese specialty film producers to defend margins through certification-intensive medical and electronics grades.
Pricing Analysis
Technology-generation pricing gaps separate legacy blown-film commodity tiers from next-generation coated barrier films and prior-generation cast optical grades. Three-tier pricing structure across premium, standard, and economy levels reflects FDA and REACH certification status, with migration-tested medical grades commanding substantial premiums over food-contact baselines. Cost compression in commodity polyethylene runs through crude-linked naphtha volatility, while price erosion in standard tiers reflects Chinese overcapacity. Brand owners in France and the Netherlands exhibit lowest price sensitivity for blockchain-traceable supply chains, whereas Indian dairy cooperatives and Southeast Asian produce distributors anchor the economy tier with volume-driven procurement.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes and port congestion at Rotterdam and Hamburg inflate landed costs for Japanese optical-grade substrates and German pharmaceutical films. Resin supply concentrates in Saudi Arabia, South Korea, and the United States for polyethylene feedstock, while polyamide polymerization clusters in Germany, China, and Japan. Raw material dependencies rest on naphtha crackers, adipic acid for nylon, and bisphenol-A for polycarbonate. Single-source vulnerability concentrates in thin-gauge cast film capacity at Chubu and Kansai regions. Distribution runs through converter-direct relationships for specialty grades and regional distributors for commodity blown film.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face a substitution defense against bio-based barrier coatings and cellulose nanofibril surface treatments that threaten conventional extrusion-based film architectures. Mono-material recyclability mandates and compostable packaging specifications demand strategic repositioning before regulatory deadlines consolidate specification power.
For Market Incumbents: Secure backward integration into polymer production to capture margin pools eroded by resin volatility, particularly in Saudi and South Korean naphtha supply. Deepen certification investments for FDA and EFSA food-contact approvals to filter smaller compounders from medical-grade supply chains. Capacity additions in Maharashtra and Gujarat under India's PLI scheme will anchor Southeast Asian export positions against Chinese overcapacity. For New Entrants and Emerging Players: Technical service gaps in blockchain-anchored batch traceability and real-time migration data disclosure present white-space opportunities for mid-sized converters. Direct-to-brand e-commerce channels serving French and Dutch retailers seeking shorter-run customized barrier specifications offer the most penetrable entry point. Target automotive electrification demand for polyamide thermal management films where German and Japanese incumbents face capacity constraints. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated compounders with captive resin supply and regulatory certification depth. Long-term viability hinges on exposure to pharmaceutical barrier films and electrical insulation grades rather than commodity flexible packaging. Acquisition targets should demonstrate ECHA pre-registration dossiers and CDSCO alignment capabilities. Watch FDA food-contact notification backlog resolution as the inflection signal for novel additive commercialization timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Production | Captive naphtha and adipic acid supply insulates margin stability from Brent crude swings. |
| Green Manufacturing Transition | Bio-based barrier coatings align with EU Green Deal packaging waste regulations and EPR sorting mandates. |
| Long-term Supply Agreement | Annual volume contracts with German automotive wiring harness suppliers secure polypropylene dielectric film offtake. |
| Joint Venture | PLI-qualified partnerships in Gujarat reduce import dependence for Indian electrical insulation markets. |
| Capacity Expansion | Cast film investments in Chubu region serve South Korean and Taiwanese display panel laminators. |
Research Methodology
Operator-level perspectives from blown film extrusion plant managers, pharmaceutical packaging procurement leads, automotive wiring harness technical directors, and flexible packaging brand managers anchored the qualitative base. These primary inputs combined with secondary validation from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and FDA food-contact notification databases. Bottom-up resin consumption modeling and top-down end-use demand estimates underwent cross-triangulation to reconcile volume figures.
Sensitivity analysis tested forecast robustness across crude price scenarios, regulatory enforcement intensity variations, and substitution elasticity assumptions for bio-based alternatives. The analytical framework segmented volume and value projections across polymer chemistry tiers, manufacturing process types, end-use industry verticals, and regional production hub clusters. CAGRs derived from historical growth pattern analysis and demand driver elasticity modeling incorporated automotive electrification content-per-vehicle trajectories and pharmaceutical blister packaging specification upgrade rates.
Forecasts assume regulatory continuity in REACH enforcement across Germany and France, FDA food-contact notification processing timelines in the United States, and GB standards implementation in China; material policy shifts would require re-modeling. Specific risks include ECHA restriction candidate list expansion accelerating beyond baseline assumptions, mechanical recycling contamination threshold relaxations enabling PCR content penetration, and crude-linked resin cost volatility exceeding historical bands. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Twist Wrap Film Market
Poly film
Polymer Dispersed Liquid Crystal (PDLC) Film Market
Poly film
Hexacomb Packaging Market
Poly film
Global BOPP Films Market
Poly film
Spain Plastic Packaging Films Market
Poly film
France Plastic Packaging Films Market
Poly film
PVC Film for Medical Market
Poly film
In-Mould Label Film Market
Poly film
Colombia Plastic Packaging Films Market
Poly film
Polyethylene Film Market
Poly film
Synthetic and Bio Thermoplastic Polyurethane (TPU) Films Market
Poly film
PP Film Blowing Machine Market
Poly film
Brazil Plastic Packaging Films Market
Poly film
Thermoplastic Polyurethane (TPU) Films Market
Poly film
Tube Laminating Films Market
Poly film
Polyolefin Battery Separator Films Market