
 Heat Seal Coating Market | 2026-2036
Heat Seal Coating Market Size, Share, and Industry Trends Forecast 2026-2036
Heat Seal Coating Market Outlook
The divergence between premium performance grades and commodity polyethylene tiers is shifting procurement patterns across converter networks. BASF SE leverages its polymer research infrastructure to sustain high-barrier coating portfolios for pharmaceutical blister films. Henkel AG & Co. KGaA anchors European flexible packaging demand through specialized hot-melt adhesive platforms. Michelman, Inc. competes in water-based niches where regulatory pressure on solvent emissions intensifies specification requirements.
Heat seal coating denotes a thermally activated adhesive layer, typically formulated from ethylene-vinyl acetate copolymers or polyolefin dispersions, that bonds substrates at 80–180°C to form hermetic seals in packaging operations. Water-based technology leads volume shipments but carries thinner margin pools due to formulation commoditization, while solvent-based systems retain premium positioning in high-speed pharmaceutical lines where seal integrity thresholds are non-negotiable. Flexible packaging applications capture the dominant share of industry vertical demand, though electronics segment growth in moisture-barrier pouch formats is accelerating fastest from a smaller base.
EMA and REACH frameworks in Europe restrict residual monomer content and mandate substance-of-very-high-concern disclosure across coating supply chains, pushing reformulation investments toward compliant chemistries. FDA regulations in the United States govern indirect food additive migration limits, creating divergent testing burdens for suppliers serving dual export markets. Stakeholders must monitor evolving PFAS restrictions in both jurisdictions, as fluorinated barrier additives face phased elimination timelines that will force substrate-level redesigns across multiple packaging categories.
Market Dynamics
REACH compliance deadlines and the EU Green Deal are forcing coating manufacturers to abandon solvent-based formulations, compressing reformulation timelines while water-based alternatives mature in performance parity.
Growth Catalysts
- Flexible food packaging:Multinational CPG brands are expanding mono-material pouch formats that require heat-activated bonding layers compatible with existing filling equipment.
- REACH substance disclosure:ECHA mandates on substances of very high concern are accelerating specification switches toward compliant water-based chemistries among European converters.
- Pharmaceutical blister films:Moisture-barrier requirements in oral solid dose packaging are elevating demand for high-integrity seal coatings in Germany and Switzerland.
Market Restraints
- Ethylene-vinyl acetate price volatility:Crude oil derivative costs swing coating margins unpredictably, squeezing formulators without long-term feedstock contracts.
- German converter concentration:Packaging film production clusters in Baden-Württemberg and Bavaria create geographic supply risk for coating distributors serving broader European demand.
- PFAS elimination timelines:Fluorinated barrier additives face phased restrictions under ECHA and EPA frameworks, forcing substrate redesigns without drop-in replacements.
Strategic Opportunities
- Electronics moisture-barrier pouches:Semiconductor and battery component packaging is emerging as a high-specification application with faster growth rates than food verticals.
- Water-based hot-melt convergence:Hybrid formulations combining aqueous carrier systems with reactive hot-melt functionality are opening pharmaceutical lines previously closed to water chemistry.
- India FSSAI packaging standards:Evolving food contact material regulations are creating first-mover advantage for compliant coating suppliers in a historically solvent-dominated market.
Industry Challenges
- Migration testing capacity:FDA indirect food additive protocols and EFSA compliance documentation are overwhelming analytical laboratories, extending product qualification timelines.
- Legacy equipment retrofit:Water-based coating viscosity and drying profiles often conflict with existing solvent-optimized coating lines, requiring capital-intensive line modifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heat Seal Coating Market |
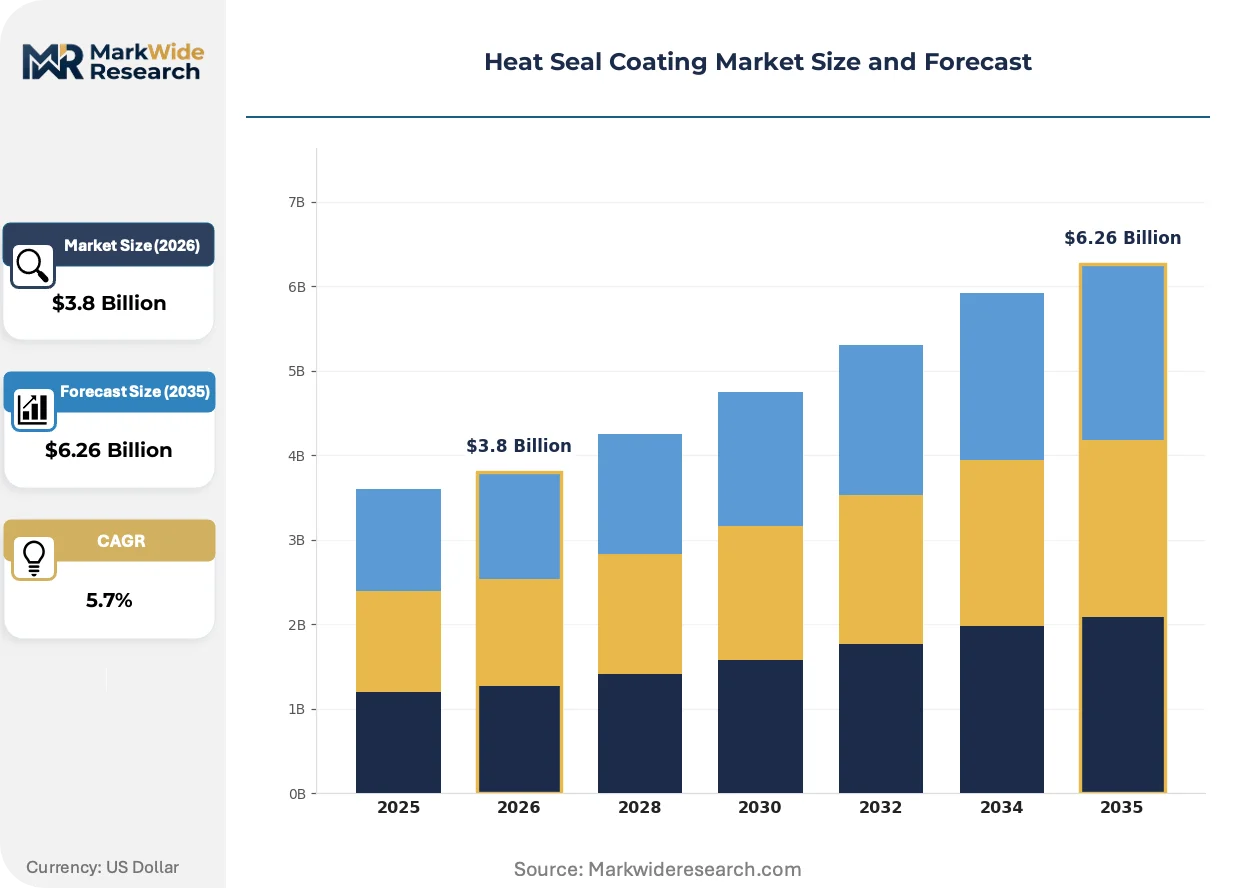
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, Nylon, Others Industry Vertical: Food Packaging, Pharmaceutical Packaging, Consumer Goods, Electronics Application: Flexible Packaging, Rigid Packaging, Labeling, Sealant Films Technology: Hot Melt, Cold Seal, Solvent-Based, Water-Based |
| Companies Covered | BASF SE, Evonik Industries AG, Henkel AG & Co. KGaA, Michelman, Inc., 3M Company, H.B. Fuller Company, Arkema SA, DuPont de Nemours, Inc., Dow Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heat Seal Coating Market Strategic Shifts
Reformulation pressures are converging with digital printing adoption to reshape how converters specify coating systems, creating demand for chemistries that bond at lower temperatures without compromising line speeds.
Water-based polyolefin dispersions are unifying the performance gap between aqueous and solvent systems. Pharmaceutical blister film manufacturers in Germany and Switzerland are piloting these formulations at commercial scale. This unification is compressing the premium pricing power historically held by solvent-based suppliers.
EMA and ECHA coordination on PFAS restriction proposals is tightening substance authorization pathways. Coating formulators must now submit comprehensive safety dossiers for fluorinated chemistries previously grandfathered under legacy regulations. Pharmaceutical packaging lines in Germany and France are accelerating qualification of PFAS-free barrier alternatives ahead of enforcement dates.
Specification consolidation among multinational CPG brands is displacing fragmented regional procurement. Centralized technical teams at headquarters now mandate coating platforms across multiple converting sites, favoring suppliers with global formulation consistency and unified regulatory documentation. This pattern is most visible in North American and European flexible packaging networks.
Heat Seal Coating Market Segmentation
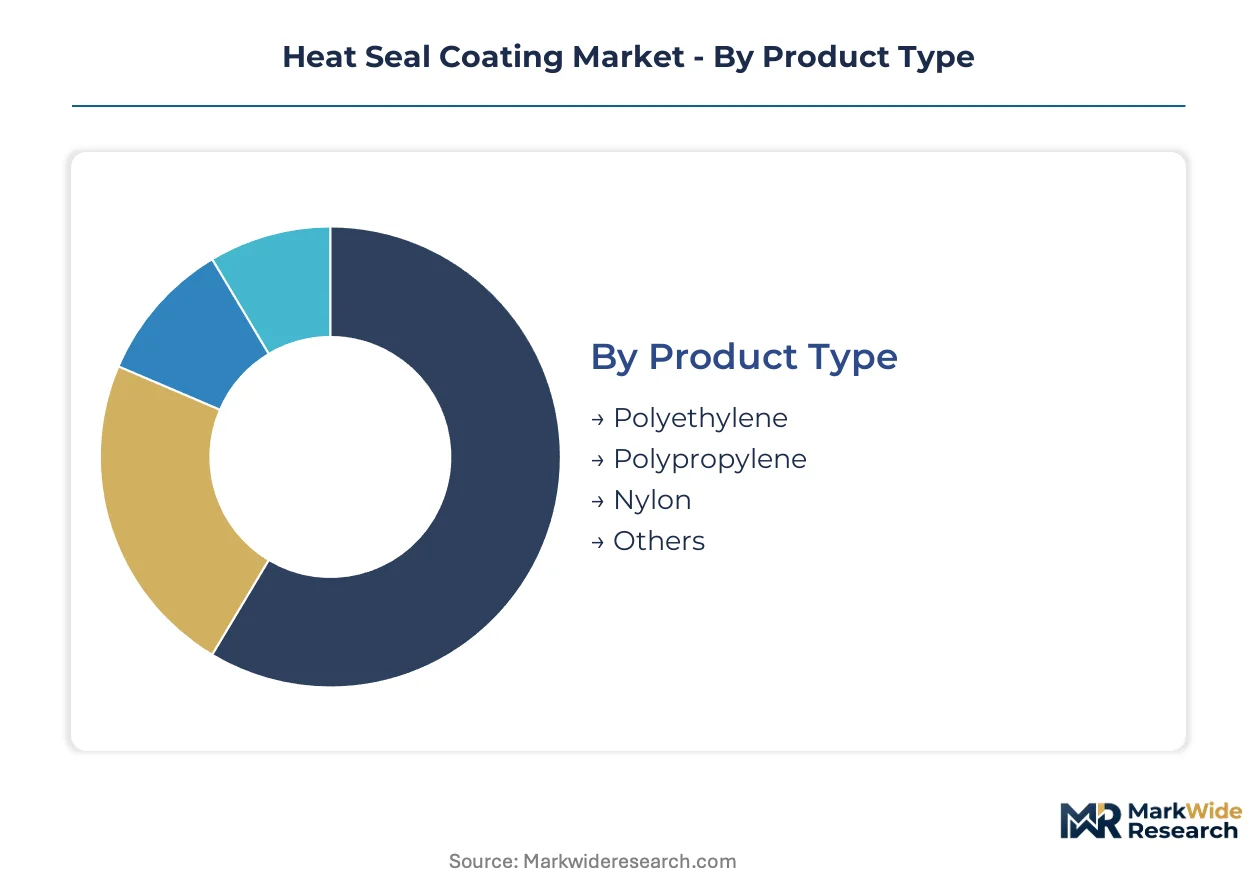
Heat seal coating procurement patterns diverge sharply across substrate chemistry, end-use integrity requirements, and regulatory compliance tiers. Specification teams at multinational converters must match coating platforms to precise thermal bonding profiles while navigating substance disclosure mandates.
Product Type:
FDA indirect food additive protocols and EFSA compliance documentation impose distinct migration testing burdens on each polymer chemistry, with polyolefin grades facing stricter monomer residual thresholds than specialty synthetics.
- Polyethylene:Low-density and linear low-density variants dominate flexible food pouch applications due to broad thermal compatibility with standard filling equipment. Demand concentrates among German converters in Baden-Württemberg supplying pan-European CPG networks, though ethylene-vinyl acetate price volatility squeezes formulator margins unpredictably.
- Polypropylene:Higher melting point specifications suit retort and hot-fill applications where seal integrity must survive sterilization cycles. Swiss pharmaceutical blister film manufacturers in Basel-Stadt are expanding polypropylene coating trials for moisture-barrier oral solid dose packaging, driven by EMA stability requirements.
- Nylon:Barrier-grade coextrusions serve high-oxygen-resistance specifications in specialty meat and cheese packaging.
- Others:Polyester and ionomer formulations occupy niche pharmaceutical and electronics moisture-barrier segments.
Polyethylene sits at the top of the volume ranking, with polypropylene climbing the fastest.
Industry Vertical:
End-use sectors separate by seal integrity thresholds, with pharmaceutical and electronics applications commanding premium formulation investments compared to commodity food tiers.
- Food Packaging:Mono-material pouch adoption at multinational CPG brands drives specification consolidation across converting networks. Water-based polyolefin dispersions are unifying performance parity with solvent systems, compressing historical premium pricing in this high-volume vertical.
- Pharmaceutical Packaging:Blister film moisture-barrier requirements elevate demand for high-integrity seal coatings in Germany and Switzerland. EMA and ECHA coordination on PFAS restrictions is accelerating qualification of fluorine-free barrier alternatives ahead of enforcement timelines.
- Consumer Goods:Personal care and household product packaging favors cost-optimized polyethylene tiers with moderate barrier specifications.
- Electronics:Semiconductor and battery component moisture-barrier pouches represent the steepest expansion trajectory from a smaller base, with faster growth rates than food verticals.
Food packaging commands absolute volume leadership, while electronics gains share fastest.
Application:
Physical format determines coating viscosity, drying profile, and line speed compatibility, with flexible formats requiring fundamentally different rheology than rigid substrate bonding.
- Flexible Packaging:Film and pouch formats capture dominant industry vertical demand through heat-activated bonding layers compatible with existing filling equipment. REACH substance disclosure mandates are accelerating specification switches toward compliant water-based chemistries among European converters.
- Rigid Packaging:Tray and container sealing applications require higher tack formulations for polypropylene and polystyrene substrates.
- Labeling:Pressure-sensitive and in-mold label adhesives operate at lower thermal activation thresholds than primary packaging seals.
- Sealant Films:Dedicated coextruded or coated sealant layers supply converter toll-coating operations.
Flexible packaging holds the volume advantage, with sealant films expanding most quickly as converters outsource specialty coating operations.
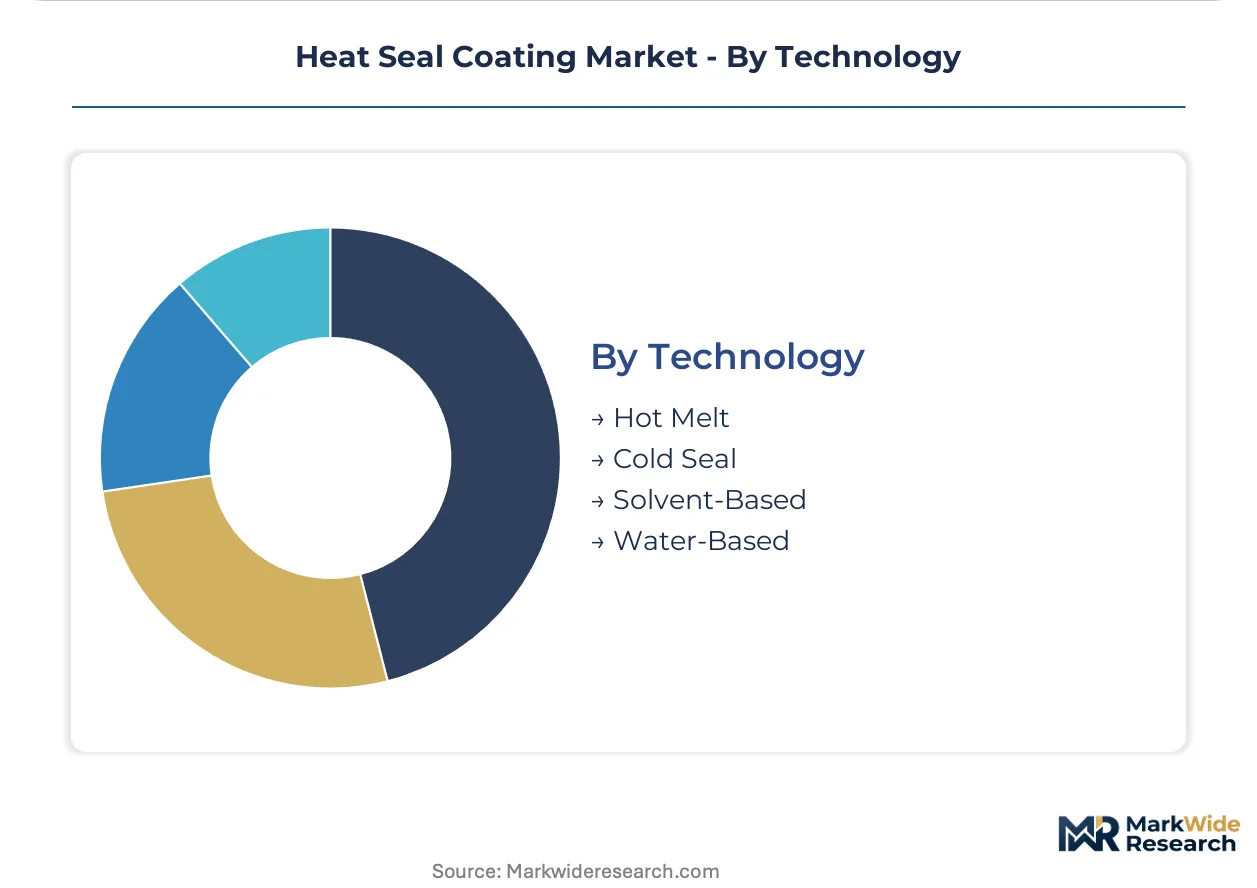
Technology:
Regulatory pressure on solvent emissions and PFAS elimination timelines are bifurcating technology investment, with water-based systems capturing volume leadership while solvent retains premium pharmaceutical positioning.
- Water-Based:Polyolefin dispersions and acrylic emulsions lead volume shipments despite thinner margin pools from formulation commoditization. EU Green Deal compliance requirements are elevating demand for these systems across German packaging converter clusters.
- Solvent-Based:Ethyl acetate and MEK-borne systems retain premium positioning in high-speed pharmaceutical lines where seal integrity thresholds are non-negotiable. ECHA substance-of-very-high-concern disclosure mandates are forcing reformulation investments toward compliant chemistries.
- Hot Melt:Reactive polyurethane and EVA-based systems serve labeling and specialty flexible applications requiring immediate green strength.
- Cold Seal:Natural rubber latex formulations enable heat-sensitive chocolate and confectionery packaging without thermal activation.
Water-based technology dominates shipment volumes, with hot melt systems gaining traction fastest through hybrid aqueous-reactive formulations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Technical workforce concentrations in polymer chemistry and film converting anchor regional demand patterns across three continents. Regulatory divergence between jurisdictions shapes formulation requirements. Industrial clustering in specific metropolitan areas concentrates procurement decisions.
Germany
Packaging converter clusters in Baden-Württemberg and Bavaria dominate European flexible film output, driving specification consolidation across pan-European CPG networks. REACH substance disclosure mandates and EU Green Deal compliance deadlines accelerate water-based chemistry adoption among formulators. Stuttgart and Munich metropolitan areas host the densest concentrations of coating qualification laboratories serving pharmaceutical blister film manufacturers.
United States
FDA indirect food additive migration limits create testing burdens for suppliers serving dual export markets, while EPA frameworks on PFAS elimination force substrate redesign timelines. Flexible food pouch demand concentrates among Midwestern and Southeastern converting operations supplying multinational brand headquarters. Chicago and Atlanta logistics corridors channel coating distribution to regional film production sites.
Switzerland
Swissmedic stability requirements and EMA coordination on barrier specifications elevate demand for high-integrity seal coatings in oral solid dose packaging. Basel-Stadt pharmaceutical manufacturing clusters are expanding polypropylene coating trials for moisture-barrier applications. The country's precision chemistry workforce supports specialized formulation development for premium pharmaceutical tiers.
China
SAMR food contact material standards and MIIT industrial upgrading programs reshape domestic coating specifications toward aqueous systems. Yangtze River Delta flexible packaging production clusters absorb growing volumes of water-based polyolefin dispersions. Shanghai and surrounding Jiangsu province cities concentrate converter capacity for both domestic consumption and export-oriented electronics moisture-barrier pouch manufacturing.
India
FSSAI packaging standards evolution creates first-mover advantage for compliant coating suppliers in a historically solvent-dominated market. Maharashtra and Gujarat industrial corridors host expanding flexible film converting operations serving domestic FMCG growth. Mumbai-Ahmedabad logistics networks distribute reformulated water-based systems to regional packaging hubs.
Heat Seal Coating Market Competitive Environment
Capital-heavy producers compete with asset-light designers across formulation and application technology boundaries. The market structures around three tiers: integrated polymer manufacturers with captive coating divisions, specialized adhesive formulators with dedicated flexible packaging expertise, and regional toll-coating operations serving converter outsourcing demand. Dominant competitive moves include portfolio diversification toward water-based platforms and strategic partnerships with film manufacturers for co-development of mono-material pouch solutions.
Among European-headquartered chemical conglomerates, BASF SE and Evonik Industries AG exemplify integrated polymer research infrastructure sustaining high-barrier coating portfolios. Henkel AG & Co. KGaA occupies a position anchoring flexible packaging demand through specialized adhesive platforms. Michelman, Inc. represents the specialized formulator archetype competing in water-based niches where regulatory pressure intensifies specification requirements.
| Leading Market Players |
|---|
| BASF SE |
| Evonik Industries AG |
| Henkel AG & Co. KGaA |
| Michelman, Inc. |
| 3M Company |
| H.B. Fuller Company |
| Arkema SA |
| DuPont de Nemours, Inc. |
| Dow Inc. |
| Others |
Value Chain & Pricing Dynamics
REACH substance disclosure mandates from ECHA are forcing European converters to abandon solvent-based coating platforms, compelling suppliers to absorb reformulation costs while water-based alternatives mature toward performance parity at compressed margin structures.
Pricing Analysis
Bundled technical service contracts dominate pharmaceutical blister film procurement, while unbundled commodity transactions prevail in flexible food packaging. Three-tier pricing structure across premium, standard, and economy levels separates solvent-based pharmaceutical grades from water-based food tiers and generic polyethylene formulations. Cost compression in water-based segments is intensifying because formulation commoditization erodes differentiation. Food packaging converters exhibit highest price sensitivity due to volume procurement and specification consolidation, whereas pharmaceutical buyers prioritize seal integrity over unit cost.
Supply Chain Analysis
Direct-to-converter channels handle multinational CPG brand demand, while distributor networks serve regional toll-coating operations. Manufacturing concentrates in Germany, China, and the United States, with Baden-Württemberg converter clusters anchoring European supply. Feedstock supply draws from ethylene-vinyl acetate copolymer producers, polyolefin resin manufacturers, and specialty acrylic emulsion suppliers. Single-source vulnerability in German packaging converter clusters creates geographic concentration risk for coating distributors serving pan-European demand. Distribution runs through Stuttgart and Munich logistics corridors to pharmaceutical manufacturers, with Shanghai and Chicago anchoring regional hub operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU Green Deal compliance costs in Germany and Switzerland exceed FSSAI implementation burdens in India, creating margin expansion opportunities for suppliers with dual-hemisphere manufacturing footprints.
For Market Incumbents: Cement market position through backward integration into polyolefin dispersion manufacturing and captive supply of water-based raw materials. ECHA PFAS elimination timelines threaten fluorinated barrier portfolios, demanding accelerated qualification of PFAS-free alternatives. Capacity addition in India captures first-mover advantage as FSSAI standards displace solvent-based imports. For New Entrants and Emerging Players: Water-based hot-melt hybrid formulations offer a technology-first wedge into pharmaceutical lines previously closed to aqueous chemistry. Electronics moisture-barrier pouches in China and India represent the most penetrable segment with faster growth rates than mature food verticals. Partner with Yangtze River Delta flexible packaging converters for co-development of mono-material pouch bonding layers. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized water-based formulators holding EFSA compliance documentation and unified regulatory dossiers across multiple jurisdictions. Long-term viability centers on suppliers with pharmaceutical certification depth and electronics segment diversification. Watch for EMA-ECHA coordination announcements on PFAS restriction enforcement timelines as inflection indicators for barrier coating demand shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyolefin Dispersion Manufacturing | Captive supply secures margin control against ethylene-vinyl acetate price volatility. |
| PFAS-Free Barrier Formulation Development | Preemptive qualification ahead of ECHA enforcement timelines protects pharmaceutical customer relationships. |
| Joint Venture with Indian Flexible Film Converters | FSSAI compliance capabilities unlock first-mover positioning in historically solvent-dominated market. |
| Long-Term Supply Agreement with Electronics OEMs | Moisture-barrier pouch demand from semiconductor packaging anchors premium pricing tier. |
| Capacity Expansion in Yangtze River Delta | Proximity to Shanghai converter clusters reduces logistics costs for water-based coating distribution. |
Study Parameters
Direct dialogue with coating formulator technical directors, procurement leads at German flexible packaging converters, pharmaceutical packaging engineers in Basel-Stadt, and regulatory affairs specialists at ECHA-affiliated laboratories grounded qualitative insights. Secondary validation drew from REACH substance registration databases, EMA stability guideline publications, FDA indirect food additive regulations, and EU Green Deal implementation progress reports. Bottom-up demand modeling triangulated against top-down polymer consumption data from Cefic and ACC industry statistics.
Bottom-up volume estimates aggregated coating consumption across polyethylene, polypropylene, nylon, and specialty polymer substrate tiers, while top-down analysis calibrated against flexible packaging production data from Baden-Württemberg and Bavaria industrial clusters. Segmentation dimensions spanned product chemistry, end-use vertical integrity requirements, application format rheology needs, and technology regulatory compliance tiers across the analysis window. CAGRs derived from regression analysis of historical coating formulation shipments against converter capacity expansion and EMA pharmaceutical packaging growth trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to PFAS restriction enforcement timelines, ethylene-vinyl acetate feedstock price volatility, and German converter cluster concentration risks. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Biodegradable Plastic Films Market
Packaging Barrier Films
Cling Films Market
Packaging Barrier Films
Barrier Coated Flexible Paper Packaging Market
Packaging Barrier Films
Electron High Barrier Packaging Film Market
Packaging Barrier Films
Global Adhesive Films Market
Packaging Barrier Films
Global Medical Packaging Films Market
Packaging Barrier Films
LDPE and LLDPE Sealant Web Films Market
Packaging Barrier Films
Antimicrobial Packaging Market
Packaging Barrier Films
Holographic Transfer Film Market
Packaging Barrier Films
Aluminum Barrier Laminate (ABL) Tubes Market
Packaging Barrier Films
Cold Seal Plastic Films Market
Packaging Barrier Films
North America Barrier Films Market
Packaging Barrier Films
Protective Films Market
Packaging Barrier Films
Barrier Shrink Films Market
Packaging Barrier Films
Hydrocolloid Coating Market
Packaging Barrier Films
Child-Resistant Foil Packaging Market