
 Single Dose Sachet Market | 2026-2036
Single Dose Sachet Market Size, Share, and Industry Trends Forecast 2026-2036
Single Dose Sachet Market Outlook
India is narrowing the gap between regional supply capacity and export demand for pharmaceutical-grade sachets. Amcor plc leverages its integrated film-to-sachet manufacturing footprint across multiple continents to sustain cost advantages. Huhtamaki Oyj anchors its position through specialized high-barrier coatings that extend product shelf life in tropical climates.
Single dose sachets are sealed pouches, typically 2–10 mL in volume, constructed from multi-layer laminates or mono-material films designed to protect contents from moisture, oxygen, and light contamination. They serve primary functions in portion-controlled dispensing, sample distribution, and sterile unit-dose delivery across food, pharmaceutical, and personal care industries. Liquid formulations dominate current volume owing to their prevalence in condiments, sauces, and oral care products, while biodegradable packaging types represent the fastest-expanding margin pool as regulatory pressure intensifies. Foil-based sachets retain entrenched positions in healthcare applications where moisture barrier integrity remains non-negotiable.
The FDA enforces strict child-resistant and tamper-evident standards for unit-dose pharmaceutical packaging, directly influencing laminate specifications and seal-strength requirements. REACH and the EU Green Deal mandate recyclability targets and restrict certain plastic additives, compelling converters to reformulate barrier layers. Stakeholders must monitor evolving extended producer responsibility frameworks and decide whether to invest in mono-material compatible lines or advanced coating technologies that maintain barrier performance without compromising recyclability.
Market Dynamics
Material substitution pressure from EU Green Deal mandates is forcing converters to abandon multi-layer laminates before recyclable mono-material alternatives achieve equivalent barrier performance, compressing margin structures across the supply base.
Growth Catalysts
- REACH chemical restrictions:The EU's tightening limits on perfluorinated compounds in food-contact materials accelerate R&D investment in bio-based barrier coatings. Pharmaceutical exporters in India expand sachet production to capture rising demand from African and Southeast Asian markets.
- Oral care unit-dose formats:Mouthwash and toothpaste sachets displace bottles in travel retail and hospitality channels. Hotels and airlines in the Middle East adopt single-dose amenities to reduce waste handling costs.
- Aluminum oxide deposition:Thin-film vacuum coating technology replaces foil layers in moisture-sensitive pharmaceutical applications. CDSCO's alignment with ICH stability guidelines validates these barrier alternatives for domestic Indian generics.
Market Restraints
- Ethylene-vinyl alcohol resin pricing:EVOH supply concentrates among three Japanese and US petrochemical groups, exposing converters to feedstock volatility without viable substitutes for oxygen barrier layers.
- Extended producer responsibility fees:Germany's VerpackG and France's Citeo schemes impose per-unit costs on non-recyclable formats that erode the cost advantage of conventional multi-layer sachets against rigid alternatives.
- High-speed form-fill-seal equipment:Mono-material films require retooled sealing jaws and modified temperature profiles, stranding existing machinery investments and extending payback periods for mid-scale converters.
Strategic Opportunities
- Rural India's FMCG penetration:Shampoo and conditioner sachets priced below ten rupees reach consumers outside traditional retail networks through direct-to-home distribution models.
- FSSAI fortification mandates:Government-mandated micronutrient addition to edible oils and milk creates demand for light-protected single-dose formats that preserve vitamin stability through the supply chain.
- Digital printing convergence with barrier coating:Inkjet personalization at production speed enables pharmaceutical serialization compliance without separate labeling operations, collapsing two process steps into one.
Industry Challenges
- Migration testing protocols:Demonstrating compliance with EU 10/2011 plastic food-contact regulations demands 12-18 month validation timelines for novel bio-based substrates, delaying commercialization.
- Heat-seal technician shortage:Operating precision servo-driven sealing systems requires skills absent from conventional flexible packaging workforces, constraining output at brownfield expansion sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Single Dose Sachet Market |
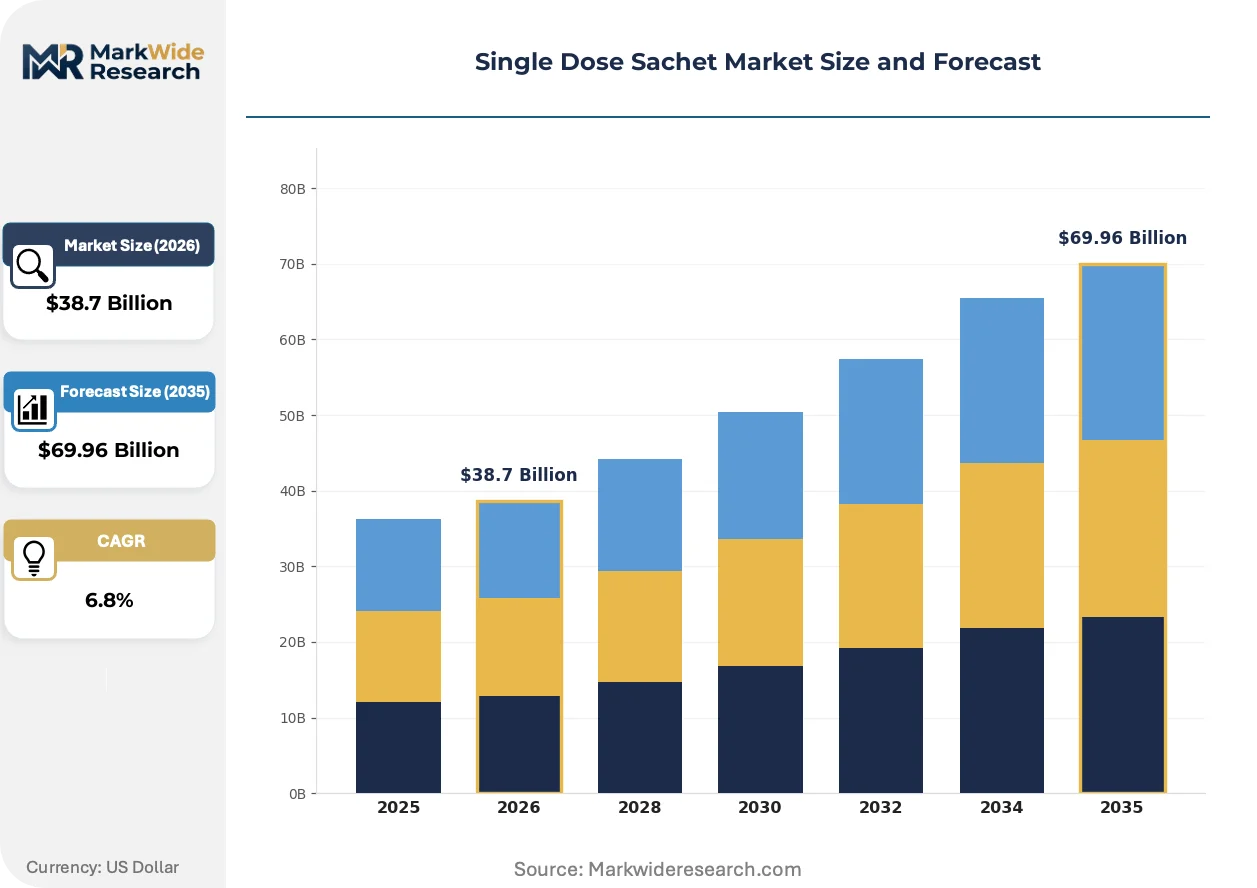
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Granule, Gel End User: Household, Food Service, Healthcare, Retail Packaging Type: Biodegradable, Plastic, Foil, Paper Distribution Channel: Online, Supermarket, Convenience Store, Pharmacy |
| Companies Covered | Amcor plc, Huhtamaki Oyj, Constantia Flexibles, Sealed Air Corporation, Mondi Group, ProAmpac, Berry Global Inc., Sonoco Products Company, Uflex Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Single Dose Sachet Market Strategic Shifts
Digital manufacturing integration and regulatory-driven material science are converging to redefine production economics and product authentication capabilities across pharmaceutical and food-grade sachet segments.
Blockchain-enabled serialization is virtualizing supply chain verification for pharmaceutical unit-dose packaging. Indian generics manufacturers deploying these systems achieve compliance with FDA track-and-trace mandates while compressing recall response times. The technology substitutes distributed ledger confirmation for physical documentation, reducing audit preparation labor.
REACH Annex XVII restrictions on intentionally added microplastics extend to rinse-off cosmetics, compelling reformulation of sachet films used for shampoo and body wash samples. German converters accelerate starch-based and cellulose-derived alternatives through pilot production. The personal care sample segment faces immediate format migration pressure.
Direct-store-delivery networks in Southeast Asia bypass traditional distributor tiers for condiment and sauce sachets. Indonesian and Vietnamese food manufacturers build captive last-mile fleets to secure shelf placement in independent retailers. Urban consolidation of traditional trade outlets concentrates buyer power and compresses payment cycles.
Single Dose Sachet Market Segmentation
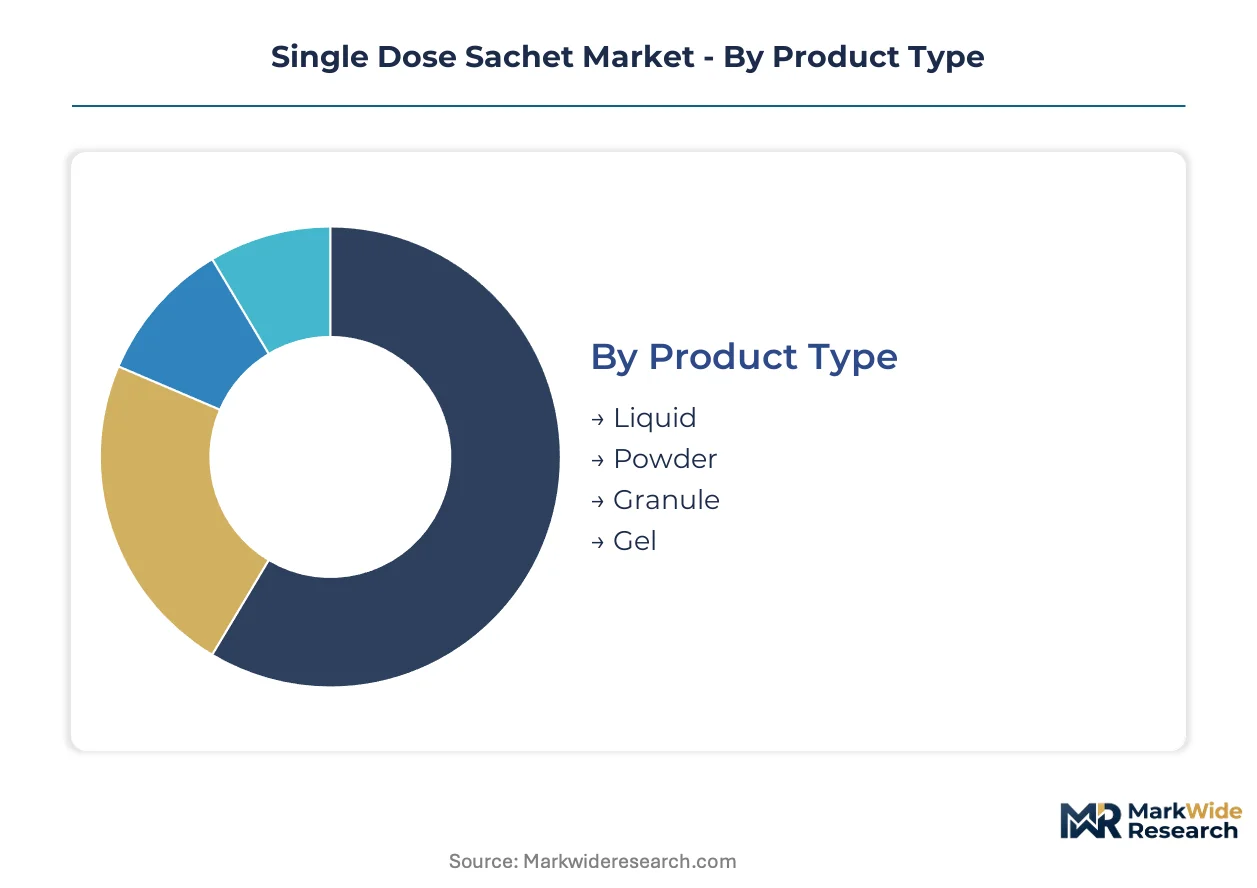
Segmentation in the single dose sachet market reveals divergent margin profiles and regulatory exposure across material platforms. Product format and end-use channel selection determine barrier specification requirements, equipment utilization rates, and compliance validation timelines for converters.
Product Type:
Liquid formulations cycle through production fastest, with form-fill-seal lines achieving output rates that powder and granule formats cannot match due to dosing precision constraints.
- Liquid:Composed of aqueous or oil-based solutions sealed in multi-layer laminates with heat-seal integrity tested to pharmaceutical standards. Demand concentrates in Indian pharmaceutical exports to African markets, driven by oral rehydration salts and pediatric antibiotics requiring sterile unit-dose delivery.
- Powder:Dry formulations requiring moisture barrier ratings equivalent to 0.1 g/m²/day water vapor transmission. European condiment manufacturers specify these for instant soup and seasoning sachets as EPR fees pressure converters toward lighter-weight substrates.
- Granule:Free-flowing crystalline materials dosed through volumetric cup systems with anti-static film treatments. Coffee and sugar sachets in Middle Eastern hospitality channels dominate this segment's volume.
- Gel:Semi-viscous formulations demanding modified sealing jaw geometries to prevent squeeze-out during closure. Personal care samples in Southeast Asian direct-store-delivery networks are expanding most quickly here.
Liquid dominates installed base. Gel is where expansion concentrates.
End User:
Cost tier stratification separates premium healthcare validation requirements from economy-focused household consumption patterns.
- Household:Price-sensitive consumption of shampoo, conditioner, and condiment sachets through traditional retail and direct-to-home networks. Indian rural penetration programs by FMCG majors drive volume here.
- Food Service:High-volume institutional procurement of sauce, oil, and beverage sachets with standardized portion control. Indonesian captive last-mile fleets supply independent warungs with daily replenishment cycles.
- Healthcare:Sterile unit-dose pharmaceuticals requiring FDA 21 CFR Part 211 compliance and child-resistant features. CDSCO-aligned ICH stability guidelines validate barrier alternatives for Indian generics manufacturers exporting to regulated markets.
- Retail:Branded sample distribution and travel-size formats through duty-free and convenience channels. Oral care sachets displace bottles in Middle Eastern airline amenity kits.
Household commands the largest addressable volume. Healthcare delivers the steepest expansion trajectory.
Packaging Type:
Supply concentration in barrier coating technology creates margin differentiation between incumbent multi-layer laminates and emerging mono-material alternatives.
- Biodegradable:Starch-based and cellulose-derived substrates with compostability certifications under EN 13432. German converters pilot these for rinse-off cosmetics as REACH Annex XVII microplastic restrictions take effect.
- Plastic:Conventional polyethylene and polypropylene mono-materials compatible with existing recycling streams. Supermarket private-label condiment sachets in France and Germany specify these to minimize Citeo and VerpackG fee exposure.
- Foil:Aluminum-laminate constructions delivering sub-0.01 g/m²/day moisture barrier performance. Indian pharmaceutical exporters retain foil for moisture-sensitive generics bound for tropical climates.
- Paper:Fiber-based substrates with polymer barrier coatings for dry food applications. Limited penetration due to seal-strength constraints in high-speed form-fill-seal operations.
Plastic retains the broadest installed equipment base. Biodegradable is gaining share fastest.
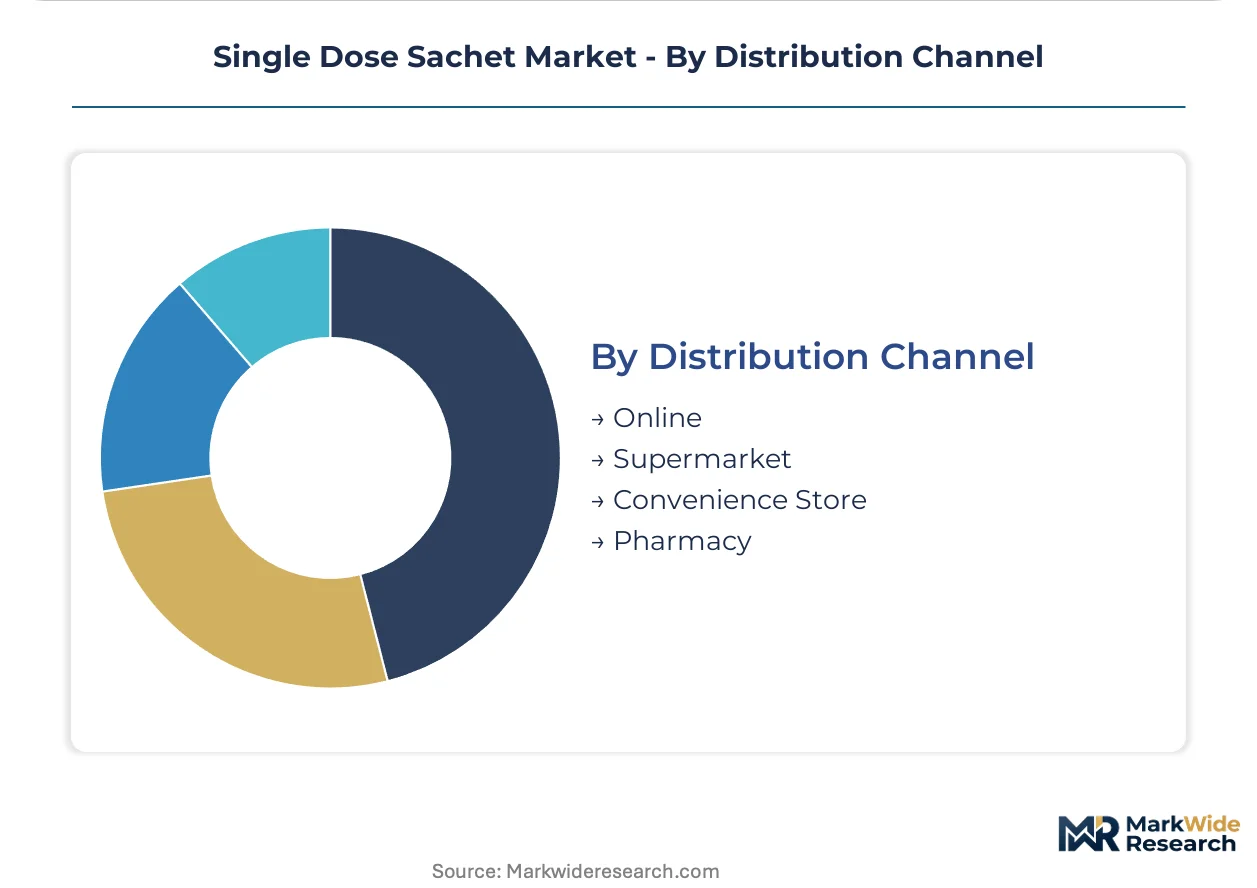
Distribution Channel:
Customer type and purchase occasion determine pack size, branding investment, and serialization requirements across channel formats.
- Online:Direct-to-consumer fulfillment with customized pack configurations and blockchain-tracked pharmaceutical serialization. Indian generics manufacturers deploy these systems for FDA track-and-trace compliance.
- Supermarket:Multi-SKU shelf presence requiring high-impact graphics and standardized case counts. Indonesian and Vietnamese food manufacturers negotiate placement through urban consolidation of traditional trade outlets.
- Convenience Store:Impulse-oriented single-unit and small-count packs with localized language labeling. Rural India's FMCG sachets priced below ten rupees reach consumers outside traditional retail networks here.
- Pharmacy:Regulated dispensing with tamper-evident features and batch-level traceability. FSSAI fortification mandates for edible oils and milk create demand for light-protected single-dose formats through this channel.
Supermarket anchors current volume concentration. Online is where channel investment is concentrating.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FSSAI fortification mandates and CDSCO pharmaceutical export guidelines anchor India's dominance in single-dose sachet production. The EU Green Deal and REACH chemical restrictions reshape material specifications across European conversion facilities.
India
Pharmaceutical exports to African and Southeast Asian markets drive sachet volume expansion for oral rehydration salts and pediatric antibiotics. CDSCO alignment with ICH stability guidelines validates barrier alternatives for domestic generics manufacturers. Gujarat and Maharashtra host concentrated flexible packaging clusters where converters retrofit lines for mono-material compatibility.
Germany
REACH Annex XVII microplastic restrictions accelerate starch-based and cellulose-derived substrate pilot programs for rinse-off cosmetics. VerpackG extended producer responsibility fees compress margins on conventional multi-layer formats. The Ruhr industrial corridor shelters specialized high-barrier coating developers serving pharmaceutical and personal care segments.
United States
FDA 21 CFR Part 211 compliance requirements for sterile unit-dose pharmaceuticals sustain foil-laminate demand in moisture-sensitive applications. Oral care sachets displace bottles in travel retail channels. New Jersey and Pennsylvania conversion corridors supply child-resistant and tamper-evident formats to regulated healthcare markets.
Indonesia
Captive last-mile fleets for condiment and sauce sachets bypass traditional distributor tiers to secure warung shelf placement. Direct-store-delivery networks concentrate procurement power among urban consolidated buyers. Java-based food manufacturers expand daily replenishment cycles to independent retailers outside formal wholesale channels.
France
Citeo EPR schemes impose per-unit costs on non-recyclable formats that erode multi-layer sachet competitiveness against rigid alternatives. Supermarket private-label condiment specifications prioritize mono-material polyethylene and polypropylene substrates. The Lyon packaging cluster advances digital printing convergence with barrier coating for pharmaceutical serialization compliance.
Single Dose Sachet Market Competitive Environment
Integrated film-to-sachet manufacturers and specialized barrier coating developers split the market between scale efficiency and technical differentiation. Tier concentration remains moderate, with top-tier converters commanding pharmaceutical validation capabilities while mid-scale players serve commodity FMCG segments. Three archetypes dominate: continental multi-site integrators, regional high-barrier specialists, and emerging-market cost optimizers. Capacity expansion and strategic technology licensing represent the dominant competitive moves as converters navigate material substitution timelines.
Among integrated packaging conglomerates, Amcor plc and Huhtamaki Oyj exemplify contrasting strategic positions. Amcor leverages multi-continental manufacturing footprints to sustain cost advantages across standardized formats. Huhtamaki anchors its market presence through specialized coating expertise extending product shelf life in tropical climates. Constantia Flexibles occupies a position between these poles, representing the mid-tier specialist archetype with concentrated European pharmaceutical validation capabilities.
| Leading Market Players |
|---|
| Amcor plc |
| Huhtamaki Oyj |
| Constantia Flexibles |
| Sealed Air Corporation |
| Mondi Group |
| ProAmpac |
| Berry Global Inc. |
| Sonoco Products Company |
| Uflex Ltd. |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in European high-barrier coating facilities drives supplier selectivity and pricing power toward pharmaceutical-grade converters, while Asian form-fill-seal capacity expansion compresses commodity sachet margins through volume competition.
Pricing Analysis
Indian pharmaceutical-grade sachets trade at 15-25% premiums over Southeast Asian commodity equivalents due to CDSCO validation requirements and ICH stability compliance. Three-tier pricing structure separates FDA-validated healthcare formats from FSSAI-compliant food-grade and unregulated household samples. Cost compression in European biodegradable substrates is intensifying because REACH Annex XVII restrictions accelerate material substitution before scale economies emerge. Household FMCG buyers in rural India exhibit highest price sensitivity, while Middle Eastern hospitality procurement shows lowest elasticity due to waste-handling cost priorities.
Supply Chain Analysis
Contract manufacturing concentrates among Gujarat and Maharashtra flexible packaging clusters, where Uflex and regional specialists operate integrated film-to-sachet lines. Raw material sourcing draws from Saudi ethylene feedstock, Japanese EVOH resin suppliers, and German starch-based substrate developers. Single-source vulnerability in oxygen barrier layers creates exposure to petrochemical group pricing power. Distribution runs through Indonesian captive last-mile fleets, Indian direct-to-home networks, and European supermarket private-label procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated Middle Eastern hospitality procurement and urban Indonesian warung networks, fragmenting converter margin capture across dispersed downstream channels.
For Market Incumbents: Harden barrier coating intellectual property positions against aluminum oxide deposition substitutes entering from German and Japanese equipment suppliers. Deepen upstream control over EVOH resin allocation through long-term offtake with Japanese petrochemical groups. Expand mono-material line retrofit capacity in Gujarat clusters ahead of EU Green Deal enforcement timelines. For New Entrants and Emerging Players: Build out digital printing convergence capabilities serving Indian pharmaceutical serialization compliance, where FDA track-and-trace mandates create immediate equipment demand. Target rural India's FMCG direct-to-home distribution as the most penetrable volume segment. Lead with inkjet personalization at production speed as the differentiated go-to-market angle. For Investors and Strategic Acquirers: Capital is best deployed toward specialized high-barrier coating developers with tropical climate validation and pharmaceutical certification track records. Long-term viability centers on converters navigating material substitution timelines without stranded equipment investments. Watch German VerpackG and French Citeo EPR fee escalation rates as the inflection signal for mono-material adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Line Retrofit | EU Green Deal compliance protects European market access against EPR fee erosion. |
| High-Barrier Coating R&D Partnership | Aluminum oxide deposition validation opens moisture-sensitive pharmaceutical applications. |
| Captive Last-Mile Fleet Buildout | Indonesian warung direct-store-delivery secures shelf placement outside wholesale channels. |
| Digital Printing Convergence | FDA serialization compliance collapses labeling and barrier coating into single process step. |
| Biodegradable Substrate Pilot Scale-Up | REACH Annex XVII alignment captures rinse-off cosmetics format migration demand. |
Study Parameters
Desk research of customs trade records, CDSCO regulatory filings, and EU packaging directive documentation preceded structured interviews with flexible packaging plant managers, pharmaceutical procurement leads at Indian generics exporters, FSSAI compliance officers, and German coating technology R&D directors. Primary fieldwork validated secondary estimates through bottom-up capacity surveys and top-down demand reconciliation across end-use segments.
Assumptions held regulatory enforcement timelines and EVOH resin supply concentration fixed while varying biodegradable substrate adoption curves and Indian pharmaceutical export growth rates. Segmentation modeling spanned product type, end user, packaging material platform, and distribution channel dimensions. CAGRs derived from installed base growth, line utilization rates, and per-unit value migration across material transitions.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese mono-material equipment suppliers or sudden EVOH feedstock disruption would shift outcomes. Quarterly review of German VerpackG fee schedules, Indian pharmaceutical export licensing data, and REACH Annex XVII enforcement actions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sachet Packaging
Sachet Packaging Market
Sachet Packaging
Sachet and Pouch Handling Systems Market
Sachet Packaging
Snap Sachets Market
Sachet Packaging
China Sachet Packaging Market
Sachet Packaging
North America Sachet Packaging Market
Sachet Packaging
Asia Pacific Sachet Packaging Market
Sachet Packaging
Canada Sachet Packaging Market
Sachet Packaging
Japan Sachet Packaging Market
Sachet Packaging
Sanitizer Sachet Market
Sachet Packaging
Aluminium Foil Sachet Market
Sachet Packaging
India Sachet Packaging Market
Sachet Packaging
US Sachet Packaging Market
Sachet Packaging
India Plastic Packaging Market
Sachet Packaging
Germany Sachet Packaging Market
Sachet Packaging
Full Container Shrink Sleeves Market
Sachet Packaging
Sachet Packaging Machines Market