
 Poland Plastic Packaging Films Market | 2026-2036
Poland Plastic Packaging Films Market Size, Share, and Industry Trends Forecast 2026-2036
Poland Plastic Packaging Films Market Insights
Multi-source resin procurement is expanding across Polish converters as polypropylene and polyethylene supply volatility prompts diversification strategies. Amerplast Sp z o.o. leverages its extrusion capabilities to serve pan-European food clients from central Poland. Flex Films Europa SP. Z.O.O. anchors regional metallized film production for snack and confectionery barrier applications. SÜDPACK Holding GmbH differentiates through high-performance multilayer structures targeting premium meat packaging.
Poland plastic packaging films constitute flexible polymer substrates manufactured through blown or cast extrusion, typically ranging from 8 to 150 microns in thickness, engineered for moisture and oxygen barrier protection across consumer and industrial goods. Stretch film dominates volume throughput in Polish logistics corridors, while BOPP film captures margin concentration in branded food labels and overwrap segments. The 20-50 micron thickness band sustains the broadest end-use coverage, from pallet unitization to pharmaceutical blister lidding.
Polish film producers navigate overlapping compliance obligations from EU REACH chemical registration, the Packaging and Packaging Waste Directive's recycling targets, and national BIS-equivalent quality certification administered by the Polish Centre for Testing and Certification. These frameworks elevate technical specifications for recycled content integration and migration testing protocols. Stakeholders must monitor forthcoming EU PPWR implementation timelines and assess mechanical recycling infrastructure partnerships before committing capital to capacity expansions.
Market Dynamics
Polypropylene and polyethylene supply volatility is fragmenting resin procurement strategies across Polish converters, forcing diversification away from single-source dependencies and compressing margin structures for undifferentiated commodity film grades.
Growth Catalysts
- EU Single-Use Plastics Directive:Extended producer responsibility rules are accelerating capital deployment into mechanical recycling infrastructure and film-to-film circularity systems.
- Meat and dairy processors:Polish food manufacturers are expanding flexible packaging procurement for modified-atmosphere applications requiring oxygen barrier performance.
- Greater Poland Voivodeship:Concentration of extrusion and metallization assets around Poznań's polymer processing cluster is reducing logistics costs for pan-European distribution.
Market Restraints
- Feedstock price volatility:Naphtha and natural gas-derived monomer costs swing with European energy market disruptions, compressing converter margins unpredictably.
- Recyclate quality deficit:Post-consumer film waste streams carry contamination levels that degrade mechanical properties below food-contact migration thresholds.
- Barrier film substitution:Aluminum foil and metallized paperboard are reclaiming premium shelf-stable segments where plastic sustainability credentials face scrutiny.
Strategic Opportunities
- Chemical recycling partnerships:Pyrolysis and depolymerization investments can unlock food-grade recyclate volumes that mechanical processes cannot achieve.
- Pharmaceutical blister lidding:Cold-formable aluminum-plastic laminates for unit-dose medications represent an underpenetrated high-margin application.
- EU Packaging and Packaging Waste Directive:Mandatory recycled content minimums create guaranteed offtake for domestic recyclers achieving EFSA food-contact clearance.
Industry Challenges
- Migration testing backlog:Polish Centre for Testing and Certification approval timelines for novel multilayer structures extend commercialization cycles.
- Skilled extrusion technicians:Shortage of blown-film process engineers with coextrusion die expertise limits operational flexibility at mid-scale converters.
- Legacy equipment retrofit:Integrating inline thickness measurement and automated gauge control into existing cast lines demands capital without immediate yield recovery.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Poland Plastic Packaging Films Market |
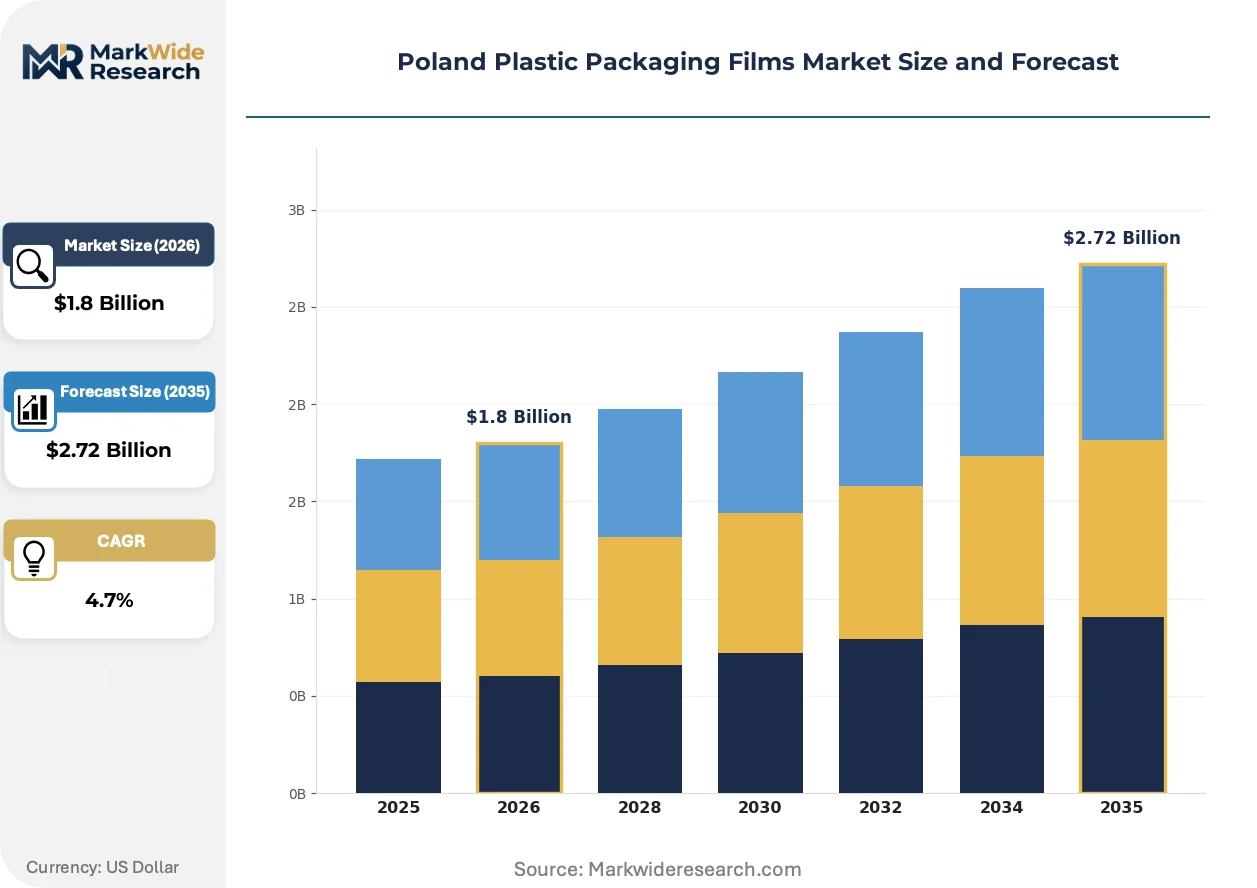
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stretch Film, Shrink Film, BOPP Film, CPP Film End Use Industry: Food & Beverage, Healthcare, Personal Care, Electronics Thickness: Below 20 Micron, 20-50 Micron, 51-100 Micron, Above 100 Micron Form: Rolls, Bags, Pouches, Sheets |
| Companies Covered | Luigi Bandera SpA, Amerplast Sp z o.o., Innovia Films, TEKNIKA GROUP, Sigma Stretch Film of Europe SP ZOO, Berry Global Inc., Flex Films Europa SP. Z.O.O., Dekofilm Polska SP ZOO, SÜDPACK Holding GmbH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Poland Plastic Packaging Films Market Trends and Innovations
Digital printing and solventless adhesive lamination are compressing minimum order quantities and shortening design-to-delivery cycles, enabling Polish converters to compete with Western European suppliers on responsiveness rather than scale alone.
Bio-based polypropylene derived from renewable feedstocks is decentralizing resin sourcing strategies for premium branded applications. Polish converters serving organic food labels are piloting ISCC PLUS-certified grades at 15-30% price premiums to conventional polymer. This shift is decentralizing supply chain control from petrochemical majors toward agricultural commodity-linked producers.
REACH chemical registration requirements are tightening migration testing protocols for food-contact layers. The European Chemicals Agency's expanded substance restrictions are forcing reformulation of slip agents and anti-block additives. High-barrier meat packaging applications face the steepest compliance costs as oxygen scavenger chemistries require renewed safety dossiers.
Consolidated procurement by pan-European retail chains is compressing supplier rosters and demanding integrated design-to-recyclability services. Polish converters are responding by embedding EPR compliance management and packaging optimization software into customer contracts. This behavioral shift concentrates most visibly in the snack and confectionery segments where private-label volume aggregates across Carrefour, Lidl, and Biedronka networks.
Poland Plastic Packaging Films Market Segmentation
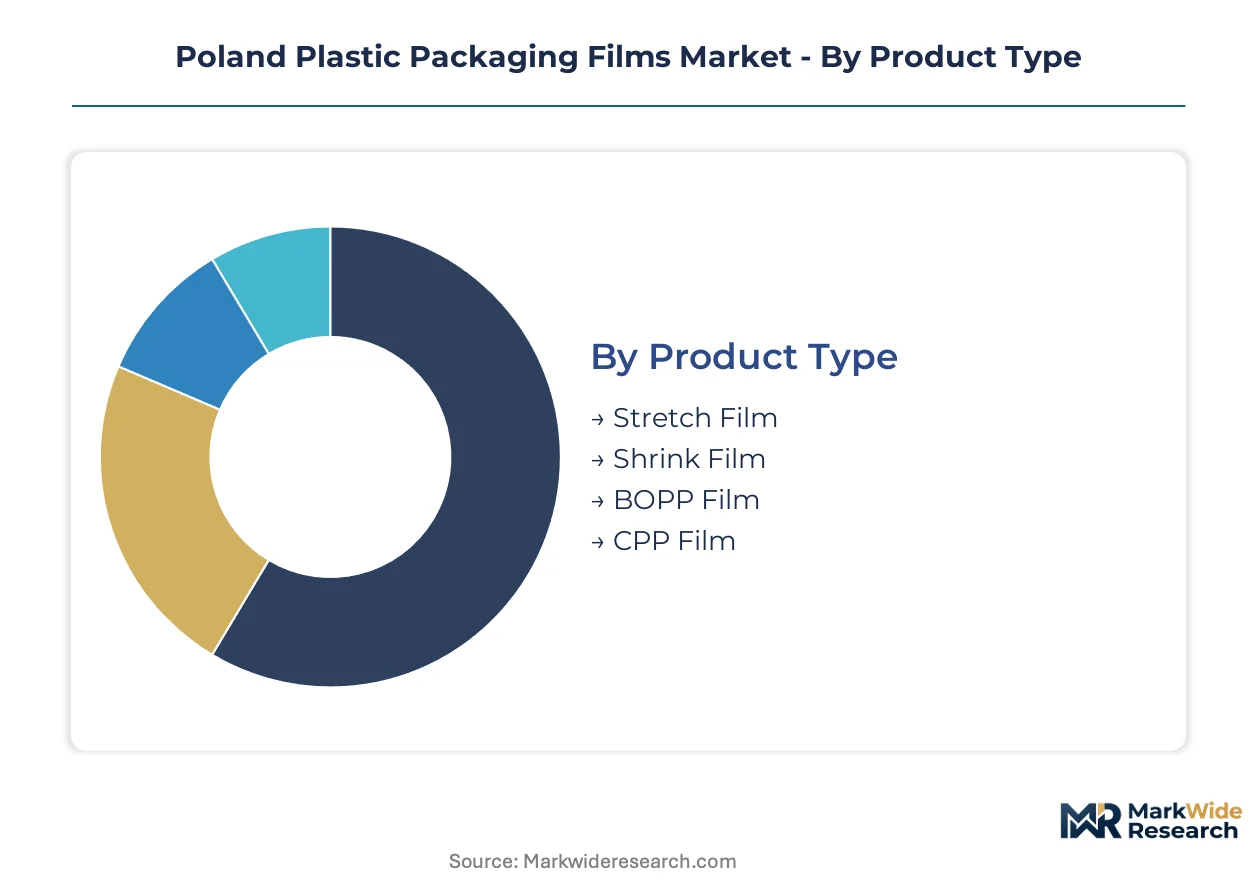
Segmentation in Poland's plastic packaging films market reveals how capital deployment and technical specifications align with distinct customer procurement patterns. Each dimension—product chemistry, end-use requirements, gauge thickness, and physical form—carries different margin profiles and compliance burdens that reshape converter investment priorities.
Product Type:
Capital intensity varies sharply across extrusion technologies, with multilayer coextrusion lines demanding substantially higher upfront outlays than monolayer blown film equipment.
- Stretch Film:Linear low-density polyethylene formulations dominate pallet unitization and load containment across Polish logistics corridors. Demand concentrates in Greater Poland Voivodeship distribution hubs serving German retail supply chains, though margin compression from resin volatility forces converters toward gauge-down engineering.
- Shrink Film:Polyethylene and polyolefin variants provide printed sleeve applications for beverage multipacks and consumer goods bundling. Polish bottlers around Poznań's polymer cluster are expanding procurement for PET bottle collation, driven by retail-ready packaging mandates from pan-European grocers.
- BOPP Film:Biaxially oriented polypropylene delivers clarity and stiffness for snack overwrap and adhesive tape backing.
- CPP Film:Cast polypropylene offers heat-seal layers for retort pouches and metallized barrier laminates.
Most installed capacity flows through stretch film. Expansion is steepest in BOPP film.
End Use Industry:
Application-specific migration testing and barrier performance requirements fragment converter capabilities, with pharmaceutical and food-contact segments demanding discrete certification tracks.
- Food & Beverage:Modified-atmosphere packaging for Polish meat processors requires oxygen transmission rates below 5 cc/m²/day. Dairy applications around Łódź Voivodeship are driving metallized film lamination demand as extended shelf-life formats displace traditional wrapping.
- Healthcare:Sterile barrier systems and pharmaceutical blister lidding demand compliance with EU MDR and EFSA migration thresholds. Cold-formable aluminum-plastic laminates for unit-dose medications represent a margin-dense niche where domestic capacity remains underdeveloped.
- Personal Care:Flexible sachets and pillow pouches for hygiene products prioritize seal integrity and print registration over barrier performance.
- Electronics:Anti-static films and moisture barrier bags for component shipping require dissipative surface treatments and desiccant compatibility.
Food & Beverage commands the largest volume share. Healthcare is climbing the fastest on value terms.
Thickness:
Gauge selection directly determines extrusion line configuration, with sub-20 micron production requiring specialized die design and air ring precision that elevates equipment costs.
- Below 20 Micron:Ultra-thin stretch and overwrap applications minimize resin consumption per unit. Polish converters serving discount retail chains are pushing gauge limits to offset polypropylene price volatility, though downstream processing speeds constrain adoption.
- 20-50 Micron:The workhorse band spans pallet wrap, food labels, and pharmaceutical lidding with broad extruder compatibility. Greater Poland Voivodeship converters concentrate capacity here to serve pan-European distribution with minimal changeover downtime.
- 51-100 Micron:Heavy-duty shrink bundling and industrial liners require enhanced puncture resistance.
- Above 100 Micron:Construction vapor barriers and agricultural mulch films demand UV stabilization and extended field life.
20-50 micron thickness hosts the broadest equipment base. Below 20 micron is gaining share fastest as resin economics tighten.
Form:
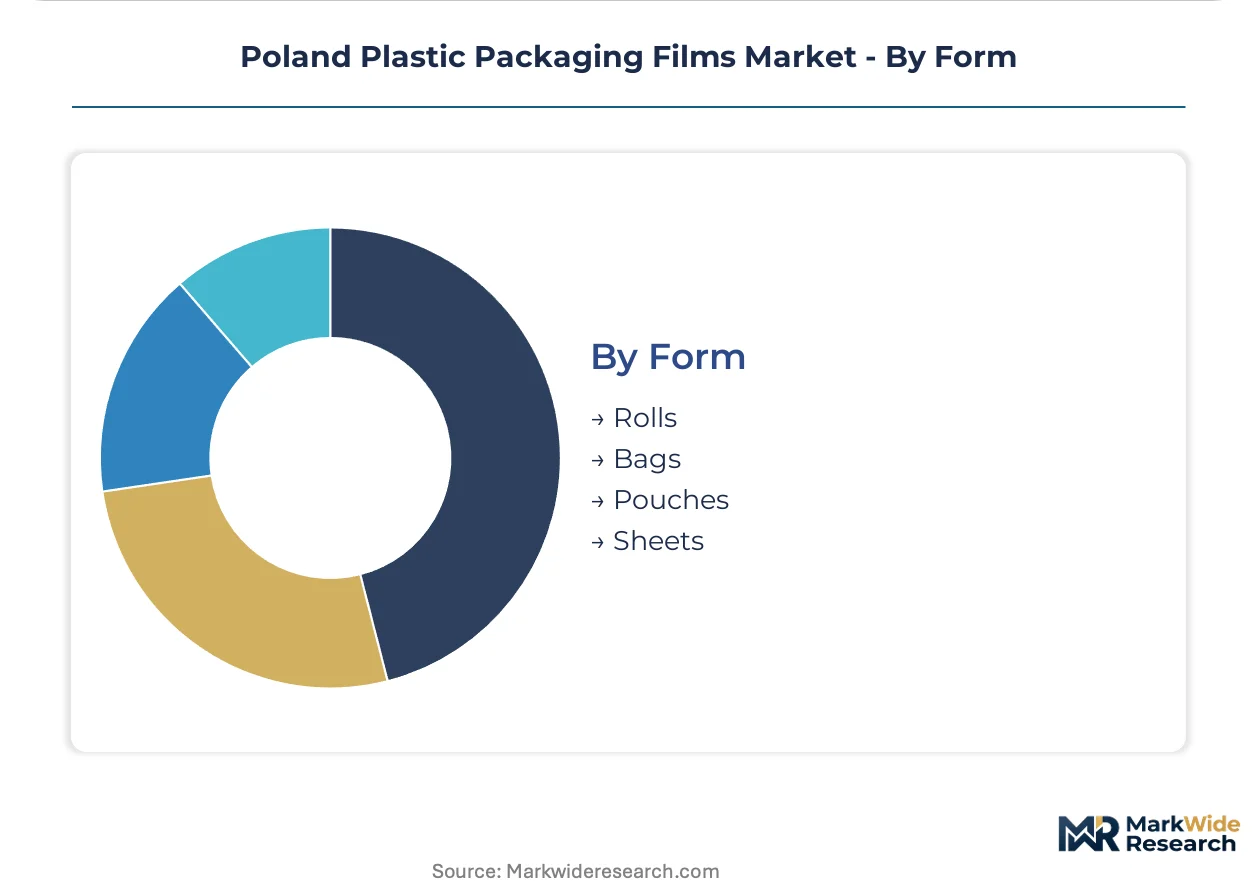
Downstream converting steps—slitting, sealing, and forming—determine whether film producers capture margin in finished goods or cede value to specialized packaging converters.
- Rolls:Master roll and slit roll formats supply downstream converters with minimal value-add. Polish stretch film producers around Poznań dominate this segment, leveraging central location for just-in-time delivery to German and Czech packaging operations.
- Bags:Pre-formed gusseted and flat bags target industrial liner and retail carryout applications. E-commerce fulfillment growth in Silesian logistics hubs is accelerating demand for printed mailer bags with adhesive strip closures.
- Pouches:Stand-up and flat pouches require multilayer lamination and zipper integration that shifts production to flexible packaging specialists.
- Sheets:Cut-to-size formats serve construction vapor barriers and pallet top sheets with minimal processing.
Rolls absorb the majority of extrusion output. Pouches are expanding most quickly as brand owners consolidate supplier rosters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Greater Poland Voivodeship anchors Poland's plastic packaging films sector through Poznań's polymer processing cluster, where extrusion and metallization assets concentrate to serve pan-European distribution networks. The country's central location reduces logistics costs for converters supplying German retail supply chains and Czech packaging operations. Regional demand patterns reflect proximity to meat processing facilities around Łódź and dairy operations across central Poland.
Greater Poland Voivodeship
Modified-atmosphere packaging procurement from Poznań-area meat processors drives oxygen barrier film demand. EFSA migration thresholds govern food-contact layer formulations. The Konin-Turek corridor hosts stretch film extrusion lines supplying German logistics hubs.
Łódź Voivodeship
Dairy processors around Łódź are expanding metallized film lamination for extended shelf-life formats. EU Packaging and Packaging Waste Directive recycling targets pressure converters toward mechanical recyclate integration. Stryków's distribution parks attract pouch converting investments.
Silesian Voivodeship
E-commerce fulfillment growth in Katowice logistics corridors accelerates printed mailer bag demand with adhesive strip closures. Extended producer responsibility rules under Polish national implementation of the EU Single-Use Plastics Directive elevate compliance costs. The Upper Silesian Industrial Zone concentrates pre-formed bag production.
Lower Silesian Voivodeship
Pharmaceutical blister lidding demand from Wrocław's generic drug manufacturers creates high-margin opportunities. EU MDR sterile barrier requirements constrain supplier qualification. The Wrocław Technology Park anchors cold-formable laminate pilot production.
Masovian Voivodeship
Warsaw-headquartered retail chains consolidate procurement across Carrefour, Lidl, and Biedronka networks. REACH chemical registration through ECHA tightens slip agent formulations for snack overwrap. Pruszków's converting parks serve brand owners with design-to-recyclability contracts.
Poland Plastic Packaging Films Market Competitive Landscape
Global majors compete with regional champions across resin procurement and barrier technology dimensions, producing a tiered structure where scale-driven multinationals face specialized mid-cap converters. The vendor base fragments across blown film extrusion, cast film production, and metallization capabilities. Three archetypes dominate: integrated polymer processors with captive resin supply, flexible packaging specialists with laminating and printing assets, and logistics-focused stretch film producers. Competitive moves center on mechanical recycling partnerships and coextrusion line upgrades for gauge-down engineering.
Within the regional specialist tier, Amerplast Sp z o.o. and Flex Films Europa SP. Z.O.O. exemplify Polish converters leveraging central European location for pan-European food client service. SÜDPACK Holding GmbH represents German-owned premium positioning through high-performance multilayer structures. These three entities anchor the competitive landscape without dominating share, leaving room for mid-scale players to defend niche applications.
| Leading Market Players |
|---|
| Luigi Bandera SpA |
| Amerplast Sp z o.o. |
| Innovia Films |
| TEKNIKA GROUP |
| Sigma Stretch Film of Europe SP ZOO |
| Berry Global Inc. |
| Flex Films Europa SP. Z.O.O. |
| Dekofilm Polska SP ZOO |
| SÜDPACK Holding GmbH |
| Others |
Pricing and Supply Chain Analysis
Consolidated procurement by pan-European retail chains is compressing supplier rosters and demanding integrated design-to-recyclability services, forcing Polish converters to absorb compliance costs into contract pricing while seeking resin diversification to protect margin structures.
Pricing Analysis
Input-cost pass-through from naphtha and natural gas-derived monomer swings governs converter margin volatility. Three-tier pricing structure across premium, standard, and economy levels separates SÜDPACK's high-performance multilayer meat packaging from commodity stretch film grades. Price differentiation hinges on EFSA food-contact certification and oxygen barrier performance tiers. Cost compression in standard-grade stretch film is intensifying because German retail supply chains are consolidating volume tenders. Discount retail chains exhibit highest price sensitivity, while pharmaceutical blister lidding buyers prioritize migration compliance over unit economics.
Supply Chain Analysis
Polish national implementation of extended producer responsibility rules under the EU Single-Use Plastics Directive is reshaping sourcing toward domestic mechanical recyclers with EFSA clearance. Resin supply draws from Germany, Belgium, and the Netherlands, with polypropylene and polyethylene feedstocks anchored in Northwest European petrochemical corridors. Raw material dependencies rest on naphtha crackers, natural gas liquids, and imported polymer pellets. Single-source vulnerability elevates risk for undifferentiated converters without multi-country procurement desks. Distribution runs through Greater Poland Voivodeship extrusion clusters serving German logistics hubs and Czech packaging operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Poland's plastic packaging films sector functions as a stable compounder, with EU Packaging and Packaging Waste Directive recycling mandates guaranteeing offtake for domestic recyclers achieving food-contact clearance.
For Market Incumbents: Deepen mechanical recycling infrastructure partnerships before EU PPWR implementation timelines harden. Secure captive supply of post-industrial film scrap to offset recyclate quality deficits. Add coextrusion capacity in Greater Poland Voivodeship to defend position against German-owned premium competitors. Prioritize EFSA migration testing pre-submissions to compress Polish Centre for Testing and Certification approval cycles. For New Entrants and Emerging Players: Capture pharmaceutical blister lidding demand from Wrocław's generic drug manufacturers, where domestic cold-formable laminate capacity remains underdeveloped. Target metallized film lamination for Łódź Voivodeship dairy processors expanding extended shelf-life formats. Lead with ISCC PLUS-certified bio-based polypropylene pilots for organic food labels commanding 15-30% price premiums. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale converters possessing coextrusion die expertise and existing EFSA food-contact dossiers. Five-to-ten-year viability rests on mechanical recyclate integration capabilities rather than virgin resin scale. Watch for Polish Centre for Testing and Certification approval timeline compression as inflection signal for commercialization velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Mechanical Recycling Partnership | EFSA food-contact clearance for film-to-film circularity unlocks guaranteed offtake under EU PPWR mandates. |
| Coextrusion Line Upgrade | Blown-film gauge-down engineering offsets polypropylene price volatility for Greater Poland Voivodeship converters. |
| Chemical Recycling Investment | Pyrolysis partnerships achieve food-grade recyclate volumes beyond mechanical process limitations. |
| Pharmaceutical Laminate Pilot | Cold-formable aluminum-plastic capacity addresses Wrocław generic drug manufacturer demand. |
| Bio-based Resin Certification | ISCC PLUS accreditation captures organic food label premiums from pan-European retail chains. |
Research Methodology
Multiple input streams — extrusion plant managers, procurement leads at Polish meat processors, distribution channel partners, and polymer sourcing directors — were reconciled against trade flow databases, Polish Centre for Testing and Certification filings, and EU ECHA REACH substance registrations. Primary interviews with blown-film process engineers and metallization technicians informed operational constraint assessments. Secondary validation drew from Polish customs records, Cefic polymer demand reports, and SEC filings of listed packaging multinationals. Bottom-up capacity installation tallies and top-down end-use consumption estimates were triangulated to anchor volume figures.
Data-stream reconciliation across product chemistry, end-use application, gauge thickness, and physical form dimensions shaped the analytical framework throughout the projection horizon. Modeled segmentation spanned stretch film, shrink film, BOPP film, and CPP film categories crossed against food and beverage, healthcare, personal care, and electronics end-use industries. CAGRs were derived from elasticity-adjusted demand curves incorporating resin price volatility coefficients and EU regulatory compliance cost trajectories. Forecast inputs included Polish meat processor packaging procurement patterns and pan-European retail chain consolidation timelines.
Feedstock price volatility, EU PPWR implementation schedule shifts, and EFSA migration testing approval backlogs are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions regarding mechanical recycling infrastructure buildout rates and chemical recycling technology cost curves. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
PVC Films Market
Poly film
Australia and New Zealand Plastic Packaging Film Market
Poly film
Poly Coated Paper Market
Poly film
Polyester Film Market
Poly film
Hexacomb Packaging Market
Poly film
Polyolefin Battery Separator Films Market
Poly film
US Cleanroom Film and Bags Market
Poly film
Twist Wrap Film Market
Poly film
Light Reflective Film Market
Poly film
Global BOPP Films Market
Poly film
Bopet Films Market
Poly film
Silicone-Coated PET Films Market
Poly film
Timber Wrap Films Market
Poly film
Biaxially Oriented Polyethylene Terephthalate (BOPET) Films Market
Poly film
India Plastic Packaging Film Market
Poly film
Polyurethane (PU) Film Market