
 Vinyl Films Market | 2026-2036
Vinyl Films Market Size, Share, and Industry Trends Forecast 2026-2036
Vinyl Films Market Analytics
China's calendering corridor is fragmenting as new domestic capacity reshapes regional supply dynamics. Avery Dennison leverages its adhesive science heritage to dominate premium automotive wrap channels across North America. Saint-Gobain anchors European architectural film demand through specialized coated films for building facades. ORAFOL competes in reflective safety applications where optical performance standards differentiate procurement decisions.
Vinyl films are flexible polyvinyl chloride (PVC) or polyolefin substrates, typically 50-200 microns thick, manufactured through calendering or extrusion processes and functionalized with adhesives, coatings, or thermal transfer layers for surface protection, decoration, or information display. Calendering technology sustains cost leadership in high-volume decorative and adhesive film production where gauge consistency determines downstream printability. Extrusion-based thermal films are capturing share in textile transfer applications where lower minimum order quantities attract mid-size print service providers. Coated films command margin premiums in automotive and branding segments where weathering resistance and conformability to complex curves justify specification upgrades.
REACH phthalate restrictions and the EU Green Deal's polymer circularity targets are forcing reformulation investments across European vinyl film supply chains. China's GB standards and the US EPA's vinyl chloride emissions rules shape product standards and market access conditions in the two largest production geographies. Stakeholders must monitor regulatory divergence between jurisdictions while calibrating R&D budgets toward compliant plasticizer platforms.
Market Dynamics
REACH phthalate restrictions and the EU Green Deal are forcing immediate reformulation across European vinyl film supply chains, while China's calendering capacity expansion reshapes regional sourcing patterns for Asia-Pacific converters.
Growth Catalysts
- Fleet Branding Mandates:Commercial vehicle operators in the United States are specifying durable wrap films for consistent corporate identity across distributed fleets, creating pull-through demand for high-performance calendered grades.
- ECHA Plasticizer Phase-outs:REACH Annex XVII restrictions on ortho-phthalates are accelerating bio-based adipate and citrate plasticizer adoption, opening specification windows for compliant film producers.
- Digital Printing Convergence:UV-curable and latex ink technologies are expanding addressable substrate ranges, enabling mid-volume print service providers to enter textured and metallic vinyl applications previously reserved for screen houses.
Market Restraints
- Chlor-Alkali Feedstock Volatility:Vinyl chloride monomer prices track caustic soda and ethylene dichloride markets, compressing margin predictability for extrusion-grade film producers.
- Calendering Concentration in East Asia:China's domestic capacity expansion is consolidating regional supply, creating dependency risks for converters in Southeast Asia and Oceania.
- Polyolefin Substitution in Textile Transfers:TPU and TPO thermal films are capturing share in heat-transfer applications where PVC face-stock regulations tighten.
Strategic Opportunities
- Architectural Refurbishment Cycles:Building facade renovation mandates in Germany and France are expanding specification opportunities for specialized coated films with extended weathering warranties.
- Reflective Safety Standardization:EN 12899 and ASTM D4956 harmonization gaps create first-mover advantage for producers qualifying dual-certified sheeting for road signage and vehicle conspicuity.
- Closed-Loop Collection Infrastructure:Extended producer responsibility frameworks in the Netherlands and Belgium are enabling post-industrial PVC film recovery streams that reduce virgin resin exposure.
Industry Challenges
- Adhesive Formulation Expertise Gap:Solvent-free and hot-melt PSA development requires polymer science capabilities scarce among traditional calendering houses.
- Multi-Jurisdiction Compliance Parallelism:Simultaneous REACH, GB standards, and US EPA vinyl chloride emission compliance demands redundant testing protocols and documentation systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vinyl Films Market |
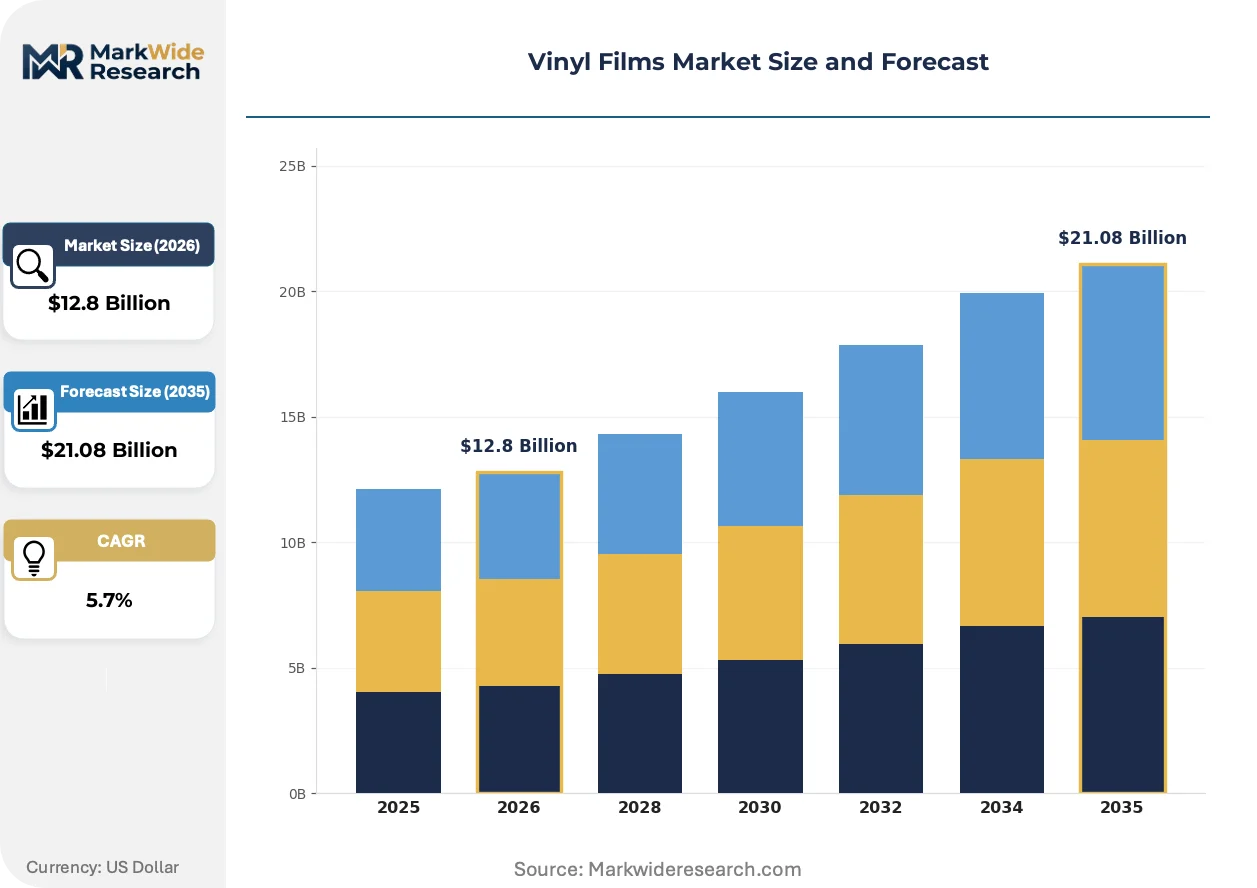
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $21.08 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Decorative Films, Adhesive Films, Coated Films, Thermal Films Application: Packaging, Branding, Textiles, Automotive End User: Manufacturers, Retailers, Print Service Providers, Consumers Technology: Calendering, Extrusion, Injection Molding, Laminating |
| Companies Covered | 3M, Avery Dennison, Saint-Gobain, Eastman Chemical Company, ORAFOL, Hexis, Arlon Graphics, Lintec Corporation, Tekra Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vinyl Films Market Evolving Landscape
Material science advances and regulatory stringency are compressing product development cycles, while digital workflow integration is reshaping how converters specify and procure film substrates.
Hybrid polymer systems combining PVC with bio-based copolymers are hybridizing traditional calendering lines to achieve lower Shore A hardness without ortho-phthalate plasticizers. Automotive wrap installers in California and Texas are qualifying these grades for complex curve applications where conformability determines labor efficiency. The structural result is hybridizing the boundary between commodity decorative films and premium cast automotive grades, compressing price stratification in mid-tier segments.
REACH Annex XIV authorization requirements for medium-chain chlorinated paraffins are forcing flame-retardant film reformulations across European construction and transportation applications. Compounders are pivoting toward phosphate ester and metal hydrate alternatives, though these shift smoke density profiles in rail and aviation specifications. Building product manufacturers in Germany and the United Kingdom are absorbing certification retesting costs while pressuring suppliers for formulation transparency.
Specification workflows are migrating toward digital color matching and remote sampling platforms that compress the traditional converter-distributor relationship. Mid-size print service providers in the United States are adopting cloud-based substrate libraries that bypass regional distributor inventory constraints. This disintermediation is most pronounced in custom color architectural film procurement, where project-specific batch matching previously required physical sample circulation.
Vinyl Films Market Segmentation
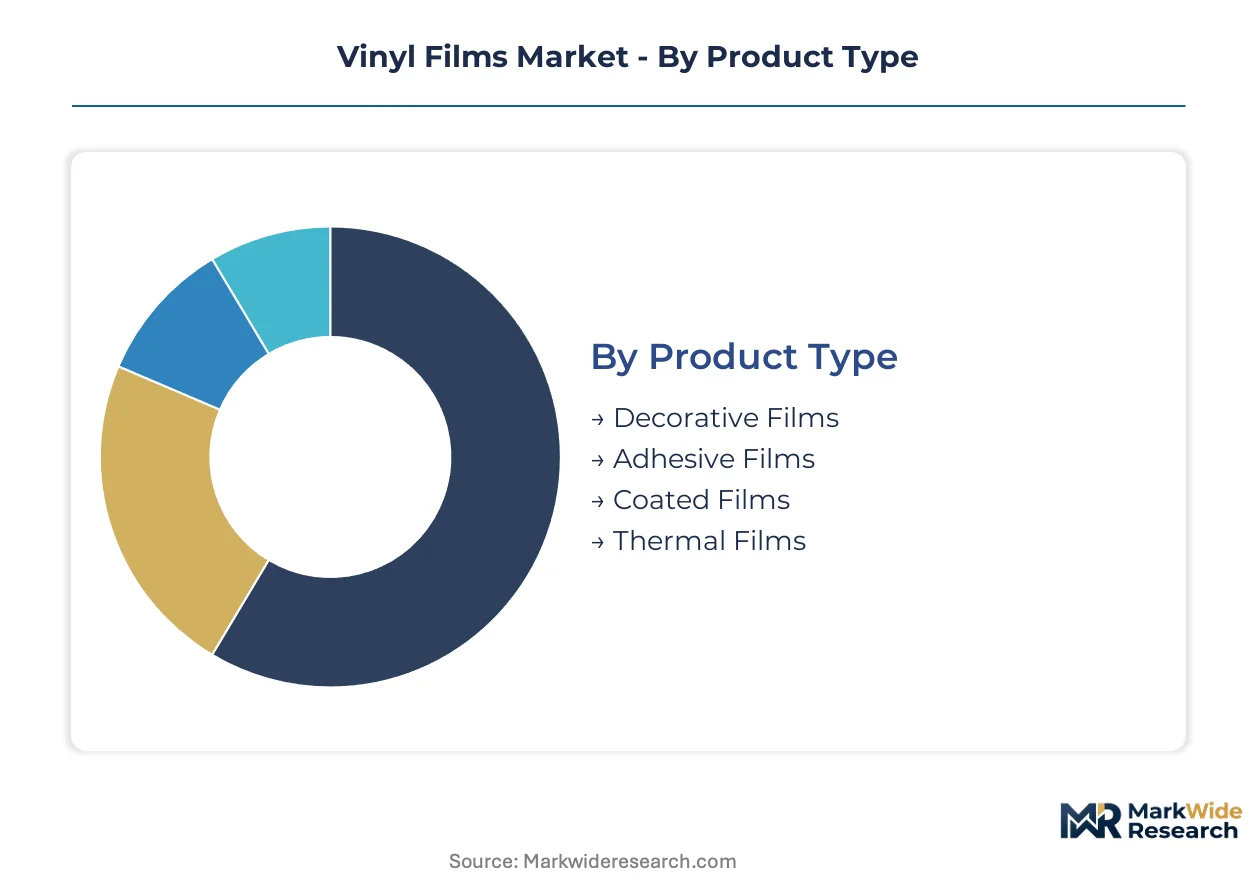
Vinyl film procurement patterns diverge sharply across end-use specifications, with automotive wraps demanding conformability warranties while packaging converters prioritize gauge consistency at scale. Segmentation clarity enables suppliers to align calendering investments against margin pools rather than commoditized volume.
Product Type:
After-sales service intensity varies dramatically across product categories, with coated films requiring field technical support for warranty claims while decorative films operate through distributor inventory programs.
- Decorative Films:Calendered PVC substrates with embossed or printed surface patterns serve interior refurbishment and point-of-sale display applications. Fleet operators in the United States specify these grades for vehicle livery where color consistency across replacement panels determines brand integrity. Demand concentrates in high-volume roll goods where gauge tolerance directly impacts automated cutting yields.
- Adhesive Films:Pressure-sensitive constructions combining face-stock with solvent-acrylic or hot-melt PSA layers dominate removable and permanent bonding applications. Print service providers in Germany and France are qualifying these grades for architectural facade refurbishment where EN 13501 fire reaction classifications govern specification. The segment commands technical support resources for surface preparation protocols and dwell time optimization.
- Coated Films:Specialized top-coated constructions for weathering resistance and chemical protection.
- Thermal Films:Heat-activated adhesive systems for textile transfer and lamination applications.
By volume, decorative films lead. By growth pace, adhesive films are expanding most quickly.
Application:
Cost tier stratification separates specification-grade automotive applications from commodity packaging converters, with branding occupying the contested middle ground where digital print compatibility determines switching costs.
- Packaging:High-clarity calendered films with food-contact compliance serve blister packs, labels, and shrink sleeves. Retailers in the Netherlands specify these grades for private-label cosmetics where ECHA plasticizer restrictions mandate adipate-based formulations. Volume concentration in folding carton and flexible packaging converters drives minimum order quantity discipline.
- Branding:Premium cast and calendered constructions for corporate identity, fleet graphics, and retail environments. Fleet operators across Texas and California are specifying these grades for vehicle wraps where conformability to compound curves reduces installation labor hours. The segment absorbs disproportionate technical service investment for color matching and installation training.
- Textiles:Heat-transfer films for apparel decoration and industrial fabric lamination.
- Automotive:Cast PVC and hybrid polymer films for exterior wrap and paint protection applications.
By volume, packaging leads. By growth pace, automotive is gaining share fastest.
End User:
Customer type determines specification authority, with manufacturers controlling material selection while print service providers increasingly influence substrate procurement through digital workflow integration.
- Manufacturers:OEM and tier suppliers integrating vinyl films into finished products. Automotive manufacturers in Germany specify coated films for interior trim applications where KBA homologation requirements govern material approvals. Procurement concentrates through qualified supplier lists with multi-year volume commitments.
- Retailers:Private-label and house-brand operators sourcing packaging and promotional films. Large-format retailers in the United States are consolidating vinyl film procurement through centralized category management, pressuring distributors for inventory visibility and consignment arrangements.
- Print Service Providers:Wide-format and industrial converters specifying substrates for client projects.
- Consumers:DIY and small-scale users purchasing through retail and e-commerce channels.
By volume, manufacturers lead. By growth pace, print service providers show the steepest expansion trajectory.
Technology:
Supply concentration in East Asian calendering capacity is reshaping technology selection, with extrusion capturing share where lower capital barriers attract mid-scale entrants.
- Calendering:Multi-roll polishing systems producing gauge-consistent films at high throughput. China's domestic capacity expansion in Zhejiang and Jiangsu provinces is scaling output for Asia-Pacific converters, though REACH-compliant formulations for European export require dedicated production lines. The technology sustains cost leadership in decorative and adhesive film categories.
- Extrusion:Single and twin-screw systems for thermal films and specialized constructions. Mid-size converters in the United States are adopting extrusion-based thermal films for textile transfer applications where reduced minimum order quantities improve inventory turns. Equipment flexibility enables rapid formulation pivots for regulatory compliance.
- Injection Molding:Limited vinyl film applications in rigid-over-flexible combinations.
- Laminating:Adhesive and thermal bonding of multi-layer constructions.
By volume, calendering leads. By growth pace, extrusion is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Calendering capacity clusters in China's coastal provinces, while formulation expertise concentrates in German industrial corridors and specialty film production anchors in the US Midwest.
United States
Fleet branding mandates and automotive wrap demand pull high-performance calendered grades through Texas and California installer networks. EPA vinyl chloride emission rules shape production standards at Gulf Coast resin complexes. The Midwest manufacturing belt sustains captive supply chains for pressure-sensitive adhesive constructions serving North American converters.
Germany
Building facade refurbishment cycles and automotive OEM specifications drive coated film demand across Bavaria and North Rhine-Westphalia. REACH Annex XVII phthalate restrictions and KBA homologation requirements force simultaneous compliance investments. The Rhine-Ruhr industrial corridor hosts compounders pivoting toward bio-based adipate plasticizers for construction-grade films.
China
Domestic calendering expansion in Zhejiang and Jiangsu provinces scales output for Asia-Pacific converter demand. GB standards on plasticizer migration and MEE environmental enforcement tighten formulation protocols. The Yangtze River Delta concentration is consolidating regional supply, creating sourcing dependencies for Southeast Asian processors.
Japan
Precision coating applications and electronics-grade film specifications sustain premium thermal film production. METI circular economy guidelines and JIS standards on chemical content shape material selection protocols. The Kanto region around Tokyo anchors specialized laminating operations for industrial textile transfers.
France
Architectural film demand concentrates in Île-de-France renovation projects and Auvergne-Rhône-Alpes industrial signage. ECHA authorization requirements for medium-chain chlorinated paraffins force flame-retardant reformulations. Lyon-based compounders are absorbing certification retesting costs while qualifying phosphate ester alternatives for rail specifications.
Vinyl Films Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream where formulation science and adhesive chemistry determine specification authority. Market structure consolidates around three to five vertically integrated resin-to-film producers alongside fragmented regional calendering houses. Strategic archetypes separate global specification leaders, regional volume suppliers, and niche technology licensors. Competitive moves concentrate on capacity expansion in East Asian calendering corridors and backward integration into captive plasticizer supply.
Among North American specification leaders, 3M and Avery Dennison occupy positions where adhesive platform heritage translates into automotive wrap and fleet branding procurement decisions. Hexis represents the European specialist tier where cast film expertise commands premium positioning in complex curve applications. These anchors exemplify how formulation depth and installation training ecosystems create switching costs that resist commoditization pressure from volume-driven Asian competitors.
| Leading Market Players |
|---|
| 3M |
| Avery Dennison |
| Saint-Gobain |
| Eastman Chemical Company |
| ORAFOL |
| Hexis |
| Arlon Graphics |
| Lintec Corporation |
| Tekra Corporation |
| Others |
Value Network & Pricing Analysis
Zhejiang and Jiangsu provinces anchor calendering capacity expansion that feeds downstream pricing power into Asia-Pacific converter markets, while REACH-compliant production lines in Europe command specification premiums through plasticizer reformulation costs.
Pricing Analysis
REACH Annex XVII dictates the pricing tier structure across European vinyl film procurement. Three-tier pricing structure across premium, standard, and economy levels separates cast automotive grades with conformability warranties from commodity decorative rolls. Price differentiation hinges on certification grade for EN 12899 reflective sheeting and volume scale for fleet branding contracts. Pricing pressure stems from chlor-alkali feedstock volatility compressing extrusion-grade margins. Packaging converters show highest price sensitivity due to minimum order quantity discipline, while automotive wrap installers absorb premiums for labor-efficient installation grades.
Supply Chain Analysis
Export-control regimes on medium-chain chlorinated paraffins under REACH Annex XIV restrict flame-retardant film flows from European compounders to rail and aviation specifications. Geographic supply concentrates in China, Germany, and the United States, with China's domestic capacity scaling for Asia-Pacific converter demand. Raw material dependencies rest on vinyl chloride monomer from Gulf Coast resin complexes, adipate plasticizers from Rhine-Ruhr compounders, and pressure-sensitive adhesive polymers from Midwest chemical corridors. Single-source vulnerability concentrates in East Asian calendering equipment. Distribution runs through regional distributor networks for decorative films and direct technical sales for coated automotive grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vinyl films represent a high-growth disruption as digital printing convergence and bio-based plasticizer mandates compress product development cycles and open specification windows for compliant producers.
For Market Incumbents: Insulate specification authority by deepening captive plasticizer supply through backward integration into adipate and citrate compounder networks. Expand dedicated REACH-compliant production lines in German industrial corridors to defend margin position against volume-driven Asian competitors. Prioritize adhesive formulation R&D for solvent-free PSA platforms where polymer science capabilities create switching costs. For New Entrants and Emerging Players: Pursue white-space opportunities in textile transfer applications where extrusion-based thermal films capture share from PVC face-stock regulations. Target mid-size print service providers in the United States adopting cloud-based substrate libraries that bypass traditional distributor constraints. Lead with lower minimum order quantities and rapid formulation pivots for regulatory compliance as the primary go-to-market angle. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with stranded calendering assets lacking adhesive science capabilities. Long-term viability favors producers with vertical control over plasticizer supply and certification depth for multi-jurisdiction compliance. Watch for ECHA authorization timeline acceleration as the inflection signal forcing consolidation among non-compliant compounders.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plasticizer Supply | Captive adipate and citrate production secures REACH compliance margins against feedstock volatility. |
| Capacity Expansion in Zhejiang Corridor | Domestic calendering scale captures Asia-Pacific converter volume while export lines serve European specification demand. |
| Green Manufacturing Transition | Bio-based copolymer hybridization opens automotive wrap specifications in California and Texas markets. |
| Long-term Supply Agreement | Fleet operator contracts for durable wrap films lock in multi-year volume commitments across distributed vehicle networks. |
| Joint Venture | Adhesive science partnerships with polymer specialists close formulation expertise gaps in traditional calendering houses. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC filings from resin producers, ECHA substance restriction notifications, and industry association reports from ACC and Cefic. Conversations with calendering plant managers, procurement leads at automotive wrap installers, distribution channel partners, and technical R&D directors at adhesive compounders inform demand-side validation. Bottom-up volume triangulation across product grades and applications converges with top-down macroeconomic sensitivity testing.
Forecast inputs include capacity utilization rates at Zhejiang and Jiangsu calendering facilities, plasticizer price indices, and fleet branding contract volumes across the projection horizon. Segmentation dimensions span product type, application, end user, and technology with regional production hub differentiation. CAGRs derive from regression analysis against historical volume trajectories and elasticity modeling for regulatory compliance cost pass-through. Industry-specific inputs incorporate EN 12899 certification adoption curves and digital print penetration rates among mid-size service providers.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Asian volume producers or accelerated ECHA authorization timelines would shift outcomes. Material shifts in chlor-alkali feedstock pricing or REACH plasticizer restriction scope would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Silicone Release Films Market
Poly film
China BOPP Film Market
Poly film
Latin America Polypropylene (PP) Packaging Film Market
Poly film
Polyolefin Films Market
Poly film
Stretch Films Packs Market
Poly film
Nylon Films for Liquid Packaging Market
Poly film
Polylaminate Capsules Market
Poly film
PP Film Blowing Machine Market
Poly film
Polysaccharide Films Market
Poly film
Global Specialty Films Polymer Market
Poly film
US Cleanroom Film and Bags Market
Poly film
Shrink Bundling Films Market
Poly film
MOPP Packaging Films Market
Poly film
Hexacomb Packaging Market
Poly film
Poly Coated Paper Market
Poly film
Global Sound Insulation PVB Film Market