
 Acrylic Boxes Market | 2026-2036
Acrylic Boxes Market Size, Share, and Industry Trends Forecast 2026-2036
Acrylic Boxes Market Outlook
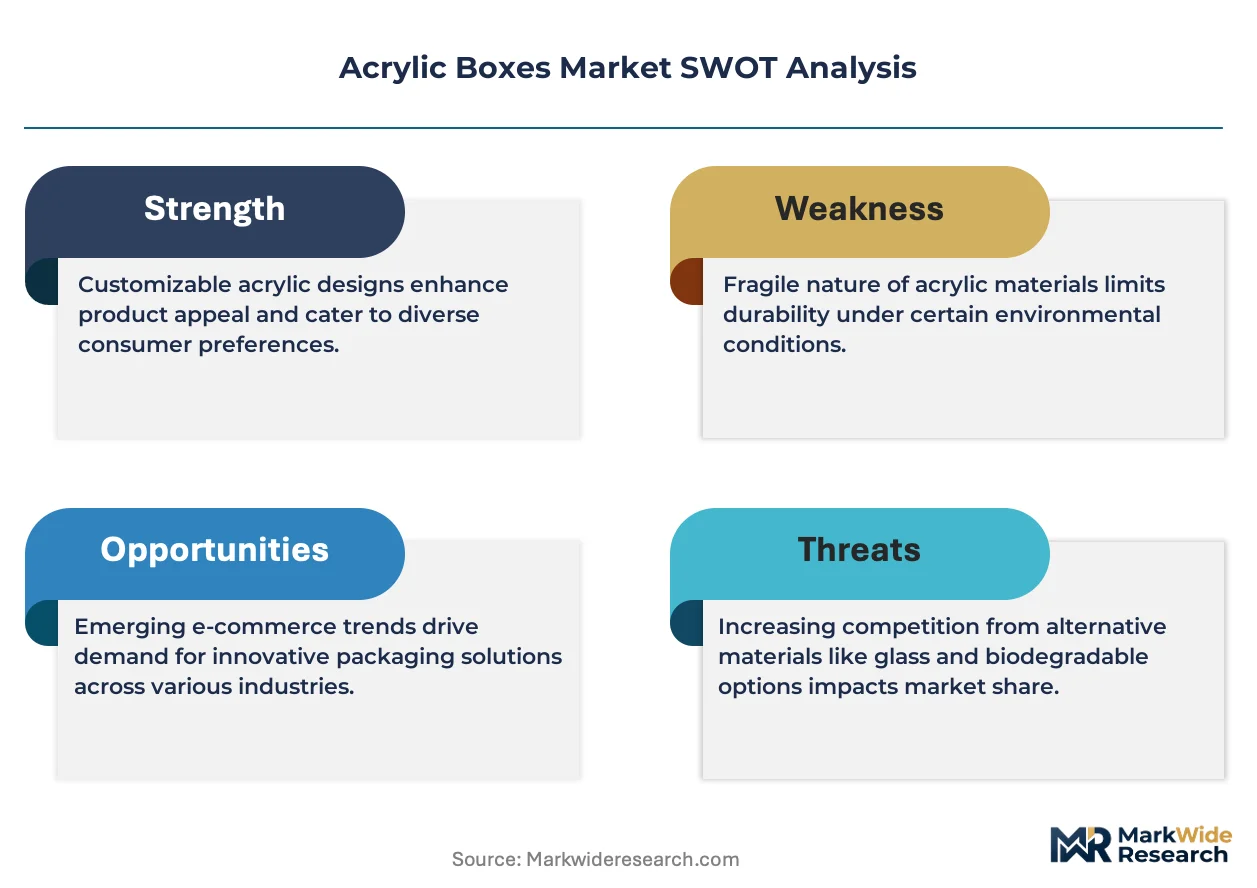
EU REACH compliance is recalibrating how acrylic box manufacturers source monomers and additives across European supply chains. Displays2Go leverages its North American distribution network to sustain volume leadership in retail fixtures. Pioneer Plastics anchors its position through specialized fabrication capabilities for museum-grade cases. Clear-Ad competes aggressively on turnaround speed for custom display orders.
Acrylic boxes are transparent thermoplastic enclosures fabricated from polymethyl methacrylate (PMMA), typically extruded or cast into sheets ranging from 2 mm to 25 mm thickness before being cut, bent, and bonded into finished forms. Display cases dominate product type revenue due to sustained replacement cycles in retail environments, while protective covers represent the fastest-growing segment as collectors and institutions prioritize conservation-grade UV-filtering formulations. Small and medium dimensions capture the majority of unit volume, though custom sizing commands disproportionate margin pools in art gallery and luxury retail applications.
EPA guidelines on volatile organic compound emissions shape domestic manufacturing standards for acrylic fabrication facilities in the United States. FDA food-contact regulations influence material grades for storage containers deployed in commercial and educational settings. OSHA workplace exposure limits for methyl methacrylate vapor affect plant layout decisions and automation investments. Stakeholders must monitor evolving state-level extended producer responsibility frameworks that could shift end-of-life collection obligations onto manufacturers.
Market Dynamics
REACH compliance in Europe is recalibrating how acrylic box manufacturers source monomers and additives across European supply chains. Specialty retail and museum sectors in the United States sustain premium acrylic consumption through sustained replacement cycles and conservation-grade specifications.
Growth Catalysts
- Retail Visual Merchandising:Brands prioritize transparent display fixtures to enhance product visibility and customer engagement in high-traffic environments.
- REACH Regulation:ECHA enforcement drives reformulation toward lower-emission monomer streams and certified additive packages across EU manufacturing.
- UV-Filtering Formulations:Conservation-grade PMMA variants penetrate museum and collector markets demanding archival protection standards.
Market Restraints
- Methyl Methacrylate Volatility:Feedstock price swings compress margins for extruded sheet producers serving volume retail accounts.
- Asian Supply Concentration:Cast sheet production clusters in China create vulnerability to freight cost spikes and tariff uncertainty.
- Glass Substitution:Tempered glass retains cost advantage in large-format applications above 50 liters internal volume.
Strategic Opportunities
- Indian Specialty Retail:Organized retail expansion in Mumbai and Delhi generates demand for branded fixture programs with custom acrylic components.
- Extended Producer Responsibility:EU Green Deal frameworks incentivize closed-loop PMMA recycling infrastructure and take-back program development.
- Digital Fabrication Convergence:CNC routing combined with laser edge-polishing enables batch-size-one production at mass-market price points.
Industry Challenges
- Skilled Thermoforming Labor:Complex radius bending and solvent welding require trained technicians that fabricators struggle to recruit in Midwest US manufacturing zones.
- OSHA Compliance Timelines:Methyl methacrylate vapor monitoring and ventilation upgrades demand capital deployment ahead of enforcement windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acrylic Boxes Market |
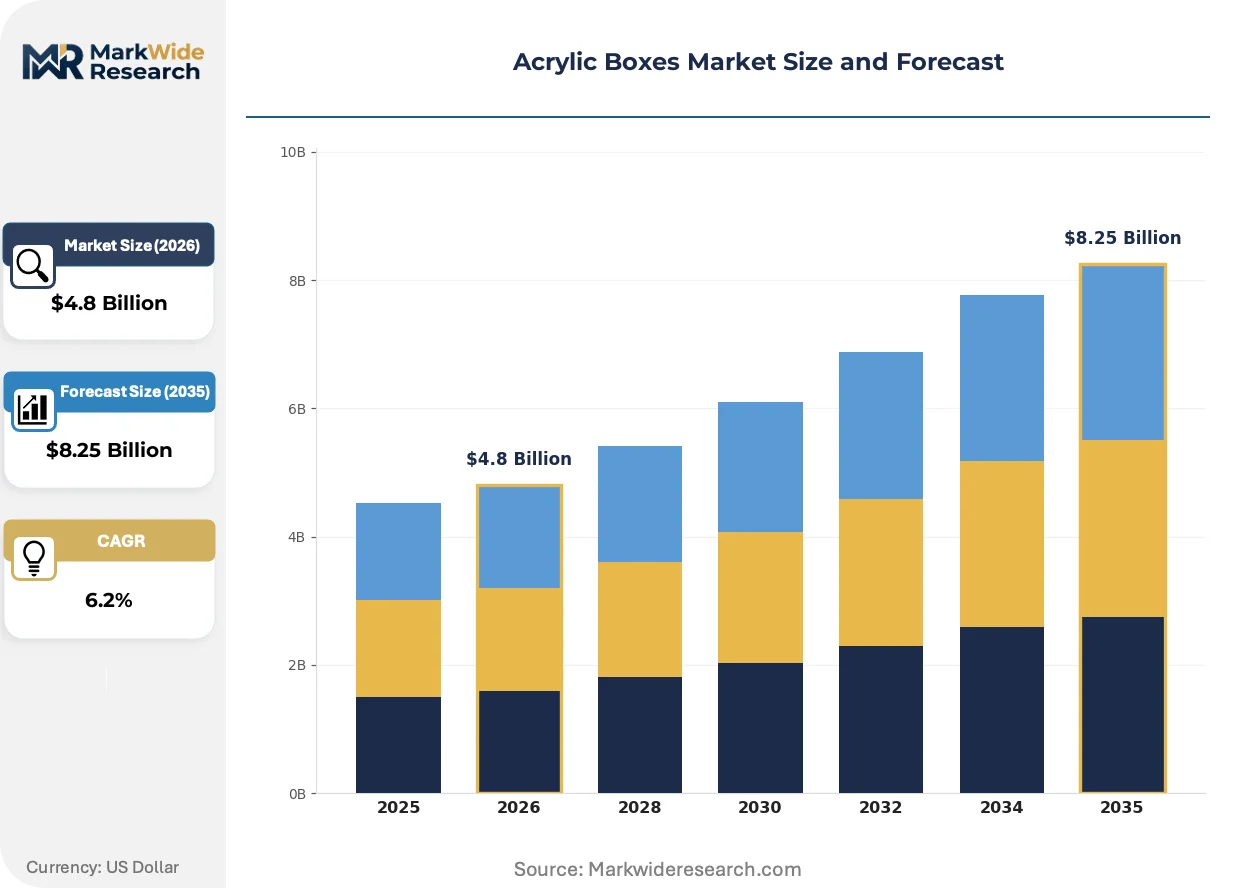
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.25 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Display Cases, Storage Containers, Protective Covers, Specialty Boxes End User: Retail Stores, Art Galleries, Homeowners, Educational Institutions Dimension: Small, Medium, Large, Custom Application: Organization, Decoration, Protection, Showcase |
| Companies Covered | Displays2Go, Pioneer Plastics, Clear-Ad, Linde & Larsen ApS, Weprofab, AKRYLIX, ULINE, ShopPOPDisplays, Plexibox, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acrylic Boxes Market Strategic Shifts
Acrylic box fabrication is absorbing digital production methods and regulatory compliance pressures simultaneously. Material science advances and buyer behavior shifts are compressing traditional supply chain configurations.
Cast PMMA with embedded nanoparticle UV inhibitors is absorbing market share from standard extruded grades in conservation applications. Museum procurement departments specify these formulations for artifact cases exceeding 50-year display horizons. The technology is absorbing premium margin pools previously captured by glass-dominated archival suppliers.
ECHA REACH Annex XVII restrictions on residual monomer content are forcing reformulation investments across European sheet extruders. Manufacturers must certify additive packages through SCIP database registration for SVHC substances above 0.1% threshold. Specialty retail packaging segments face the steepest compliance cost escalation due to complex multi-supplier material flows.
Direct-to-fabricator digital platforms are shortening specification-to-delivery cycles for custom display programs. Brand visual merchandising teams upload CAD files for same-day quoting, bypassing traditional distributor intermediaries. This pattern concentrates in United States specialty retail and pop-up installation markets where speed outweighs unit cost optimization.
Acrylic Boxes Market Segmentation
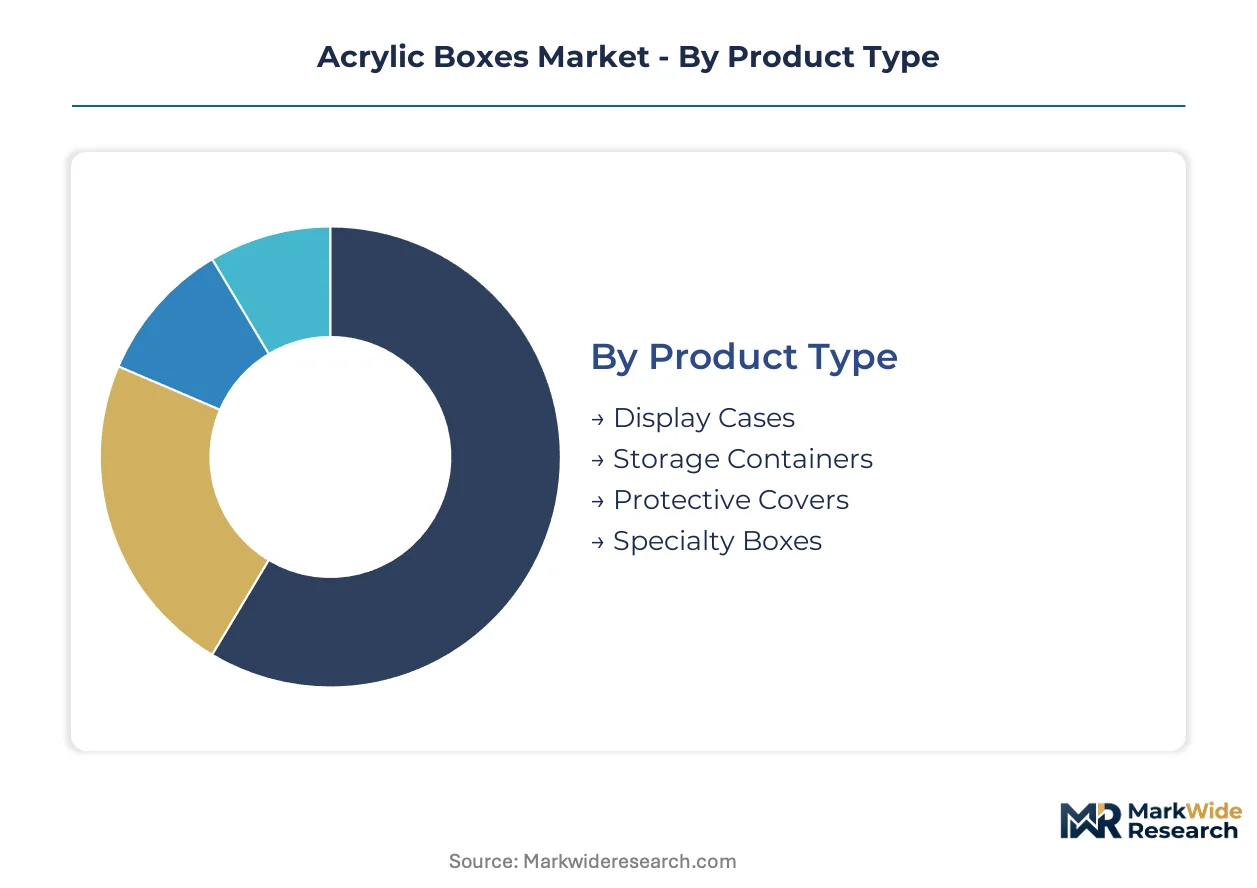
Acrylic box segmentation reveals how material specifications and end-use durability requirements fragment procurement patterns across replacement-driven retail environments and conservation-focused institutional settings. Distinct performance tiers emerge from the interplay of optical clarity standards, dimensional precision, and UV-filtering capabilities demanded by specific applications.
Product Type:
Replacement cycles in visual merchandising and archival conservation create divergent upgrade pathways across product categories, with retail fixtures prioritizing cost-efficient refresh schedules while museum cases demand generational durability investments.
- Display Cases:Fabricated from extruded or cast PMMA sheets with polished edges and solvent-welded seams, these fixtures dominate fixture procurement budgets in United States specialty retail chains. Sustained replacement cycles in high-traffic mall environments and pop-up installations drive volume demand, though margin compression intensifies as direct-to-fabricator digital platforms bypass traditional distribution.
- Protective Covers:Conservation-grade formulations with embedded nanoparticle UV inhibitors serve museum and collector markets demanding archival protection standards. Collector markets in the United States and European conservation institutions sustain premium pricing for formulations exceeding 50-year display horizons, absorbing margin pools previously captured by glass-dominated suppliers.
- Storage Containers:FDA food-contact compliant grades serve commercial kitchens and educational cafeterias where material certification outweighs optical premium requirements.
- Specialty Boxes:Custom-fabricated forms with integrated lighting channels or humidity control features address niche jewelry and electronics packaging segments.
Volume placements concentrate in Display Cases; the faster expansion belongs to Protective Covers.
End User:
Customer procurement sophistication spans from specification-heavy institutional buyers to price-sensitive residential purchasers, creating tiered service requirements that reshape fabricator sales organization structures.
- Retail Stores:Visual merchandising teams in United States specialty retail chains specify batch-size-one custom programs with compressed turnaround demands. Direct digital platform adoption accelerates as brand teams upload CAD files for same-day quoting, bypassing distributor intermediaries where speed outweighs unit cost optimization.
- Art Galleries:Conservation-grade specifications and white-glove installation services command premium positioning, with procurement departments certifying UV-filtering formulations through documented testing protocols.
- Homeowners:E-commerce channels and big-box retail capture this price-sensitive segment where standardized dimensions and self-assembly designs dominate purchasing decisions.
- Educational Institutions:FDA-compliant storage containers and display cases for science departments operate within constrained procurement frameworks emphasizing durability warranties and volume discounts.
Revenue concentration sits with Retail Stores; Art Galleries deliver the steepest margin expansion trajectory.
Dimension:
Manufacturing economies of scale in standardized sheet sizes create cost discontinuities at dimensional thresholds, while custom fabrication capabilities unlock premium positioning in specification-heavy segments.
- Small:Jewelry and collectibles cases exploit material efficiency from standardized sheet cutting patterns, with CNC routing enabling complex interior fittings at mass-market price points.
- Medium:Countertop display fixtures and museum pedestal cases capture the majority of unit volume through balanced material yield and shipping logistics optimization.
- Large:Tempered glass substitution pressure intensifies above 50-liter internal volumes where acrylic weight and material cost disadvantages compound.
- Custom:Art gallery and luxury retail applications command disproportionate margin pools through specialized fabrication capabilities including complex radius bending and solvent welding of non-rectilinear forms.
Unit economics favor Medium dimensions; Custom sizing extracts the highest margin per square meter fabricated.
Application:
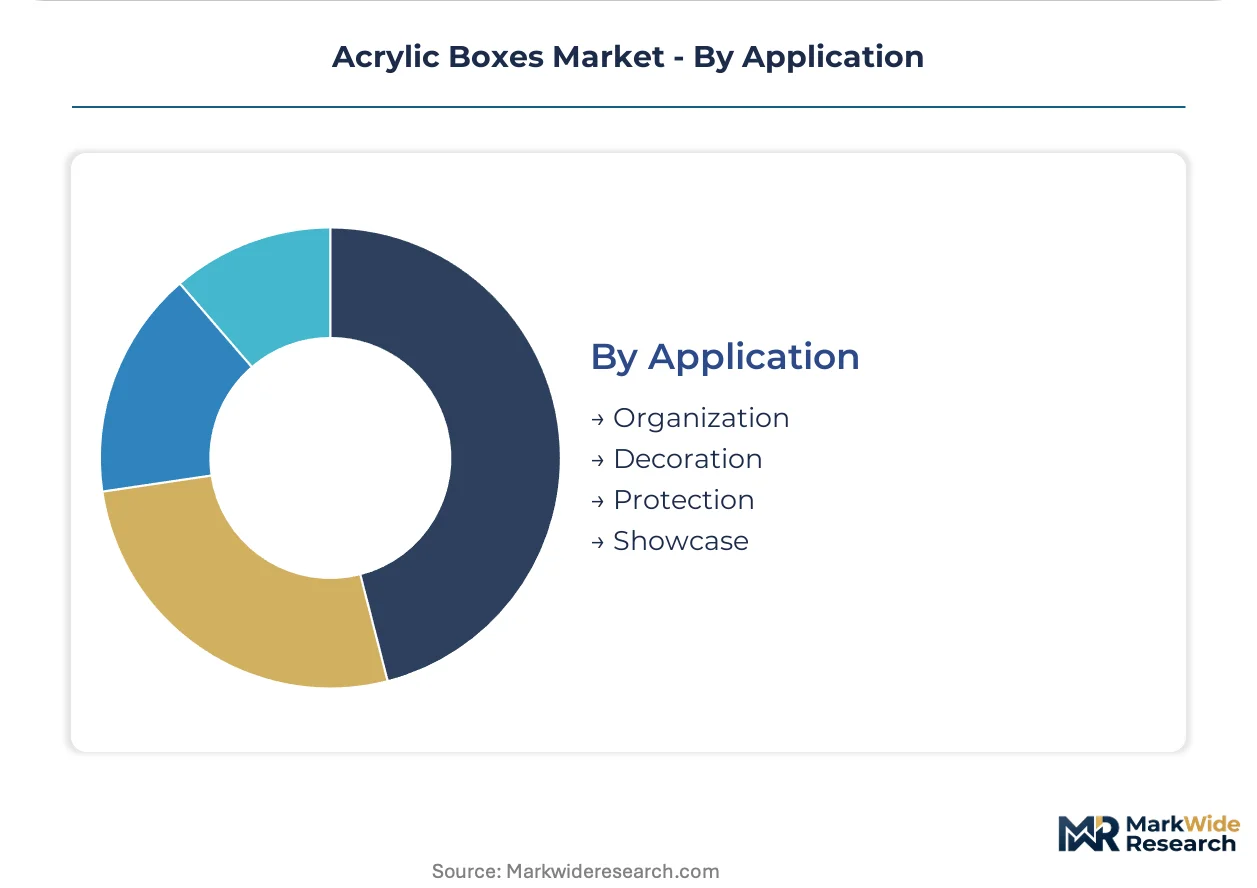
Functional purpose determines material grade selection and durability specifications, with protection and showcase applications driving premium formulation adoption against commoditized organization and decoration segments.
- Organization:Desktop accessories and drawer inserts utilize standard extruded grades where optical clarity requirements remain minimal and cost competition from alternative materials constrains pricing power.
- Decoration:Residential accent pieces and event staging components prioritize aesthetic surface finishes over structural performance, with seasonal demand patterns creating production scheduling challenges for fabricators.
- Protection:Conservation-grade PMMA with UV-filtering formulations penetrates museum and archival markets where failure costs justify generational material investments and certified additive packages.
- Showcase:Retail visual merchandising demands combine optical clarity with durability against cleaning chemical exposure and physical impact in high-traffic environments.
Protection applications sustain the highest material grade premiums; Showcase drives the largest absolute volume throughput.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Guangzhou anchors cast PMMA sheet production for Asian export markets, while specialty fabrication clusters in the United States and Germany serve premium retail and museum segments with differentiated UV-filtering formulations.
United States
Specialty retail chains in New York and Los Angeles drive custom fixture demand with compressed turnaround requirements. OSHA workplace exposure limits for methyl methacrylate vapor shape plant layout decisions across Midwest manufacturing zones. Chicago-area fabricators invest in automation to address skilled thermoforming labor scarcity.
Germany
Museum procurement departments in Berlin and Munich specify conservation-grade PMMA with embedded nanoparticle UV inhibitors. ECHA REACH Annex XVII restrictions on residual monomer content force reformulation investments across European sheet extruders. Bavarian fabrication clusters develop certified additive packages for archival applications.
China
Cast sheet production concentrates in Guangdong and Zhejiang provinces for cost-sensitive retail display exports. The country's national environmental regulator enforces volatile organic compound emission standards at fabrication facilities. Yangtze River Delta manufacturers face freight cost volatility and tariff uncertainty on North American-bound shipments.
India
Organized retail expansion in Mumbai and Delhi generates demand for branded fixture programs with custom acrylic components. BIS certification requirements influence material grade selection for commercial storage applications. Gujarat-based fabricators scale CNC routing capabilities to serve domestic countertop display fixture growth.
Japan
Collector markets in Tokyo and Osaka sustain premium pricing for conservation-grade formulations exceeding 50-year display horizons. METI industrial standards shape optical clarity specifications for archival case applications. Kansai-region fabricators specialize in complex radius bending for luxury retail packaging segments.
Acrylic Boxes Market Competitive Environment
Premium-margin players sit above commodity-margin players across fabrication capability and material certification tiers. The vendor base stratifies between volume-driven extruded sheet distributors and specialized conservation-grade fabricators serving institutional procurement. Three archetypes dominate: North American retail fixture specialists, European museum-grade case fabricators, and Asian cast sheet producers. Competitive moves concentrate on direct-to-fabricator digital platform deployment and closed-loop PMMA recycling infrastructure development.
Among North American retail fixture specialists, Displays2Go exemplifies distribution network scale, while Pioneer Plastics occupies a position within the museum-grade fabrication tier. Clear-Ad represents the turnaround-speed competitive vector. These three names anchor the competitive structure without exhausting the vendor landscape.
| Leading Market Players |
|---|
| Displays2Go |
| Pioneer Plastics |
| Clear-Ad |
| Linde & Larsen ApS |
| Weprofab |
| AKRYLIX |
| ULINE |
| ShopPOPDisplays |
| Plexibox |
| Others |
Value Chain & Pricing Dynamics
Captive integration into monomer production anchors supply positions for European and North American fabricators, insulating premium-tier participants from methyl methacrylate feedstock volatility while compressing margin pools for distributors lacking upstream control. This structural choice simultaneously determines pricing power in conservation-grade segments and vulnerability in commodity display fixture markets.
Pricing Analysis
Outcome-based pricing tied to archival protection duration anchors conservation-grade PMMA premiums, with museum procurement departments paying for certified 50-year display horizons rather than per-kilogram material costs. Three-tier pricing structure across conservation-grade, commercial-grade, and economy extruded tiers separates UV-filtering formulations from standard optical grades from recycled-content batches. Cost compression in economy extruded tiers is intensifying because direct-to-fabricator digital platforms bypass distributor markups. Retail visual merchandising teams exhibit highest price sensitivity, while European museum conservators demonstrate lowest sensitivity due to failure-cost justification.
Supply Chain Analysis
Returns and end-of-life collection flows are emerging as critical infrastructure investments under EU Green Deal extended producer responsibility frameworks, with German fabricators piloting closed-loop PMMA recycling to recover scrap from fabrication offcuts. Raw material supply concentrates in China, Germany, and the United States, with cast sheet production clustering in Guangdong and extruded grades anchored in North American petrochemical corridors. Methyl methacrylate monomer, UV inhibitor nanoparticles, and solvent bonding agents constitute the critical input trinity. Single-source vulnerability in Chinese cast sheet exports creates exposure to freight cost spikes and tariff uncertainty. Distribution runs through direct digital platforms for custom specifications and traditional industrial distributors for standardized volume accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH compliance functions as a cost-of-compliance moat, with ECHA enforcement recalibrating material sourcing requirements and forcing reformulation investments that disadvantage undercapitalized entrants lacking SCIP database registration capabilities.
For Market Incumbents: To counter direct-to-fabricator digital platform disintermediation, Displays2Go and Pioneer Plastics should deepen backward integration into certified additive package formulation and expand CNC routing automation in Midwest manufacturing zones to offset skilled thermoforming labor scarcity. For New Entrants and Emerging Players: Launch via direct digital platforms targeting Indian organized retail expansion in Mumbai and Delhi, where branded fixture program demand outpaces domestic fabrication capacity. White-space concentration sits in batch-size-one custom programs for pop-up installations where speed outweighs unit cost optimization. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by North American retail fixture specialists seeking conservation-grade fabrication capabilities. Long-term viability favors participants with certified REACH compliance and closed-loop recycling infrastructure. Monitor ECHA enforcement timelines for methyl methacrylate residual content restrictions as inflection indicator for compliance-cost escalation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Monomer Production | Insulates margin pools from methyl methacrylate feedstock volatility affecting extruded sheet producers. |
| Closed-Loop PMMA Recycling Infrastructure | Positions fabricators for EU Green Deal extended producer responsibility compliance and take-back program mandates. |
| Direct-to-Fabricator Digital Platform Deployment | Disintermediates traditional distributors in United States specialty retail and pop-up installation markets. |
| Conservation-Grade UV-Filtering Formulation Investment | Captures premium margin pools in museum and collector markets demanding archival protection standards. |
| CNC Routing Automation Scale-Up | Addresses skilled thermoforming labor scarcity in Midwest US manufacturing zones and enables batch-size-one production. |
Study Parameters
Multi-period observation of methyl methacrylate feedstock pricing, REACH compliance cost trajectories, and replacement cycle frequencies in United States specialty retail anchored the trend analysis, supplemented by interviews with acrylic fabrication plant managers, museum procurement directors, visual merchandising leads at retail chains, and distribution channel partners. Secondary validation drew from ECHA SCIP database disclosures, EPA volatile organic compound emission filings, SEC 10-K reports from petrochemical suppliers, and customs trade data for cast and extruded PMMA sheet flows. Bottom-up fabrication capacity estimates triangulated against top-down end-use demand segmentation.
Input-output matrices modeled unit volume and value flows across product type, dimension tier, end-user segment, and application purpose dimensions throughout the projection horizon. CAGRs were derived from regression analysis of historical replacement cycle patterns and forward projection of regulatory compliance cost absorption rates. Industry-specific forecast inputs included ECHA enforcement intensity indices for residual monomer restrictions and Indian organized retail square footage expansion rates.
Feedstock price volatility, REACH regulatory expansion beyond current Annex XVII restrictions, and substitution acceleration toward tempered glass in large-format applications are the dominant revision risks to modeled outputs. Practitioners should monitor ECHA enforcement calendars, methyl methacrylate contract pricing trends, and museum procurement specification shifts for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Containers
Double Seam Bowl Market
Packaging Containers
Gable Top Liquid Cartons Market
Packaging Containers
Packing Boxes Market
Packaging Containers
Bottles Market
Packaging Containers
Single Serve Packaging Market
Packaging Containers
Food Grade Bottles Market
Packaging Containers
Latin America Aerosol Cans Market
Packaging Containers
Child Resistant Bottles Market
Packaging Containers
Middle-East and Africa Paper Cups Market
Packaging Containers
Roll-On Bottles Market
Packaging Containers
Self - Locking Trays Market
Packaging Containers
Insulated Food Containers Market
Packaging Containers
Europe Punnet Trays Market
Packaging Containers
Automotive Parts Packaging Market
Packaging Containers
Dispensing Trays Market
Packaging Containers
Middle East and Africa Aerosol Cans Market