
 Asia Pacific Plastic Packaging Film Market | 2026-2036
Asia Pacific Plastic Packaging Film Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Plastic Packaging Film Market Insights
Multi-source procurement among brand owners is broadening across the Asia Pacific plastic packaging film supply base. Amcor Plc leverages its integrated film-to-package network to secure long-term contracts with multinational food brands. UFlex Limited anchors its position through backward integration into resin compounding and metallization. Cosmo Films Limited differentiates via specialized BOPP film grades for high-barrier pharmaceutical applications.
Asia Pacific plastic packaging film encompasses thermoplastic substrates—primarily polyethylene, polypropylene, and polyester—manufactured through cast extrusion, blown extrusion, or biaxial orientation to thicknesses ranging from ultra-thin (below 12 microns) to thick gauges exceeding 100 microns, serving functions of containment, protection, shelf-life extension, and unitization across industrial and consumer supply chains. Barrier film commands premium positioning due to oxygen and moisture transmission specifications required by processed food and healthcare end users, while stretch film dominates volume throughput in logistics palletization across the region's manufacturing hubs. BOPP film maintains mature, cost-competitive status in snack and confectionery wrapping where clarity and printability drive specification.
Japan's METI enforces container and packaging recycling targets that reshape material selection toward mono-material constructions compatible with mechanical recycling streams. India's BIS mandates food-contact compliance testing that filters out uncertified imports and elevates domestic converter capabilities. China's SAMR oversees national standards for biodegradable films that redirect R&D spending among regional producers. Stakeholders must track how extended producer responsibility frameworks evolve across these jurisdictions to align capital allocation with compliance-bound demand.
Market Dynamics
Asia Pacific plastic packaging film converters face mounting pressure to reconfigure extrusion lines for mono-material compatibility as Japan's METI recycling mandates and India's BIS food-contact certification reshape specification requirements across the regional supply base.
Growth Catalysts
- Multilayer barrier film adoption:Southeast Asian food and beverage producers are expanding specification of ethylene-vinyl alcohol and polyamide coextrusions to extend shelf life of processed proteins and ready meals for export markets.
- India's BIS certification filter:Mandatory food-contact compliance testing under Bureau of Indian Standards regulations is elevating domestic converter capabilities while screening uncertified import volumes.
- Export zone concentration:Vietnam's processing zones anchored near Ho Chi Minh City and Hai Phong are drawing Japanese and Korean brand owner procurement for regional flexible packaging distribution.
Market Restraints
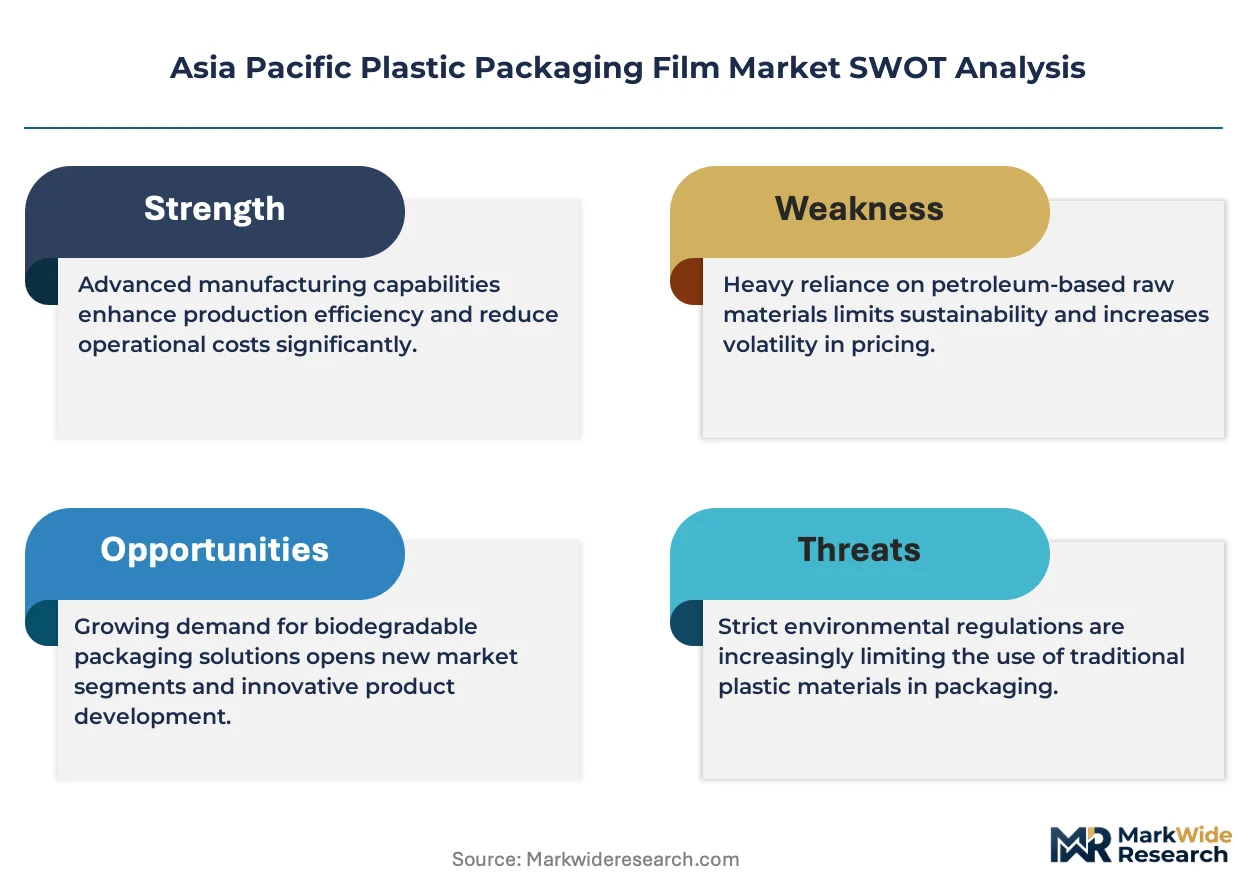
- Resin cost volatility:Polypropylene and polyethylene feedstock prices track naphtha and ethylene cracker margins, compressing film converter margins during upstream petrochemical cycle peaks.
- Metallization supply concentration:Vacuum metallization capacity for high-barrier applications clusters among Korean and Japanese equipment owners, creating bottle-neck risk for regional converters without captive metallization.
- Mechanical recycling incompatibility:Legacy multi-material laminates containing PET, aluminum, and polyethylene layers face rejection by Japan's container recycling streams, stranding existing film inventories.
Strategic Opportunities
- Philippines packaging underpenetration:Domestic food processing expansion in Luzon and Visayas regions offers first-mover positioning for certified film suppliers ahead of formal extended producer responsibility implementation.
- Biodegradable film R&D redirection:China's SAMR national standards for biodegradable substrates are redirecting capital toward polylactic acid and polyhydroxyalkanoate film trials among regional resin compounders.
- Pharmaceutical barrier specialization:Blister pack and cold-form foil applications in India's CDSCO-regulated drug packaging are absorbing higher-margin PVDC-coated and Aclar-laminated film grades.
Industry Challenges
- Mono-material line reconfiguration:Converters must retool coextrusion dies and sealing layer formulations to eliminate incompatible polymers without sacrificing oxygen barrier performance below 0.5 cc/m²/day.
- BIS certification timeline compression:Indian food-contact testing protocols require 12-16 week laboratory cycles, delaying new product qualification for export-oriented brand owners with seasonal launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Plastic Packaging Film Market |
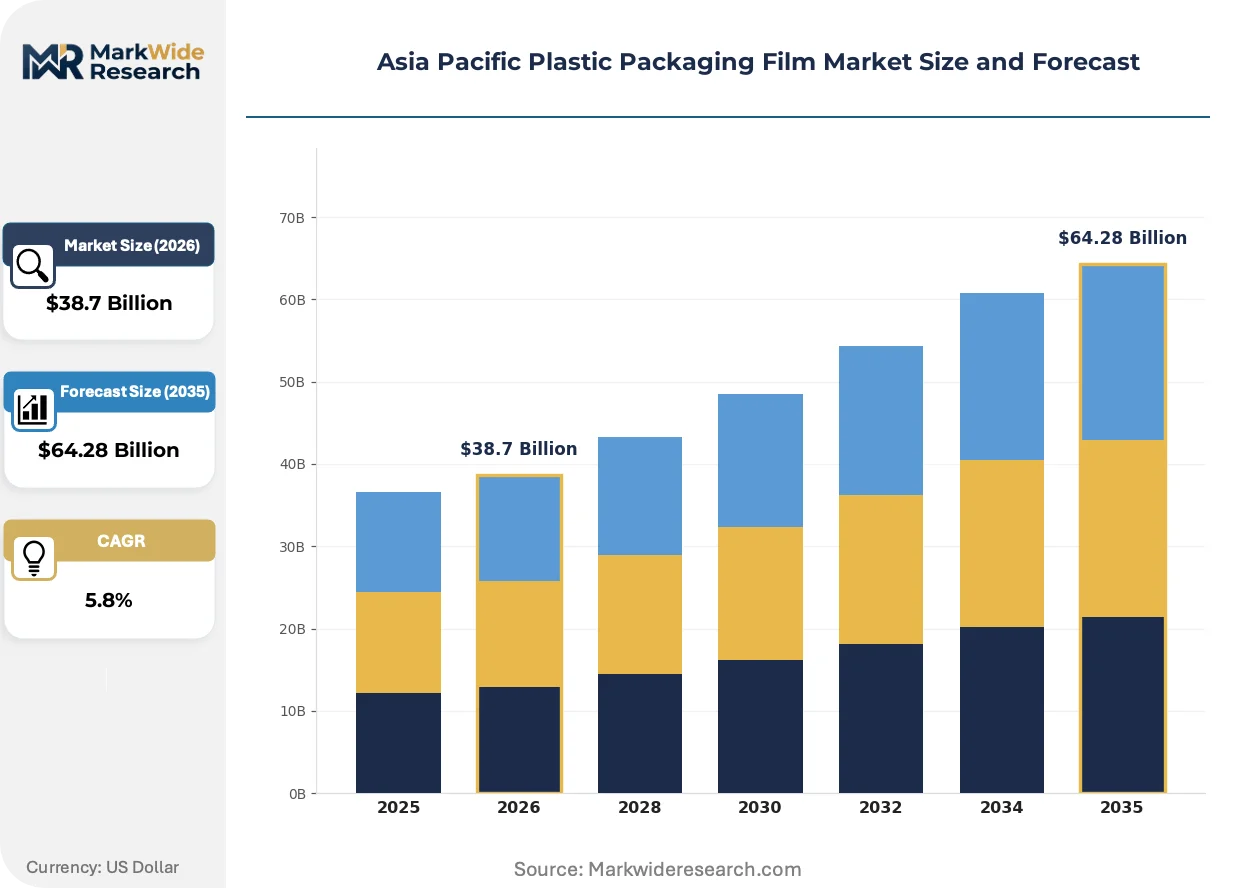
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $64.28 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stretch Film, Shrink Film, Barrier Film, BOPP Film End Use Industry: Food & Beverage, Healthcare, Electronics, Personal Care Form: Rolls, Bags, Pouches, Sheets Thickness: Thin, Medium, Thick, Ultra-Thin |
| Companies Covered | Toray Advanced Film Co. Ltd, UFlex Limited, Cosmo Films Limited, Toppan Packaging Service Co., Ltd., Kingchuan Packaging, SCG Packaging, Berry Global Inc., Amcor Plc, Huhtamaki India Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Plastic Packaging Film Market Trends and Innovations
Asia Pacific plastic packaging film is absorbing three concurrent pressures: regulatory specification tightening, substrate simplification for recyclability, and end-user procurement consolidation toward integrated film-to-package suppliers.
Mono-material polyethylene and polypropylene barrier structures are absorbing technical development resources previously allocated to complex multi-polymer laminates. Japanese snack food manufacturers and Australian fresh produce exporters are piloting these substrates at commercial scale. The technology is absorbing oxygen scavenger and mineral coating innovations that compensate for lost barrier performance from eliminated aluminum and EVOH layers.
China's SAMR biodegradable film standards and Japan's METI container recycling targets are forcing parallel compliance investments across the regional supply base. Converters serving dual export and domestic markets must maintain separate inventory positions certified to each jurisdiction's mechanical recycling or composting streams. Korean food brands with pan-Asian distribution networks are most exposed, consolidating supplier audits to reduce qualification burden.
Brand owner technical procurement teams are consolidating specification authority away from regional purchasing offices toward centralized packaging engineering functions in Singapore and Shanghai. Japanese and Korean multinational food companies are compressing approved supplier lists from twenty-plus converters to five or six with integrated metallization, printing, and pouch-making capabilities. Vietnam's export processing zones display this concentration most visibly, where Japanese brand owners now source complete flexible packaging solutions rather than commodity film rolls.
Asia Pacific Plastic Packaging Film Market Segmentation
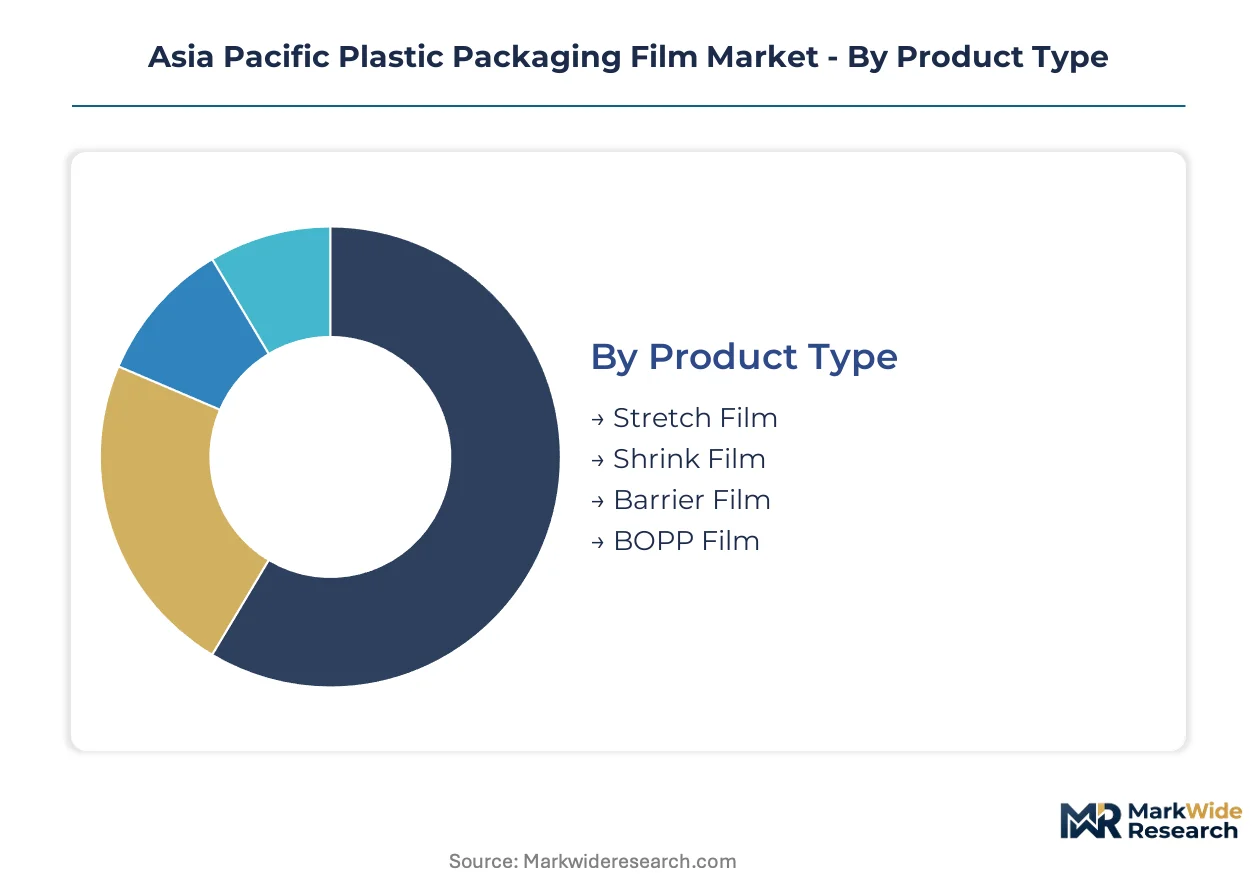
Asia Pacific plastic packaging film segments diverge sharply by technical specification and regulatory compliance burden. Film converters configure extrusion assets around thickness tolerances and barrier performance tiers that align with end-use certification requirements across Japan's METI recycling streams and India's BIS food-contact mandates.
Product Type:
Technology and specification axes determine converter capital allocation and margin capture.
- Barrier Film:Multilayer coextrusions incorporating EVOH or polyamide layers achieve oxygen transmission below 0.5 cc/m²/day. Japanese and Korean brand owners in Vietnam's export processing zones specify these grades for processed protein shelf-life extension.
- BOPP Film:Biaxially oriented polypropylene delivers cost-competitive clarity and printability at 12-40 micron gauges. Mature demand concentrates in snack and confectionery wrapping across Southeast Asian markets where metallization upgrades barrier for premium applications.
- Stretch Film:Linear low-density polyethylene formulations dominate logistics palletization volume in the region's manufacturing hubs.
- Shrink Film:Cross-linked polyethylene and polyolefin grades serve unitization and retail display functions.
Mature deployment sits with BOPP film. Newer deployment is concentrated in barrier film.
End Use Industry:
Application-driven specification tiers separate commodity volume from certified premium grades.
- Food & Beverage:Processed proteins, ready meals, and snack categories drive multilayer barrier adoption. Southeast Asian export-oriented processors specify EVOH coextrusions to meet Japanese distribution shelf-life requirements.
- Healthcare:Pharmaceutical blister packs and cold-form foil applications absorb PVDC-coated and Aclar-laminated grades regulated under India's CDSCO and Japan's PMDA.
- Electronics:Anti-static and moisture-barrier films protect semiconductor and component shipments from humidity damage in regional distribution.
- Personal Care:Mono-material polyethylene structures are gaining specification for compatibility with Japan's mechanical recycling streams.
Volume concentration rests with food and beverage. Steepest expansion trajectory appears in healthcare barrier specialization.
Form:
Supply chain position determines whether converters sell commodity rolls or capture downstream value in finished formats.
- Rolls:Unconverted film stock serves converters with in-house printing and pouch-making, common among integrated suppliers serving Japanese brand owners.
- Pouches:Pre-formed flexible packaging commands premium positioning when certified to India's BIS food-contact protocols and Japan's container recycling targets.
- Bags:Standard formats for retail and industrial containment across high-volume applications.
- Sheets:Cut-to-size substrates for thermoforming and custom fabrication.
Margin capture favors pouches. Volume throughput concentrates in rolls.
Thickness:
Gauge specification directly maps to resin consumption, barrier performance, and equipment compatibility.
- Ultra-Thin:Below 12 micron substrates reduce material intensity for cost-sensitive applications while requiring precision extrusion control.
- Thin:12-25 micron range balances clarity and handling in snack wrapping and label applications.
- Medium:25-50 micron gauges serve general-purpose barrier and protection functions across food and industrial segments.
- Thick:Above 100 micron films absorb structural loads in heavy-duty logistics and industrial containment.
Technology investment flows toward ultra-thin capability. Revenue concentration remains with medium gauges.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Naphtha-fed petrochemical complexes along Asia Pacific's eastern seaboard anchor regional film substrate supply. Japanese and Korean resin producers feed extrusion lines across Vietnam's export processing zones and India's western industrial corridors.
China
Domestic snack food manufacturers and cross-border e-commerce fulfillment centers drive multilayer film consumption. SAMR biodegradable film standards redirect compounding R&D toward polylactic acid substrates. Yangtze River Delta converters near Shanghai pilot mono-material barrier structures for Japanese brand owner export orders.
India
Processed food exporters and pharmaceutical blister pack manufacturers absorb certified barrier film volumes. BIS food-contact testing mandates filter import supply while elevating domestic converter technical capabilities. Gujarat's petrochemical belt and Maharashtra's Thane-Bhiwandi corridor concentrate extrusion and metallization assets.
Japan
Snack food producers and fresh produce exporters pilot mono-material polyethylene barrier films for mechanical recycling compatibility. METI container recycling targets reshape specification authority toward centralized packaging engineering functions. Kanto region converters around Tokyo supply integrated film-to-pouch solutions for pan-Asian distribution networks.
Vietnam
Japanese and Korean brand owners source flexible packaging from export-oriented processing zones for regional Southeast Asian distribution. BIS-equivalent food safety protocols apply to re-export shipments bound for India. Ho Chi Minh City and Hai Phong industrial zones concentrate Japanese-invested film converting and pouch-making operations.
South Korea
Pan-Asian food brands consolidate supplier audits to reduce qualification burden across multiple jurisdiction compliance requirements. MFDS pharmaceutical packaging regulations elevate barrier film specification for regional drug distribution. Busan-Ulsan corridor petrochemical complexes supply resin to captive film extrusion serving Japanese and Vietnamese converter demand.
Asia Pacific Plastic Packaging Film Market Competitive Landscape
Capacity expansion dominates the current landscape as converters add metallization and pouch-making lines to capture downstream margin. The supply base stratifies between integrated multinational suppliers with film-to-package networks and regional specialists focused on substrate grades. Three archetypes occupy distinct positions: resin-integrated compounders with captive extrusion, equipment-heavy metallizers serving barrier applications, and brand-owner-aligned converters with centralized qualification. M&A activity and geographic expansion toward Vietnam's processing zones represent the dominant competitive vectors reshaping market structure.
Among India-based integrated suppliers, UFlex Limited and Cosmo Films Limited exemplify the resin-backward archetype with captive compounding capabilities. Toray Advanced Film Co. Ltd represents Japanese equipment-heavy positioning in high-barrier substrate development. Amcor Plc anchors the multinational integrated tier with film-to-package network coverage across Southeast Asian export zones. These three occupy positions that illustrate how scale, vertical control, and geographic alignment separate competitive tiers in regional procurement consolidation.
| Leading Market Players |
|---|
| Toray Advanced Film Co. Ltd |
| UFlex Limited |
| Cosmo Films Limited |
| Toppan Packaging Service Co., Ltd. |
| Kingchuan Packaging |
| SCG Packaging |
| Berry Global Inc. |
| Amcor Plc |
| Huhtamaki India Ltd. |
| Others |
Pricing and Supply Chain Analysis
Japanese and Korean brand owners sourcing from Vietnam's export processing zones concentrate procurement authority among five to six integrated suppliers, compressing contract negotiations toward long-term offtake agreements with metallization and pouch-making bundled into unit pricing. This buyer consolidation shifts pricing power toward converters with captive resin compounding and in-house barrier coating capabilities.
Pricing Analysis
Service bundling separates certified film converters from commodity roll suppliers, with BIS food-contact testing and METI recycling compliance documentation included in premium tier contracts while standard grades trade unbundled. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and barrier performance specifications. Cost compression in standard BOPP film is intensifying because Thai and Malaysian converters are adding metallization capacity. Export-oriented brand owners in Vietnam's processing zones show least price sensitivity for EVOH coextrusion grades, while domestic Indian snack manufacturers drive hard volume discounts on unconverted roll stock.
Supply Chain Analysis
Dual-sourcing mandates from Japanese brand owners require qualified backup suppliers for each film grade, forcing converters to maintain redundant metallization lines and BIS-certified inventory positions. Resin supply draws from naphtha-fed petrochemical complexes in South Korea, Japan, and Thailand's Eastern Economic Corridor. Raw material dependencies center on polypropylene homopolymer, ethylene-vinyl alcohol copolymer, and vacuum-deposited aluminum metallization. Single-source vulnerability concentrates in Korean and Japanese vacuum metallization equipment owners. Distribution runs through converter-direct relationships with brand owner packaging engineering functions in Singapore and Shanghai, bypassing traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's BIS certification timeline functions as a cost-of-compliance moat, filtering out uncertified imports and elevating domestic converter margins for food-contact grades. METI's mechanical recycling targets in Japan create parallel compliance barriers for mono-material qualification.
For Market Incumbents: Cement barrier film specialization through captive metallization expansion in Vietnam's processing zones, where Japanese brand owners are consolidating supplier lists. Acquire BIS-certified Indian converters ahead of formal extended producer responsibility implementation. Mono-material line reconfiguration costs threaten legacy multi-layer laminate inventories. For New Entrants and Emerging Players: Biodegradable film pilot production under China's SAMR standards offers technology-first wedge positioning before national mandates harden. Target Philippine domestic food processing in Luzon ahead of EPR formalization. Pursue toll-compounding arrangements with established resin suppliers to bypass capital-intensive extrusion asset requirements. For Investors and Strategic Acquirers: The window for entry favors equipment-heavy metallizers with vacuum deposition capabilities serving pharmaceutical barrier applications. Five-to-ten year viability hinges on regulatory compliance infrastructure rather than commodity scale. Watch India's CDSCO enforcement intensity on pharmaceutical packaging as inflection signal for PVDC-coated film demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive polypropylene supply buffers margin compression during naphtha cycle peaks for Indian converters. |
| Metallization Capacity Expansion | Vacuum deposition assets in Vietnam's processing zones secure long-term contracts with Korean brand owners. |
| Mono-Material Line Reconfiguration | Polyethylene barrier structures compatible with Japan's METI recycling streams command specification premiums. |
| BIS Certification Investment | Food-contact testing capabilities filter import competition and elevate domestic converter positioning in India. |
| Pharmaceutical Barrier Specialization | PVDC-coated grades under India's CDSCO regulations absorb higher-margin demand from blister pack manufacturers. |
Research Methodology
Independent corroboration across extrusion plant managers, procurement leads at Japanese brand owners, metallization equipment operators, and BIS laboratory directors underwrites the qualitative findings. Primary fieldwork combined structured interviews with secondary validation from customs trade data, BIS certification registries, METI container recycling reports, and SAMR biodegradable standards documentation. Bottom-up capacity assessments across Vietnam's processing zones triangulate against top-down demand estimates from food and pharmaceutical end-use segments.
Comparable-period anchoring to historical resin price cycles and certification timeline data establishes the forecast baseline across the analysis window. Segmentation dimensions modeled include barrier performance tier, end-use industry vertical, form factor, and thickness gauge. CAGRs derive from elasticity-adjusted volume projections tied to export processing zone expansion and regulatory compliance phase-in schedules. Industry-specific inputs incorporate naphtha-to-polypropylene spread assumptions and BIS testing queue duration estimates.
Several conditions sit outside the modeled scope, including sudden resin feedstock disruptions, accelerated biodegradable mandate timelines, and trade policy shifts affecting Vietnam's re-export tariff status. Forecasts reflect assumptions about regulatory enforcement continuity and brand owner consolidation pace. Deviation in Japan's METI recycling target stringency or India's BIS laboratory capacity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Polyvinyl Alcohol (PVA) Films Market
Poly film
United Kingdom Plastic Packaging Films Market
Poly film
Biaxially Oriented Polyamide (BOPA) Films Market
Poly film
Laminated Packaging Films Market
Poly film
Global Specialty Films Polymer Market
Poly film
Tube Laminating Films Market
Poly film
Polyethylene Terephthalate (PET) Shrink Films Market
Poly film
France Plastic Packaging Films Market
Poly film
Indonesia Plastic Packaging Films Market
Poly film
China BOPP Film Market
Poly film
Polysaccharide Films Market
Poly film
Global Reclosable Films Market
Poly film
High Density Polyethylene Film Market
Poly film
Thermoforming Films Market
Poly film
Nigeria Plastic Packaging Films Market
Poly film
China Plastic Packaging Film Market