
 Poly Tubing Market | 2026-2036
Poly Tubing Market Size, Share, and Industry Trends Forecast 2026-2036
Poly Tubing Market Analytics
Aftermarket service revenue for tubing system refurbishment and field jointing is narrowing as original equipment manufacturers push captive consumables strategies. Berry Global leverages vertical integration from resin compounding to finished coil production across North American agriculture channels. Saint-Gobain sustains technology leadership in fluoropolymer-lined medical tubing through specialized extrusion capabilities. Zeus Industrial Products differentiates via precision small-diameter PTFE and FEP products serving catheter and endoscope OEMs.
Poly tubing denotes extruded thermoplastic conduits manufactured through single-screw or twin-screw extrusion with wall thicknesses typically ranging from 0.010 to 0.500 inches, engineered for fluid transport, pneumatic conveyance, or protective sleeving across industrial and commercial systems. Flexible tubing dominates volume consumption in irrigation and fluid-handling applications where bend radius and coilability reduce installation labor. Medical tubing commands premium positioning due to USP Class VI and ISO 10993 biocompatibility requirements that constrain supplier pools. Food-grade tubing faces accelerating specification intensity as processors migrate from PVC to LDPE and LLDPE formulations to satisfy evolving migration limits.
The US FDA enforces food-contact notification requirements under 21 CFR that directly shape resin selection and additive packages for tubing entering food processing equipment. The EPA regulates stormwater and agricultural runoff containment systems that specify polyethylene liner and tubing performance standards. REACH restrictions on phthalate plasticizers in European import markets are forcing compound reformulation across PVC-dominant product lines. Stakeholders must monitor regulatory divergence between FDA, EPA, and ECHA frameworks when configuring multi-territory product portfolios and certification investments.
Market Dynamics
Precision agriculture adoption is compressing tubing specifications toward thinner-walled, higher-pressure-rated products that reduce water waste while demanding tighter extrusion tolerances from compounders.
Growth Catalysts
- Drip-line irrigation mandates:Water-stressed agricultural regions in California, Spain, and Israel now require subsurface drip systems for new orchard installations. Tubing manufacturers serving these markets report sustained order visibility from state-level conservation programs.
- FDA 21 CFR food-contact compliance:Processors replacing PVC with LDPE and LLDPE formulations for fluid handling create specification windows for tubing producers with validated additive packages and migration testing documentation.
- Fluoropolymer extrusion advances:Medical device OEMs in Massachusetts and Minnesota are qualifying FEP-lined catheter shafts for interventional cardiology, opening premium product tiers beyond commodity irrigation tubing.
Market Restraints
- Ethylene feedstock volatility:North American and Middle Eastern resin producers pass through naphtha and ethane price swings with minimal lag, compressing converter margins on fixed-price agricultural contracts.
- REACH phthalate restrictions:ECHA classifications on DEHP and DINP migration limits force PVC-dominant medical tubing lines into compound reformulation or material substitution, extending requalification timelines by 12-18 months.
- Fluoropolymer supply concentration:PTFE and FEP resin production concentrates among three global chemical conglomerates, creating allocation risk for precision medical tubing specialists during semiconductor industry demand spikes.
Strategic Opportunities
- India agricultural mechanization:Punjab and Haryana state governments subsidize drip irrigation infrastructure for rice-wheat rotation systems, creating import substitution potential for domestic extrusion capacity expansion.
- EU Green Deal circularity mandates:Packaging and processing equipment OEMs in Germany and the Netherlands now specify post-industrial recycled content thresholds, rewarding tubing producers with closed-loop regrind capabilities.
- Telemedicine device proliferation:Remote patient monitoring systems require disposable pneumatic tubing for blood pressure cuffs and spirometry, opening volume channels outside traditional hospital supply chains.
Industry Challenges
- Medical tubing cleanroom certification:ISO 14644 Class 7 and Class 8 facility qualification demands capital deployment for HVAC and particulate monitoring systems that commodity irrigation producers rarely maintain.
- Multi-territory regulatory divergence:Tubing producers serving both FDA-regulated US food processing and ECHA-regulated EU export markets must maintain parallel additive registries and migration testing protocols, fragmenting quality management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Poly Tubing Market |
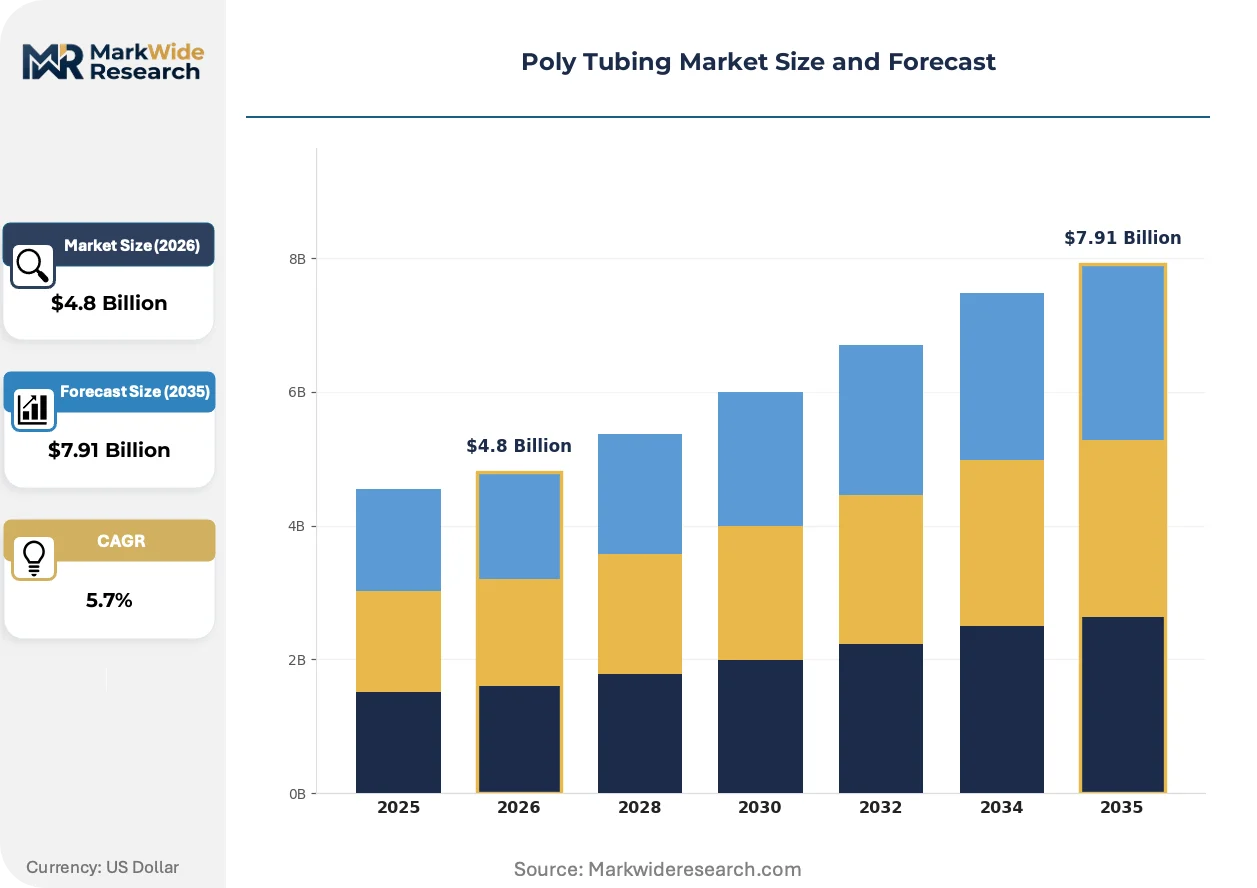
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Tubing, Rigid Tubing, Food-Grade Tubing, Medical Tubing End Use: Agriculture, Food Processing, Healthcare, Industrial Material: LDPE, HDPE, LLDPE, PVC Diameter: Small Diameter, Medium Diameter, Large Diameter, Custom Size |
| Companies Covered | United States Plastic Corp, Atlantic Poly Inc, Euthenia Manufacturing Group, Acme Plastics, Boedeker Plastics, Berry Global, Nelson Global Products, Saint-Gobain, Zeus Industrial Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Poly Tubing Market Evolving Landscape
Material science advances and regulatory specification intensity are converging to differentiate tubing portfolios by performance tier rather than commodity resin grade alone.
Co-extruded barrier-layer tubing is migrating from pharmaceutical packaging into sensitive agricultural chemigation applications where fertilizer and pesticide permeation degrades standard polyethylene. Israeli and Australian irrigation OEMs now specify ethylene vinyl alcohol (EVOH) intermediate layers for subsurface drip lines in high-salinity soils. This migration from packaging to field deployment is compressing the supplier base toward compounders with multi-layer die head capabilities and adhesive tie-layer formulation expertise.
REACH restrictions on intentionally added microplastics are forcing irrigation tubing producers to reformulate UV stabilizer packages away from conventional benzophenone and hindered amine light stabilizer chemistries. The industrial consequence is accelerated qualification of polymer-bound stabilizer systems that resist leaching into soil and groundwater. Spanish and Italian agricultural tubing exporters face the most immediate compliance pressure as ECHA enforcement concentrates on Mediterranean basin installations with documented soil contamination risk.
Original equipment manufacturers in the United States are consolidating tubing procurement through direct extruder relationships that bypass traditional distribution channels serving the maintenance-repair-operations segment. John Deere and Lindsay Corporation now specify captive-supplier programs for center-pivot and lateral-move irrigation systems, displacing independent distributors that previously stocked generic replacement coil inventory. This consolidation is most visible in Nebraska and Kansas, where dealership networks have reduced SKU breadth by 40% in favor of OEM-branded consumables with guaranteed interchangeability.
Poly Tubing Market Segmentation
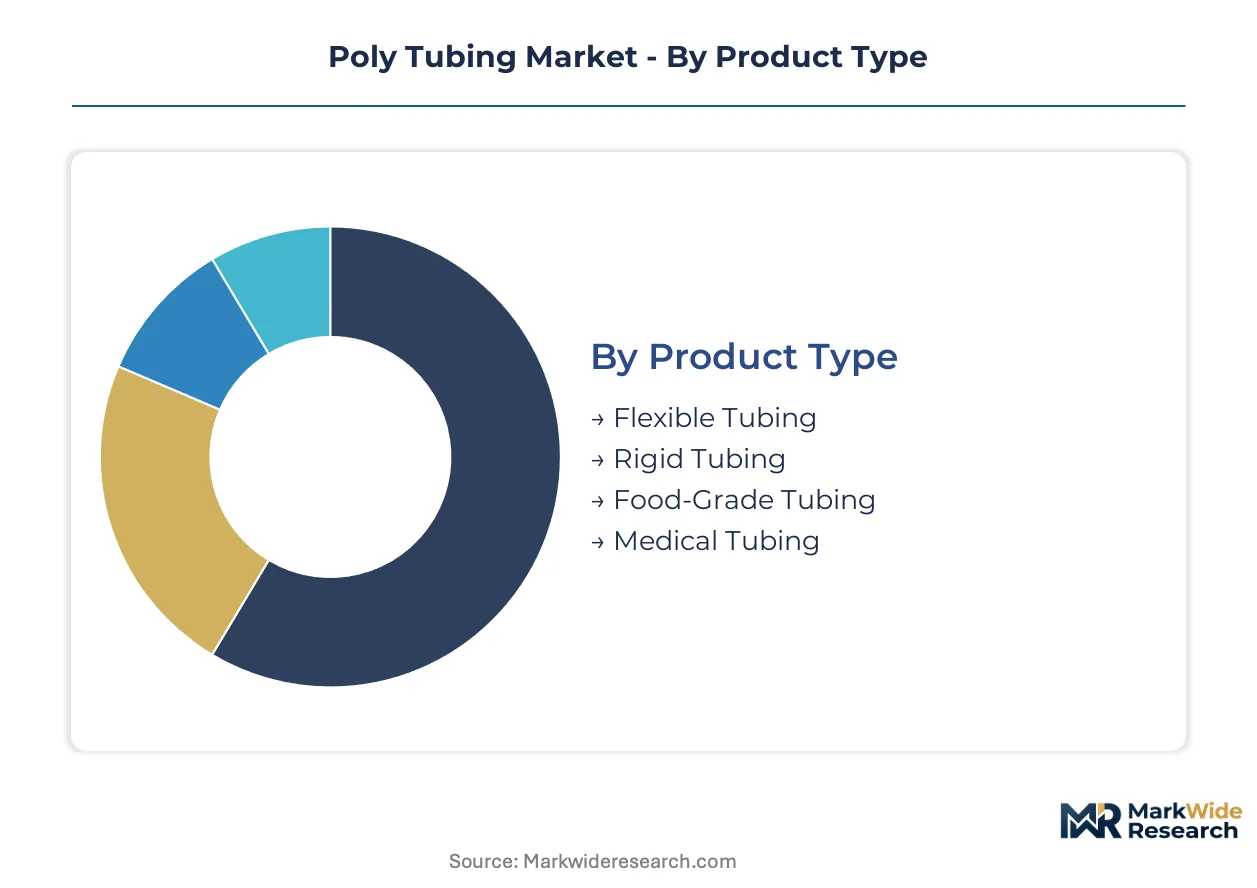
Poly tubing segmentation reflects divergent technical requirements across irrigation infrastructure, medical devices, and food-contact systems. Specification intensity varies dramatically by end-use, with medical and food-grade segments demanding validated additive packages while agricultural volumes prioritize cost-optimized extrusion.
Product Type:
Cost tier differentiation separates commodity irrigation products from premium medical and food-contact formulations with specialized certification requirements.
- Flexible Tubing:Extruded LDPE and LLDPE formulations with wall thicknesses of 0.010 to 0.250 inches enable coilability and tight bend radii for drip-line irrigation. California's Central Valley growers specify thin-walled flexible products for subsurface installations under state water conservation mandates.
- Medical Tubing:USP Class VI and ISO 10993 biocompatibility requirements constrain supplier pools to compounders with validated cleanroom extrusion. Minnesota and Massachusetts catheter OEMs drive qualification demand for fluoropolymer-lined configurations in interventional cardiology.
- Food-Grade Tubing:FDA 21 CFR compliant LDPE and LLDPE formulations replace legacy PVC in fluid handling equipment.
- Rigid Tubing:HDPE and PVC structural profiles serve protective conduit and industrial pneumatic applications.
Flexible tubing holds installed capacity. Medical tubing is rotating up the share rankings.
End Use:
Application requirements dictate material selection, with agricultural volumes dominating unit consumption while healthcare commands premium pricing.
- Agriculture:Drip-line and center-pivot systems consume polyethylene tubing in high volumes across water-stressed growing regions. Israeli and Spanish regulators now mandate subsurface drip installations for new orchard permits, locking in replacement demand cycles.
- Healthcare:Catheter shafts, endoscope channels, and pneumatic delivery systems require precision small-diameter extrusion with documented biocompatibility. FEP-lined configurations from specialized compounders serve Massachusetts-based interventional device OEMs.
- Food Processing:Fluid transfer and CIP (clean-in-place) systems specify migration-tested formulations under FDA and EU REACH frameworks.
- Industrial:Pneumatic conveyance and protective sleeving applications tolerate broader specification tolerances than regulated end-uses.
Agriculture holds installed capacity. Healthcare is rotating up the share rankings.
Material:
Volume concentration and margin structure vary by resin chemistry, with polyethylene grades dominating agricultural applications and PVC facing regulatory substitution pressure.
- LDPE:Low-density formulations provide flexibility and clarity for food-contact and medical applications where FDA 21 CFR compliance is mandatory. Processors migrating from PVC specify LDPE for fluid handling equipment in US and EU export markets.
- LLDPE:Linear low-density grades deliver puncture resistance and tensile strength for agricultural drip-lines in abrasive soil conditions. Israeli irrigation OEMs specify LLDPE for subsurface chemigation systems with EVOH barrier layers.
- HDPE:High-density grades serve rigid conduit and industrial applications requiring structural integrity.
- PVC:Phthalate plasticizer formulations face REACH restrictions and FDA scrutiny, forcing compound reformulation or material substitution.
LDPE holds installed capacity. LLDPE is rotating up the share rankings.
Diameter:
Customer type and specification intensity correlate directly with diameter class, with small-diameter medical products commanding the highest unit economics.
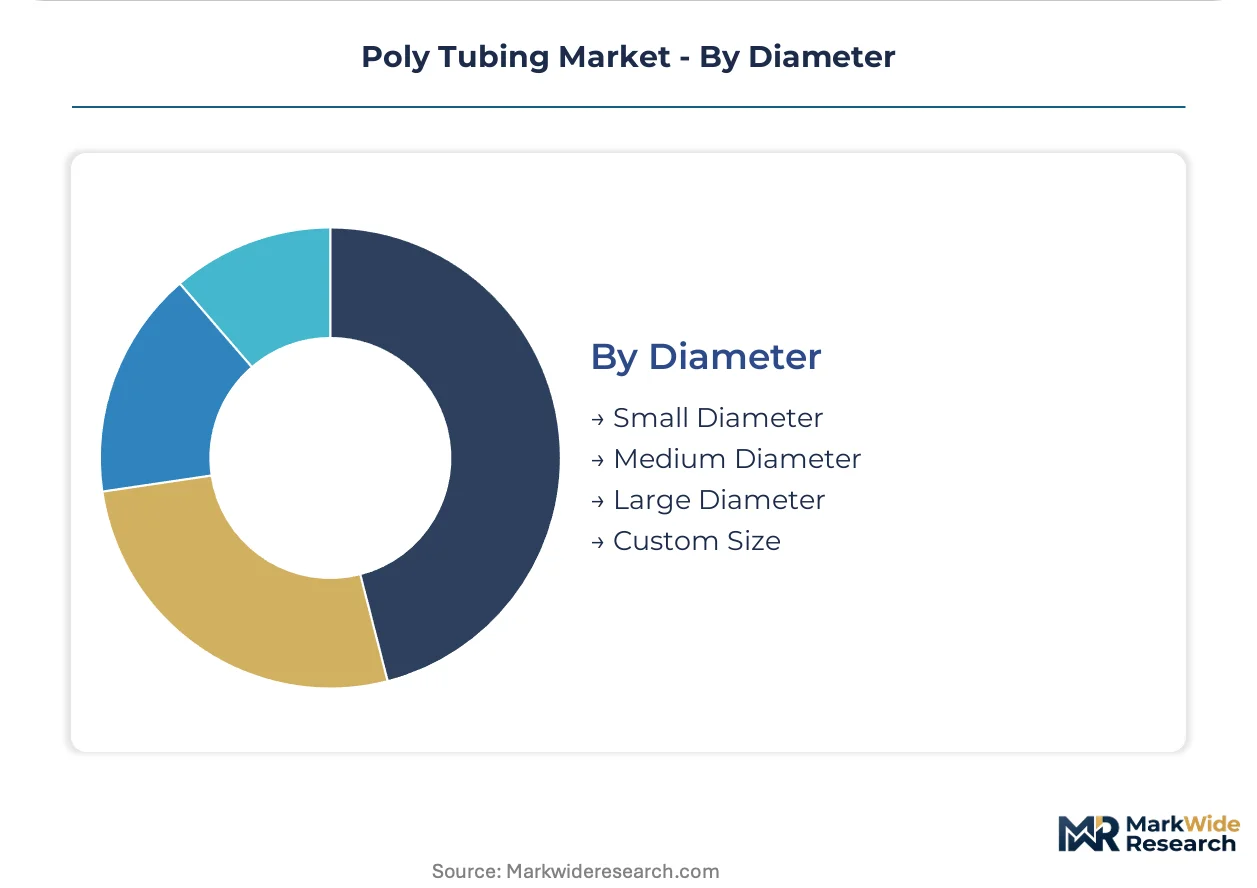
- Small Diameter:Precision extrusion below 0.125 inches serves catheter and endoscope OEMs with tight tolerance requirements. PTFE and FEP configurations from specialized compounders in Minnesota and Massachusetts qualify for interventional cardiology applications.
- Medium Diameter:Standard agricultural drip-line and food-processing fluid handling dimensions balance extrusion throughput with performance requirements.
- Large Diameter:Center-pivot and lateral-move irrigation systems specify thicker walls for structural load bearing.
- Custom Size:Application-specific tooling investments serve OEM captive programs with guaranteed volume commitments.
Medium diameter holds installed capacity. Small diameter is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Agricultural irrigation dominates tubing consumption in water-stressed growing regions, while medical-grade specifications concentrate in established device manufacturing clusters with validated cleanroom infrastructure.
United States
California's Central Valley growers deploy subsurface drip systems under state water conservation mandates, while Minnesota and Massachusetts host catheter OEMs qualifying fluoropolymer-lined configurations. The EPA regulates stormwater containment systems specifying polyethylene liner performance. Nebraska and Kansas dealership networks have reduced generic replacement SKU breadth by 40% in favor of OEM-branded consumables.
China
Domestic extrusion capacity serves agricultural mechanization programs across the Yangtze River Delta, with NMPA-regulated medical tubing production clustering in coastal manufacturing zones. The country's national pharmaceutical regulator enforces biocompatibility documentation parallel to ISO 10993 frameworks. Shandong Peninsula compounders supply LLDPE formulations for abrasive soil conditions in northwestern growing regions.
Germany
Packaging and processing equipment OEMs in Bavaria and Baden-Württemberg specify post-industrial recycled content thresholds under EU Green Deal circularity mandates. ECHA REACH restrictions on phthalate plasticizers force PVC-dominant medical tubing lines into compound reformulation. The Eindhoven Region across the Dutch border supplies multi-layer die head capabilities for EVOH barrier-layer agricultural products.
Israel
State-level drip irrigation mandates for new orchard permits lock in replacement demand cycles for subsurface chemigation systems. National water authority regulations require documented soil contamination risk mitigation in Mediterranean basin installations. Tel Aviv-area irrigation OEMs specify polymer-bound UV stabilizer packages resisting leaching into groundwater.
India
Punjab and Haryana state governments subsidize drip infrastructure for rice-wheat rotation systems, creating import substitution potential for domestic extrusion capacity. The Bureau of Indian Standards oversees material specifications for agricultural applications. Gujarat-based compounders are expanding LLDPE production to serve western state irrigation networks.
Poly Tubing Market Competitive Landscape
Capability concentration sits with specialized fluoropolymer extruders serving medical device OEMs; scale advantage sits with agricultural converters operating captive resin compounding through finished coil production. The vendor base separates into three strategic archetypes: vertically integrated resin-to-tubing producers, precision medical specialists with cleanroom certification, and regional extruders serving maintenance-repair-operations channels. Dominant competitive moves include backward integration into resin compounding and qualification of multi-layer barrier constructions for chemigation applications.
Among North American fabricators, Berry Global exemplifies the vertically integrated archetype with in-house production from resin compounding through agricultural channel distribution. Saint-Gobain occupies a position representing specialized fluoropolymer-lined medical tubing capabilities. Zeus Industrial Products anchors the precision small-diameter segment serving interventional device manufacturers in established New England and Upper Midwest clusters.
| Leading Market Players |
|---|
| United States Plastic Corp |
| Atlantic Poly Inc |
| Euthenia Manufacturing Group |
| Acme Plastics |
| Boedeker Plastics |
| Berry Global |
| Nelson Global Products |
| Saint-Gobain |
| Zeus Industrial Products |
| Others |
Value Network & Pricing Analysis
The Port of Houston resin corridor feeds North American poly tubing converters with polyethylene feedstock, its freight cost volatility amplifying margin pressure for agricultural-grade producers while enabling price differentiation for medical-certified compounders with captive logistics arrangements.
Pricing Analysis
Long-term offtake contracts dominate agricultural tubing procurement, with California irrigation OEMs locking in twelve-month resin-plus-conversion pricing to hedge ethylene feedstock swings. Medical tubing commands premium-mid-economy pricing differentiation driven by ISO 14644 cleanroom certification tier and USP Class VI validation documentation. Cost compression in commodity irrigation grades is intensifying because fixed-price contract exposure prevents margin pass-through during ethane price spikes. Agricultural distributors exhibit highest price sensitivity, while interventional cardiology OEMs in Massachusetts prioritize supply assurance over unit cost.
Supply Chain Analysis
Contract manufacturing concentration for precision medical tubing sits with specialized extruders in Minnesota and Massachusetts maintaining ISO 13485 quality systems. Geographic supply concentration centers on the United States, China, and Germany as these countries host the largest resin compounding and finished coil production bases. Raw material dependencies draw from Saudi ethane-based polyethylene, Korean fluoropolymer resin, and domestic LLDPE from Gulf Coast crackers. Single-source vulnerability concentrates in PTFE and FEP resin supply among three global chemical conglomerates. Distribution runs through OEM captive-supplier programs that displace independent agricultural distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is entering cyclical recovery as agricultural capital expenditure resumes following two seasons of drought-induced inventory destocking across California and Israeli growing regions.
For Market Incumbents: Build regulatory certification moats by securing parallel FDA 21 CFR and ECHA REACH additive registries before EU microplastic restrictions tighten. Berry Global's backward integration into resin compounding demonstrates the margin defense achievable through upstream control. Saint-Gobain's fluoropolymer extrusion specialization illustrates how cleanroom infrastructure investments create switching costs against commodity converters. Priority lever: multi-layer barrier technology for chemigation applications. For New Entrants and Emerging Players: Mid-tier agricultural tubing for Indian state subsidy programs represents the most penetrable entry point given import substitution mandates in Punjab and Haryana. Gujarat-based LLDPE compounders expanding domestic capacity illustrate viable localization strategy. Telemedicine disposable pneumatic tubing for remote patient monitoring opens volume channels outside hospital GPO capture. Go-to-market angle: direct extruder relationships with irrigation OEMs bypassing traditional distribution. For Investors and Strategic Acquirers: Precision small-diameter fluoropolymer extruders with validated catheter OEM qualifications offer the strongest acquisition target archetype given supply scarcity and premium pricing power. Long-term viability over a five-to-ten year window hinges on medical device outsourcing trends and interventional procedure volume recovery. Signal to watch: qualification timelines for FEP-lined configurations at Massachusetts-based interventional cardiology OEMs.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive polyethylene supply from Gulf Coast crackers insulates margin compression during ethane price volatility. |
| Multi-Layer Barrier Layer Qualification | EVOH intermediate layers for Israeli chemigation systems command premium positioning over commodity drip-line. |
| ISO 14644 Cleanroom Certification | Class 7 facility qualification opens catheter shaft supply to Minnesota and Massachusetts device OEMs. |
| Post-Industrial Recycled Content Integration | Closed-loop regrind capabilities satisfy EU Green Deal thresholds for German packaging equipment OEMs. |
| Polymer-Bound UV Stabilizer Reformulation | Leach-resistant packages address ECHA microplastic restrictions for Spanish and Italian agricultural exporters. |
Research Methodology
A spread of perspectives from agricultural irrigation OEM procurement managers, medical device quality assurance directors, resin compounding technical leads, and food processing equipment engineers converged on the working assumptions. Primary field engagement combined with secondary validation from FDA food-contact notification databases, ECHA REACH restriction dossiers, SEC 10-K resin producer filings, and customs trade data for polyethylene tubing classifications. Bottom-up unit economics from extrusion throughput models and top-down demand aggregation from state-level irrigation subsidy programs were triangulated.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning product type flexibility grades, material chemistry tiers, end-use application intensity, and regional regulatory clusters. CAGRs were derived from installed base replacement cycles, agricultural mechanization penetration curves, and medical device outsourcing trends. Industry-specific forecast inputs incorporated California subsurface drip mandate compliance timelines and fluoropolymer resin allocation patterns during semiconductor demand spikes.
Practitioners should monitor ethylene feedstock price volatility, ECHA enforcement intensity on Mediterranean basin installations, and catheter OEM qualification pipeline velocity for early signals of forecast revision. Quarterly review of state irrigation subsidy disbursement rates and medical device 510(k) submission volumes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Global BOPP Films Market
Poly film
United Kingdom Plastic Packaging Films Market
Poly film
PCR Lidding Films Market
Poly film
Polyester Film Market
Poly film
Morocco Plastic Packaging Films Market
Poly film
Twist Wrap Film Market
Poly film
Thermoforming Films Market
Poly film
APET Film Market
Poly film
Middle East and Africa Plastic Packaging Films Market
Poly film
Blown Film Extruder Market
Poly film
Polymer Dispersed Liquid Crystal (PDLC) Film Market
Poly film
North America Shrink and Stretch Film Market
Poly film
PP Film Blowing Machine Market
Poly film
Global Sound Insulation PVB Film Market
Poly film
Polyurethane (PU) Film Market
Poly film
Vinyl Films Market