
 Anatomic Pathology Market | 2026-2036
Anatomic Pathology Market Size, Share, and Industry Trends Forecast 2026-2036
Anatomic Pathology Market Intelligence
Clinical-grade digital pathology adoption is bifurcating the market between automated, high-throughput labs and traditional manual-read facilities. F. Hoffmann-La Roche AG leverages its integrated diagnostics portfolio to capture share in this transition. Danaher Corporation competes through its Leica Biosystems brand, offering a full workflow from slide preparation to analysis. Thermo Fisher Scientific sustains a strong position with its extensive range of consumables and instruments.
Anatomic pathology involves the macroscopic and microscopic examination of tissues and organs to diagnose disease. The discipline relies on techniques like tissue fixation with formalin and staining with hematoxylin and eosin (H&E) to reveal critical cellular morphology. The cancer diagnosis application continues to dominate all use cases, driven by rising oncology screening programs and case volumes. Within product types, histopathology remains foundational, while molecular diagnostics and immunohistochemistry show significant expansion due to precision medicine demands.
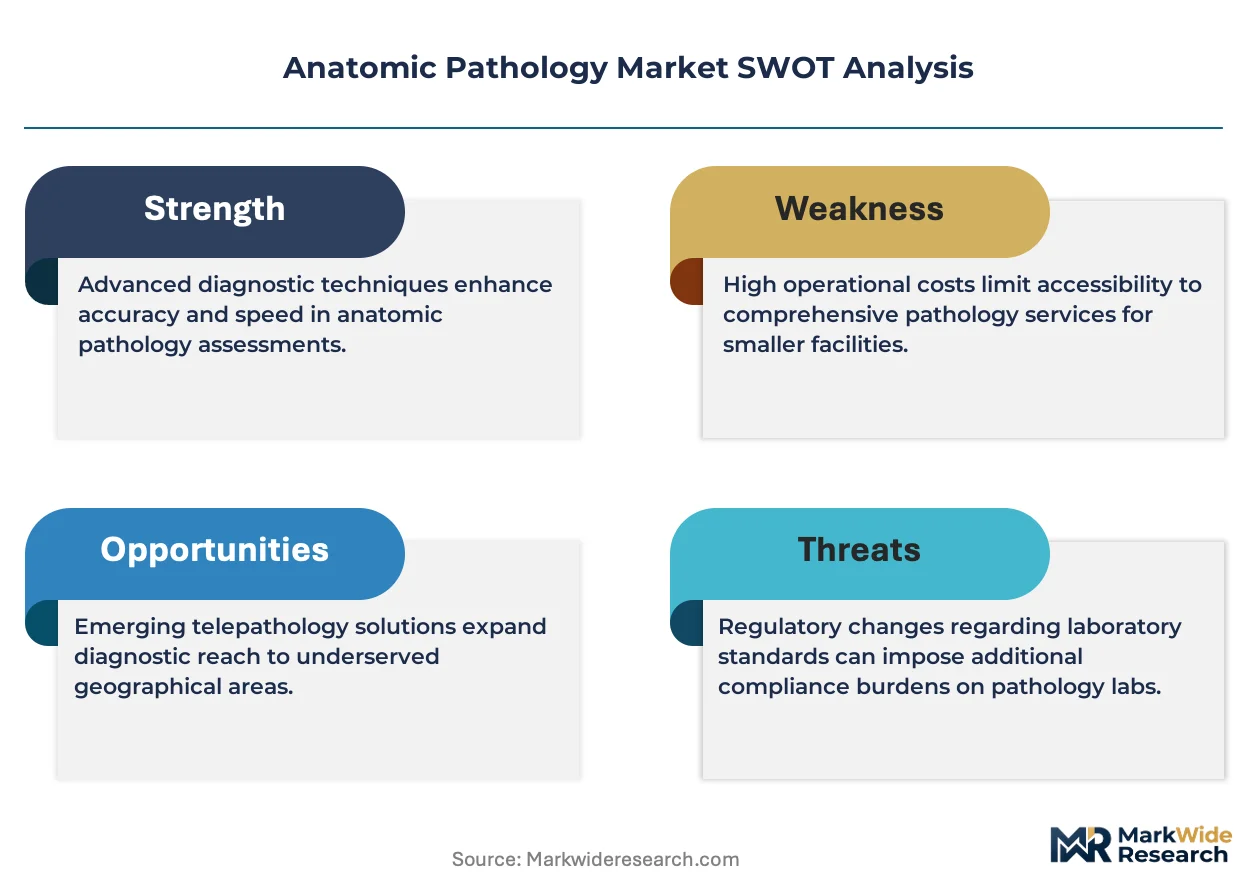
Regulatory frameworks from the FDA in the United States and the EMA in Europe, particularly through the In Vitro Diagnostic Regulation (IVDR), govern instrument and assay approvals. In China, the NMPA sets stringent standards for market entry, impacting both domestic and foreign manufacturers. Navigating the evolving landscape of laboratory developed tests (LDTs) versus IVD-cleared platforms is a critical strategic decision for all stakeholders.
Market Dynamics
The central force shaping the anatomic pathology market is the technological transition from analog glass slides to digital whole slide imaging. This shift redefines laboratory workflows, enables computational analysis, and creates a clear divide between automated and manual facilities.
Growth Catalysts
- Digital Pathology Adoption:The integration of whole slide imaging scanners and artificial intelligence algorithms enhances diagnostic accuracy and operational efficiency, particularly within high-volume laboratories in the United States and Germany.
- Oncology Case Volume:Expansion of national cancer screening programs in the UK and Australia increases case volume, requiring more pathology services. Demand for companion diagnostics to guide targeted therapies further fuels this growth.
- Precision Medicine Initiatives:Government and private funding for precision medicine encourages the use of advanced molecular and immunohistochemistry techniques, which depend on detailed anatomic pathology analysis for tissue characterization.
Market Restraints
- High Capital Costs:Significant capital investment for digital scanners, data storage solutions, and IT infrastructure presents a substantial barrier to adoption for smaller independent laboratories and hospitals in less developed economies.
- Interoperability and Data Standards:The lack of universal standards for digital image formats and software interfaces creates integration challenges between different vendor platforms and existing Laboratory Information Systems (LIS), hindering seamless workflows.
- Regulatory Hurdles:The EU's In Vitro Diagnostic Regulation (IVDR) creates higher barriers for assay and instrument approval, lengthening time-to-market and increasing compliance costs for manufacturers operating in Europe.
Strategic Opportunities
- Emerging Market Expansion:Investing in healthcare infrastructure in countries like Brazil and India presents an opportunity to establish digital pathology platforms, bypassing legacy analog systems in regions with rising cancer incidence.
- Multi-Omic Tissue Analysis:Converging genomics with histopathology creates multi-omic tissue analysis opportunities, providing deeper biological insights for complex diseases. This opens new avenues for diagnostic and prognostic tool development.
- Decentralized Pathology Networks:Developing telepathology platforms allows skilled pathologists to provide remote diagnostic services, addressing specialist shortages in rural areas and enabling workload balancing across different healthcare networks.
Industry Challenges
- Pathologist Skill Gap:A persistent shortage of board-certified pathologists with digital and computational expertise constrains laboratory capacity. The steep learning curve for new software and analytical tools slows the transition from traditional methods.
- Data Management Complexity:The massive data files generated by whole slide imaging require sophisticated and costly storage, security, and archival solutions, posing a significant operational challenge for IT departments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anatomic Pathology Market |
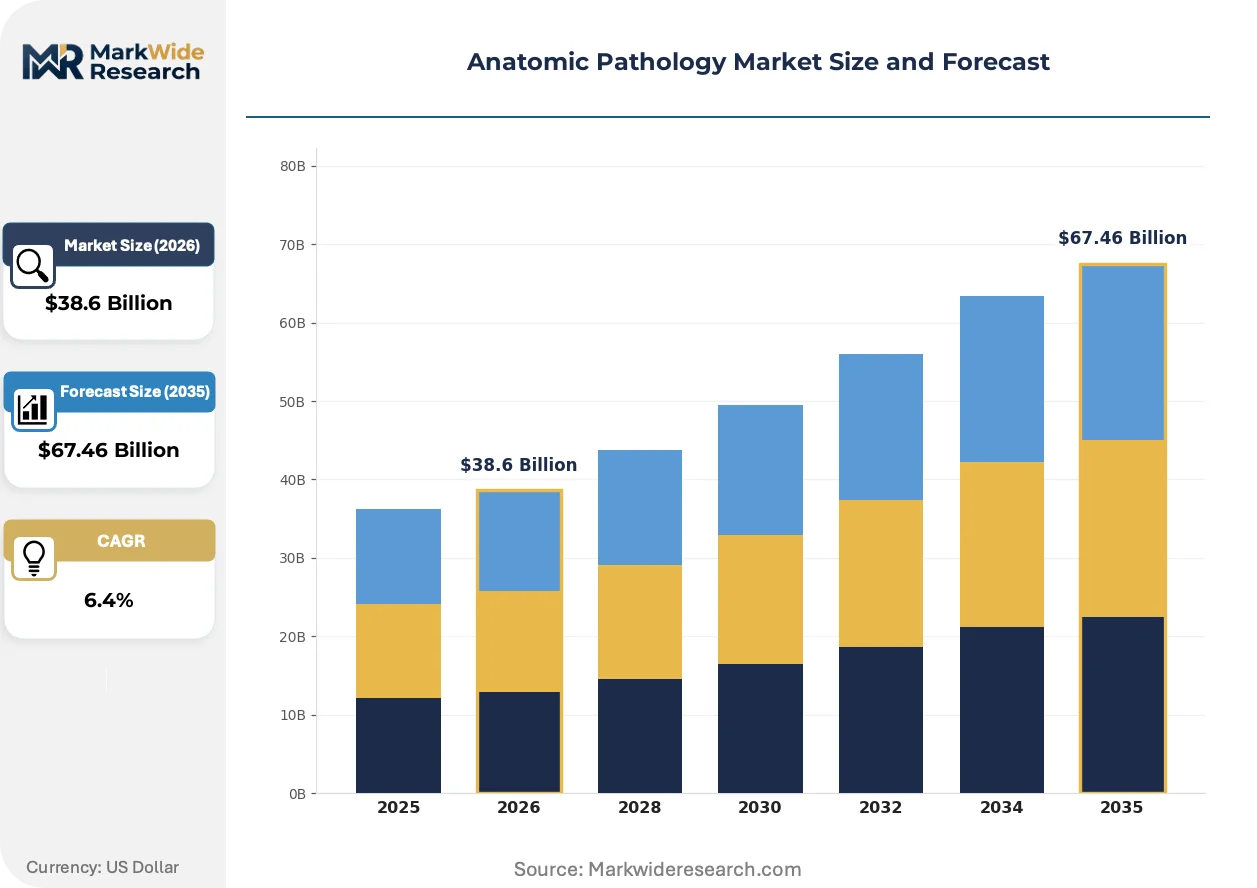
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $67.46 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Histopathology, Cytology, Molecular Diagnostics, Immunohistochemistry, In Situ Hybridization Application: Cancer Diagnosis, Infectious Disease Analysis, Genetic Disorder Testing, Forensic Pathology, Toxicology Studies End User: Diagnostic Laboratories, Academic Research Centers, Pharmaceutical Companies, Government Agencies, Reference Laboratories Technology: Digital Pathology, Automated Slide Staining, Whole Slide Imaging, Image Analysis Software, Telepathology |
| Companies Covered | Thermo Fisher Scientific, Danaher Corporation, F. Hoffmann-La Roche AG, PHC Holdings Corporation, Quest Diagnostics Incorporated, Laboratory Corporation of America Holdings, Agilent Technologies, Inc., Sakura Finetek USA, Inc., NeoGenomics Laboratories, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anatomic Pathology Market Strategic Shifts & Innovations
The discipline of anatomic pathology is transforming from a qualitative, morphology-based practice into a quantitative, data-driven science. This evolution is driven by the integration of computational tools and the push for more objective and reproducible diagnostic criteria.
Whole slide imaging (WSI) technology converts glass slides into high-resolution digital files for screen-based viewing and analysis. High-throughput laboratories and academic medical centers are the primary adopters of this technology. This computational workflow is displacing traditional manual microscopy for primary diagnosis and consultations in advanced settings.
Europe's In Vitro Diagnostic Regulation (IVDR) establishes a more rigorous framework for market access. The regulation demands greater clinical evidence and post-market surveillance for all diagnostic tests and instruments. This affects manufacturers and labs developing their own tests, forcing reassessment of product portfolios and validation.
A shift is occurring from entirely on-site pathology services to networked, remote-reading models. This disrupts the model of pathologists being co-located with the laboratory, allowing for load-balancing of cases across geographies. This trend is most apparent in the United States and Canada, where it helps mitigate specialist shortages in remote regions.
Anatomic Pathology Market Segmentation
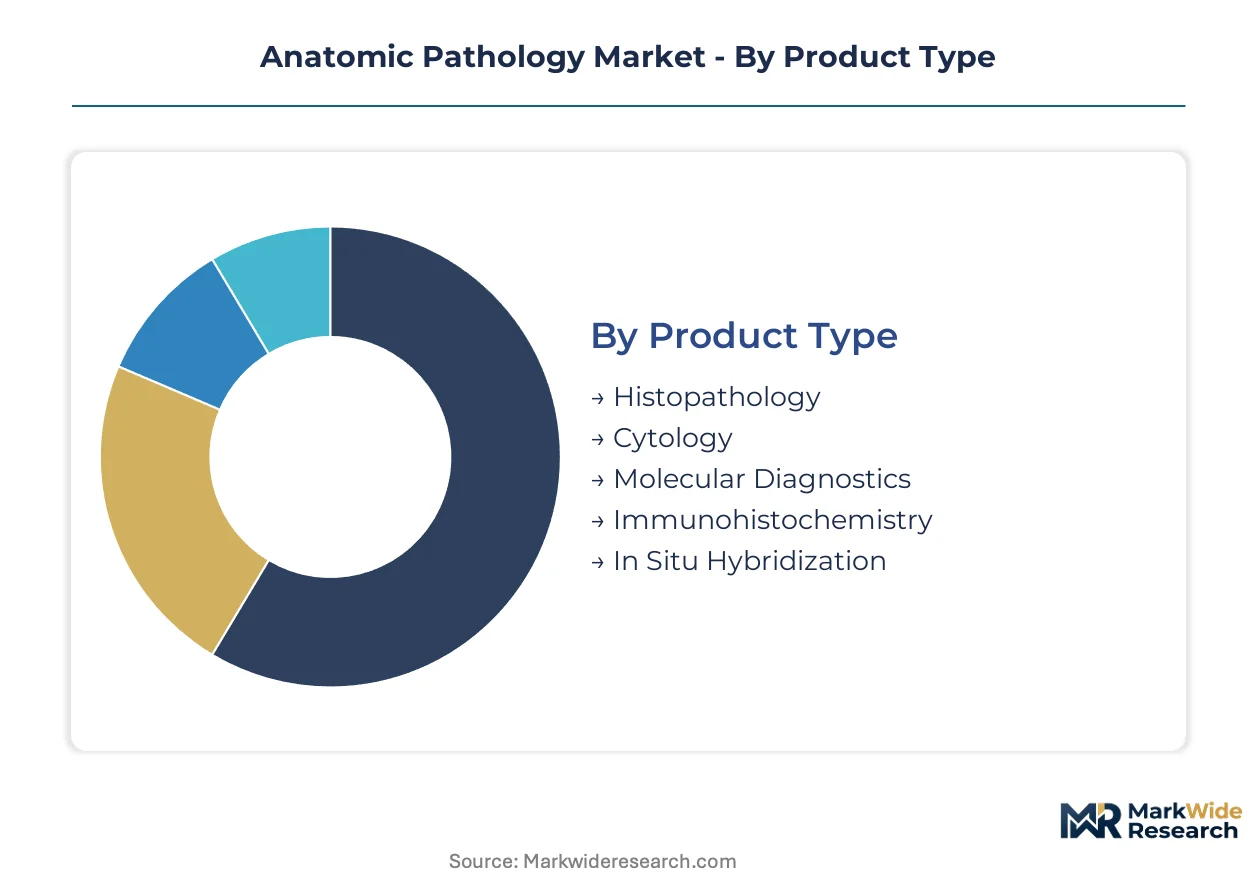
Market segmentation for anatomic pathology illuminates the diverse components driving diagnostic advancements and patient care. Understanding these distinct categories provides clarity on where investment flows and innovation concentrates within the global healthcare ecosystem. Each segment reflects specific technological applications or end-user demands, shaping the overall market trajectory.
Product Type:
The product type distribution reveals varying levels of technological maturity and geographic adoption, with some techniques serving as foundational practices globally while others gain traction in specific, advanced markets.
- Histopathology:This foundational technique involves the macroscopic and microscopic examination of tissue biopsies fixed with formalin and stained with hematoxylin and eosin (H&E). Demand remains consistently high across all regions, particularly in cancer diagnosis where precise tissue morphology guides treatment decisions.
- Molecular Diagnostics:This segment includes techniques for detecting specific genetic sequences or biomarkers, vital for precision medicine initiatives and targeted therapies. Its expansion is pronounced in developed economies like the United States and Germany, driven by oncology advancements and research funding.
- Cytology:Cytology focuses on the microscopic examination of individual cells, often collected from fluid or fine needle aspirates, to diagnose disease. This method offers a less invasive diagnostic approach, widely utilized for cervical cancer screening programs in many countries.
- Immunohistochemistry:Utilizing antibody-antigen reactions to identify specific proteins within tissue sections, this technique is crucial for tumor classification and prognostication. Precision medicine demands significantly expand its application in both clinical and research settings.
- In Situ Hybridization:This method detects specific DNA or RNA sequences directly within cells or tissues, providing insights into gene expression and chromosomal abnormalities. It supports advanced cancer diagnostics and genetic disorder identification.
Histopathology holds the largest share; momentum sits with Molecular Diagnostics.
Application:
Applications within anatomic pathology highlight the critical diagnostic needs addressed by these techniques, with varying levels of intensity and specific requirements across different disease areas.
- Cancer Diagnosis:This application dominates the market, relying on precise tissue analysis to identify tumor type, stage, and molecular characteristics, directly influencing therapeutic strategies. Rising oncology screening programs in countries like the UK and Australia significantly increase case volumes.
- Infectious Disease Analysis:Anatomic pathology aids in identifying pathogens and observing tissue responses to infections, crucial for diagnosing complex or atypical infectious diseases. This application sees consistent demand in public health surveillance and outbreak management.
- Genetic Disorder Testing:This segment utilizes anatomic pathology to identify structural or molecular abnormalities associated with inherited conditions or developmental disorders. Demand is driven by advancements in prenatal screening and personalized medicine.
- Forensic Pathology:Forensic applications involve the examination of tissues and organs to determine the cause and manner of death in legal investigations. This specialized field requires highly detailed and legally defensible diagnostic procedures.
- Toxicology Studies:These studies use anatomic pathology to assess the effects of toxic substances on tissues and organs, frequently employed in drug development, environmental health, and overdose investigations.
The cancer diagnosis segment maintains significant market volume, while genetic disorder testing is climbing the fastest due to precision medicine advancements.
End User:
The end-user landscape for anatomic pathology reflects the diverse institutional structures that consume diagnostic services, each with distinct operational scales and technical requirements.
- Diagnostic Laboratories:These facilities, ranging from large commercial labs to hospital-based units, perform a high volume of routine and specialized pathology tests. High-throughput laboratories in the United States and Germany are leading adopters of digital pathology systems.
- Academic Research Centers:These institutions engage in both clinical diagnostics and cutting-edge research, driving the development and adoption of new techniques like multi-omic tissue analysis. They often serve as early adopters for advanced technologies.
- Pharmaceutical Companies:These companies utilize anatomic pathology for drug discovery, preclinical safety assessments, and companion diagnostic development during clinical trials. Their demand focuses on highly standardized and reproducible results.
- Government Agencies:Government bodies often operate public health laboratories, forensic labs, and regulatory oversight functions that require anatomic pathology services. They ensure public safety and disease surveillance.
- Reference Laboratories:These specialized laboratories provide advanced or esoteric testing that smaller facilities cannot perform, often serving as referral centers for complex cases. They support a broad network of healthcare providers.
Diagnostic laboratories constitute the primary customer base, with academic research centers demonstrating a strong growth trajectory in advanced technique adoption.
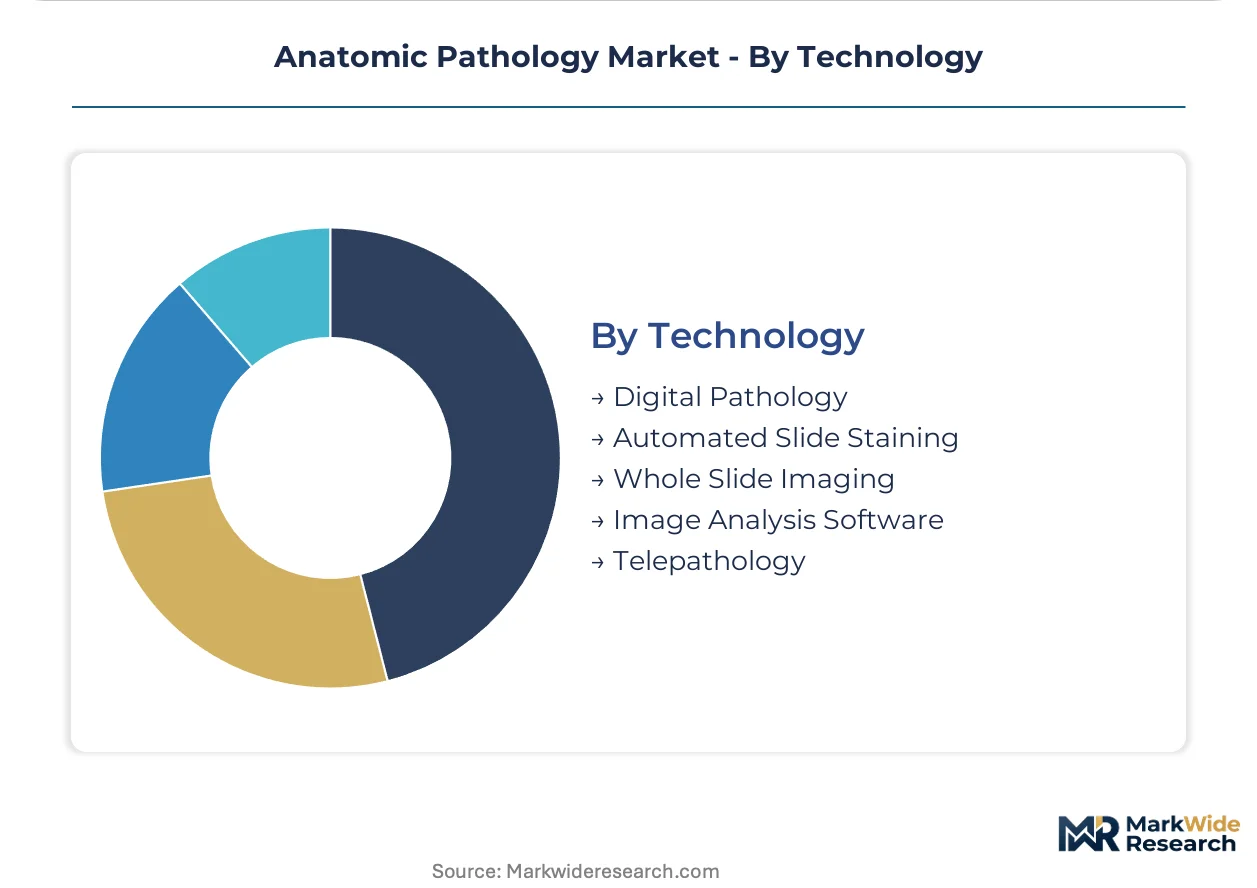
Technology:
The technology segment showcases the maturity and transformative impact of various tools employed in anatomic pathology, ranging from established methods to innovative digital solutions.
- Digital Pathology:This technology involves the acquisition, management, and interpretation of pathology information generated from digitized glass slides. Its maturity is advancing rapidly, particularly in high-volume laboratories seeking improved efficiency and remote diagnostic capabilities.
- Whole Slide Imaging:WSI technology converts traditional glass slides into high-resolution digital images, enabling screen-based viewing and computational analysis. This innovation is displacing manual microscopy in advanced settings and is integral to digital pathology adoption.
- Automated Slide Staining:These systems automate the process of preparing and staining tissue slides, ensuring standardization, reducing manual errors, and increasing laboratory throughput. Their maturity is high, serving as a critical component in high-volume diagnostic workflows.
- Image Analysis Software:AI-powered algorithms and computational tools within this software quantitatively analyze digital pathology images, enhancing diagnostic accuracy and reproducibility. This technology is rapidly evolving, offering new insights into complex diseases.
- Telepathology:Telepathology platforms enable remote diagnostic services by allowing pathologists to review digital slides from off-site locations. This technology addresses specialist shortages and facilitates workload balancing across geographically dispersed healthcare networks.
Digital Pathology represents the most impactful technological shift, while image analysis software is gaining share fastest due to AI integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The anatomic pathology market exhibits a concentrated supply landscape, with diagnostic services and technological innovation primarily centered in developed economies. These regions drive the adoption of advanced digital pathology systems and molecular diagnostics. This concentration reflects significant investment in healthcare infrastructure and research capabilities.
United States
Demand for precision medicine initiatives and oncology case volume drives significant growth in the United States. The FDA's regulatory frameworks govern instrument and assay approvals, influencing market entry. High-throughput laboratories in major cities like Boston and San Francisco are early adopters of digital pathology systems.
Germany
Strong demand for advanced diagnostics stems from robust healthcare funding and academic medical centers across Germany. The EMA's In Vitro Diagnostic Regulation (IVDR) sets stringent standards for market access. Specialized diagnostic laboratories in regions like Bavaria and North Rhine-Westphalia lead in digital pathology adoption.
United Kingdom
Expansion of national cancer screening programs increases pathology service requirements throughout the United Kingdom. The National Health Service (NHS) drives demand for efficient diagnostic solutions across its network. Major academic centers in London and Manchester are advancing digital pathology integration and AI algorithms.
India
Rising cancer incidence and improving healthcare infrastructure stimulate demand for diagnostic services in India. The CDSCO regulates medical device and diagnostic approvals, impacting market growth. Emerging diagnostic hubs in cities such as Mumbai and Bangalore are investing in new pathology platforms.
China
The growing need for accurate cancer diagnosis and precision medicine fuels market expansion in China. The NMPA sets stringent standards for market entry, influencing both domestic and foreign manufacturers. Large diagnostic chains in the Yangtze River Delta region are adopting advanced molecular and immunohistochemistry techniques.
Anatomic Pathology Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the anatomic pathology market. The market structure is bifurcated, with established multinational corporations competing alongside specialized digital pathology innovators. Strategic archetypes include integrated diagnostics providers, instrument and consumables manufacturers, and focused software developers, each addressing distinct needs. Companies pursue portfolio diversification and strategic partnerships to strengthen their market positions and expand geographic reach.
Integrated diagnostics providers, such as the US-based Danaher Corporation and Swiss-based F. Hoffmann-La Roche AG, exemplify companies offering comprehensive workflow solutions from sample preparation to analysis. These entities anchor positions across multiple segments of the pathology market. US-based Thermo Fisher Scientific represents a major player specializing in extensive consumables and instrumentation, supporting various diagnostic workflows. These companies often drive innovation in digital pathology and molecular diagnostics through their broad portfolios.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Danaher Corporation |
| F. Hoffmann-La Roche AG |
| PHC Holdings Corporation |
| Quest Diagnostics Incorporated |
| Laboratory Corporation of America Holdings |
| Agilent Technologies, Inc. |
| Sakura Finetek USA, Inc. |
| NeoGenomics Laboratories, Inc. |
| Others |
Cost & Logistics Intelligence
Extended lead times for specialized digital pathology scanners and advanced molecular diagnostic reagents directly influence pricing power for manufacturers. These longer delivery cycles create inventory buffers for high-volume diagnostic laboratories, impacting their operational costs.
Pricing Analysis
The EU's In Vitro Diagnostic Regulation (IVDR) dictates the pricing tier structure for many diagnostic instruments and assays, emphasizing compliance costs. Pricing for digital pathology solutions often follows a hybrid model, combining per-unit instrument sales with recurring software subscriptions and service contracts. Price differentiation stems from regulatory clearance levels, such as FDA approval, and the breadth of after-sales support provided by vendors. Pricing pressure intensifies for basic histopathology consumables due to high competition, making smaller independent laboratories highly price-sensitive, while large academic medical centers prioritize advanced features.
Supply Chain Analysis
Port congestion in major shipping hubs, particularly in Asia, impacts the inbound logistics costs for diagnostic instrument manufacturers. The supply chain for anatomic pathology equipment and reagents concentrates in Germany, the United States, and China, which host key manufacturers of specialized optics and molecular diagnostic reagents. Single-source vulnerability for critical software components and advanced imaging sensors represents a significant structural risk. Distribution runs primarily through direct sales channels for large diagnostic laboratories and academic medical centers, with regional distributors serving smaller independent facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The anatomic pathology market is at a platform-economics inflection point, driven by the digital pathology ecosystem. Interoperability standards for whole slide imaging and AI algorithms are reshaping diagnostic workflows.
For Market Incumbents: Compound existing market leadership by investing in advanced AI algorithm development for image analysis, securing intellectual property in computational pathology. Strengthen channel control by offering comprehensive, integrated diagnostic platforms that deter competition from specialized software vendors. This strategy mitigates the threat of emerging AI-driven diagnostic tools from new entrants. Vertical integration into software development and data management solutions serves as a critical lever.
For New Entrants and Emerging Players: Differentiate on specialized AI-powered image analysis for niche disease areas, such as rare cancers or specific infectious diseases, where current solutions lack precision. Target the underpenetrated segment of smaller independent laboratories in emerging markets like India and Brazil with cloud-based telepathology platforms. Focus on a value-based pricing model combined with robust remote support as a key go-to-market angle. This approach allows for rapid market entry without significant capital investment in hardware.
For Investors and Strategic Acquirers: Long-term, this sits as a technology-driven consolidation play because the transition to digital pathology requires significant capital and expertise. Acquisition targets should include specialized AI software developers with strong intellectual property in image recognition and computational biology. These firms offer capabilities that enhance existing diagnostic workflows. A critical signal to watch is the increasing regulatory clearance of AI algorithms for primary diagnosis in major markets like the United States and Europe.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifying disparate digital pathology systems enhances workflow efficiency for diagnostic laboratories. |
| AI Algorithm Development | Creating advanced image analysis tools improves diagnostic accuracy in oncology. |
| Telepathology Network Expansion | Building remote diagnostic capabilities addresses pathologist shortages in rural areas. |
| Molecular Diagnostics Portfolio Diversification | Expanding genetic testing options supports precision medicine initiatives. |
| Regulatory Pathway Investment | Securing FDA and IVDR approvals accelerates market access for new instruments. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted to gather primary insights for this analysis. Interviews included board-certified pathologists, laboratory directors, oncology specialists, and medical device engineers. This primary research was triangulated with extensive secondary data from sources like FDA filings, EMA submissions, and peer-reviewed medical journals. A rigorous bottom-up and top-down approach ensured data consistency and market sizing accuracy.
The market size and growth projections across the analysis window were derived using a robust analytical framework. This framework modeled segmentation across product type, application, end-user, technology, geographic region, and digital readiness level. Compound annual growth rates were calculated based on historical trends and future adoption forecasts. Key inputs included projected oncology case volumes and digital pathology integration rates within diagnostic laboratories.
The analysis sits within stated boundaries; outcomes outside significant regulatory changes or unforeseen technological breakthroughs would require recalibration. Forecasts reflect current market assumptions regarding healthcare funding and adoption trends. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Human Immunodeficiency Virus Rapid Test Kit Market
Diagnostics
RT-PCR Kits Market
Diagnostics
Cellular Health Screening Market
Diagnostics
Total Iron Binding Capacity Reagents Market
Diagnostics
Influenza Diagnostics Market
Diagnostics
Global Oral Cancer Rapid Test Kit Market
Diagnostics
Primary Care POC Diagnostics Market
Diagnostics
Middle East and Africa Syndromic Multiplex Diagnostic Market
Diagnostics
Fungal Antigens Market
Diagnostics
Multiplexed Diagnostics Market
Diagnostics
Helicobacter Pylori (H. Pylori) Diagnostics Market
Diagnostics
North America Breast Cancer Screening Tests Market
Diagnostics
Veterinary Diagnostics Market
Diagnostics
China in Vitro Diagnostics Market
Diagnostics
Mycology Immunoassays Testing Market
Diagnostics
Mycoplasma Detection System Market