
 Mycology Immunoassays Testing Market | 2026-2036
Mycology Immunoassays Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Mycology Immunoassays Testing Market Outlook
Multi-sourced reagent procurement is repositioning supply chain economics for mycology immunoassay manufacturers. Roche leverages captive biologics production to secure antibody supply chains for histoplasmosis and blastomycosis panels. Siemens Healthineers anchors its competitive stance through integrated instrument-reagent platforms deployed across European hospital networks. bioMérieux specializes in niche fungal antigen detection, competing on assay specificity rather than throughput scale.
Mycology immunoassays testing encompasses immunological methods that detect fungal antigens, antibodies, or metabolites in clinical and environmental specimens, typically employing enzyme-linked immunosorbent assay (ELISA) or chemiluminescence architectures with detection thresholds ranging from picogram to nanogram per milliliter. These systems serve primarily to diagnose invasive fungal infections where culture-based methods exhibit prolonged turnaround times or poor sensitivity. ELISA and chemiluminescence technologies command the dominant installed base due to regulatory familiarity and workflow integration, while lateral flow assays represent the fastest-expanding format for point-of-care screening in resource-limited settings. Disease diagnosis applications concentrate the majority of revenue, though environmental testing for airborne fungal pathogens in healthcare construction zones is emerging as a margin-accretive specialty segment.
FDA 510(k) pathways and EMA in vitro diagnostic regulations shape assay development priorities, with both agencies intensifying scrutiny of analytical validation for emerging fungal biomarkers such as T2 magnetic resonance and galactomannan variants. CLIA complexity categorization in the United States directly determines whether novel mycology tests deploy in centralized laboratories or near-patient settings. Stakeholders must monitor evolving CMS reimbursement determinations for multiplex fungal panels, as coverage decisions will determine whether hospital laboratories absorb these tests into routine sepsis workups or relegate them to send-out reference patterns.
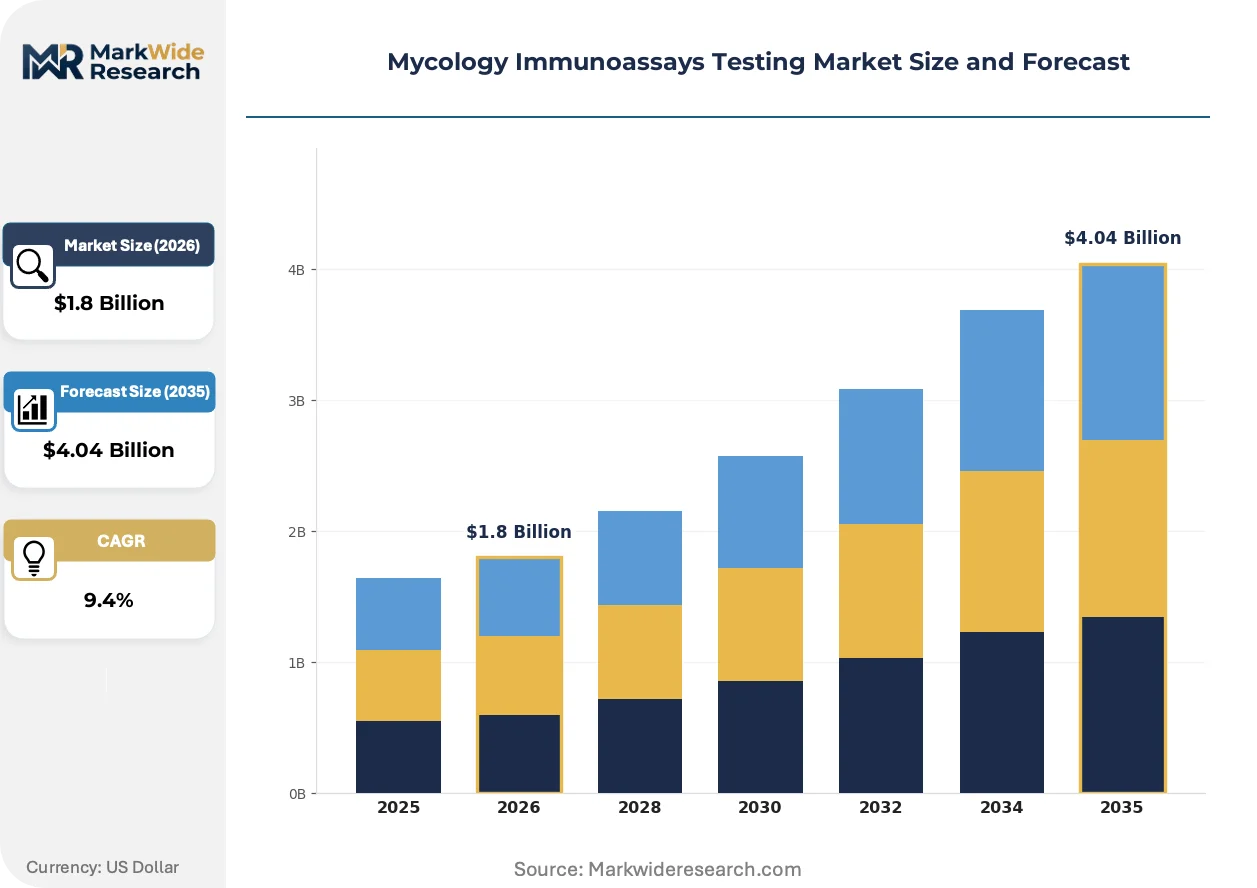
Market Dynamics
CLIA complexity categorization and CMS reimbursement determinations are compressing assay deployment timelines, forcing manufacturers to pre-validate for both centralized laboratory and near-patient workflows before FDA 510(k) submission rather than retrofitting post-clearance.
Growth Catalysts
- Hospital-acquired candidiasis surveillance mandates:Tightening infection control protocols in the United States, Germany, and Japan are mandating routine screening for invasive fungal infections in immunocompromised patient populations.
- EMA in vitro diagnostic regulation streamlining:Compressed development timelines for novel fungal biomarker assays are accelerating market entry for galactomannan variant tests across European hospital networks.
- ELISA-to-chemiluminescence platform upgrades:Diagnostics laboratories are replacing legacy enzyme-linked immunosorbent assay systems with higher-throughput chemiluminescence architectures to reduce turnaround times for sepsis workups.
Market Restraints
- Antibody supply concentration:Captive biologics production by vertically integrated diagnostics conglomerates limits third-party access to high-affinity reagents for histoplasmosis and blastomycosis panels.
- Analytical validation scrutiny:FDA and EMA intensified review of emerging fungal biomarkers such as T2 magnetic resonance is extending premarket notification cycles and inflating clinical study costs.
- Culture-based method persistence:Gold-standard microbiological confirmation remains required for reimbursement in many jurisdictions, creating dual-testing cost burdens that suppress immunoassay volume expansion.
Strategic Opportunities
- Point-of-care lateral flow expansion:Resource-limited settings in sub-Saharan Africa and Southeast Asia present untapped demand for portable screening formats that bypass cold-chain logistics requirements.
- Environmental testing for healthcare construction:Airborne fungal pathogen monitoring in renovation zones is emerging as a margin-accretive specialty segment with limited incumbent competition.
- Multiplex fungal panel integration:CMS favorable coverage determinations for combined antigen detection assays would enable hospital laboratories to absorb these tests into routine sepsis protocols rather than reference send-out patterns.
Industry Challenges
- Cross-reactivity elimination:Assay developers struggle to engineer antibody specificity sufficient to distinguish cryptococcal antigen from interfering substances in cerebrospinal fluid matrices.
- Laboratory information system integration:Middleware compatibility gaps between novel immunoassay instruments and legacy hospital IT infrastructure are delaying workflow automation benefits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mycology Immunoassays Testing Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ELISA, Rapid Tests, Western Blot, Lateral Flow Assays Application: Disease Diagnosis, Environmental Testing, Food Safety, Research & Development End User: Hospitals, Diagnostics Laboratories, Research Institutions, Academic Universities Technology: Fluorescence, Chemiluminescence, Colorimetric, Optical Detection |
| Companies Covered | Roche, Abbott Laboratories, Siemens Healthineers, Beckman Coulter, bioMérieux, Ortho Clinical Diagnostics, Thermo Fisher Scientific, Bio-Rad Laboratories, MiraVista Diagnostics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mycology Immunoassays Testing Market Strategic Shifts
Magnetic resonance-based detection architectures and artificial intelligence-enabled result interpretation are compressing diagnostic timelines while regulatory agencies recalibrate validation frameworks for these convergent technologies.
T2 magnetic resonance technology is converging with automated sample-to-answer platforms to eliminate culture-based confirmation steps for candidemia diagnosis. Academic medical centers in the United States are piloting these integrated systems for emergency department triage. The structural consequence is a compression of time-to-appropriate antifungal therapy from days to hours, displacing empiric broad-spectrum prescribing patterns.
The FDA 510(k) pathway is tightening analytical validation requirements for novel fungal biomarkers while simultaneously expanding breakthrough device designation eligibility for assays addressing antifungal resistance. Manufacturers must now submit expanded clinical performance data prior to clearance. European IVD manufacturers are responding by front-loading clinical studies in anticipation of parallel EMA MDR conformity assessment.
Hospital laboratory directors are consolidating vendor relationships around integrated instrument-reagent platforms to secure supply continuity and simplify service contracting. This concentration is displacing best-of-breed procurement strategies that previously mixed instruments from Siemens Healthineers with reagents from specialized antigen detection suppliers. The shift is most visible in German and Japanese hospital networks where central purchasing authorities negotiate multi-year sole-source agreements.
Mycology Immunoassays Testing Market Segmentation
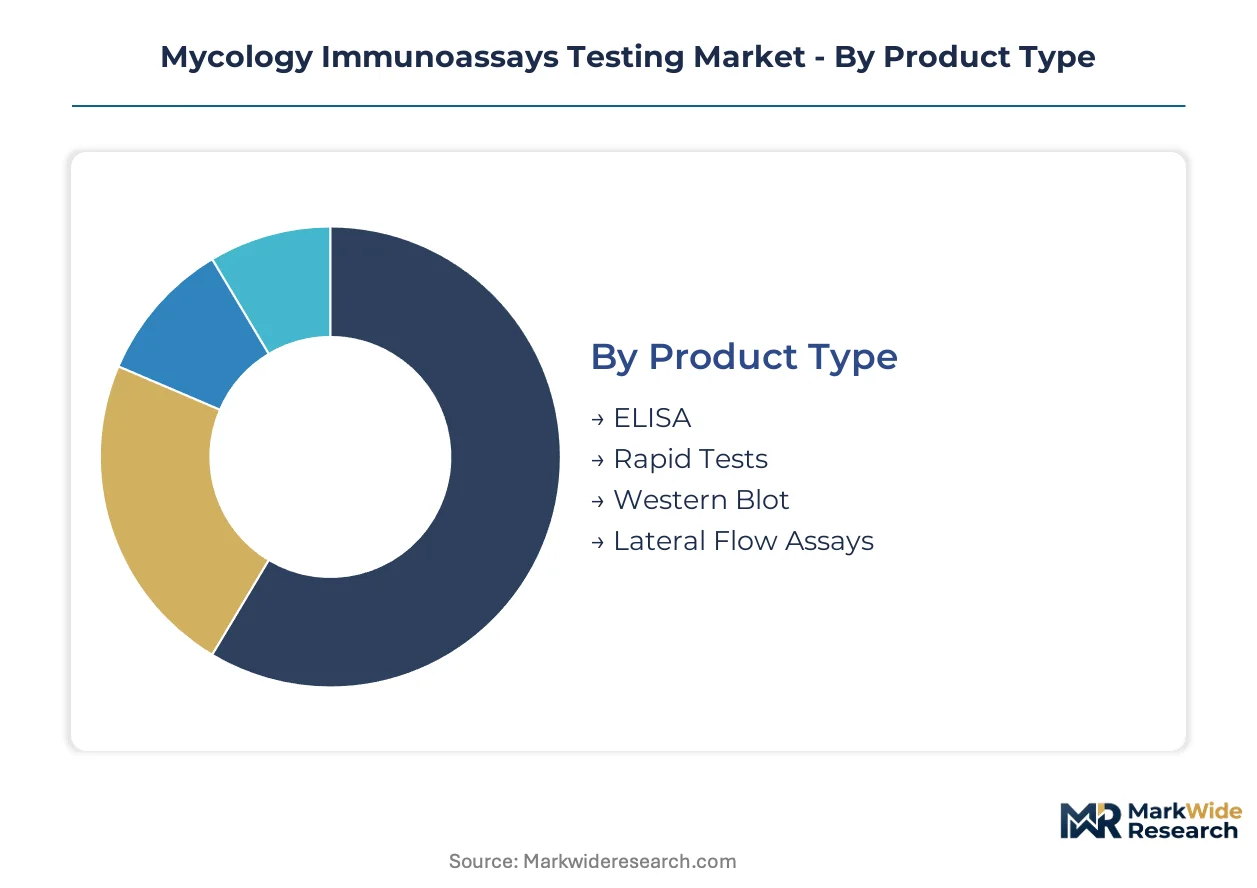
Segmentation in mycology immunoassays testing reveals how regulatory pathways, workflow integration requirements, and reimbursement structures fragment procurement decisions across hospital laboratories and reference facilities. Understanding these divides clarifies why certain formats dominate centralized settings while others penetrate point-of-care environments.
Product Type:
ELISA platforms carry moderate-complexity CLIA certification burdens in the United States, while lateral flow assays qualify for waived status, compressing deployment timelines in near-patient settings.
- ELISA:Enzyme-linked immunosorbent assay systems detect fungal antigens and antibodies through colorimetric signal generation with established FDA 510(k) predicate pathways. Hospital laboratories in Germany and Japan concentrate procurement around these platforms for high-throughput screening of immunocompromised oncology patients, driven by EMA MDR familiarity and reimbursement stability for centralized workflows.
- Lateral Flow Assays:Single-use cassettes deliver qualitative results within 15-30 minutes without instrument dependency, enabling deployment in resource-limited clinics lacking cold-chain infrastructure. Demand concentrates in sub-Saharan African healthcare facilities and Southeast Asian community health centers where CLIA-waived equivalence accelerates regulatory clearance.
- Rapid Tests:Simplified immunoassay formats prioritize speed over sensitivity for emergency department triage decisions.
- Western Blot:Confirmatory testing method reserved for reference laboratories requiring high analytical specificity.
Leading the category by volume: ELISA. Growing fastest: Lateral Flow Assays.
Application:
Disease diagnosis commands premium pricing tiers due to clinical outcome stakes, while environmental testing operates on project-based contracting with fragmented purchaser concentration.
- Disease Diagnosis:Detection of invasive candidiasis, aspergillosis, and cryptococcal meningitis in immunocompromised patients relies on antigen detection sensitivity thresholds measured in picograms per milliliter. Academic medical centers in the United States and university hospitals in Japan anchor demand, pressured by hospital-acquired infection surveillance mandates and sepsis bundle reimbursement incentives.
- Environmental Testing:Airborne fungal spore monitoring during healthcare facility construction and renovation projects requires assay formats capable of detecting Aspergillus fumigatus in high-particulate matrices. Demand clusters around specialized environmental consulting firms serving German hospital networks and Japanese metropolitan healthcare districts, where building code enforcement has tightened post-renovation clearance protocols.
- Food Safety:Mycotoxin detection in agricultural commodities and processed foods.
- Research & Development:Exploratory biomarker validation and assay development for emerging fungal pathogens.
Volume leadership sits with Disease Diagnosis. Steepest expansion trajectory: Environmental Testing.
End User:
Procurement sophistication varies sharply — hospitals negotiate sole-source multi-year agreements while academic institutions prioritize grant-funded flexibility and reagent interchangeability.
- Hospitals:Integrated health systems in the United States and centralized purchasing authorities in Germany consolidate vendor relationships around instrument-reagent locked platforms to secure service continuity and volume pricing. CLIA high-complexity laboratory directors drive selection criteria toward middleware compatibility and LIS integration rather than standalone assay performance.
- Diagnostics Laboratories:Commercial reference laboratories process high specimen volumes across regional catchment areas, demanding throughput scalability and automated sample handling. Japanese commercial lab chains and German hospital-affiliated diagnostics networks represent concentrated purchasing power, with EMA MDR conformity assessment timelines influencing vendor selection.
- Research Institutions:Exploratory assay development and biomarker discovery projects.
- Academic Universities:Teaching hospital laboratories with mixed clinical-research missions.
Hospitals dominate procurement value. Diagnostics Laboratories are expanding most quickly.
Technology:
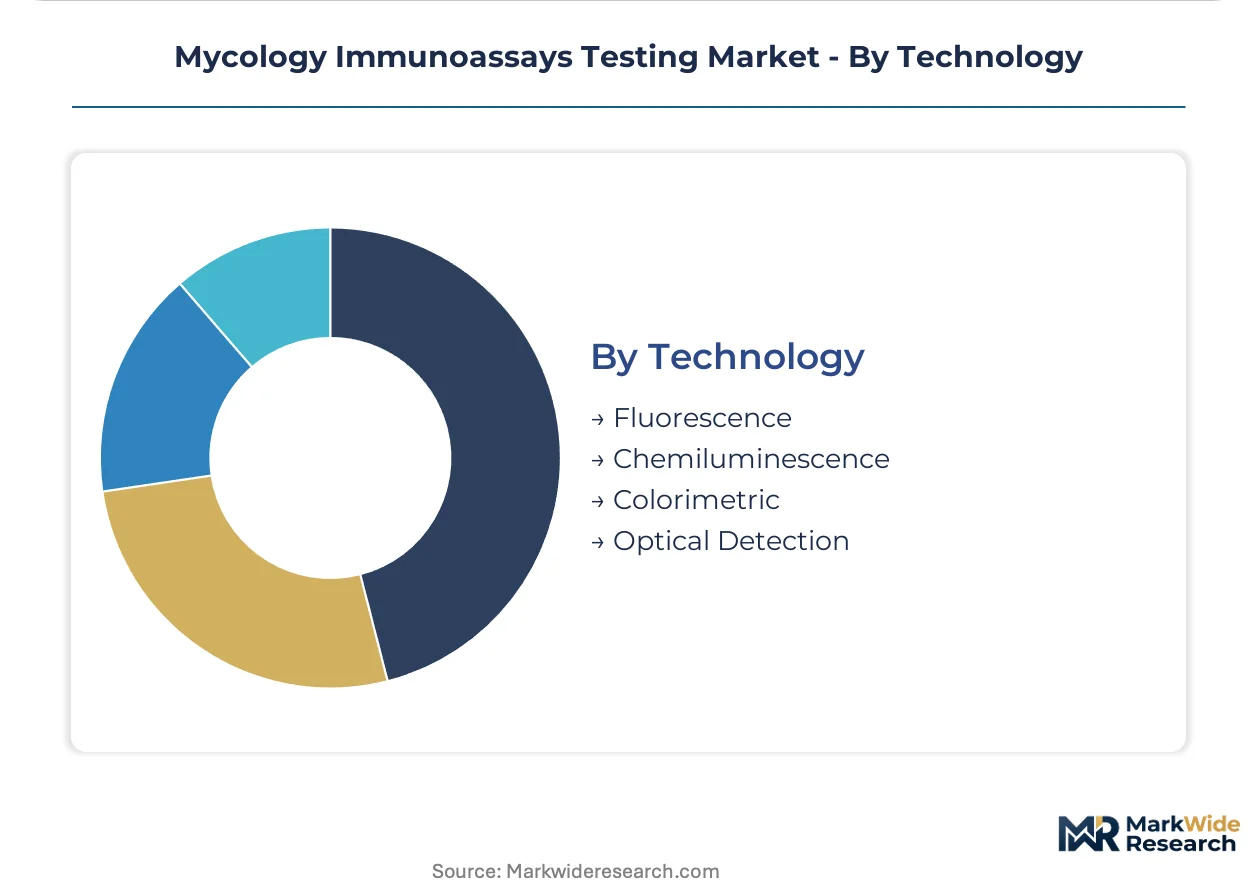
Detection modality selection determines instrument capital requirements, reagent stability profiles, and regulatory validation burden — fluorescence and chemiluminescence demand substantial upfront investment while colorimetric formats minimize infrastructure barriers.
- Chemiluminescence:Enzyme-triggered light emission enables detection sensitivity surpassing colorimetric methods by orders of magnitude, supporting quantitative fungal antigen measurement in low-biomass specimens. Siemens Healthineers and Roche anchor installed bases across European hospital networks, with Japanese metropolitan laboratories accelerating platform upgrades to reduce sepsis workup turnaround times.
- Fluorescence:Excitation-emission detection architectures support multiplexed analyte identification in single reaction wells.
- Colorimetric:Visual or spectrophotometric endpoint detection suits resource-limited settings lacking specialized instrumentation.
- Optical Detection:Light-scattering and absorbance-based measurement systems for turbidimetric fungal antigen assays.
Chemiluminescence leads technology deployment by value. Fluorescence is gaining share fastest in multiplex applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Antibody production clusters in Switzerland and Germany anchor reagent supply chains for mycology immunoassay manufacturers serving diagnostic laboratories worldwide.
United States
Hospital-acquired candidiasis surveillance mandates from the Centers for Disease Control and Prevention drive routine screening volumes in immunocompromised oncology wards. FDA 510(k) pathway refinements for breakthrough device designation accelerate clearance timelines for novel fungal biomarker assays. Academic medical centers in Boston and Baltimore pilot integrated T2 magnetic resonance platforms for emergency department triage, compressing time-to-appropriate antifungal therapy.
Germany
Centralized purchasing authorities in North Rhine-Westphalia and Bavaria negotiate multi-year sole-source agreements for instrument-reagent platforms. EMA MDR conformity assessment streamlining reduces premarket notification cycles for galactomannan variant tests. University hospital networks in Heidelberg and Munich anchor demand for high-throughput chemiluminescence architectures in sepsis workup protocols.
Japan
Metropolitan healthcare districts in Tokyo and Osaka enforce tightened building code clearance protocols for post-renovation environmental testing. PMDA regulatory harmonization with FDA validation standards compresses development timelines for multinational assay manufacturers. Japanese commercial laboratory chains concentrate purchasing power for automated sample handling systems across regional catchment areas.
Switzerland
Captive biologics production facilities in Basel secure high-affinity antibody supply chains for histoplasmosis and blastomycosis panels. Swissmedic maintains rigorous analytical validation scrutiny for emerging fungal biomarkers while facilitating market access for innovative diagnostics. The Lake Geneva corridor hosts specialized environmental consulting firms serving healthcare construction monitoring contracts.
India
Community health centers in Maharashtra and Karnataka generate demand for CLIA-waived lateral flow formats bypassing cold-chain logistics requirements. CDSCO regulatory pathway alignment with WHO prequalification standards accelerates deployment of point-of-care screening tools. Research institutions in Bangalore and Hyderabad pursue exploratory biomarker validation for emerging fungal pathogens affecting immunocompromised populations.
Mycology Immunoassays Testing Market Competitive Environment
Global majors compete with regional champions across instrument-reagent integration depth, with consolidated purchasing power in German and Japanese hospital networks favoring sole-source platform vendors over best-of-breed procurement strategies. The vendor base stratifies into three archetypes: vertically integrated conglomerates controlling captive antibody production, specialized antigen detection firms competing on assay specificity, and emerging point-of-care format developers targeting resource-limited settings. Dominant competitive moves include backward integration into biologics manufacturing and multi-year service contracting to secure installed base loyalty.
Among Swiss and German-based conglomerates, Roche and Siemens Healthineers exemplify the vertically integrated archetype through instrument-reagent platform dominance across European hospital networks. BioMérieux occupies a position representing specialized fungal antigen detection competitors prioritizing assay specificity over throughput scale. These three anchors illustrate how regulatory familiarity and middleware compatibility determine vendor selection criteria for CLIA high-complexity laboratory directors.
| Leading Market Players |
|---|
| Roche |
| Abbott Laboratories |
| Siemens Healthineers |
| Beckman Coulter |
| bioMérieux |
| Ortho Clinical Diagnostics |
| Thermo Fisher Scientific |
| Bio-Rad Laboratories |
| MiraVista Diagnostics |
| Others |
Value Chain & Pricing Dynamics
Antibody-grade bovine serum albumin price indices cascade through mycology immunoassay manufacturing into three distinct procurement tiers: instrument-reagent locked platforms, best-of-breed reagent sourcing, and point-of-care disposable formats. German and Japanese hospital networks leverage multi-year sole-source agreements to compress per-test costs, while reference laboratories in the United States absorb premium pricing for CLIA high-complexity certification maintenance.
Pricing Analysis
Warranty and service bundling separates Siemens Healthineers' multi-year maintenance contracts from Roche's instrument-reagent integration packages, with bioMérieux competing on unbundled reagent flexibility. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) predicate pathway maturity, CE marking tier, and throughput scale. Pricing pressure stems from CMS reimbursement compression for multiplex fungal panels, forcing manufacturers to absorb validation costs. Community health centers in India exhibit highest price sensitivity; academic medical centers in the United States demonstrate lowest sensitivity due to grant-funded flexibility.
Supply Chain Analysis
Single-source vulnerability sits with Swiss captive biologics production for high-affinity histoplasmosis antibodies. Manufacturing concentrates in Switzerland, Germany, and the United States, with reagent formulation drawing from antibody production clusters in Basel and Heidelberg. Supply chain risk centers on EMA MDR regulatory restriction extending conformity assessment timelines for novel fungal biomarkers. Distribution runs through integrated instrument-reagent platform vendors serving hospital network central purchasing authorities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where FDA 510(k) pathway intensification and EMA MDR streamlining create barrier-to-entry moats for analytically validated incumbents.
For Market Incumbents: Deploy backward integration into captive antibody production to secure reagent supply continuity against emerging point-of-care format developers. Siemens Healthineers and Roche should consolidate German and Japanese hospital network relationships through middleware compatibility investments, displacing best-of-breed procurement strategies before CLIA complexity categorization compresses deployment timelines further. For New Entrants and Emerging Players: Lateral flow assay miniaturization offers the most penetrable wedge for sub-Saharan African and Southeast Asian community health centers lacking cold-chain infrastructure. Target CLIA-waived equivalence pathways and WHO prequalification alignment to bypass centralized laboratory procurement concentration. Partner with regional distributors possessing existing malaria and HIV rapid test relationships to accelerate channel access. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized fungal antigen detection firms with EMA MDR dossier preparation in European university hospital corridors. Long-term viability hinges on multiplex fungal panel integration into routine sepsis protocols rather than reference send-out patterns. Monitor CMS reimbursement determinations for combined antigen detection assays as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| EMA MDR Conformity Assessment Streamlining | Accelerates market entry for galactomannan variant tests across European hospital networks. |
| Integrated T2 Magnetic Resonance Platform Deployment | Compresses candidemia diagnosis timelines from days to hours in United States academic medical centers. |
| Point-of-Care Lateral Flow Format Expansion | Bypasses cold-chain logistics requirements in sub-Saharan African and Southeast Asian clinics. |
| Environmental Testing Capability Buildout | Captures margin-accretive specialty segment in German and Japanese healthcare construction monitoring. |
| Multiplex Fungal Panel Reimbursement Strategy | Enables hospital laboratory absorption into routine sepsis workups versus reference send-out patterns. |
Study Parameters
Independent corroboration across hospital laboratory directors, CLIA compliance officers, and biomedical engineers underwrites the qualitative findings in this analysis. Primary interviews with diagnostics procurement managers at German centralized purchasing authorities, Japanese commercial laboratory chains, and United States academic medical centers combined with secondary validation from FDA 510(k) filings, EMA MDR submission databases, and CMS reimbursement determinations. Bottom-up instrument installation counts and top-down reagent consumption estimates triangulate market sizing across the analysis window.
Comparable-period anchoring to historical CLIA complexity categorization shifts and EMA regulatory streamlining initiatives structured the forecast framework. Segmentation dimensions modeled include product format, detection technology, application type, and end-user procurement sophistication across the projection horizon. CAGRs derive from elasticity-adjusted penetration curves for chemiluminescence platform upgrades and lateral flow assay deployment in resource-limited settings. Forecast inputs incorporate hospital-acquired candidiasis surveillance mandate expansion timelines and environmental testing protocol adoption in healthcare construction zones.
Several conditions sit outside the modeled scope, including unforeseen fungal pathogen emergence requiring novel biomarker development and abrupt CMS reimbursement category reclassification. Forecasts reflect documented assumptions regarding regulatory pathway stability and antibody supply continuity from Swiss manufacturing clusters. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Inflammatory Markers Market
Diagnostics
Poultry Diagnostics Market
Diagnostics
Cancer IVD Market
Diagnostics
Mycoplasma Detection System Market
Diagnostics
In Vitro Diagnostics (IVD) Quality Control Market
Diagnostics
Vision Screeners Market
Diagnostics
Hepatitis Test Solution and Diagnosis Market
Diagnostics
Multiplexed Diagnostics Market
Diagnostics
Asia-Pacific Syndromic Multiplex Diagnostic Market
Diagnostics
North America Molecular Diagnostics Market
Diagnostics
United States Melanoma Diagnostics & Therapeutics Market
Diagnostics
Asia-Pacific Radioimmunoassay Market
Diagnostics
Europe Colorectal Cancer Diagnostics Market
Diagnostics
Antigen Kit Market
Diagnostics
Glaucoma Diagnostics Market
Diagnostics
North America Antinuclear Antibody Test Market