
 Cellular Health Screening Market | 2026-2036
Cellular Health Screening Market Size, Share, and Industry Trends Forecast 2026-2036
Cellular Health Screening Market Intelligence
The EU Green Deal is repositioning European demand toward biomarker panels that quantify cellular aging and metabolic resilience for occupational health programs. Quest Diagnostics leverages its national laboratory network to sustain high-throughput processing of oxidative stress assays. Genova Diagnostics specializes in functional medicine panels that anchor its position among integrative health practitioners. SpectraCell Laboratories controls niche expertise in intracellular micronutrient testing, differentiating through patented lymphocyte proliferation technology.
Cellular health screening encompasses laboratory and point-of-care analyses that quantify biomarkers of oxidative stress, telomere length, mitochondrial function, and intracellular nutrient status, typically requiring venous blood draw or buccal swab collection with controlled temperature handling and 24-72 hour analytical turnaround. Its primary commercial purpose is enabling early detection of subclinical dysfunction before disease manifestation, thereby supporting preventive interventions and personalized treatment protocols. Blood test formats dominate current volume due to established clinical validation and reimbursement familiarity, while saliva test adoption accelerates among home users seeking non-invasive collection convenience. Flow cytometry occupies the premium technology tier for multiparameter immune profiling, whereas PCR-based telomere analysis represents the fastest-expanding segment driven by longevity medicine demand.
FDA oversight of laboratory-developed tests shapes validation requirements and commercialization timelines for domestic manufacturers, while the EU's In Vitro Diagnostic Regulation (IVDR) imposes new conformity assessment burdens on CE-marked products entering European markets. CLIA certification requirements administered by CMS govern analytical quality standards for clinical laboratories processing cellular health specimens across the United States. Stakeholders must monitor evolving payer coverage determinations for preventive biomarker panels as Medicare Advantage plans and self-insured employers recalibrate benefit designs around measurable health outcomes.
Market Dynamics
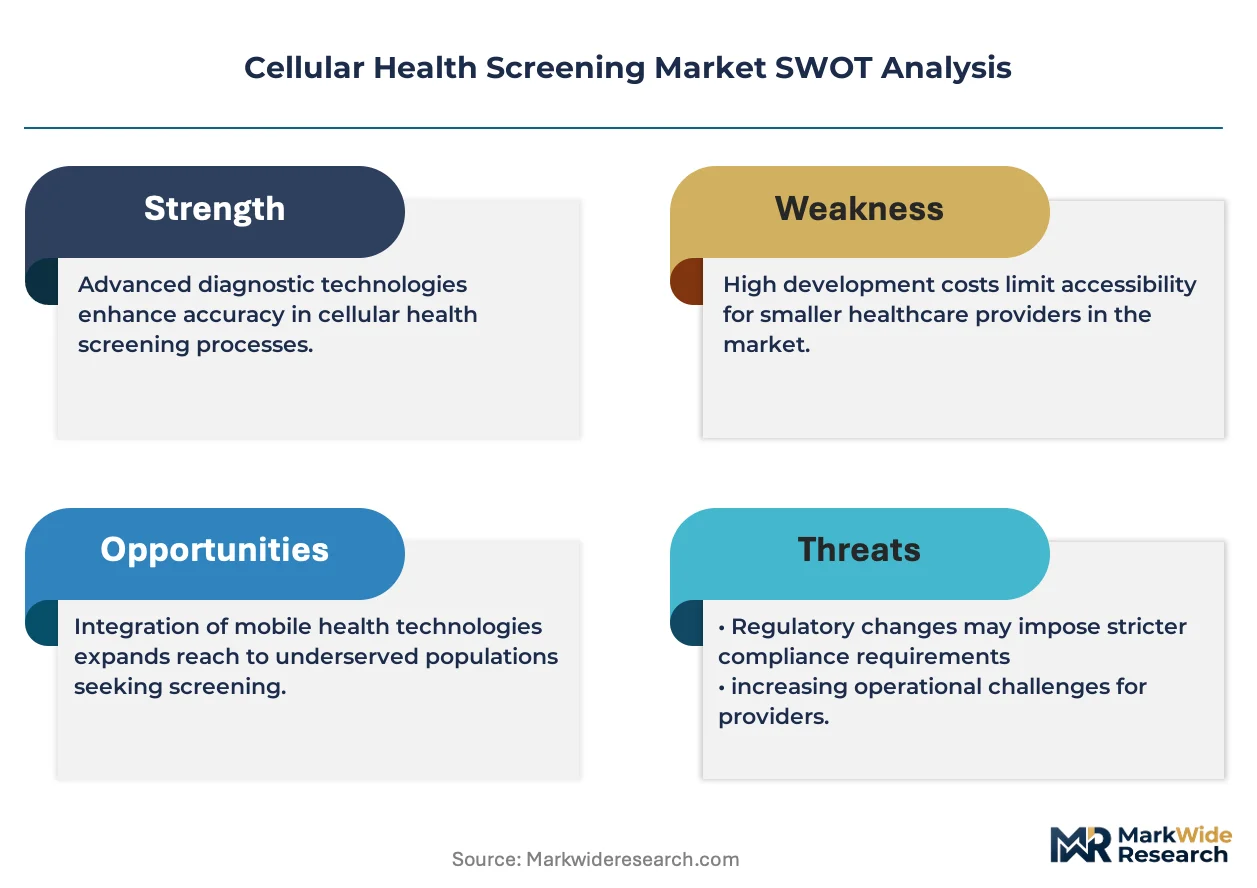
Corporate wellness programs are consolidating purchasing power around validated biomarker panels, compressing vendor margins while elevating analytical quality standards for oxidative stress and telomere length assays.
Growth Catalysts
- Employer-Sponsored Preventive Benefits:Self-insured corporations in the United States are expanding coverage for subclinical dysfunction detection, creating guaranteed volume for CLIA-certified laboratories processing cellular health specimens.
- EU Green Deal Biomarker Mandates:European occupational health programs are integrating cellular aging metrics into workforce resilience protocols, opening public procurement channels for metabolic resilience panels.
- PCR-Based Telomere Analysis:Longevity medicine clinics are adopting high-throughput polymerase chain reaction methods for telomere length quantification, accelerating test standardization and reimbursement familiarity.
Market Restraints
- IVDR Conformity Assessment Burden:The European Union's In Vitro Diagnostic Regulation imposes extended validation timelines and notified body bottlenecks on CE-marked products entering European markets.
- Venous Blood Draw Cold Chain Requirements:Temperature-controlled specimen handling from collection site to analytical laboratory adds logistical cost and geographic service radius constraints.
- Salivary Biomarker Substitution:Non-invasive buccal swab collection methods are capturing home-user segments, threatening volume retention for blood-draw-dependent laboratory networks.
Strategic Opportunities
- Medicare Advantage Outcome-Based Contracts:Preventive biomarker panel coverage determinations are recalibrating around measurable health outcomes, creating reimbursement precedent for functional medicine practitioners.
- Flow Cytometry-PCR Convergence:Multiparameter immune profiling platforms are integrating with telomere analysis workflows, enabling single-specimen comprehensive cellular health assessments.
- Direct-to-Consumer Channel Expansion:Home collection kits with telehealth result consultation are penetrating underpenetrated employer segments without on-site wellness infrastructure.
Industry Challenges
- CLIA Certification Talent Scarcity:Clinical laboratory directors with subspecialty expertise in lymphocyte proliferation assays command premium compensation, constraining laboratory expansion timelines.
- FDA Laboratory-Developed Test Validation Uncertainty:Evolving oversight frameworks for LDTs create compliance timeline risk and capital allocation hesitation for domestic test developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cellular Health Screening Market |
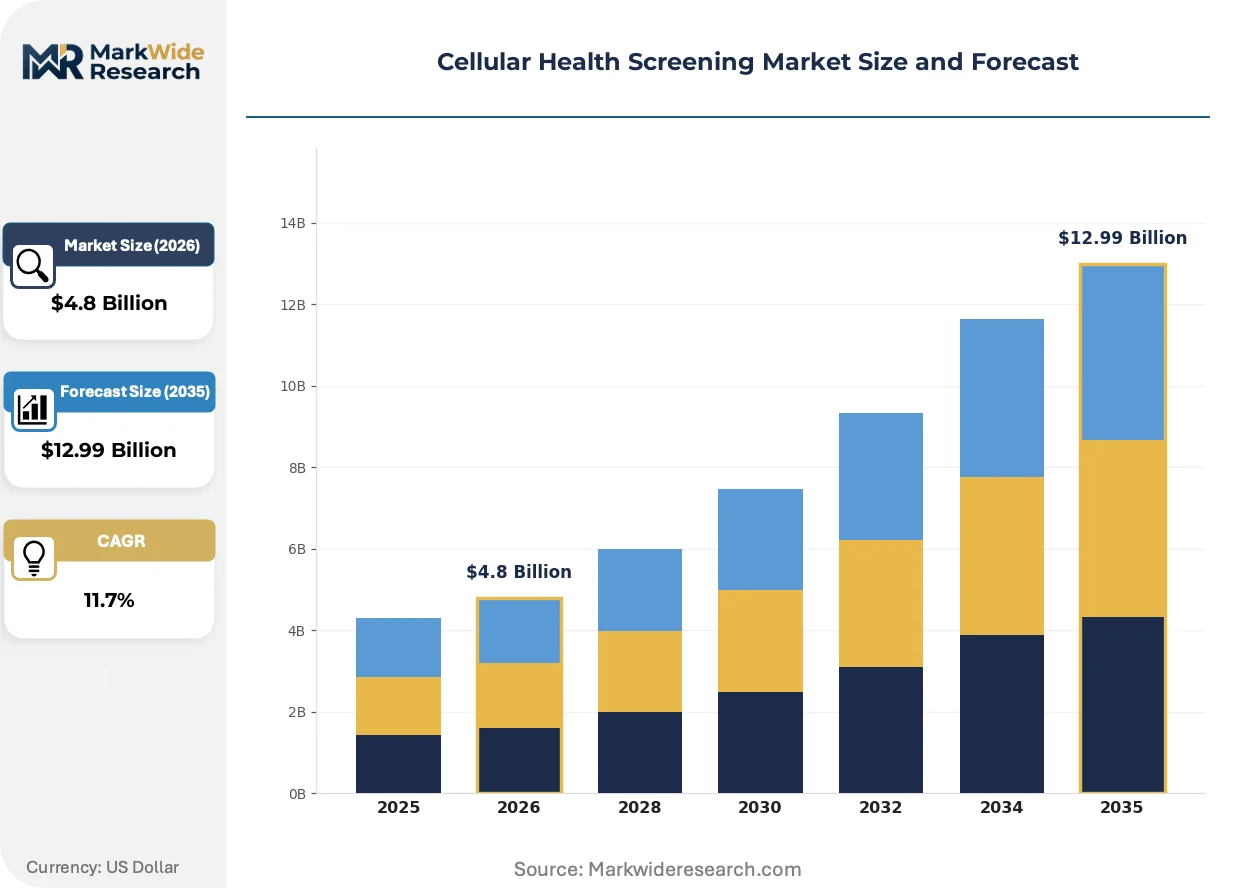
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blood Test, Urine Test, Saliva Test, Tissue Sample Technology: Flow Cytometry, PCR, ELISA, Mass Spectrometry Application: Preventive Health, Diagnostics, Research, Wellness End User: Hospitals, Clinics, Laboratories, Home Users |
| Companies Covered | Quest Diagnostics, Genova Diagnostics, SpectraCell Laboratories, Telomere Diagnostics, Life Length, Cell Science Systems, Laboratory Corporation of America Holdings, Immundiagnostik AG, Repeat Diagnostics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cellular Health Screening Market Strategic Shifts & Innovations
Longevity medicine demand is compressing analytical turnaround expectations while elevating multiplexing requirements, forcing technology convergence across previously discrete biomarker categories.
Flow cytometry platforms are consolidating multiparameter immune profiling capabilities with oxidative stress quantification, enabling simultaneous measurement of mitochondrial function and intracellular micronutrient status from single specimens. Functional medicine clinics and integrative health practitioners are adopting these integrated systems to reduce patient venipuncture frequency. This consolidation is compressing the addressable market for standalone assay providers while rewarding laboratories with captive lymphocyte proliferation technology.
The EU Green Deal is repositioning biomarker panel demand toward occupational health applications, with member state occupational safety regulators incorporating cellular aging metrics into workforce monitoring protocols. Industrial consequence includes mandatory periodic health surveillance contracts for hazardous exposure sectors. Manufacturing and chemical processing employers in Germany, France, and the Netherlands are responding by pre-qualifying laboratory vendors with IVDR-compliant metabolic resilience panels.
Home collection convenience preferences are fragmenting traditional laboratory referral patterns, with saliva test adoption accelerating among individual consumers seeking privacy and reduced clinic visitation. Direct-to-consumer platforms with telehealth-integrated result interpretation are displacing physician-mediated ordering in wellness-focused segments. This channel disintermediation is most visible in United States metropolitan markets with established employer-sponsored preventive health benefit saturation.
Cellular Health Screening Market Segmentation
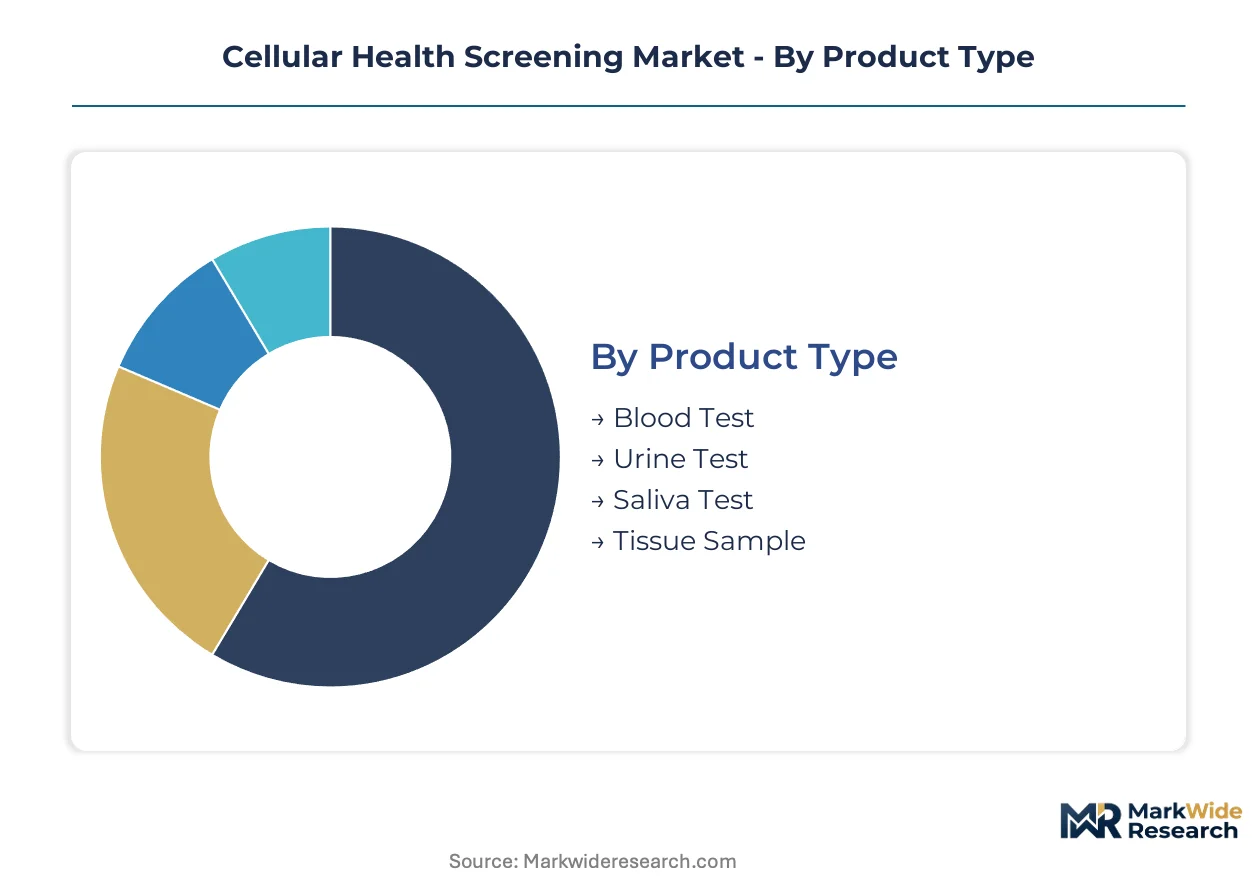
Segmentation in cellular health screening reveals divergent technical requirements between clinical-grade laboratories and home-collection consumers. Product format, analytical technology, and end-user setting each impose distinct validation, logistics, and reimbursement constraints that reshape vendor positioning.
Product Type:
Collection method selection hinges on analyte stability requirements versus patient compliance tradeoffs, with venous blood maintaining analytical superiority for oxidative stress quantification.
- Blood Test:Venous draws enable gold-standard quantification of intracellular micronutrients and mitochondrial function markers through lymphocyte proliferation assays. Demand concentrates in United States employer-sponsored wellness programs where CLIA-certified laboratory networks process high-throughput oxidative stress panels under temperature-controlled logistics.
- Saliva Test:Non-invasive buccal swab collection captures telomere length and cortisol rhythm data with reduced patient burden. Adoption accelerates among United States metropolitan home users seeking privacy and telehealth-integrated result interpretation without clinic visitation.
- Urine Test:Metabolite excretion patterns support oxidative damage assessment and nutrient sufficiency indexing through 24-hour collection protocols.
- Tissue Sample:Biopsy-derived specimens enable direct mitochondrial density measurement in functional medicine research settings.
Blood test leads on scale; saliva test leads on momentum.
Technology:
Analytical platform selection reflects the tension between multiplexing depth and throughput economics, with longevity medicine clinics demanding faster turnaround on comprehensive panels.
- PCR:Polymerase chain reaction methods deliver high-throughput telomere length quantification with standardized reproducibility across laboratory networks. Longevity medicine clinics in the United States are adopting PCR-based workflows to compress analytical turnaround while maintaining analytical precision for patient monitoring protocols.
- Flow Cytometry:Multiparameter immune profiling platforms simultaneously measure oxidative stress, mitochondrial membrane potential, and intracellular nutrient status from single specimens. Functional medicine practitioners favor these integrated systems to reduce patient venipuncture frequency and consolidate billing codes.
- ELISA:Enzyme-linked immunosorbent assays provide cost-accessible entry points for single-analyte oxidative stress markers in smaller clinical laboratories.
- Mass Spectrometry:High-resolution metabolomic profiling identifies novel cellular dysfunction signatures in academic research collaborations.
PCR leads on momentum; flow cytometry leads on analytical integration depth.
Application:
Use-case segmentation separates reimbursable clinical indications from discretionary wellness spending, with preventive health commanding the largest addressable base.
- Preventive Health:Subclinical dysfunction detection enables intervention before disease manifestation, supporting personalized treatment protocols. United States self-insured corporations are expanding coverage for these panels, creating guaranteed volume for CLIA-certified laboratories processing cellular aging biomarkers under outcome-based contracts.
- Wellness:Lifestyle optimization applications target health-conscious consumers seeking longevity-focused biomarker tracking. Direct-to-consumer platforms with home collection kits are penetrating this segment through telehealth-integrated result consultation in United States metropolitan markets with established preventive benefit saturation.
- Diagnostics:Disease-adjacent screening supports early-stage condition monitoring in integrative health practice settings.
- Research:Academic and pharmaceutical investigations employ cellular health panels for mechanism-of-action studies and biomarker discovery.
Preventive health leads on scale; wellness leads on channel innovation velocity.
End User:
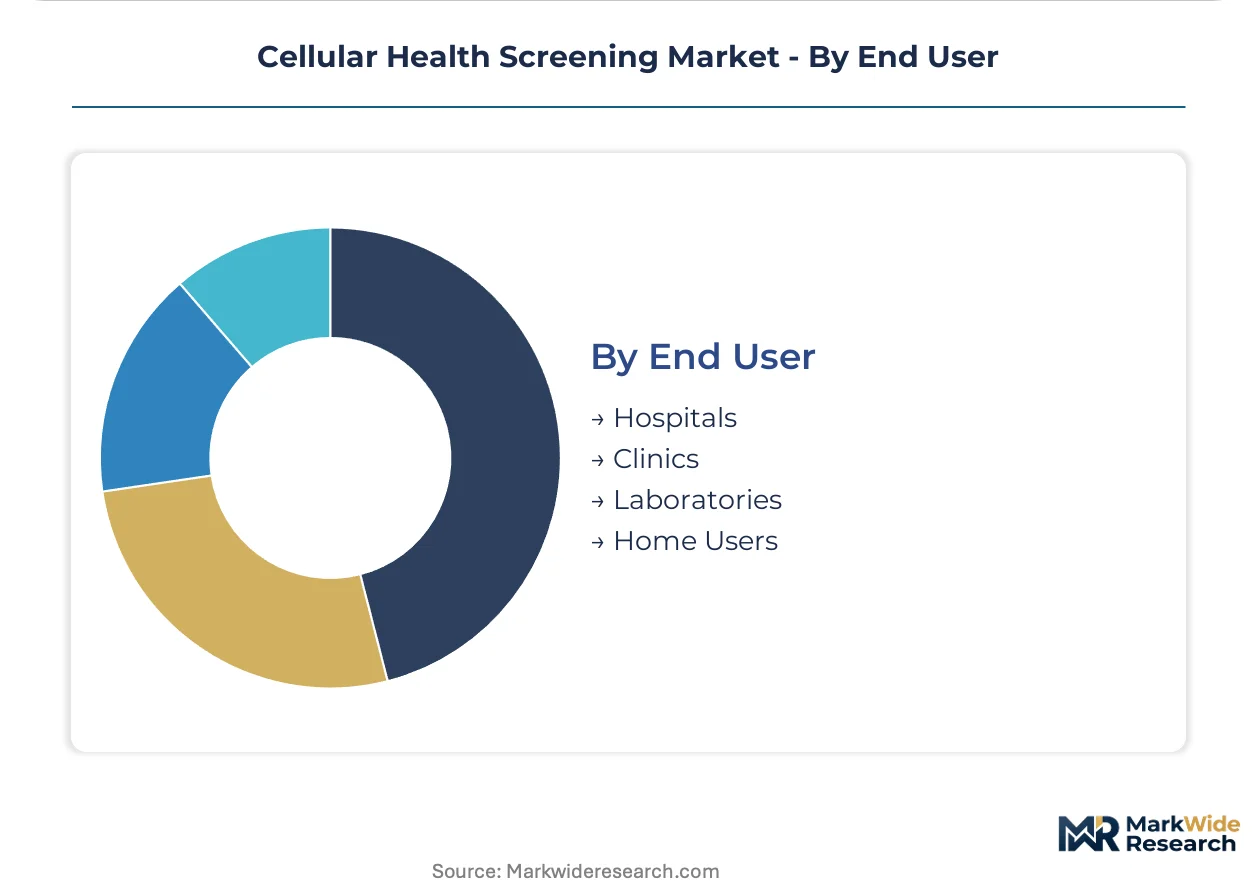
Customer-type segmentation exposes divergent procurement authority, with hospital systems consolidating purchasing power around validated panels while home users fragment across direct-to-consumer platforms.
- Laboratories:CLIA-certified reference laboratories anchor the value chain through high-throughput processing of oxidative stress and telomere length assays. Quest Diagnostics leverages its national United States network to sustain volume leadership in employer-sponsored wellness program contracts.
- Home Users:Individual consumers bypass physician-mediated ordering through direct-to-consumer platforms offering privacy-protected collection and telehealth interpretation. This channel is expanding fastest in United States urban corridors with dense employer wellness infrastructure and established digital health adoption.
- Hospitals:Acute care systems integrate cellular health panels into pre-operative optimization and chronic disease management protocols.
- Clinics:Functional medicine and integrative health practices anchor demand for comprehensive micronutrient and mitochondrial function assessments.
Laboratories lead on scale; home users lead on growth trajectory steepness.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The cellular health screening industry traces its commercial origins to specialized diagnostic laboratories in the United States, where employer-sponsored preventive health benefits first created sustained reimbursement pathways for oxidative stress and telomere length assays during the early 2000s.
United States
Self-insured corporations and Medicare Advantage plans drive demand for CLIA-certified laboratory networks processing high-throughput cellular aging panels. FDA oversight of laboratory-developed tests shapes validation requirements for domestic test developers. The Boston-Cambridge corridor anchors functional medicine research collaborations, while Quest Diagnostics sustains national volume leadership through its employer wellness program contracts.
Germany
Manufacturing and chemical processing employers are pre-qualifying IVDR-compliant laboratory vendors for mandatory occupational health surveillance under EU Green Deal workforce resilience protocols. The country's national pharmaceutical regulator enforces extended conformity assessment timelines for CE-marked diagnostic products. The Rhine-Ruhr industrial cluster generates concentrated demand for metabolic resilience screening in hazardous exposure sectors.
United Kingdom
Integrative health practitioners in private clinical settings anchor demand for comprehensive micronutrient and mitochondrial function assessments. The Medicines and Healthcare products Regulatory Agency aligns with EU IVDR requirements for post-Brexit market access. London's Harley Street medical district concentrates functional medicine clinic density, driving adoption of flow cytometry-integrated cellular health platforms.
Japan
Longevity medicine clinics are adopting PCR-based telomere analysis workflows to compress analytical turnaround for aging population monitoring. The Pharmaceuticals and Medical Devices Agency governs in vitro diagnostic quality standards for clinical laboratory accreditation. The Tokyo-Osaka corridor hosts the highest concentration of preventive health screening centers offering cellular aging biomarker panels.
Australia
Telehealth-integrated direct-to-consumer platforms are penetrating metropolitan markets with home collection kits for telomere length and cortisol rhythm assessment. The Therapeutic Goods Administration regulates laboratory-developed test commercialization timelines for domestic manufacturers. Sydney and Melbourne anchor digital health adoption clusters where privacy-protected cellular health screening bypasses traditional physician-mediated ordering.
Cellular Health Screening Market Key Industry Players
Premium-margin players sit above commodity-margin players across analytical integration depth and lymphocyte proliferation technology ownership. National reference laboratories with captive high-throughput networks command pricing power in employer-sponsored wellness contracts, while specialized functional medicine panel providers defend position through practitioner relationship density. Three archetypes dominate: scale-driven diagnostic conglomerates with CLIA-certified national networks, technology specialists with patented lymphocyte proliferation or flow cytometry platforms, and direct-to-consumer platforms with telehealth-integrated result interpretation. Consolidation pressure is elevating through laboratory network acquisitions and technology licensing arrangements for multiplexed biomarker quantification.
Within the reference laboratory tier, Quest Diagnostics and Laboratory Corporation of America Holdings exemplify scale-driven consolidation archetypes with national specimen processing infrastructure. Genova Diagnostics occupies a position among integrative health practitioners through functional medicine panel specialization. SpectraCell Laboratories anchors the technology-specialist vector with lymphocyte proliferation assay expertise.
| Leading Market Players |
|---|
| Quest Diagnostics |
| Genova Diagnostics |
| SpectraCell Laboratories |
| Telomere Diagnostics |
| Life Length |
| Cell Science Systems |
| Laboratory Corporation of America Holdings |
| Immundiagnostik AG |
| Repeat Diagnostics |
| Others |
Cost & Logistics Intelligence
Reagent-grade chemical pricing indices cascade through cellular health screening supply chains, compressing margins for high-throughput oxidative stress assay providers while amplifying pricing power for laboratories with captive lymphocyte proliferation technology and temperature-controlled logistics infrastructure.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by analytical integration depth and certification grade. Flow cytometry-integrated panels with CLIA-certified laboratory networks command premium positioning, while single-analyte ELISA entry points face cost compression from salivary biomarker substitution. Employer-sponsored wellness programs exhibit lowest price sensitivity due to outcome-based contract structures, whereas direct-to-consumer home collection kits compete intensely on per-test accessibility.
Supply Chain Analysis
Domestic-content mandates for critical laboratory reagents are reshaping sourcing patterns across the United States, Germany, and Japan. Polymerase chain reaction primers, fluorescence-activated cell sorting antibodies, and lymphocyte culture media draw from concentrated biotechnology manufacturing clusters in the Boston-Cambridge corridor and Rhine-Ruhr industrial zone. Single-source vulnerability in temperature-controlled specimen logistics creates structural risk for rural service radius expansion. Distribution runs through national reference laboratory networks with regional specimen processing hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cellular health screening offers margin expansion through automation-driven cost compression in high-throughput oxidative stress processing and premium-tier consolidation around flow cytometry-PCR convergence platforms.
For Market Incumbents: Deepen captive lymphocyte proliferation technology ownership to defend against salivary biomarker substitution threats. Consolidate regional specimen processing capacity in United States metropolitan corridors with dense employer wellness infrastructure. Invest in IVDR conformity assessment pre-certification for European occupational health procurement channels.
For New Entrants and Emerging Players: Launch via telehealth-integrated direct-to-consumer platforms targeting underpenetrated employer segments without on-site wellness infrastructure. White-space opportunity concentrates in Medicare Advantage outcome-based contracting and Australian metropolitan digital health adoption clusters. Differentiate through home collection kit convenience with privacy-protected result interpretation.
For Investors and Strategic Acquirers: Asymmetric upside sits with technology specialists possessing patented flow cytometry platforms and established integrative health practitioner relationships. Long-term viability hinges on regulatory navigation capability across FDA laboratory-developed test frameworks and EU IVDR transition timelines. Watch for CLIA-certified laboratory network acquisition activity as consolidation inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Flow Cytometry-PCR Platform Integration | Consolidates multiparameter immune profiling with telomere analysis for single-specimen comprehensive assessment. |
| CLIA Certification Expansion | Extends high-throughput processing capacity for employer-sponsored wellness program contract capture. |
| IVDR Conformity Pre-Assessment | Accelerates European market access for metabolic resilience panels under EU Green Deal procurement. |
| Telehealth-Integrated DTC Launch | Penetrates privacy-seeking home user segments without physician-mediated ordering friction. |
| Lymphocyte Proliferation Technology Licensing | Captures functional medicine practitioner loyalty through patented intracellular micronutrient testing differentiation. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with CLIA-certified laboratory directors, functional medicine practitioners, employer benefits managers, and diagnostic reagent procurement specialists with secondary validation against FDA 510(k) filings, CMS laboratory certification databases, EU IVDR notified body registers, and hospital GPO contract repositories. Bottom-up specimen volume modeling and top-down revenue triangulation anchored market size estimation.
Comparable-period anchoring tied projection trajectories to historical employer wellness program adoption curves and longevity medicine clinic expansion patterns across the analysis window. Segmentation dimensions spanned collection method, analytical technology, application use-case, and end-user procurement authority. CAGRs derived from regression-adjusted trend extrapolation incorporating PCR-based telomere analysis standardization velocity and Medicare Advantage preventive benefit recalibration.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA laboratory-developed test enforcement shifts and EU notified body capacity constraints. Assumptions reflect current regulatory frameworks and reimbursement pathways. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Mycology Immunoassays Testing Market
Diagnostics
Blood Culture Media Market
Diagnostics
Glucose Biosensors Market
Diagnostics
Canada Latent Tuberculosis Infection Detection Market
Diagnostics
Hepatitis E Diagnostic Tests Market
Diagnostics
Blood Glucose Testing Devices Market
Diagnostics
Europe in Vitro Diagnostics (IVD) Market
Diagnostics
Clostridium Diagnostics Market
Diagnostics
Global Oral Cancer Rapid Test Kit Market
Diagnostics
Global Chemiluminescence Immunoassay (CLIA) Market
Diagnostics
E.Coli Latex Agglutination Test Kits Market
Diagnostics
Cancer Tissue Diagnostics Market
Diagnostics
US Prostate Cancer Nuclear Medicine Diagnostics Market
Diagnostics
Cancer IVD Market
Diagnostics
Global Predictive Genetic Testing and Consumer/Wellness Genomics Market
Diagnostics
Immunoassay Interference Blocker Market