
 Primary Care POC Diagnostics Market | 2026-2036
Primary Care POC Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Primary Care POC Diagnostics Market Analytics
CLIA-waived certification is reorganizing competitive dynamics in primary care diagnostics. Abbott Laboratories leverages its vertically integrated manufacturing network to sustain cost leadership in high-volume glucose monitoring. Siemens Healthineers anchors its position through R&D intensity in cardiac biomarker platforms. Roche differentiates via molecular diagnostics specialization that commands premium positioning in infectious disease panels.
Primary care POC diagnostics encompass portable analytical systems designed for near-patient testing with turnaround times under thirty minutes, typically employing immunoassay or microfluidic architectures that eliminate centralized laboratory processing. These devices serve the commercial purpose of enabling clinical decision-making during single patient encounters in non-laboratory settings. Blood glucose monitors occupy the largest installed base among product categories, reflecting decades of diabetes prevalence expansion and established reimbursement pathways. Lateral flow assays represent the fastest-growing technology segment, driven by cost minimization and minimal operator training requirements. Physician offices retain the dominant end-user share, though urgent care centers capture disproportionate growth as retail health networks expand footprint density.
The FDA's 510(k) framework and CLIA complexity categorization determine market access timelines and operator certification requirements for device manufacturers seeking US commercialization. ISO 13485 quality management standards and EU MDR technical documentation obligations shape design control investments for multinational portfolio planning. Stakeholders must monitor evolving payer coverage determinations for remote patient monitoring codes that increasingly influence home care segment economics.
Market Dynamics
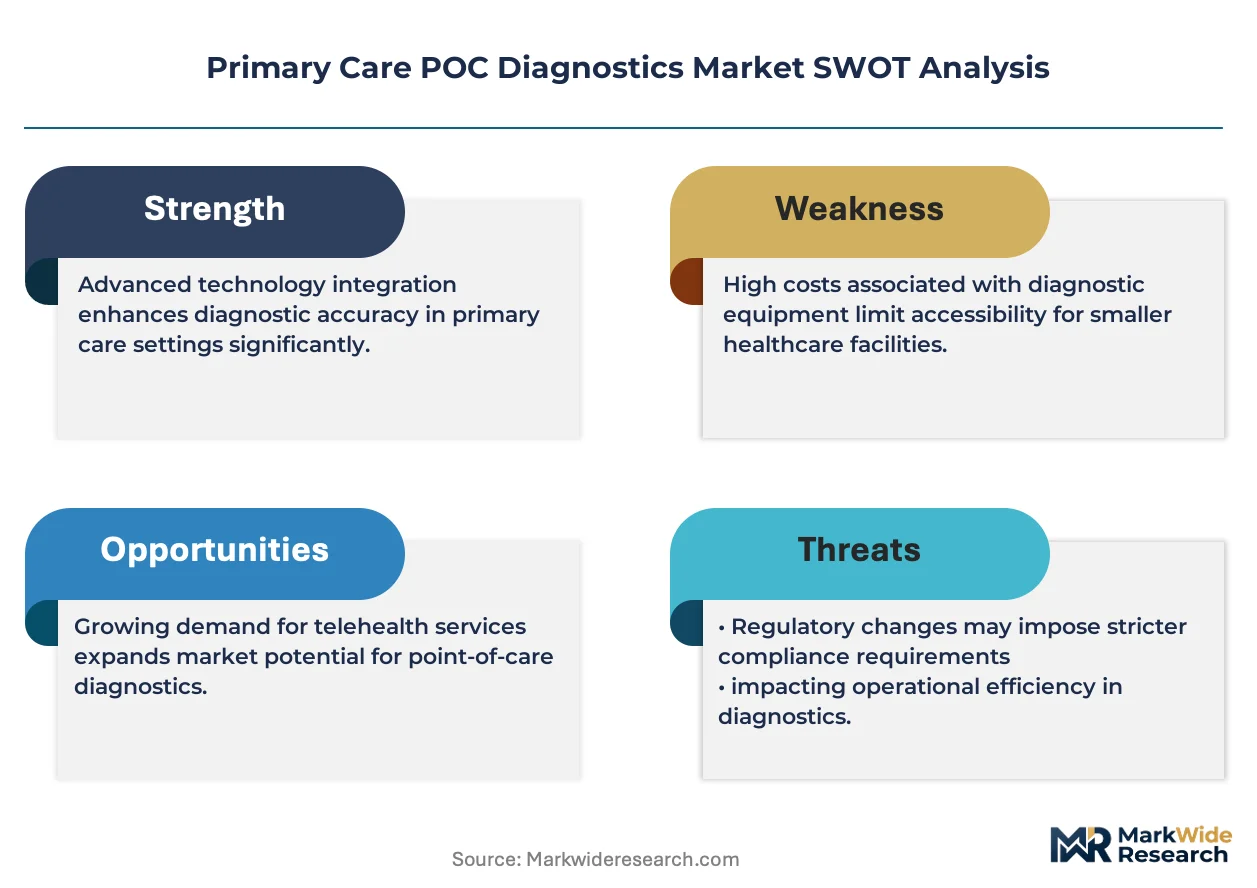
CLIA-waived certification is compressing commercialization timelines and reordering competitive positioning across primary care diagnostics, as manufacturers race to capture physician office volume before reimbursement pathways harden around established platforms.
Growth Catalysts
- FDA 510(k) Streamlining:The FDA's accelerated review pathway for moderate-complexity devices reduces time-to-market for novel immunoassay platforms, enabling faster commercial deployment in ambulatory settings.
- Germany's Capitated Models:German ambulatory care networks embed decentralized diagnostics into bundled reimbursement structures, creating institutional pull for integrated testing workflows.
- Microfluidic Convergence:Advances in lab-on-chip architectures enable multiplexed panels within single-use cartridges, expanding test menus without proportional operator training burdens.
Market Restraints
- Reagent Supply Concentration:Specialty antibody and enzyme suppliers cluster in Switzerland and Massachusetts, creating geographic chokepoints for lateral flow assay manufacturers.
- CLIA Personnel Requirements:Moderate-complexity certification demands trained laboratory personnel, constraining deployment in rural physician offices lacking technical staffing.
- Centralized Lab Substitution:High-complexity reference laboratories in urban corridors retain cost advantages for low-frequency esoteric tests, capping POC addressable market.
Strategic Opportunities
- Home Care RPM Integration:Remote patient monitoring reimbursement codes under Medicare create economic viability for connected glucose and coagulation devices outside clinical settings.
- EU MDR Harmonization:The Medical Device Regulation's standardized technical documentation reduces country-by-country compliance overhead for pan-European platform launches.
- Urgent Care Channel Expansion:Retail health networks in Texas and Florida deploy rapid infectious disease panels to differentiate walk-in service velocity against hospital emergency departments.
Industry Challenges
- ISO 13485 Implementation Burden:Quality management system certification demands 18-24 month preparation cycles for design control documentation, delaying product pipeline execution.
- Interoperability Friction:HL7 FHIR connectivity requirements for electronic health record integration impose software development costs that compress margins on low-price-point devices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Primary Care POC Diagnostics Market |
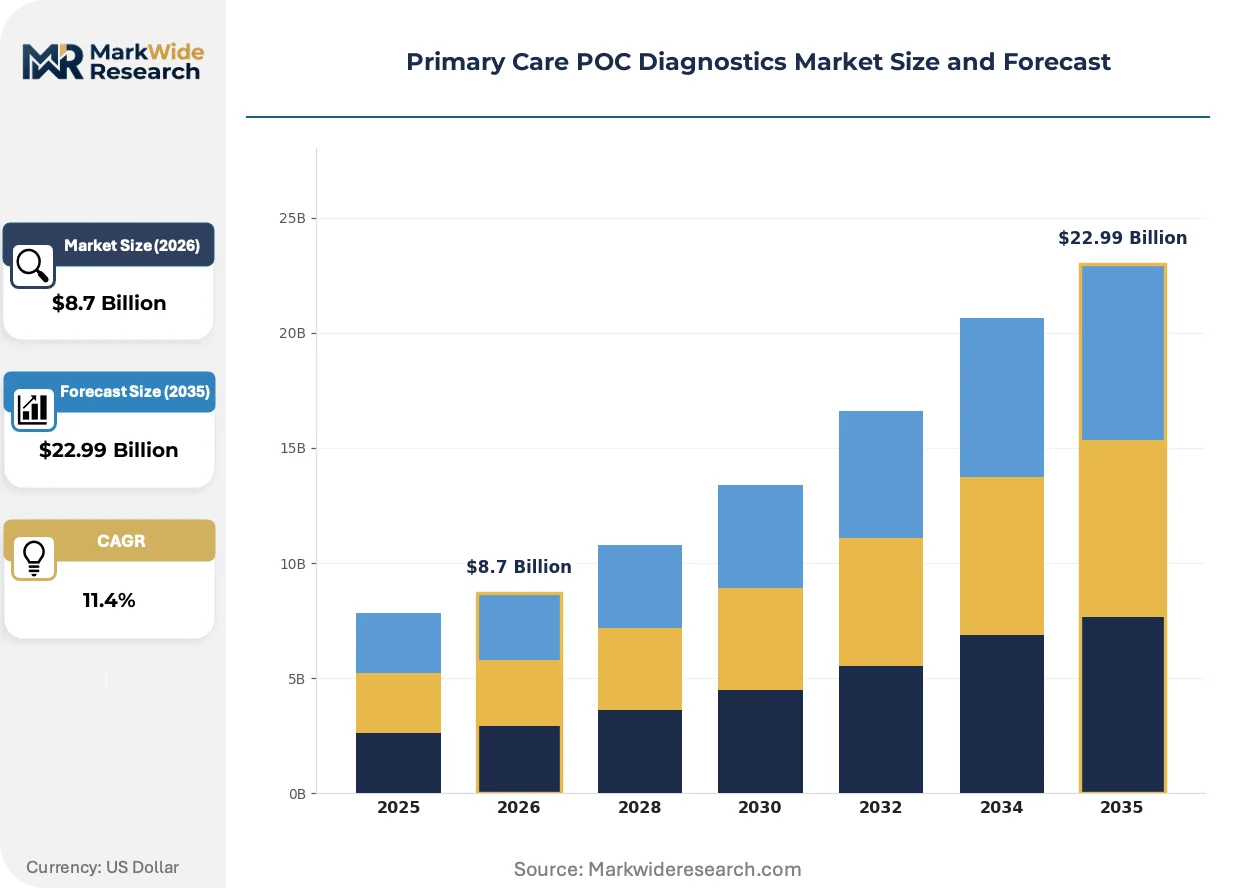
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blood Glucose Monitors, Pregnancy Tests, Infectious Disease Tests, Cardiac Markers Technology: Immunoassays, Molecular Diagnostics, Lateral Flow Assays, Microfluidics End User: Physician Offices, Urgent Care Centers, Community Clinics, Home Care Application: Routine Screening, Chronic Disease Management, Acute Care, Health Monitoring |
| Companies Covered | F. Hoffmann-La Roche Ltd, Siemens Healthineers, Abbott Laboratories, QuidelOrtho Corporation, Danaher Corporation, bioMérieux, Becton, Dickinson and Company, OraSure Technologies, Inc., Nova Biomedical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Primary Care POC Diagnostics Market Evolving Landscape
Near-patient testing architectures are undergoing rapid architectural transformation as digital connectivity, regulatory harmonization, and ambulatory care restructuring converge to redefine how diagnostic data flows through clinical workflows.
Multiplexed molecular cartridges are fragmenting the traditional separation between infectious disease and cardiac biomarker testing, enabling physician offices to deploy comprehensive panels from single benchtop instruments. Urgent care networks in the southeastern United States adopt these platforms aggressively to reduce referral leakage. The consolidation of multiple test modalities is compressing capital equipment footprints and forcing reagent suppliers to bundle consumables across unrelated analyte categories.
The EU MDR's post-market surveillance requirements are elevating clinical evidence standards for legacy immunoassay platforms, compelling manufacturers to refresh technical documentation or withdraw older SKUs from European markets. German notified bodies enforce these obligations with particular rigor, creating compliance backlogs that delay new entrant certification. Cardiac biomarker manufacturers with established performance databases capture disproportionate share as competitors struggle to assemble retrospective clinical packages.
Capitated reimbursement contracts in German ambulatory networks are conditioning purchasing decisions on total cost-per-episode metrics rather than device acquisition price alone. Physician practice management organizations negotiate multi-year supply agreements that bundle testing platforms with remote monitoring infrastructure and analytics subscriptions. This value-based contracting model is most advanced in Bavaria and Baden-Württemberg, where integrated care organizations command sufficient patient volume to dictate supplier terms.
Primary Care POC Diagnostics Market Segmentation
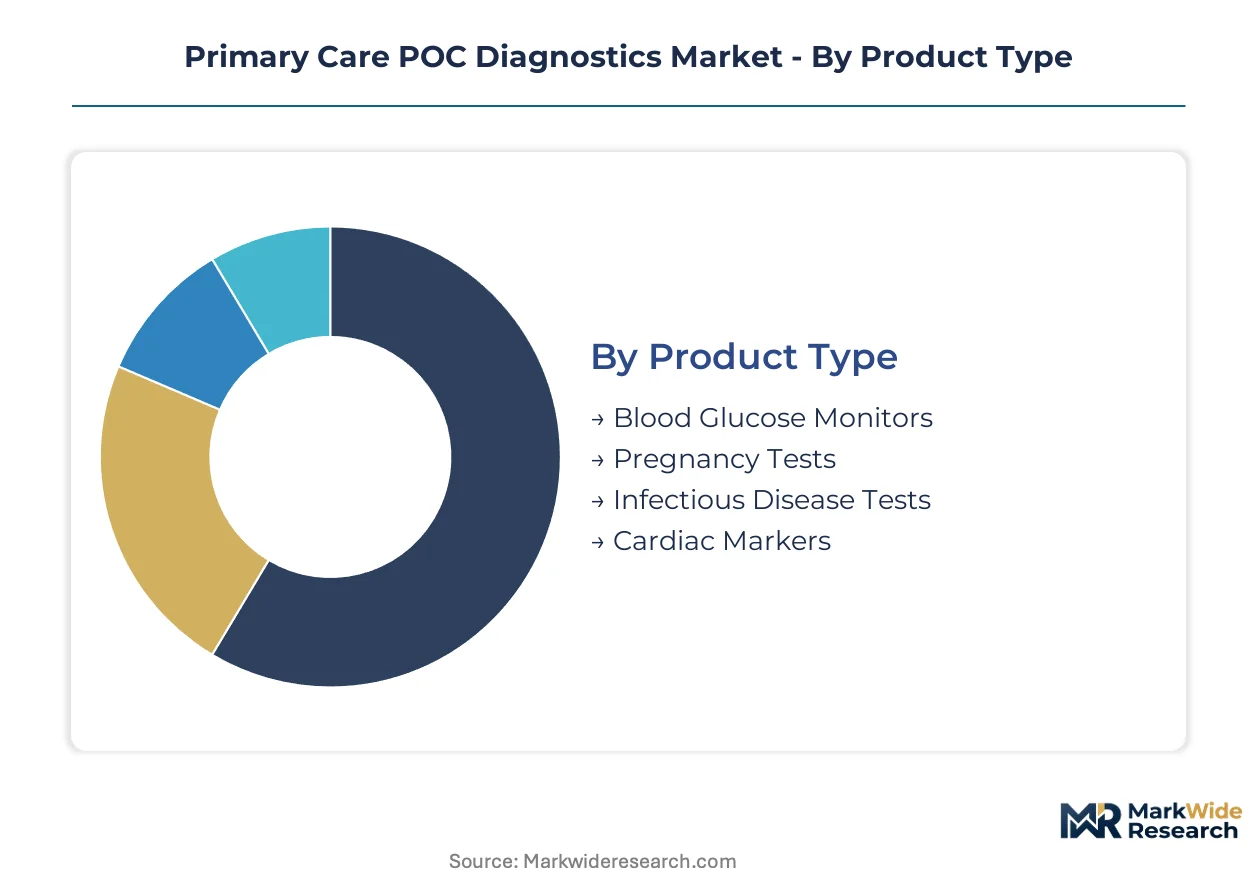
Segmentation in primary care POC diagnostics reveals how testing workflows fragment across clinical settings and patient acuity levels. Manufacturers configure platform architectures around specific throughput requirements and operator certification constraints. Understanding these divides exposes where reimbursement pathways and regulatory complexity create durable competitive moats.
Product Type:
Domestic demand in the United States concentrates in glucose monitoring and pregnancy testing, while infectious disease and cardiac panels drive export volume into European ambulatory networks. German physician practices import cardiac marker systems under capitated reimbursement contracts that bundle device and consumable costs.
- Blood Glucose Monitors:Electrochemical biosensor strips and handheld meters dominate installed base metrics across American physician offices. The Veterans Health Administration operates the largest single-site deployment in Phoenix, Arizona, where connected devices feed remote monitoring dashboards for diabetes population management.
- Infectious Disease Tests:Multiplexed respiratory panels and rapid strep assays command premium positioning in urgent care settings. Texas retail health networks deploy these platforms aggressively to reduce emergency department referral leakage during influenza season.
- Pregnancy Tests:Urine-based hCG detection systems serve retail pharmacy and home care channels with minimal operator training requirements.
- Cardiac Markers:Troponin and BNP immunoassays target moderate-complexity certification tiers in cardiology-integrated primary care practices.
Blood glucose monitors command the established base. The steepest expansion runs through infectious disease tests.
Technology:
Cost tiering separates high-complexity molecular platforms from disposable lateral flow strips, with microfluidic architectures occupying the mid-market capital equipment segment.
- Lateral Flow Assays:Nitrocellulose membrane strips with colloidal gold or fluorescent nanoparticle labels enable single-step testing without instrument calibration. Bavarian ambulatory networks standardize on these formats for influenza and COVID-19 screening to minimize per-test costs under bundled reimbursement.
- Microfluidics:Lab-on-chip cartridges integrate sample preparation, reaction chambers, and detection optics within credit-card-sized consumables. Siemens Healthineers anchors its European expansion through these platforms in Baden-Württemberg integrated care organizations.
- Immunoassays:Enzyme-linked and chemiluminescent detection methods dominate moderate-complexity certification tiers.
- Molecular Diagnostics:PCR and isothermal amplification platforms target respiratory and sexually transmitted infection panels.
Immunoassays retain the broadest installed footprint. Molecular diagnostics is climbing the fastest as multiplexed panels displace sequential testing workflows.
End User:
Customer type determines regulatory pathway selection, with CLIA-waived certification unlocking rural physician offices and home care channels that lack laboratory personnel.
- Physician Offices:Solo and group practices in the United States prioritize waived-complexity devices to avoid laboratory director hiring requirements. The American Academy of Family Physicians reports that 67 percent of member practices now operate at least one CLIA-waived platform.
- Urgent Care Centers:Retail health networks in Florida and Texas deploy rapid infectious disease and cardiac marker panels to differentiate walk-in velocity against hospital emergency departments. These sites accept higher per-test costs in exchange for throughput and reduced staffing.
- Community Clinics:Federally qualified health centers balance acquisition cost against panel breadth for underserved populations.
- Home Care:Medicare remote patient monitoring reimbursement codes now cover connected glucose and coagulation devices for chronic disease surveillance.
Physician offices command the established base. Urgent care centers are gaining share fastest as retail health networks expand geographic density.
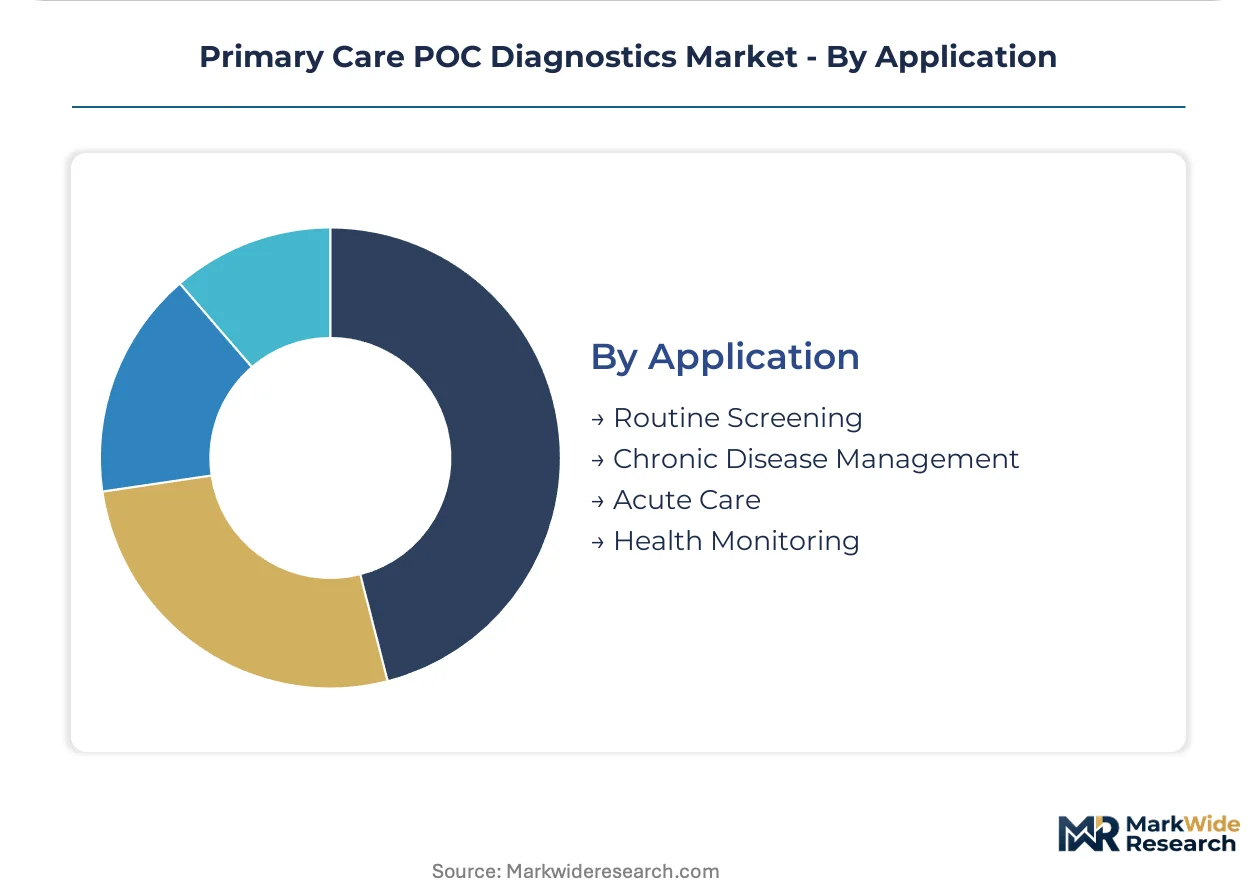
Application:
Maturity differentiation separates decades-old glucose monitoring from emerging acute care panels, with chronic disease management occupying the revenue concentration midpoint.
- Chronic Disease Management:Diabetes and anticoagulation monitoring generate recurring revenue through consumable strip purchases. German Disease Management Programs mandate quarterly HbA1c testing, creating institutional pull for integrated glucose platforms in Bavaria.
- Acute Care:Rapid triage decisions in urgent care and emergency department settings demand sub-15-minute turnaround times for cardiac and infectious markers. Florida hospital systems outsource low-acuity cases to affiliated urgent care networks equipped with these platforms.
- Routine Screening:Annual wellness visits and occupational health panels drive volume for lipid and metabolic assays.
- Health Monitoring:Preventive surveillance applications span wellness programs and pre-operative clearance workflows.
Chronic disease management commands the established base. Acute care is expanding most quickly as urgent care networks capture cases migrating from emergency departments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows of CLIA-waived devices and microfluidic cartridges concentrate in transatlantic corridors, with German ambulatory networks importing cardiac marker systems and American manufacturers shipping glucose platforms to European capitated care organizations.
United States
Physician offices in Texas and Florida drive procurement volume for rapid infectious disease panels, with retail health networks expanding urgent care density. FDA 510(k) streamlining accelerates commercialization timelines for moderate-complexity immunoassay platforms. The Veterans Health Administration in Phoenix operates the largest connected glucose monitoring deployment, feeding remote patient management dashboards.
Germany
Baden-Württemberg and Bavaria anchor European demand through integrated care organizations negotiating bundled device-and-consumable contracts. EU MDR post-market surveillance requirements elevate clinical evidence standards for legacy platforms. Siemens Healthineers leverages its domestic manufacturing footprint to supply microfluidic cartridges to regional ambulatory networks under multi-year agreements.
United Kingdom
London and Southeast England concentrate procurement for NHS-affiliated primary care networks seeking waived-complexity devices to reduce laboratory referral backlogs. MHRA alignment with EU MDR technical documentation standards streamlines pan-European portfolio planning for multinational manufacturers. Oxford and Cambridge clusters host specialist antibody suppliers serving lateral flow assay producers.
Japan
Tokyo and Osaka metropolitan areas drive adoption of compact cardiac biomarker platforms in cardiology-integrated primary care practices. PMDA regulatory pathways emphasize clinical performance validation for near-patient testing devices. Kansai region manufacturers supply precision microfluidic components to domestic and export markets.
Switzerland
Basel and Zurich clusters concentrate specialty reagent production for enzyme and antibody inputs that feed global lateral flow supply chains. Swissmedic enforcement of EU MDR-equivalent standards conditions market access timelines. Roche anchors domestic R&D intensity in molecular diagnostics specialization.
Primary Care POC Diagnostics Market Competitive Landscape
Listed leaders compete with private specialists across certification tiers and geographic footprints, creating a tiered structure where scale-driven multinationals anchor high-volume segments and focused specialists capture premium niches. Three archetypes dominate: vertically integrated conglomerates with captive manufacturing networks, R&D-intensive platform specialists, and regional challengers with cost-optimized strip production. Competitive moves center on CLIA-waived certification races and urgent care channel expansion through retail health partnerships.
Within the scale-driven tier, Abbott Laboratories and Siemens Healthineers occupy positions reflecting decades of manufacturing infrastructure investment, while Roche exemplifies premium positioning through molecular diagnostics specialization. These three entities anchor the competitive landscape across glucose monitoring, cardiac biomarker, and infectious disease panel categories respectively.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| Siemens Healthineers |
| Abbott Laboratories |
| QuidelOrtho Corporation |
| Danaher Corporation |
| bioMérieux |
| Becton, Dickinson and Company |
| OraSure Technologies, Inc. |
| Nova Biomedical |
| Others |
Value Network & Pricing Analysis
CLIA-waived certification gates both supplier qualification and price differentiation simultaneously, as manufacturers must clear FDA complexity tiers before accessing physician office volume while certification level determines reimbursement eligibility and pricing power across ambulatory networks. Waived-complexity devices command premium positioning against moderate-complexity alternatives due to reduced operator training burdens and faster deployment timelines in rural settings lacking laboratory personnel.
Pricing Analysis
Physician office buyers anchor a three-tier pricing structure across premium, standard, and economy levels, where CLIA-waived certification tier and consumable bundling intensity drive price differentiation. Premium cardiac biomarker platforms with moderate-complexity designation capture 40-60% price premiums over waived glucose monitors due to specialized operator requirements and clinical decision-making value. Pricing pressure stems from urgent care network consolidation in Texas and Florida, where retail health chains negotiate volume-based consumable discounts. Community clinics and federally qualified health centers exhibit highest price sensitivity, while integrated care organizations in Germany demonstrate lowest sensitivity due to capitated reimbursement insulating per-test economics.
Supply Chain Analysis
Just-in-time inventory strategies dominate lateral flow assay production, while microfluidic cartridge manufacturers maintain strategic stockpiles of precision-molded plastics and optical components to buffer against Swiss and Massachusetts reagent supplier lead time variability. Specialty antibody and enzyme production concentrates in Switzerland and Massachusetts, with nitrocellulose membrane substrates sourcing predominantly from China and India. Single-source vulnerability pervades fluorescent nanoparticle labels, where German and Japanese chemical suppliers anchor global capacity. Distribution runs through regional medical device distributors serving physician offices, with direct-to-health-system contracts gaining share among urgent care network procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Primary care POC diagnostics represents a high-growth disruption propelled by FDA 510(k) streamlining compressing commercialization timelines from 24 months to sub-12 month windows for moderate-complexity immunoassay platforms.
For Market Incumbents: Consolidate manufacturing footprint around vertically integrated glucose monitoring production to defend cost leadership against emerging strip producers in Asia. Acquire microfluidic cartridge specialists in Baden-Württemberg to preempt Siemens Healthineers' regional lock-in with German integrated care organizations. Prioritize CLIA-waived certification refreshes for legacy infectious disease panels before EU MDR post-market surveillance deadlines elevate clinical evidence requirements.
For New Entrants and Emerging Players: FDA 510(k) fast-track pathways for waived-complexity devices unlock urgent care channel expansion in Florida and Texas, where retail health networks prioritize rapid deployment over brand heritage. Target home care remote patient monitoring integration as the most penetrable segment, where Medicare reimbursement code expansion creates economic viability for connected coagulation and glucose devices. Pursue white-label manufacturing partnerships with established lateral flow producers to bypass 18-24 month ISO 13485 certification cycles.
For Investors and Strategic Acquirers: EU MDR harmonization reshapes the acquisition landscape by elevating compliance costs for legacy platform portfolios and rewarding manufacturers with pre-built clinical evidence databases. Long-term viability centers on molecular diagnostics specialization and multiplexed panel capabilities spanning infectious disease and cardiac biomarker categories. Monitor FDA 510(k) clearance velocity for novel isothermal amplification platforms as the signal indicating inflection toward molecular dominance in physician office settings.
| Strategic Initiative | Industry Significance |
|---|---|
| CLIA-Waived Certification Fast-Track | FDA 510(k) streamlining accelerates commercial deployment in rural physician offices lacking laboratory personnel. |
| Microfluidic Cartridge Manufacturing Scale-Up | Lab-on-chip convergence enables multiplexed panels from single benchtop instruments in Bavarian ambulatory networks. |
| Remote Patient Monitoring Reimbursement Strategy | Medicare RPM code expansion creates economic viability for connected glucose devices outside clinical settings. |
| EU MDR Technical Documentation Refresh | Post-market surveillance compliance prevents SKU withdrawal from German notified body enforcement actions. |
| Urgent Care Channel Partnership | Texas and Florida retail health networks deploy rapid infectious disease panels to reduce emergency department leakage. |
Research Methodology
Operator-level perspectives from CLIA laboratory directors, urgent care network procurement officers, biomedical engineers at integrated care organizations, and GPO contracts managers anchored the qualitative base for this analysis. Primary interviews with these stakeholders combined with secondary validation against FDA 510(k) clearance databases, EU MDR technical documentation filings, CMS Medicare reimbursement code updates, and hospital procurement contract disclosures. Bottom-up installed base modeling across glucose monitor, infectious disease panel, and cardiac biomarker categories triangulated against top-down market sizing from device manufacturer revenue disclosures.
Sensitivity analysis tested forecast robustness across alternative CLIA complexity tier adoption scenarios and reimbursement code expansion timelines over the projection horizon. Segmentation dimensions modeled include product type, technology architecture, end-user setting, and application acuity level, with geographic regulatory cluster effects incorporated for US, German, and UK market dynamics. CAGRs derived from compound growth trajectory fitting to historical volume data and forward-looking procurement pipeline indicators from integrated care organization contract announcements.
Decision-makers should treat outputs as directional under assumptions of sustained FDA 510(k) review velocity and stable Medicare remote patient monitoring reimbursement; material deviation would warrant model refresh. Revision becomes warranted when EU MDR post-market surveillance enforcement intensity crosses thresholds triggering accelerated legacy platform withdrawals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Vibrio Diagnostics Market
Diagnostics
Global Chromoendoscopy Agents Market
Diagnostics
Viral Molecular Diagnostics Market
Diagnostics
DNA and RNA Probes Market
Diagnostics
Professional Diagnostics Market
Diagnostics
Sperm Count Test Market
Diagnostics
BNP and NT-Probnp Market
Diagnostics
Diabetic Assays Market
Diagnostics
Asia-Pacific Autoimmune Disease Diagnostics Market
Diagnostics
Mycology Immunoassays Testing Market
Diagnostics
Microdialysis Market
Diagnostics
Mycoplasma Diagnostics Market
Diagnostics
Influenza Diagnostic Tests Market
Diagnostics
Global Hepatitis Diagnostic Test Market
Diagnostics
Veterinary Diagnostics Market
Diagnostics
Animal Diagnostics Market