
 Mycoplasma Detection System Market | 2026-2036
Mycoplasma Detection System Market Size, Share, and Industry Trends Forecast 2026-2036
Mycoplasma Detection System Market Insights
The FDA's 1993 Points to Consider document on mycoplasma detection in cell substrates is hardening into de facto binding expectations for biologics license applications. Thermo Fisher Scientific Inc. leverages its TaqPath platform dominance to anchor real-time PCR workflows across North American contract manufacturing organizations. Lonza sustains European market presence through integrated biosafety testing services that bundle mycoplasma detection with broader cell-line characterization. Charles River Laboratories competes on geographic reach, operating testing facilities that support just-in-time release decisions for multi-site biopharma production networks.
Mycoplasma detection systems comprise analytical instruments, reagent kits, and software platforms engineered to identify mycoplasma contamination in cell cultures with sensitivity thresholds reaching 10 genome copies per reaction. These systems deploy nucleic acid amplification, enzymatic immunoassay, or mass spectrometric methods to prevent compromised biopharmaceutical batches, gene therapy vectors, and vaccine substrates from advancing through manufacturing pipelines. Real-time PCR occupies the largest revenue share among product types due to its specificity for regulatory submissions, while microfluidics technology is gaining fastest adoption as manufacturers miniaturize workflows for point-of-need testing in distributed production networks. Nucleic acid testing commands premium pricing in vaccine manufacturing applications where pharmacopeial compliance carries zero-tolerance contamination standards.
The FDA, EMA, and Pharmacopeia Convention (USP Chapter 63 and EP 2.6.7) collectively determine acceptable detection methodologies, creating harmonized but jurisdictionally distinct compliance burdens for multinational biopharma firms. The FDA's emphasis on nucleic acid testing as equivalent or superior to traditional culture methods has accelerated kit-based platform conversions, while EMA's alignment with EP standards sustains demand for validated alternative methods in European manufacturing facilities. Stakeholders must monitor evolving pharmacopeial chapter revisions and regional divergence in acceptance criteria for rapid molecular methods versus compendial culture approaches.
Market Dynamics
Regulatory convergence on nucleic acid testing is compressing validation timelines for cell-culture verification, forcing biopharma manufacturers to retire legacy culture methods ahead of pharmacopeial deadlines.
Growth Catalysts
- FDA Guidance Alignment:The FDA's equivalence determination for PCR-based methods accelerates platform conversions in biologics license applications, eliminating regulatory friction for rapid molecular workflows.
- Vaccine Manufacturing Scale-Up:mRNA and viral vector production facilities in the United States, Germany, and Japan require zero-tolerance contamination protocols that drive kit standardization.
- Gene Therapy Commercialization:Autologous cell therapy manufacturing creates point-of-need testing demand at distributed production sites.
Market Restraints
- Reference Standard Scarcity:Certified mycoplasma DNA calibrators concentrate among three European suppliers, creating single-source vulnerability for assay validation.
- Compendial Method Persistence:EP 2.6.7 culture requirements in European facilities sustain dual-method compliance costs despite EMA acceptance of alternatives.
- Specialized Technician Shortage:Molecular diagnostics expertise gaps in contract manufacturing organizations extend onboarding timelines for new platform deployments.
Strategic Opportunities
- Microfluidics Miniaturization:Lab-on-chip architectures enable at-line testing in continuous manufacturing setups, reducing batch release latency.
- Indian Biopharma Expansion:CDSCO's harmonization with ICH quality guidelines creates first-mover advantage for validated kit providers in emerging biosimilar clusters.
- Cloud-Based Data Integrity:21 CFR Part 11-compliant software platforms capture audit trail requirements that on-premise systems cannot satisfy.
Industry Challenges
- Multi-Site Validation Burden:Biopharma networks with facilities across FDA, EMA, and PMDA jurisdictions face divergent change-control documentation for assay transfers.
- Legacy LIMS Integration:Proprietary data formats from established PCR platforms create middleware development costs for unified quality management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mycoplasma Detection System Market |
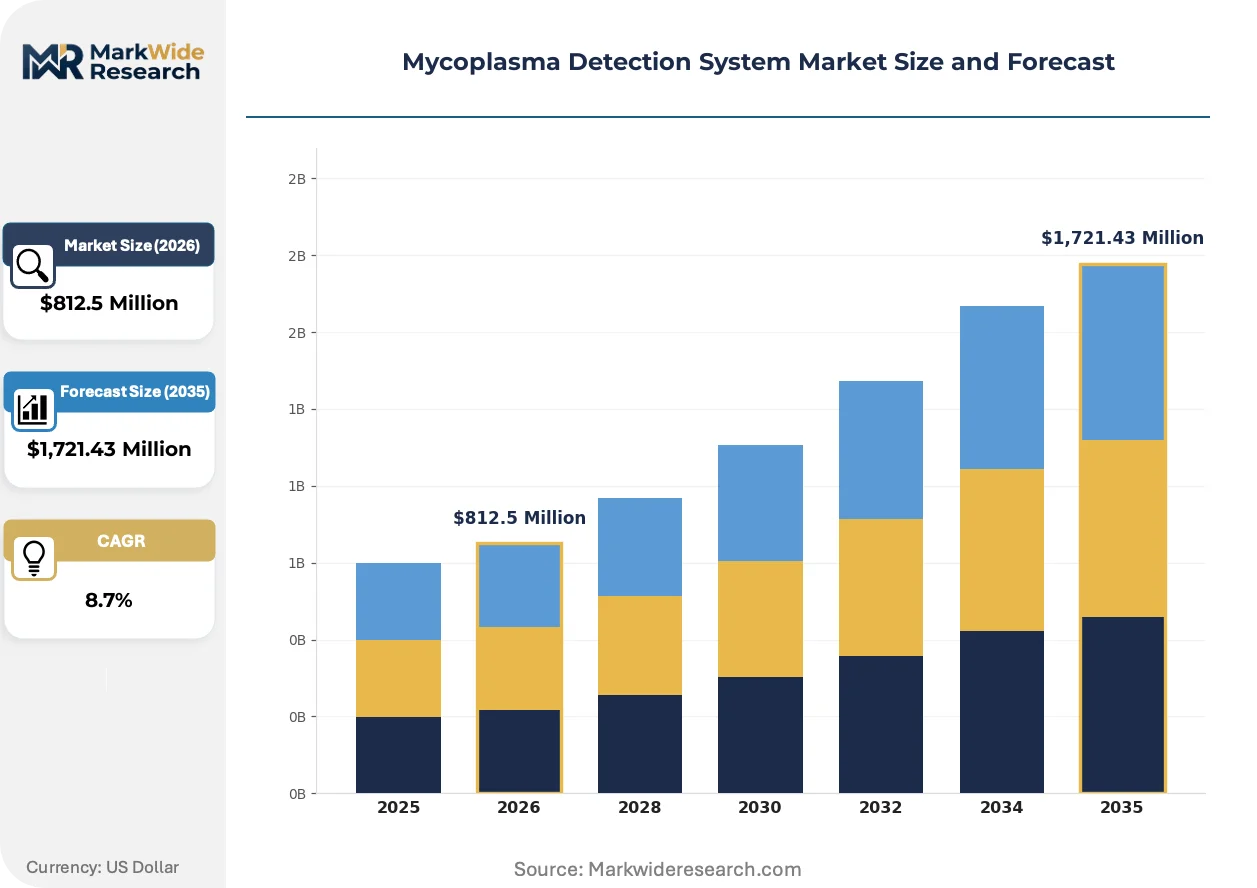
| Market Size in 2026 | $812.5 Million |
| Market Size in 2035 | $1,721.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Real-Time PCR, ELISA, Nucleic Acid Testing, Mass Spectrometry Technology: Fluorescent Probes, Antibody-Based Detection, DNA Probes, Microfluidics End User: Pharmaceutical Companies, Biotechnology Firms, Academic Research Institutes, Contract Manufacturing Organizations Application: Quality Control, Research & Development, Diagnostics, Vaccine Manufacturing |
| Companies Covered | Thermo Fisher Scientific Inc., Lonza, Charles River Laboratories, Sartorius AG, Bio-Rad Laboratories Inc., Merck KGaA, InvivoGen, Eurofins Scientific, ATCC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mycoplasma Detection System Market Trends and Innovations
Detection sensitivity thresholds are compressing toward single-digit genome copy detection, reshaping instrument specifications and reagent formulation requirements across the competitive landscape.
Digital PCR technology is absorbing the most demanding contamination detection use cases in gene therapy vector production. Viral vector manufacturers in Massachusetts and North Carolina are adopting absolute quantification workflows that eliminate standard curve dependencies. This shift is absorbing validation burden from reference material shortages while enabling direct comparison across production sites.
EMA's revised Annex 1 on sterile manufacturing now explicitly addresses rapid microbiological methods, creating regulatory cover for mycoplasma detection automation. European vaccine facilities are interpreting this as permission to deploy at-line PCR systems in Grade C environments. The guidance is accelerating capital allocation toward integrated sampling robotics in Belgium and Netherlands manufacturing hubs.
Consolidated procurement by top-twenty biopharma companies is compressing vendor qualification cycles. Multi-year kit supply agreements with embedded technical support are displacing transactional reagent purchases at contract manufacturing organizations. This concentration is most visible in the San Francisco Bay Area and Boston-Cambridge clusters where CDMOs serve overlapping sponsor portfolios.
Mycoplasma Detection System Market Segmentation
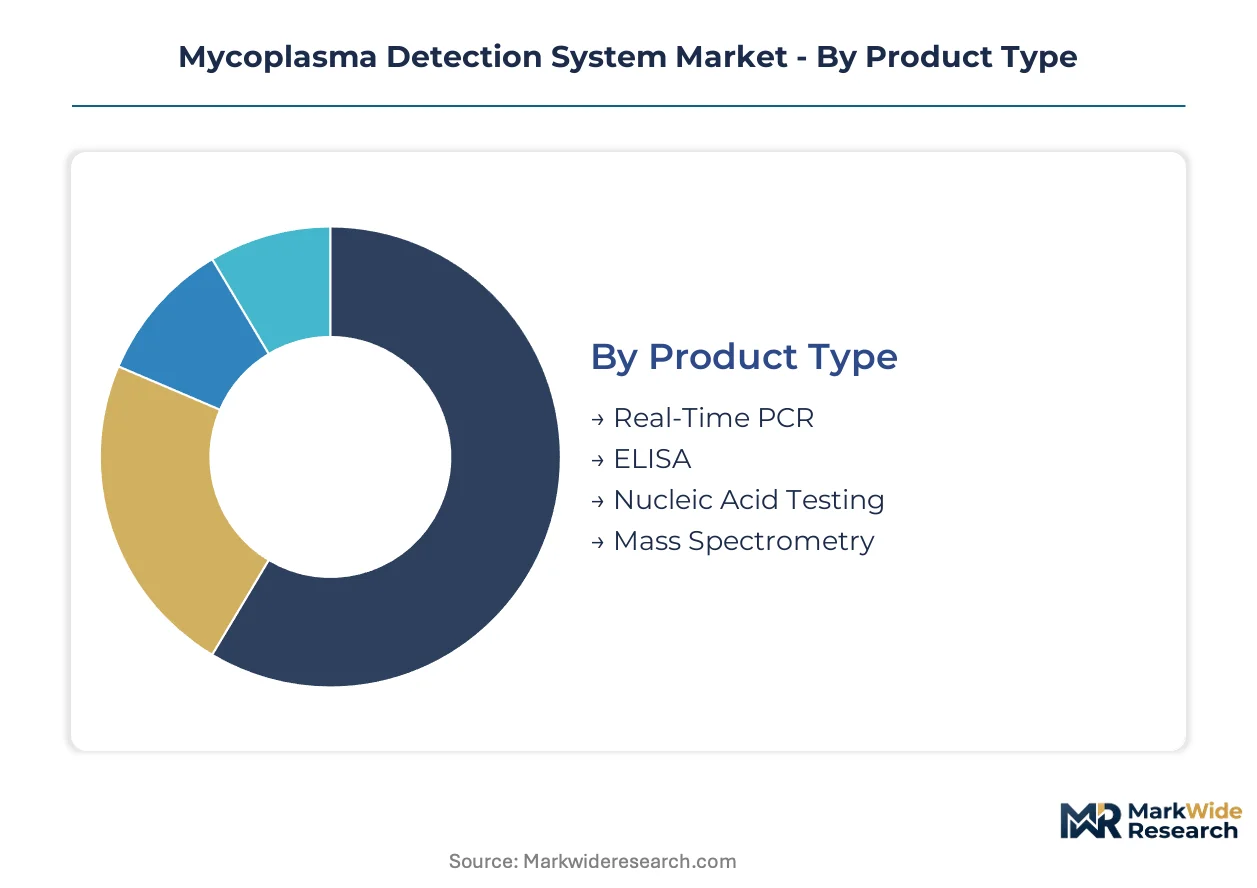
Segmentation in mycoplasma detection systems reveals how capital allocation, technical validation requirements, and regulatory compliance burdens distribute across the value chain. Manufacturers prioritize segments offering the shortest path to pharmacopeial acceptance and multi-site deployment scalability.
Product Type:
Capital intensity varies sharply across detection platforms, with instrumentation costs ranging from benchtop analyzers to fully automated high-throughput systems requiring dedicated cleanroom infrastructure.
- Real-Time PCR:Thermocycler-based amplification platforms with fluorescent readout achieve sensitivity thresholds of 10 genome copies per reaction. Demand concentrates in United States biologics license applications where FDA equivalence determinations have accelerated kit standardization. Thermo Fisher's TaqPath dominance anchors workflows across North American contract manufacturing organizations.
- Nucleic Acid Testing:Broad-spectrum molecular methods encompass isothermal amplification and hybridization-based approaches. Vaccine manufacturing facilities in Germany and Japan absorb premium pricing for pharmacopeial-compliant zero-tolerance contamination protocols. EMA alignment with EP standards sustains validated alternative method demand.
- ELISA:Enzyme-linked immunosorbent assays detect mycoplasma antigens with lower capital barriers but reduced sensitivity versus molecular methods.
- Mass Spectrometry:MALDI-TOF and LC-MS platforms identify species-specific protein signatures for research applications.
Most installed capacity flows through Real-Time PCR. Expansion is steepest in Nucleic Acid Testing.
Technology:
Detection chemistry selection determines assay specificity, throughput scalability, and integration complexity with existing laboratory information management systems.
- Fluorescent Probes:Hydrolysis probes and molecular beacons enable multiplexed target detection in single-tube reactions. Massachusetts and North Carolina viral vector manufacturers adopt absolute quantification workflows that eliminate standard curve dependencies. Digital PCR absorption of demanding gene therapy use cases is reshaping probe design specifications.
- Microfluidics:Lab-on-chip architectures miniaturize reagent volumes and integrate sample preparation with amplification. Belgium and Netherlands vaccine facilities deploy at-line systems in Grade C environments following EMA Annex 1 revisions. Integrated sampling robotics capture capital allocation in European manufacturing hubs.
- Antibody-Based Detection:Polyclonal and monoclonal antibody cocktails capture cell-culture supernatant screening applications.
- DNA Probes:Chemiluminescent and colorimetric hybridization methods serve legacy validation protocols.
Fluorescent Probes anchor the largest installed base. Microfluidics is gaining share fastest.
End User:
Procurement authority and validation burden distribution shape vendor engagement models, from centralized biopharma quality organizations to distributed academic core facilities.
- Contract Manufacturing Organizations:CDMOs face compressed batch release timelines and multi-sponsor audit requirements. San Francisco Bay Area and Boston-Cambridge clusters serve overlapping sponsor portfolios with consolidated kit supply agreements. Multi-year technical support contracts displace transactional reagent purchases.
- Pharmaceutical Companies:In-house biologics manufacturing drives direct platform ownership for cell-line verification. Top-twenty biopharma procurement concentration compresses vendor qualification cycles. Quality control budget expansion in North America and Europe prioritizes real-time PCR standardization.
- Biotechnology Firms:Gene therapy developers require point-of-need testing at distributed autologous cell therapy production sites.
- Academic Research Institutes:Core facilities balance sensitivity requirements against grant-funded capital constraints.
Contract Manufacturing Organizations absorb the highest kit volume. Biotechnology Firms are expanding capacity most aggressively.
Application:
Regulatory stringency tiers separate applications by contamination tolerance, from zero-tolerance vaccine substrates to research-grade cell-culture screening.
- Quality Control:In-process and release testing for biopharmaceutical batches demands documented sensitivity and specificity. FDA Points to Consider hardening into de facto binding expectations drives platform conversion timelines. Culture method retirement accelerates ahead of pharmacopeial deadlines.
- Vaccine Manufacturing:mRNA and viral vector production requires genome copy detection at single-digit thresholds. United States, Germany, and Japan manufacturing clusters operate under stringent pharmacopeial requirements. USP Chapter 63 and EP 2.6.7 compliance creates harmonized but jurisdictionally distinct burdens.
- Research & Development:Cell-line establishment and early-stage characterization tolerates broader method flexibility.
- Diagnostics:Clinical mycoplasma detection for respiratory and urogenital infections follows separate regulatory pathways.
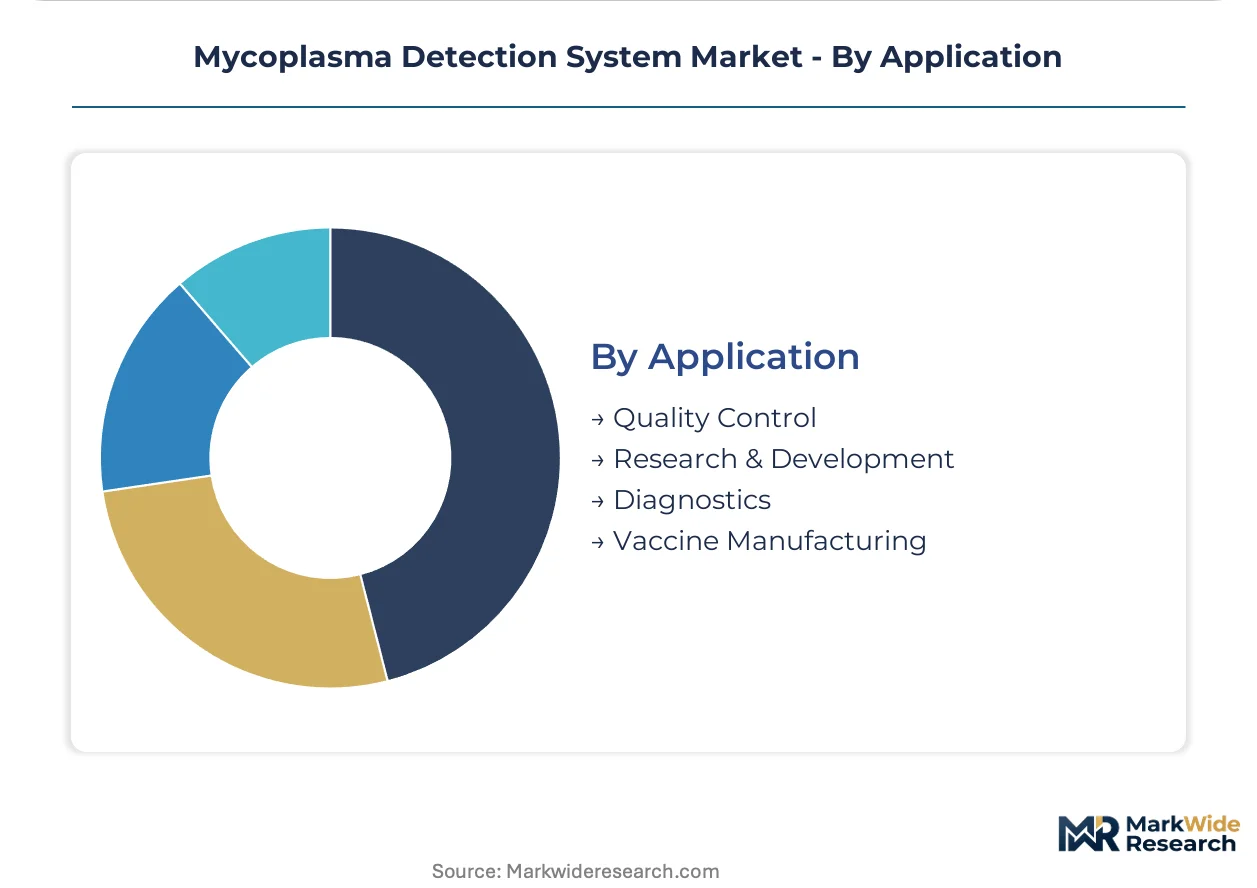
Quality Control commands the largest instrumentation footprint. Vaccine Manufacturing is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Molecular diagnostics specialists cluster around Boston-Cambridge, Basel, and Tokyo where gene therapy manufacturing demands rapid contamination detection. These talent pools anchor platform development and regulatory validation services.
United States
Viral vector producers in Massachusetts and North Carolina drive demand for absolute quantification workflows. FDA equivalence determinations for PCR-based methods accelerate kit standardization in biologics license applications. The San Francisco Bay Area concentrates contract manufacturing organizations serving overlapping sponsor portfolios with consolidated procurement.
Germany
Vaccine manufacturing facilities absorb premium pricing for pharmacopeial-compliant zero-tolerance protocols. EMA alignment with EP standards sustains validated alternative method demand despite culture requirements. The Rhine-Main and Bavarian biotech clusters deploy integrated biosafety testing services.
Japan
PMDA oversight of cell therapy commercialization creates stringent documentation requirements for distributed production sites. Tokyo and Osaka manufacturing hubs operate under pharmacopeial standards harmonized with USP Chapter 63. Autologous therapy facilities require point-of-need testing capacity.
Belgium
EMA Annex 1 revisions on rapid microbiological methods enable at-line PCR deployment in Grade C environments. Flanders vaccine facilities interpret guidance as permission for integrated sampling robotics. The Leuven-Antwerp corridor captures capital allocation toward automation.
India
CDSCO harmonization with ICH quality guidelines creates first-mover opportunity in emerging biosimilar clusters. Hyderabad and Bengaluru biopharma parks expand quality control budgets for cell-line verification. Contract research organizations build molecular diagnostics capabilities for export manufacturing.
Mycoplasma Detection System Market Competitive Landscape
Capital-heavy instrument manufacturers compete with asset-light reagent specialists for recurring revenue streams in mycoplasma detection. The vendor base stratifies across three tiers: diversified life science conglomerates with platform ecosystems, focused biosafety testing service providers, and niche molecular diagnostics innovators. Consolidation pressure intensifies as top-twenty biopharma procurement concentrates vendor qualification cycles. Multi-year kit supply agreements displace transactional purchases while technical support contracts deepen customer lock-in.
Within the diversified conglomerate tier, Thermo Fisher Scientific Inc. and Merck KGaA represent integrated platform providers spanning instrumentation, reagents, and compliance software. Lonza occupies a position between equipment and services, bundling detection with broader cell-line characterization. Charles River Laboratories exemplifies the geographic reach archetype, operating testing facilities that support multi-site production networks. Bio-Rad Laboratories Inc. sits within the specialty reagent tier, supplying validated assay components to third-party platform developers.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Lonza |
| Charles River Laboratories |
| Sartorius AG |
| Bio-Rad Laboratories Inc. |
| Merck KGaA |
| InvivoGen |
| Eurofins Scientific |
| ATCC |
| Others |
Pricing and Supply Chain Analysis
Digital PCR platform adoption simultaneously compresses per-test reagent economics and concentrates supply leverage among thermocycler manufacturers with validated pharmacopeial workflows. Cost trajectories diverge between high-throughput centralized facilities and distributed point-of-need sites, reshaping procurement patterns across biopharma manufacturing networks.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates pharmacopeial-grade validated kits from research-use reagents and unvalidated economy alternatives. Price differentiation hinges on FDA equivalence documentation and ISO 13485 certification tier, with premium tiers commanding substantial markups for biologics license application submissions. Cost compression in standard-tier PCR kits is intensifying because consolidated procurement by top-twenty biopharma companies forces volume discounts. Contract manufacturing organizations exhibit highest price sensitivity due to multi-sponsor audit cost absorption, while gene therapy developers show lowest sensitivity given zero-tolerance contamination requirements.
Supply Chain Analysis
Fluorescent probe chemistries rest on German and Japanese specialty chemical producers for hydrolysis probe synthesis, with thermocycler hardware anchored in United States and Chinese manufacturing facilities. Critical inputs span certified mycoplasma DNA calibrators, fluorophore-labeled oligonucleotides, and precision-molded microfluidic chips. Single-source vulnerability concentrates among European reference material suppliers, creating validation bottleneck exposure for assay developers. Distribution runs through authorized distributor networks serving biopharma quality organizations, with direct manufacturer relationships dominating high-volume CDMO accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mycoplasma detection system market functions as a stable compounder anchored by irreversible regulatory conversion from culture to molecular methods. Pharmacopeial deadline alignment sustains predictable replacement demand across biopharma manufacturing infrastructure.
For Market Incumbents: Extend platform ecosystems through embedded compliance software that captures 21 CFR Part 11 audit trail requirements competitors cannot satisfy. Deepen technical support contracts with multi-year kit supply agreements that lock in CDMO procurement committees. Threat exposure from digital PCR substitutes demands accelerated probe multiplexing R&D to preserve real-time PCR installed base relevance. For New Entrants and Emerging Players: Launch via cloud-native LIMS integration targeting mid-size biotechnology firms with fragmented legacy data systems. White-space concentration sits with Indian biosimilar manufacturers building quality control capabilities under CDSCO harmonization with ICH guidelines. Go-to-market angle emphasizes rapid validation support for first-time pharmacopeial compliance entrants. For Investors and Strategic Acquirers: Valuations sit cheapest among microfluidics specialists with Grade C environment deployment capabilities but limited commercial scale. Long-term viability framing centers on automation-enabling technologies for continuous manufacturing adoption across the projection horizon. Acquisition target archetype combines lab-on-chip hardware with validated reagent chemistry. Signal to watch is EMA Annex 1 enforcement intensity driving at-line system capital allocation.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmacopeial Validation Investment | FDA equivalence documentation accelerates kit standardization in United States biologics submissions. |
| Microfluidics Platform Development | Lab-on-chip architectures enable at-line testing in Belgium and Netherlands vaccine facilities. |
| Cloud-Based Compliance Software | 21 CFR Part 11-compliant platforms capture audit requirements that on-premise systems fail. |
| Indian Market Entry | CDSCO harmonization with ICH guidelines creates first-mover positioning in Hyderabad biosimilar clusters. |
| Reference Material Supply Security | Certified DNA calibrator diversification reduces single-source vulnerability for assay validation. |
Research Methodology
Direct dialogue with quality control directors, regulatory affairs leads at biopharma manufacturers, CDMO procurement managers, and pharmacopeial committee members grounded demand-side validation. Secondary sources encompass FDA guidance documents, USP Chapter 63 and EP 2.6.7 pharmacopeial standards, EMA Annex 1 sterile manufacturing revisions, and SEC filings from publicly traded instrument manufacturers. Bottom-up segmentation modeling triangulated against top-down market sizing from biopharma quality control budget expansion trends.
Installed base projections and reagent consumption forecasts emerged from instrument placement tracking across United States, German, and Japanese manufacturing clusters. Segmentation dimensions spanned product type, detection technology, end-user archetype, and application stringency tier. CAGRs derived from regression analysis of historical platform conversion rates and regulatory deadline alignment. Industry-specific inputs included pharmacopeial chapter revision timelines and gene therapy manufacturing capacity expansion announcements.
Forecast precision tightens around the base case; tail outcomes carry wider variance under PMDA regulatory divergence or reference material supply disruption scenarios. Forecasts reflect documented assumptions regarding molecular method equivalence acceptance timelines. A small set of named triggers warrants ongoing watch: EMA Annex 1 enforcement intensity, digital PCR cost parity achievement, and Indian CDSCO inspection capacity buildout.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Cushing's Syndrome Diagnostics and Therapeutics Market
Diagnostics
Cognitive Diagnostics Market
Diagnostics
Body Fluid Collection and Diagnostics Market
Diagnostics
Neglected Tropical Diseases Diagnosis Market
Diagnostics
Global Yersiniosis Diagnostics and Treatment Market
Diagnostics
Influenza Diagnostics Market
Diagnostics
Global Respiratory Syncytial Virus (RSV) Diagnostic Market
Diagnostics
Mycology Immunoassays Testing Market
Diagnostics
United States Melanoma Diagnostics & Therapeutics Market
Diagnostics
Global Digital Diagnostics Market
Diagnostics
Semen Analysis Systems Market
Diagnostics
Haptoglobin Reagent Market
Diagnostics
North America Antinuclear Antibody Test Market
Diagnostics
Lipid Panel Test Market
Diagnostics
Global Artificial Intelligence (AI) in Diagnostics Market
Diagnostics
Thrombosis and Hemostasis Biomarkers Market