
 Middle East and Africa Syndromic Multiplex Diagnostic Market | 2026-2036
Middle East and Africa Syndromic Multiplex Diagnostic Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Syndromic Multiplex Diagnostic Market Foresight
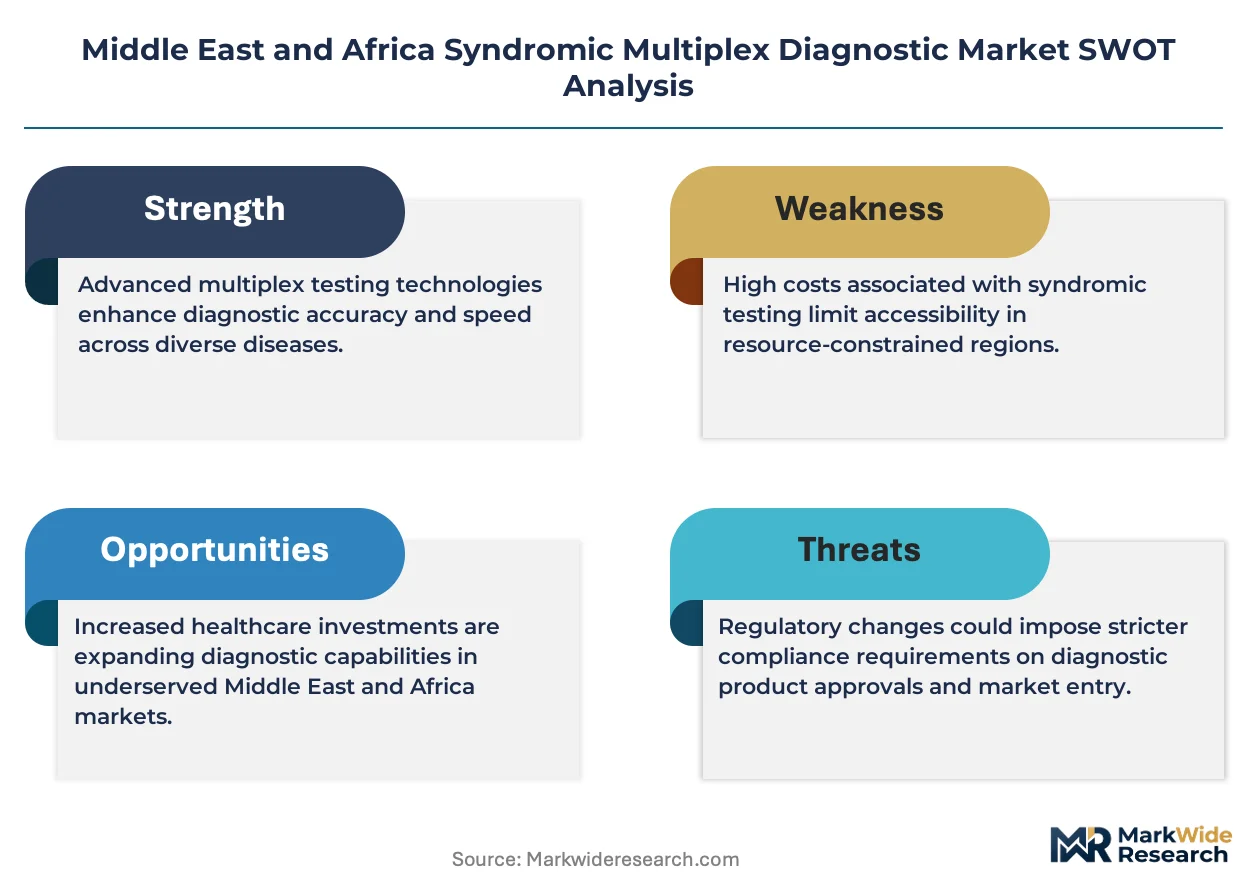
Multi-source procurement of assay reagents and instrument consumables is expanding across Middle East and Africa public health systems. Abbott Laboratories leverages its installed base of integrated molecular platforms to sustain service contracts in Saudi Arabian reference hospitals. bioMérieux competes through specialized blood culture and sepsis panel configurations tailored to antimicrobial resistance surveillance networks.
Syndromic multiplex diagnostic systems simultaneously detect multiple pathogens from a single patient sample using nucleic acid amplification, typically resolving 15-30 target organisms within 1-4 hours through cartridge-based or open-platform PCR workflows. Real-Time PCR technology dominates current installations due to established workflows and regulatory familiarity, while Next-Generation Sequencing segments attract investment for outbreak surveillance and novel pathogen discovery in research institutes. Infectious Diseases applications anchor volume demand, though Cancer Screening panels represent a developing margin pool as oncology centers adopt liquid biopsy multiplexing.
SFDA in Saudi Arabia, SAHPRA in South Africa, and the UAE's Ministry of Health and Prevention enforce divergent registration timelines and clinical evidence requirements that fragment market access timelines for assay manufacturers. CE-IVDR alignment pressures from European notified bodies cascade into Middle East import documentation, compelling manufacturers to maintain dual technical files. Stakeholders must monitor harmonization negotiations between Gulf standardization bodies and African Medicines Agency frameworks to anticipate shifts in conformity assessment burdens.
Market Dynamics
Central laboratory consolidation across Gulf Cooperation Council hospital networks is compressing procurement timelines and favoring integrated platform vendors over discrete assay suppliers. This structural concentration is reshaping vendor qualification criteria and service contract structures throughout the region.
Growth Catalysts
- Antimicrobial Resistance Surveillance Mandates:National health ministries in Saudi Arabia and South Africa now require multiplex pathogen detection for bloodstream infections, driving panel standardization in tertiary care facilities.
- Cartridge-Based PCR Workflows:Diagnostic laboratories are adopting closed-system nucleic acid amplification to reduce contamination risk and technician training burdens in high-throughput settings.
- Reference Hospital Modernization:Saudi Food and Drug Authority streamlined emergency use authorization pathways during recent health security exercises, accelerating validation timelines for respiratory panels.
Market Restraints
- Reagent Import Dependency:Cold-chain logistics for temperature-sensitive assay cartridges concentrate through single-source distributors in Dubai and Johannesburg, creating supply vulnerability.
- CE-IVDR Documentation Cascades:European notified body alignment requirements inflate technical file preparation costs for manufacturers seeking parallel Middle East registration.
- Laboratory Information System Fragmentation:Proprietary data formats from legacy hematology and chemistry analyzers impede seamless multiplex result integration.
Strategic Opportunities
- Next-Generation Sequencing Convergence:Research institutes in Cape Town and Riyadh are piloting hybrid PCR-NGS workflows for novel pathogen discovery during outbreak investigations.
- Point-of-Care Decentralization:Nigeria and Kenya present underpenetrated demand for syndromic panels in provincial hospital networks lacking central lab access.
- UAE Ministry of Health and Prevention Procurement Reform:Bulk purchasing frameworks for federal hospital networks favor vendors offering multi-year consumable supply guarantees.
Industry Challenges
- Molecular Diagnostics Specialist Shortage:Saudi Arabia and South Africa face competing demand for trained PCR technicians from pharmaceutical manufacturing and academic research sectors.
- Dual Technical File Maintenance:Manufacturers must sustain parallel regulatory dossiers for SAHPRA and SFDA with divergent clinical evidence requirements, stretching quality assurance resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Syndromic Multiplex Diagnostic Market |
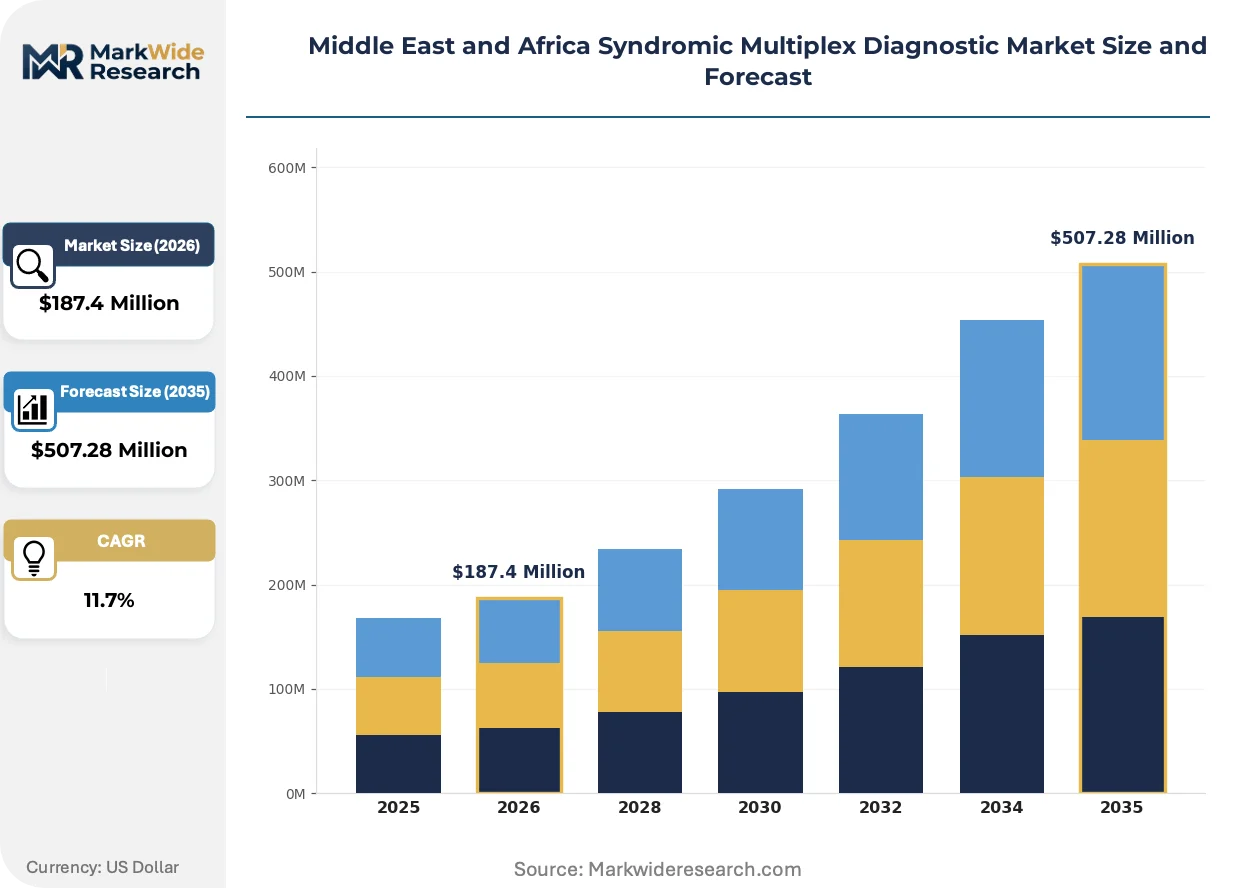
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PCR, Microarray, Chip Technology, LAMP Application: Infectious Diseases, Genetic Testing, Cancer Screening, Allergy Testing Technology: Real-Time PCR, Next-Generation Sequencing, Bioinformatics, Isothermal Amplification End User: Hospitals, Diagnostic Laboratories, Research Institutes, Clinics |
| Companies Covered | Abbott Laboratories, F. Hoffmann-La Roche Ltd, bioMérieux, Thermo Fisher Scientific, BD, DiaSorin, Bio-Rad Laboratories, QIAGEN, Cepheid, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Syndromic Multiplex Diagnostic Market Shifts & Advancements
Multiplex diagnostic platforms are absorbing artificial intelligence-assisted result interpretation while regulatory frameworks across the Middle East and Africa impose divergent validation requirements. These intersecting forces are compressing product development cycles and expanding service contract scope.
Random-access cartridge architectures are absorbing laboratory workflow demands for stat testing alongside batch processing. Tertiary care hospitals in Jeddah and Pretoria deploy these systems for simultaneous respiratory and bloodstream pathogen detection. The flexibility is absorbing capital allocation from standalone analyzers toward integrated platforms with expandable menu capabilities.
SAHPRA's tightened in vitro diagnostic registration requirements now mandate local clinical performance studies for Class C and D multiplex assays. Manufacturers must establish South African investigator sites or contract with regional clinical research organizations. Blood culture and sepsis panel categories face extended review timelines, prompting earlier submission strategies.
Public health systems are consolidating reagent procurement through centralized tendering offices rather than hospital-level purchasing. The UAE's Ministry of Health and Prevention and Saudi Arabia's National Unified Procurement Company now negotiate multi-year supply agreements directly with manufacturers. This concentration is displacing distributor intermediaries in federal hospital networks while preserving their role in private laboratory segments.
Middle East and Africa Syndromic Multiplex Diagnostic Market Segmentation
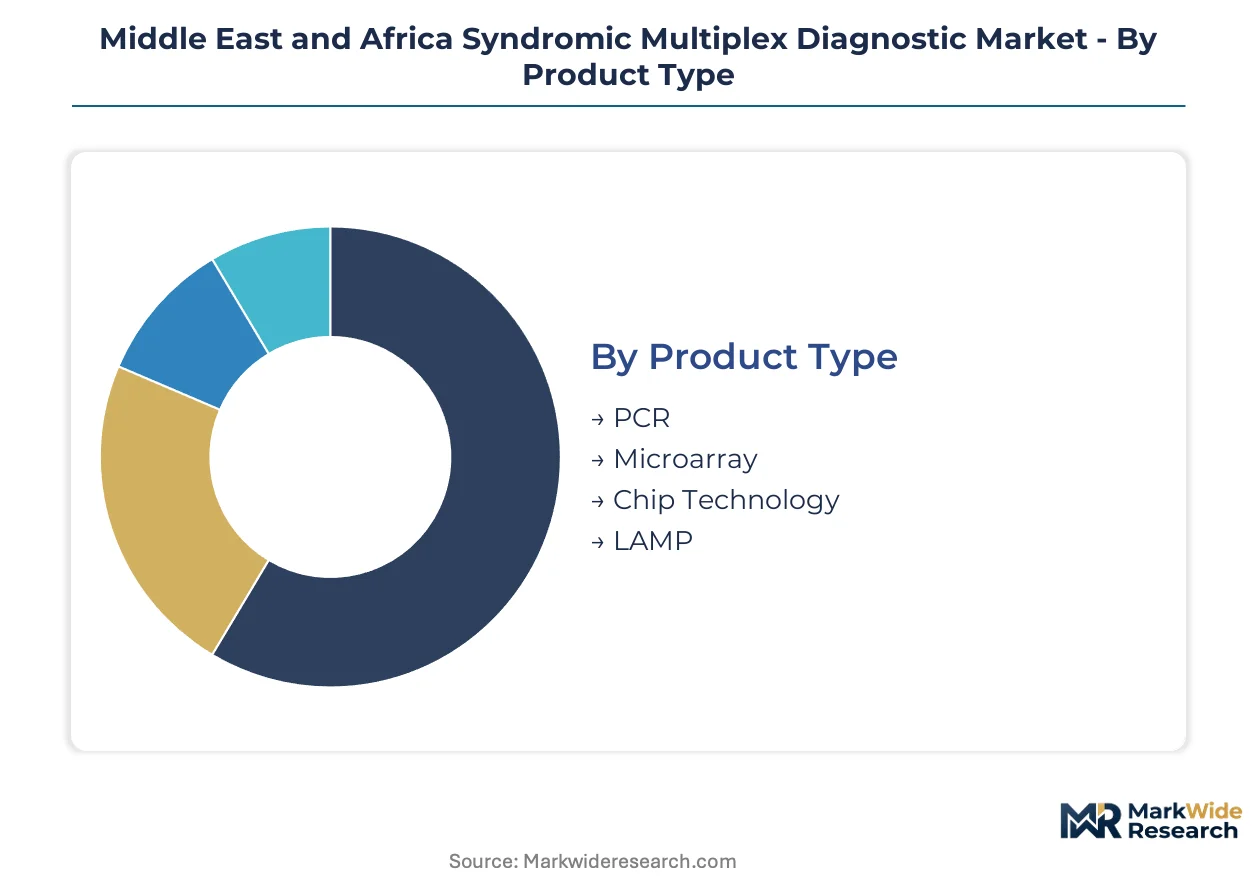
Syndromic multiplex diagnostic procurement across Middle East and Africa fragments across four structural dimensions. Each dimension carries distinct regulatory, technical, and commercial implications for assay manufacturers and laboratory operators.
Product Type:
Supply concentration in cartridge-based systems favors vendors with integrated instrument-reagent platforms over discrete component suppliers.
- PCR:Real-time and digital PCR platforms dominate installed capacity in Saudi Arabian reference hospitals and South African academic medical centers. SFDA emergency use authorizations accelerated respiratory panel validation during recent health security exercises, entrenching PCR as the default amplification chemistry.
- Microarray:Planar and bead-based microarray configurations serve genetic testing and pharmacogenomics applications in UAE federal hospital networks. The format's higher throughput per run absorbs demand from centralized laboratories processing >500 samples daily.
- Chip Technology:Lab-on-chip architectures reduce reagent volumes and hands-on time for point-of-care deployments in Nigerian provincial hospitals.
- LAMP:Loop-mediated isothermal amplification operates without thermal cyclers, suiting resource-limited settings with unreliable power infrastructure in Kenya and Ethiopia.
PCR absorbs the bulk of installed capacity; LAMP is expanding most quickly in decentralization pilot programs.
Application:
Margin structure varies sharply across indication categories, with oncology panels commanding premium pricing over commoditized respiratory assays.
- Infectious Diseases:Respiratory, bloodstream, and gastrointestinal pathogen panels anchor volume demand across Gulf Cooperation Council hospital networks. SAHPRA mandates multiplex detection for antimicrobial resistance surveillance in South African tertiary care facilities.
- Genetic Testing:Carrier screening and prenatal diagnostics concentrate in private laboratory chains across Dubai and Riyadh. Reimbursement fragmentation between federal and private payers constrains panel standardization.
- Cancer Screening:Liquid biopsy multiplexing for circulating tumor DNA detection is gaining traction in Saudi oncology centers. High reagent costs and limited public reimbursement restrict penetration outside premium private networks.
- Allergy Testing:Molecular allergen panels remain niche, deployed primarily in specialized immunology clinics in Cape Town and Abu Dhabi.
Infectious Diseases absorbs the bulk of installed capacity; Cancer Screening is climbing the fastest as liquid biopsy validation expands.
Technology:
Workflow integration requirements are compressing vendor selection criteria toward platforms with expandable menu architectures.
- Real-Time PCR:Established regulatory familiarity and technician training infrastructure sustain dominance in diagnostic laboratories across Jeddah, Riyadh, and Pretoria. Random-access cartridge configurations enable stat testing alongside batch processing.
- Next-Generation Sequencing:Targeted amplicon sequencing and metagenomic workflows attract investment for outbreak surveillance in Cape Town and Riyadh research institutes. Hybrid PCR-NGS protocols are piloting for novel pathogen discovery.
- Bioinformatics:Cloud-based analysis pipelines and AI-assisted result interpretation are expanding service contract scope for integrated platform vendors.
- Isothermal Amplification:Recombinase polymerase amplification and helicase-dependent amplification operate at constant temperature, reducing instrument complexity for peripheral laboratories.
Real-Time PCR absorbs the bulk of installed capacity; Next-Generation Sequencing is gaining share fastest in surveillance applications.
End User:
Procurement centralization is reshaping vendor qualification criteria and contract structures across public health systems.
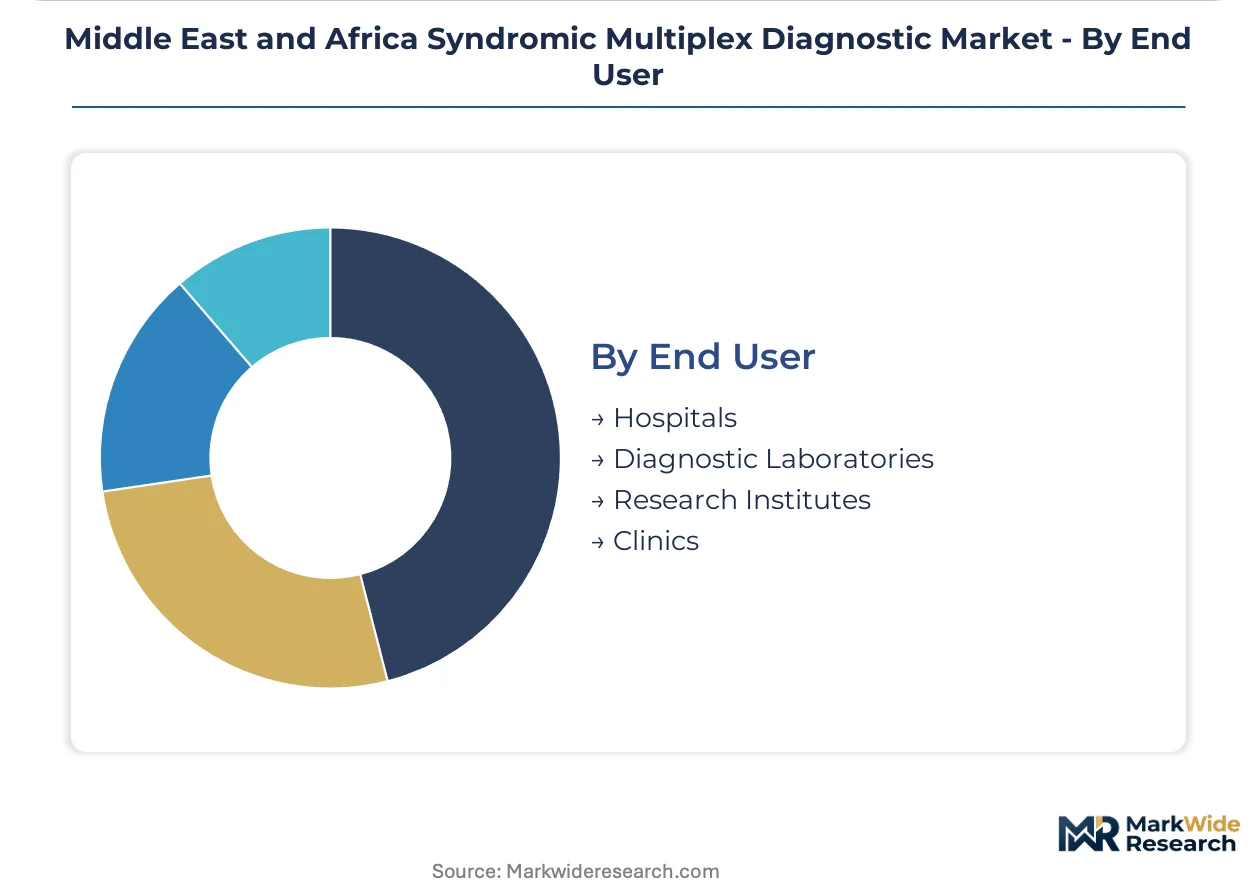
- Hospitals:Tertiary care facilities in Saudi Arabia and UAE federal networks deploy integrated platforms for simultaneous respiratory and bloodstream pathogen detection. The UAE Ministry of Health and Prevention negotiates multi-year consumable supply agreements directly with manufacturers.
- Diagnostic Laboratories:Central laboratory consolidation across Gulf Cooperation Council networks compresses procurement timelines and favors vendors with regional service infrastructure.
- Research Institutes:Cape Town and Riyadh academic centers pilot hybrid workflows for novel pathogen discovery during outbreak investigations.
- Clinics:Provincial hospital networks in Nigeria and Kenya present underpenetrated demand for point-of-care syndromic panels lacking central lab access.
Hospitals absorb the bulk of installed capacity; Clinics are expanding most quickly in decentralization corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reagent cold-chain logistics through Dubai and Johannesburg anchor distribution networks across the Middle East and Africa syndromic multiplex diagnostic market. Procurement centralization in Gulf Cooperation Council federal hospital networks is compressing vendor qualification timelines. Research institutes in Cape Town and Riyadh pilot hybrid PCR-NGS workflows for outbreak surveillance applications.
Saudi Arabia
Reference hospital modernization in Riyadh and Jeddah drives integrated platform installations for respiratory and bloodstream pathogen detection. SFDA streamlined emergency use authorization pathways during recent health security exercises, accelerating respiratory panel validation timelines. The National Unified Procurement Company negotiates multi-year consumable supply agreements directly with manufacturers, displacing distributor intermediaries in federal networks.
South Africa
Academic medical centers in Pretoria and Cape Town absorb demand for antimicrobial resistance surveillance panels in tertiary care facilities. SAHPRA tightened in vitro diagnostic registration requirements, mandating local clinical performance studies for Class C and D multiplex assays. Blood culture and sepsis panel categories face extended review timelines, prompting earlier submission strategies from assay manufacturers.
United Arab Emirates
Federal hospital networks in Dubai and Abu Dhabi deploy random-access cartridge architectures for stat testing alongside batch processing workflows. MOHAP procurement reform enables bulk purchasing frameworks with multi-year consumable supply guarantees favoring integrated platform vendors. Centralized tendering through the Ministry of Health and Prevention concentrates reagent procurement authority at the federal level.
Nigeria
Provincial hospital networks lacking central laboratory access present underpenetrated demand for point-of-care syndromic panels. The country's national pharmaceutical regulator maintains divergent registration timelines from Gulf standardization bodies, fragmenting market access documentation. Lagos and Abuja clinical clusters pilot LAMP-based isothermal amplification for resource-limited settings with unreliable power infrastructure.
Kenya
Decentralization corridors in Nairobi and Mombasa expand demand for cartridge-based PCR workflows reducing technician training burdens. National health ministry procurement operates through centralized tendering offices rather than hospital-level purchasing, reshaping vendor qualification criteria. Research institutes pilot hybrid workflows for novel pathogen discovery during regional outbreak investigations.
Middle East and Africa Syndromic Multiplex Diagnostic Market Competitive Landscape
Strategic partnerships dominate the current landscape as assay manufacturers establish regional clinical research organizations to satisfy divergent registration requirements. The vendor base clusters around integrated instrument-reagent platforms and specialized panel configuration suppliers, with procurement centralization favoring vendors with expandable menu architectures. Two archetypes occupy distinct positions: multinational diagnostics conglomerates leveraging installed base service contracts, and specialized molecular platform developers targeting antimicrobial resistance surveillance networks. M&A activity and technology licensing agreements represent the dominant competitive moves as manufacturers seek to absorb bioinformatics and AI-assisted result interpretation capabilities.
Among North American-based conglomerates, Abbott Laboratories and Thermo Fisher Scientific occupy positions exemplifying the integrated platform archetype, with service contract structures designed to sustain long-term relationships with reference hospital networks. Within the specialized European tier, bioMérieux represents the antimicrobial resistance surveillance focus, while F. Hoffmann-La Roche Ltd anchors the premium instrument-reagent bundling segment. These three companies collectively illustrate the competitive tension between scale-driven service infrastructure and panel specialization depth that defines current procurement dynamics across Saudi Arabian and South African tertiary care facilities.
| Leading Market Players |
|---|
| Abbott Laboratories |
| F. Hoffmann-La Roche Ltd |
| bioMérieux |
| Thermo Fisher Scientific |
| BD |
| DiaSorin |
| Bio-Rad Laboratories |
| QIAGEN |
| Cepheid |
| Others |
Supply & Pricing Matrix
Federal hospital procurement networks across Gulf Cooperation Council countries concentrate purchasing authority through centralized tendering offices, compressing vendor margins into multi-year consumable supply contracts with service bundling as the primary pricing anchor. This buyer concentration shifts pricing power toward integrated platform vendors capable of absorbing extended warranty obligations and regional technical support commitments within headline contract values.
Pricing Analysis
Instrument-reagent bundling with embedded service warranties dominates contract structures, while unbundled reagent-only pricing persists for reference laboratories with captive maintenance capabilities. Three-tier pricing structure across premium, standard, and economy levels separates CE-IVDR certified panels from emergency use authorized assays and research-use-only configurations. Cost compression in economy tiers intensifies because distributor intermediaries face displacement by direct manufacturer negotiations with federal procurement entities. Provincial hospital networks lacking central lab infrastructure exhibit highest price sensitivity, whereas Saudi Arabian reference hospitals prioritize turnaround time guarantees over per-test economics.
Supply Chain Analysis
CE-IVDR certification and SAHPRA registration requirements gate market access, forcing manufacturers to maintain parallel technical files for European and South African regulatory alignment. Cold-chain logistics concentrates in Germany, the Netherlands, and Singapore as manufacturing origins for temperature-sensitive assay cartridges, with final distribution runs through Dubai and Johannesburg hub facilities. Lyophilized reagent beads, optical detection modules, and proprietary cartridge plastics constitute critical component dependencies. Single-source vulnerability permeates the channel because SFDA and SAHPRA mandate identical lot release documentation from primary manufacturing sites, limiting qualified secondary sourcing options.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SAHPRA's tightened Class C and D multiplex assay registration requirements erect a cost-of-compliance barrier that entrenches incumbents with established South African clinical research organization relationships while screening out capital-constrained challengers.
For Market Incumbents: Cement defensive positioning by acquiring regional clinical research organization capabilities to satisfy SAHPRA's local performance study mandates, while extending service contract durations with Saudi Arabia's National Unified Procurement Company to lock out emerging platform competitors. Substitute LAMP-based point-of-care systems from Chinese manufacturers threaten economy-tier market share, necessitating backward integration into cartridge manufacturing to preserve margin structure against low-cost decentralization plays. For New Entrants and Emerging Players: Regional distributors with existing cold-chain infrastructure and SFDA registration experience offer the fastest path to federal hospital network qualification without direct manufacturer establishment costs. Nigerian and Kenyan provincial hospital networks present the most penetrable white-space opportunity, where LAMP-based isothermal amplification systems bypass thermal cycler capital requirements. A go-to-market angle anchored on antimicrobial resistance surveillance panel specialization, with contracted investigator site relationships in Pretoria academic medical centers, satisfies SAHPRA evidentiary demands while differentiating from respiratory panel commoditization. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized molecular platform developers with validated sepsis panel configurations and existing South African clinical trial footprints, as SAHPRA registration timelines stretch quality assurance resources at mid-cap manufacturers. Long-term viability across the projection horizon hinges on expandable menu architectures capable of absorbing NGS convergence and AI-assisted result interpretation without instrument replacement. The signal to monitor is harmonization progress between Gulf standardization bodies and African Medicines Agency frameworks, which would collapse dual technical file maintenance burdens and revalue compliant asset bases.| Strategic Initiative | Industry Significance |
|---|---|
| SAHPRA Registration Pathway Investment | Local clinical performance studies in Pretoria secure Class C and D assay approvals ahead of competitors. |
| Multi-Year Consumable Supply Guarantee | Direct contracting with UAE Ministry of Health and Prevention displaces distributor intermediaries in federal networks. |
| Hybrid PCR-NGS Platform Development | Cape Town and Riyadh research institute pilots validate expandable menu architectures for outbreak surveillance. |
| Regional Clinical Research Organization Acquisition | South African investigator site control compresses SAHPRA submission timelines for sepsis panel categories. |
| Point-of-Care LAMP Manufacturing Partnership | Isothermal amplification production in Nigeria reduces cold-chain dependency for provincial hospital networks. |
Research Methodology
Document review covered regulatory filings with SFDA, SAHPRA, and UAE Ministry of Health and Prevention, complemented by interviews with hospital laboratory directors, biomedical engineers, procurement managers at Gulf Cooperation Council federal networks, and distribution channel specialists in Dubai and Johannesburg. Secondary sources included GPO contract databases, CE-IVDR technical file summaries, and customs records for diagnostic reagent imports. Bottom-up instrument installation tracking and top-down healthcare expenditure allocation models were cross-validated through triangulation.
Historical adoption curves for respiratory and bloodstream pathogen panels were cross-referenced against panel expert assessments of technology transition timing. Segmentation dimensions spanned amplification chemistry, application indication, detection technology, and end-user facility tier across the analysis window. CAGRs were derived from logistic diffusion modeling of cartridge-based system penetration rates, with inputs including reference hospital modernization budgets and antimicrobial resistance surveillance mandate implementation schedules.
Caveats apply where SAHPRA registration timeline extensions, Gulf procurement centralization reversals, or cold-chain logistics disruptions could materially shift the outlook. A model refresh is warranted upon material change in harmonization negotiations between Gulf standardization bodies and African Medicines Agency frameworks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Food Allergy Diagnostics and Therapeutics Market
Diagnostics
Europe Molecular Diagnostics Market
Diagnostics
Global Chromoendoscopy Agents Market
Diagnostics
Asia-Pacific Womens Health Diagnostics Market
Diagnostics
Malaria Diagnostics Market
Diagnostics
Septicemia Diagnostic Testing Market
Diagnostics
Cancer IVD Market
Diagnostics
Primary Care POC Diagnostics Market
Diagnostics
Viral Disease Diagnosis Market
Diagnostics
Point of Care (Poc) Molecular Diagnostics Market
Diagnostics
GCC in-Vitro Diagnostic Devices Market
Diagnostics
Global Immunoassay Market
Diagnostics
Mexico in-Vitro Diagnostics Market
Diagnostics
Hepatitis B Diagnostic Tests Market
Diagnostics
DNA and RNA Probes Market
Diagnostics
Glucose Biosensors Market