
 Preclinical Brain Imaging Market | 2026-2036
Preclinical Brain Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Preclinical Brain Imaging Market Analytics
Multi-source procurement of preclinical imaging hardware is broadening as contract research organizations diversify vendor relationships beyond single-platform dependencies. Bruker Corporation leverages its cryogen-free magnet technology to sustain dominance in high-field preclinical MRI installations across European neuroscience clusters. Siemens Healthineers anchors its position through integrated PET-MRI workflows that reduce isotope dosing in longitudinal neuroimaging studies. Fujifilm VisualSonics differentiates via photoacoustic-ultrasound fusion systems that occupy a specialized niche in cerebrovascular phenotyping.
Preclinical brain imaging encompasses non-invasive visualization technologies applied to animal models—principally rodents and non-human primates—to assess neural structure, function, and pharmacodynamic response prior to human trials, typically achieving spatial resolutions below 100 micrometers for micro-MRI and sensitivity thresholds in the picomolar range for PET tracers. Magnetic Resonance Imaging leads technology adoption due to its soft-tissue contrast and absence of ionizing radiation, while Positron Emission Tomography captures the fastest growth trajectory as radiochemistry automation expands access to novel neurology tracers. Among end users, Contract Research Organizations represent the most concentrated margin pool as pharmaceutical sponsors outsource IND-enabling neurotoxicology imaging packages.
FDA 21 CFR Part 11 electronic records requirements and EMA's preclinical imaging quality guidelines jointly shape equipment validation protocols and data integrity standards for cross-border regulatory submissions. ISO 13485 quality management systems and IEC 60601-1-3 medical electrical safety standards further govern hardware design and software risk classification for imaging systems deployed in GLP-compliant facilities. Stakeholders must monitor evolving alignment between automated image analysis algorithms and regulatory expectations for computational pathology in neurodegenerative drug development programs.
Market Dynamics
Contract research organizations are consolidating imaging service procurement around multi-vendor platforms, fragmenting historical single-supplier dependencies and forcing equipment manufacturers to integrate cross-modal data workflows.
Growth Catalysts
- EMA Preclinical Imaging Quality Guidelines:Harmonized validation standards across European GLP facilities accelerate cross-border study submissions and reduce redundant equipment certification cycles.
- Radiochemistry Automation:Automated tracer synthesis platforms expand PET accessibility to mid-tier academic labs previously constrained by cyclotron infrastructure requirements.
- Helmholtz Association Centers:German neuroscience clusters sustain concentrated demand for high-field MRI systems through centralized federal research funding mechanisms.
Market Restraints
- Helium Supply Concentration:Cryogen dependency for superconducting magnets exposes European installations to Qatar and Algeria supply volatility and price spikes.
- FDA 21 CFR Part 11 Compliance Burden:Electronic records validation requirements extend equipment qualification timelines by 8-14 months for IND-enabling toxicology programs.
- Optical Imaging Depth Limitation:Tissue penetration constraints below 2 millimeters restrict photoacoustic-ultrasound systems to superficial cerebrovascular applications.
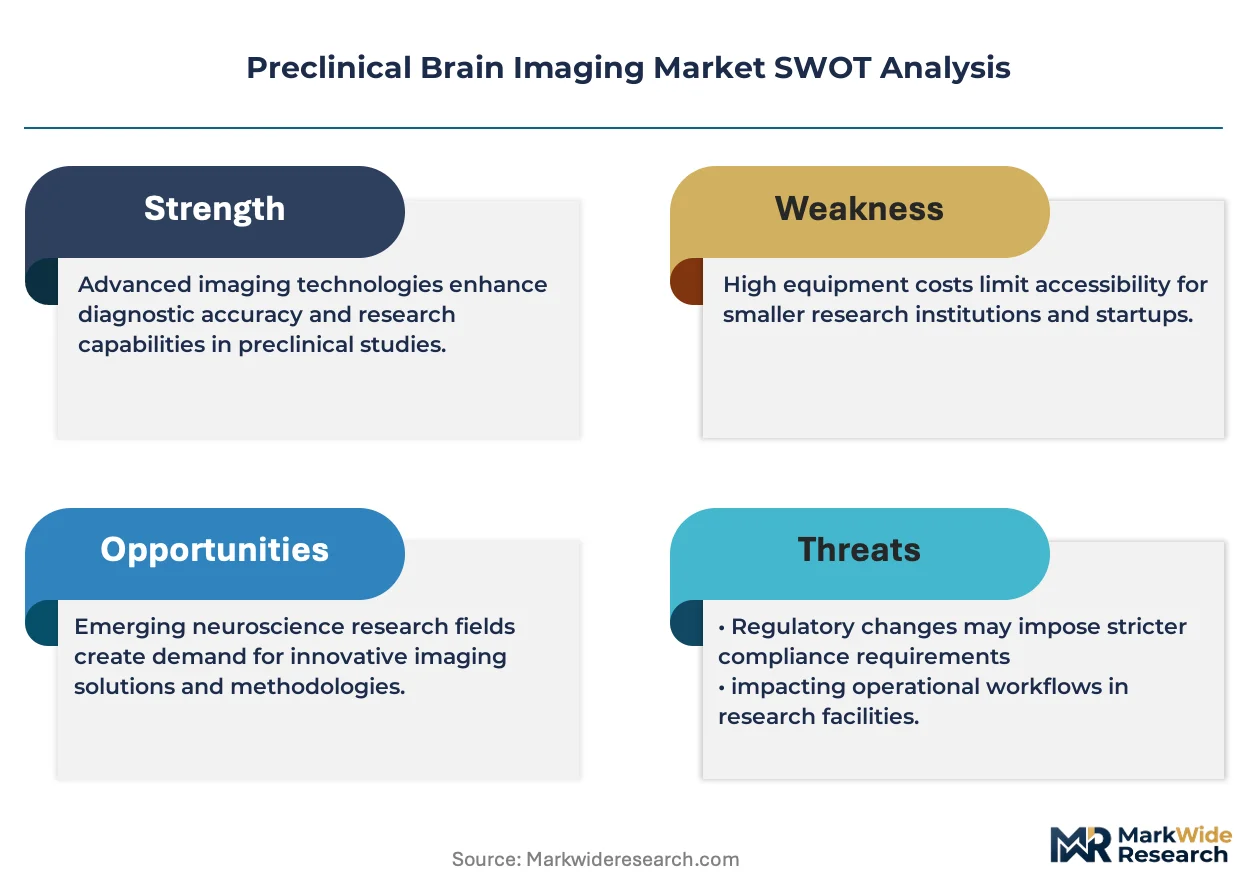
Strategic Opportunities
- India CDSCO Alignment:Emerging regulatory harmonization with ICH M3(R2) guidelines positions Indian CROs to capture outsourced neurotoxicology imaging from Western sponsors.
- AI-Accelerated Image Reconstruction:Deep learning denoising algorithms enable reduced scan times and lower gadolinium dosing in longitudinal rodent studies.
- Non-Human Primate Facilities:Southeast Asian breeding centers expand PET-MRI service capacity for Alzheimer's therapeutic antibody programs requiring closer phylogenetic models.
Industry Challenges
- Computational Pathology Skill Gap:Shortage of dual-trained imaging scientists fluent in both neuroanatomy and algorithm validation delays automated analysis deployment.
- Isotope Logistics Coordination:PET tracer half-lives below 110 minutes demand synchronized cyclotron production, animal handling, and scanner scheduling across distributed sites.
- Legacy System Interoperability:Proprietary DICOM extensions from 2010-era scanners block seamless data migration to cloud-based archival platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Preclinical Brain Imaging Market |
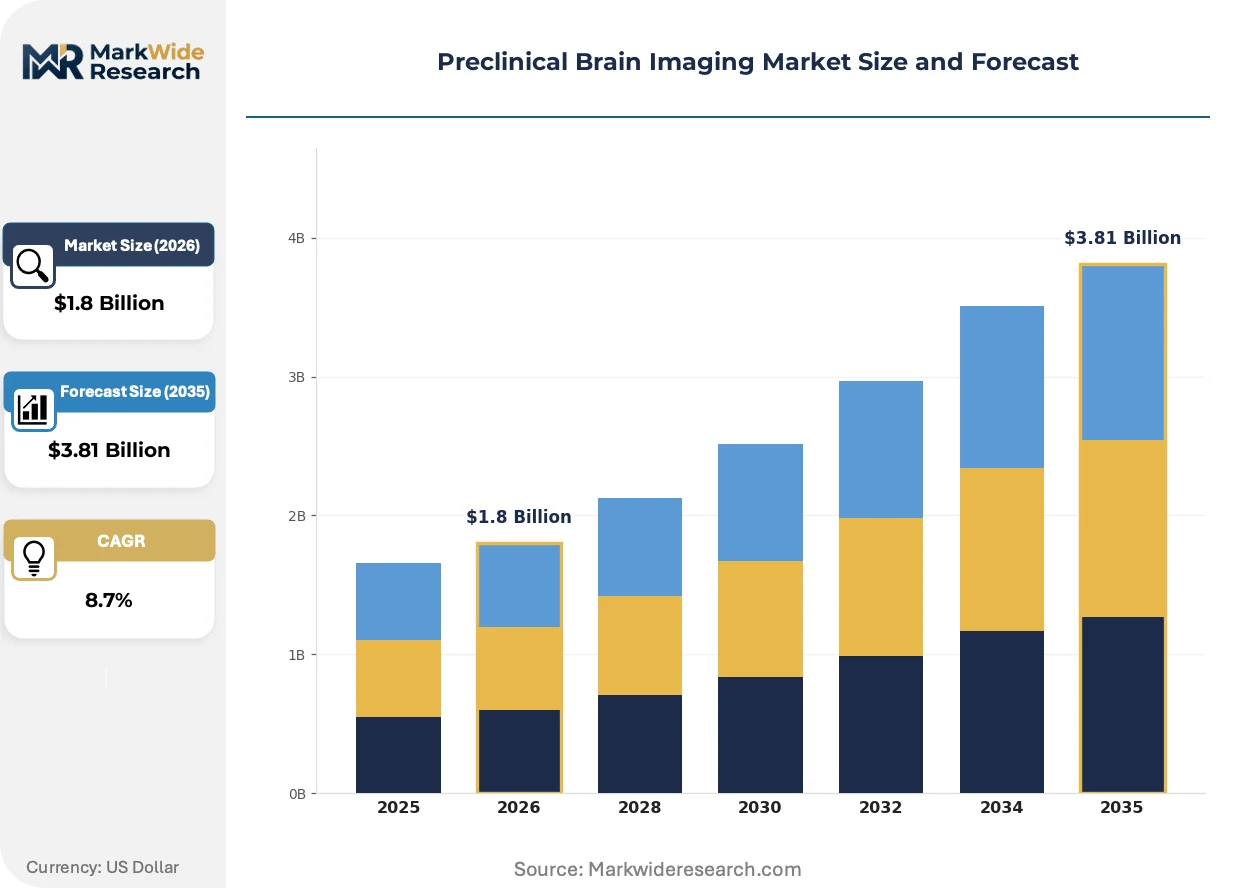
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Magnetic Resonance Imaging, Computed Tomography, Positron Emission Tomography, Optical Imaging End User: Pharmaceutical Companies, Academic Institutes, Biotech Firms, Contract Research Organizations Application: Drug Development, Disease Modeling, Neuroscience Research, Toxicology Studies Product Type: Imaging Systems, Software Solutions, Imaging Agents, Accessories |
| Companies Covered | Bruker Corporation, Siemens Healthineers, General Electric, TriFoil Imaging, PerkinElmer, Fujifilm VisualSonics, Mediso, Agilent Technologies, MILabs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Preclinical Brain Imaging Market Evolving Landscape
Preclinical brain imaging is converging around automated workflows that compress study timelines while expanding molecular specificity through tracer chemistry advances and computational integration.
Cryogen-free magnet technology is overtaking conventional liquid helium systems in mid-field MRI installations. Academic institutes in Germany and the Netherlands are retrofitting aging 7 Tesla platforms with closed-cycle refrigeration to eliminate helium dependency. This shift is compressing total cost of ownership curves and enabling deployment in facilities without cryogen infrastructure.
EMA's 2023 update to GLP imaging annexes now mandates audit trails for algorithm-assisted image analysis in regulatory submissions. Contract research organizations must validate computational pathology tools under the same rigor as hardware calibration. European neurodegenerative drug developers are responding by embedding ISO 13485-compliant software quality systems into imaging core facilities.
Consortium-based equipment sharing is displacing sole-ownership models among mid-tier pharmaceutical sponsors. Multi-site access agreements pool PET-MRI scanner time across academic medical centers and dedicated CRO campuses. This restructuring is most visible in the Boston-Cambridge and Basel-Zurich corridors, where sponsor demand concentrates around IND-enabling packages requiring rapid cohort turnaround.
Preclinical Brain Imaging Market Segmentation
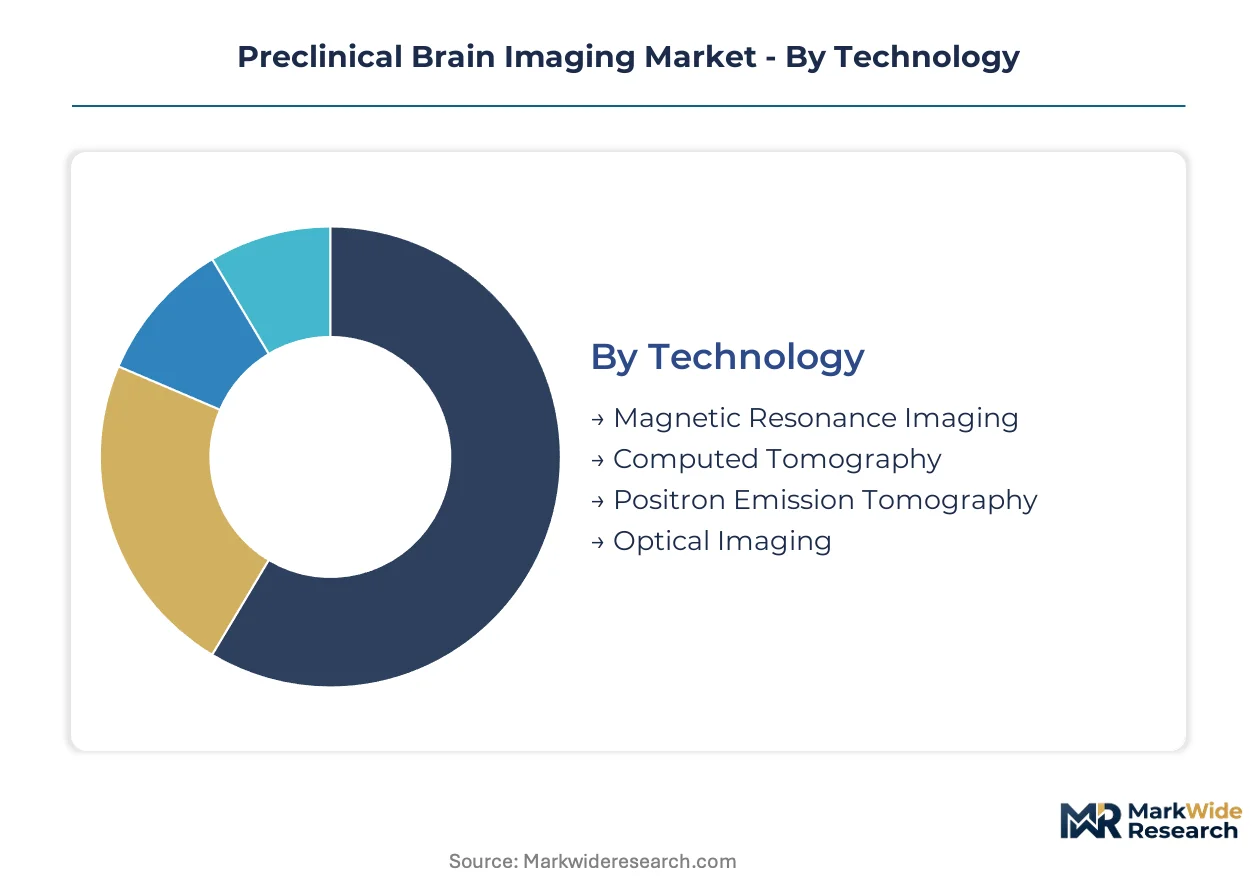
Preclinical brain imaging equipment and services fragment across four structural dimensions that determine procurement patterns, validation requirements, and vendor engagement models. Technology choices dictate capital intensity and regulatory pathway, while end-user concentration shapes pricing power and service bundling.
Technology:
Standalone imaging platforms dominate high-throughput CRO facilities, whereas hybrid multimodal systems embed into academic consortia requiring correlated structural-functional data.
- Magnetic Resonance Imaging:Cryogen-free 7 Tesla and 9.4 Tesla systems achieve sub-100 micrometer resolution in rodent brain atlasing without ionizing radiation. Demand concentrates in German Helmholtz centers and Dutch neuroscience institutes where federal funding sustains high-field infrastructure.
- Positron Emission Tomography:Radiochemistry automation now enables picomolar sensitivity tracer detection in mid-tier labs previously excluded by cyclotron capital barriers. Contract research organizations in the Boston-Cambridge corridor are consolidating procurement around integrated PET-MRI workflows to reduce isotope dosing in longitudinal neurodegenerative studies.
- Computed Tomography:Rapid bone-tissue contrast and calcium quantification support stroke and trauma modeling in acute time windows.
- Optical Imaging:Photoacoustic-ultrasound fusion systems occupy cerebrovascular phenotyping niches constrained by sub-2 millimeter tissue penetration limits.
Magnetic Resonance Imaging leads volumes today; Positron Emission Tomography is gaining share fastest.
End User:
Purchasing authority and validation burden vary sharply between sponsors outsourcing IND packages and institutions owning captive imaging cores.
- Contract Research Organizations:Multi-vendor platform consolidation fragments historical single-supplier dependencies as CROs diversify vendor relationships to secure pricing leverage and operational redundancy.
- Academic Institutes:Federal funding mechanisms in Germany and consortium-based equipment sharing in the Boston-Cambridge corridor displace sole-ownership models among mid-tier research programs.
- Pharmaceutical Companies:Internal imaging cores at large-cap sponsors retain strategic capacity for proprietary therapeutic antibody programs.
- Biotech Firms:Virtual development models drive reliance on outsourced imaging services rather than captive infrastructure investment.
Contract Research Organizations capture the most concentrated margin pool; Academic Institutes are expanding procurement most rapidly.
Application:
Regulatory submission requirements determine whether imaging endpoints qualify as primary efficacy readouts or supportive safety biomarkers.
- Drug Development:FDA 21 CFR Part 11 electronic records validation and EMA GLP imaging annexes mandate audit trails for algorithm-assisted analysis in IND-enabling packages.
- Disease Modeling:Alzheimer's therapeutic programs in Southeast Asian non-human primate facilities demand PET-MRI correlation for amyloid and tau pathology tracking.
- Neuroscience Research:Basic mechanistic studies face lighter validation burdens but require higher spatial resolution for connectomics applications.
- Toxicology Studies:GLP-compliant neurotoxicology imaging packages require ISO 13485 software quality systems and IEC 60601-1-3 electrical safety certification.
Drug Development commands premium pricing; Disease Modeling is climbing the fastest as antibody programs proliferate.
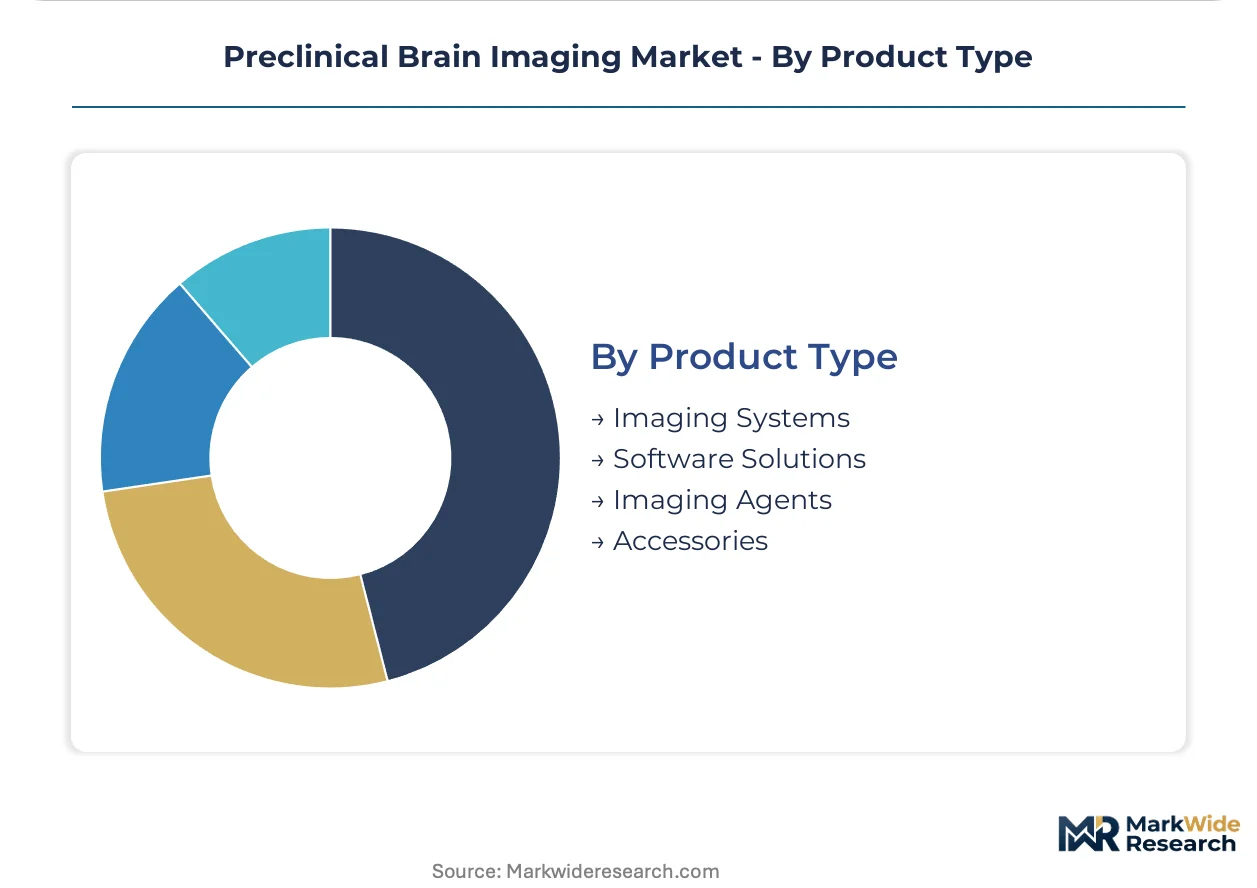
Product Type:
Hardware margins compress as software and consumables capture recurring revenue streams in installed base expansion strategies.
- Imaging Systems:Cryogen-free magnet retrofits and closed-cycle refrigeration systems are displacing conventional liquid helium platforms in European mid-field installations.
- Software Solutions:EMA's 2023 GLP imaging annex update mandates computational pathology tool validation under equivalent rigor to hardware calibration.
- Imaging Agents:Novel neurology tracers require synchronized cyclotron production, animal handling, and scanner scheduling across distributed sites.
- Accessories:RF coil arrays and animal handling systems differentiate vendor ecosystems through proprietary interfaces.
Imaging Systems dominate capital expenditure; Software Solutions are expanding most quickly as regulatory validation requirements deepen.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Boston-Cambridge corridor anchors global demand for preclinical brain imaging infrastructure, with contract research organizations clustering around IND-enabling neurotoxicology services. Academic medical centers in Germany and the Netherlands sustain high-field MRI procurement through federal funding mechanisms. Southeast Asian non-human primate facilities are expanding PET-MRI capacity for Alzheimer's therapeutic antibody programs.
United States
FDA 21 CFR Part 11 electronic records requirements extend equipment qualification timelines for IND-enabling toxicology programs. The Boston-Cambridge corridor concentrates CRO procurement around integrated PET-MRI workflows. Pharmaceutical sponsors outsource imaging packages to capture rapid cohort turnaround capabilities.
Germany
Helmholtz Association centers and Max Planck Institutes drive adoption of cryogen-free 7 Tesla and 9.4 Tesla systems. EMA preclinical imaging quality guidelines harmonize validation standards across GLP facilities. Munich and Heidelberg neuroscience clusters retrofit aging platforms with closed-cycle refrigeration to eliminate helium dependency.
Netherlands
Academic institutes in Amsterdam and Utrecht expand multimodal imaging procurement through consortium-based equipment sharing. Dutch neuroscience programs prioritize photoacoustic-ultrasound fusion systems for cerebrovascular phenotyping. Federal research funding displaces sole-ownership models among mid-tier research programs.
China
NMPA alignment with ICH M3(R2) guidelines positions domestic CROs to capture outsourced neurotoxicology imaging. Shanghai and Beijing academic medical centers install high-field preclinical MRI for translational neuroscience studies. Radiochemistry automation expands PET accessibility to mid-tier labs previously excluded by cyclotron capital barriers.
Singapore
Non-human primate breeding centers expand PET-MRI service capacity for Alzheimer's therapeutic programs. The country's national pharmaceutical regulator harmonizes preclinical imaging standards with ASEAN ICH guidelines. Biopolis research cluster attracts Western sponsors requiring closer phylogenetic models for antibody development.
Preclinical Brain Imaging Market Competitive Landscape
Global majors compete with regional champions across technology integration and service bundling dimensions. The vendor base stratifies into three tiers: integrated diagnostic conglomerates with multimodal platforms, specialized preclinical imaging firms with cryogen-free magnet expertise, and niche ultrasound-photoacoustic fusion providers. Strategic moves center on cross-modal data workflow integration and consortium-based equipment sharing agreements that displace sole-ownership procurement models.
Within the integrated diagnostic tier, Siemens Healthineers and General Electric exemplify global scale advantages through PET-MRI workflow integration. Bruker Corporation occupies a specialized position among cryogen-free magnet technology providers serving European neuroscience clusters. Fujifilm VisualSonics represents the niche specialist archetype with photoacoustic-ultrasound fusion systems for cerebrovascular applications.
| Leading Market Players |
|---|
| Bruker Corporation |
| Siemens Healthineers |
| General Electric |
| TriFoil Imaging |
| PerkinElmer |
| Fujifilm VisualSonics |
| Mediso |
| Agilent Technologies |
| MILabs |
| Others |
Value Network & Pricing Analysis
Captive integration into cryogen-free magnet manufacturing anchors both supply security and pricing power for European high-field MRI vendors. Siemens Healthineers and Bruker Corporation control magnet refrigeration subsystems through in-house production, insulating installed base pricing from Qatar and Algeria helium volatility while locking academic buyers into proprietary service contracts.
Pricing Analysis
Helium cost pass-through dominates pricing structures for conventional superconducting systems, with cryogen-free platforms commanding 15-25% premiums justified by total cost of ownership compression. Three-tier pricing structure across premium, standard, and economy levels separates GLP-validated PET-MRI workflows from mid-field academic installations and refurbished legacy hardware. Pricing pressure stems from radiochemistry automation expanding PET accessibility to mid-tier labs previously excluded by cyclotron capital barriers. Contract research organizations exhibit highest price sensitivity due to sponsor procurement consolidation, while Helmholtz Association centers accept premium positioning for federal-funded infrastructure.
Supply Chain Analysis
Domestic-content mandates in China's NMPA regulatory pathway reshape sourcing for cyclotron and magnet components, requiring local assembly partnerships for Western vendors seeking CRO market access. Manufacturing concentrates in Germany, the United States, and China for superconducting wire, gradient coil arrays, and PET detector crystals. Raw material dependencies include niobium-titanium superconductors, lutetium-based scintillators, and liquid helium reserves. Single-source vulnerability runs through Qatar's helium export concentration. Distribution feeds from vendor direct sales for high-field systems and regional service partners for consumables and software licenses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Preclinical brain imaging has shifted to a late-cycle quality story as EMA's 2023 GLP imaging annex mandates elevate validation requirements from hardware calibration to computational pathology software systems. Sponsor procurement now prioritizes audit-trail integrity over capital cost minimization.
For Market Incumbents: Hedge helium supply exposure by accelerating cryogen-free retrofit programs for European installed bases before Qatar export policy shifts. Lock CRO pricing power through integrated PET-MRI workflow bundling that embeds proprietary software validation layers resistant to unbundling. Counter radiochemistry automation threats by acquiring tracer synthesis platform specialists to capture recurring consumables revenue.
For New Entrants and Emerging Players: CDSCO alignment with ICH M3(R2) guidelines in India opens a window for CRO imaging service expansion as Western sponsors seek lower-cost IND-enabling neurotoxicology packages. Target mid-tier academic institutes in the Netherlands and Germany with photoacoustic-ultrasound fusion systems for cerebrovascular phenotyping niches underserved by MRI-PET incumbents. Pursue consortium-based equipment sharing agreements that displace sole-ownership procurement models among federal-funded neuroscience clusters.
For Investors and Strategic Acquirers: Roll-up economics work for specialized preclinical imaging software vendors because EMA and FDA regulatory convergence creates scarcity value for ISO 13485-compliant computational pathology tools. Five-to-ten year viability hinges on automated image analysis algorithm deployment at CRO scale. Monitor PET tracer half-life logistics coordination as the inflection signal—synchronized cyclotron production and scanner scheduling capabilities separate acquirable specialists from stranded asset risks.
| Strategic Initiative | Industry Significance |
|---|---|
| Cryogen-Free Magnet Retrofit | Eliminates Qatar helium dependency while extending high-field MRI service contract tenures in German Helmholtz centers. |
| Radiochemistry Automation Platform | Expands PET tracer accessibility to mid-tier academic labs previously excluded by cyclotron capital barriers. |
| Computational Pathology Validation | EMA's 2023 GLP annex mandates ISO 13485 software quality systems for algorithm-assisted regulatory submissions. |
| Non-Human Primate Facility Expansion | Southeast Asian breeding centers capture Alzheimer's antibody program demand requiring closer phylogenetic models. |
| Consortium Equipment Sharing Agreement | Pools PET-MRI scanner time across Boston-Cambridge academic medical centers and CRO campuses. |
Research Methodology
Direct dialogue with CRO imaging service directors, academic core facility managers, regulatory affairs specialists at FDA and EMA, and PET tracer radiochemistry operators grounded qualitative findings. Secondary validation drew from FDA 21 CFR Part 11 guidance documents, EMA preclinical imaging quality guidelines, ISO 13485 certification registries, and GLP facility inspection reports. Bottom-up equipment installation tracking and top-down pharmaceutical R&D spending analysis were triangulated against vendor shipment disclosures.
Market size outputs and growth trajectories were produced through segmented modeling across technology platform, end-user concentration, application regulatory burden, and geographic funding mechanism dimensions. CAGRs were derived from installed base expansion rates, replacement cycle compression, and tracer chemistry automation penetration curves. Forecast inputs incorporated Helmholtz Association federal budget allocations, IND submission volumes from FDA databases, and cyclotron infrastructure deployment patterns across academic medical centers.
Revisions become necessary when helium supply disruptions, regulatory algorithm validation requirement shifts, or AI-accelerated image reconstruction adoption curves materially alter equipment qualification timelines or CRO outsourcing economics. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Americas Interventional Radiology Market
Medical Imaging
Global Automated Breast Ultrasound System (ABUS) Market
Medical Imaging
Global Artificial Intelligence in Ultrasound Imaging Market
Medical Imaging
UK Digital Radiology Market
Medical Imaging
Global Refurbished Medical Imaging Equipment Market
Medical Imaging
Molecular Breast Imaging Market
Medical Imaging
Argentina Magnetic Resonance Imaging (MRI) Market
Medical Imaging
Medical Imaging Informatics Market
Medical Imaging
Brazil Computed Tomography Market
Medical Imaging
Industrial Computed Radiography Market
Medical Imaging
Medical Digital Imaging Systems Market
Medical Imaging
Spain Digital Radiology Market
Medical Imaging
Saudi Arabia Digital Radiology Market
Medical Imaging
Non-Invasive & Minimally Invasive Medical Imaging and Visualization Systems Market
Medical Imaging
Asia Pacific Computed Tomography (CT) Market
Medical Imaging
South America Mammography Market