
 Influenza Diagnostics Market | 2026-2036
Influenza Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Influenza Diagnostics Market Intelligence
Expanded manufacturing capacity in key Asian production hubs like China and South Korea is realigning the supply chain for rapid antigen test components. Abbott Laboratories leverages its extensive global distribution network to maintain market leadership in point-of-care solutions. QuidelOrtho specializes in rapid immunoassay tests, competing on speed and ease of use in outpatient settings. Meanwhile, bioMérieux differentiates through its sophisticated molecular diagnostic platforms, targeting hospital and high-complexity laboratory segments.
Influenza diagnostics encompass in vitro tests designed to detect the presence of influenza A and B viral antigens or nucleic acids in patient samples. These assays provide a definitive method for confirming infection, guiding antiviral treatment, and enabling epidemiological tracking. Rapid antigen tests dominate the point-of-care testing segment due to their speed and low cost, though with lower sensitivity. Nucleic acid amplification tests, including RT-PCR, represent the gold standard in diagnostic laboratories, offering superior accuracy and commanding higher reimbursement.
Regulatory oversight from bodies like the US FDA and compliance with Europe's CE marking under the MDR dictate stringent performance and quality requirements. In parallel, China's NMPA sets market access protocols for both domestic and imported diagnostic kits. The critical decision for test developers now revolves around investing in standalone influenza assays versus developing broader multiplex respiratory panels that can differentiate between clinically similar pathogens.
Market Dynamics
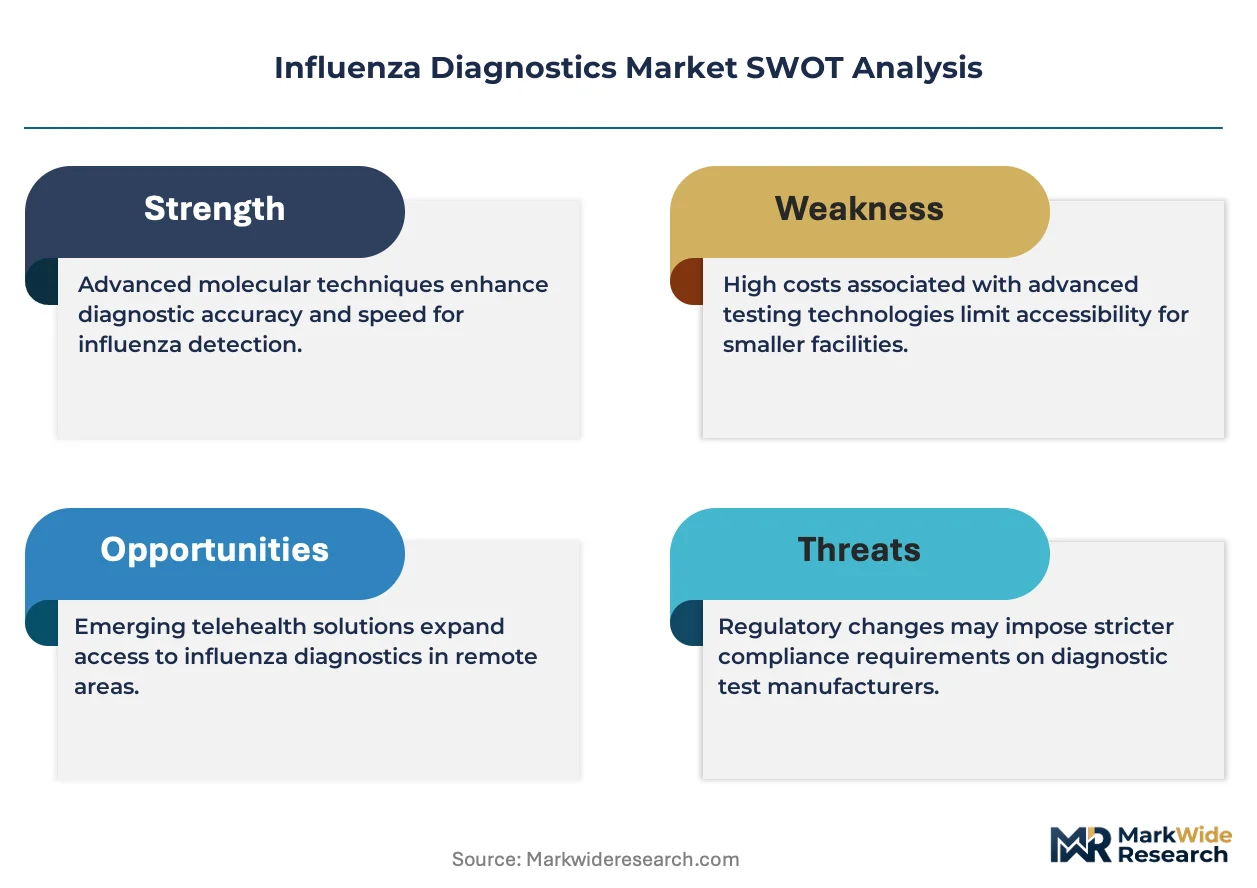
The central force shaping the influenza diagnostics market is the technological tension between rapid, low-cost antigen tests for point-of-care settings and highly accurate, but more complex, nucleic acid amplification tests used in laboratories, a gap that multiplex panels are beginning to bridge.
Growth Catalysts
- Multiplex Panel Development:The creation of multiplex PCR assays that simultaneously detect influenza A, B, and other respiratory pathogens like RSV and SARS-CoV-2 streamlines workflows in clinical laboratories and supports differential diagnosis from a single patient sample.
- Government Surveillance Programs:Public health initiatives, particularly seasonal influenza surveillance programs managed by agencies like the US Centers for Disease Control and Prevention (CDC), sustain high testing volumes and provide a stable demand floor for diagnostic manufacturers.
- Point-of-Care Expansion:Demand for rapid diagnostics is increasing in non-traditional settings such as primary care centers, outpatient clinics, and pharmacies, where quick results are essential for immediate patient management and antiviral prescription decisions.
Market Restraints
- Sensitivity Limitations:Rapid antigen tests, despite their speed and low cost, exhibit lower sensitivity compared to molecular assays, leading to a risk of false-negative results that can compromise patient care and infection control measures.
- High Cost of Molecular Testing:The capital expenditure for nucleic acid amplification test (NAAT) instruments and the higher per-test cost can be prohibitive for smaller clinics and healthcare facilities in resource-limited settings, constraining adoption.
- Stringent Regulatory Hurdles:Market access is governed by rigorous approval processes from bodies like the US FDA and China's NMPA, which involve lengthy and expensive clinical validation, delaying the introduction of new diagnostic products.
Strategic Opportunities
- At-Home Testing Kits:Developing over-the-counter influenza tests that offer high accuracy and digital connectivity presents an opportunity to empower consumers and expand the market beyond clinical settings, mirroring trends in other infectious diseases.
- Digital Health Integration:Linking diagnostic test results with digital health platforms enables real-time data reporting for epidemiological surveillance, creating value for public health organizations and ministries of health worldwide.
- Emerging Market Penetration:Expanding diagnostic infrastructure and test availability in underpenetrated regions, such as Latin America and Southeast Asia, offers significant long-term growth potential as healthcare systems in these areas modernize.
Industry Challenges
- Supply Chain Volatility:Manufacturers face challenges in managing a global supply chain for critical components like reagents and plastic consumables, with production concentrated in Asian hubs, creating vulnerability to geopolitical tensions and logistical disruptions.
- Data Interoperability:A lack of standardization for reporting results from diverse diagnostic platforms creates difficulties in integrating data into electronic health records and national surveillance systems, limiting the utility of collected information.
- Multiplex Licensing Complexity:Developing broad respiratory panels requires navigating a complex intellectual property landscape, involving licensing agreements for various pathogen targets, which can increase development costs and time-to-market.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Influenza Diagnostics Market |
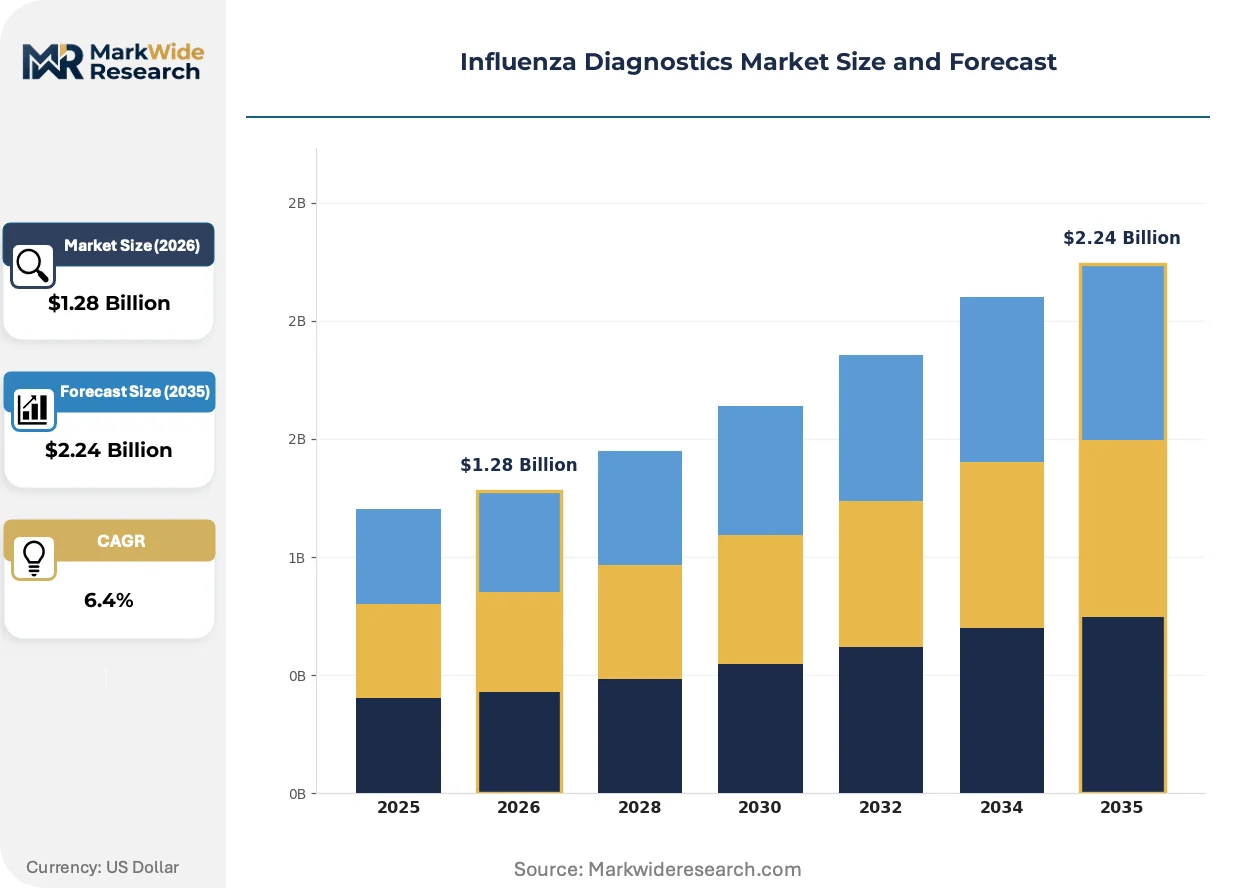
| Market Size in 2026 | $1.28 Billion |
| Market Size in 2035 | $2.24 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rapid Antigen Test, Nucleic Acid Amplification Test, Immunofluorescence Assay, Serological Test, Molecular Test Application: Clinical Diagnosis, Point-of-Care Testing, Epidemiological Surveillance, Vaccine Development, Blood Screening End User: Diagnostic Laboratories, Research Institutions, Public Health Agencies, Primary Care Centers, Specialty Clinics Deployment: Hospital-based, Standalone, Mobile Clinics, Community Health Centers, Telemedicine Platforms |
| Companies Covered | Abbott Laboratories, F. Hoffmann-La Roche Ltd, Becton Dickinson and Company, Thermo Fisher Scientific, QuidelOrtho, Danaher Corporation, Hologic, bioMérieux, Siemens Healthineers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Influenza Diagnostics Market Strategic Shifts & Innovations
The market is being redefined by the push for diagnostic decentralization, moving testing from centralized labs closer to the patient. This shift prioritizes speed and actionable results, influencing both product development and regulatory pathways for new influenza assays.
Multiplex molecular technologies allow for the simultaneous detection of multiple respiratory pathogens from one sample. High-complexity laboratories and hospitals are the primary adopters of these comprehensive panels. This capability is absorbing the testing volume previously managed by numerous separate, single-pathogen assays, thereby consolidating laboratory workflows and reducing turnaround time.
Europe's stringent In Vitro Diagnostic Regulation (IVDR) is elevating compliance requirements for all diagnostic manufacturers. The regulation imposes stricter demands for clinical evidence, performance evaluation, and post-market surveillance. Consequently, companies targeting the European market must allocate significant resources to update technical files and quality management systems to maintain their CE marking.
A notable behavioral change is the migration of testing services from hospitals to decentralized locations like retail pharmacies and urgent care clinics. This "test-and-treat" model, where a diagnosis is immediately followed by a prescription, is disrupting conventional patient care pathways. The trend is especially visible in the United States, where major pharmacy chains are expanding their role as primary healthcare access points.
Influenza Diagnostics Market Segmentation
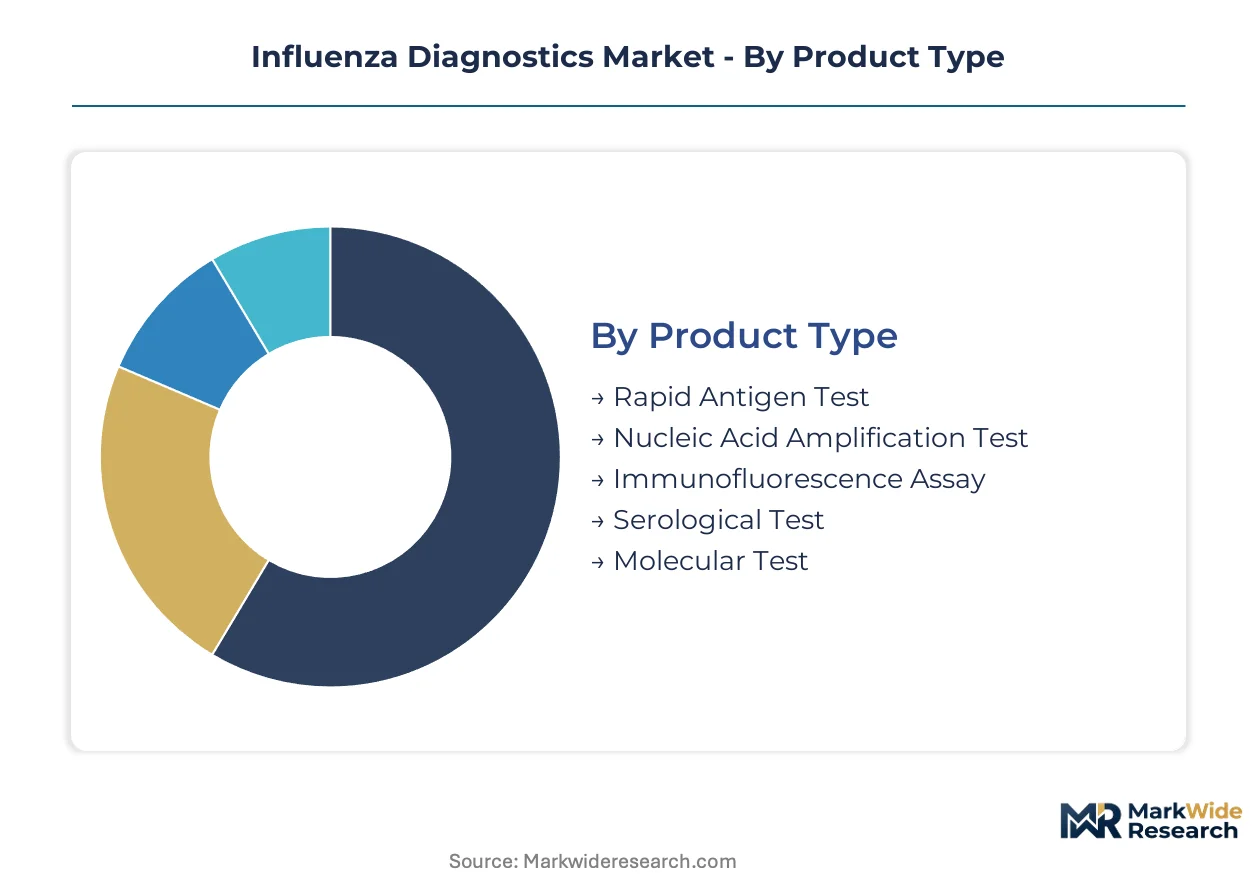
The influenza diagnostics market is segmented by technical specifications, intended use, operational settings, and target end-users. This classification helps manufacturers align product development with specific clinical needs and assists healthcare providers in optimizing diagnostic workflows.
Product Type:
Buyer decisions for influenza diagnostic products balance speed, accuracy, and cost, influencing the chosen testing methodology.
- Rapid Antigen Test:These assays detect viral proteins from samples, providing results within minutes at the point of care. Demand concentrates in primary care centers for quick patient management.
- Nucleic Acid Amplification Test:NAATs, including RT-PCR, detect viral genetic material with high sensitivity and specificity. These tests command higher reimbursement in hospital laboratories due to superior accuracy.
- Immunofluorescence Assay:IFAs identify viral antigens using fluorescently labeled antibodies, employed in labs for initial screening.
- Serological Test:These tests detect host antibodies to infection, primarily for epidemiological studies.
- Molecular Test:Nucleic acid-based methods offer high precision for differentiating influenza strains and other respiratory pathogens.
Volume sits with Rapid Antigen Test; growth tilts toward Nucleic Acid Amplification Test.
Application:
The specific application dictates required performance characteristics and operational environment for influenza diagnostic tools.
- Clinical Diagnosis:This application involves identifying active influenza infections in symptomatic patients to guide treatment decisions. Diagnostic laboratories and primary care centers drive demand.
- Point-of-Care Testing:POCT involves tests outside traditional laboratory settings, delivering rapid results directly to the patient. This segment is expanding most quickly due to decentralized healthcare access.
- Epidemiological Surveillance:This application monitors influenza prevalence, strain types, and geographic spread, crucial for public health agencies.
- Vaccine Development:Diagnostic tools support vaccine research by identifying circulating strains and evaluating vaccine efficacy.
- Blood Screening:Certain diagnostic methods may be used in specific research contexts related to viral presence in blood products.
Clinical utility drives demand in Clinical Diagnosis, while convenience and speed accelerate Point-of-Care Testing.
End User:
Different end-user segments require tailored diagnostic solutions, reflecting varying expertise and infrastructural capabilities.
- Diagnostic Laboratories:These facilities perform complex molecular and serological tests, serving as central hubs for high-volume, high-accuracy influenza diagnostics. They invest in automated platforms.
- Primary Care Centers:General practitioners use rapid, easy-to-use tests to quickly diagnose influenza, enabling prompt antiviral prescriptions. Demand is high for cost-effective solutions.
- Research Institutions:These organizations employ advanced techniques for studying viral evolution and developing novel diagnostic markers.
- Public Health Agencies:Government bodies use diagnostic data for surveillance, outbreak management, and guiding public health interventions.
- Specialty Clinics:Urgent care centers require rapid, accurate diagnostics to manage patient flow and prevent nosocomial transmission.
Investment flows into Diagnostic Laboratories for advanced platforms, with Primary Care Centers addressing immediate patient needs.
Deployment:
The deployment model impacts accessibility, turnaround time, and integration into existing healthcare infrastructure.
- Hospital-based:Diagnostics are conducted within hospital laboratories or dedicated testing units, supporting inpatient care and emergency departments. This model ensures access to high-complexity testing.
- Standalone:Independent diagnostic centers and reference laboratories offer a broad spectrum of influenza tests, often handling samples referred from multiple healthcare providers. These facilities focus on specialized testing.
- Mobile Clinics:These portable units bring testing services directly to underserved communities or during outbreaks, enhancing diagnostic accessibility.
- Community Health Centers:Local health centers provide essential diagnostic services, often relying on rapid tests for influenza management.
- Telemedicine Platforms:Telemedicine integrates diagnostic results from other settings to inform remote consultations and treatment plans.
Hospital-based facilities remain foundational for comprehensive care, and Standalone centers drive efficiency through specialized testing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States anchors demand for influenza diagnostics, driven by extensive seasonal surveillance programs and high testing volumes. Manufacturing capacity in Asian hubs like China and South Korea supports global supply. European markets also maintain significant demand, influenced by stringent regulatory frameworks.
United States
Demand for rapid influenza diagnostics in the United States stems from widespread point-of-care testing in primary care centers. The US Centers for Disease Control and Prevention (CDC) sustains high testing volumes through robust surveillance programs. Major pharmaceutical and diagnostic companies in regions like California and Massachusetts drive innovation in multiplex PCR panels.
China
China's influenza diagnostics market benefits from a robust domestic manufacturing base for rapid antigen test components. The National Medical Products Administration (NMPA) dictates stringent market access protocols for both local and imported diagnostic kits. Production hubs in regions like the Yangtze River Delta are expanding capacity for new diagnostic technologies.
South Korea
South Korea exhibits strong demand for advanced molecular diagnostics, particularly for multiplex respiratory panels. The Ministry of Food and Drug Safety (MFDS) oversees the regulatory approval process for diagnostic devices. Seoul and its surrounding Gyeonggi Province house numerous biotech firms specializing in innovative diagnostic assay development.
Germany
German healthcare providers increasingly adopt sophisticated molecular diagnostic platforms for precise influenza detection. Compliance with Europe's In Vitro Diagnostic Regulation (IVDR) under CE marking ensures high quality standards. Research institutions and diagnostic manufacturers in Bavaria contribute to the development of next-generation influenza assays.
India
India's market for influenza diagnostics is expanding due to modernization of healthcare infrastructure and increasing diagnostic accessibility. The Central Drugs Standard Control Organization (CDSCO) regulates diagnostic kit approvals and quality. Major metropolitan areas like Mumbai and Bengaluru are witnessing growth in diagnostic laboratory services.
Influenza Diagnostics Market Key Industry Players
Global majors compete with regional champions across diverse technology platforms, ranging from rapid antigen tests to complex molecular diagnostics. The market structure exhibits a tiered consolidation, with large diversified healthcare companies alongside specialized diagnostic firms. Strategic archetypes include innovation-driven molecular specialists, volume-focused point-of-care providers, and broad-portfolio diagnostic solution providers offering comprehensive respiratory panels. Capacity expansion and strategic partnerships are dominant competitive moves employed to broaden market reach and technology portfolios.
Specialists in point-of-care solutions, such as Abbott Laboratories, leverage extensive global distribution networks to maintain market leadership in rapid antigen testing. QuidelOrtho, a company focused on rapid immunoassay tests, occupies a position emphasizing speed and ease of use, particularly in outpatient settings for immediate patient management. Meanwhile, bioMérieux, a molecular diagnostics firm, exemplifies differentiation through sophisticated molecular platforms, specifically targeting hospital and high-complexity laboratory segments with high-accuracy assays. These distinct approaches underscore the varied operational strategies employed by key players within the influenza diagnostics market.
| Leading Market Players |
|---|
| Abbott Laboratories |
| F. Hoffmann-La Roche Ltd |
| Becton Dickinson and Company |
| Thermo Fisher Scientific |
| QuidelOrtho |
| Danaher Corporation |
| Hologic |
| bioMérieux |
| Siemens Healthineers |
Cost & Logistics Intelligence
The clear divergence between rapid antigen tests and sophisticated molecular diagnostics manifests in both pricing and supply chain configurations for influenza diagnostics. This bifurcation influences procurement decisions and manufacturing strategies across the market.
Pricing Analysis
Warranty and service bundling often differentiate molecular diagnostic platforms, while rapid antigen tests are typically sold on a per-unit transactional basis. Pricing stratifies across high-accuracy molecular tests and lower-cost rapid antigen kits. Price differentiation drivers include test sensitivity and specificity, the specific regulatory approval (e.g., US FDA, CE marking), and the speed of results. Pricing softness runs through the rapid antigen test segment due to commoditization. Primary care centers exhibit high price sensitivity for rapid tests, whereas diagnostic laboratories prioritize accuracy and platform integration, showing less sensitivity for molecular solutions.
Supply Chain Analysis
Reverse logistics for diagnostic instruments and expired reagent kits manage waste and potential refurbishment needs. Geographic supply concentration for critical components and some finished goods centers on China and South Korea, with advanced molecular platforms often originating from the USA and Germany. Raw material dependencies include specialized enzymes, viral RNA extraction kits, and plastic consumables like test cartridges. Geopolitical tensions impacting Asian production hubs pose a structural risk. Distribution runs through direct sales channels for large hospital networks and diagnostic laboratories, while distributor networks serve primary care centers and pharmacies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The influenza diagnostics market is becoming a vertical-integration race, with companies pursuing upstream control over critical reagent manufacturing to secure supply and manage costs.
For Market Incumbents:
Hedge against commoditization by investing in the research and development of next-generation multiplex PCR panels. Expand global distribution networks, especially in emerging markets, to maintain market share against regional competitors. Complying with stringent regulatory frameworks like Europe's IVDR ensures continued market access. Focus on integrating diagnostic platforms with digital health solutions to provide added value beyond testing.
For New Entrants and Emerging Players:
Launch via direct-to-consumer channels with innovative at-home testing kits that offer high accuracy and digital connectivity. Target underpenetrated regions in Latin America and Southeast Asia by expanding diagnostic infrastructure. Focus on developing cost-effective, rapid molecular solutions tailored for outpatient clinics and pharmacies. A go-to-market angle emphasizing ease of use and immediate actionable results can capture market share.
For Investors and Strategic Acquirers:
Re-rating potential sits with specialized molecular diagnostics firms given the increasing demand for high-accuracy multiplex panels. Long-term viability favors companies with robust intellectual property portfolios and strong regulatory compliance. Acquire digital health platform providers to integrate diagnostic results with real-time epidemiological surveillance systems. Investors should monitor the adoption rates of multiplex respiratory panels in hospital settings as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Multiplex PCR Panel Development | Consolidates laboratory workflows and enhances diagnostic accuracy. |
| Capacity Expansion in Asian Hubs | Secures global supply for critical test components. |
| Digital Health Platform Integration | Enables real-time epidemiological surveillance and data utility. |
| IVDR Compliance Upgrades | Ensures market access and maintains quality standards in Europe. |
| At-Home Test Kit Development | Expands market reach and empowers consumer-driven diagnostics. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, providing a comprehensive view of market dynamics. This analysis combined extensive primary interviews with diagnostic company executives, hospital laboratory directors, primary care physicians, and public health officials. Secondary data sources included US FDA approvals, CE marking databases, China's NMPA announcements, and WHO influenza surveillance reports. The approach employed bottom-up analysis of market segments, validated through top-down reconciliation with overall market size estimates.
Data-stream reconciliation ensured consistency across various data points, building a robust analytical framework for market projections. The forecast framework modeled segmentation dimensions including product type, application, end user, deployment model, and regional regulatory clusters. Compound annual growth rates were derived from historical trend analysis and projected adoption rates of new diagnostic technologies. Key forecast inputs included public health spending on surveillance programs and new diagnostic technology approvals.
The model assumes a particular technology adoption path; alternative pathways for multiplex molecular diagnostics would alter the outlook. Forecasts reflect assumptions regarding regulatory changes and pandemic preparedness funding levels. Supply chain disruptions and the emergence of novel respiratory pathogens represent specific risk factors. Practitioners should monitor public health policy shifts and major technological breakthroughs in diagnostics for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
North America Autoimmune Disease Diagnostics Market
Diagnostics
Connected Diagnostics Market
Diagnostics
LDL Test Market
Diagnostics
Diabetic Assays Market
Diagnostics
Global Serological Testing Market
Diagnostics
Global Artificial Intelligence (AI) in Diagnostics Market
Diagnostics
In Vitro Diagnostic Substrate Market
Diagnostics
Immunoassay Interference Blocker Market
Diagnostics
Thrombosis and Hemostasis Biomarkers Market
Diagnostics
Clostridium Diagnostics Market
Diagnostics
Alanine Aminotransferase Reagent Market
Diagnostics
Global Non-Small Cell Lung Cancer Diagnostics Market
Diagnostics
Infectious Respiratory Disease Diagnostics Market
Diagnostics
Complement C3 ELISA Kits Market
Diagnostics
Population Screening Market
Diagnostics
Europe Lung Cancer Diagnostics Market