
 North America Breast Cancer Screening Tests Market | 2026-2036
North America Breast Cancer Screening Tests Market Size, Share, and Industry Trends Forecast 2026-2036
North America Breast Cancer Screening Tests Market Analytics
Aftermarket service revenue from legacy mammography systems is fragmenting across independent service organizations and original equipment manufacturers. Hologic Inc. leverages its installed base of 3D mammography systems to sustain recurring service contracts. GE Healthcare competes through backward integration into imaging software and AI-assisted detection tools. Siemens Healthineers anchors its North American position with dense field engineering coverage across major hospital networks.
North America breast cancer screening tests encompass imaging modalities and molecular assays designed to detect malignant tissue prior to symptomatic presentation, with mammography systems typically operating at 25-30 kVp target filtration and digital detectors achieving spatial resolution of 70-100 micrometers. These technologies serve the primary commercial purpose of enabling early-stage intervention, where tumor burden remains localized and treatment protocols carry higher probability of curative outcome. Mammography and tomosynthesis command the dominant share of procedure volume, while MRI screening captures premium positioning in high-risk patient stratification. Ultrasound segments extend access in dense breast tissue populations where conventional mammography sensitivity degrades. Diagnostic centers and hospitals represent the principal end-user channels, with automated workflow technologies gaining traction in high-throughput screening programs.
FDA mammography quality standards under the Mammography Quality Standards Act govern equipment performance, personnel certification, and medical audit requirements across United States screening facilities. Health Canada and the Canadian Partnership Against Cancer coordinate provincial screening program guidelines, creating heterogeneous reimbursement landscapes across Ontario, Quebec, and British Columbia. Stakeholders must monitor evolving AI diagnostic algorithm classification pathways and provincial funding commitments to anticipate capital deployment timing and technology refresh cycles.
Market Dynamics
FDA's updated mammography quality standards are compressing equipment refresh cycles across United States screening networks, forcing capital redeployment toward digital breast tomosynthesis systems and AI-enhanced detection platforms.
Growth Catalysts
- MQSA Equipment Mandates:The Mammography Quality Standards Act requires facilities to upgrade analog systems to full-field digital mammography, creating replacement demand across California, Texas, and Florida hospital networks.
- Dense Breast Notification Laws:State-level mandates in 38 US jurisdictions require physicians to inform patients of dense breast tissue status, driving supplemental ultrasound and MRI screening volumes.
- 3D Tomosynthesis Diffusion:Academic medical centers in Ontario and British Columbia are deploying DBT as standard-of-care, expanding procedure throughput per screening slot.
Market Restraints
- Radiologist Workforce Constraints:The American College of Radiology reports fellowship-trained breast imager shortages in rural Wisconsin, Alabama, and Mississippi markets, limiting screening program expansion.
- helium Supply Vulnerability:MRI screening dependence on liquid helium for magnet cooling exposes high-risk patient protocols to price volatility from Qatar and Russia supply disruptions.
- Provincial Reimbursement Fragmentation:Health Canada's non-binding screening guidelines create coverage gaps between Ontario's organized program and Quebec's opportunistic screening model.
Strategic Opportunities
- AI Algorithm Integration:FDA's 510(k) pathway for computer-aided detection software creates vendor opportunity to embed machine learning into existing Hologic and GE Healthcare installed bases.
- Mobile Screening Units:Federally Qualified Health Centers in Texas Rio Grande Valley and Central Valley California are deploying truck-based mammography to reach uninsured populations.
- Contrast-Enhanced Mammography:Emerging iodinated contrast protocols offer MRI-equivalent sensitivity at lower cost, positioning community hospitals to capture high-risk surveillance volumes.
Industry Challenges
- Interoperability Friction:DICOM standard variations between tomosynthesis vendors complicate image exchange across Kaiser Permanente, Mayo Clinic, and Cleveland Clinic multi-site networks.
- Quality Control Personnel Certification:MQSA mandates for medical physicist oversight of digital systems strain accredited inspector availability in Mountain West and Great Plains states.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Breast Cancer Screening Tests Market |
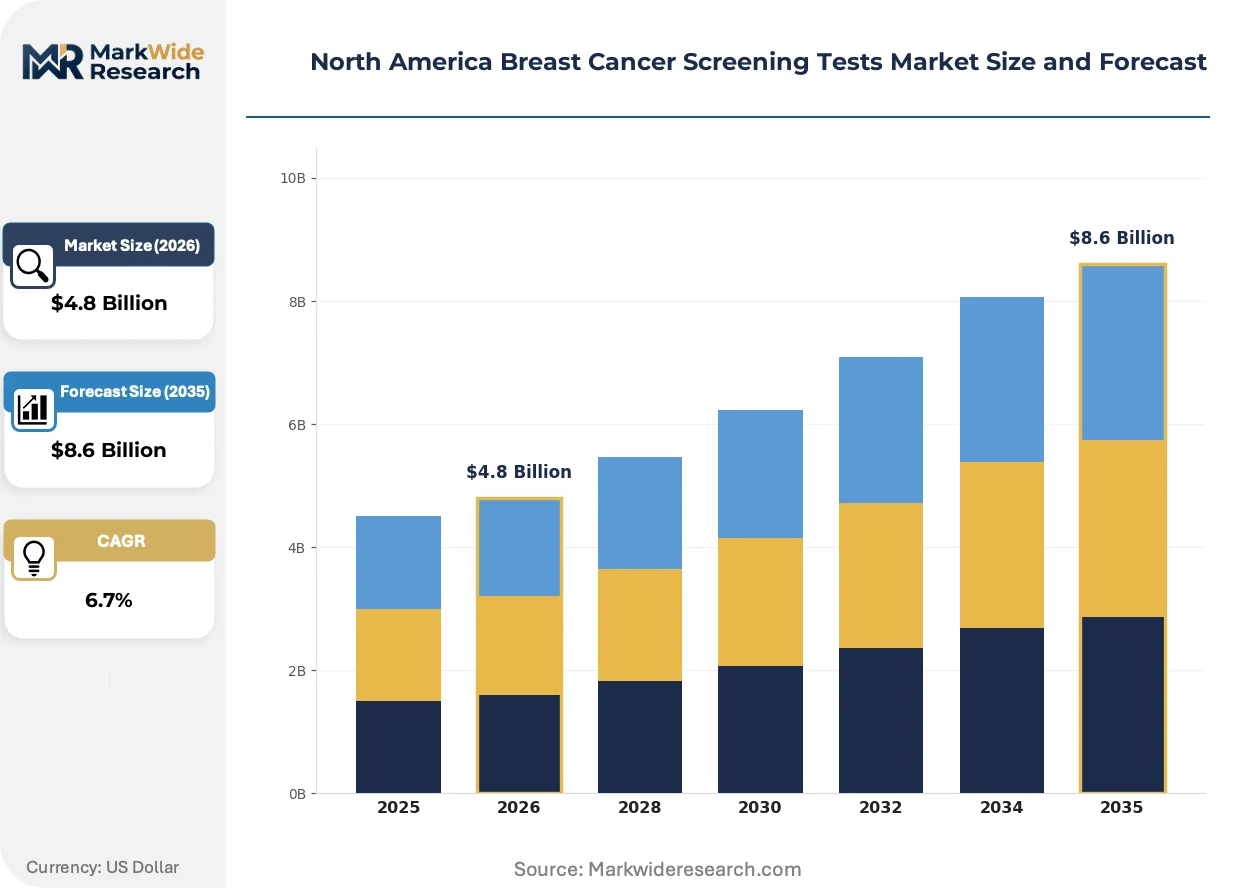
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: Mammography, MRI, Ultrasound, Tomosynthesis End User: Hospitals, Diagnostic Centers, Clinics, Research Institutions Technology: Digital, Conventional, 3D, Automated Application: Early Detection, Routine Screening, Follow-Up, Diagnosis |
| Companies Covered | Hologic Inc., Siemens Healthineers, GE Healthcare, Myriad Genetics, Fujifilm Holdings Corporation, Philips Healthcare, QIAGEN NV, Quest Diagnostics Incorporated, Exact Sciences Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Breast Cancer Screening Tests Market Evolving Landscape
Artificial intelligence integration and workflow automation are compressing interpretation timelines while dense breast tissue protocols are expanding modality mix beyond conventional mammography across North American screening programs.
Digital breast tomosynthesis is digitizing planar mammography acquisition by capturing multiple projection angles for synthetic reconstruction. Community health systems in suburban Dallas and Phoenix are replacing 2D systems at 18-month deployment cycles. This technology is digitizing film-based archives and enabling cloud-native storage architectures that reduce physical footprint in urban medical office buildings.
The FDA's 2023 mammography quality standards amendment mandates electronic reporting of patient breast density and facility performance metrics to central registries. Equipment vendors must embed automated quality assurance software to maintain accreditation. Dense breast notification compliance is most acute in Texas and California, where state laws predate federal requirements and impose additional disclosure obligations.
Patient self-scheduling through hospital portal systems is displacing physician-referral gatekeeping in Ontario and British Columbia provincial programs. Direct-to-consumer booking platforms operated by Screening Mammography Program of British Columbia and Cancer Care Ontario are capturing asymptomatic women outside traditional primary care pathways. This behavioral shift concentrates demand in metropolitan corridors where digital infrastructure supports automated eligibility verification and result delivery.
North America Breast Cancer Screening Tests Market Segmentation
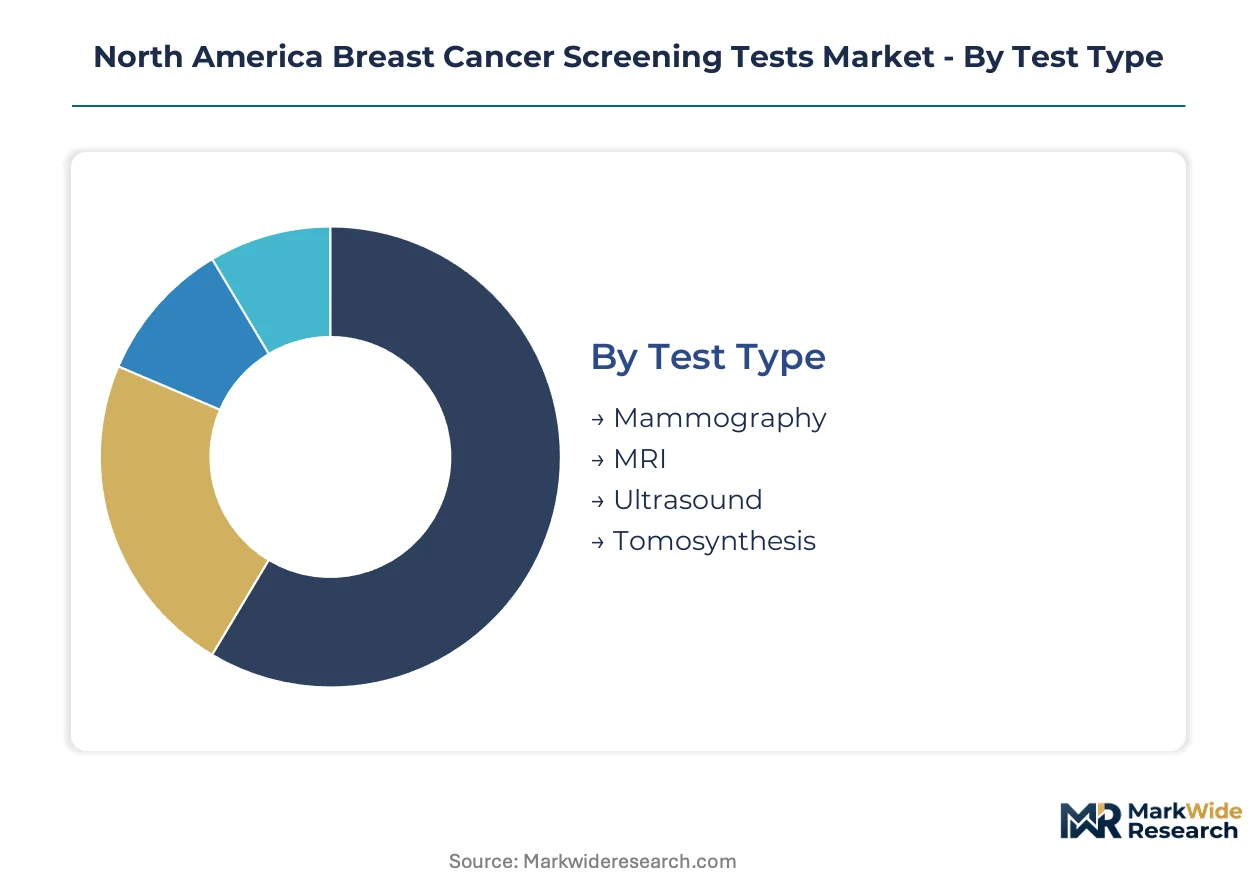
Segmentation reveals how modality mix, care setting, and workflow automation stratify procurement decisions across North American screening networks. Understanding these divisions exposes where capital deployment concentrates and where technology refresh cycles accelerate.
Test Type:
Use-case spectrum spans asymptomatic population screening through high-risk surveillance, with modality selection driven by tissue density, risk stratification, and reimbursement parity.
- Mammography:Full-field digital systems operate at 25-30 kVp with 70-100 micrometer spatial resolution. Demand concentrates in California and Texas hospital networks where MQSA mandates force analog-to-digital conversion.
- Tomosynthesis:Multi-angle projection reconstruction generates synthetic 3D slices, reducing tissue overlap artifacts. Academic medical centers in Ontario and British Columbia deploy DBT as standard-of-care, expanding throughput per screening slot.
- MRI:High-field systems with dedicated breast coils serve BRCA-positive and dense breast cohorts in Mayo Clinic and Cleveland Clinic referral networks.
- Ultrasound:Handheld and automated whole-breast systems extend access in dense breast populations where conventional mammography sensitivity degrades, particularly in 38 US jurisdictions with notification laws.
Established volume favors Mammography; emerging adoption favors Tomosynthesis.
End User:
Procurement authority and patient volume determine equipment specification, with integrated delivery networks commanding premium configurations.
- Hospitals:Kaiser Permanente and Mayo Clinic multi-site networks require DICOM-compliant tomosynthesis with enterprise PACS integration. Capital budgets accommodate AI-enhanced detection platforms and automated quality assurance software.
- Diagnostic Centers:High-throughput screening programs in suburban Dallas and Phoenix prioritize rapid image acquisition and cloud-native storage architectures.
- Clinics:Federally Qualified Health Centers in Texas Rio Grande Valley deploy truck-based mobile units to reach uninsured populations.
- Research Institutions:Dana-Farber and MD Anderson anchor clinical trial recruitment for contrast-enhanced mammography protocols and AI algorithm validation.
Capital deployment concentrates in Hospitals; patient access expansion targets Clinics.
Technology:
Workflow maturity and interoperability requirements segment procurement between legacy-compatible and cloud-native architectures.
- Digital:Detector-based acquisition with soft-copy interpretation dominates United States screening facilities under MQSA equipment mandates.
- 3D:Tomosynthesis reconstruction engines require enhanced computing infrastructure, positioning community health systems for 18-month replacement cycles.
- Conventional:Analog film-screen systems persist in rural Wisconsin and Alabama markets where radiologist workforce constraints limit program expansion.
- Automated:FDA 510(k) cleared computer-aided detection software embeds machine learning into existing installed bases, compressing interpretation timelines.
Regulatory pressure accelerates Digital transition; Automated represents the fastest-growing trajectory.
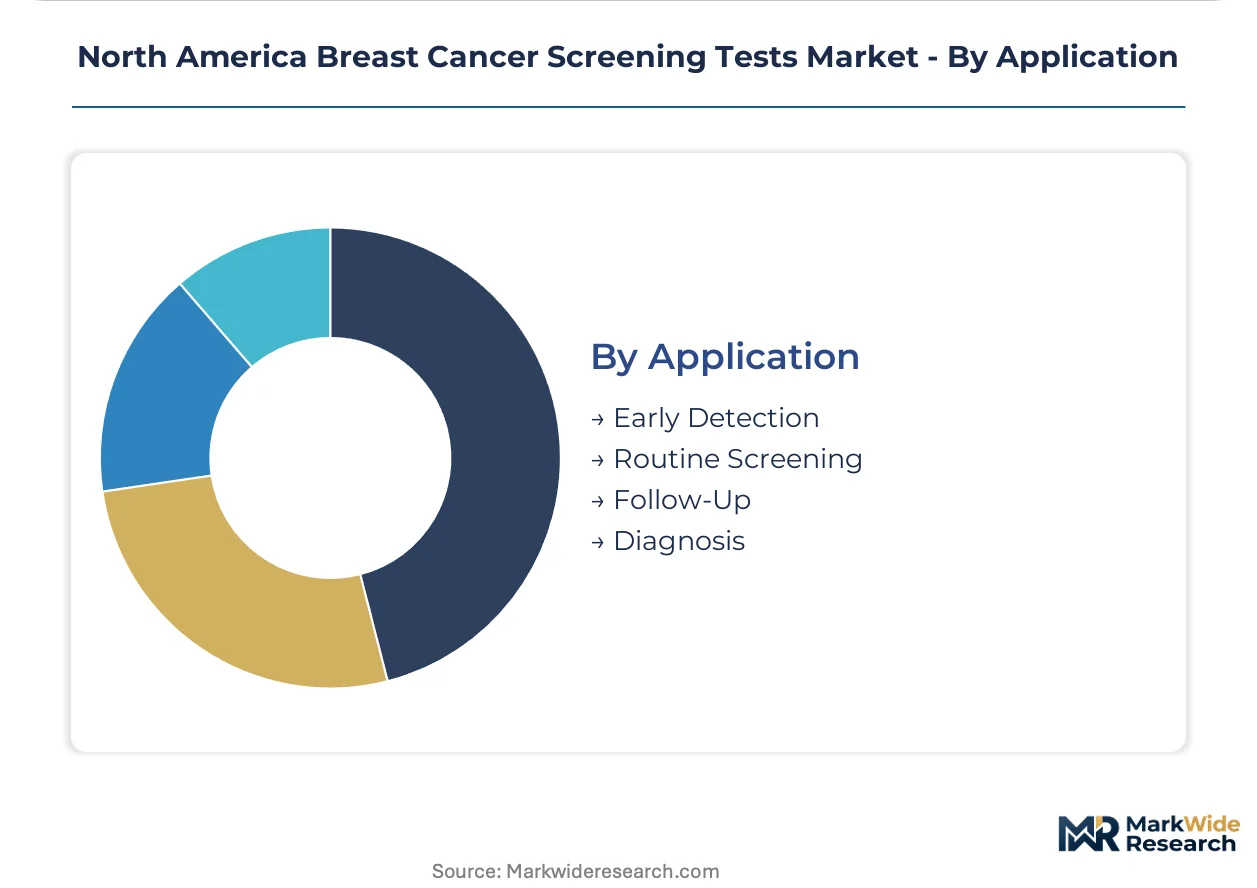
Application:
Clinical intent shapes modality intensity and reimbursement pathway, from asymptomatic surveillance through diagnostic workup.
- Routine Screening:Asymptomatic women aged 40-74 drive procedure volume through Cancer Care Ontario and Screening Mammography Program of British Columbia direct-to-consumer portals.
- Early Detection:Tumor burden localization protocols prioritize curative outcome probability, commanding premium positioning in high-risk patient stratification.
- Follow-Up:Surveillance imaging for prior benign biopsies or dense breast status generates supplemental ultrasound and MRI volumes under state notification laws.
- Diagnosis:Tissue characterization and staging protocols integrate contrast-enhanced mammography as MRI-equivalent sensitivity at lower cost.
Population coverage anchors Routine Screening; clinical value concentrates in Early Detection.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment procurement concentrates in metropolitan corridors where hospital networks command capital budgets and regulatory mandates force technology refresh cycles. The FDA's Mammography Quality Standards Act drives analog-to-digital conversion timelines. Provincial screening programs in Canada create heterogeneous reimbursement landscapes.
United States
California and Texas metropolitan corridors anchor equipment demand as Kaiser Permanente and Mayo Clinic multi-site networks expand 3D tomosynthesis deployment. The FDA's updated MQSA standards mandate electronic reporting of patient breast density and facility performance metrics to central registries. Dense breast notification laws in 38 US jurisdictions drive supplemental ultrasound and MRI screening volumes.
Canada
Ontario and British Columbia provincial programs deploy direct-to-consumer booking platforms that capture asymptomatic women outside traditional primary care pathways. Health Canada coordinates with the Canadian Partnership Against Cancer to establish non-binding screening guidelines that create coverage gaps between organized and opportunistic screening models. Academic medical centers in Toronto and Vancouver deploy digital breast tomosynthesis as standard-of-care.
Mexico
Private hospital networks in Mexico City and Monterrey import refurbished digital mammography systems from US hospital decommissioning cycles. The national pharmaceutical regulator oversees medical device registration pathways for imaging equipment. Diagnostic chains in Guadalajara and Puebla concentrate screening capacity for insured populations in central Mexico.
North America Breast Cancer Screening Tests Market Competitive Landscape
Full-system vendors and molecular assay specialists split the market between imaging hardware procurement and genetic testing services. The vendor base clusters around three strategic archetypes: integrated imaging conglomerates with software-AI stacks, independent diagnostic laboratories with proprietary assay platforms, and regional service organizations maintaining legacy installed bases. Dominant competitive moves include backward integration into imaging software and AI-assisted detection tools, plus dense field engineering coverage across major hospital networks.
Within the integrated imaging tier, Hologic Inc. and GE Healthcare exemplify archetypes leveraging installed bases to sustain recurring service contracts and embed machine learning into existing equipment. Siemens Healthineers anchors its position through engineering coverage density. Among molecular diagnostic specialists, Myriad Genetics and Exact Sciences Corporation occupy positions in genetic risk stratification and liquid biopsy screening protocols.
| Leading Market Players |
|---|
| Hologic Inc. |
| Siemens Healthineers |
| GE Healthcare |
| Myriad Genetics |
| Fujifilm Holdings Corporation |
| Philips Healthcare |
| QIAGEN NV |
| Quest Diagnostics Incorporated |
| Exact Sciences Corporation |
| Others |
Value Network & Pricing Analysis
Greater Boston's concentration of FDA-cleared imaging software developers feeds pricing power downstream to hospital procurement committees negotiating enterprise-wide mammography contracts. Equipment vendors leverage this geographic clustering to bundle AI-enhanced detection modules at premium service tiers while independent service organizations compete on legacy system maintenance.
Pricing Analysis
Aftermarket service contracts generate lifetime value exceeding initial equipment sales for full-field digital mammography systems. Pricing stratifies across premium, standard, and economy tiers based on detector resolution specifications and AI software bundling. Cost compression in economy-tier refurbished equipment intensifies as US hospital decommissioning cycles accelerate. Federally Qualified Health Centers exhibit highest price sensitivity; academic medical centers prioritize performance over unit cost.
Supply Chain Analysis
Helium supply disruption risk between Qatar and Russia dominates MRI magnet cooling logistics across North American screening networks. Manufacturing concentrates in Germany, Japan, and the United States for high-field breast coils and digital detector arrays. Component sourcing draws from specialized semiconductor foundries in Taiwan and South Korea for image reconstruction chipsets. Distribution runs through authorized dealer networks serving integrated delivery networks and independent diagnostic centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
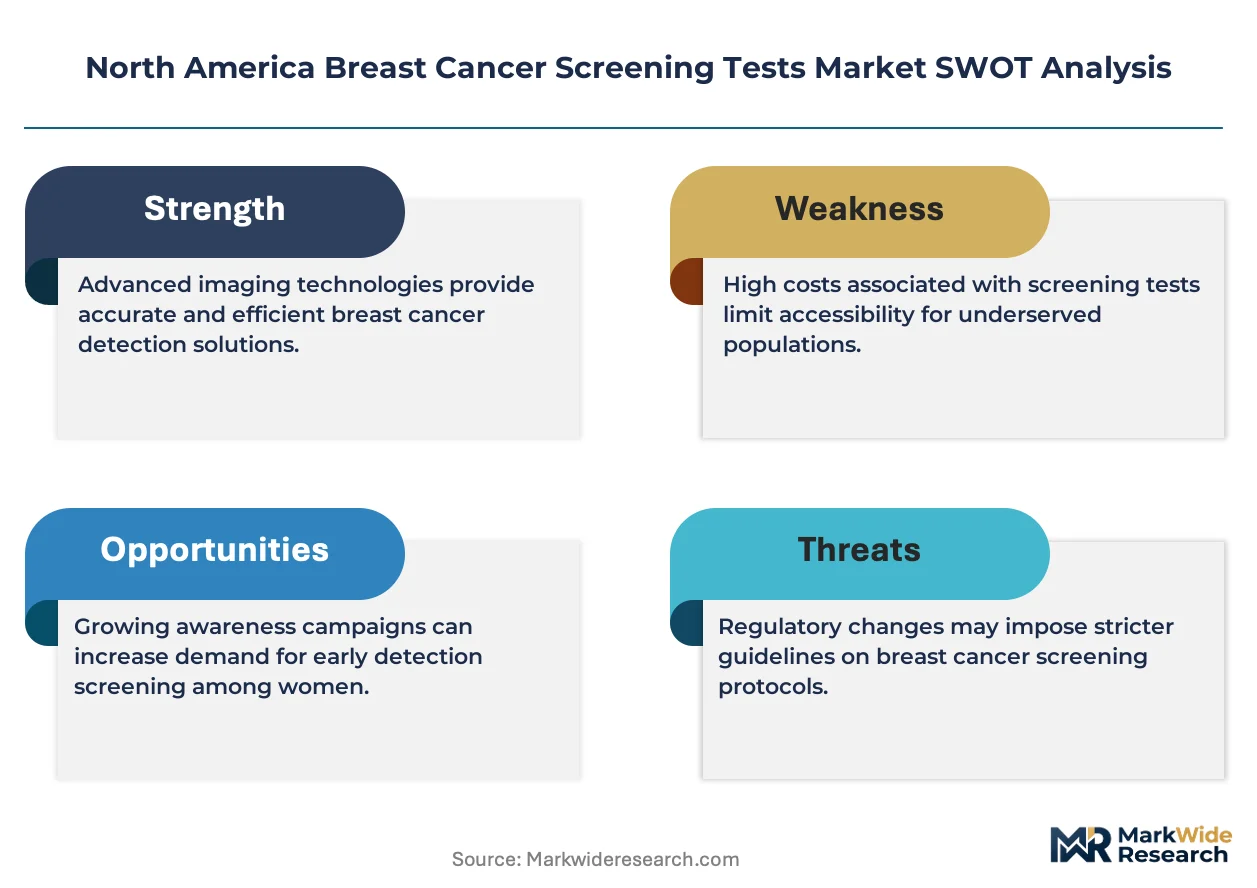
This market fragments across modality mix and care setting, creating niches for specialists as dense breast notification laws expand supplemental screening demand beyond conventional mammography.
For Market Incumbents: Entrench installed base loyalty through backward integration into cloud-native storage architectures and automated quality assurance software. Defend against independent service organization encroachment by embedding predictive maintenance algorithms into Hologic and GE Healthcare legacy systems. Prioritize FDA 510(k) clearance for AI companion diagnostics to lock in recurring revenue streams. For New Entrants and Emerging Players: Pursue mobile screening unit deployment in Texas Rio Grande Valley and Central Valley California where uninsured population density exceeds fixed-site capacity. Target contrast-enhanced mammography protocol development as MRI-equivalent sensitivity at lower capital cost. Anchor go-to-market through Federally Qualified Health Center partnerships rather than hospital network competition. For Investors and Strategic Acquirers: Long-term, this sits as a recurring revenue play because screening program mandates create predictable equipment refresh cycles and aftermarket service demand. Acquire AI algorithm developers with FDA-cleared computer-aided detection pathways. Monitor provincial reimbursement commitments in Ontario and British Columbia as inflection indicators for technology adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission for AI Detection Software | Accelerates embedded machine learning deployment across Hologic and GE Healthcare installed bases. |
| Hospital System Partnership for Enterprise PACS Integration | Secures multi-site procurement commitments from Kaiser Permanente and Mayo Clinic networks. |
| Contrast-Enhanced Mammography Protocol Development | Positions community hospitals to capture high-risk surveillance volumes from MRI-dependent cohorts. |
| Mobile Screening Unit Fleet Expansion | Extends reach to uninsured populations in Texas Rio Grande Valley and Central Valley California. |
| Reimbursement Strategy for Dense Breast Supplemental Screening | Aligns with 38 US state notification laws driving ultrasound and MRI volume growth. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with breast imaging radiologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers; and secondary validation against FDA MQSA facility inspection databases, CMS Medicare procedure claims, hospital procurement records, and provincial screening program reports. Bottom-up equipment unit estimates triangulated against top-down addressable population screening volumes.
Forecast inputs incorporated modality mix shifts, technology refresh cycle timing, and reimbursement pathway evolution across the projection horizon. Segmentation dimensions modeled include test type, end user category, technology tier, and application intent. CAGRs derived from fitted adoption curves for digital breast tomosynthesis and AI-enhanced detection platforms, calibrated against historical analog-to-digital conversion patterns.
Macroeconomic conditions sit as an overlay; deviation in helium commodity pricing, radiologist workforce availability, or provincial funding commitments would shift the trajectory. Forecasts reflect documented assumptions regarding MQSA enforcement continuity and dense breast notification law expansion. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Veterinary Diagnostic Services Market
Diagnostics
Non-Alcoholic Steatohepatitis (NASH) Biomarkers Market
Diagnostics
Vision Screeners Market
Diagnostics
Italy in Vitro Diagnostics Market
Diagnostics
Adenovirus Diagnostic Testing Market
Diagnostics
Canada Latent Tuberculosis Infection Detection Market
Diagnostics
Middle East and Africa Ovarian Cancer Diagnostics Market
Diagnostics
Diabetes Diagnostics Market
Diagnostics
Global Syphilis Immunoassay Diagnostics Market
Diagnostics
Europe Womens Health Diagnostics Market
Diagnostics
Viral Disease Diagnosis Market
Diagnostics
Brazil in Vitro Diagnostics Market
Diagnostics
Brain Cancer Diagnostics Market
Diagnostics
Asia Pacific in Vitro Diagnostics Market
Diagnostics
Self-Administered HPV Test Market
Diagnostics
Rapid Oral Fluid Screening Device Market