
 Total Iron Binding Capacity Reagents Market | 2026-2036
Total Iron Binding Capacity Reagents Market Size, Share, and Industry Trends Forecast 2026-2036
Total Iron Binding Capacity Reagents Market Analytics
The US FDA's clinical laboratory improvement amendments is repositioning quality benchmarks for iron metabolism diagnostics across American healthcare networks. Thermo Fisher Scientific leverages its automated platform installed base to sustain reagent pull-through in high-throughput hospital laboratories. Siemens Healthineers anchors European demand through integrated hematology workstreams that bundle TIBC testing with complete blood count protocols. Randox Laboratories competes on specialized calibrator ranges that address traceability requirements under stricter accreditation regimes.
Total iron binding capacity reagents measure serum transferrin's iron-binding sites through colorimetric or enzymatic reaction with added ferric ions, typically reported alongside serum iron and ferritin to assess iron deficiency or overload states. Liquid reagents dominate routine diagnostic workflows due to ready-to-use convenience and reduced preparation error, while enzymatic assays capture expanding share in automated analyzer environments where specificity for direct TIBC measurement reduces interference from non-transferrin iron binders. Diagnostic laboratories represent the primary consumption node as centralized testing consolidates anemia workups away from point-of-care settings.
The US FDA and Clinical Laboratory Improvement Amendments program shape product validation requirements, while ISO 15189 accreditation drives harmonization of TIBC reference intervals across national laboratory networks. The EU In Vitro Diagnostic Regulation introduces new conformity assessment burdens that favor established manufacturers with notified body relationships. Stakeholders must monitor evolving ferritin-transferrin ratio protocols that could shift reagent consumption patterns between standalone TIBC assays and multiparameter iron panels.
Market Dynamics
Automated hematology platforms are compressing standalone TIBC testing volumes into bundled iron panel workflows, forcing reagent suppliers to defend placement through calibrator specificity and analyzer integration rather than standalone assay performance.
Growth Catalysts
- CLIA Quality Mandates:The US FDA's Clinical Laboratory Improvement Amendments tighten traceability requirements for iron metabolism assays, compelling laboratories to refresh reagent inventories with certified reference material-compliant formulations.
- Geriatric Screening Protocols:Japan's aging population drives routine anemia workups through centralized diagnostic networks, expanding reagent consumption in high-throughput hospital laboratories.
- Enzymatic Assay Specificity:Direct TIBC measurement technologies reduce interference from non-transferrin iron binders, capturing preference in automated analyzer environments where specificity commands premium positioning.
Market Restraints
- Reagent Input Concentration:Ferric chloride and chromogenic substrate supply chains concentrate among specialty chemical producers in Germany and Switzerland, exposing margins to raw material volatility.
- Analyzer Platform Lock-in:Closed-system architectures at dominant hematology OEMs restrict third-party reagent penetration, compressing addressable market for independent suppliers.
- Serum Ferritin Substitution:Single-marker iron deficiency screening using ferritin immunoassays displaces complete iron panel ordering in resource-constrained settings.
Strategic Opportunities
- Indian Accreditation Expansion:NABL's ISO 15189 harmonization program creates demand for traceable calibrator systems among diagnostic chains consolidating in Mumbai and Delhi.
- Point-of-Care Iron Panels:Lateral flow and microfluidic platforms enable decentralized anemia screening in rural clinics, opening reagent formats beyond liquid chemistry.
- EU MDR Conformity Pathways:The In Vitro Diagnostic Regulation's technical documentation requirements favor established manufacturers with notified body relationships, creating acquisition leverage over smaller competitors.
Industry Challenges
- Reference Interval Harmonization:Transferrin saturation calculation methods vary across laboratory information systems, complicating multi-site standardization for health network clients.
- Analyzer Migration Cycles:Seven-to-ten-year capital equipment replacement timelines delay reagent contract renegotiations, freezing competitive switching opportunities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Total Iron Binding Capacity Reagents Market |
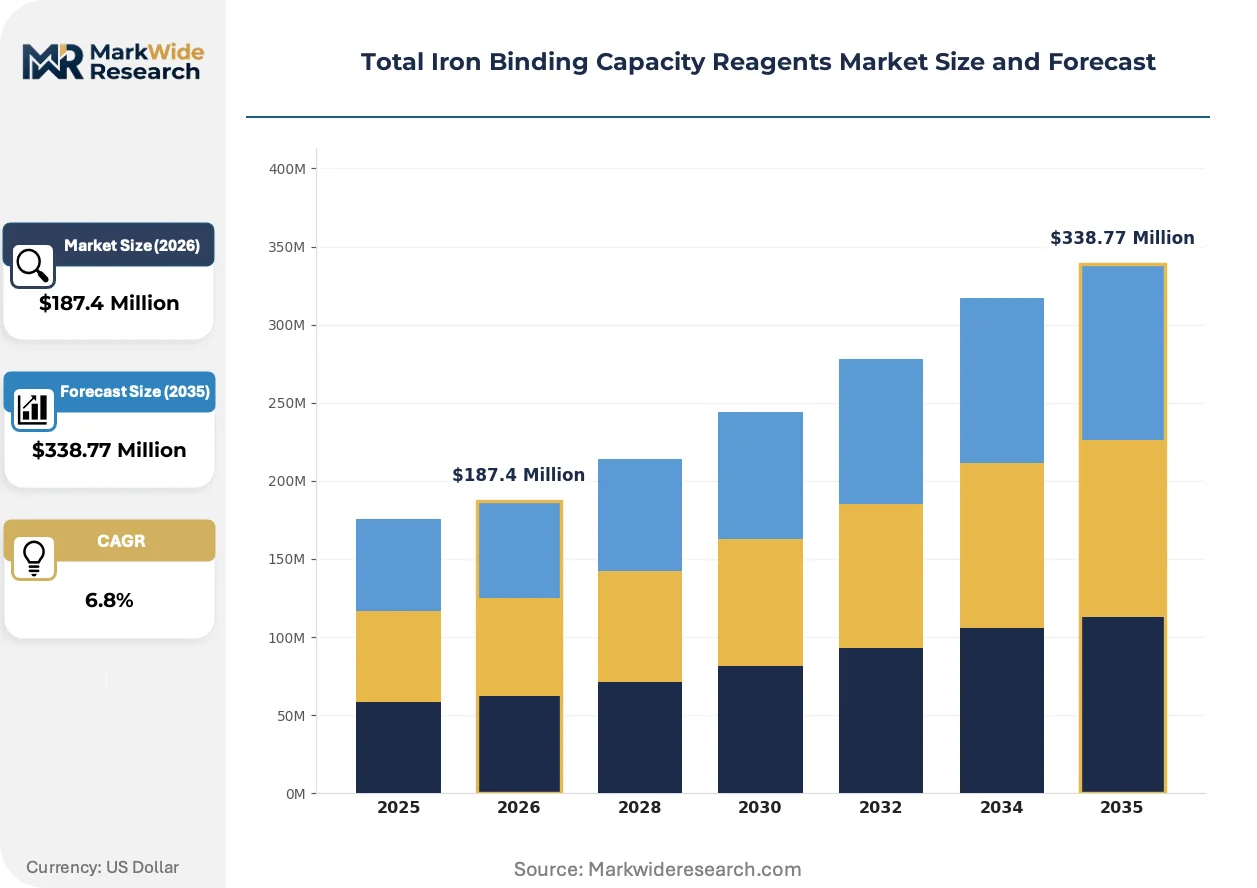
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Reagents, Powder Reagents, Kits, Standards End User: Diagnostic Laboratories, Hospitals, Research Institutions, Clinics Technology: Spectrophotometry, Colorimetric Assays, Enzymatic Assays, Electrochemical Techniques Application: Anemia Testing, Hematology Analysis, Nutritional Assessment, Clinical Research |
| Companies Covered | Randox Laboratories, Biosystems S.A., Sekisui Diagnostics, Thermo Fisher Scientific, Siemens Healthineers, Pointe Scientific, Henry Schein, Linear Chemicals, HUMAN Diagnostics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Total Iron Binding Capacity Reagents Market Evolving Landscape
Liquid-stable reagent formulations are displacing lyophilized preparations across automated platforms, while regulatory pressure on traceability accelerates investment in certified reference materials and metrological anchoring.
Enzymatic direct TIBC assays are consolidating market preference in high-throughput laboratories. These methods eliminate iron saturation calculation artifacts that plague indirect approaches. Major hospital networks in the United States and Germany now specify direct measurement in analyzer procurement tenders. The technology is consolidating competitive position around specificity claims rather than throughput metrics.
The EU In Vitro Diagnostic Regulation introduces new conformity assessment burdens for iron metabolism assays. Manufacturers must maintain technical documentation and post-market surveillance systems that exceed previous directive requirements. Mid-sized reagent suppliers face disproportionate compliance costs, accelerating consolidation toward notified body-aligned market leaders.
Diagnostic laboratories are unbundling reagent procurement from analyzer service contracts. Third-party group purchasing organizations now negotiate multi-manufacturer reagent panels for health network clients. This behavior is most visible in United States hospital systems responding to CMS price transparency mandates and supply chain diversification directives.
Total Iron Binding Capacity Reagents Market Segmentation
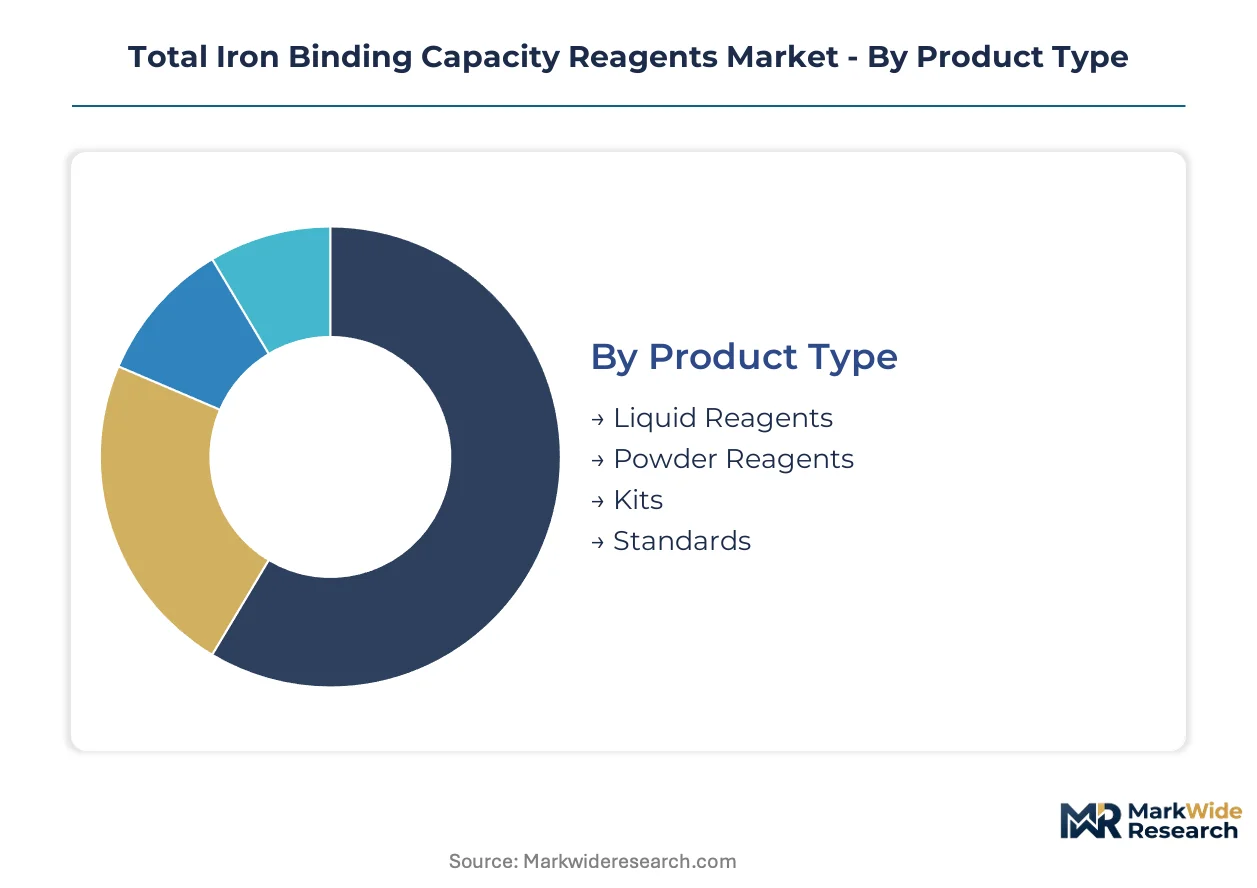
Segmentation in the TIBC reagents market reveals how technology choices, end-user workflows, and application requirements reshape procurement patterns. Manufacturers align formulation strategies with analyzer integration demands while laboratories prioritize throughput and traceability compliance.
Product Type:
Formulation chemistry determines stability profiles, preparation protocols, and shelf-life economics across laboratory workflows.
- Liquid Reagents:Ready-to-use aqueous formulations eliminate reconstitution errors and reduce technician handling time. Demand concentrates in high-throughput hospital laboratories across the United States and Germany where CLIA and ISO 15189 accreditation protocols favor minimized preparation variability.
- Powder Reagents:Lyophilized preparations offer extended stability during ambient temperature shipping and storage. Procurement from centralized diagnostic networks in Japan emphasizes cold-chain resilience for remote clinic distribution.
- Kits:Bundled calibrator and control combinations simplify quality management for mid-sized laboratories.
- Standards:Certified reference materials anchor traceability chains under tightening metrological requirements.
Liquid reagents lead on scale; kits lead on momentum as unbundled procurement patterns expand.
End User:
Testing volume concentration and capital equipment ownership create divergent purchasing power across customer categories.
- Diagnostic Laboratories:Centralized testing hubs process anemia workups at industrial scale, driving reagent consumption through automated platform throughput. Consolidation in United States health networks and German hospital chains compresses vendor selection to ISO-compliant suppliers with multi-year service agreements.
- Hospitals:Integrated hematology departments demand seamless analyzer-reagent compatibility for STAT testing workflows. Japanese tertiary centers specify direct TIBC enzymatic methods to reduce interference in complex patient populations.
- Research Institutions:Academic medical centers pursue specialized assay modifications for iron metabolism studies.
- Clinics:Point-of-care settings favor simplified protocols with minimal quality control overhead.
Diagnostic laboratories dominate absolute volume; clinics represent the steepest expansion trajectory as decentralized screening protocols proliferate.
Technology:
Measurement specificity and automation compatibility determine competitive positioning in analyzer procurement tenders.
- Enzymatic Assays:Direct TIBC measurement eliminates iron saturation calculation artifacts inherent to indirect methods. United States hospital networks and German laboratory consortia now specify this technology in automated platform tenders, capturing preference where non-transferrin iron binder interference compromises diagnostic accuracy.
- Colorimetric Assays:Chromogenic iron-binding reactions remain cost-effective for moderate-throughput installations. Demand persists in Indian diagnostic chains and Brazilian public health laboratories where capital constraints limit enzymatic platform adoption.
- Spectrophotometry:UV-visible detection architectures underpin most automated chemistry analyzers.
- Electrochemical Techniques:Emerging biosensor approaches target point-of-care iron panel miniaturization.
Colorimetric assays retain installed base dominance; enzymatic methods gain share fastest through specificity-driven replacement cycles.
Application:
Clinical utility and reimbursement pathways shape panel composition and testing frequency across patient populations.
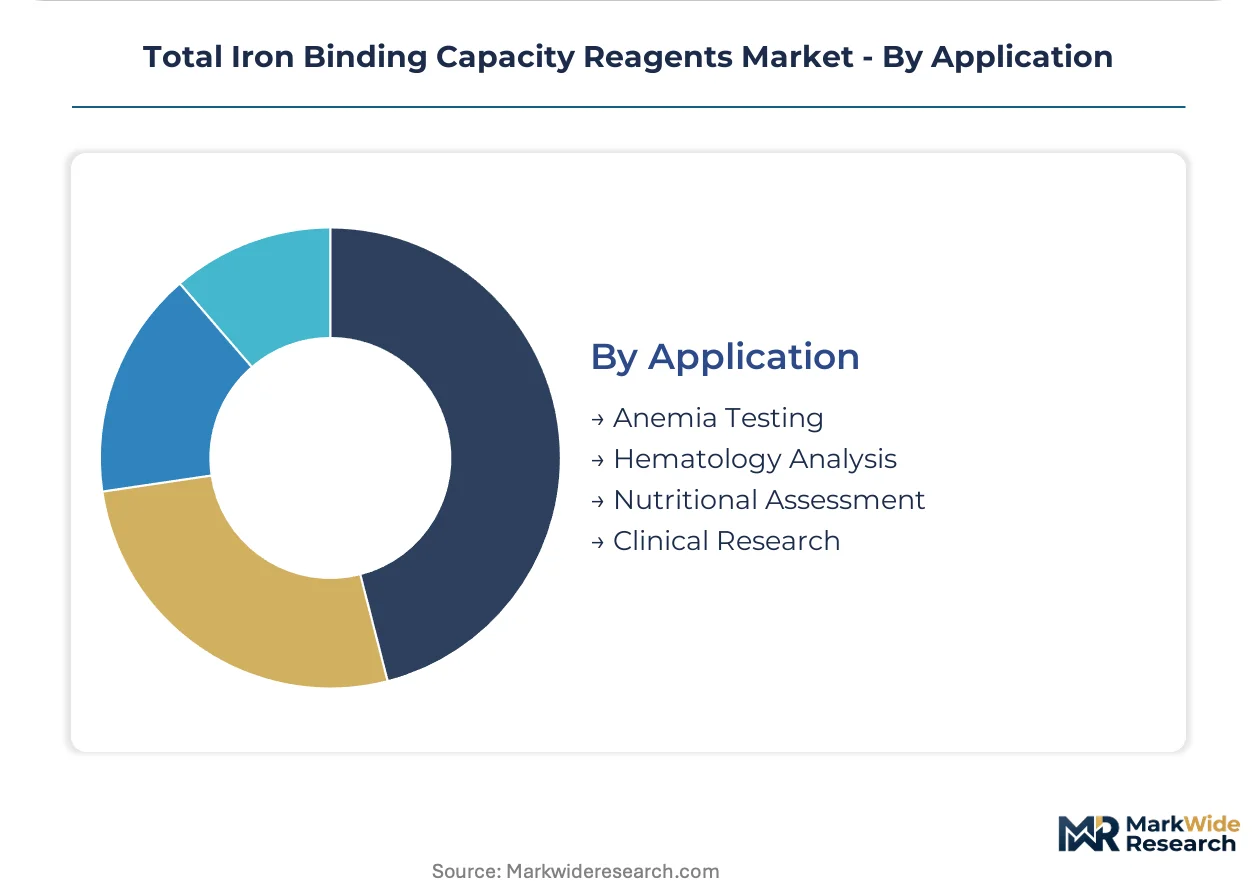
- Anemia Testing:Iron deficiency workups constitute the primary clinical indication, with geriatric screening protocols in Japan and routine prenatal panels in Germany driving reagent consumption. Japan's aging demographics expand testing volumes through centralized diagnostic networks.
- Hematology Analysis:Integrated complete blood count workflows bundle TIBC with ferritin and transferrin saturation calculations. United States health networks increasingly demand harmonized reference intervals across multi-site laboratory information systems.
- Nutritional Assessment:Bariatric surgery follow-up and malnutrition screening create specialized demand.
- Clinical Research:Pharmaceutical trials for iron-modulating therapeutics require customized assay validation.
Hematology analysis commands the largest addressable base; nutritional assessment climbs fastest as metabolic syndrome protocols expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The total iron binding capacity reagents industry traces its commercial origins to post-war European clinical chemistry laboratories, where standardized iron metabolism assays first achieved industrial scale during the 1960s.
United States
Hospital consolidation and health network centralization concentrate reagent procurement decisions among fewer buyers with greater negotiating leverage. The FDA's Clinical Laboratory Improvement Amendments mandate traceable calibrator systems, compelling laboratories to refresh inventory with certified reference material-compliant formulations. Major diagnostic chains in Texas and the Northeast Corridor now specify direct enzymatic TIBC methods in multi-year service agreements.
Germany
Integrated hematology workstreams bundle TIBC testing with complete blood count protocols, sustaining reagent pull-through in high-throughput hospital laboratories. The EU In Vitro Diagnostic Regulation imposes new conformity assessment burdens that favor established manufacturers with notified body relationships. Industrial clusters in Baden-Württemberg and North Rhine-Westphalia host specialized chemical producers supplying ferric chloride and chromogenic substrates.
Japan
Aging demographics expand routine anemia screening volumes through centralized diagnostic networks serving geriatric populations. METI standards harmonization aligns reference intervals across national laboratory networks, reducing inter-facility variability. Tokyo and Osaka metropolitan areas concentrate tertiary care centers specifying enzymatic direct measurement technologies to reduce interference in complex patient populations.
India
Diagnostic chain consolidation in Mumbai and Delhi creates demand for ISO 15189-accredited reagent systems among emerging laboratory networks. NABL harmonization programs drive traceable calibrator procurement, though capital constraints limit enzymatic platform adoption in public health settings. Maharashtra and Karnataka states exhibit the steepest expansion trajectory as decentralized screening protocols proliferate beyond metropolitan cores.
United Kingdom
Point-of-care iron panel development targets rural clinic distribution, opening reagent formats beyond liquid chemistry for decentralized anemia screening. NHS procurement frameworks emphasize cost containment, favoring bundled reagent panels over standalone assays. London and Southeast England concentrate research institutions pursuing specialized assay modifications for iron metabolism studies.
Total Iron Binding Capacity Reagents Market Competitive Landscape
Premium-margin players sit above commodity-margin players across analyzer integration depth and calibrator specificity dimensions. The vendor base organizes into three tiers: multinational platform OEMs with captive reagent ecosystems, independent diagnostic chemical specialists with broad menu flexibility, and regional distributors serving price-sensitive installations. Two dominant competitive moves define current positioning: analyzer service contract unbundling that separates reagent procurement from equipment maintenance, and strategic partnerships with group purchasing organizations negotiating multi-manufacturer panels for health network clients.
Within the platform-integrated tier, Thermo Fisher Scientific and Siemens Healthineers occupy positions shaped by installed base scale and automated workflow bundling. Randox Laboratories exemplifies the independent specialist archetype, competing through calibrator range breadth and accreditation regime responsiveness. Sekisui Diagnostics represents the Asia-Pacific anchored competitor, leveraging regional manufacturing proximity to serve diagnostic laboratory networks across Japan and emerging Asian markets.
| Leading Market Players |
|---|
| Randox Laboratories |
| Biosystems S.A. |
| Sekisui Diagnostics |
| Thermo Fisher Scientific |
| Siemens Healthineers |
| Pointe Scientific |
| Henry Schein |
| Linear Chemicals |
| HUMAN Diagnostics |
| Others |
Value Network & Pricing Analysis
Ferric chloride and chromogenic substrate costs cascade through three pricing tiers for TIBC reagents, with German and Swiss specialty chemical producers anchoring upstream supply and diagnostic laboratories in the United States, Germany, and Japan absorbing downstream price differentiation through bundled analyzer contracts.
Pricing Analysis
Contract-based long-term offtake agreements dominate reagent procurement, with pricing stratifying across premium enzymatic direct-measurement tiers, standard colorimetric formulations, and economy-grade powder reagents for remote distribution. Price differentiation hinges on ISO 15189 certification compliance and analyzer platform integration depth. Cost compression in the economy tier intensifies as Indian diagnostic chains and Brazilian public health laboratories negotiate volume-based discounts. Hospital networks in the United States and Japan exhibit the lowest price sensitivity due to bundled service agreements, while independent laboratories in emerging markets drive the steepest procurement negotiations.
Supply Chain Analysis
CE marking and FDA 510(k) clearance requirements gate market entry, concentrating qualified production among established manufacturers with notified body relationships. Supply concentrates in Germany for chromogenic substrates, Switzerland for precision chemical intermediates, and the United States for certified reference materials. Raw material dependencies include ferric chloride, transferrin-specific antibodies for enzymatic assays, and stabilized aqueous buffers. Single-source vulnerability exists for high-purity ferric chloride from specialty chemical producers in Baden-Württemberg. Distribution runs through diagnostic equipment OEMs, third-party group purchasing organizations, and regional distributors serving price-sensitive installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The TIBC reagents market functions as a regulatory compounder where CLIA quality mandates and EU MDR conformity pathways continuously refresh demand for certified formulations.
For Market Incumbents: Deepen backward integration into ferric chloride and chromogenic substrate production to insulate margins from raw material volatility. Fortify analyzer service contract bundling to resist unbundling pressure from group purchasing organizations in United States health networks. Prioritize ISO 15189-accredited calibrator range expansion to defend placement against emerging entrants targeting Indian NABL harmonization programs. For New Entrants and Emerging Players: Group purchasing organizations represent the most penetrable channel for mid-sized manufacturers seeking scale beyond regional distributor relationships. Target Indian diagnostic chains consolidating in Mumbai and Delhi with traceable calibrator systems priced below OEM premiums. Pursue point-of-care iron panel partnerships with microfluidic platform developers to bypass closed-system analyzer lock-in. For Investors and Strategic Acquirers: Consolidation pressure builds where EU MDR technical documentation burdens disproportionately strain mid-sized reagent suppliers lacking notified body relationships. The five-to-ten year viability window favors manufacturers with metrological anchoring capabilities and multi-regulatory approval portfolios. Acquisition target archetypes include ISO 15189-specialized calibrator suppliers and enzymatic assay technology holders. Monitor NABL accreditation expansion velocity in India as an inflection indicator for emerging market reagent demand.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR conformity assessment accelerates consolidation toward notified body-aligned manufacturers. |
| Hospital System Partnership | Multi-year service agreements with United States health networks lock in reagent pull-through volumes. |
| Backward Integration | In-house production of ferric chloride reduces exposure to German specialty chemical supply concentration. |
| Software Companion Development | Laboratory information system integration harmonizes reference intervals across multi-site networks. |
| Reimbursement Strategy | CMS price transparency mandates reshape procurement patterns toward unbundled reagent panels. |
Research Methodology
Coverage spans the United States, Germany, Japan, India, and the United Kingdom, with primary inputs from each market through structured interviews with laboratory directors, diagnostic equipment procurement managers, hematology department heads, and regulatory affairs specialists at reagent manufacturers. Secondary validation draws from FDA 510(k) filings, EU MDR technical documentation databases, NABL accreditation registries, CMS laboratory payment schedules, and ISO 15189 audit reports. Bottom-up reagent volume estimates triangulate against top-down diagnostic testing procedure frequencies.
Rate-of-change decomposition separates volume growth from pricing dynamics across the projection horizon. Segmentation dimensions include formulation chemistry, measurement technology, end-user facility type, and clinical application. CAGRs derive from analyzer installed base expansion, geriatric screening protocol adoption, and enzymatic assay replacement cycles. Industry-specific forecast inputs incorporate CLIA compliance refresh rates and EU MDR transition timelines for legacy device recertification.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ferritin immunoassay substitution rates and point-of-care platform miniaturization advances. Projections reflect assumptions regarding regulatory harmonization progress and analyzer platform migration cycles. A model refresh is warranted upon material change in FDA quality mandate enforcement intensity or EU notified body capacity constraints.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Glucose Biosensors Market
Diagnostics
Hospital Clinical Chemistry and Immunodiagnostics Market
Diagnostics
Biochips Based in-Vitro Diagnostics Market
Diagnostics
Global Rubella Diagnostic Testing Market
Diagnostics
Animal Auto-Immune Disease Diagnostics Market
Diagnostics
Melanoma Cancer Diagnostics Market
Diagnostics
Global Diagnostic Radiopharmaceuticals and Contrast Media Market
Diagnostics
Hydrogen Breath Test Analyzer Market
Diagnostics
Influenza Diagnostics Market
Diagnostics
H. Pylori Breath Test Kit Market
Diagnostics
Lipid Panel Test Market
Diagnostics
Diagnostic Testing of Stds Market
Diagnostics
Asia-Pacific Radioimmunoassay Market
Diagnostics
Global Rabies Diagnostics Market
Diagnostics
Alzheimer's Disease Diagnostics and Therapeutics Market
Diagnostics
Mycoplasma Diagnostics Market