
 United States Esoteric Testing Market | 2026-2036
United States Esoteric Testing Market Size, Share, and Industry Trends Forecast 2026-2036
United States Esoteric Testing Market Analytics
Academic medical centers and integrated delivery networks is rotating toward direct esoteric test development rather than reliance on reference laboratories. Quest Diagnostics sustains broad national access through its specimen logistics network and health plan contracts. Mayo Clinic Laboratories anchors its position through deep subspecialty expertise and clinician-scientist integration. Foundation Medicine differentiates via comprehensive genomic profiling tied to therapeutic selection pathways.
Esoteric testing comprises highly specialized laboratory analyses that fall outside routine clinical chemistry and hematology, typically requiring advanced instrumentation, rare reagents, and board-certified subspecialist interpretation for complex diagnostic questions. These tests employ methodologies such as next-generation sequencing with read depths exceeding 500x for somatic mutation detection, mass spectrometry for trace analyte quantification, and microarray platforms for copy-number variation assessment. Genetic tests and infectious disease assays occupy the largest revenue pools, while oncology applications demonstrate the steepest volume growth trajectory as companion diagnostic requirements expand. Next-generation sequencing technology leads instrument investment cycles, though polymerase chain reaction retains dominant throughput for targeted panel applications.
FDA oversight of laboratory-developed tests, CLIA high-complexity certification requirements, and CMS reimbursement determinations through the MolDX program collectively shape market access and test development economics. HIPAA privacy rules and state laboratory licensing standards add compliance layers that influence data infrastructure and cross-border specimen handling protocols. Stakeholders must monitor pending FDA rulemaking on diagnostic test categorization and MolDX coverage determinations for emerging multi-cancer early detection assays.
Market Dynamics
The FDA's laboratory-developed test framework is forcing academic medical centers and specialty hospitals to recalibrate capital deployment between in-house assay development and reference laboratory partnerships. This regulatory pressure is compressing decision timelines for instrument procurement and compliance infrastructure.
Growth Catalysts
- CLIA high-complexity certification expansion:Community hospitals in Texas and Florida are pursuing elevated laboratory credentials to retain oncology specimens locally rather than shipping to national reference networks.
- Companion diagnostic mandates:FDA requirements for biomarker testing prior to targeted therapy authorization are expanding molecular assay volumes across solid tumor categories.
- Next-generation sequencing cost curves:Declining per-base sequencing expenses are enabling broader gene panel adoption in neurology and rare disease programs.
Market Restraints
- Reagent supply concentration:Critical enzymes and modified nucleotides for PCR-based assays originate from a narrow supplier base concentrated in Massachusetts and California.
- MolDX coverage lag:CMS reimbursement determinations for novel multi-gene panels trail FDA authorization by 18-24 months, compressing test development economics.
- Specialized workforce scarcity:Board-certified molecular geneticists and laboratory directors with subspecialty expertise face acute supply constraints in secondary markets.
Strategic Opportunities
- Rural health network penetration:Critical Access Hospitals in the Upper Midwest represent underserved demand for send-out reduction through targeted esoteric menu development.
- Pharmacogenomics integration:Psychiatric and cardiovascular therapeutic areas show expanding testable drug-gene interaction pairs with established clinical utility evidence.
- HIPAA-compliant cloud infrastructure:Federated data architectures enable multi-site variant interpretation without centralized specimen transport.
Industry Challenges
- Laboratory information system interoperability:Legacy EHR platforms in community health systems require expensive middleware development for discrete molecular result integration.
- Variant of uncertain significance interpretation:Ambiguous genomic findings demand sustained clinician education investments and multidisciplinary tumor board infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Esoteric Testing Market |
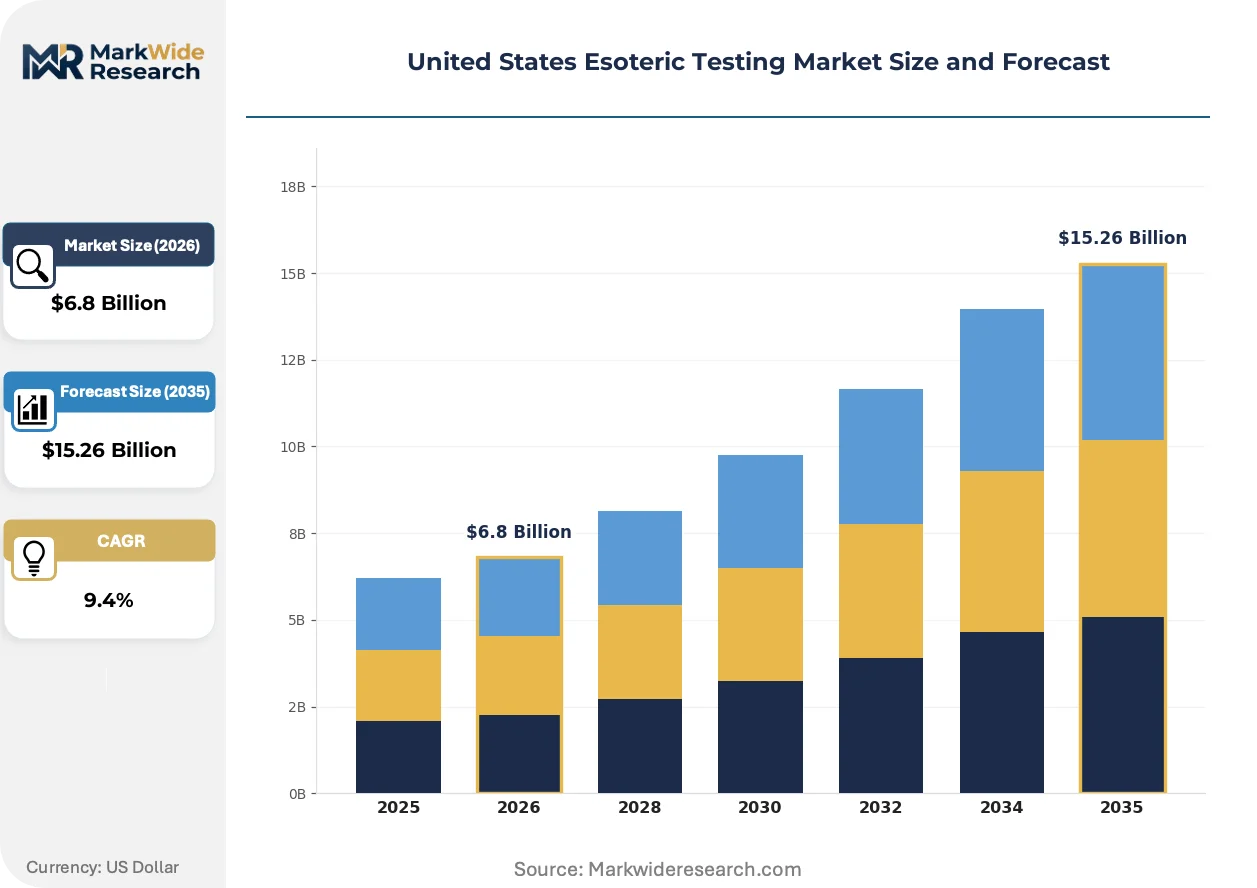
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Genetic Tests, Infectious Disease Tests, Hormonal Tests, Toxicology Tests Technology: Polymerase Chain Reaction, Mass Spectrometry, Next Generation Sequencing, Microarray Analysis End User: Hospitals, Diagnostic Laboratories, Research Institutes, Outpatient Clinics Application: Oncology, Neurology, Cardiology, Autoimmune Disorders |
| Companies Covered | Mayo Clinic Laboratories, BioReference Laboratories, Quest Diagnostics, OPKO Health, Foundation Medicine, Laboratory Corporation of America (Labcorp), Sonic Healthcare, Eurofins Scientific, ARUP Laboratories, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Esoteric Testing Market Evolving Landscape
Instrumentation and assay methodologies are fragmenting across throughput tiers, with distinct competitive dynamics emerging between high-volume centralized laboratories and distributed point-of-need platforms. This technological divergence is reshaping vendor relationships and service model economics.
Mass spectrometry platforms for trace analyte quantification are bifurcating into two deployment modes. Reference laboratories in Boston and San Francisco are installing high-resolution systems for untargeted metabolomics, while specialty hospitals in the Southeast adopt compact triple-quadrupole instruments for targeted steroid panels. This split is compressing the middle market for general-purpose LC-MS systems.
FDA's evolving LDT enforcement discretion policy is creating compliance tiering between academic medical center laboratories and commercial reference operations. High-complexity laboratories with CLIA certification and CAP accreditation face modified premarket review pathways. Oncology assay developers are responding by front-loading analytical validation studies to anticipate categorization decisions.
Health system procurement committees are consolidating molecular testing contracts under single-source agreements with incumbent reference partners. Integrated delivery networks in the Midwest and Mountain West are replacing fragmented send-out arrangements with comprehensive genomic profiling contracts. This concentration is most visible in multi-state systems seeking standardized turnaround times and unified data formats for precision oncology programs.
United States Esoteric Testing Market Segmentation
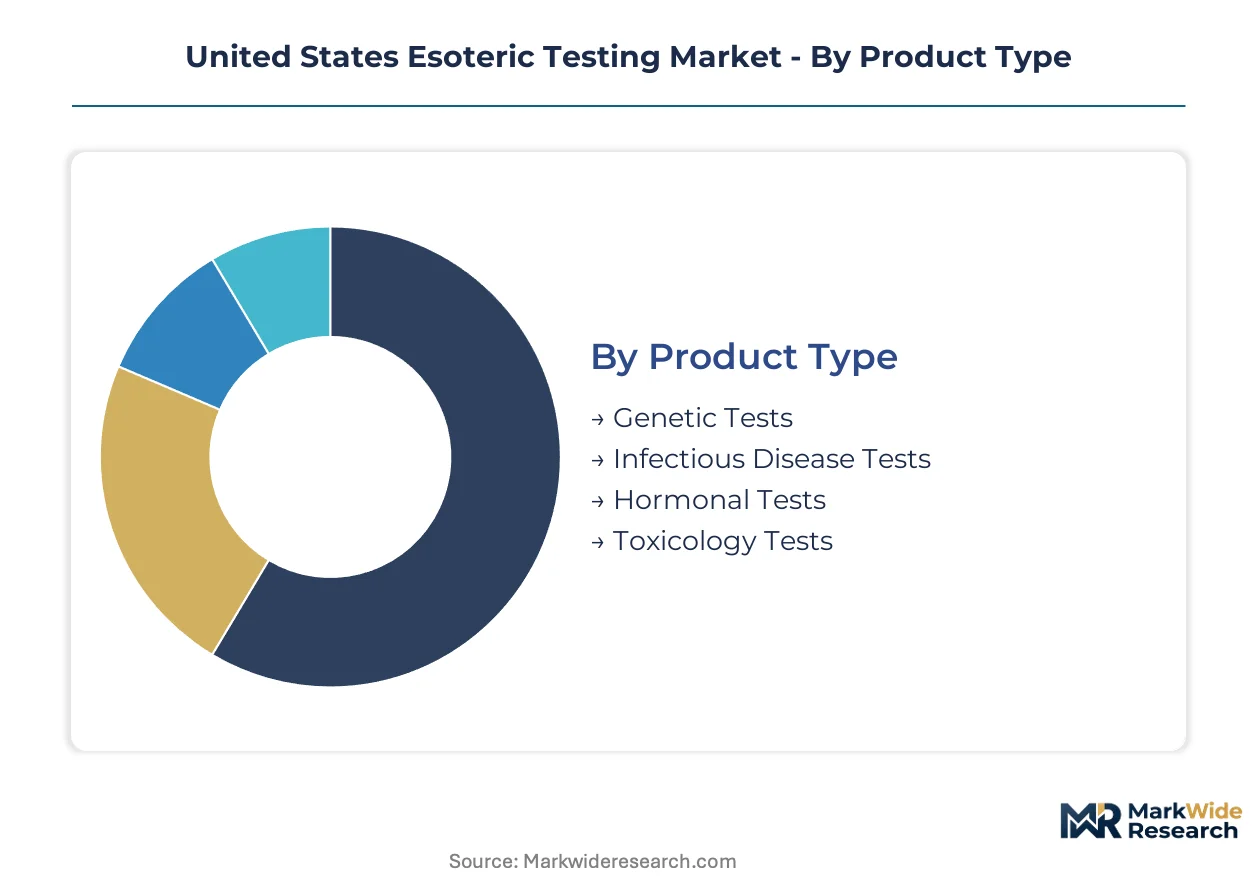
Esoteric testing segmentation reveals distinct regulatory pathways and capital intensity profiles across product categories. CLIA high-complexity certification requirements and FDA oversight frameworks create tiered compliance burdens that reshape vendor economics and customer procurement priorities.
Product Type:
FDA premarket review pathways diverge sharply across assay categories, with companion diagnostic mandates concentrating investment in oncology-linked genetic platforms.
- Genetic Tests:Molecular assays for inherited conditions and somatic mutation detection require CAP-accredited variant interpretation pipelines. Academic medical centers in Massachusetts and California deploy these for hereditary cancer screening and pharmacogenomic dosing protocols, though CMS MolDX coverage determinations lag FDA authorization by 18-24 months.
- Infectious Disease Tests:PCR-based pathogen detection and antimicrobial resistance profiling command substantial send-out volumes from community hospitals. Texas and Florida health systems retain these specimens locally through elevated CLIA credentials rather than shipping to national reference networks.
- Hormonal Tests:Mass spectrometry quantification of steroid metabolites supports endocrine and reproductive medicine programs.
- Toxicology Tests:Forensic and clinical reference intervals for drugs of abuse and therapeutic drug monitoring occupy specialty laboratory menus.
Genetic tests handle the majority of throughput; infectious disease tests are gaining share fastest as antimicrobial stewardship programs expand.
Technology:
Instrument procurement cycles cluster around throughput tiers, with high-volume centralized laboratories and distributed point-of-need platforms following divergent capital deployment strategies.
- Polymerase Chain Reaction:Targeted amplification retains dominant throughput for infectious disease and oncology panel applications. Community hospitals in the Southeast deploy compact thermocycler systems for same-day turnaround on STAT specimens, avoiding reference laboratory logistics delays.
- Next Generation Sequencing:Read depths exceeding 500x enable somatic mutation detection in solid tumor profiling. Declining per-base sequencing costs are expanding gene panel adoption in neurology and rare disease programs at specialty hospitals.
- Mass Spectrometry:Trace analyte quantification bifurcates between untargeted metabolomics and targeted steroid panels.
- Microarray Analysis:Copy-number variation assessment supports constitutional cytogenetic indications.
Polymerase chain reaction anchors current installed base; next generation sequencing shows the steepest expansion trajectory as companion diagnostic mandates multiply.
End User:
Customer procurement authority is consolidating under integrated delivery network laboratory steering committees, compressing vendor access points.
- Hospitals:Academic medical centers and specialty hospitals are expanding in-house esoteric menus to reduce send-out volumes and accelerate diagnostic turnaround. Midwest health systems negotiate comprehensive genomic profiling contracts replacing fragmented reference arrangements.
- Diagnostic Laboratories:National reference networks leverage specimen logistics infrastructure and health plan contracts for broad access.
- Research Institutes:Clinical trial assay development and analytical validation studies support FDA premarket submission packages.
- Outpatient Clinics:Limited on-site capability drives continued reference laboratory dependence for complex molecular testing.
Hospitals capture the dominant share of specimen origin; diagnostic laboratories are expanding most quickly through health system consolidation.
Application:
Precision medicine protocol penetration varies by therapeutic area, with biomarker-linked therapy authorization requirements driving differential test volume growth.
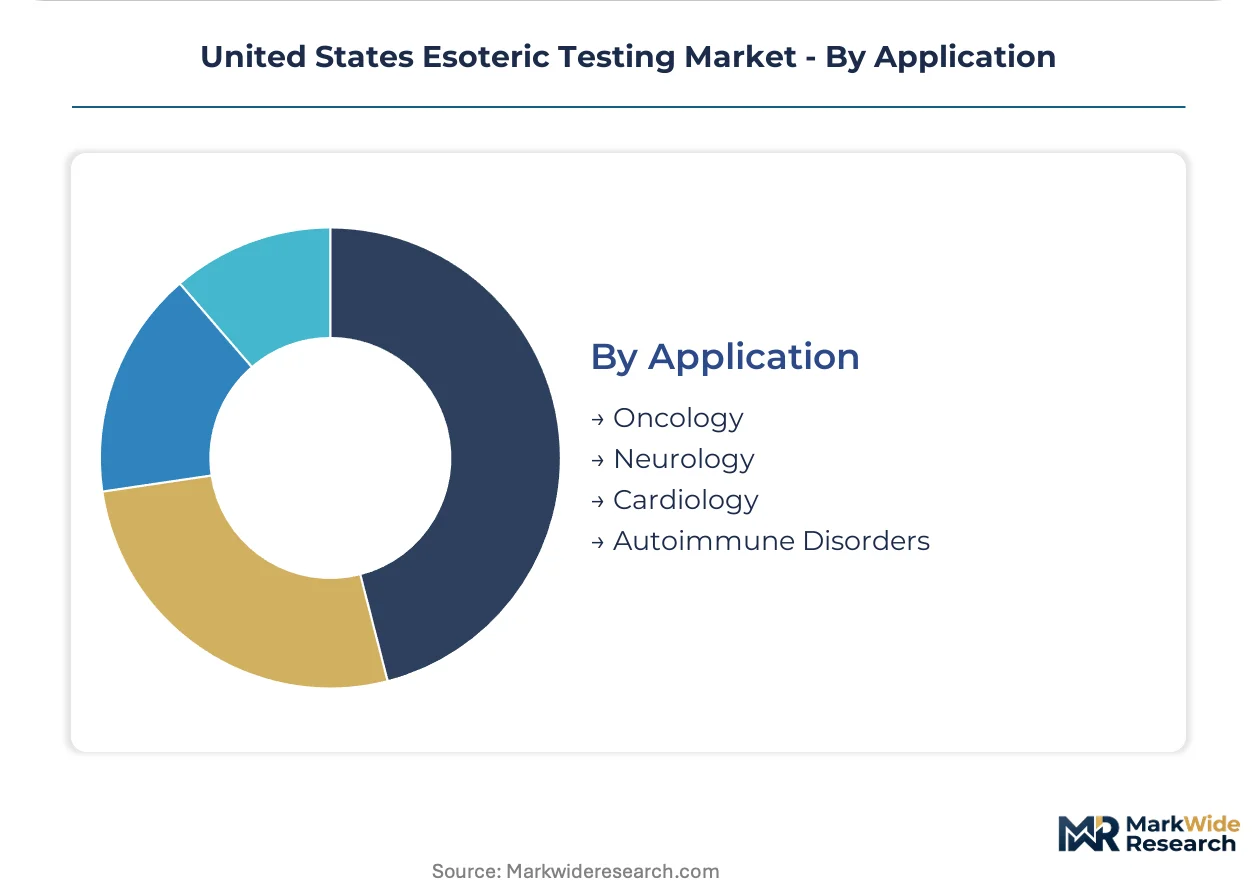
- Oncology:Companion diagnostic mandates for targeted therapy authorization are expanding molecular assay volumes across solid tumor categories. Multi-cancer early detection assays face pending CMS MolDX coverage determinations that will shape test development economics.
- Neurology:Next-generation sequencing panels for epilepsy and neurodegenerative conditions are climbing fastest as clinical utility evidence accumulates for rare disease diagnosis.
- Cardiology:Pharmacogenomic testing for anticoagulant and antiplatelet response supports therapeutic selection.
- Autoimmune Disorders:Specialized autoantibody profiling aids in complex rheumatologic and neurologic differential diagnosis.
Oncology commands the largest current volume; neurology is climbing the fastest on precision medicine protocol expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specimen flows from Texas and Florida academic medical centers feed reference laboratories in Massachusetts and California, while Midwest health systems consolidate contracts to reduce send-out volumes.
Northeast
Massachusetts academic medical centers drive hereditary cancer screening demand through CAP-accredited variant interpretation pipelines. FDA laboratory-developed test framework discussions concentrate compliance investment in Boston and Cambridge laboratory clusters. New York-Presbyterian and Memorial Sloan Kettering anchor genomic profiling capacity in the New York Metro corridor.
Southeast
Florida community hospitals pursue CLIA high-complexity certification to retain oncology specimens locally rather than shipping to national reference networks. State laboratory licensing standards add compliance layers that influence data infrastructure investments across Tampa and Miami health systems. Duke University Medical Center and UNC Health anchor precision oncology program expansion in the Research Triangle.
Midwest
Integrated delivery networks in Illinois and Ohio negotiate comprehensive genomic profiling contracts replacing fragmented reference arrangements. CMS MolDX coverage determinations through the regional Medicare administrative contractor shape test development economics for multi-gene panels. Mayo Clinic Laboratories anchors subspecialty expertise concentration in Rochester, Minnesota.
Southwest
Texas medical centers in Houston and Dallas expand in-house esoteric menus to accelerate diagnostic turnaround for complex molecular testing. HIPAA privacy rules influence cross-border specimen handling protocols for laboratories serving border populations. MD Anderson Cancer Center drives companion diagnostic assay volume through targeted therapy authorization requirements.
West Coast
California health systems deploy next-generation sequencing platforms with read depths exceeding 500x for somatic mutation detection in solid tumor profiling. FDA evolving enforcement discretion policy creates compliance tiering between academic medical center laboratories in San Francisco and Los Angeles. Stanford Health Care and UCSF Medical Center anchor neurology panel adoption for epilepsy and neurodegenerative conditions.
United States Esoteric Testing Market Competitive Landscape
Player mix skews toward integrated academic medical center laboratories and national reference networks with health plan contracting leverage. Market structure concentrates around three to five dominant operators with specimen logistics infrastructure spanning multiple states. Two strategic archetypes prevail: subspecialty expertise anchors and scale-driven national networks. Competitive moves cluster around health system consolidation of molecular testing contracts and front-loaded analytical validation studies for FDA categorization decisions.
Among national reference networks, Quest Diagnostics and Laboratory Corporation of America occupy positions exemplifying scale-driven contract consolidation, while Mayo Clinic Laboratories and ARUP Laboratories represent subspecialty expertise anchors with deep clinician-scientist integration. Foundation Medicine sits within the precision oncology profiling tier tied to therapeutic selection pathways.
| Leading Market Players |
|---|
| Mayo Clinic Laboratories |
| BioReference Laboratories |
| Quest Diagnostics |
| OPKO Health |
| Foundation Medicine |
| Laboratory Corporation of America (Labcorp) |
| Sonic Healthcare |
| Eurofins Scientific |
| ARUP Laboratories |
| Others |
Value Network & Pricing Analysis
Comprehensive genomic profiling contracts lock in multi-year pricing visibility for integrated delivery networks while securing instrument placement commitments from reference laboratories. This structure concentrates procurement authority under health system laboratory steering committees and compresses vendor access points across Midwest and Mountain West networks.
Pricing Analysis
Next-generation sequencing platforms command premium pricing against polymerase chain reaction systems and emerging point-of-need instruments. Three-tier pricing structure across premium, standard, and economy levels stratifies by CLIA certification grade and CAP accreditation status. Cost compression in infectious disease panels is intensifying because Texas and Florida community hospitals are bringing PCR-based assays in-house. Academic medical centers show lowest price sensitivity due to companion diagnostic mandate compliance requirements.
Supply Chain Analysis
Inbound logistics costs from Massachusetts and California enzyme suppliers constrain reagent availability for community hospital laboratories in secondary markets. Critical modified nucleotides and thermostable polymerases draw from concentrated production clusters in the Northeast and West Coast. Single-source vulnerability pervades rare reagent supply chains for mass spectrometry-based steroid quantification. Distribution runs through national reference laboratory logistics networks with regional specimen consolidation hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from academic medical centers developing direct esoteric test capabilities rather than maintaining reference laboratory relationships. This insourcing threat demands defensive repositioning across contract structures and subspecialty expertise anchoring.
For Market Incumbents: Shield reference laboratory volumes by embedding pathologist-scientist teams within health system tumor boards and front-loading analytical validation studies for FDA categorization decisions. Deepen backward integration into CLIA high-complexity certification consulting to capture community hospital credentialing spend. MolDX coverage determination delays represent the critical margin pressure point requiring proactive CMS engagement.
For New Entrants and Emerging Players: Lead with pharmacogenomics panels for psychiatric therapeutic areas where clinical utility evidence is established but test penetration remains limited. Critical Access Hospitals in the Upper Midwest represent the most penetrable geography given send-out reduction mandates and limited incumbent presence. Target health system laboratory steering committees with federated data architecture solutions that circumvent legacy EHR interoperability barriers.
For Investors and Strategic Acquirers: Subspecialty expertise anchors with CAP-accredited variant interpretation pipelines and embedded clinician-scientist relationships offer durable competitive positioning. Long-term viability hinges on FDA laboratory-developed test framework resolution and MolDX coverage expansion for multi-cancer early detection assays. Watch for FDA premarket review pathway announcements as the definitive inflection indicator for test development economics.
| Strategic Initiative | Industry Significance |
|---|---|
| CLIA High-Complexity Certification Expansion | Texas and Florida community hospitals retain oncology specimens locally rather than shipping to national reference networks. |
| Companion Diagnostic Assay Development | FDA biomarker testing mandates expand molecular assay volumes across solid tumor categories. |
| Federated Data Architecture Deployment | HIPAA-compliant cloud infrastructure enables multi-site variant interpretation without centralized specimen transport. |
| Pharmacogenomics Panel Integration | Psychiatric and cardiovascular therapeutic areas show expanding testable drug-gene interaction pairs. |
| Analytical Validation Study Front-Loading | Oncology assay developers anticipate FDA categorization decisions with pre-submission validation packages. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA premarket submission databases, CMS MolDX coverage determinations, and CAP accreditation records. Laboratory directors at academic medical centers, molecular geneticists, health system procurement officers, and GPO contracts managers provided operational perspective. SEC filings from publicly traded reference laboratory operators and hospital procurement databases supplied financial and volume benchmarks. Bottom-up instrument placement counts triangulate against top-down health system contract value estimates.
Segmentation dimensions modeled include technology platform throughput tier, CLIA certification level, application area by therapeutic specialty, and end-user procurement authority structure. CAGRs derive from instrument replacement cycle analysis and test volume elasticity to companion diagnostic mandate expansion. MolDX coverage lag patterns and FDA enforcement discretion policy evolution feed directly into adoption curve projections across the analysis window.
Forecasts assume regulatory continuity in FDA laboratory-developed test oversight and CMS reimbursement determinations; material policy shifts would require re-modeling. Variant interpretation pipeline capacity constraints and specialized workforce scarcity in secondary markets represent specific risk factors. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Beta-Hydroxybutyrate Testing Market
Testing Services
Alcohol Breathalyzer and Drug Testing Equipment Market
Testing Services
Zika Virus Testing Market
Testing Services
Biological Safety Testing Products and Services Market
Testing Services
Global Bioburden Testing Market
Testing Services
Rapid Hepatitis Testing Market
Testing Services
Asia-Pacific Antimicrobial Susceptibility Testing Market
Testing Services
Specific Protein Testing Market
Testing Services
Cerebrospinal Fluid (CSF) Testing Market
Testing Services
Vaginal Panel Testing Market
Testing Services
Cholesterol Testing Services Market
Testing Services
Special Coagulation Tests Market
Testing Services
Biological Indicator Incubators Market
Testing Services
Asia Pacific Sterility Testing Market
Testing Services
Blood Borne Testing Market
Testing Services
US Cannabis Testing Market