
 Helicobacter Pylori (H. Pylori) Diagnostics Market | 2026-2036
Helicobacter Pylori (H. Pylori) Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Helicobacter Pylori (H. Pylori) Diagnostics Market Foresight
Modular test panel design is decoupling H. pylori screening from full endoscopy bundles, allowing outpatient clinics to purchase standalone urea breath and stool antigen protocols. Thermo Fisher Scientific leverages its PCR platform breadth to anchor molecular diagnostic positions across hospital systems. Meridian Bioscience specializes in rapid antigen detection formats that compete on turnaround time in high-volume laboratories. Bio-Rad Laboratories sustains enzyme-linked immunosorbent assay supply chains that dominate reference lab workflows in Europe.
Helicobacter pylori diagnostics encompass laboratory and point-of-care methods that detect active infection, past exposure, or antimicrobial resistance through urease activity, antibody response, nucleic acid amplification, or histopathological examination. Urea breath tests quantify carbon isotope ratios in expired air after oral administration of labeled urea substrate, delivering non-invasive detection with sensitivity exceeding ninety percent in treated patient monitoring. Stool antigen testing captures growing demand in pediatric and geriatric populations where breath collection proves impractical, while polymerase chain reaction segments command premium positioning through clarithromycin and levofloxacin resistance profiling that guides salvage therapy selection.
The FDA regulates H. pylori diagnostic devices as Class II in vitro diagnostics requiring 510(k) premarket notification, while the EMA's In Vitro Diagnostic Regulation imposes stricter clinical evidence standards for CE-marked products entering European laboratories. Japan's PMDA maintains distinct approval pathways for urea breath test systems that constrain market entry for non-domestic manufacturers. Stakeholders must monitor how antimicrobial stewardship programs reshape reimbursement for resistance-guided testing versus empirical treatment protocols.
Market Dynamics
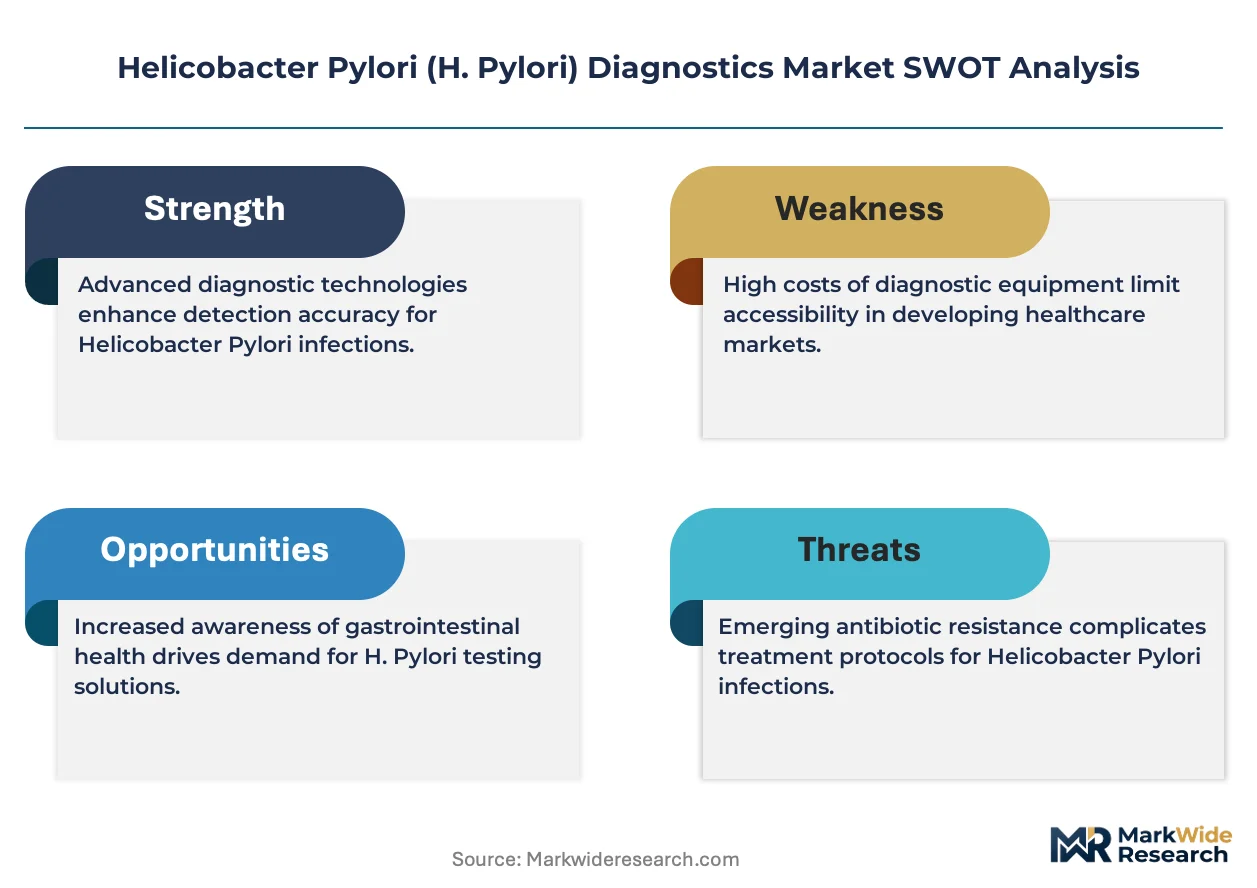
Antimicrobial stewardship programs in hospital systems are compressing empirical treatment protocols and forcing diagnostic confirmation before H. pylori therapy initiation, restructuring laboratory workflow priorities across gastroenterology departments.
Growth Catalysts
- Japan's PMDA streamlined approval:Accelerated urea breath test system clearances reduce market entry timelines for domestic manufacturers serving outpatient clinic networks.
- Non-invasive pediatric protocols:Stool antigen testing captures demand in pediatric gastroenterology where breath collection fails, expanding addressable patient populations.
- Clarithromycin resistance surveillance:Molecular resistance profiling aligns with CDC antimicrobial stewardship mandates, pulling molecular assay platforms into standard-of-care workflows.
Market Restraints
- Reimbursement compression:CMS and private payers narrow coverage for serology-based screening, constraining antibody test volumes in US clinical laboratories.
- Supply concentration in isotope substrates:Carbon-13 urea production clusters in limited North American and European radiopharmaceutical facilities, exposing breath test manufacturers to input bottlenecks.
- Histopathology dependency:Endoscopic biopsy with Giemsa staining retains gold-standard status in Japan and Germany, slowing non-invasive test penetration in academic medical centers.
Strategic Opportunities
- Point-of-care molecular platforms:Portable PCR systems enable resistance-guided therapy selection in rural and ambulatory settings lacking centralized laboratory infrastructure.
- Germany's DVG reimbursement expansion:Statutory health insurance broadens coverage for antibiotic susceptibility testing, creating payment tailwinds for molecular diagnostic providers.
- AI-assisted histopathology:Digital pathology algorithms reduce pathologist review time for H. pylori detection in gastric biopsy specimens, converging computational imaging with traditional diagnostics.
Industry Challenges
- Molecular assay validation complexity:FDA 510(k) submissions for resistance panels require extensive clinical studies documenting concordance with culture-based susceptibility testing, extending development timelines.
- Laboratory information system integration:Disparate data formats between breath test devices, PCR platforms, and hospital EMRs create interoperability friction requiring custom interface development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Helicobacter Pylori (H. Pylori) Diagnostics Market |
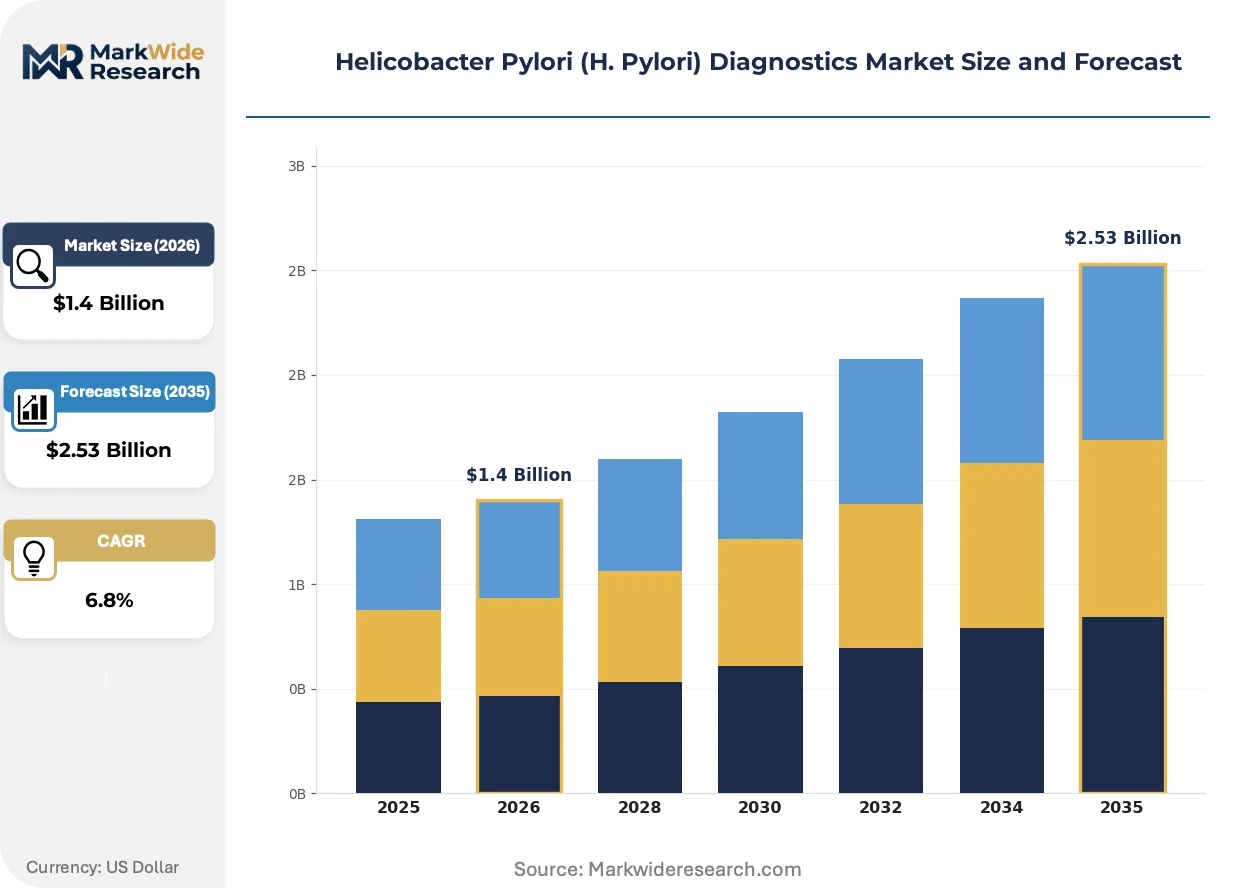
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Serological Tests, Urea Breath Tests, Stool Antigen Tests, Endoscopy Technology: Polymerase Chain Reaction, Enzyme-Linked Immunosorbent Assay, Culture Method, Rapid Antigen Detection End User: Hospitals, Diagnostic Laboratories, Clinics, Research Institutions Delivery Mode: Point-of-Care Testing, Laboratory Testing, Home Testing, Mobile Testing Units |
| Companies Covered | Thermo Fisher Scientific, Quest Diagnostics, Meridian Bioscience, Bio-Rad Laboratories, F. Hoffmann-La Roche, Abbott Laboratories, Biohit Oyj, CerTest BIOTEC, DiaSorin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Helicobacter Pylori (H. Pylori) Diagnostics Market Shifts & Advancements
Molecular diagnostic platforms are fragmenting the traditional endoscopy-centric workflow, enabling resistance-guided therapy selection at the point of care and compressing the diagnostic-therapeutic interval.
Next-generation sequencing panels for H. pylori are expanding into quadruple and triple therapy resistance profiling beyond clarithromycin, capturing mutations in rdxA and frxA genes that predict metronidazole failure. Academic medical centers in Germany and Japan are piloting these expanded panels for salvage therapy selection. The technology is expanding into outpatient gastroenterology practices previously dependent on centralized reference laboratory turnaround times.
The EMA's In Vitro Diagnostic Regulation imposes stricter clinical evidence requirements for CE-marked products, compelling manufacturers to generate prospective performance data across diverse European patient populations. IVD sponsors now face extended notified body review timelines and post-market surveillance obligations. Small and mid-cap diagnostic firms are responding by prioritizing Germany, France, and the Netherlands for initial launch sequencing based on reimbursement clarity.
Hospital procurement departments are unbundling H. pylori testing from comprehensive endoscopy service contracts, enabling standalone purchasing of urea breath and stool antigen protocols by outpatient clinics. This disintermediation favors manufacturers with direct distribution capabilities over those reliant on endoscopy equipment bundling. The shift is most visible in United States integrated delivery networks seeking operational flexibility in ambulatory expansion zones.
Helicobacter Pylori (H. Pylori) Diagnostics Market Segmentation
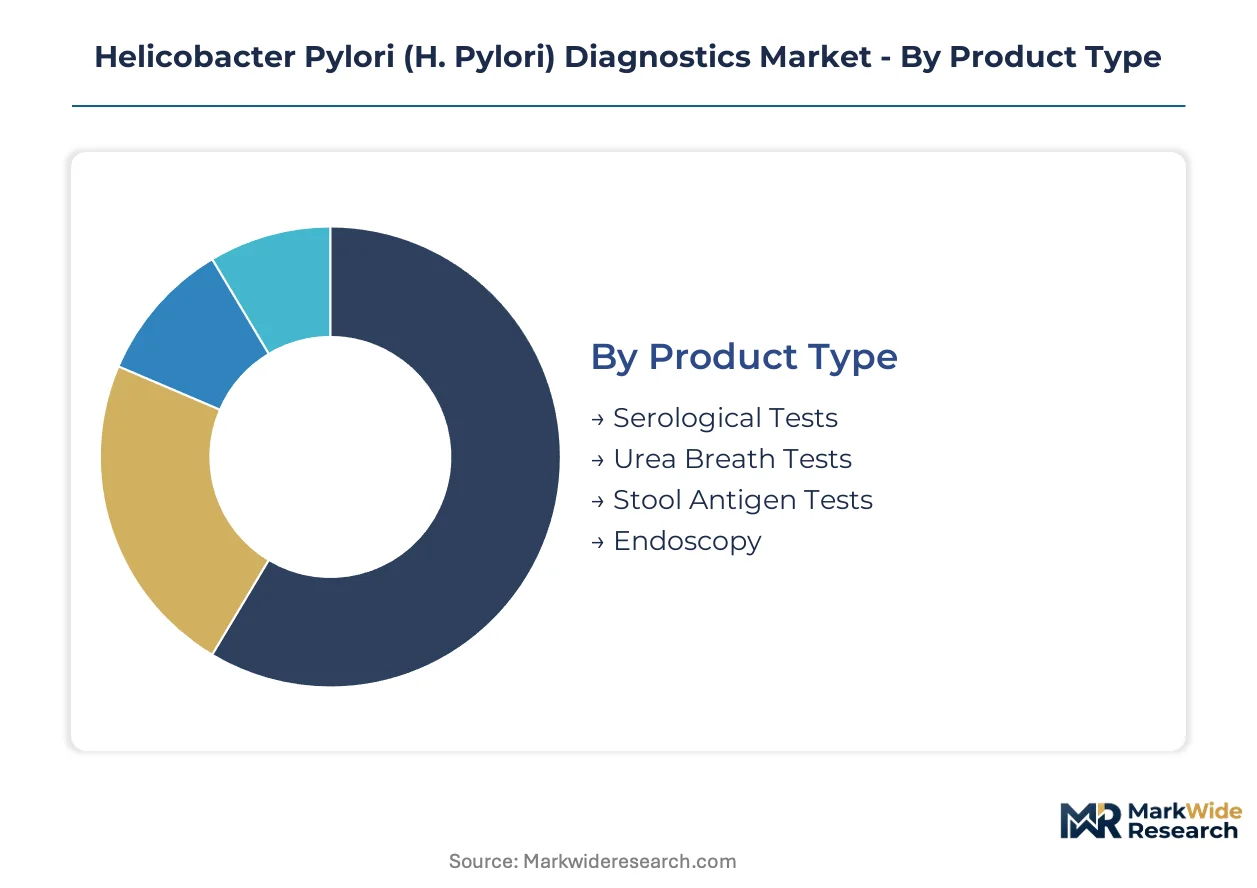
H. pylori diagnostics fragment across four intersecting dimensions that determine pricing power and customer access. Capital intensity, regulatory burden, and workflow integration requirements vary sharply by segment, reshaping competitive positioning across hospital procurement departments.
Product Type:
Urea breath and stool antigen platforms demand substantial upfront investment in substrate synthesis and antigen purification infrastructure, while serological and endoscopy-dependent methods operate on lighter capital bases.
- Urea Breath Tests:These platforms quantify carbon isotope ratios in expired air following oral administration of labeled urea substrate. Hospital networks in Japan and Germany concentrate procurement for these systems, driven by antimicrobial stewardship programs that mandate diagnostic confirmation before therapy initiation.
- Stool Antigen Tests:Fecal specimen analysis captures Helicobacter pylori antigens shed during active infection. Pediatric gastroenterology departments across United States integrated delivery networks drive volume expansion, as breath collection proves impractical in young patient populations.
- Serological Tests:Blood-based antibody detection offers lowest per-test cost but suffers specificity limitations in post-treatment monitoring.
- Endoscopy:Tissue biopsy with histopathological examination retains gold-standard status in academic medical centers despite invasive collection requirements.
Most installed capacity flows through urea breath test platforms. Expansion is steepest in stool antigen formats.
Technology:
Polymerase chain reaction systems command premium positioning through resistance profiling capabilities, while enzyme-linked immunosorbent assay infrastructure dominates high-throughput reference laboratory workflows on thinner margins.
- Polymerase Chain Reaction:Nucleic acid amplification enables simultaneous detection of clarithromycin, levofloxacin, and emerging metronidazole resistance mutations. Outpatient gastroenterology practices in Germany pilot expanded panels for salvage therapy selection, compressing turnaround times previously dependent on centralized reference laboratories.
- Enzyme-Linked Immunosorbent Assay:Plate-based antibody detection sustains dominant share in European reference laboratory workflows through standardized automation compatibility.
- Culture Method:Bacterial isolation with phenotypic susceptibility testing retains regulatory preference for resistance confirmation in Japan.
- Rapid Antigen Detection:Lateral flow and immunochromatographic formats compete on turnaround time in high-volume emergency department settings.
Volume concentrates in enzyme-linked immunosorbent assay infrastructure. Value expansion accelerates in polymerase chain reaction platforms.
End User:
Hospital procurement departments wield greatest negotiating leverage through bundled endoscopy service contracts, while diagnostic laboratories and clinics fragment purchasing across standalone test protocols.
- Hospitals:Academic medical centers in Japan and Germany anchor demand for comprehensive biopsy-histopathology workflows.
- Diagnostic Laboratories:Centralized reference facilities in United States process high-throughput serological and molecular panels for regional health system networks.
- Clinics:Outpatient gastroenterology practices increasingly purchase standalone non-invasive protocols decoupled from endoscopy bundles.
- Research Institutions:Academic centers drive pilot adoption of next-generation sequencing panels for expanded resistance profiling.
Procurement volume aggregates in hospital networks. Growth velocity peaks in clinic-based point-of-care expansion.
Delivery Mode:
Laboratory testing infrastructure represents sunk-cost dominance, while point-of-care and mobile formats require fresh capital deployment in portable instrumentation and connectivity modules.
- Point-of-Care Testing:Portable molecular platforms enable resistance-guided therapy selection in rural and ambulatory settings lacking centralized laboratory infrastructure.
- Laboratory Testing:Hospital-based and reference laboratory processing retains throughput advantages for complex molecular panels.
- Home Testing:Direct-to-consumer stool antigen collection kits expand access in pediatric and geriatric populations with mobility constraints.
- Mobile Testing Units:Deployable screening vehicles address geographic access gaps in underserved United States rural counties and emerging market regions.
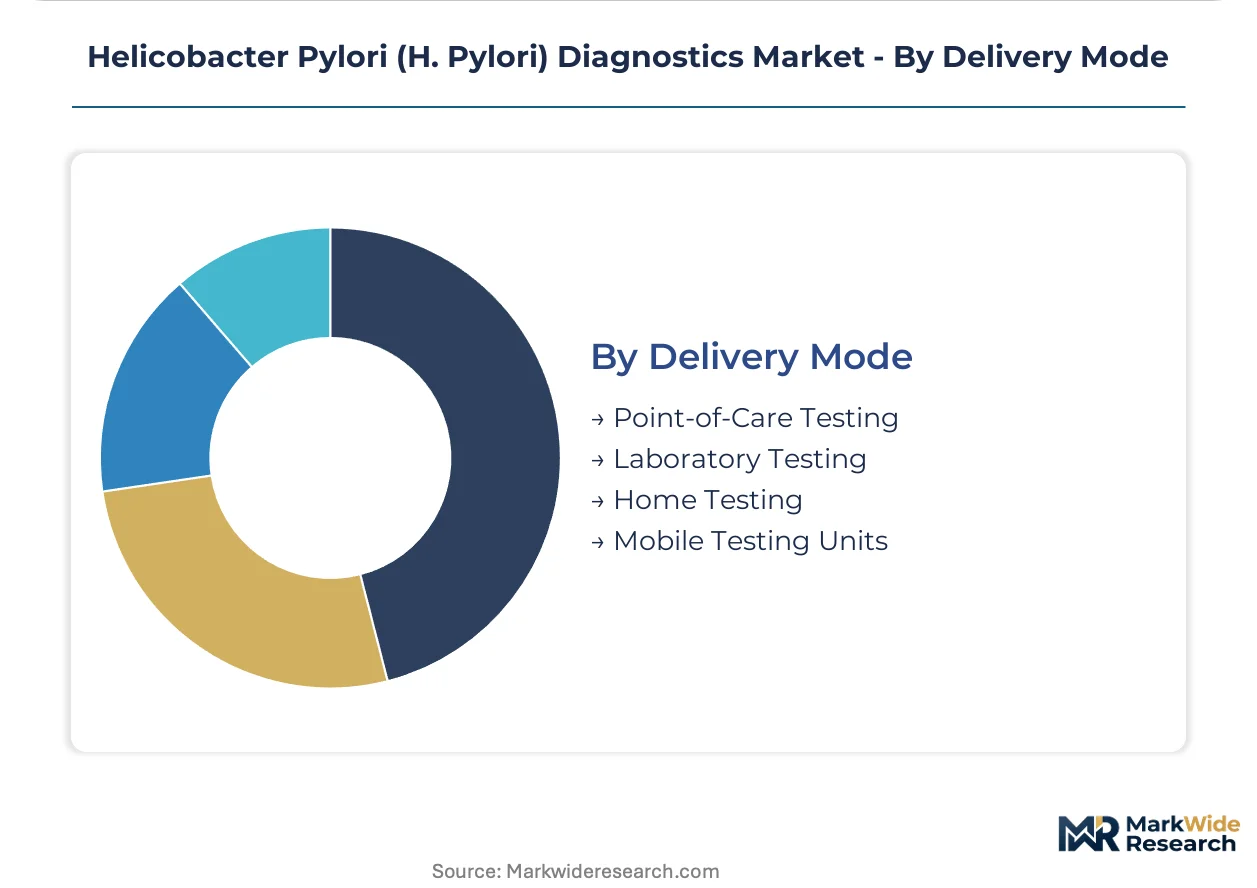
Test volume flows predominantly through laboratory channels. Deployment expansion is climbing fastest in point-of-care configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The H. pylori diagnostics industry traces its commercial origins to European and Japanese gastroenterology research programs of the 1980s, with subsequent scaling concentrated in North American hospital networks during the 1990s screening expansion era.
United States
Integrated delivery networks in Texas and Florida drive outpatient clinic procurement of standalone non-invasive protocols. FDA 510(k) pathways for molecular resistance panels compress development timelines for domestic manufacturers. The Research Triangle Park corridor anchors diagnostic platform development for hospital system networks.
Germany
Statutory health insurance reimbursement for antibiotic susceptibility testing creates payment tailwinds for molecular diagnostic providers in Bavaria and North Rhine-Westphalia. EMA In Vitro Diagnostic Regulation imposes stricter clinical evidence standards for CE-marked products entering European laboratories. The Munich-Stuttgart industrial corridor concentrates reference laboratory automation infrastructure.
Japan
Domestic manufacturers benefit from PMDA streamlined approval pathways for urea breath test systems serving Tokyo and Osaka outpatient clinic networks. Antimicrobial stewardship programs in academic medical centers mandate diagnostic confirmation before therapy initiation. The Kanto region anchors endoscopy-histopathology workflow demand despite non-invasive test penetration.
United Kingdom
NHS England procurement frameworks favor centralized laboratory processing for regional health system networks in London and the Midlands. MHRA post-Brexit regulatory divergence creates parallel compliance requirements for IVD manufacturers. The Oxford-Cambridge arc pilots next-generation sequencing panels for expanded resistance profiling.
China
NMPA regulatory harmonization accelerates molecular assay platform approvals for domestic manufacturers serving Shanghai and Beijing hospital networks. Screening program expansion in gastroenterology departments drives demand for non-invasive testing protocols. The Yangtze River Delta concentrates diagnostic reagent production infrastructure.
Helicobacter Pylori (H. Pylori) Diagnostics Market Competitive Landscape
The competitive structure tilts toward diversified life science conglomerates with platform breadth advantages over specialized diagnostic pure-plays. Market concentration remains moderate, with top-tier players commanding hospital procurement relationships while mid-cap specialists compete on turnaround time and geographic niche coverage. Three archetypes dominate: full-platform life science conglomerates, rapid-test specialists, and reference laboratory service integrators. Capacity expansion in automated molecular platforms and strategic partnerships for resistance panel distribution represent the dominant competitive moves reshaping vendor positioning.
Among full-platform conglomerates, Thermo Fisher Scientific occupies a position exemplifying PCR platform breadth across hospital systems, while Abbott Laboratories represents the diversified diagnostic portfolio archetype spanning immunoassay and molecular segments. Meridian Bioscience sits within the rapid-detection specialist tier, competing on turnaround time in high-volume laboratory environments. Bio-Rad Laboratories anchors the European reference laboratory supply position through enzyme-linked immunosorbent assay infrastructure dominance.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Quest Diagnostics |
| Meridian Bioscience |
| Bio-Rad Laboratories |
| F. Hoffmann-La Roche |
| Abbott Laboratories |
| Biohit Oyj |
| CerTest BIOTEC |
| DiaSorin |
| Others |
Supply & Pricing Matrix
Specialized radiochemist workforce concentration in Massachusetts and Basel anchors carbon-13 urea synthesis operations, with labor-cost differentials between North American and European facilities widening pricing-tier spreads for urea breath test substrates.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates molecular resistance panels from rapid antigen formats and legacy serological assays. Price differentiation hinges on FDA 510(k) clearance tier and automation compatibility for high-throughput laboratory workflows. Pricing pressure stems from CMS reimbursement compression on antibody-based screening, eroding margins in reference laboratory serology contracts. Pediatric gastroenterology clinics exhibit highest price sensitivity, while academic medical centers in Japan and Germany absorb premium pricing for biopsy-histopathology bundles.
Supply Chain Analysis
Dual-sourcing requirements for carbon-13 urea substrates now dominate procurement protocols at major diagnostic manufacturers, mandating qualification of secondary suppliers beyond Cambridge Isotope Laboratories. Geographic supply concentration clusters in the United States, Germany, and Japan for isotope enrichment infrastructure. Raw material dependencies rest on helium-3 for mass spectrometry calibration, specialized polymerase enzymes for PCR amplification, and monoclonal antibody cell lines for antigen detection kits. Single-source vulnerability in carbon-13 production exposes breath test manufacturers to radiopharmaceutical facility outages. Distribution runs through hospital procurement departments and regional laboratory supply cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The H. pylori diagnostics market functions as a stable compounder, with antimicrobial stewardship mandates in hospital systems generating durable demand for diagnostic confirmation protocols.
For Market Incumbents: To counter point-of-care molecular platform entrants, anchor hospital system relationships through long-term service contracts for resistance panel processing. Deepen backward integration into carbon-13 urea production to secure substrate supply against radiopharmaceutical facility bottlenecks. Prioritize LIS-EMR interoperability investments to raise switching costs for integrated delivery networks. For New Entrants and Emerging Players: Portable PCR systems for rural ambulatory settings represent the most penetrable white-space target, bypassing entrenched reference laboratory relationships. Direct-to-consumer stool antigen collection kits for pediatric populations offer second-mover advantage in home testing segments. Pursue GPO contract penetration through aggressive pricing on rapid antigen formats to secure initial volume footholds. For Investors and Strategic Acquirers: Full-platform life science conglomerates are the most active acquirer in this space, seeking molecular assay capabilities to complement existing immunoassay infrastructure. Target mid-cap specialists with FDA-cleared resistance panels and established hospital procurement relationships. Watch for inflection in Germany's DVG reimbursement decisions on expanded antibiotic susceptibility testing coverage.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EMA In Vitro Diagnostic Regulation imposes stricter clinical evidence standards for European market entry. |
| Hospital System Partnership | Integrated delivery networks in Texas and Florida unbundle H. pylori testing from endoscopy service contracts. |
| Software Companion Development | AI-assisted histopathology algorithms reduce pathologist review time for gastric biopsy specimen analysis. |
| Reimbursement Strategy | Antimicrobial stewardship programs reshape coverage for resistance-guided testing versus empirical treatment protocols. |
| FDA Submission | 510(k) premarket notification requirements for molecular resistance panels demand extensive clinical concordance studies. |
Research Methodology
Direct dialogue with hospital laboratory directors, gastroenterology department heads, diagnostic manufacturer regulatory affairs leads, and GPO contracts managers grounded qualitative insights, cross-referenced with FDA 510(k) filings, EMA notified body opinions, CMS Medicare reimbursement databases, and hospital procurement records. Secondary validation drew from biomedical engineering journals and antimicrobial stewardship program documentation. Bottom-up test volume modeling and top-down market sizing triangulated demand estimates.
Segmentation outputs across product type, technology platform, end-user category, and delivery mode fed into analytical frameworks spanning the projection horizon. CAGRs emerged from test volume trajectories, pricing trend analysis, and reimbursement pathway evolution. Resistance profiling adoption curves and point-of-care expansion rates served as industry-specific forecast inputs.
The model holds under stable regulatory reimbursement environments; deviation in FDA guidance on molecular assay validation or EMA notified body review timelines would shift competitive positioning dynamics. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Autoimmunity Immunoassay Market
Diagnostics
North America and Europe Companion Animal Diagnostics Imaging Market
Diagnostics
Global Chromoendoscopy Agents Market
Diagnostics
North America Point of Care Diagnostics Market
Diagnostics
Diagnostic Exosome Biomarkers Market
Diagnostics
DNA and RNA Probes Market
Diagnostics
Europe Breast Cancer Screening Tests Market
Diagnostics
Global Kidney Cancer Diagnostics Market
Diagnostics
Haptoglobin Reagent Market
Diagnostics
Tuberculosis (TB) Diagnostics Market
Diagnostics
Germany in-Vitro Diagnostics Market
Diagnostics
Global Immunoassay Market
Diagnostics
Global Paper Diagnostics Market
Diagnostics
Hypopituitarism Diagnostics Market
Diagnostics
IVD Antibody Market
Diagnostics
In Vitro Diagnostics (IVD) Quality Control Market