
 Fungal Antigens Market | 2026-2036
Fungal Antigens Market Size, Share, and Industry Trends Forecast 2026-2036
Fungal Antigens Market Analytics
The gap between premium recombinant fungal antigens and commodity-grade native extracts is rebalancing procurement patterns across diagnostic supply chains. Thermo Fisher Scientific leverages its global distribution network to sustain bulk antigen contracts with reference laboratories, while Bio-Rad Laboratories differentiates through specialized immunoassay-grade formulations for clinical diagnostics. Siemens Healthineers anchors its position in automated analyzer-integrated antigen kits, competing on workflow efficiency rather than price alone.
Fungal antigens are purified protein or polysaccharide preparations derived from pathogenic species such as Aspergillus fumigatus and Candida albicans, manufactured through cell culture fermentation or recombinant expression in bacterial or yeast systems, and standardized by protein concentration and immunoreactivity titers for use in serological detection platforms. The Aspergillus Fumigatus segment dominates clinical diagnostics due to the rising incidence of invasive aspergillosis in immunocompromised patient populations, while Cryptococcus Neoformans antigen detection commands premium pricing in therapeutic research applications. Injectable delivery mode leads hospital procurement, though intranasal formulations are gaining traction in vaccine development pipelines targeting mucosal immunity.
The FDA's Quality System Regulation and the EU IVDR framework impose stringent batch-to-batch consistency requirements on fungal antigen manufacturers, directly shaping R&D allocation toward controlled-expression systems. ISO 13485 certification and WHO prequalification pathways further govern market access for products targeting low-resource diagnostic settings. Stakeholders must monitor evolving serological assay harmonization initiatives and decide whether to internalize recombinant production capabilities or maintain reliance on specialized contract manufacturers.
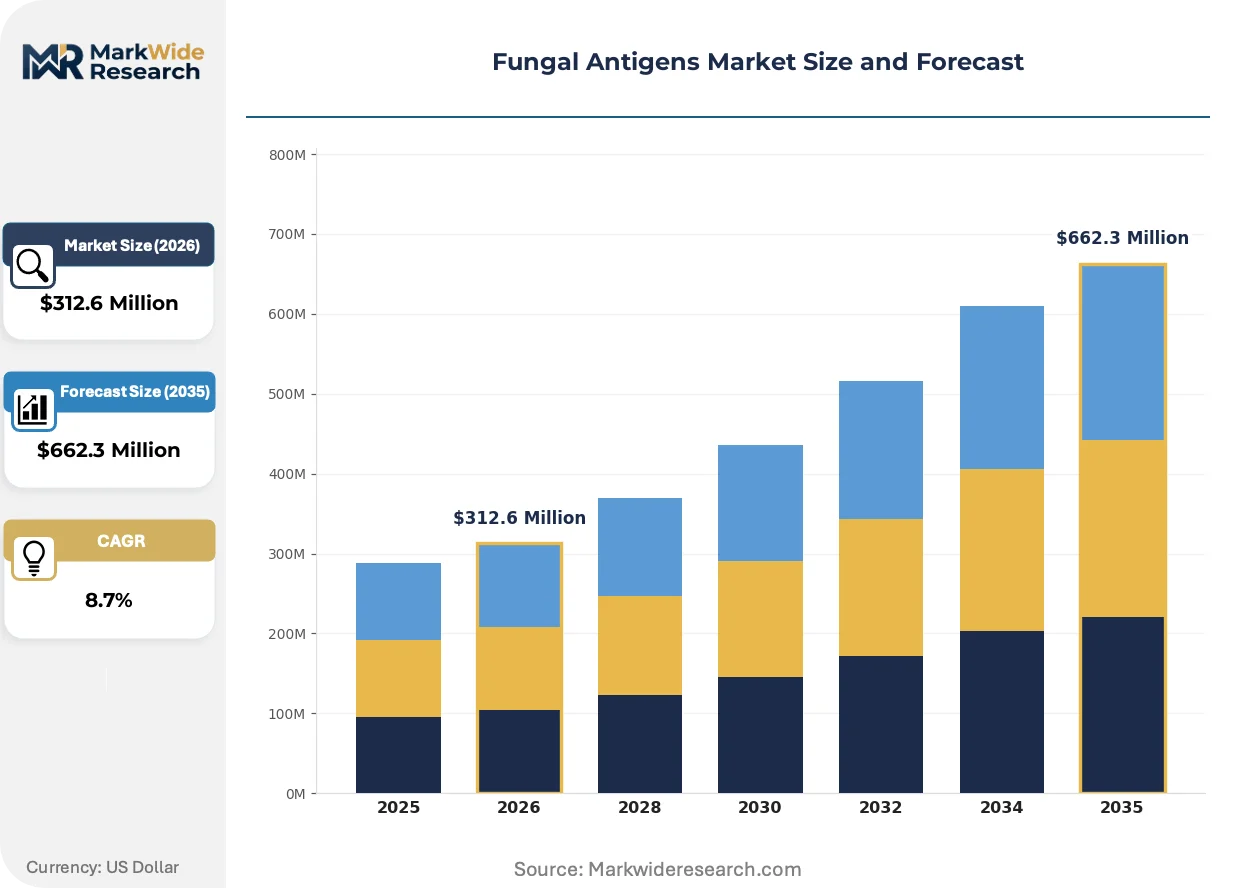
Market Dynamics
Recombinant expression systems are displacing native antigen extraction as the dominant production methodology, compressing batch variability and forcing manufacturers to reconfigure fermentation capacity toward controlled bacterial and yeast platforms.
Growth Catalysts
- EU IVDR Compliance Deadlines:The In Vitro Diagnostic Regulation mandates enhanced analytical sensitivity for serological assays, pulling diagnostic laboratories toward certified high-purity antigen suppliers.
- Hospital-Acquired Infection Surveillance:Medicare reimbursement policies in the United States create institutional procurement pull-through for invasive aspergillosis screening protocols.
- Immunocompromised Patient Volumes:Expanding transplant medicine and oncology immunosuppression regimens drive sustained clinical demand for cryptococcal meningitis detection.
Market Restraints
- Recombinant Production Capex:Bioreactor infrastructure and downstream purification systems require substantial capital deployment, elevating barriers for mid-scale entrants.
- Batch-to-Batch Consistency Enforcement:FDA Quality System Regulation and ISO 13485 certification timelines extend product validation cycles, constraining speed-to-market for novel antigen formulations.
- Native Extract Substitution Risk:Commodity-grade polysaccharide preparations from Aspergillus species retain cost advantages in research-only applications, limiting premium recombinant penetration in non-clinical segments.
Strategic Opportunities
- WHO Prequalification Pathways:Low-resource diagnostic settings in sub-Saharan Africa and Southeast Asia present volume expansion potential for manufacturers achieving harmonized serological assay standards.
- Mucosal Vaccine Formulations:Intranasal delivery development pipelines targeting mucosal immunity create demand for novel antigen adjuvant combinations beyond injectable presentations.
- Automated Analyzer Integration:Siemens Healthineers and Roche Diagnostics platforms favor antigen kits with standardized calibrator ranges, rewarding suppliers with embedded workflow partnerships.
Industry Challenges
- Fermentation Specialist Scarcity:Controlled-expression system operation and downstream protein purification expertise concentrates among contract manufacturing organizations, limiting in-house capability building.
- Serological Harmonization Delays:Divergent reference standard adoption across EMA, FDA, and WHO frameworks complicates multi-jurisdictional product registration strategies.
- Legacy Immunoassay Integration:Reference laboratories maintain substantial installed bases of enzyme-linked immunosorbent assay protocols, creating friction for chemiluminescent and lateral flow platform transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fungal Antigens Market |
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $662.3 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aspergillus Fumigatus, Candida Albicans, Histoplasma Capsulatum, Cryptococcus Neoformans Delivery Mode: Injectable, Oral, Intranasal, Transdermal End User: Hospitals, Diagnostic Laboratories, Research Institutes, Pharmacies Application: Clinical Diagnostics, Vaccine Development, Therapeutic Research, Epidemiological Studies |
| Companies Covered | Bio-Rad Laboratories, Creative Diagnostics, IMMY, QED Bioscience, Pulse Scientific, Jena Bioscience, Thermo Fisher Scientific, Siemens Healthineers, F. Hoffmann-La Roche, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fungal Antigens Market Evolving Landscape
Antigen production platforms are fragmenting into specialized recombinant and native extraction camps, while regulatory harmonization initiatives and procurement consolidation reshape competitive positioning across diagnostic supply chains.
Recombinant protein expression in Pichia pastoris and Escherichia coli systems delivers standardized immunoreactivity profiles for Aspergillus galactomannan detection. Large reference laboratories in Germany and the United States are adopting these platforms at accelerating pace to satisfy IVDR and FDA batch consistency requirements. This standardization is modularizing quality control workflows and compressing validation timelines for multi-analyte serological panels.
The EU In Vitro Diagnostic Regulation imposes stricter performance documentation and post-market surveillance obligations on serological assay manufacturers. Industrial consequence includes elevated documentation burdens and accelerated phase-out of legacy native antigen formulations lacking traceable calibration chains. Automated analyzer-integrated antigen kits face the steepest compliance ramps, driving consolidation toward suppliers with dedicated regulatory affairs infrastructure.
Diagnostic procurement is concentrating through group purchasing organizations and integrated delivery networks, displacing fragmented laboratory-level contracting. Reference laboratories and hospital systems are consolidating vendor relationships to secure volume pricing and technical support standardization. This concentration is most visible in the United States, where Medicare reimbursement compression incentivizes operational efficiency through supplier reduction programs.
Fungal Antigens Market Segmentation
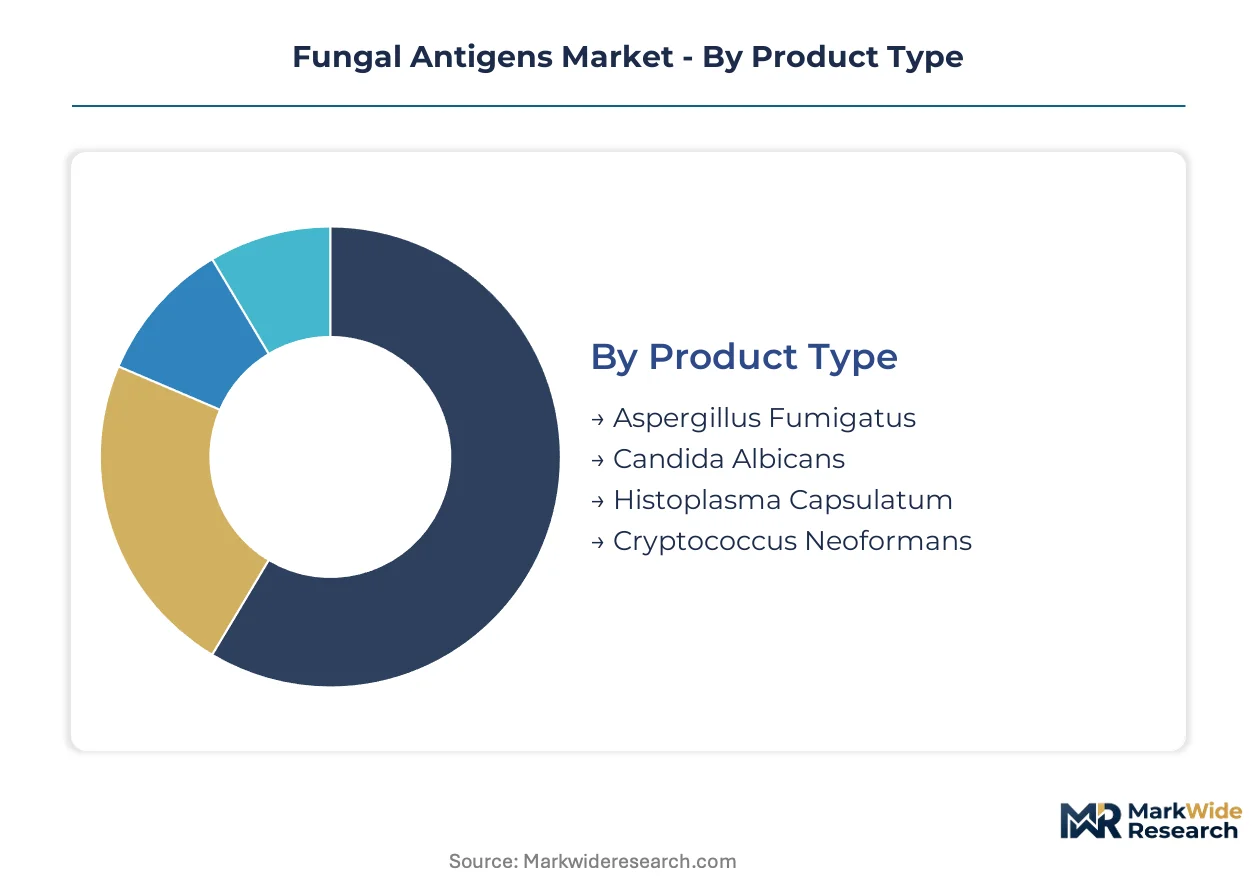
Diagnostic manufacturers configure antigen portfolios around pathogen prevalence and assay platform compatibility. Procurement patterns diverge sharply between high-volume hospital screening contracts and specialized research-grade formulations.
Product Type:
Recombinant expression platforms and native extraction methods define manufacturing economics and regulatory qualification pathways across pathogen-specific offerings.
- Aspergillus Fumigatus:Galactomannan and crude antigen preparations dominate invasive aspergillosis serological detection. Hospital laboratories in the United States and Germany drive procurement volume through Medicare-reimbursed screening protocols for immunocompromised hematology-oncology patients.
- Cryptococcus Neoformans:Capsular polysaccharide antigens command premium positioning in cryptococcal meningitis diagnostics. Sub-Saharan African reference laboratories and Southeast Asian hospital networks represent concentrated demand centers for WHO-prequalified lateral flow assays.
- Candida Albicans:Mannan and anti-mannan antibody detection reagents serve systemic candidiasis panels in intensive care unit surveillance.
- Histoplasma Capsulatum:Histoplasmin preparations remain concentrated in endemic region reference laboratories and CDC-affiliated public health networks.
Mature deployment sits with Aspergillus Fumigatus. Newer deployment is concentrated in Cryptococcus Neoformans.
Delivery Mode:
Route of administration determines formulation stability requirements, cold chain infrastructure, and reimbursement coding complexity across customer segments.
- Injectable:Intravenous and subcutaneous presentations constitute the standard for therapeutic protein delivery and diagnostic skin testing. Hospital and clinical laboratory procurement accounts for dominant volume through established reimbursement frameworks.
- Intranasal:Mucosal delivery formulations target vaccine development pipelines emphasizing IgA-mediated immunity. Biotechnology research institutes in Massachusetts and Bavaria represent accelerating investment in adjuvant-compatible powder and liquid formulations.
- Oral:Enteric-coated preparations serve veterinary and limited human therapeutic applications with reduced bioavailability profiles.
- Transdermal:Microneedle and patch-based delivery remains experimental for fungal antigen applications, concentrated in academic research consortia.
Injectable formats anchor revenue concentration. Intranasal formats are climbing the fastest on vaccine platform investment.
End User:
Customer procurement authority and technical specification requirements fragment vendor engagement models across institutional categories.
- Hospitals:Integrated delivery networks and academic medical centers drive consolidated purchasing for invasive fungal infection screening programs. FDA-cleared assay integration with Siemens and Roche automated analyzers shapes vendor selection criteria.
- Diagnostic Laboratories:Reference laboratories and commercial testing chains prioritize batch-to-batch consistency documentation for IVDR and CLIA compliance.
- Research Institutes:Academic and government laboratories procure non-GMP antigen grades for assay development and epidemiological surveillance protocols.
- Pharmacies:Retail and specialty pharmacy channels represent minimal direct procurement, serving primarily as distribution nodes for point-of-care testing kits.
Volume leadership rests with Hospitals. Specification complexity concentrates in Diagnostic Laboratories.
Application:
Use case determines purity grade, regulatory pathway, and pricing tier across the value chain.
- Clinical Diagnostics:IVDR- and FDA-cleared immunoassays for aspergillosis, cryptococcosis, and candidiasis detection represent the revenue foundation. Automated analyzer compatibility and calibrator traceability determine supplier stickiness.
- Vaccine Development:Adjuvant-formulated antigen candidates for mucosal and systemic fungal vaccines command development-stage premiums. Biotechnology sponsors in California and Basel evaluate recombinant expression yields and immunogenicity profiles.
- Therapeutic Research:Immunotherapy and desensitization protocols utilize standardized allergen extracts in controlled clinical trial settings.
- Epidemiological Studies:Seroprevalence surveys and outbreak investigations consume bulk antigen quantities with reduced documentation requirements.
Revenue scale favors Clinical Diagnostics. Pipeline investment flows fastest into Vaccine Development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's biotechnology corridor anchors North American fungal antigen development, with Massachusetts-based research institutes driving recombinant expression platform advancement and clinical assay validation.
United States
Medicare reimbursement policies for invasive aspergillosis screening sustain hospital procurement volumes, particularly within hematology-oncology departments. FDA Quality System Regulation mandates rigorous batch-to-batch documentation for serological assay manufacturers. The Research Triangle Park in North Carolina concentrates contract manufacturing capacity for diagnostic-grade antigen production.
Germany
Reference laboratories in Bavaria and Baden-Württemberg accelerate adoption of IVDR-compliant recombinant antigen platforms for automated analyzer integration. EMA guidance on in vitro diagnostic performance standards shapes supplier qualification protocols. The Munich-Planegg biotech cluster hosts specialized fermentation capacity for controlled-expression system manufacturing.
India
CDSCO regulatory pathways for diagnostic reagents attract contract manufacturing investment targeting price-sensitive hospital networks. WHO prequalification initiatives for cryptococcal meningitis lateral flow assays concentrate procurement authority at national reference laboratories in Delhi and Pune. The Hyderabad-Genome Valley corridor builds recombinant protein expression capabilities for export-oriented antigen supply.
China
NMPA medical device classification rules for in vitro diagnostics reshape import substitution strategies among domestic antigen producers. Shanghai and Suzhou industrial parks concentrate GMP-compliant fermentation infrastructure serving Asia-Pacific diagnostic kit manufacturers. The Yangtze River Delta corridor integrates upstream antigen production with downstream immunoassay assembly.
Brazil
ANVISA regulatory harmonization with PAHO standards facilitates regional distribution of fungal diagnostic reagents from São Paulo-based distributors. Hospital-acquired infection surveillance programs in southeastern state networks drive institutional procurement of aspergillosis detection kits. The Campinas biotech cluster develops localized antigen formulations for tropical mycosis applications.
Fungal Antigens Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the fungal antigen value chain, with fermentation infrastructure owners facing pressure from specialized formulation developers outsourcing manufacturing. The supplier base concentrates around three tiers: integrated diagnostic conglomerates with captive antigen production, dedicated recombinant protein specialists, and regional native extract distributors. Consolidation pressures intensify as IVDR and FDA documentation burdens favor entities with dedicated regulatory affairs infrastructure. Dominant competitive moves include backward integration into recombinant expression capacity and strategic partnerships with automated analyzer platform owners.
Among diversified life science conglomerates, Thermo Fisher Scientific occupies a position exemplifying global distribution scale, while Bio-Rad Laboratories represents specialized immunoassay-grade formulation expertise. Siemens Healthineers anchors the workflow-integrated tier, competing through analyzer compatibility rather than standalone antigen supply. These three entities collectively illustrate the strategic segmentation between volume-driven bulk supply, precision diagnostics, and platform-embedded positioning.
| Leading Market Players |
|---|
| Bio-Rad Laboratories |
| Creative Diagnostics |
| IMMY |
| QED Bioscience |
| Pulse Scientific |
| Jena Bioscience |
| Thermo Fisher Scientific |
| Siemens Healthineers |
| F. Hoffmann-La Roche |
| Others |
Value Network & Pricing Analysis
Specialized fermentation biologists in Bavaria and the Research Triangle Park anchor production economics, with labor-cost differentials between German contract manufacturers and Indian CDMOs widening spreads between IVDR-certified premium tiers and research-grade economy offerings.
Pricing Analysis
Assay analytical sensitivity serves as the value-based pricing anchor, with FDA-cleared and IVDR-compliant recombinant antigens commanding substantial premiums over native extracts. Pricing stratifies across GMP-certified clinical diagnostic grades, ISO 13485-qualified reference standards, and non-GMP research formulations. Cost compression in the research-grade tier is intensifying because CDSCO-registered Indian manufacturers are scaling Pichia pastoris capacity for export markets. Hospital laboratories integrated with Siemens and Roche automated platforms exhibit the least price sensitivity, while academic research institutes purchasing bulk native extracts demonstrate maximum price elasticity.
Supply Chain Analysis
Dual-sourcing requirements from FDA Quality System Regulation and EU IVDR mandate that diagnostic kit manufacturers qualify at least two antigen suppliers per pathogen target, fragmenting procurement across multiple fermentation specialists. Controlled-expression bioreactor capacity concentrates in Germany, the United States, and India, with downstream purification consumables drawing from specialized resin suppliers in Switzerland and Japan. Single-source vulnerability persists in high-affinity monoclonal antibody detection reagents for cryptococcal antigen assays. Distribution runs through group purchasing organizations in North America and reference laboratory networks in Europe, with direct manufacturer relationships dominating high-volume hospital contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fungal antigens market is becoming a vertical-integration race, with diagnostic conglomerates pursuing captive recombinant expression capacity to secure supply continuity and margin control amid tightening IVDR documentation requirements.
For Market Incumbents: Cement analyzer-embedded positioning through exclusive calibrator partnerships with Siemens Healthineers and Roche Diagnostics platforms, while acquiring specialized Pichia pastoris fermentation capacity in the Munich-Planegg or Research Triangle Park clusters to neutralize CDSCO-registered Indian cost competition. Native extract substitution by research-only buyers represents the primary margin threat.
For New Entrants and Emerging Players: The mid-tier price-point gap between premium recombinant antigens and commodity native extracts offers white-space entry for WHO-prequalified lateral flow assay suppliers targeting sub-Saharan African reference laboratories. Southeast Asian hospital networks present the most penetrable geography given accelerating cryptococcal meningitis surveillance investment. A go-to-market angle anchored in automated analyzer calibrator standardization bypasses entrenched reference laboratory relationships.
For Investors and Strategic Acquirers: Re-rating potential sits with mid-scale recombinant specialists possessing dedicated regulatory affairs infrastructure given EU IVDR compliance deadline acceleration. The five-to-ten year viability window favors targets with backward integration into bacterial and yeast expression systems rather than reliance on contract manufacturing organizations. Monitor serological harmonization progress across EMA, FDA, and WHO frameworks as the inflection signal for multi-jurisdictional revenue scalability.
| Strategic Initiative | Industry Significance |
|---|---|
| Recombinant Expression Capacity Buildout | Controlled bacterial and yeast fermentation infrastructure secures IVDR batch consistency compliance and reduces native extract substitution risk. |
| Automated Analyzer Calibration Partnership | Embedded positioning with Siemens and Roche platforms creates switching costs for hospital laboratory procurement committees. |
| WHO Prequalification Pathway Investment | Harmonized serological assay standards unlock volume expansion in sub-Saharan African and Southeast Asian diagnostic networks. |
| Regulatory Affairs Infrastructure Expansion | Dedicated FDA and EMA submission capabilities compress product validation cycles and accelerate speed-to-market for novel antigen formulations. |
| Mucosal Vaccine Adjuvant Development | Intranasal formulation expertise positions suppliers for biotechnology sponsor pipelines targeting IgA-mediated immunity in Massachusetts and Basel. |
Research Methodology
Multi-period observation of Medicare reimbursement policy shifts, EU IVDR implementation timelines, and recombinant expression platform adoption rates anchored the trend analysis, supplemented by interviews with diagnostic laboratory directors, regulatory affairs specialists at antigen manufacturers, hospital procurement managers, and WHO prequalification officers. Secondary validation drew from FDA 510(k) filings, EMA IVDR technical documentation, ClinicalTrials.gov vaccine development protocols, and CMS Medicare claims data. Bottom-up segment sizing triangulated against top-down diagnostic kit production estimates.
Segment-weighting across pathogen-specific antigen demand, delivery mode formulation requirements, and end-user procurement authority shaped the analytical framework throughout the forecast period. CAGRs were derived from exponential growth modeling applied to hospital-acquired infection surveillance expansion, immunocompromised patient volume trajectories, and recombinant platform displacement curves for native extraction methods. Industry-specific inputs included fermentation capacity utilization rates and automated analyzer installed base growth.
Underlying measurement precision varies by segment; clinical diagnostics applications carry tighter precision than research-grade procurement given standardized reimbursement coding and regulatory filing transparency. Forecasts reflect assumptions regarding IVDR compliance deadline adherence and WHO prequalification pathway throughput. Deviation in serological harmonization timelines across EMA, FDA, and WHO frameworks would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Global Phytopathological Disease Diagnostics Market
Diagnostics
Sperm Density Testing Market
Diagnostics
Global Inflammatory Bowel Disease (IBD) Diagnostic Market
Diagnostics
Asia-Pacific Radioimmunoassay Market
Diagnostics
Infectious Disease in Vitro Diagnostics Market
Diagnostics
Food Allergy Diagnostics and Therapeutics Market
Diagnostics
Melanoma Cancer Diagnostics Market
Diagnostics
Equine Diagnostic Services Market
Diagnostics
Global Syphilis Immunoassay Diagnostics Market
Diagnostics
Glucose Tolerance Test Market
Diagnostics
Europe Lung Cancer Diagnostics Market
Diagnostics
In Vitro Diagnostic (IVD) Reagent Market
Diagnostics
Hydrogen Breath Test Analyzer Market
Diagnostics
Rapid RNA Testing Kits Market
Diagnostics
Syndromic Multiplex Diagnostic Market
Diagnostics
Global Lyme Disease Diagnostic Market