
 Multiplexed Diagnostics Market | 2026-2036
Multiplexed Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Multiplexed Diagnostics Market Analysis
The capital-intensity divergence between installed-base incumbents and emerging platform developers is redrawing competitive boundaries in multiplexed diagnostics. Abbott Laboratories leverages its vertically integrated reagent-instrument ecosystem to sustain pricing power across hospital networks. Thermo Fisher Scientific anchors its position through captive consumable pull-through on high-throughput mass spectrometry workflows. Bio-Rad Laboratories differentiates via specialized droplet digital PCR multiplexing for oncology companion diagnostics.
Multiplexed diagnostics encompasses simultaneous detection and quantification of multiple analytes—nucleic acids, proteins, or metabolites—within a single assay run, typically achieving throughput of 10–1,000 targets per sample through spatial encoding, bead-based barcoding, or mass-tag differentiation. The primary purpose centers on reducing sample volume requirements, turnaround time, and per-test cost while expanding diagnostic information density for complex disease profiling. Reagent and assay segments capture the majority of recurring revenue pools given consumable pull-through on locked instrument platforms. PCR-based multiplexing maintains installed-base dominance in infectious disease applications, while mass spectrometry multiplexing represents the fastest-expanding technology segment for metabolite and protein biomarker panels. Oncology application demand is concentrating in comprehensive genomic profiling assays that consolidate mutation detection, microsatellite instability, and tumor mutational burden into single workflows.
The US FDA regulates multiplexed devices through its in vitro diagnostics framework, with escalating scrutiny on analytical and clinical validation for high-plex panels. The EMA's IVDR transition in Europe is forcing restructuring of conformity assessment pathways for existing multiplex assay portfolios. China's NMPA has accelerated review timelines for domestically manufactured infectious disease multiplex platforms under its innovation device channel. Stakeholders must monitor regulatory divergence between jurisdictions as a primary determinant of platform launch sequencing and market access economics.
Market Dynamics
Hospital consolidation across the United States is concentrating purchasing power into centralized procurement networks, forcing platform developers to restructure go-to-market economics around high-throughput instrument placements and locked reagent contracts.
Growth Catalysts
- Companion diagnostics expansion:The US FDA's broadening guidance on co-developed therapeutics is mandating multiplexed biomarker panels for oncology drug approvals, pulling through platform installations at major academic medical centers.
- Infectious disease surveillance modernization:Public health laboratories are replacing single-plex workflows with respiratory pathogen panels that consolidate viral and bacterial detection, reducing turnaround times during outbreak response.
- Mass spectrometry multiplexing:Clinical metabolomics laboratories are adopting high-resolution mass-tag workflows for newborn screening expansion, enabling simultaneous quantification of dozens of metabolic disorders from dried blood spots.
Market Restraints
- Reagent supply concentration:Three suppliers control the majority of fluorescent bead and mass-tag chemistries, creating vulnerability in panel manufacturing continuity.
- IVDR conformity costs:Europe's transition to the In Vitro Diagnostic Regulation is forcing portfolio restructuring and notified body bottlenecks that delay market access for mid-plex assays.
- Technical ceiling on plexity:Current spatial encoding and barcoding architectures face signal-to-noise degradation beyond approximately 1,000 targets, limiting information density gains for whole-transcriptome applications.
Strategic Opportunities
- Point-of-care decentralization:CLIA-waived multiplex platforms for respiratory panels remain underpenetrated in urgent care and retail clinic settings across the United States.
- Pharmacogenomics integration:Payers are expanding coverage for preemptive CYP450 and HLA-B*57:01 testing, creating demand for compact multiplex chemistries that consolidate drug-gene interaction panels.
- Digital PCR convergence:Droplet partitioning combined with fluorescent barcoding is opening absolute quantification applications in cell therapy potency testing and residual disease monitoring.
Industry Challenges
- Bioinformatics talent scarcity:Clinical laboratories lack sufficient computational biologists to validate, interpret, and maintain the software pipelines required for high-plex assay deployment.
- Interoperability friction:LIMS integration with proprietary instrument data formats creates workflow bottlenecks that delay result reporting in high-volume hospital laboratories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multiplexed Diagnostics Market |
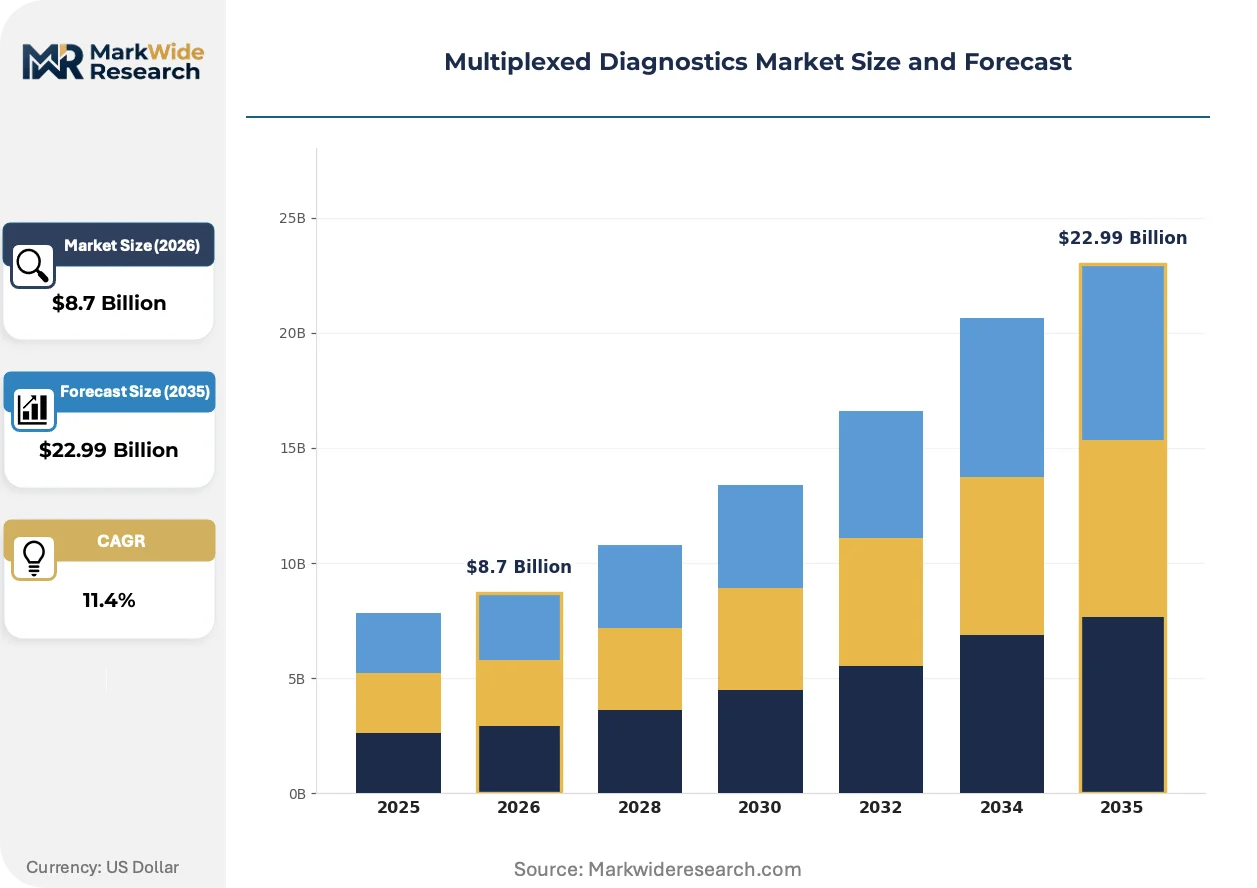
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Assays, Instruments, Kits Technology: PCR, Microarray, Mass Spectrometry, ELISA End User: Hospitals, Laboratories, Research Institutions, Diagnostic Centers Application: Infectious Diseases, Oncology, Genetic Testing, Autoimmune Disorders |
| Companies Covered | Abbott Laboratories, Thermo Fisher Scientific, Bio-Rad Laboratories, Illumina, F. Hoffmann-La Roche, Luminex Corporation, Siemens Healthineers, bioMérieux, Becton Dickinson and Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multiplexed Diagnostics Market Emerging Trajectories
Next-generation sequencing readouts are compressing the addressable market for hybridization-based multiplex panels, forcing incumbent platforms to defend installed bases through reagent lock-in and workflow integration.
Next-generation sequencing is supplanting hybridization microarrays in comprehensive genomic profiling for solid tumors. Major cancer centers are migrating mutation detection, copy number variation, and microsatellite instability assessment onto unified sequencing workflows. This transition is compressing demand for discrete PCR-based oncology panels and forcing reagent manufacturers to reposition mid-plex chemistries toward point-of-care and near-patient settings.
Europe's In Vitro Diagnostic Regulation is restructuring conformity assessment pathways for legacy multiplex assays. Notified body capacity constraints are extending technical documentation review timelines. Manufacturers with pre-IVDR portfolios are prioritizing United States FDA submissions to maintain revenue continuity while European certifications pend.
Consolidated hospital procurement is unbundling instrument and reagent negotiations. Integrated delivery networks are demanding separate pricing visibility on capital equipment and consumable contracts. This pattern is most pronounced in United States health systems with centralized laboratory oversight, where procurement committees now benchmark total cost-per-reportable across competing platform ecosystems.
Multiplexed Diagnostics Market Segmentation
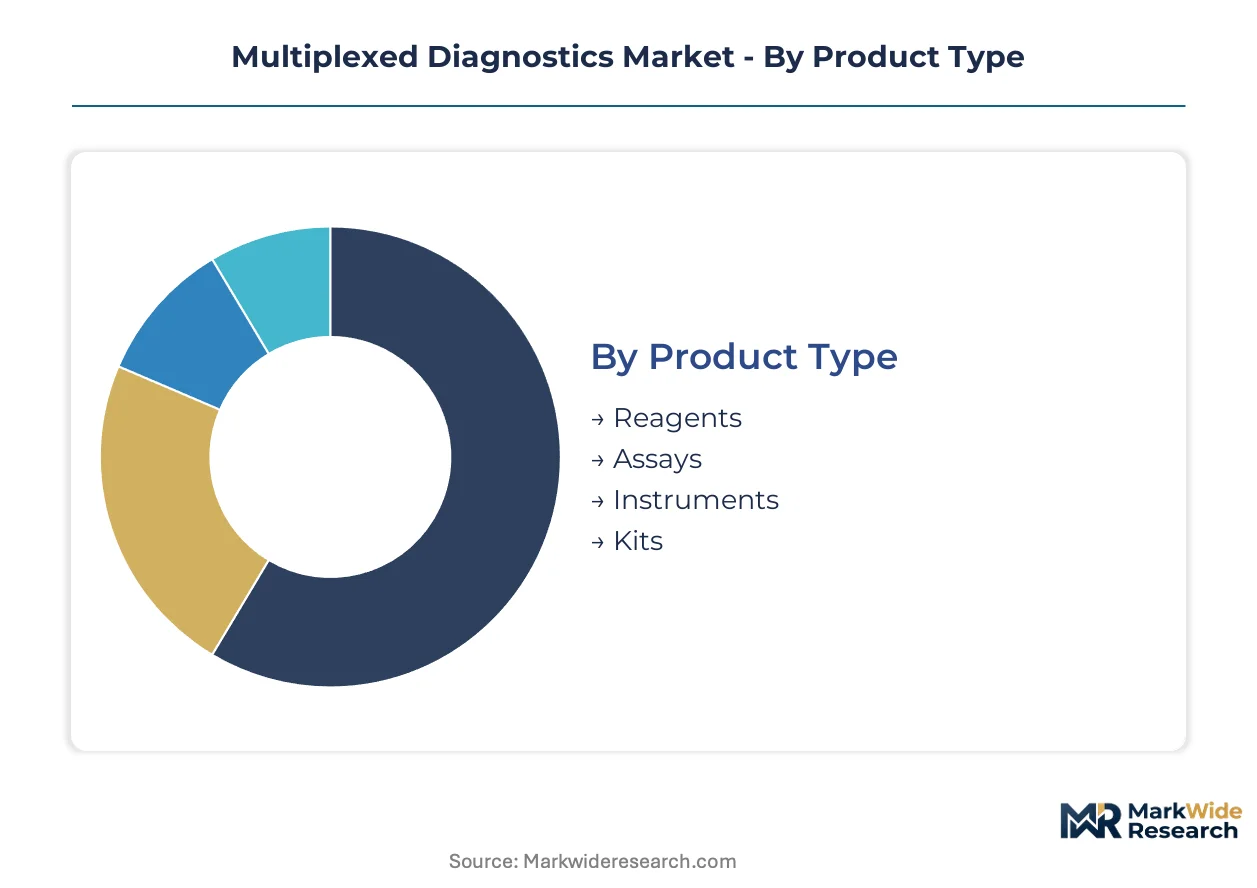
Multiplexed diagnostics segmentation reflects divergent regulatory pathways across product categories and divergent reimbursement economics across end-use settings. Technology choices determine validation burden and time-to-market, while application focus shapes platform architecture and consumable pull-through rates.
Product Type:
FDA's 510(k) and PMA pathways impose distinct clinical evidence requirements on reagents versus instruments, fragmenting go-to-market timelines and capital allocation priorities.
- Reagents:Fluorescent beads, mass-tag chemistries, and enzyme master mixes constitute the recurring revenue backbone of locked instrument ecosystems. Hospital laboratories in the United States concentrate procurement of high-plex respiratory panels and oncology companion diagnostic reagents through multi-year consumable contracts.
- Assays:Pre-validated analyte-specific reagent configurations reduce in-house development burden for clinical laboratories. Demand clusters in FDA-cleared respiratory pathogen panels and EUA-authorized infectious disease menus, where regulatory clearance accelerates hospital adoption.
- Instruments:Capital equipment spans flow cytometry platforms, mass spectrometry systems, and digital PCR workstations. Academic medical centers prioritize high-throughput installations with integrated bioinformatics pipelines.
- Kits:Research-use-only configurations dominate translational workflows and biomarker discovery programs. Biotechnology companies in Boston and San Diego corridors drive volume for customizable panel architectures.
Established volume favors Reagents; emerging adoption favors Assays.
Technology:
Cost tier stratification separates capital-intensive mass spectrometry installations from benchtop PCR workflows, concentrating placement decisions in consolidated procurement committees.
- PCR:Thermal cycling with fluorescent probe multiplexing dominates infectious disease installed bases. Public health laboratories in the United States standardize on respiratory pathogen panels that consolidate viral and bacterial targets.
- Mass Spectrometry:High-resolution mass-tag workflows enable simultaneous quantification of metabolites and proteins from dried blood spots. Newborn screening expansion in state laboratories drives the steepest expansion trajectory for this segment.
- Microarray:Hybridization-based nucleic acid detection faces compression from next-generation sequencing readouts. Remaining demand concentrates in agricultural genomics and food safety applications.
- ELISA:Enzyme-linked immunosorbent assays retain cost advantages for low-plex protein quantification. Reference laboratories deploy these for cytokine panels and autoimmune serology.
Installed-base concentration favors PCR; capability expansion favors Mass Spectrometry.
End User:
Customer type determines reimbursement pathway and test volume economics, with hospitals capturing the majority of high-margin companion diagnostic revenue.
- Hospitals:Integrated delivery networks consolidate purchasing power through centralized laboratory oversight. Oncology companion diagnostic panels generate premium pricing at major academic medical centers.
- Laboratories:Independent reference laboratories and public health facilities prioritize high-throughput respiratory surveillance. CLIA-waived platform adoption remains underpenetrated in urgent care settings.
- Research Institutions:Universities and government research centers drive demand for customizable research-use-only panels. NIH-funded genomics centers in Bethesda and Boston corridors anchor volume.
- Diagnostic Centers:Specialized testing facilities focus on pharmacogenomics and wellness screening. Retail clinic expansion creates emerging demand for point-of-care multiplex platforms.
Revenue concentration favors Hospitals; volume expansion favors Laboratories.
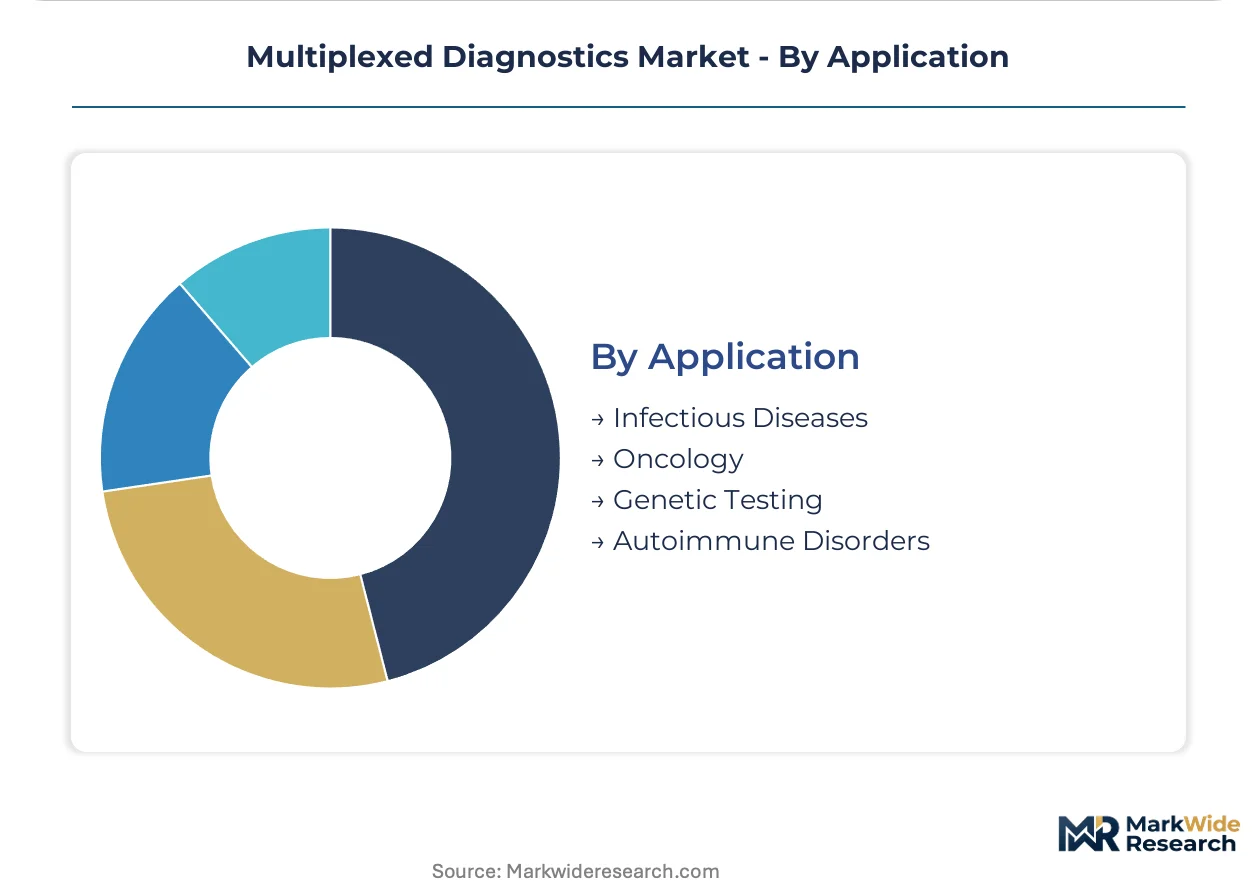
Application:
Maturity gradients separate established infectious disease menus from emerging autoimmune disorder portfolios, reshaping R&D allocation across platform developers.
- Infectious Diseases:Respiratory pathogen panels and bloodstream infection assays constitute the most validated commercial menus. FDA-cleared sepsis panels consolidate bacterial and fungal detection at Cleveland Clinic and Mayo Clinic networks.
- Oncology:Comprehensive genomic profiling consolidates mutation detection, microsatellite instability, and tumor mutational burden into unified workflows. Payer coverage expansion for companion diagnostics pulls through platform installations.
- Genetic Testing:Carrier screening and pharmacogenomics panels gain reimbursement traction with commercial payers. Preemptive CYP450 testing expands in integrated health systems.
- Autoimmune Disorders:Cytokine multiplexing and autoantibody panels remain concentrated in reference laboratory settings. Rheumatology and gastroenterology clinics drive emerging demand.
Validation depth favors Infectious Diseases; reimbursement expansion favors Oncology.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States while European laboratories absorb IVDR compliance costs that compress margin structures. Germany and Switzerland maintain premium positioning through specialized oncology companion diagnostics. China's NMPA innovation channel accelerates domestic platform approvals.
United States
Hospital consolidation into integrated delivery networks concentrates procurement leverage at Cleveland Clinic and Mayo Clinic systems. The FDA's expanding companion diagnostics guidance mandates multiplexed biomarker panels for oncology drug approvals. Boston and San Diego biotechnology corridors anchor demand for customizable research-use-only panel architectures.
Germany
Academic medical centers in Heidelberg and Munich drive high-throughput mass spectrometry installations for newborn screening expansion. The EMA's IVDR transition forces restructuring of conformity assessment pathways for existing assay portfolios. Bavaria's precision medicine clusters concentrate pharmacogenomics panel development for CYP450 testing.
China
Domestic infectious disease surveillance modernization replaces single-plex workflows with respiratory pathogen panels at provincial laboratories. The NMPA's innovation device channel accelerates review timelines for domestically manufactured multiplex platforms. Yangtze River Delta biotech parks in Shanghai and Suzhou concentrate droplet digital PCR development for oncology applications.
Switzerland
Specialized diagnostics developers in Basel and Zurich leverage proximity to pharmaceutical headquarters for companion diagnostic co-development partnerships. Swissmedic maintains streamlined review pathways for CE-marked multiplex assays seeking concurrent national approval. The country's precision medicine infrastructure supports premium pricing for comprehensive genomic profiling panels.
Japan
PMDA regulatory harmonization with FDA standards accelerates approval timelines for imported multiplex platforms at Tokyo and Osaka university hospitals. METI funding for genomic medicine infrastructure expands comprehensive genomic profiling reimbursement. Kanto region medical centers concentrate demand for respiratory pathogen panels in preparedness for seasonal influenza surveillance.
Multiplexed Diagnostics Market Vendor Landscape
Concentration sits with vertically integrated conglomerates that control instrument-reagent ecosystems. Three supplier groups dominate fluorescent bead and mass-tag chemistries, creating manufacturing continuity vulnerabilities for panel developers. Strategic archetypes include locked-platform incumbents defending installed bases, emerging platform developers seeking CLIA-waived point-of-care positioning, and specialized droplet digital PCR providers. Competitive moves center on multi-year consumable contract lock-ins and bioinformatics pipeline integration to delay next-generation sequencing displacement.
Among United States-based conglomerates, Abbott Laboratories and Thermo Fisher Scientific exemplify the locked-platform archetype through captive consumable pull-through strategies. Bio-Rad Laboratories occupies a specialist position in droplet digital PCR multiplexing for oncology companion diagnostics. These three anchors represent divergent responses to next-generation sequencing compression: ecosystem defense, workflow integration, and specialized capability depth.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Thermo Fisher Scientific |
| Bio-Rad Laboratories |
| Illumina |
| F. Hoffmann-La Roche |
| Luminex Corporation |
| Siemens Healthineers |
| bioMérieux |
| Becton Dickinson and Company |
| Others |
Supply Flow & Price Mechanics
Fluorescent bead chemistries replacing mass-tag reagents in mid-plex respiratory panels simultaneously redraw procurement geography toward Chinese specialty chemical manufacturers and compress pricing spreads between configured-to-order oncology companion diagnostics and standard infectious disease menus. This substitution dynamic concentrates cost leverage in three suppliers controlling bead and tag chemistries while forcing platform developers to restructure contract economics around locked instrument placements.
Pricing Analysis
The customization-premium spread separates FDA-cleared companion diagnostic reagent configurations from research-use-only panel architectures. Three-tier pricing structure across premium, standard, and economy levels tracks certification tier and volume scale, with academic medical centers absorbing premium pricing for comprehensive genomic profiling while public health laboratories negotiate standard-tier respiratory pathogen contracts. Cost compression in economy-tier research-use-only kits is intensifying because biotechnology corridors demand configurable architectures without regulatory validation overhead. Hospital procurement committees exhibit lowest price sensitivity for oncology companion diagnostics with therapeutic co-development mandates.
Supply Chain Analysis
China and Germany anchor fluorescent bead and mass-tag chemistry production for panel manufacturers. The supply chain draws from rare-earth phosphors, specialized polymer substrates, and enzyme master mixes as critical inputs. Single-source vulnerability concentrates in mass-tag chemistries where three suppliers control global capacity. Distribution runs through locked instrument-reagent ecosystems with multi-year consumable contracts dominating hospital network procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The multiplexed diagnostics market sits at a platform-economics inflection where next-generation sequencing readouts threaten to displace hybridization-based panels, forcing stakeholders to bet on ecosystem lock-in versus interoperability openness.
For Market Incumbents: Fortify captive consumable pull-through by deepening bioinformatics pipeline integration and securing multi-year reagent contracts with consolidated hospital procurement networks. The priority defensive move centers on embedding instrument-reagent ecosystems into laboratory information management system workflows to delay next-generation sequencing displacement. Incumbent platforms must simultaneously invest in CLIA-waived point-of-care configurations to defend against emerging decentralized testing entrants. For New Entrants and Emerging Players: Bioinformatics talent scarcity in clinical laboratories presents a service-layer gap where incumbents under-serve validation and interpretation needs. New entrants should target urgent care and retail clinic settings with CLIA-waived respiratory pathogen platforms, the most penetrable segment given underpenetrated point-of-care multiplex adoption. The optimal go-to-market angle pairs compact instrument footprints with cloud-based bioinformatics pipelines that reduce in-house computational burden. For Investors and Strategic Acquirers: Capital is best deployed toward specialized droplet digital PCR developers with oncology companion diagnostic positioning and proprietary fluorescent barcoding chemistries. Long-term viability across the projection horizon hinges on defensible intellectual property in absolute quantification applications for cell therapy potency testing. The signal to monitor is FDA guidance expansion on co-developed therapeutics mandating multiplexed biomarker panels.| Strategic Initiative | Industry Significance |
|---|---|
| Reagent Contract Lock-In | Multi-year consumable agreements with Cleveland Clinic and Mayo Clinic systems secure recurring revenue streams. |
| CLIA-Waived Platform Development | Point-of-care respiratory panel clearance opens urgent care and retail clinic distribution channels. |
| Bioinformatics Pipeline Integration | Embedded software workflows reduce laboratory information management system friction and delay sequencing displacement. |
| Companion Diagnostic Co-Development | FDA-mandated multiplexed biomarker panels for oncology drug approvals pull through high-margin platform installations. |
| Digital PCR Convergence Investment | Droplet partitioning with fluorescent barcoding enables absolute quantification in cell therapy potency testing. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with regulatory affairs leads, hospital procurement managers, clinical laboratory directors, and biomedical engineers; and secondary validation against FDA 510(k) and PMA filings, EMA IVDR submission databases, hospital GPO contracts, and CMS reimbursement schedules. Bottom-up triangulation across instrument placement data and reagent consumable pull-through rates was cross-checked with top-down market sizing from public company segment disclosures.
Across the analysis window, the forecasting framework modeled volume and value outputs through segmentation across product type, technology platform, end-user setting, and application area. CAGRs were derived from installed base expansion trajectories and consumable attach rate assumptions. Industry-specific forecast inputs incorporated NMPA innovation channel approval timelines and IVDR notified body capacity constraints.
Forecasts assume regulatory continuity in FDA, EMA, and NMPA regimes; material policy shifts would require re-modeling. Specific risks that could revise projections include IVDR conformity assessment bottlenecks extending European market access delays and next-generation sequencing cost curves accelerating panel displacement timelines. Recalibration cycles align with material shifts in companion diagnostics guidance and hospital consolidation patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Global Fecal Occult Blood Tests Market
Diagnostics
Europe Kidney Cancer Diagnostics Market
Diagnostics
Gastrointestinal Diagnostics Market
Diagnostics
Anatomic Pathology Market
Diagnostics
Allergy Diagnostics Market
Diagnostics
Blood Culture Media Market
Diagnostics
Syndromic Multiplex Diagnostic Market
Diagnostics
France in-Vitro Diagnostics Market
Diagnostics
Brain Cancer Diagnostics Market
Diagnostics
Chile in Vitro Diagnostics Market
Diagnostics
E.Coli Latex Agglutination Test Kits Market
Diagnostics
Respiratory Pathogen Testing Kits Market
Diagnostics
Middle East and Africa in-Vitro Diagnostics Market
Diagnostics
Immunodiagnostics Market
Diagnostics
Canada in-Vitro Diagnostics Market
Diagnostics
Food Allergy Diagnostics and Therapeutics Market