
 RT-PCR Kits Market | 2026-2036
RT-PCR Kits Market Size, Share, and Industry Trends Forecast 2026-2036
RT-PCR Kits Market Analytics
Multiplexing capability is tilting the RT-PCR technology stack toward higher-throughput, panel-based detection architectures. Thermo Fisher Scientific leverages its integrated instrument-reagent ecosystems to dominate high-volume reference lab contracts. QIAGEN sustains competitive position through sample-to-insight workflow automation that reduces hands-on time for diagnostic technicians. Bio-Rad Laboratories specializes in droplet digital PCR applications where absolute quantification commands premium positioning.
RT-PCR kits contain reverse transcriptase enzymes, Taq polymerase, sequence-specific primers, and fluorescent probe chemistries designed to amplify and detect RNA-derived cDNA targets with sensitivity thresholds reaching single-copy detection. The clinical diagnostics application segment anchors the largest revenue pool as infectious disease panels and oncology liquid biopsy assays expand reimbursement coverage. Fully automated technologies capture the fastest growth trajectory by minimizing operator error and standardizing throughput across hospital networks and centralized laboratories.
The FDA enforces Emergency Use Authorization pathways and quality system regulation compliance for in vitro diagnostic kits, while the EMA's In Vitro Diagnostic Regulation imposes stricter clinical evidence requirements for CE-marked products entering European markets. ISO 13485 certification and WHO prequalification standards shape procurement eligibility for public health programs across multiple geographies. Stakeholders must monitor evolving regulatory convergence between FDA and EMA post-market surveillance requirements to anticipate compliance cost structures and competitive entry barriers.
Market Dynamics
Multiplex RT-PCR panel architectures are compressing testing workflows from sequential single-target assays to simultaneous pathogen detection, forcing kit manufacturers to reconfigure reagent formulations and thermal cycling protocols around higher-order chemistry complexity.
Growth Catalysts
- Hospital-acquired infection surveillance mandates:The US Centers for Medicare & Medicaid Services ties reimbursement to active MRSA and C. difficile screening programs, institutionalizing molecular testing volumes in acute care networks.
- IVDR compliance deadlines:The EU's In Vitro Diagnostic Regulation imposes stricter clinical evidence requirements, accelerating kit standardization and consolidating procurement toward pre-qualified suppliers.
- Liquid biopsy assay expansion:Oncology minimal residual disease monitoring is migrating from tissue-based histology to blood-draw RNA analysis, opening new specimen streams for RT-PCR consumables.
Market Restraints
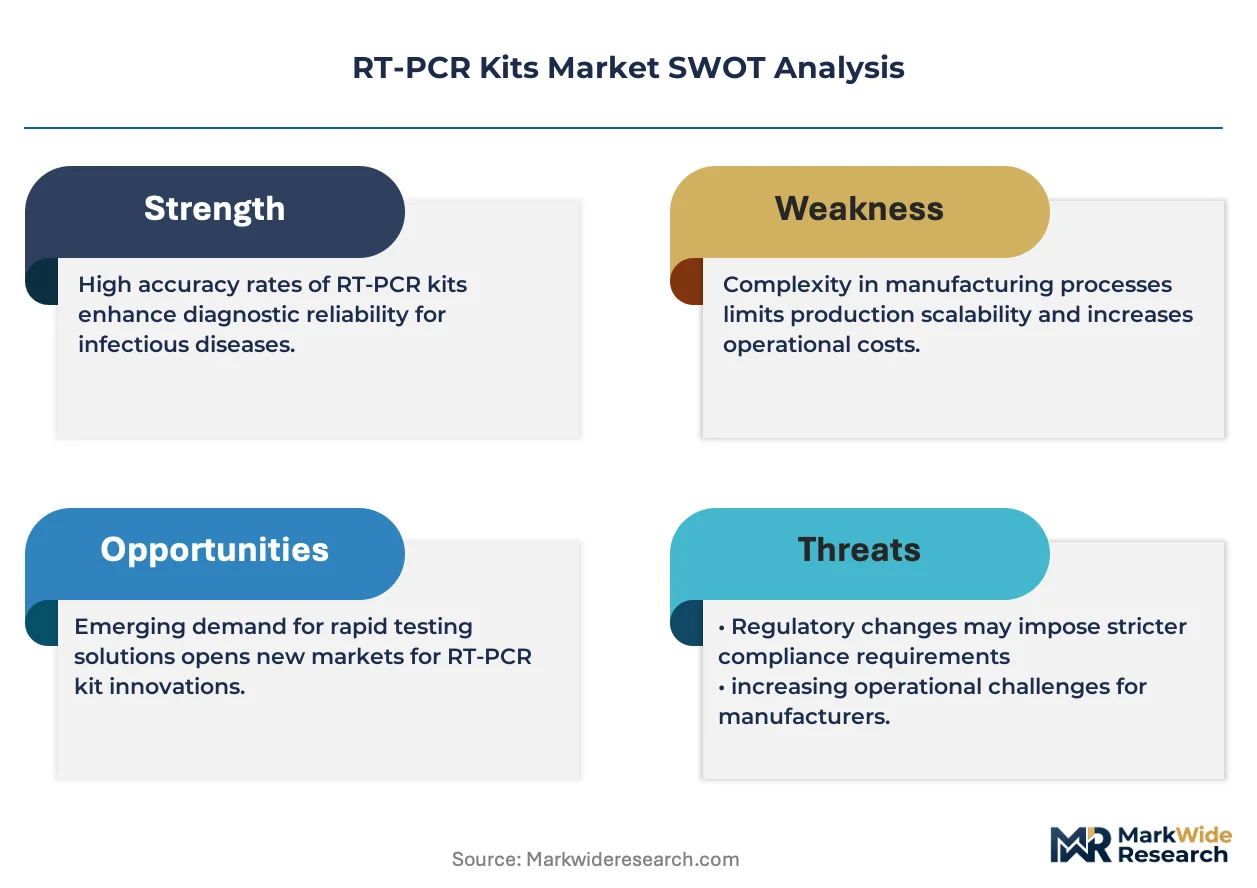
- Enzyme input cost volatility:Reverse transcriptase and high-fidelity Taq polymerase production concentrates in specialized fermentation facilities, exposing margins to bioprocess raw material price swings.
- Reference standard fragmentation:Lack of harmonized RNA quantification standards across WHO, ISO, and national metrology institutes complicates kit calibration and inter-laboratory result comparability.
- Isothermal amplification substitution:LAMP and RPA chemistries eliminate thermal cycling hardware requirements, pressuring RT-PCR positioning in point-of-care and resource-limited settings.
Strategic Opportunities
- Untapped veterinary diagnostics:Companion animal infectious disease panels and livestock pathogen surveillance represent nascent demand pools with limited multiplex assay penetration.
- Home collection-to-lab models:Direct-to-consumer respiratory panels and STI screening services are creating specimen logistics infrastructure that favors centralized high-throughput RT-PCR processing.
- Digital PCR convergence:Droplet digital PCR absolute quantification is merging with RT-PCR workflows for rare transcript detection, enabling premium pricing in oncology and transplant monitoring applications.
Industry Challenges
- Bioinformatics specialist scarcity:Multiplex panel interpretation demands computational biology expertise that outpaces clinical laboratory training pipeline output, creating assay deployment bottlenecks.
- ISO 13485 certification timelines:Quality management system audits and technical documentation reviews extend product launch schedules, compressing effective patent protection windows for novel chemistries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | RT-PCR Kits Market |
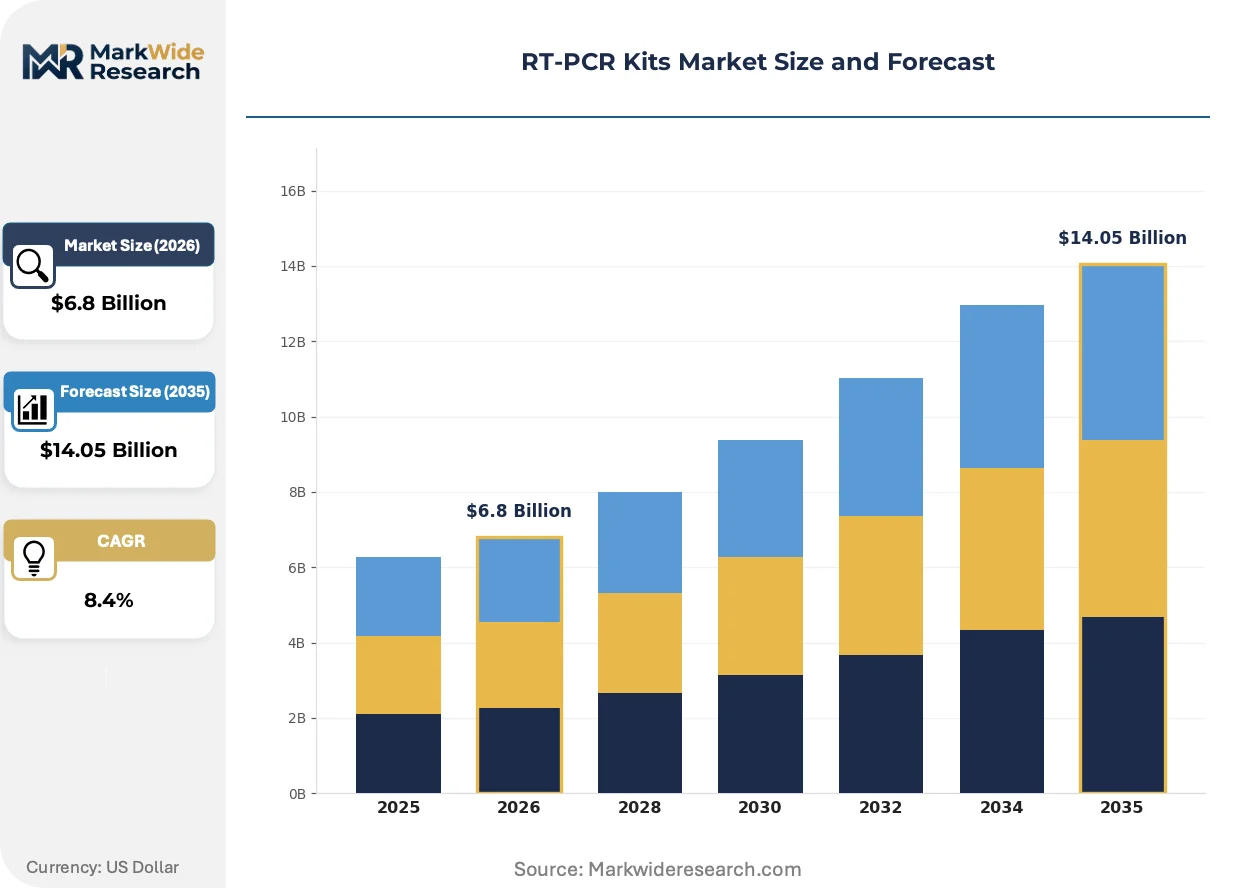
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
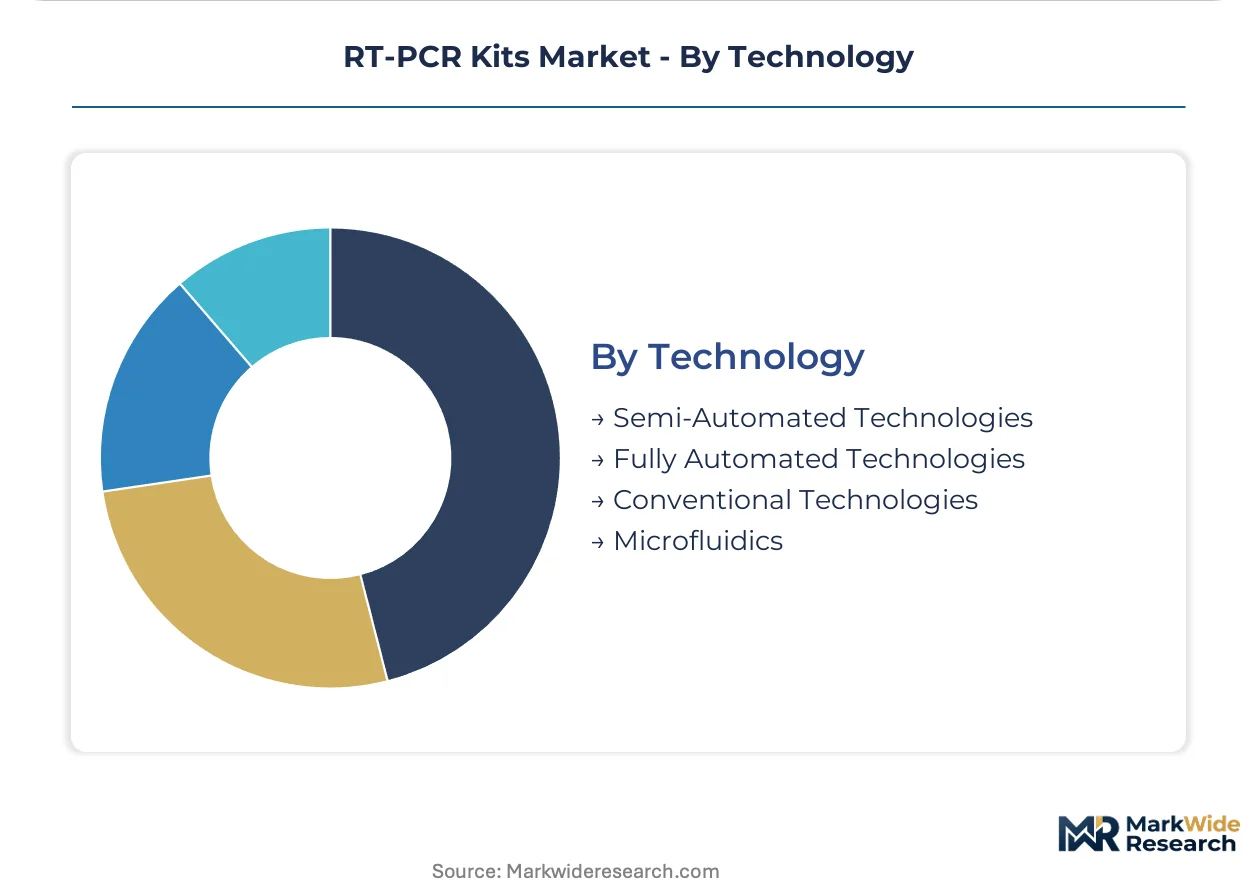
| Segmentation | Product Type: Standard Kits, Digital Kits, Multiplex Kits, Reverse Transcription Kits End User: Academic Research Institutes, Hospitals, Diagnostic Laboratories, Pharmaceutical Companies Application: Clinical Diagnostics, Research Applications, Veterinary Diagnostics, Environmental Testing Technology: Semi-Automated Technologies, Fully Automated Technologies, Conventional Technologies, Microfluidics |
| Companies Covered | Thermo Fisher Scientific, QIAGEN, Merck KGaA, Roche Diagnostics, Bio-Rad Laboratories, Takara Bio Inc., Abbott Laboratories, Promega Corporation, Agilent Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
RT-PCR Kits Market Evolving Landscape
Cloud-connected instrument platforms and AI-assisted assay design tools are compressing development cycles and enabling remote diagnostic network management across distributed laboratory systems.
One-step RT-qPCR master mixes with integrated hot-start polymerase and RNase inhibitor formulations are virtualizing traditional multi-tube workflow steps into single-reaction configurations. Reference laboratories in the United States and Germany are adopting these chemistries at accelerated pace to reduce pipetting error rates. This consolidation is virtualizing technician training requirements and enabling less-specialized personnel to execute complex amplification protocols.
The EU's In Vitro Diagnostic Regulation (IVDR) performance evaluation and post-market surveillance requirements entered full enforcement, mandating clinical evidence generation for Class C and D devices. Kit manufacturers must now maintain ongoing safety and performance documentation beyond initial CE marking. High-complexity molecular diagnostics face extended conformity assessment timelines, prompting some suppliers to deprioritize lower-volume EU market entry.
Centralized laboratory networks are consolidating procurement decisions through group purchasing organizations and integrated delivery system contracts. Independent hospital laboratories face exclusion from preferred vendor tiers as health systems standardize on single-source instrument-reagent ecosystems. This concentration is most visible in US metropolitan markets where academic medical centers anchor regional reference laboratory consolidation.
RT-PCR Kits Market Segmentation
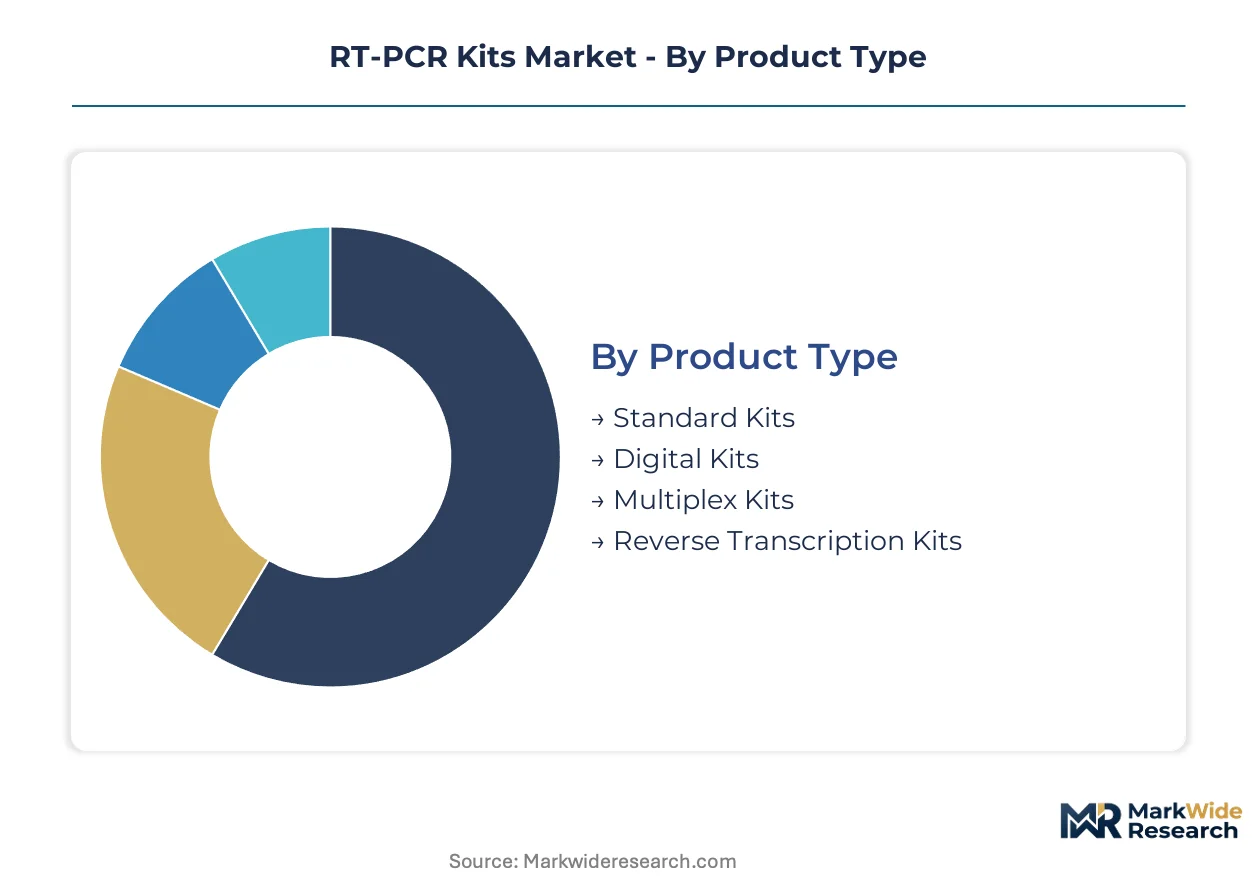
RT-PCR kit manufacturers configure product portfolios around four intersecting dimensions that determine pricing power and customer retention. Product architecture, end-user workflow requirements, application-specific sensitivity demands, and automation integration depth each create distinct competitive battlegrounds with different margin profiles and switching costs.
Product Type:
Mature reagent formats dominate installed base volumes while emerging multiplex and digital architectures capture premium positioning and new account growth.
- Standard Kits:Single-target amplification chemistries with pre-mixed reverse transcriptase and Taq polymerase formulations anchor high-throughput infectious disease screening contracts. Demand concentrates in United States hospital networks where CMS reimbursement mandates for MRSA and C. difficile surveillance sustain predictable reorder patterns.
- Multiplex Kits:Panel-based detection architectures amplify multiple RNA targets in single thermal cycling reactions, reducing per-sample reagent consumption and technician handling steps. Academic medical centers in Germany and diagnostic laboratory chains in the United States are migrating respiratory pathogen and STI screening workflows toward these configurations to compress turnaround times.
- Digital Kits:Droplet digital PCR absolute quantification chemistries command premium positioning in oncology minimal residual disease monitoring and transplant rejection surveillance.
- Reverse Transcription Kits:Stand-alone cDNA synthesis reagents serve research laboratories requiring customized primer design flexibility outside validated diagnostic workflows.
Standard kits retain volume leadership; multiplex configurations hold the steepest expansion curve as panel-based testing displaces sequential single-target assays.
End User:
Customer procurement sophistication spans from price-sensitive research grant funding to value-based hospital system contracting with stringent quality system requirements.
- Diagnostic Laboratories:High-throughput reference labs and hospital-affiliated molecular diagnostics units drive the majority of kit consumption through multi-year instrument-reagent rental agreements. United States-based laboratory chains leverage group purchasing organization contracts to standardize on single-vendor ecosystems, locking out smaller suppliers.
- Hospitals:Acute care networks with on-site molecular diagnostics capabilities prioritize fully automated platforms that minimize technician training requirements and reduce pre-analytical error rates. Infection control departments in German university hospitals and United States academic medical centers anchor this segment's specification influence.
- Academic Research Institutes:Grant-funded laboratories favor modular reagent configurations enabling protocol customization for novel transcript detection applications.
- Pharmaceutical Companies:Drug development and clinical trial service operations consume specialized kits for biomarker validation and companion diagnostic co-development programs.
Diagnostic laboratories command the largest revenue pool; hospital point-of-care expansion is gaining share fastest as decentralized testing networks mature.
Application:
Clinical validation requirements and reimbursement coverage depth create sharp segmentation between regulated diagnostic markets and exploratory research applications.
- Clinical Diagnostics:FDA-cleared and CE-IVD marked kits for infectious disease, oncology, and genetic disorder testing face stringent quality system regulation and post-market surveillance obligations. United States reference laboratories and German hospital networks anchor demand as precision medicine initiatives and infection surveillance mandates expand molecular testing menus.
- Research Applications:RUO-labeled reagents for gene expression profiling, viral load quantification, and transcriptomics studies operate outside clinical validation requirements with faster product update cycles. Academic institutions in the United States and research hospitals in Germany sustain this segment through federal and institutional funding streams.
- Veterinary Diagnostics:Companion animal infectious disease panels and livestock pathogen surveillance represent nascent demand with limited multiplex penetration and evolving regulatory frameworks.
- Environmental Testing:Water quality monitoring and food safety applications employ RT-PCR for RNA virus detection in regulatory compliance and outbreak investigation contexts.
Clinical diagnostics retains volume leadership; veterinary applications are climbing the fastest as companion animal healthcare spending professionalizes.
Technology:
Automation integration depth determines labor cost absorption and result standardization capabilities across distributed laboratory networks.
- Fully Automated Technologies:Sample-to-result platforms with integrated nucleic acid extraction, amplification, and detection eliminate manual pipetting steps and reduce operator error rates. United States health system consolidation and German laboratory network centralization favor these configurations for high-volume infectious disease and oncology testing.
- Semi-Automated Technologies:Modular systems combining standalone extraction instruments with thermal cyclers preserve workflow flexibility for lower-volume or multi-assay laboratories. Community hospital laboratories in the United States and mid-sized diagnostic providers in Germany balance throughput needs against capital constraint through these intermediate configurations.
- Conventional Technologies:Manual multi-tube workflows with discrete reverse transcription and amplification steps persist in research settings and resource-limited environments.
- Microfluidics:Chip-based reaction compartmentalization enables miniaturized reagent volumes and rapid thermal cycling for point-of-care and near-patient deployment scenarios.
Fully automated technologies command the largest revenue share; microfluidics is expanding most quickly as portable molecular diagnostics penetrate ambulatory and emergency care settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports RT-PCR reagent formulations to diagnostic laboratory networks across France and the Netherlands, establishing a north-south trade corridor that shapes procurement standards for molecular testing infrastructure in Western Europe.
United States
Hospital-acquired infection surveillance programs and precision medicine initiatives drive kit consumption. The FDA enforces Emergency Use Authorization pathways and quality system regulation compliance for in vitro diagnostic kits. Reference laboratory chains in the Boston-Cambridge cluster leverage group purchasing organization contracts to standardize on single-vendor instrument-reagent ecosystems.
Germany
Academic medical centers and university hospital networks anchor demand for multiplex panel configurations. The EMA's In Vitro Diagnostic Regulation imposes stricter clinical evidence requirements for CE-marked products entering European markets. The Munich-Heidelberg corridor concentrates diagnostic laboratory automation development and serves as a distribution hub for Central European markets.
China
Domestic infectious disease surveillance expansion and oncology liquid biopsy assay development fuel local kit production. The NMPA regulates in vitro diagnostic reagents through registration and manufacturing quality system requirements. The Yangtze River Delta region clusters contract research organizations and clinical testing facilities that consume high-throughput RT-PCR consumables.
Japan
Aging demographics and chronic disease monitoring programs sustain molecular diagnostics demand. The PMDA oversees pharmaceutical and medical device approval processes including nucleic acid amplification test kits. The Kanto region surrounding Tokyo concentrates hospital networks and reference laboratories that prioritize fully automated sample-to-result platforms.
India
Public health screening programs and veterinary diagnostics expansion create emerging demand pools. The CDSCO regulates medical devices and in vitro diagnostics under the Drugs and Cosmetics Act framework. The Maharashtra-Gujarat pharmaceutical manufacturing belt hosts contract manufacturing organizations producing enzyme formulations for regional kit assemblers.
RT-PCR Kits Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three discernible tiers. Integrated life science conglomerates with instrument-reagent lock-in capabilities occupy the top tier, while mid-scale reagent specialists and regional distributors fill intermediate positions. The market structure rewards backward integration into enzyme fermentation and forward integration into diagnostic service provision. Consolidation pressures concentrate procurement decisions through health system standardization and group purchasing organization centralization.
Among diversified life science conglomerates, Thermo Fisher Scientific and QIAGEN exemplify channel-controlling archetypes that anchor competitive positioning through workflow automation ecosystems. Bio-Rad Laboratories occupies a specialist position in absolute quantification applications. These three entities represent distinct strategic postures: the first through integrated instrument-platform dominance, the second through sample-to-insight workflow reduction, and the third through premium positioning in digital PCR convergence segments.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| QIAGEN |
| Merck KGaA |
| Roche Diagnostics |
| Bio-Rad Laboratories |
| Takara Bio Inc. |
| Abbott Laboratories |
| Promega Corporation |
| Agilent Technologies |
| Others |
Value Network & Pricing Analysis
The Rhine-Alpine freight corridor connecting Rotterdam to Milan transmits enzyme fermentation inputs and finished reagent formulations across Western European diagnostic networks, with logistics cost volatility amplifying margin compression for non-integrated suppliers while enabling tiered pricing power for manufacturers with captive bioprocess capacity.
Pricing Analysis
Current-generation one-step RT-qPCR master mixes command substantial premiums over prior-generation multi-tube workflows, while next-generation digital PCR chemistries occupy ultra-premium positioning. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared diagnostic kits from research-use-only reagents and private-label economy formulations. Pricing pressure stems from isothermal amplification substitution in point-of-care settings. Academic research institutes exhibit highest price sensitivity; reference laboratory chains with GPO contracts demonstrate lowest.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculus for enzyme fermentation inputs. Manufacturing concentrates in the United States, Germany, and China. Reverse transcriptase and high-fidelity Taq polymerase production draws from specialized fermentation facilities; fluorescent probe chemistries rely on oligonucleotide synthesis capacity. Single-source vulnerability persists for GMP-grade enzyme suppliers. Distribution runs through diagnostic laboratory networks and group purchasing organization channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized bioinformatics expertise for multiplex panel interpretation constitutes the critical capability gap constraining assay deployment velocity, with computational biology training pipeline output lagging clinical laboratory demand across major diagnostic markets.
For Market Incumbents: Build regulatory certification moats through accelerated IVDR conformity assessment investments and WHO prequalification pursuit. Thermo Fisher Scientific and QIAGEN should deepen backward integration into GMP enzyme fermentation to offset bioprocess raw material volatility. Consolidate procurement influence through expanded instrument-reagent rental agreements that lock hospital systems into single-vendor ecosystems. For New Entrants and Emerging Players: Pursue veterinary diagnostics white space where companion animal infectious disease panels remain underpenetrated by multiplex architectures. Target livestock pathogen surveillance in India and Brazil where regulatory frameworks are evolving and incumbent presence is limited. Deploy home collection-to-lab service partnerships as the primary go-to-market mechanism to bypass capital-intensive hospital sales cycles. For Investors and Strategic Acquirers: Sample-to-insight workflow automation specialists with integrated informatics capabilities represent the most attractive acquisition archetype for medium-term consolidation plays. Long-term viability hinges on regulatory navigation expertise rather than chemistry differentiation alone. Monitor FDA-EU regulatory convergence momentum as the critical inflection signal for compliance cost structure shifts.| Strategic Initiative | Industry Significance |
|---|---|
| IVDR Conformity Acceleration | EMA compliance timelines compress effective patent windows for novel chemistries. |
| Enzyme Fermentation Backward Integration | Captive bioprocess capacity insulates margins from raw material price swings. |
| Cloud-Connected Platform Launch | AI-assisted assay design tools compress development cycles for distributed networks. |
| Veterinary Panel Diversification | Companion animal healthcare spending professionalization opens nascent demand pools. |
| Digital PCR Convergence Investment | Absolute quantification capabilities enable premium pricing in oncology monitoring. |
Research Methodology
Cross-validation between primary interviews with diagnostic laboratory directors, GPO contracts managers, biomedical engineers, and regulatory affairs specialists and secondary sources including FDA 510(k) filings, EMA IVDR submissions, CMS reimbursement databases, and hospital procurement records anchors the qualitative findings. Bottom-up kit volume modeling triangulates against top-down market sizing from instrument installed base estimates.
Calibration against historical growth trajectories and instrument placement data shapes the analytical framework across the projection horizon. Segmentation dimensions include product architecture, end-user workflow requirements, application-specific sensitivity demands, and automation integration depth. CAGRs derive from trend extrapolation moderated by technology substitution risk and regulatory timeline uncertainty. Enzyme cost curves and reimbursement coverage expansion patterns constitute key forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in healthcare capital expenditure cycles or diagnostic testing reimbursement rates would shift the trajectory. Forecasts reflect documented assumptions regarding IVDR enforcement consistency and precision medicine initiative funding continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
North America Point of Care Diagnostics Market
Diagnostics
Pancreatic Cyst Diagnostics Market
Diagnostics
Global Urinalysis Market
Diagnostics
Brain Cancer Diagnostics Market
Diagnostics
North America Breast Cancer Screening Tests Market
Diagnostics
Asia Pacific in Vitro Diagnostics Market
Diagnostics
Viral Antigens Market
Diagnostics
Global Rheumatoid Arthritis Diagnostic Tests Market
Diagnostics
Prostate Cancer Diagnostics Market
Diagnostics
Helicobacter Pylori (H. Pylori) Diagnostics Market
Diagnostics
Mexico in-Vitro Diagnostics Market
Diagnostics
EMEA Meningitis Diagnostic Testing Market
Diagnostics
North America Thyroid Cancer Diagnostics Market
Diagnostics
In Vitro Diagnostics (IVD) Quality Control Market
Diagnostics
Diagnostic Testing of Stds Market
Diagnostics
Mycoplasma Diagnostics Market