
 Veterinary Diagnostics Market | 2026-2036
Veterinary Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Veterinary Diagnostics Market Intelligence
Veterinary reference laboratory networks is reshaping how diagnostics reach end users, consolidating testing volume into fewer high-throughput hubs. IDEXX Laboratories sustains dominant channel control through captive reference lab franchises and in-clinic analyzer placements. Zoetis Services LLC leverages its integrated pharmaceutical-diagnostics portfolio to lock in multi-year clinic contracts. Thermo Fisher Scientific anchors its position through applied bioscience platforms that span human and veterinary molecular testing.
Veterinary diagnostics encompasses analytical methods and instrumentation used to detect, monitor, and manage disease states in animal patients, employing technologies ranging from automated hematology counters with species-specific algorithms to real-time PCR systems detecting pathogen nucleic acid at femtogram sensitivity. These tools serve the primary commercial purpose of enabling evidence-based treatment decisions that reduce antimicrobial misuse and improve herd or individual animal outcomes. Immunoassays and molecular diagnostics command the deepest margin pools, reflecting reagent annuity models and the premium pricing power of rapid pathogen identification. Clinical chemistry and hematology analyzers represent the most mature revenue base, with replacement cycles driving predictable aftermarket demand.
FDA oversight of veterinary laboratory-developed tests, USDA accreditation requirements for interstate movement testing, and ISO 17025 standards for diagnostic laboratory quality together elevate compliance costs while creating barriers to informal competitors. The EU's IVDR framework and MDR are extending conformity assessment burdens to imported veterinary devices sold in European markets. Stakeholders must monitor how AI-enabled image analysis tools navigate emerging software-as-medical-device classifications across jurisdictions.
Market Dynamics
Reference laboratory consolidation is compressing testing economics, concentrating volume into high-throughput hubs that exploit scale efficiencies in reagent procurement and automated workflow management. This structural concentration privileges operators with captive instrument placements and multi-year service contracts, marginalizing independent clinics that lack capital for in-house molecular platforms.
Growth Catalysts
- USDA interstate movement mandates:Federal accreditation requirements for livestock health certificates sustain mandatory testing volumes across cattle, equine, and swine supply chains, insulating diagnostic demand from cyclical veterinary spending.
- Companion animal insurance penetration:Pet insurance carriers in the United States now reimburse advanced imaging and molecular panels, removing price sensitivity that previously constrained specialist referrals.
- Real-time PCR miniaturization:Benchtop thermal cyclers with femtogram sensitivity are migrating from reference laboratories into general practice settings, expanding addressable test menus.
Market Restraints
- Reagent supply concentration:Proprietary chemistries for species-specific immunoassays concentrate with three global suppliers, exposing buyers to sole-source risk and limited price negotiation leverage.
- FDA LDT oversight expansion:Draft guidance on veterinary laboratory-developed tests threatens compliance timelines and validation costs for clinic-based molecular assays.
- Pathogen substitution in food animal panels:Shrinking federal brucellosis and tuberculosis eradication programs reduce mandatory screening volumes in cattle operations.
Strategic Opportunities
- AI-enabled cytology in general practice:Cloud-based image classification algorithms for blood smear and fine-needle aspirate interpretation address specialist pathologist scarcity in suburban and rural markets.
- Point-of-care antimicrobial susceptibility testing:Rapid phenotypic resistance profiling aligns with FDA veterinary feed directive compliance pressures, creating substitution opportunity against send-out cultures.
- Subscription reagent models:Per-test pricing with instrument placement waivers lower capital barriers for independent clinics, capturing volume from reference laboratory networks.
Industry Challenges
- Veterinary clinical pathologist recruitment:Residency program output fails to match demand for board-certified specialists, extending turnaround times for complex case consultation.
- Multi-instrument integration complexity:Hematology, chemistry, and immunoassay platforms from different manufacturers resist seamless data interoperability, fragmenting patient record workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Veterinary Diagnostics Market |
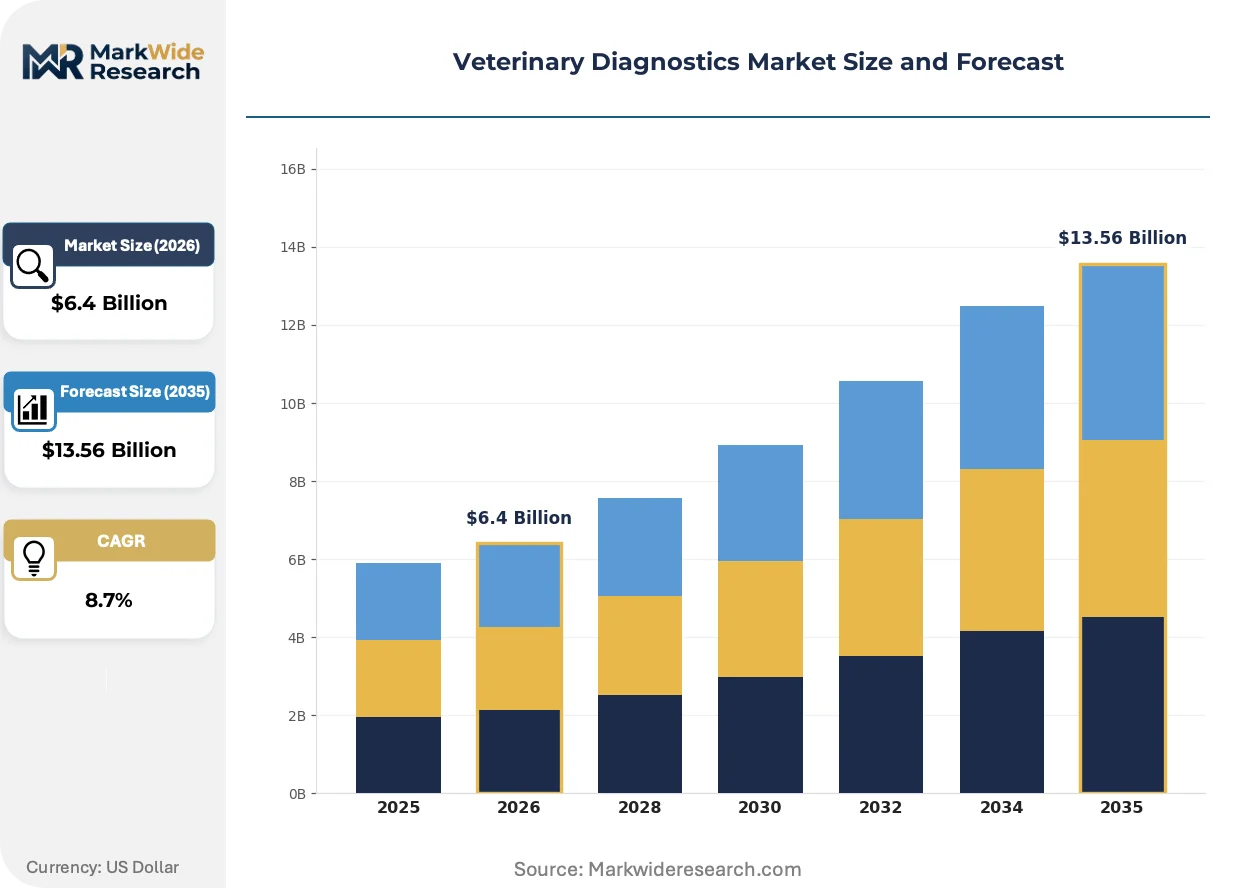
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $13.56 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Imaging Systems, Immunoassays, Molecular Diagnostics, Hematology Analyzers, Clinical Chemistry Technology: Polymerase Chain Reaction, ELISA, Flow Cytometry, Mass Spectrometry, Microarray Analysis Application: Disease Detection, Fertility Evaluation, Parasite Identification, Nutritional Assessment, Genetic Screening End User: Veterinary Hospitals, Diagnostic Laboratories, Animal Research Centers, Zoos, Wildlife Reserves |
| Companies Covered | IDEXX Laboratories, Inc., Zoetis Services LLC, Antech Diagnostics, Inc., Thermo Fisher Scientific, Inc., bioMérieux SA, Heska Corporation, Neogen Corporation, Virbac, Agrolabo S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Veterinary Diagnostics Market Strategic Shifts & Innovations
Digital pathology infrastructure is virtualizing diagnostic expertise, collapsing geographic distance between specimen origin and interpretation capacity. Three convergent developments are restructuring how veterinary diagnostics are produced, regulated, and consumed.
Telepathology platforms with whole-slide imaging are virtualizing specialist access for remote and general practice settings. Companion animal clinics in the United States and Western Europe deploy these systems to submit cytology and histology cases for remote board-certified review. This architecture compresses the specialist-to-patient ratio constraint that previously limited advanced diagnostic penetration outside academic centers.
The EU's In Vitro Diagnostic Regulation extends conformity assessment burdens to imported veterinary devices, elevating documentation requirements for molecular test kits and automated analyzers. Manufacturers targeting European markets must now engage notified bodies for clinical evidence review, extending product launch timelines. Smaller assay developers without dedicated regulatory affairs functions are withdrawing from EU distribution, concentrating supply among established platform holders.
Consolidated buying groups now negotiate enterprise pricing for multi-site veterinary hospital networks, displacing individual clinic procurement autonomy. These aggregators demand standardized instrument platforms across their footprints, privileging suppliers with comprehensive chemistry, hematology, and immunoassay menus. The United States exhibits the most advanced concentration, where corporate-owned practice chains command national purchasing agreements that independent operators cannot replicate.
Veterinary Diagnostics Market Segmentation
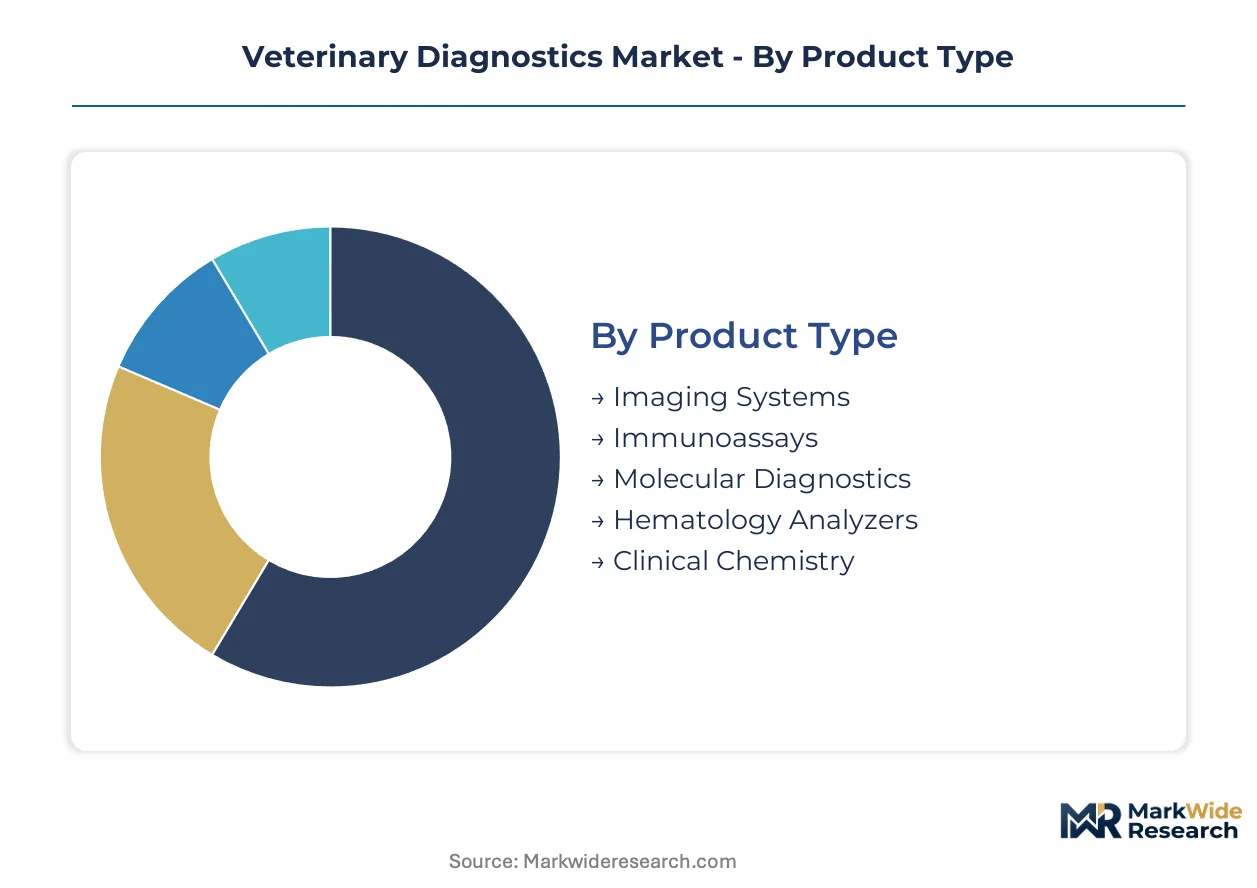
Veterinary diagnostics segmentation reveals how capital intensity, reagent consumption patterns, and regulatory pathways create divergent margin profiles across product categories. Understanding these structural differences enables targeted positioning against reference laboratory consolidation and point-of-care decentralization trends.
Product Type:
Cycle times vary dramatically across modalities, with consumable reagents turning over in weeks while capital equipment extends across multi-year depreciation schedules.
- Imaging Systems:Radiography, ultrasound, and MRI platforms with species-specific positioning algorithms command premium placement in specialty referral hospitals. Demand concentrates in the United States where pet insurance reimbursement for advanced imaging has removed price barriers that previously limited general practice adoption.
- Immunoassays:Species-specific antibody detection kits employing chemiluminescent or fluorescent reporters deliver rapid pathogen and hormone quantification. Companion animal clinics in North America drive volume expansion as wellness screening panels become standard in preventive care protocols.
- Molecular Diagnostics:Real-time PCR and nucleic acid amplification platforms detect pathogen DNA at trace concentrations.
- Hematology Analyzers:Automated cell counters with veterinary species algorithms process high-throughput complete blood counts.
- Clinical Chemistry:Wet chemistry and dry-slide analyzers measure metabolic panels and organ function markers.
Clinical chemistry dominates installed base. Molecular diagnostics is where expansion concentrates.
Technology:
Cost tiers separate reference laboratory workflows from point-of-care deployment, with miniaturization driving platform migration toward general practice settings.
- Polymerase Chain Reaction:Thermal cycling amplification of pathogen nucleic acid achieves femtogram sensitivity for infectious disease confirmation. Benchtop systems are displacing send-out testing in United States companion animal practices as instrument costs decline and menu breadth expands.
- ELISA:Enzyme-linked immunosorbent assays provide cost-effective antibody and antigen detection across high-volume screening applications. USDA interstate movement mandates for livestock health certification sustain mandatory testing volumes in cattle, equine, and swine supply chains.
- Flow Cytometry:Laser-based cell characterization enables immunophenotyping and leukemia diagnostics.
- Mass Spectrometry:High-resolution molecular identification supports toxicology and metabolomics applications.
- Microarray Analysis:Parallel genetic screening identifies heritable disease markers and pathogen resistance profiles.
ELISA anchors routine screening economics. Polymerase chain reaction is climbing the fastest as sensitivity requirements intensify.
Application:
Volume concentration aligns with regulatory mandates and insurance reimbursement patterns, creating divergent growth trajectories across testing categories.
- Disease Detection:Infectious agent identification and chronic disease monitoring through serology, molecular, and culture-based methods. Veterinary hospitals in the United States prioritize rapid turnaround capabilities to support same-day treatment decisions and reduce antimicrobial misuse.
- Genetic Screening:DNA-based testing for heritable conditions and breed-specific disease predispositions. Premium breeding operations and pet owners seeking predictive health insights are expanding addressable demand beyond traditional diagnostic indications.
- Fertility Evaluation:Hormone profiling and semen analysis support reproductive management.
- Parasite Identification:Fecal examination and vector-borne pathogen detection guide deworming protocols.
- Nutritional Assessment:Metabolic panel interpretation and deficiency screening inform dietary interventions.
Disease detection commands current procedure volume. Genetic screening is gaining share fastest as consumer willingness-to-pay for predictive information expands.
End User:
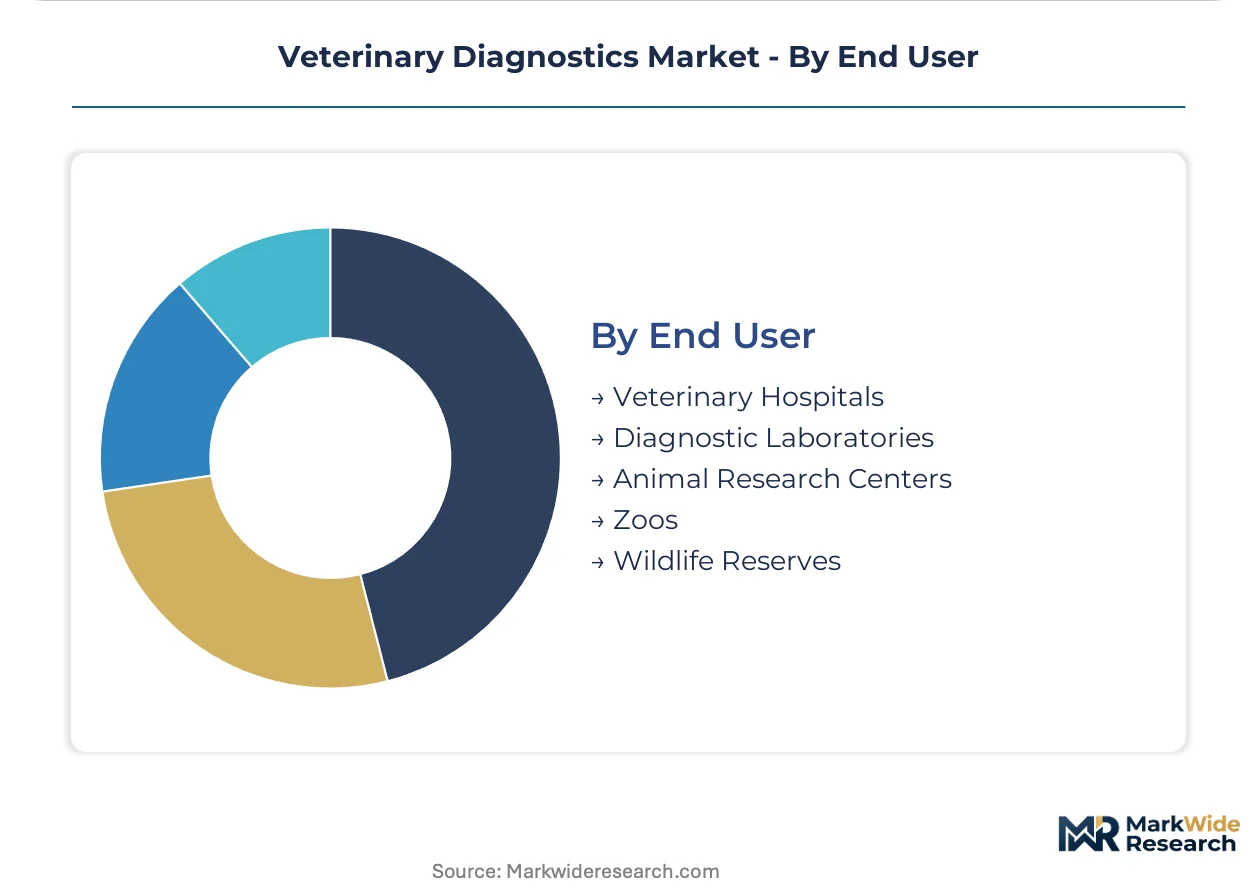
Customer type determines procurement autonomy, with consolidated buying groups displacing individual clinic decision-making across multi-site networks.
- Veterinary Hospitals:Primary and specialty care facilities with in-house laboratory capabilities or reference laboratory partnerships. Corporate-owned practice chains in the United States negotiate enterprise pricing that independent operators cannot replicate, standardizing instrument platforms across national footprints.
- Diagnostic Laboratories:Centralized high-throughput testing hubs with comprehensive menu breadth and board-certified pathologist oversight. Reference laboratory consolidation is compressing testing economics and marginalizing independent clinics lacking capital for molecular platforms.
- Animal Research Centers:Academic and commercial facilities requiring GLP-compliant pathology support.
- Zoos:Exotic species veterinary programs with specialized reference laboratory relationships.
- Wildlife Reserves:Conservation medicine operations conducting population health surveillance.
Diagnostic laboratories concentrate testing volume. Veterinary hospitals are where point-of-care decentralization is displacing reference send-outs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's veterinary cold-chain logistics infrastructure underwrites Europe's distribution dominance for temperature-sensitive reagents and diagnostic specimens. This maritime connectivity shapes how regional markets access molecular testing platforms and reference laboratory networks.
United States
Pet insurance carriers now reimburse advanced imaging and molecular panels, removing price sensitivity that previously constrained specialist referrals. The FDA's expanded oversight of laboratory-developed tests tightens quality benchmarks for clinic-based molecular assays. Corporate-owned practice chains in Texas and California negotiate enterprise pricing agreements that independent operators cannot replicate.
Germany
The EU's In Vitro Diagnostic Regulation extends conformity assessment burdens to imported veterinary devices, elevating documentation requirements for molecular test kits. EMA quality standards for veterinary medicinal products intersect with diagnostic device classifications. Bavaria's Munich-Stuttgart corridor hosts dense clusters of specialty veterinary hospitals deploying telepathology platforms for remote cytology interpretation.
China
NMPA registration pathways for imported veterinary diagnostic instruments are compressing product launch timelines for multinational suppliers. The country's dual carbon goals accelerate energy-efficiency mandates for high-throughput laboratory equipment. Shanghai's Yangtze River Delta concentration of contract research organizations drives demand for GLP-compliant pathology support in animal research applications.
United Kingdom
Post-Brexit divergence from EU IVDR frameworks creates parallel compliance tracks for veterinary device manufacturers serving British markets. The Veterinary Medicines Directorate maintains distinct accreditation requirements for diagnostic laboratories supporting livestock export certification. London's referral hospital network concentrates specialist pathologist capacity for complex case consultation.
Veterinary Diagnostics Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream supplying reagents and consumables to captive instrument placements. The market structure concentrates around three global suppliers controlling proprietary chemistries for species-specific immunoassays. Strategic archetypes include integrated pharmaceutical-diagnostics conglomerates, captive reference laboratory networks, and applied bioscience platform holders. Dominant competitive moves involve multi-year service contract lock-ins and subscription reagent models that lower capital barriers for independent clinics.
Within the integrated portfolio tier, IDEXX Laboratories and Zoetis Services LLC exemplify operators leveraging captive reference lab franchises and pharmaceutical-diagnostics bundling to secure clinic relationships. Thermo Fisher Scientific occupies a position spanning human and veterinary molecular testing through applied bioscience platforms. These three Delaware-incorporated and Massachusetts-based entities represent how scale-driven reagent annuity models and multi-site instrument standardization displace fragmented independent competitors.
| Leading Market Players |
|---|
| IDEXX Laboratories, Inc. |
| Zoetis Services LLC |
| Antech Diagnostics, Inc. |
| Thermo Fisher Scientific, Inc. |
| bioMérieux SA |
| Heska Corporation |
| Neogen Corporation |
| Virbac |
| Agrolabo S.p.A. |
| Others |
Cost & Logistics Intelligence
The Port of Rotterdam's veterinary cold-chain logistics infrastructure shapes cost dynamics across temperature-sensitive reagent flows, concentrating supply power among three global immunoassay chemistry suppliers while forcing downstream price differentiation between corporate hospital chains and independent clinics.
Pricing Analysis
Volume-discount tiering separates corporate-owned practice chains from independent operators, with enterprise procurement agreements in the United States commanding 15-30% reagent cost advantages over single-site clinics. Three-tier pricing structure across premium, standard, and economy levels aligns with ISO 17025 certification status and after-sales service bundling. Pricing pressure stems from subscription reagent models that waive instrument placement fees, compressing margins on capital equipment. Independent clinics exhibit highest price sensitivity due to limited capital access for in-house molecular platforms.
Supply Chain Analysis
Export-control restrictions on thermal cycler components and nucleic acid amplification chemistries limit flows from the United States and Germany to Chinese and Indian veterinary device assemblers. Manufacturing concentrates in the United States, Germany, and China, with proprietary species-specific antibody production anchored in Delaware and Massachusetts facilities. Supply chains draw from rare-earth magnet suppliers for hematology analyzer motors, photopolymer reagents for immunoassay detection, and temperature-stable enzymes for PCR mastermixes. Single-source vulnerability concentrates in chemiluminescent substrate supply. Distribution runs through captive reference laboratory networks and direct instrument placements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Veterinary diagnostics represents a high-growth disruption as real-time PCR miniaturization collapses testing economics from reference laboratories into general practice settings, accelerated by FDA laboratory-developed test oversight that privileges validated platform holders.
For Market Incumbents: Harden captive instrument placements through multi-year service contracts that lock in reagent annuity streams. Deepen backward integration into species-specific antibody production to reduce sole-source exposure from global chemistry suppliers. Accelerate AI-enabled cytology validation to preempt specialist pathologist scarcity from eroding turnaround-time advantages.
For New Entrants and Emerging Players: Build out point-of-care antimicrobial susceptibility testing capabilities targeting FDA veterinary feed directive compliance pressures in United States livestock operations. White-space opportunity concentrates in suburban companion animal clinics lacking molecular platforms. Go-to-market angle should emphasize subscription reagent pricing with zero-capital instrument placement to displace reference laboratory send-outs.
For Investors and Strategic Acquirers: Carve-out targets emerge from pharmaceutical conglomerates seeking to divest non-core diagnostic divisions. Long-term viability favors operators with integrated pharmaceutical-diagnostics portfolios and validated AI pathology platforms. Signal to watch is corporate practice chain consolidation velocity in Texas and California, which dictates enterprise pricing leverage and instrument standardization mandates.
| Strategic Initiative | Industry Significance |
|---|---|
| Reference Laboratory Network Expansion | IDEXX Laboratories consolidates testing volume into high-throughput hubs with board-certified pathologist oversight. |
| AI-Enabled Cytology Platform Launch | Cloud-based image classification addresses specialist scarcity in suburban United States markets. |
| Subscription Reagent Model Rollout | Per-test pricing with instrument waivers lowers capital barriers for independent clinic acquisition. |
| EU IVDR Conformity Assessment Investment | Notified body engagement extends product launch timelines but secures European market access. |
| Multi-Site Hospital Chain Partnership | Corporate-owned practice networks in California negotiate enterprise pricing unmatchable by independents. |
Research Approach
Initial hypotheses were tested against primary input from veterinary reference laboratory directors, companion animal clinic owners, pharmaceutical diagnostics portfolio managers, and regulatory affairs specialists, and refined through secondary validation against FDA guidance documents, USDA accreditation databases, EU IVDR notified body registers, and ISO 17025 laboratory certification records. Bottom-up demand modeling triangulated with top-down market sizing across product type, technology platform, application category, and end-user segments.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning immunoassay versus molecular modality, point-of-care versus reference laboratory deployment, and companion animal versus livestock application. CAGRs were derived from instrument placement trajectories, reagent consumption curves, and insurance reimbursement expansion patterns. Industry-specific inputs included pet insurance penetration rates by United States state and FDA laboratory-developed test guidance implementation timelines.
The forecast holds incumbent behavior within observed patterns; aggressive moves by integrated pharmaceutical-diagnostics conglomerates or AI-native diagnostic entrants would shift outcomes beyond modeled ranges. Material shifts in FDA enforcement posture on veterinary laboratory-developed tests or pet insurance reimbursement policy changes would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Vibrio Diagnostics Market
Diagnostics
Veterinary Chemistry Analyzers Market
Diagnostics
GCC in-Vitro Diagnostics Market
Diagnostics
Infectious Respiratory Disease Diagnostics Market
Diagnostics
Gastrointestinal Diagnostics Market
Diagnostics
Rapid Diagnostics Market
Diagnostics
Global Artificial Intelligence (AI) in Diagnostics Market
Diagnostics
Europe Womens Health Diagnostics Market
Diagnostics
Respiratory Pathogen Testing Kits Market
Diagnostics
South Africa in-Vitro Diagnostics Market
Diagnostics
Brain Cancer Diagnostics Market
Diagnostics
In-Vitro Diagnostics (IVD) Instruments Market
Diagnostics
Global Cervical Cancer Diagnostics Market
Diagnostics
Argentina in Vitro Diagnostics Market
Diagnostics
Epigenetics Diagnostics Market
Diagnostics
Europe Breast Cancer Screening Tests Market