
 Vascular Ulcer Treatment Market | 2026-2036
Vascular Ulcer Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Vascular Ulcer Treatment Market Analytics
Modular dressing kits that combine debridement tools, antimicrobial layers, and moisture-retentive foams in single configurations is consolidating buyer preference across institutional procurement channels. Smith & Nephew plc leverages its integrated wound management portfolio to sustain high-margin recurring revenue from advanced dressing replacements. Mölnlycke Health Care anchors European hospital supply contracts through specialized silicone adhesive technologies that reduce skin trauma during dressing changes. ConvaTec Group plc competes on ostomy and wound care convergence, extending its clinical sales force into outpatient settings.
Vascular ulcer treatment encompasses medical interventions targeting chronic wounds arising from impaired blood circulation, typically involving compression therapy systems, bioactive dressings containing collagen or silver compounds, and negative pressure wound therapy devices designed to maintain moist healing environments and stimulate granulation tissue formation. Venous ulcers command the largest addressable population among application segments, while advanced technologies including skin substitutes and growth factor delivery systems represent the fastest-expanding margin pool as payers gradually expand coverage for biologic interventions. Dressings retain volume leadership across product types due to standardized reimbursement codes, though devices segment benefits from homecare migration trends that favor portable negative pressure units.
The FDA regulates advanced wound care products through device and biologic pathways, while the EMA's Medical Device Regulation imposes stricter clinical evidence requirements on antimicrobial claims that delay market entry for novel dressings. CMS reimbursement policies directly shape prescribing behavior by determining which compression systems and bioactive dressings qualify for outpatient payment. Stakeholders must monitor evolving health technology assessment criteria as England's NICE and Germany's IQWiG increasingly demand cost-effectiveness evidence for premium wound care technologies.
Market Dynamics
Medicare reimbursement policies in the United States are compressing site-of-care economics, forcing wound care delivery toward outpatient protocols that favor portable devices over hospital-based systems and reshaping procurement patterns across integrated delivery networks.
Growth Catalysts
- CMS Outpatient Payment Expansion:Medicare's reimbursement codes for advanced bioactive dressings and portable negative pressure devices accelerate adoption in ambulatory surgical centers across the United States.
- Silicone Adhesive Technology:Specialized silicone-based dressing interfaces reduce skin trauma during changes, cutting healing time for venous ulcer patients in European hospital systems.
- Homecare Migration:Post-acute care networks are deploying portable negative pressure wound therapy units to reduce readmission penalties and shift care from inpatient to residential settings.
Market Restraints
- EMA MDR Clinical Evidence Burden:The European Medical Device Regulation's antimicrobial claim requirements delay market entry for novel dressings by demanding extensive clinical trials.
- Silver Compound Supply Concentration:Antimicrobial dressing manufacturers face input cost volatility from concentrated silver sourcing in Latin American mining operations.
- Biologic Reimbursement Gaps:Skin substitutes and growth factor delivery systems encounter restricted payer coverage despite clinical efficacy, limiting addressable patient populations.
Strategic Opportunities
- Germany's IQWiG Cost-Effectiveness Pathway:Premium wound care technologies gaining favorable health technology assessment ratings unlock statutory insurance reimbursement.
- Ostomy-Wound Care Convergence:Integrated stoma and wound management platforms capture cross-selling opportunities in outpatient clinic networks.
- Telemedicine-Enabled Remote Monitoring:Digital wound assessment tools paired with smart dressings create subscription revenue models for home health agencies.
Industry Challenges
- Specialized Wound Care Clinician Shortage:Certified wound ostomy continence nurses remain underrepresented in rural health systems, constraining protocol adoption.
- Legacy Electronic Health Record Integration:Wound imaging and measurement software faces interoperability barriers with dominant hospital information systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vascular Ulcer Treatment Market |
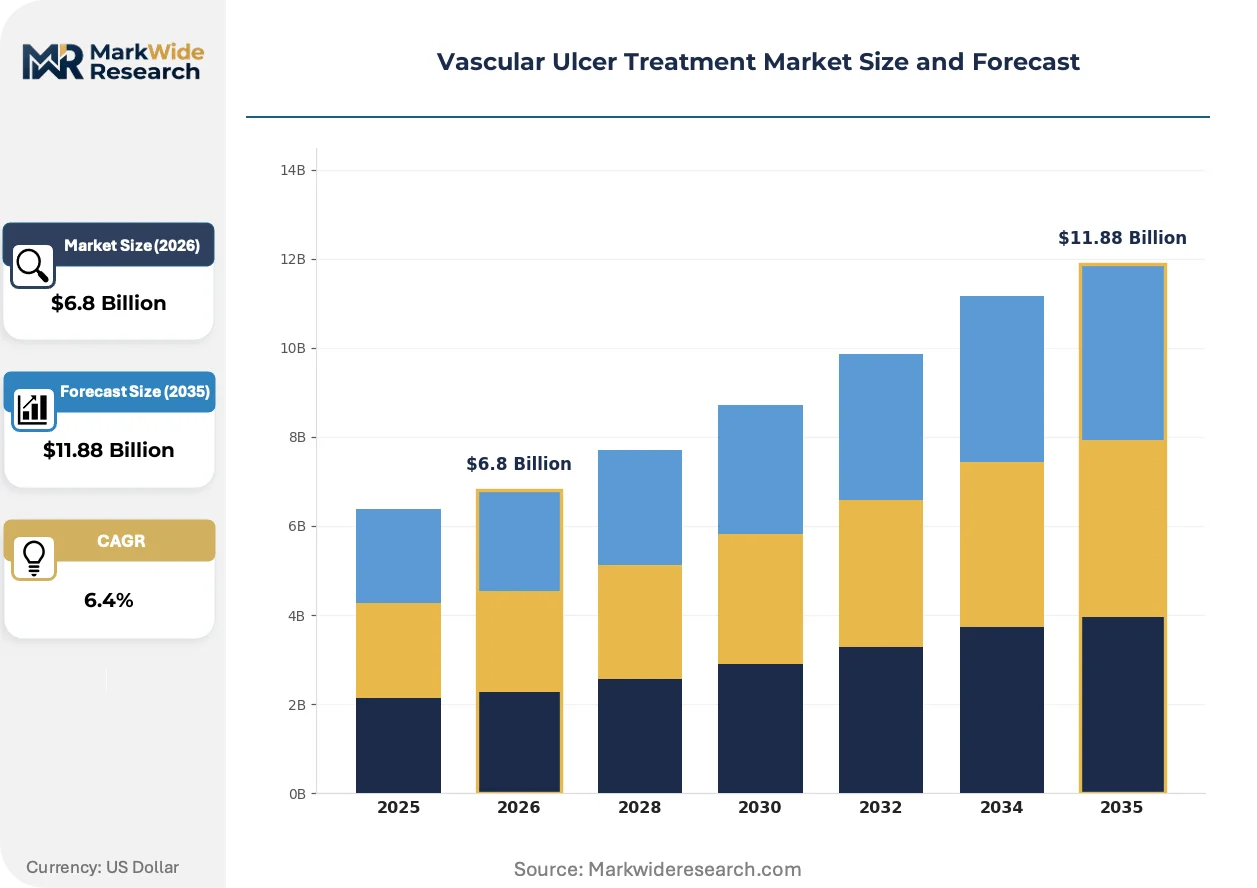
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dressings, Topical Agents, Devices, Advanced Technologies Application: Diabetic Ulcers, Venous Ulcers, Pressure Ulcers, Mixed Ulcers End User: Hospitals, Homecare, Ambulatory Surgical Centers, Wound Care Clinics Distribution Channel: Retail Pharmacies, E-commerce, Wholesale Distributors, Direct Sales |
| Companies Covered | Smith & Nephew plc, 3M Health Care, Mölnlycke Health Care, ConvaTec Group plc, Coloplast A/S, B. Braun Melsungen AG, Medline Industries LP, Integra LifeSciences Corporation, Urgo Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vascular Ulcer Treatment Market Evolving Landscape
Advanced dressing architectures are converging multiple therapeutic functions into unified configurations, while regulatory bodies on both sides of the Atlantic tighten evidentiary standards for antimicrobial claims. Buyers are consolidating vendor relationships around platforms that span debridement through closure.
Negative pressure wound therapy hardware is modularizing into compact, battery-powered units that integrate continuous pressure monitoring with automated exudate measurement. Home health agencies are adopting these systems to reduce nursing visit frequency. This convergence of therapeutic and diagnostic functions is compressing the traditional separation between device and dressing categories.
The FDA's ongoing medical device classification updates for wound healing products are narrowing the pathway for novel antimicrobial dressings by demanding clinical trial endpoints that measure infection reduction rather than proxy metrics. Manufacturers are responding by prioritizing submissions for mechanical debridement tools over silver-impregnated variants. United States-based wound care portfolios are tilting toward devices with clearer predicate pathways.
Hospital procurement committees are unbundling after-sales clinical support from product contracts, forcing manufacturers to compete on material cost while selling training and protocol implementation separately. Integrated delivery networks in the United States are driving this shift through centralized category management offices. Vendor consolidation favors suppliers with dedicated clinical education infrastructure.
Vascular Ulcer Treatment Market Segmentation
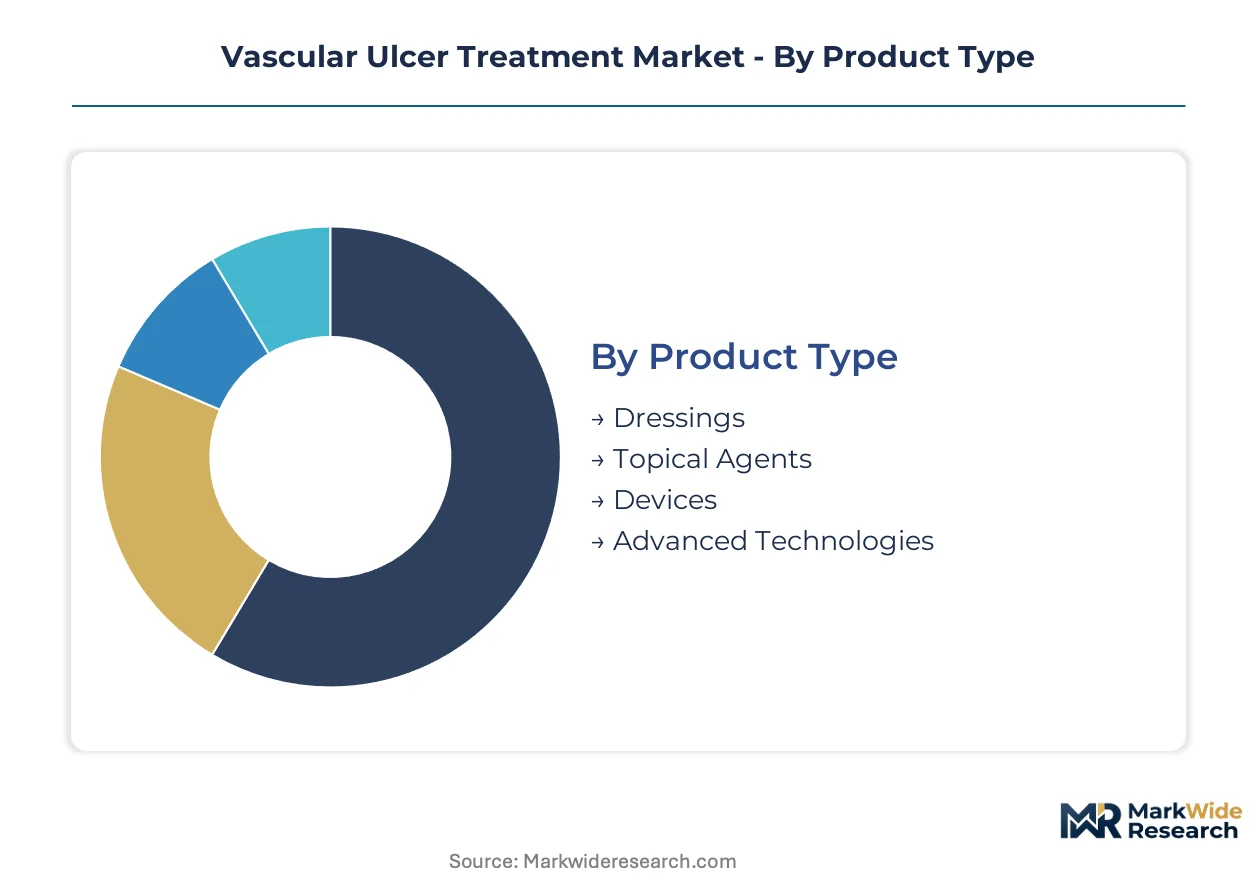
Segmentation in vascular ulcer treatment reflects divergent clinical workflows across acute and post-acute settings. Procurement patterns split between high-volume commodity dressings and capital-intensive device platforms. Reimbursement coding complexity drives vendor specialization by care site.
Product Type:
Material science and regulatory pathway complexity define competitive positioning across product categories.
- Dressings:Moisture-retentive foams, hydrocolloids, and antimicrobial silver-impregnated variants constitute the procurement volume base. Hospital formularies in the United States prioritize standardized reimbursement codes that favor established dressing architectures over novel substrates.
- Devices:Negative pressure wound therapy units and compression pump systems command capital expenditure budgets. Home health agencies in Germany deploy portable battery-powered NPWT units to reduce nursing visit frequency and statutory insurance claim costs.
- Topical Agents:Enzymatic debriders and antimicrobial ointments occupy intermediate price tiers between commodity dressings and capital devices.
- Advanced Technologies:Skin substitutes and growth factor delivery systems face restricted payer coverage despite clinical efficacy demonstrations.
Dressings lead on scale; advanced technologies lead on momentum.
Application:
Underlying etiology determines treatment protocol complexity and reimbursement intensity.
- Venous Ulcers:Chronic wounds arising from venous insufficiency command the largest addressable patient population. Compression therapy protocols in England's NHS community nursing services drive recurrent dressing consumption and device rental revenue.
- Diabetic Ulcers:Neuropathic foot lesions require specialized offloading and infection management. Medicare Advantage plans in the United States increasingly mandate protocol compliance before authorizing advanced biologic interventions.
- Pressure Ulcers:Facility-acquired wounds trigger penalty frameworks that accelerate investment in preventive monitoring systems.
- Mixed Ulcers:Complex presentations with multiple etiologies consume disproportionate specialist clinician time and diagnostic imaging resources.
Venous ulcers anchor volume; diabetic ulcers are expanding most quickly as population prevalence rises.
End User:
Site-of-care economics reshape vendor go-to-market structures and product form factors.
- Hospitals:Integrated delivery networks in the United States centralize procurement through category management offices that unbundle clinical support from material contracts. Wound care centers within hospital systems favor modular dressing kits that consolidate vendor relationships.
- Homecare:Post-acute networks deploy portable NPWT and telemedicine-enabled monitoring to reduce readmission penalties. German statutory insurance reimbursement for home-based compression therapy accelerates device penetration.
- Ambulatory Surgical Centers:CMS outpatient payment expansion for advanced bioactive dressings shifts procedural volume from inpatient settings.
- Wound Care Clinics:Specialized outpatient facilities concentrate certified wound ostomy continence nursing expertise that drives protocol adherence and premium product adoption.
Hospitals retain the largest absolute spend; homecare is gaining share fastest as site-of-care migration accelerates.
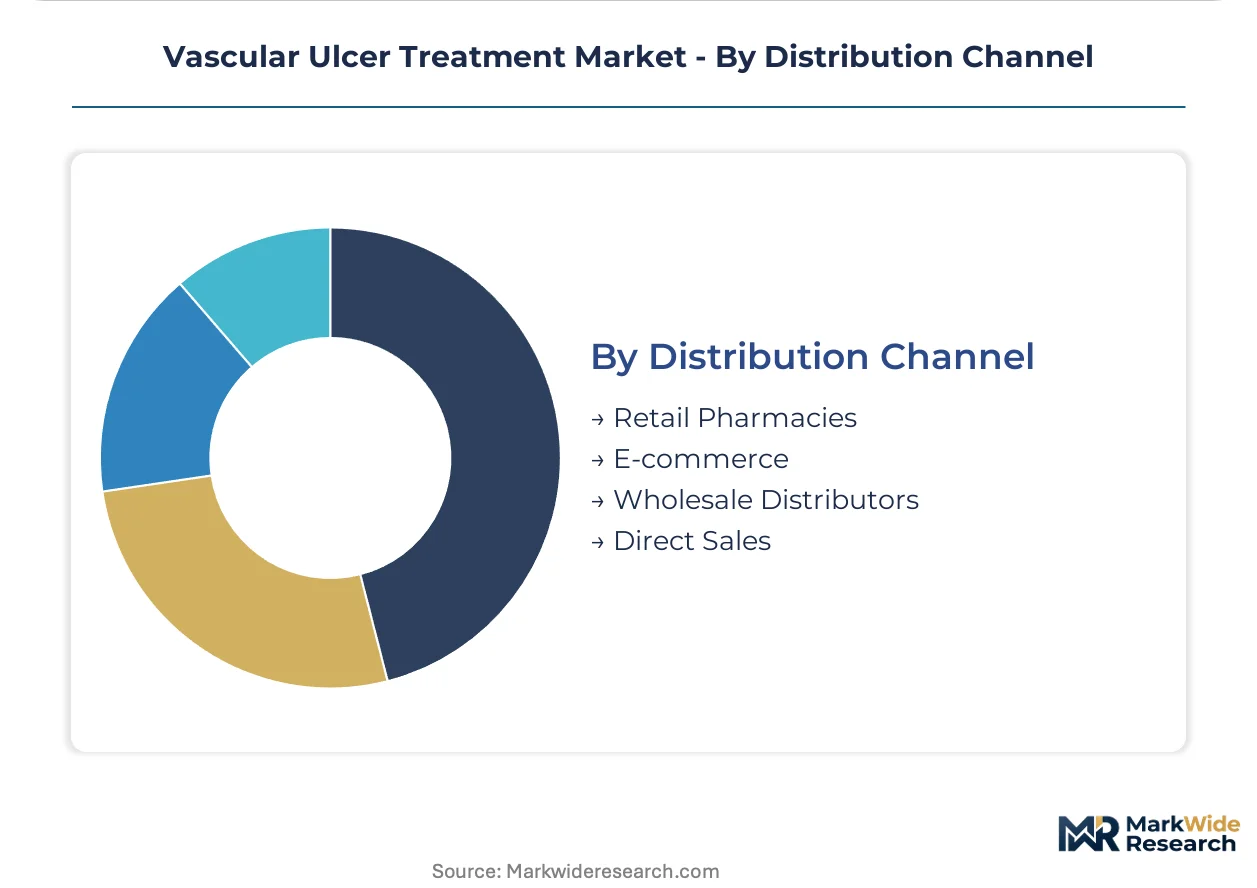
Distribution Channel:
Channel strategy determines margin capture and customer access economics.
- Wholesale Distributors:National medical-surgical distributors dominate hospital and wound care clinic supply contracts through inventory management and logistics integration.
- Direct Sales:Capital-intensive NPWT devices and advanced biologics require clinical specialist engagement for protocol implementation and reimbursement navigation.
- Retail Pharmacies:Community pharmacies capture compression garment and basic dressing refills for ambulatory patients with established prescriptions.
- E-commerce:Direct-to-patient platforms expand for homecare patients seeking convenience, though reimbursement complexity limits addressable transactions.
Wholesale distributors maintain channel leadership; direct sales delivers the steepest expansion trajectory for premium technologies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The vascular ulcer treatment industry traces its commercial origins to post-war European textile manufacturing and mid-20th century British compression therapy development, with subsequent scaling through United States Medicare reimbursement expansion during the 1980s and 1990s.
United States
Medicare Advantage plans now mandate protocol compliance before authorizing advanced biologic interventions for diabetic ulcers. The FDA's medical device classification updates narrow approval pathways for novel antimicrobial dressings. Hospital wound care centers in Texas and Florida concentrate procurement volume for modular dressing kits.
Germany
Statutory insurance reimbursement for home-based compression therapy accelerates portable negative pressure wound therapy penetration. IQWiG health technology assessments determine which premium technologies unlock statutory coverage. Medical device clusters in North Rhine-Westphalia and Baden-Württemberg anchor European supply contracts for silicone adhesive technologies.
United Kingdom
England's NHS community nursing services drive recurrent dressing consumption through venous ulcer compression protocols. NICE cost-effectiveness criteria increasingly restrict coverage for premium wound care technologies. London and Southeast hospital procurement committees unbundle clinical support from material contracts.
France
ANSM antimicrobial claim requirements align with broader EMA Medical Device Regulation evidentiary standards. Regional hospital groups in Île-de-France centralize wound care procurement through category management offices. Paris-based clinical research networks generate trial data supporting CE marking submissions.
Japan
PMDA regulatory timelines for advanced wound care products extend market entry durations relative to Western jurisdictions. METI industrial policy supports domestic medical device manufacturing competitiveness. Osaka and Tokyo medical centers concentrate adoption of portable negative pressure systems for post-acute care networks.
Vascular Ulcer Treatment Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology sophistication and clinical support bundling. The market structure consolidates around integrated wound management portfolios, specialized adhesive technologies, and ostomy-wound care convergence platforms. Three archetypes dominate: diversified medical technology conglomerates with recurring revenue from dressing replacements, mid-cap specialists in silicone-based interfaces, and ostomy-care incumbents extending into wound protocols. Competitive moves center on clinical education infrastructure investment and centralized procurement relationship capture.
Among UK-based diversified health care groups, Smith & Nephew plc exemplifies the integrated portfolio archetype, while Swedish specialist Mölnlycke Health Care occupies a position within the silicone adhesive technology tier. ConvaTec Group plc, also UK-originated, represents the ostomy-wound convergence strategy. These three entities anchor distinct competitive vectors without overlapping core positioning.
| Leading Market Players |
|---|
| Smith & Nephew plc |
| 3M Health Care |
| Mölnlycke Health Care |
| ConvaTec Group plc |
| Coloplast A/S |
| B. Braun Melsungen AG |
| Medline Industries LP |
| Integra LifeSciences Corporation |
| Urgo Medical |
| Others |
Value Network & Pricing Analysis
Hospital procurement committee consolidation across United States integrated delivery networks is forcing manufacturers to unbundle clinical support from material contracts, compressing commodity dressing margins while elevating premium device pricing power through protocol lock-in.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by clinical support bundling and silicone adhesive technology grade. Premium tiers capture recurring revenue from advanced dressing replacements with embedded clinical education; economy tiers compete on per-unit cost for high-volume hydrocolloid procurement. Cost compression in the standard tier intensifies because wholesale distributors centralize hospital contracts through inventory management integration. Ambulatory surgical centers exhibit highest price sensitivity due to CMS outpatient reimbursement caps; wound care clinics demonstrate lowest sensitivity where protocol adherence drives outcomes-based purchasing.
Supply Chain Analysis
Freight cost volatility from Latin American silver mining regions to European dressing manufacturing clusters is elevating input cost uncertainty for antimicrobial product lines. Supply concentrates in Germany for silicone adhesive technologies, the United States for negative pressure wound therapy device assembly, and Ireland for collagen substrate production. Raw material dependencies span silver compounds from Peruvian mining operations, medical-grade silicones from Bavarian chemical clusters, and hydrocolloid polymers from Dutch petrochemical refiners. Single-source vulnerability in silver sourcing creates margin exposure during commodity price swings. Distribution runs through national medical-surgical distributors for hospital contracts, direct sales forces for capital-intensive NPWT platforms, and retail pharmacy networks for compression garment refills.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers geographic-arbitrage value through Germany's IQWiG cost-effectiveness pathway, where favorable health technology assessment ratings unlock statutory insurance reimbursement unavailable under England's NICE cost-containment framework.
For Market Incumbents: Hedge against biologic reimbursement gaps by deepening backward integration into collagen substrate production and securing captive supply of medical-grade silicones. Invest in clinical education infrastructure to defend against procurement committee unbundling trends that separate training revenue from material contracts. Prioritize CE marking submissions for antimicrobial claims before EMA MDR evidentiary requirements tighten further. For New Entrants and Emerging Players: Home health agencies represent the most penetrable channel partner type, given post-acute network expansion and portable NPWT adoption curves. Target rural wound care clinic networks where certified wound ostomy continence nurse shortages constrain protocol adherence and create white-space for telemedicine-enabled remote monitoring solutions. Pursue subscription revenue models pairing digital wound assessment tools with smart dressing platforms. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap specialists possessing silicone adhesive technology differentiation and established European hospital supply contracts. Long-term viability hinges on convergence between ostomy and wound care platforms that capture cross-selling opportunities in outpatient settings. Watch for IQWiG favorable ratings as inflection indicators unlocking statutory insurance coverage expansion for premium technologies.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EMA MDR antimicrobial claim requirements demand extensive clinical trial investment before European market entry. |
| Hospital System Partnership | Integrated delivery network category management offices centralize procurement relationships around modular dressing kit platforms. |
| Software Companion Development | Digital wound assessment tools paired with smart dressings enable subscription revenue models for home health agencies. |
| Reimbursement Strategy | CMS outpatient payment expansion for bioactive dressings accelerates ambulatory surgical center adoption curves. |
| Backward Integration | Captive supply of collagen substrates and medical-grade silicones insulates margins from Latin American silver volatility. |
Research Methodology
Multiple input streams — primary interviews with wound care clinicians, hospital purchasing committee members, and GPO contracts managers; secondary validation against CMS Medicare reimbursement databases, FDA 510(k) filing records, and EMA CE marking submission repositories; plus customs trade data on silver compound imports — were reconciled through bottom-up and top-down triangulation to construct market estimates.
Data-stream reconciliation across the projection horizon applied segmentation dimensions spanning product type, underlying ulcer etiology, site-of-care setting, and regional regulatory cluster. CAGRs were derived from fitted growth curves calibrated to reimbursement policy trajectories and homecare migration adoption rates. Forecast inputs incorporated IQWiG health technology assessment timelines and CMS outpatient payment rulemaking cycles without year-specific anchoring.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EMA MDR enforcement stringency, silver commodity price volatility, and Medicare Advantage protocol compliance mandates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Vascular Dressings Market
Wound Care
Global Traditional Wound Management Market
Wound Care
Interactive Wound Dressing Market
Wound Care
US Wound Care Centers Market
Wound Care
Wound Closure and Advanced Wound Care Market
Wound Care
Wound Care Sealants Market
Wound Care
Wound Debridement (Wound Cleaning) Market
Wound Care
Wound Evacuators Market
Wound Care
Antimicrobial Regenerative Wound Matrix Market
Wound Care
Hydrocolloid Dressing Market
Wound Care
Wound Skin Care Market
Wound Care
Dental Wound Dressings Market
Wound Care
Topical Wound Agents Market
Wound Care
Global Burn Care Market
Wound Care
LAMEA Surgical Dressing Market
Wound Care
Infectious Wound Care Management Market