
 Cervical Cancer Vaccine Market | 2026-2036
Cervical Cancer Vaccine Market Size, Share, and Industry Trends Forecast 2026-2036
Cervical Cancer Vaccine Market Analysis
Subscription-based immunization scheduling software is pivoting how governments and clinics manage multi-dose HPV vaccine adherence. Merck & Co., Inc. leverages its established cold-chain logistics to sustain distribution dominance across emerging economies. Serum Institute of India Pvt. Ltd. anchors volume supply through cost-efficient manufacturing platforms that undercut Western price points. Walvax Biotechnology Co., Ltd. specializes in domestic Chinese market penetration while navigating regulatory pathways for broader Asian export.
Cervical cancer vaccines are prophylactic or therapeutic biologics targeting human papillomavirus oncogenic subtypes, formulated as virus-like particles suspended in aluminum-containing adjuvants and administered via intramuscular injection to induce neutralizing antibody responses. Their primary purpose is preventing persistent HPV infection and subsequent malignant transformation of cervical epithelium. Nonavalent formulations now dominate premium procurement channels where health systems prioritize broadest serotype coverage, while bivalent products retain significant volume share in cost-constrained government tenders. Government Health Programs represent the fastest-growing end-user channel as national immunization schedules expand adolescent coverage mandates.
FDA and EMA bioequivalence standards shape manufacturing quality thresholds for export-eligible production, while WHO prequalification unlocks Gavi-subsidized procurement pools for low-income country access. China's NMPA and India's CDSCO enforce localized clinical trial requirements that delay market entry but protect domestic manufacturer advantages. Stakeholders must monitor evolving national HPV screening-vaccination integration policies and adjuvant platform innovations that could disrupt existing virus-like particle dominance.
Market Dynamics
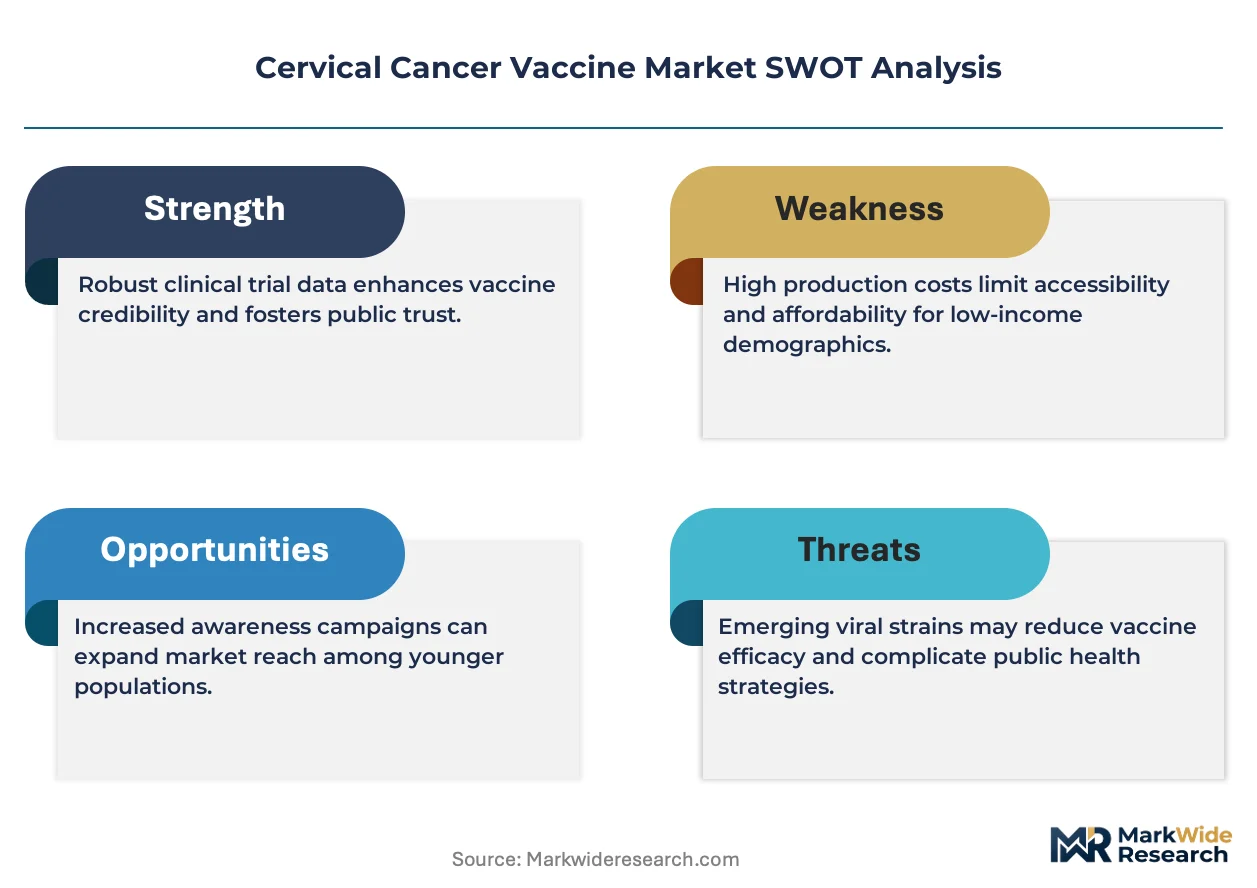
HPV vaccine supply is concentrating around manufacturers with WHO prequalification status, as Gavi alliance funding mechanisms now require this certification for procurement eligibility in low-income country immunization programs.
Growth Catalysts
- Adolescent immunization mandates:National governments in Sub-Saharan Africa and South Asia are integrating HPV vaccination into school-based health programs, creating institutional demand channels.
- WHO prequalification pathways:Streamlined biologics assessment protocols are compressing market entry timelines for multi-dose vaccine formulations in Gavi-eligible countries.
- Screening-vaccination integration:Cervical cancer prevention programs are merging diagnostic and prophylactic service delivery, expanding touchpoints for vaccine administration.
Market Restraints
- Cold-chain infrastructure gaps:Aluminum-adjuvanted formulations require sustained 2-8°C storage, limiting distribution reach in regions with unreliable refrigeration networks.
- Multi-dose regimen adherence:The 2-3 dose schedule over six months creates completion rate drop-offs in resource-constrained health systems.
- Domestic manufacturer protectionism:India's CDSCO and China's NMPA impose localized clinical trial requirements that delay foreign product registration.
Strategic Opportunities
- Single-dose formulation development:Streamlined immunization schedules would unlock coverage in pastoral communities and conflict-affected zones where return visits prove impractical.
- Subscription-based adherence platforms:Digital immunization scheduling tools are penetrating government procurement channels as standalone service contracts.
- Therapeutic vaccine pipelines:Late-stage candidates targeting existing HPV infections could expand addressable population beyond prophylactic-only segments.
Industry Challenges
- Biologics manufacturing scale-up:Virus-like particle production requires dedicated fermentation capacity that demands 3-5 year facility construction timelines.
- Serotype coverage trade-offs:Nonavalent formulations face cost-per-dose ceilings in government tenders, forcing portfolio segmentation decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cervical Cancer Vaccine Market |
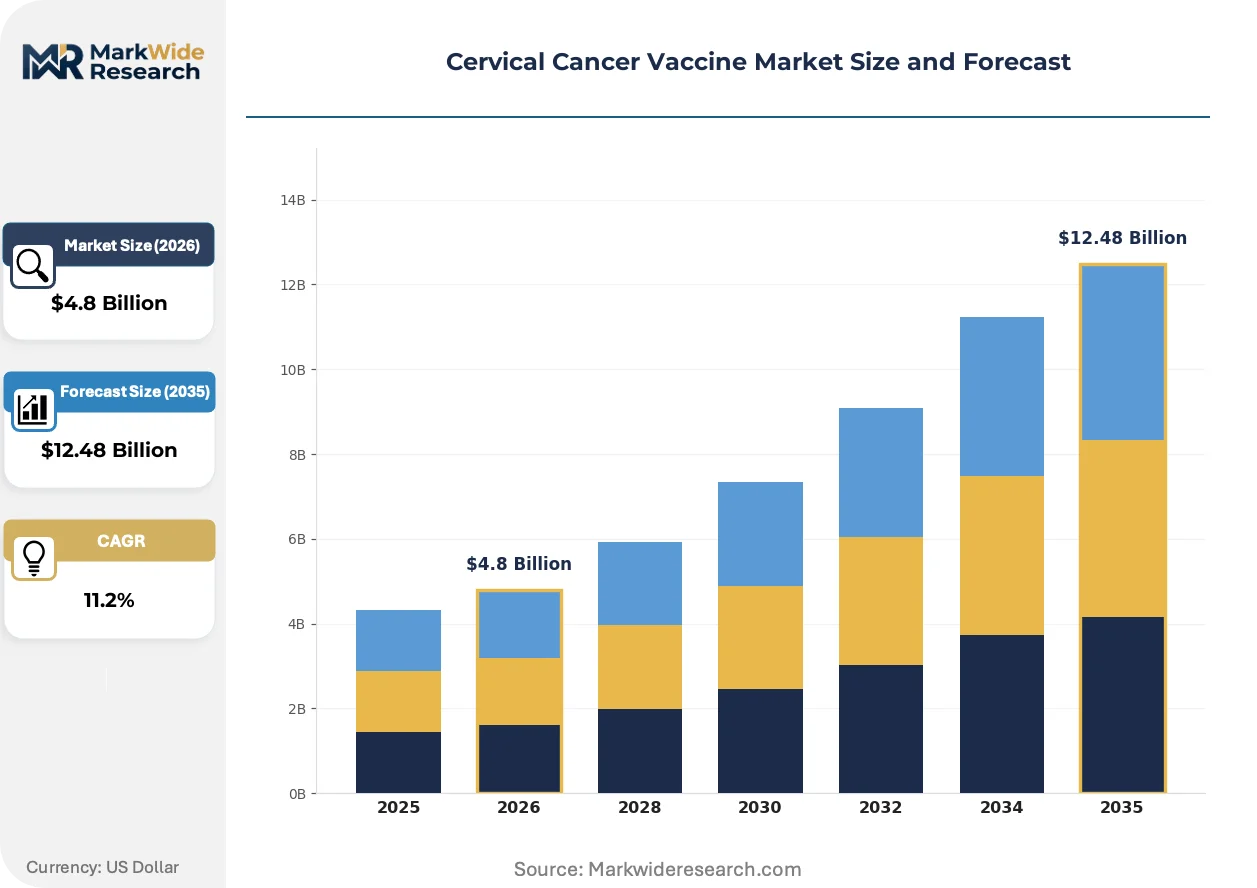
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.48 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Quadrivalent, Bivalent, Nonavalent, Therapeutic End User: Hospitals, Clinics, Research Laboratories, Government Health Programs Route of Administration: Intramuscular, Subcutaneous, Oral, Intranasal Distribution Channel: Pharmacies, Online Retail, Hospital Pharmacies, Wholesale |
| Companies Covered | Merck & Co., Inc., GlaxoSmithKline plc, Serum Institute of India Pvt. Ltd., Walvax Biotechnology Co., Ltd., Shanghai Zerun Biotechnology, GSK plc, Xiamen Innovax Biotech, Beijing Wantai BioPharm, Sanofi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cervical Cancer Vaccine Market Emerging Trajectories
mRNA platform migration is disrupting established virus-like particle manufacturing paradigms, with developers pursuing accelerated development timelines and simplified supply chains for next-generation HPV immunization.
DNA-based therapeutic vaccines are rewriting clinical trial design for persistent HPV infection management. Oncology centers in the United States and Germany are enrolling patients in Phase II studies evaluating these candidates as adjuncts to standard-of-care treatment. The technology is compressing the boundary between prophylactic and therapeutic vaccine categories, forcing portfolio strategists to reassess segment definitions.
EMA's revised biosimilar guidance for complex vaccines is tightening comparability study requirements for follow-on HPV products. Manufacturers must now demonstrate immunogenicity equivalence through head-to-head clinical trials rather than relying on analytical similarity alone. European procurement agencies are incorporating these standards into tender specifications, raising quality thresholds for contract eligibility.
Outcome-based procurement contracts are displacing traditional volume-purchase agreements in national immunization programs. Brazil's Ministry of Health and Thailand's National Health Security Office are piloting performance-linked payments tied to population coverage targets rather than doses delivered. This shift transfers epidemiological risk to manufacturers while rewarding systems-level implementation capabilities.
Cervical Cancer Vaccine Market Segmentation
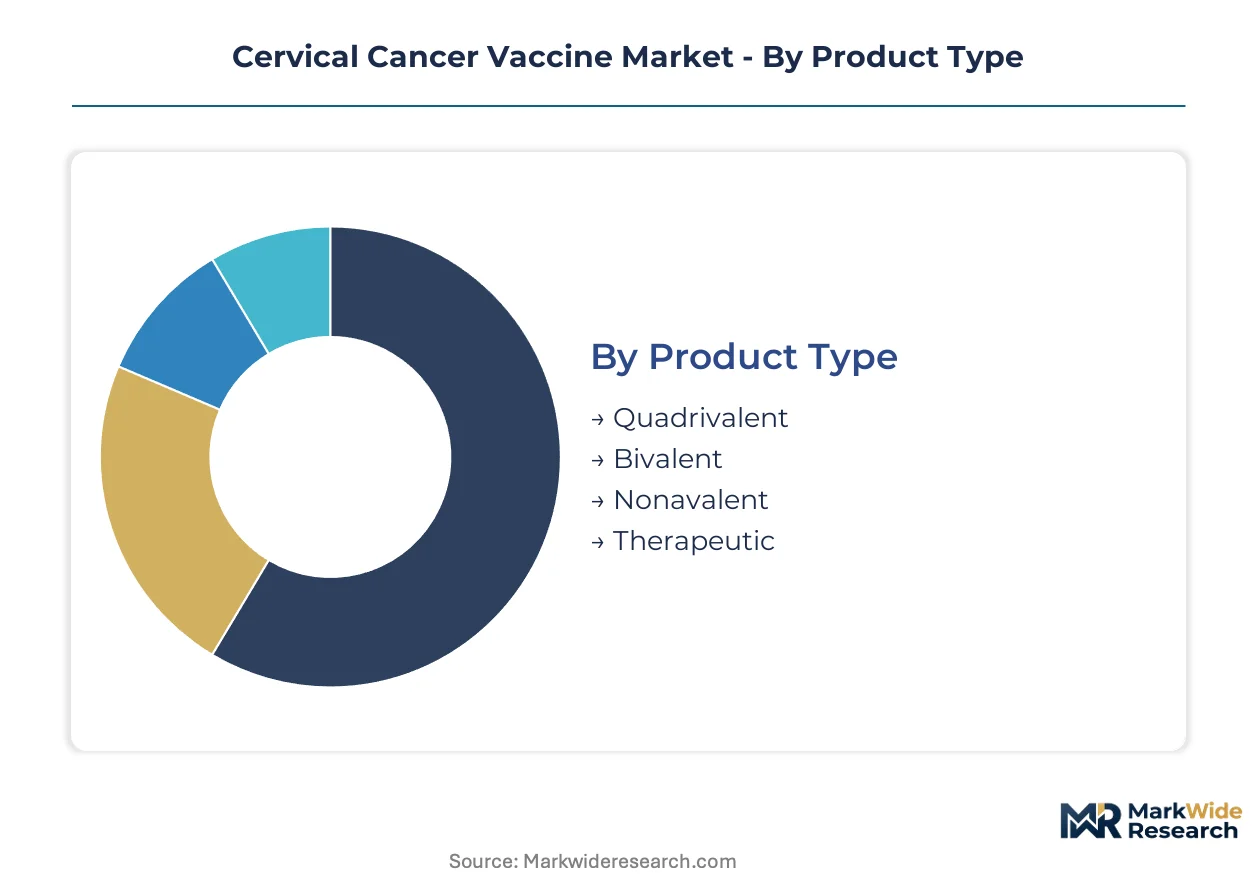
HPV vaccine procurement decisions hinge on serotype coverage breadth, delivery infrastructure, and immunization schedule feasibility. Manufacturers optimize formulation portfolios across these dimensions to capture divergent payer willingness-to-pay and cold-chain capabilities.
Product Type:
Capital intensity escalates steeply with serotype complexity, as nonavalent production requires expanded fermentation capacity and more intricate purification protocols.
- Nonavalent:Nine-valent virus-like particle formulations deliver the broadest oncogenic HPV subtype coverage. Demand concentrates in North American and Western European health systems where comprehensive serotype protection justifies premium procurement pricing, though cost-per-dose ceilings constrain penetration in bulk government tenders.
- Bivalent:Two-valent products targeting HPV 16/18 retain substantial volume share through cost-efficient manufacturing platforms. Procurement in Sub-Saharan Africa and South Asia favors this segment where health systems prioritize coverage breadth over serotype completeness within constrained immunization budgets.
- Quadrivalent:Four-valent formulations balance coverage and cost for middle-income country programs.
- Therapeutic:DNA-based and peptide candidates target persistent infection clearance in oncology settings.
Nonavalent formulations absorb the bulk of installed capacity in premium markets; bivalent products are expanding most quickly through Gavi-subsidized procurement channels.
End User:
Customer procurement sophistication varies dramatically, from centralized national tenders to fragmented clinic-level purchasing.
- Government Health Programs:National immunization schedules and school-based delivery systems generate institutional demand at scale. WHO prequalification unlocks Gavi alliance funding for low-income country access, while Brazil's Ministry of Health pilots outcome-based contracts tied to adolescent coverage targets rather than doses delivered.
- Hospitals:Acute care facilities administer catch-up vaccination for young adults and manage therapeutic candidate trials. India's CDSCO registration requirements delay foreign product entry, protecting domestic manufacturer advantages in hospital procurement.
- Clinics:Primary care and specialty women's health practices serve private-pay segments.
- Research Laboratories:Clinical trial sites and reference laboratories support pipeline development and immunogenicity surveillance.
Government Health Programs command the steepest expansion trajectory; hospitals retain the largest share of therapeutic vaccine evaluation activity.
Route of Administration:
Delivery method selection shapes cold-chain requirements, healthcare worker training needs, and patient adherence patterns.
- Intramuscular:Deltoid or vastus lateralis injection of aluminum-adjuvanted suspensions remains the established standard. This route demands sustained 2-8°C storage throughout distribution, limiting reach in regions with unreliable refrigeration networks across rural India and Sub-Saharan Africa.
- Subcutaneous:Alternative injection depth offers potential for simplified administration in resource-constrained settings.
- Oral:Enteric formulations under early development could eliminate cold-chain dependency entirely.
- Intranasal:Mucosal delivery platforms target immune response induction at viral entry sites.
Intramuscular delivery dominates current installed manufacturing capacity; oral formulations are gaining development investment fastest as supply chain simplification priorities intensify.
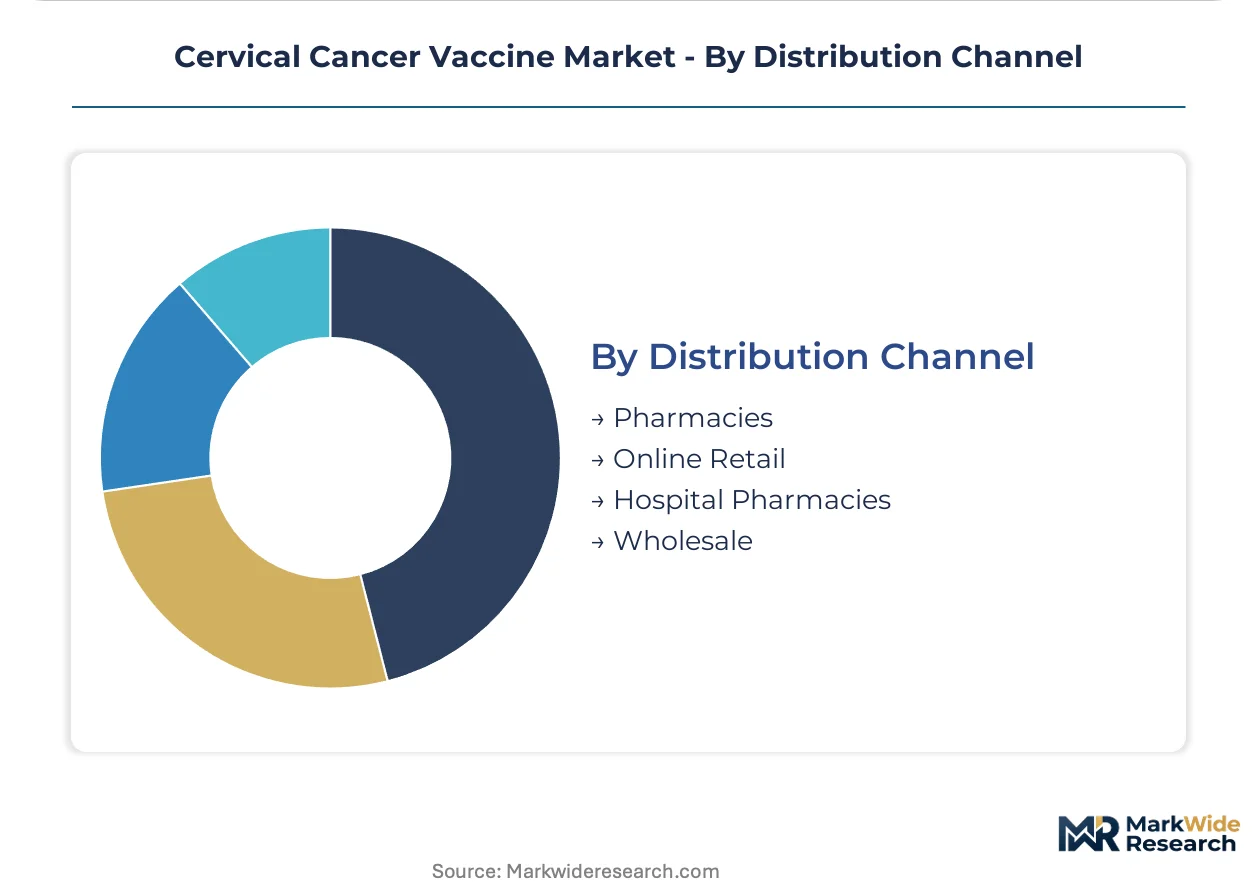
Distribution Channel:
Channel selection reflects product temperature sensitivity, batch traceability requirements, and procurement scale economics.
- Hospital Pharmacies:Captive distribution within integrated health systems ensures chain-of-custody for temperature-sensitive biologics. EMA's revised biosimilar guidance for complex vaccines tightens comparability standards that European hospital procurement agencies now embed in tender specifications.
- Wholesale:Regional distributors with validated cold-chain infrastructure serve government immunization programs at national scale.
- Pharmacies:Retail access points support private-market segments in urban centers.
- Online Retail:Digital platforms enable subscription-based immunization scheduling software penetration.
Wholesale channels handle the greatest procurement volume; hospital pharmacies are climbing fastest as integrated delivery networks expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of cervical cancer vaccines concentrates in India and China, while consumption gravity pulls toward Sub-Saharan Africa and South Asia where disease burden and immunization scale-up intersect. This supply-demand asymmetry shapes regional procurement patterns and regulatory pathway investments.
United States
Adolescent immunization mandates and private health system procurement sustain premium nonavalent demand. FDA bioequivalence standards enforce manufacturing quality thresholds that shape export-eligible production. Maryland-based Merck & Co., Inc. anchors domestic supply through established cold-chain distribution networks serving integrated health systems.
India
Government school-based health programs and Gavi-subsidized procurement generate institutional volume demand. CDSCO localized clinical trial requirements delay foreign registration while protecting domestic manufacturer advantages. Pune-based Serum Institute of India Pvt. Ltd. drives cost-efficient manufacturing platforms that undercut Western price points in bulk tenders.
China
Domestic market penetration and adolescent coverage expansion fuel production scale-up. NMPA regulatory pathways navigate export ambitions for broader Asian market access. Kunming-based Walvax Biotechnology Co., Ltd. specializes in domestic distribution while pursuing regional registration strategies.
Brazil
National immunization schedule integration and outcome-based procurement pilots reshape manufacturer contracting. ANVISA registration standards align with WHO prequalification benchmarks for Gavi-eligible access. São Paulo and Rio de Janeiro clusters concentrate public health program administration and hospital pharmacy distribution networks.
South Africa
Sub-Saharan Africa regional procurement hub status and school-based delivery systems institutionalize demand channels. National Health Department screening-vaccination integration policies expand service delivery touchpoints. Johannesburg and Cape Town metropolitan health districts pilot subscription-based immunization scheduling platforms.
Cervical Cancer Vaccine Market Vendor Landscape
Top-tier vendors anchor premium nonavalent supply, while cost-optimized bivalent manufacturers capture Gavi-subsidized procurement volume. The vendor base stratifies across WHO prequalification status, cold-chain capability, and national immunization program contracting sophistication. Three archetypes dominate: Western-origin innovators with established regulatory dossiers, emerging-market volume suppliers with cost-efficient platforms, and domestic-focused specialists navigating localized registration pathways. Competitive moves concentrate on capacity expansion in WHO-prequalified facilities and strategic partnerships for distribution reach in cold-chain-constrained regions.
Among Western-origin innovators, Merck & Co., Inc. and GlaxoSmithKline plc occupy positions reflecting established regulatory dossiers and premium market access. Serum Institute of India Pvt. Ltd. and Walvax Biotechnology Co., Ltd. exemplify the emerging-market volume archetype, representing cost-efficient manufacturing platforms that penetrate price-sensitive government tenders. These four entities collectively illustrate the competitive tension between serotype coverage breadth and procurement cost constraints that shapes portfolio positioning across regional markets.
| Leading Market Players |
|---|
| Merck & Co., Inc. |
| GlaxoSmithKline plc |
| Serum Institute of India Pvt. Ltd. |
| Walvax Biotechnology Co., Ltd. |
| Shanghai Zerun Biotechnology |
| GSK plc |
| Xiamen Innovax Biotech |
| Beijing Wantai BioPharm |
| Sanofi |
| Others |
Supply Flow & Price Mechanics
Gavi alliance procurement mandates for WHO-prequalified supply are compressing manufacturer margins and forcing capacity reallocation toward prequalification-eligible facilities, which in turn hardens price floors for nonavalent formulations in premium markets.
Pricing Analysis
Margin tightening in bivalent segments reflects Serum Institute of India's cost-efficient manufacturing platforms undercutting Western price points in bulk government tenders. Three-tier pricing structure across premium nonavalent, standard quadrivalent, and economy bivalent levels stratifies procurement channels. Cost-down pressure on nonavalent products accelerates because EMA's revised biosimilar guidance tightens comparability standards that European hospital procurement agencies embed in tender specifications. Government Health Programs in Sub-Saharan Africa exhibit highest price sensitivity, while North American integrated health systems demonstrate lowest sensitivity due to comprehensive serotype coverage mandates.
Supply Chain Analysis
India's PLI scheme and China's NMPA localization requirements are reshaping upstream sourcing toward domestic fermentation capacity and adjuvant production. Geographic supply concentrates in India, China, and the United States, with Pune-based and Kunming-based manufacturers anchoring volume production. Raw material dependencies draw from specialized yeast fermentation substrates, aluminum salt adjuvants, and single-use bioreactor components. Single-source vulnerability persists in virus-like particle purification resin supply. Distribution runs through wholesale channels with validated cold-chain infrastructure serving national immunization programs at scale.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Manufacturing capacity for WHO-prequalified virus-like particle production remains constrained by 3-5 year facility construction timelines, which props pricing power for incumbent certificate holders across the analysis window.
For Market Incumbents: Extend prequalification coverage into single-dose formulation pipelines before mRNA platform migration disrupts established manufacturing paradigms. Deepen backward integration into adjuvant production to defend margin position against aluminum salt price volatility. Prioritize capacity addition in India and China to capture Gavi-subsidized procurement volume growth. For New Entrants and Emerging Players: Begin with therapeutic vaccine development targeting persistent HPV infection clearance in oncology settings, where DNA-based candidates rewrite clinical trial design and segment definitions remain fluid. Target hospital procurement channels in the United States and Germany for Phase II trial enrollment site partnerships. Pursue subscription-based immunization scheduling software as a standalone service contract entry point. For Investors and Strategic Acquirers: Re-rating potential sits with emerging-market volume suppliers given Gavi alliance funding mechanism expansion and WHO prequalification pathway streamlining. Acquisition focus should center on manufacturers with installed fermentation capacity and active prequalification dossiers. Monitor single-dose formulation clinical trial readouts as inflection indicators for prophylactic segment disruption risk.| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Pathway | Unlocks Gavi-subsidized procurement pools for low-income country access in Sub-Saharan Africa. |
| Manufacturing Scale-Up | Dedicated fermentation capacity demands multi-year timelines that constrain supply response to demand surges. |
| Single-Dose Formulation Development | Streamlined schedules would unlock coverage in pastoral communities where return visits prove impractical. |
| Screening-Vaccination Integration | Merging diagnostic and prophylactic service delivery expands touchpoints for vaccine administration in national programs. |
| Subscription-Based Adherence Platforms | Digital immunization scheduling tools penetrate government procurement channels as standalone service contracts. |
Methodological Framework
Document review covered FDA filings, EMA submissions, ClinicalTrials.gov records, and Gavi procurement databases, complemented by interviews with vaccine development executives, regulatory affairs leads, formulary directors, and hospital procurement managers. Secondary validation drew from WHO prequalification lists, national immunization schedule disclosures, and customs trade data. Bottom-up demand modeling and top-down supply capacity estimates were triangulated to ensure consistency across the analysis window.
Segmentation outputs reflect serotype coverage breadth, end-user procurement channel, and regional regulatory cluster variations across the projection horizon. CAGRs were derived from epidemiological burden projections, immunization schedule expansion trajectories, and manufacturer capacity buildout announcements. Industry-specific forecast inputs incorporated Gavi alliance funding allocation cycles and WHO prequalification approval timelines.
Underlying measurement precision varies by segment; Government Health Programs and established nonavalent markets carry tighter precision than therapeutic vaccine pipelines and emerging oral formulation categories. Forecasts reflect documented assumptions regarding immunization mandate adoption rates and cold-chain infrastructure development. Regulatory pathway delays, adjuvant supply disruptions, or single-dose formulation breakthroughs could materially revise projections. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Peptide and Anticoagulant Drugs Market
Pharmaceuticals
Pharmaceutical Wholesale & Distribution Market
Pharmaceuticals
Antiglaucoma Drugs Market
Pharmaceuticals
Global Azithromycin Market
Pharmaceuticals
PAP and Paracetamol Market
Pharmaceuticals
Cardiometabolic Drugs Market
Pharmaceuticals
Myasthenia Gravis Therapeutics Market
Pharmaceuticals
Bladder Cancer Treatment Drugs Market
Pharmaceuticals
Europe Vaccines Market
Pharmaceuticals
Contract Pharmaceutical Fermentation Services Market
Pharmaceuticals
Sweden Pharmaceutical Market
Pharmaceuticals
Spain OTC Drugs Market
Pharmaceuticals
Antidotes Market
Pharmaceuticals
Czech Republic Pharmaceutical Market
Pharmaceuticals
Pantoprazole Market
Pharmaceuticals
Global Neuroprotective Agents Market